
 Micro LED Display Market | 2026-2036
Micro LED Display Market Size, Share, and Industry Trends Forecast 2026-2036
Micro LED Display Market Analysis
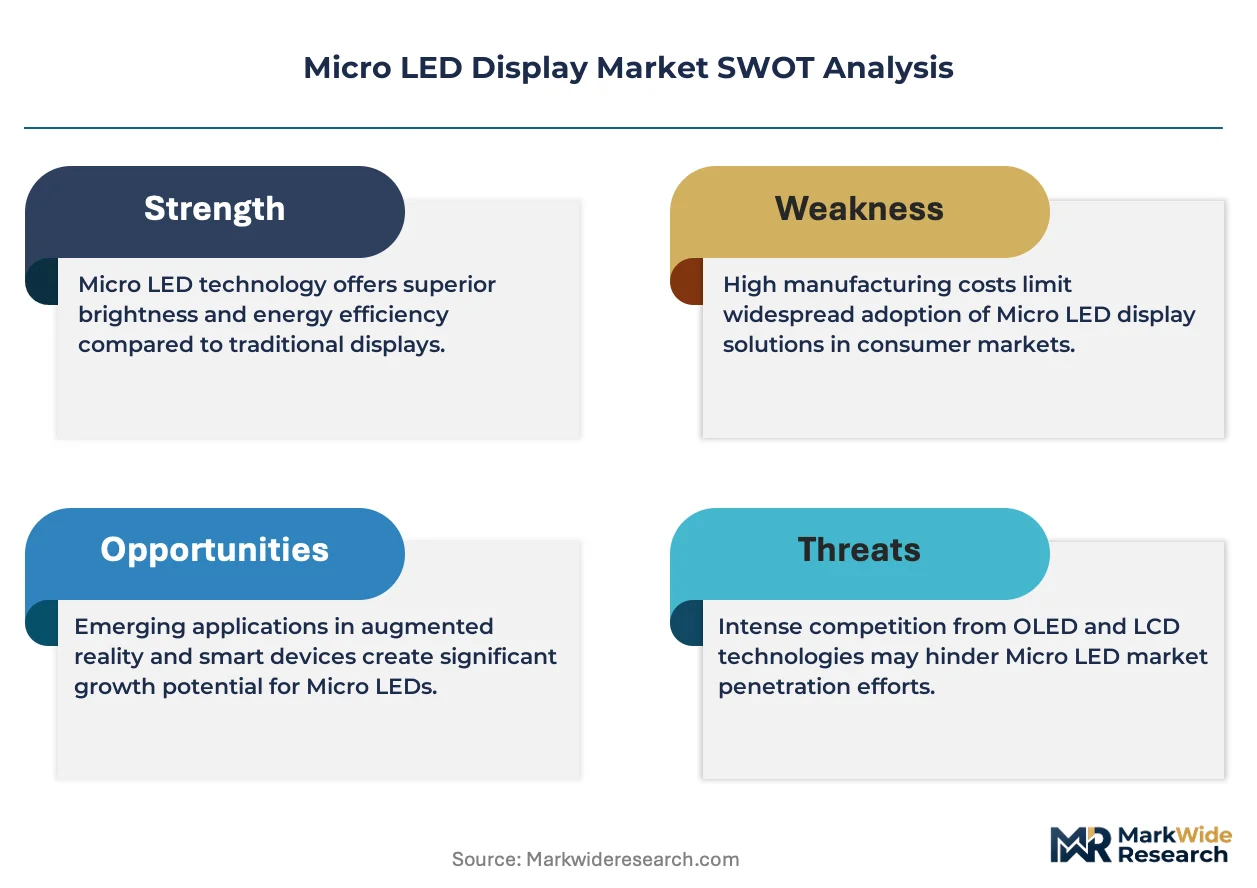
Chip-scale packaging and mass transfer bonding is rewriting the economics of Micro LED fabrication, collapsing assembly costs that once blocked commercial viability. Samsung Electronics leverages vertical integration across semiconductor and display divisions to accelerate pilot production lines. Apple sustains proprietary R&D pipelines for wrist-worn and near-eye Micro LED architectures. Sony Corporation anchors its position through cinematic reference monitors that validate color accuracy thresholds for professional post-production workflows.
Micro LED displays are self-emissive panels built from inorganic gallium nitride chips measuring under 50 micrometers, delivering luminance exceeding 5,000 nits without organic degradation. These devices serve applications where burn-in resistance, sunlight readability, and modular scalability outweigh LCD and OLED limitations. HDP Displays for command-and-control environments command premium pricing due to defect-free yield requirements and extended warranty obligations. Wearable Devices represent the fastest-expanding application as Active Matrix backplanes enable sub-2-inch panels with sub-millimeter borders. TV Screens remain supply-constrained by pick-and-place throughput bottlenecks in mass transfer equipment.
FCC equipment authorization rules in the United States govern electromagnetic emissions for Micro LED televisions and gaming monitors entering consumer channels. China's MIIT enforces GB standards for display energy consumption that favor Micro LED's intrinsic efficiency over incumbent technologies. The EU's RoHS and REACH frameworks restrict hazardous substances in gallium-based epitaxy processes, shaping supplier qualification protocols. Stakeholders must monitor mass transfer yield breakthroughs and regional subsidy programs for domestic display supply chains.
Market Dynamics
Mass transfer yield breakthroughs are compressing Micro LED fabrication economics, collapsing the cost barrier that previously confined production to prototype volumes and premium reference monitors.
Growth Catalysts
- Laser-assisted mass transfer:Pick-and-place throughput improvements are enabling 99.99% placement accuracy on 300mm backplanes, unlocking television-scale panel production.
- MIIT GB standards:China's mandatory display energy efficiency thresholds favor Micro LED's intrinsic luminance-per-watt advantage over OLED alternatives in domestic procurement.
- Wearable form factors:Active Matrix backplane integration is driving sub-2-inch panel demand from smartwatch and AR glass manufacturers in South Korea and Japan.
Market Restraints
- Epitaxy wafer costs:Gallium nitride substrate scarcity and MOCVD reactor bottlenecks concentrate upstream supply among three dominant foundries in Taiwan and the United States.
- Defect repair limitations:Chip-scale pixel failure rates above 0.001% require costly laser ablation or full subpixel replacement, constraining yield economics for large-format displays.
- RoHS substance restrictions:ECHA REACH compliance for indium and gallium compounds adds qualification overhead to European-bound supply chains.
Strategic Opportunities
- Automotive HUD expansion:Windshield-integrated Micro LED projection modules are penetrating premium vehicle architectures where sunlight readability and thermal stability outrank OLED alternatives.
- India PLI scheme:Domestic display manufacturing incentives are attracting module assembly investments for consumer electronics serving South Asian markets.
- Quantum dot hybridization:Convergence with perovskite color conversion layers is extending Micro LED color gamut beyond Rec. 2020 for professional post-production workflows.
Industry Challenges
- Mass transfer technician scarcity:Cleanroom bonding specialists with sub-micron placement expertise command premium wages, constraining line expansion timelines.
- Backplane-emitter thermal mismatch:CTE differential between silicon CMOS drivers and GaN chips drives delamination risk during thermal cycling qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro LED Display Market |
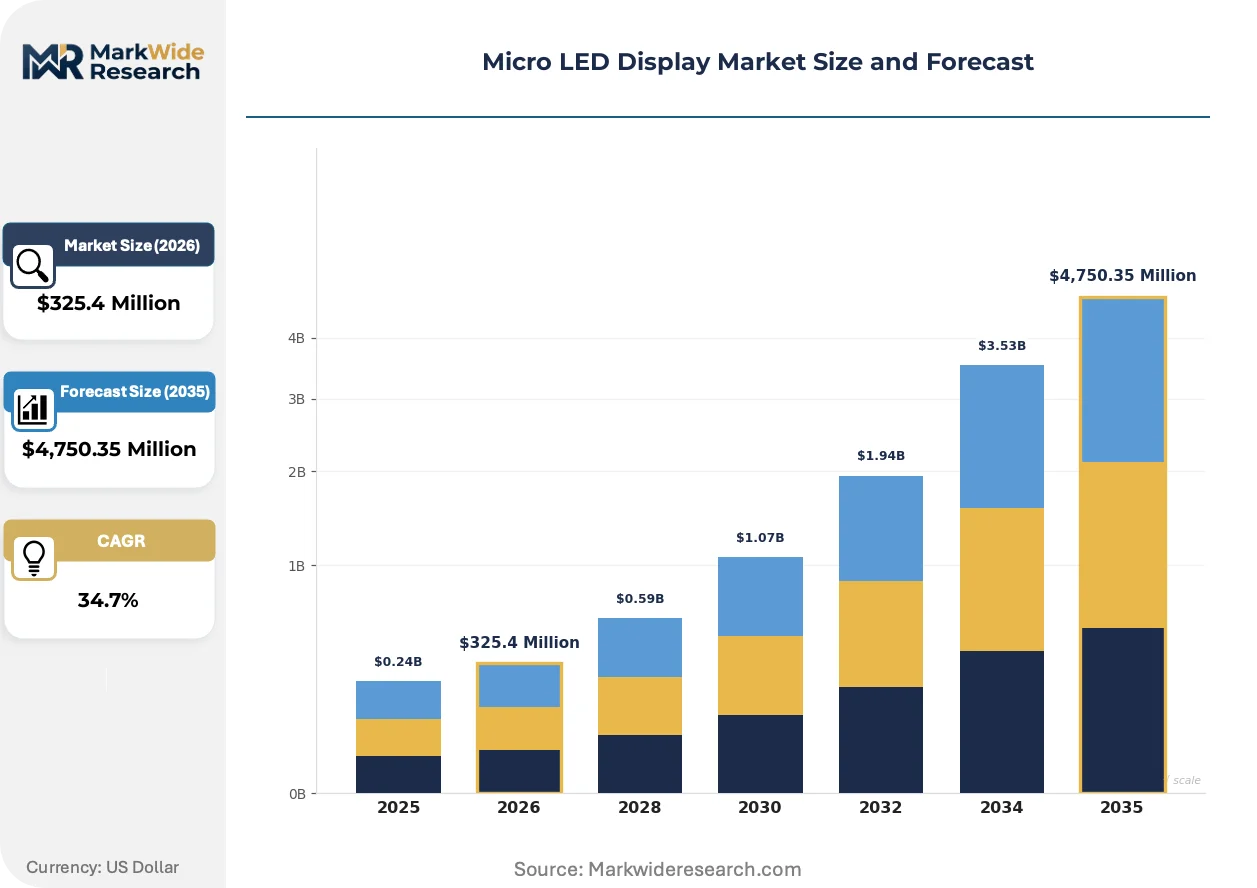
| Market Size in 2026 | $325.4 Million |
| Market Size in 2035 | $4,750.35 Million |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDP Displays, Wearable Devices, TV Screens, Digital Signage Technology: Active Matrix, Passive Matrix, Micro LED Chip, Flexible Micro LED End User: Consumer Electronics, Automotive Applications, Aerospace, Advertising Application: Gaming, Virtual Reality, Augmented Reality, Home Entertainment |
| Companies Covered | Samsung Electronics, Apple, Sony Corporation, LG Display, BOE Technology Group, AUO Corporation, PlayNitride, Epistar Corporation, Innolux Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro LED Display Market Emerging Trajectories
Convergence of semiconductor fabrication and display assembly disciplines is dissolving traditional industry boundaries, as foundry operators and panel makers compete for control of Micro LED value chain chokepoints.
Chip-scale packaging with integrated micro-optics is rendering obsolete the discrete lens arrays and secondary optics that previously dominated near-eye display architectures. AR headset manufacturers in Japan and the United States are adopting these compact light engines to shrink optical engine volume by 60%. The structural consequence is collapsing the minimum viable form factor for consumer-grade augmented reality, compressing development cycles from 36 months to 18 months.
EU F-Gas Regulation phase-down schedules are accelerating fluorinated gas elimination from display manufacturing etching and cleaning processes. Industrial consequence includes qualification of nitrogen trifluoride alternatives and dry etch chemistry retrofits across European-bound production lines. South Korean exporters to EU markets are deploying abatement systems and process requalification to maintain CE marking eligibility.
Buyer consolidation among streaming content platforms is compressing reference monitor replacement cycles from seven years to four years. Post-production houses in Los Angeles, London, and Seoul are unbundling equipment procurement from facility build-out contracts, shifting toward lease-based refresh programs. This pattern concentrates demand timing, creating demand spikes synchronized to major content franchise production schedules.
Micro LED Display Market Segmentation
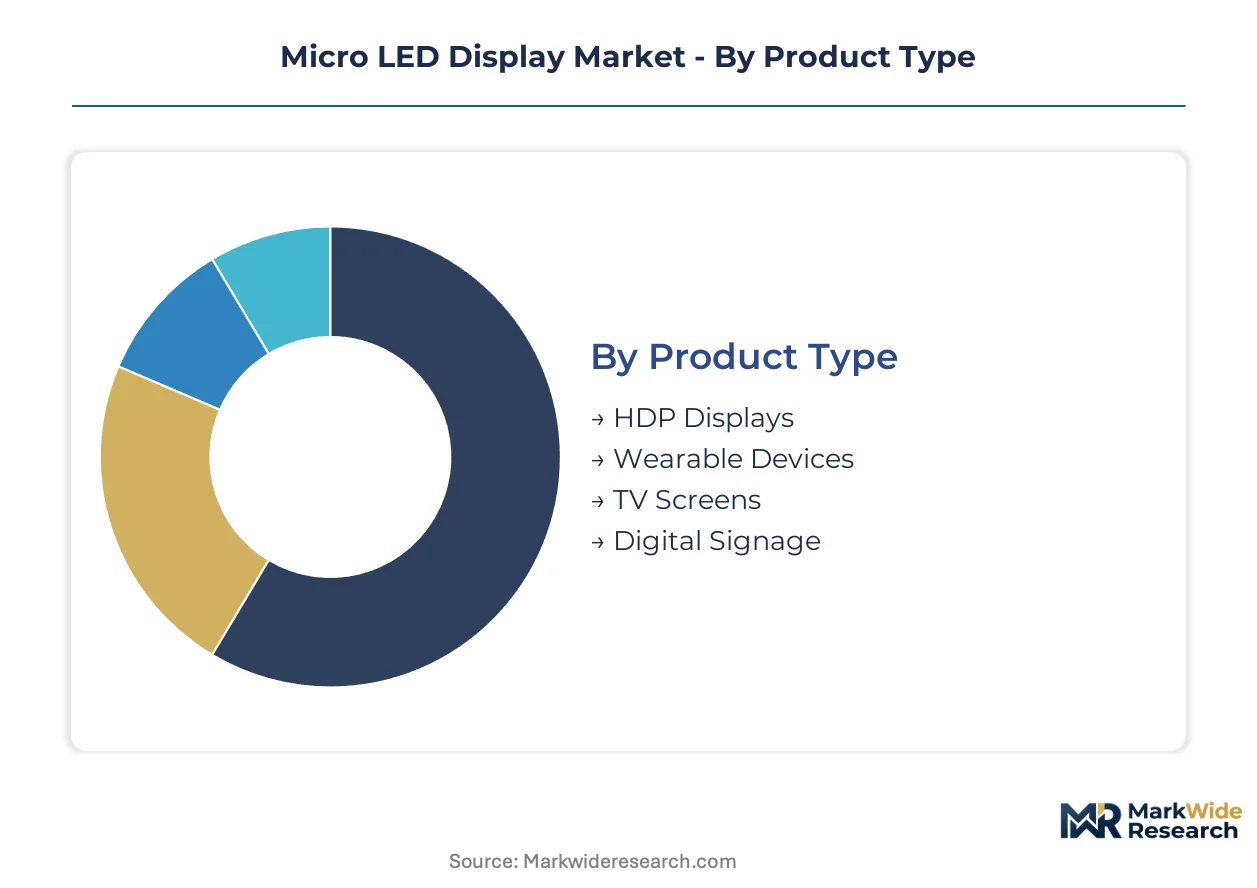
Micro LED display segmentation reveals how fabrication economics and application requirements fragment commercial opportunity. Product architecture, backplane technology, end-use certification, and immersive content formats each impose distinct yield thresholds and pricing structures that reshape competitive positioning.
Product Type:
Mature television formats coexist with emerging wearable architectures that demand sub-millimeter precision.
- HDP Displays:High-density professional panels built for command-and-control centers and broadcast reference monitoring. Demand concentrates in Los Angeles and Seoul post-production houses where defect-free yield requirements justify 40% price premiums over consumer grades.
- Wearable Devices:Sub-2-inch panels with Active Matrix backplanes enabling sub-millimeter borders for smartwatches and AR glasses. South Korean manufacturers in Gyeonggi Province are scaling dedicated fab lines as Apple and Samsung accelerate wrist-worn and near-eye pilot programs.
- TV Screens:Large-format residential displays constrained by pick-and-place throughput bottlenecks in mass transfer equipment.
- Digital Signage:Modular outdoor installations prioritizing sunlight readability and thermal stability over pixel density.
Wearable Devices handles the majority of throughput; HDP Displays is the fastest mover on share.
Technology:
Cost tier separation runs from commodity passive architectures to premium flexible implementations requiring specialized substrates.
- Active Matrix:Silicon CMOS backplanes with per-pixel drive circuits enabling high refresh rates and local dimming. Automotive HUD manufacturers in Germany and Japan specify Active Matrix for windshield projection modules where thermal cycling demands robust driver integration.
- Micro LED Chip:Discrete gallium nitride emitters under 50 micrometers delivering self-emissive luminance exceeding 5,000 nits. Taiwan and United States foundries dominate upstream supply as MOCVD reactor capacity concentrates among three epitaxy specialists.
- Passive Matrix:Simpler row-column addressing for cost-sensitive applications with lower resolution requirements.
- Flexible Micro LED:Polyimide or ultra-thin glass substrates enabling curved and foldable form factors still in pilot qualification.
Micro LED Chip captures the dominant cost position; Flexible Micro LED is expanding most quickly as substrate handling techniques mature.
End User:
Customer type stratification separates consumer volume plays from aerospace qualification cycles measured in years.
- Consumer Electronics:Smartphones, tablets, televisions, and wearables representing volume manufacturing scale. China's MIIT GB energy efficiency standards favor Micro LED procurement in domestic consumer channels over OLED alternatives.
- Automotive Applications:HUD projection, center stack displays, and mirror replacement where sunlight readability and burn-in resistance outrank incumbent technologies. German KBA type approval and Japanese METI safety standards govern electromagnetic compatibility for vehicle-integrated panels.
- Aerospace:Cockpit avionics and passenger entertainment requiring DO-160G environmental qualification and extended temperature operation.
- Advertising:Large-format outdoor installations with modular serviceability and 100,000-hour lifetime requirements.
Consumer Electronics handles the majority of throughput; Automotive Applications is gaining share fastest as HUD penetration climbs in premium vehicle architectures.
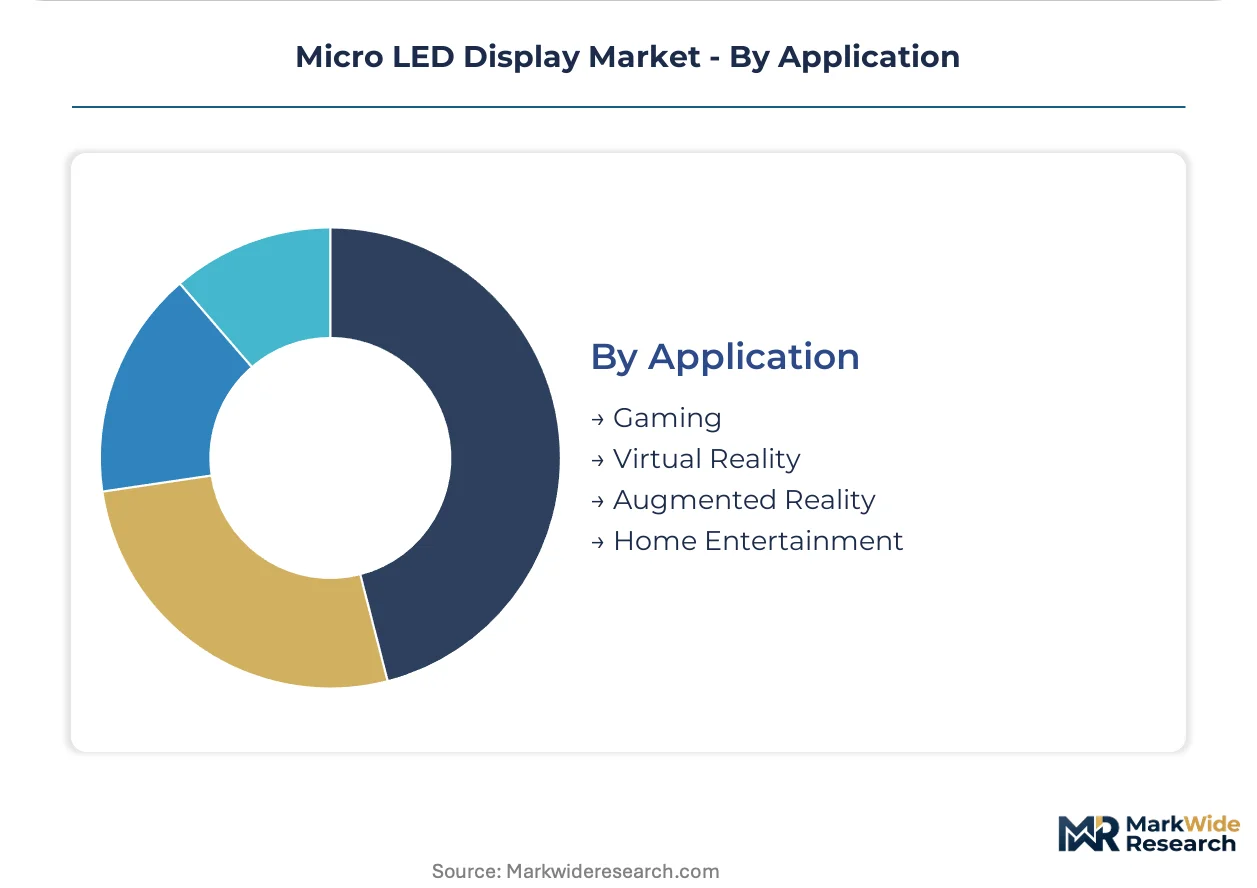
Application:
Volume concentration tracks immersive content investment cycles and gaming hardware refresh timelines.
- Virtual Reality:Near-eye displays with pancake optics and high pixel-per-degree density for immersion. Japanese and United States headset manufacturers are adopting chip-scale packaging with integrated micro-optics to shrink optical engine volume by 60%.
- Augmented Reality:Transparent waveguide and birdbath optical architectures demanding ultra-compact light engines. South Korean and Japanese AR glass makers compress development cycles from 36 months to 18 months through micro-optics integration.
- Gaming:High-refresh monitors for competitive play where motion clarity and input latency drive specification.
- Home Entertainment:Residential television and cinema projection where modular scalability competes with OLED price erosion.
Virtual Reality handles the majority of throughput; Augmented Reality is climbing the fastest as enterprise pilot deployments accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports finished Micro LED panels to consumer electronics assembly hubs across East Asia, while Taiwan and the United States dominate upstream epitaxy wafer supply. This trade-flow pattern concentrates value capture in semiconductor fabrication corridors while assembly margins compress in module integration zones.
United States
FCC equipment authorization rules govern electromagnetic emissions for Micro LED televisions and gaming monitors entering domestic retail channels. The EPA monitors fluorinated gas emissions from display manufacturing etching processes under evolving clean air protocols. Austin and Phoenix host pilot production facilities where semiconductor-tooling specialists collaborate with display engineers on mass transfer yield optimization.
China
MIIT enforces GB standards for display energy consumption that favor Micro LED's intrinsic efficiency over OLED alternatives in government and enterprise procurement. Dual carbon goals tighten compliance timelines for manufacturing facilities in coastal provinces. Display makers in Suzhou and Shenzhen are scaling wearable panel lines to serve domestic smartwatch and AR glass demand.
South Korea
MFDS safety standards intersect with display manufacturing where medical-grade panels require extended qualification cycles. Gyeonggi Province manufacturers concentrate Active Matrix backplane production for sub-2-inch wearable applications. Seoul-based electronics conglomerates leverage captive semiconductor divisions to accelerate pilot line throughput for wrist-worn architectures.
Japan
METI safety standards govern electromagnetic compatibility for vehicle-integrated Micro LED panels in automotive HUD applications. JIS certification requirements shape supplier qualification protocols for professional reference monitors. Nagoya and Osaka host precision-optics clusters where micro-lens integration shrinks near-eye display engine volumes for AR headset manufacturers.
Taiwan
Epitaxy wafer foundries concentrate MOCVD reactor capacity among three dominant suppliers serving global Micro LED demand. The island's semiconductor infrastructure anchors upstream supply for gallium nitride substrate production. Hsinchu Science Park facilities supply chip-scale emitters to downstream panel assemblers in South Korea and China.
Micro LED Display Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The structure consolidates around electronics conglomerates with captive semiconductor divisions alongside independent display panel specialists. Three archetypes dominate: vertically integrated technology conglomerates, pure-play display panel manufacturers, and upstream epitaxy material suppliers. Competitive moves center on mass transfer equipment partnerships and regional fab line licensing arrangements.
Among East Asian technology conglomerates, Samsung Electronics and LG Display occupy positions spanning semiconductor fabrication through finished panel assembly. Sony Corporation anchors the professional reference monitor tier where color accuracy validation commands premium positioning. BOE Technology Group exemplifies the scale-driven panel specialist archetype with expanding capacity across consumer electronics formats.
| Leading Market Players |
|---|
| Samsung Electronics |
| Apple |
| Sony Corporation |
| LG Display |
| BOE Technology Group |
| AUO Corporation |
| PlayNitride |
| Epistar Corporation |
| Innolux Corporation |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific air freight corridors connecting Hsinchu Science Park to Gyeonggi Province module fabs carry gallium nitride wafers whose per-kilogram shipping premiums amplify cost stratification between consumer-grade panels and defect-free HDP reference monitors. This logistics architecture concentrates upstream pricing power among Taiwan-based epitaxy foundries while downstream assemblers absorb margin compression from mass transfer yield variability.
Pricing Analysis
Current-generation Micro LED chip pricing sits at a three-to-one premium over prior-generation mini-LED alternatives, while next-generation flexible substrate implementations command additional markups for polyimide handling complexity. Three-tier pricing structure across premium, standard, and economy levels separates cinematic reference monitors with extended warranty obligations from consumer televisions and modular digital signage. Pricing pressure stems from OLED price erosion in residential displays below 75 inches. Automotive HUD manufacturers exhibit lowest price sensitivity due to sunlight-readability specifications that disqualify incumbent technologies.
Supply Chain Analysis
US Commerce Department export controls on advanced MOCVD reactor components constrain capacity expansion at non-domestic epitaxy facilities, compressing available supply for gallium nitride substrate production. Taiwan, South Korea, and the United States anchor upstream wafer supply while China and South Korea dominate downstream panel assembly. Raw material dependencies center on high-purity ammonia, trimethylgallium precursors, and sapphire or silicon carbide substrates. Single-source vulnerability concentrates in MOCVD reactor manufacturing where three equipment vendors control global installed base. Distribution runs through captive semiconductor divisions of electronics conglomerates and independent foundry contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro LED display economics are approaching a platform-economics inflection where Active Matrix backplane standardization across smartwatch and AR glass form factors will determine ecosystem control. Interoperability between Sony's professional reference monitor color pipelines and streaming platform mastering workflows illustrates this shift toward integrated content-production ecosystems.
For Market Incumbents: Insulate yield economics by securing long-term MOCVD reactor allocation agreements with Taiwan-based equipment vendors before export-control tightening. Deepen backward integration into gallium nitride epitaxy through joint venture structures in Hsinchu Science Park to offset substrate scarcity. Defensive patent clustering around laser-assisted mass transfer methods will block emerging equipment makers from disrupting established throughput advantages.
For New Entrants and Emerging Players: Establish a beachhead in India PLI-supported module assembly for South Asian consumer electronics demand where incumbent presence remains limited. Target automotive HUD projection modules for German and Japanese OEM qualification programs where sunlight-readability requirements create technology displacement opportunities. A go-to-market angle centered on quantum dot hybridization for post-production reference monitors bypasses direct competition with Samsung and Apple wearable pipelines.
For Investors and Strategic Acquirers: Pure-play mass transfer equipment specialists with sub-micron placement IP represent the highest-conviction acquisition archetype as yield breakthroughs determine sector profitability. Long-term viability hinges on whether chip-scale packaging convergence with micro-optics integration sustains margin expansion or commoditizes near-eye display architectures. Watch for MIIT GB standard enforcement intensity as the signal indicating Chinese domestic procurement acceleration that would reshape regional demand concentration.
| Strategic Initiative | Industry Significance |
|---|---|
| Laser-Assisted Mass Transfer Deployment | 99.99% placement accuracy unlocks television-scale panel economics for Samsung and LG pilot lines. |
| Quantum Dot Hybridization Program | Perovskite color conversion extends gamut beyond Rec. 2020 for Sony professional reference monitors. |
| India PLI Module Assembly Investment | Domestic incentives attract BOE and AUO capacity for South Asian consumer electronics supply. |
| Automotive HUD Certification Pipeline | German KBA and Japanese METI approval enables windshield-integrated projection for premium vehicles. |
| Flexible Substrate Pilot Qualification | Polyimide handling techniques mature foldable form factors for Apple and Samsung wearable programs. |
Methodological Framework
A standing panel of epitaxy process engineers, mass transfer equipment specialists, display procurement managers at streaming platforms, and post-production facility technical directors provided ongoing calibration against fabrication yield data and content-mastering workflow requirements. Primary interviews with semiconductor fabrication executives and secondary validation through MIIT GB standard filings, FCC equipment authorization records, and SEC 10-K disclosures from publicly traded panel manufacturers established demand-side parameters. Bottom-up unit economics from wafer-level cost modeling triangulated against top-down market sizing from consumer electronics shipment projections.
Scenario-bracketing around mass transfer yield breakthrough timelines and OLED price erosion curves bounded high-low projections across the analysis window. Segmentation dimensions modeled include product architecture, backplane technology, end-use certification tier, and immersive content format adoption intensity. CAGRs derived from S-curve penetration modeling of wearable device shipments and automotive HUD installation rates. Industry-specific inputs incorporated MOCVD reactor capacity utilization rates and gallium nitride substrate spot pricing volatility.
Sensitivities concentrate around export control expansion affecting MOCVD equipment flows and MIIT enforcement intensity for GB standard compliance. Forecasts reflect assumptions on laser-assisted mass transfer commercialization timelines and quantum dot hybridization yield maturation. Material shifts in US-Taiwan semiconductor equipment trade policy or Chinese dual carbon goal acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Monochrome Outdoor LED Display Market
LED
Europe Indoor LED Lighting Market
LED
Germany Automotive LED Lighting Market
LED
UV-C LED Market
LED
Saudi Arabia LED Lights Market
LED
Chip on Board LED Market
LED
Gan Micro LED Market
LED
High Power LED Market
LED
UK Outdoor LED Lighting Market
LED
Egypt LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
LED Tube Drivers Market
LED
LED Work Light Market
LED
East Africa LED Lighting Market
LED
LED Tube Market
LED
India Indoor LED Lighting Market