
 UK Indoor LED Lighting Market | 2026-2036
UK Indoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
UK Indoor LED Lighting Market Insights
Buyer concentration among UK commercial property landlords is restructuring procurement patterns across the indoor LED lighting value chain. Signify leverages its connected lighting platforms to capture recurring service revenue from large estate holders. Thorlux Lighting anchors its position through British manufacturing and rapid customisation for specifiers. Osram competes on component depth, supplying COB arrays and drivers to luminaire assemblers serving mid-market fit-out contractors.
UK indoor LED lighting encompasses solid-state luminaires, control gear, and integrated management systems designed for enclosed environments, typically operating at colour temperatures between 2700K and 6500K with efficacies exceeding 130 lumens per watt for premium commercial products. The primary purpose is to deliver regulated illuminance for visual tasks while minimising operational energy and maintenance burden across multi-tenancy buildings. Commercial retrofit leads volume, driven by MEES compliance deadlines and EPC rating imperatives, while smart LED technology captures disproportionate margin through sensor integration and circadian tuning capabilities. Residential new-build lags in value terms, constrained by developer cost ceilings and fragmented specification authority.
The Department for Levelling Up, Housing and Communities enforces Building Regulations Part L conservation standards, which mandate minimum luminaire efficacy and lighting control provisions in new and refurbished buildings. BEIS policy frameworks and the UK Net Zero Strategy shape long-term demand by embedding operational carbon targets into property valuation and financing. The British Standards Institution publishes BS EN 12464 and related illumination standards that define performance benchmarks for workplace and educational environments. Stakeholders must monitor how the proposed Future Homes Standard and tightening MEES thresholds reconfigure the retrofit-replacement balance across England's building stock.
Market Dynamics
Minimum Energy Efficiency Standards (MEES) and Building Regulations Part L are forcing a wholesale replacement cycle across England's commercial building stock, compressing the retrofit timeline for landlords facing EPC rating deadlines.
Growth Catalysts
- MEES Compliance Deadlines:Landlords must upgrade to minimum EPC ratings or face letting restrictions, accelerating LED retrofits in regional office portfolios.
- Connected Lighting Platforms:Sensor-integrated luminaires enable energy monitoring and space utilisation analytics, attracting large estate holders seeking operational visibility.
- Regional City Aging Stock:Birmingham, Manchester and Leeds retain substantial pre-2000 commercial floor space requiring complete lighting system replacement.
Market Restraints
- Semiconductor Supply Concentration:LED driver ICs and COB substrates depend on concentrated Asian foundry capacity, exposing UK assemblers to extended lead times.
- Skilled Installation Bottleneck:Electrical contractor capacity constraints in England's regional cities delay project completion and compress margins for retrofit specialists.
- Fluorescent Stockpiling:Some landlords accelerated purchases of legacy T5/T8 gear ahead of anticipated phase-out dates, temporarily deferring LED conversion.
Strategic Opportunities
- Circadian Lighting in Healthcare:Tunable white systems with melanopic output adjustment are penetrating NHS trusts and private hospital new-builds.
- Human-Centric Retrofit Premium:Workplaces in London's financial district are specifying biodynamic lighting to differentiate tenant amenities and justify rental premiums.
- Service Revenue Attachment:Lighting-as-a-service models decouple capital expenditure from operational budgets, unlocking municipal and education sector procurement.
Industry Challenges
- Integration with Legacy BMS:Open-protocol interoperability between proprietary lighting control networks and existing building management systems requires costly middleware development.
- BS EN 12464 Compliance Complexity:Specifiers must navigate illuminance uniformity and glare index calculations across diverse task environments, extending design timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Indoor LED Lighting Market |
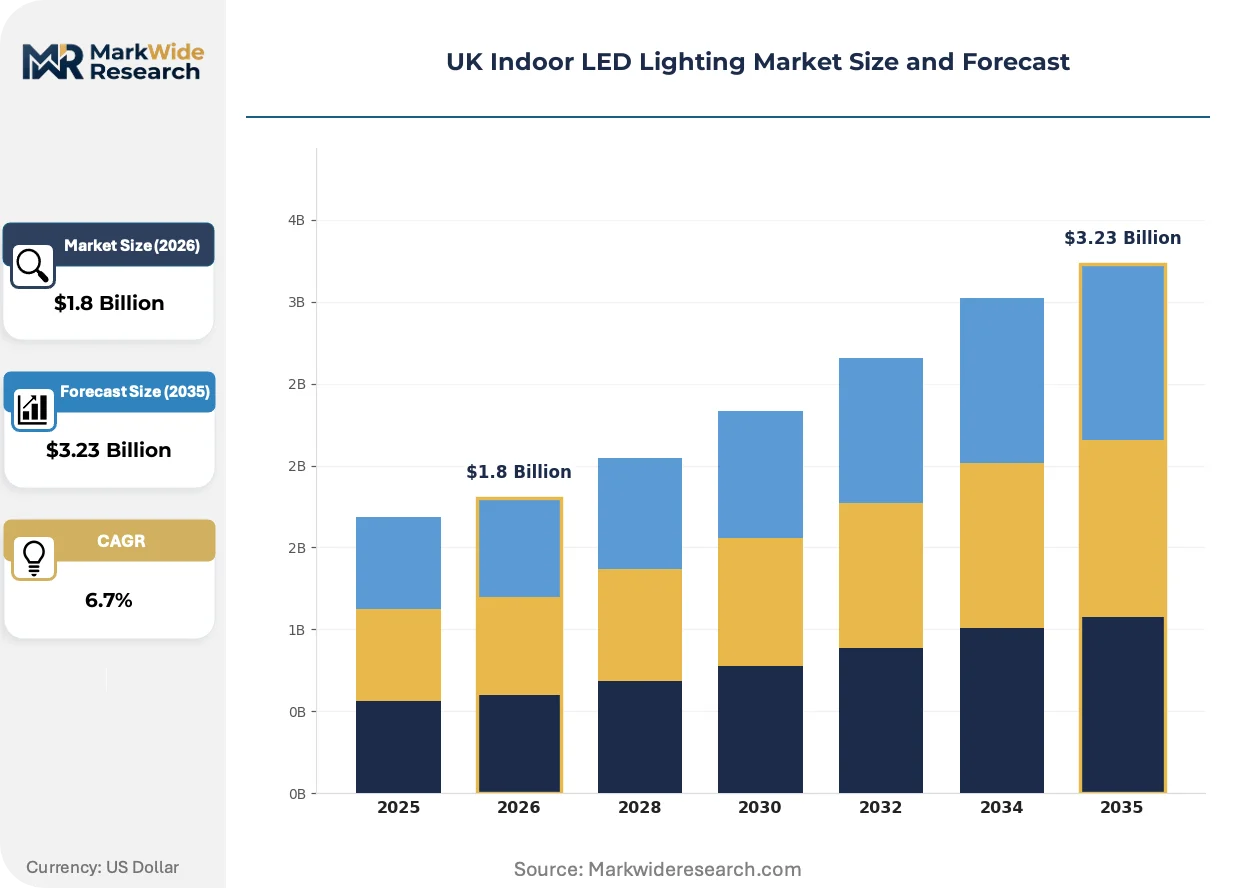
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
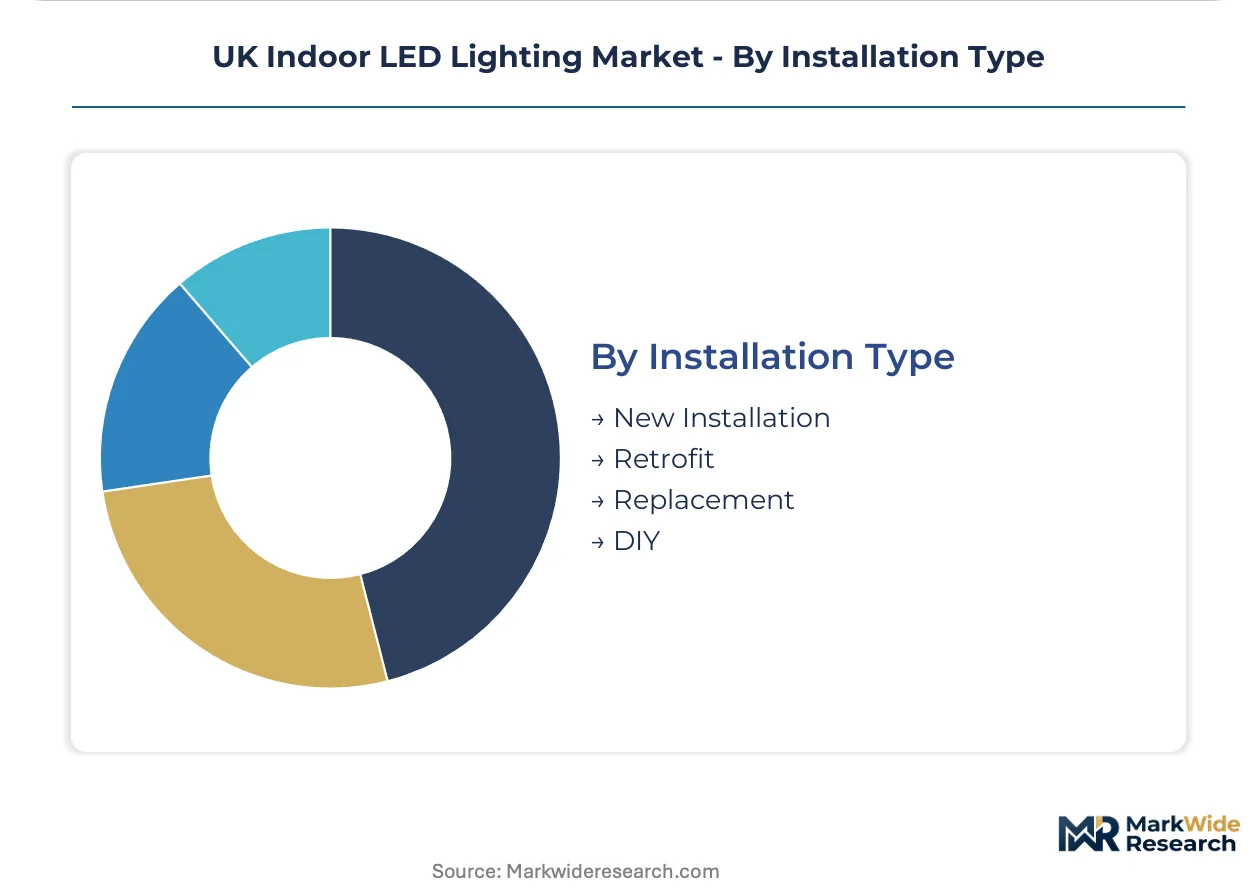
| Segmentation | Product Type: Residential, Commercial, Industrial, Architectural Technology: Smart LED, Linear LED, Downlights, Panel Lights End User: Retail, Hospitality, Offices, Educational Installation Type: New Installation, Retrofit, Replacement, DIY |
| Companies Covered | Signify, Osram, Acuity Brands, Zumtobel, Legrand, GE Current, Dialight, Thorlux Lighting, TRILUX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Indoor LED Lighting Market Trends and Innovations
Power-over-Ethernet (PoE) infrastructure and wireless mesh protocols are dissolving the boundary between lighting hardware and building IT networks, enabling software-defined illumination management.
LiFi optical wireless communication is converging with LED luminaire architecture to deliver high-bandwidth data transmission through room lighting. University research campuses and defence facilities in southern England are piloting integrated illumination-communication systems. This convergence is compressing the traditional separation between lighting specification and network infrastructure procurement.
Building Regulations Part L conservation standards are tightening efficacy thresholds and mandating daylight-responsive controls in refurbished commercial premises. The Department for Levelling Up, Housing and Communities is embedding operational carbon metrics into compliance verification. Commercial retrofit projects across England's regional cities are accelerating specification of sensor-integrated luminaires to satisfy these provisions.
Consolidated procurement by large property investment trusts is displacing fragmented contractor-led specification. REITs and institutional landlords are centralising lighting decisions across multi-site portfolios, compressing the influence of traditional M&E contractors. This concentration is most visible in London and Manchester office markets where single landlords control substantial floor space volumes.
UK Indoor LED Lighting Market Segmentation
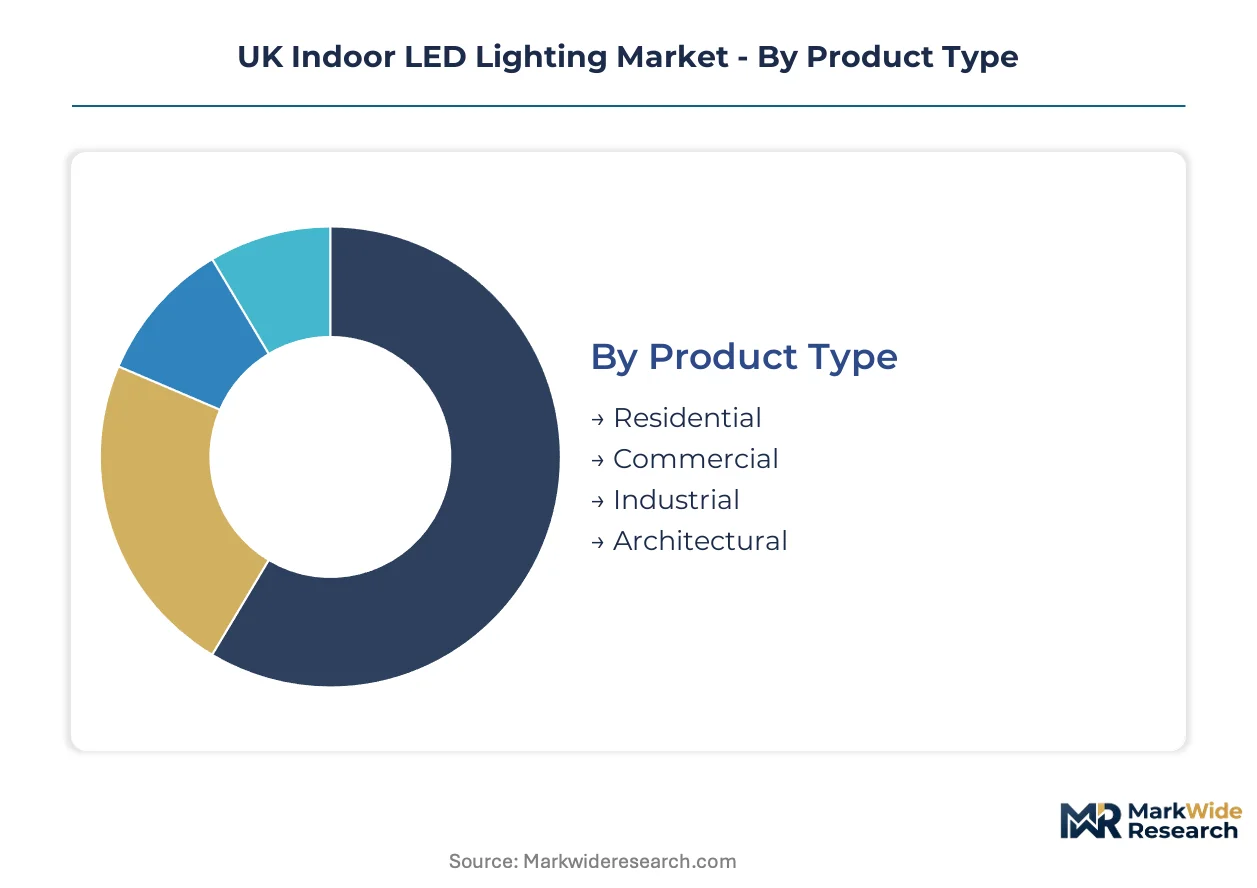
Segmentation in the UK indoor LED lighting market reveals how regulatory pressure and asset ownership patterns concentrate demand in distinct buyer groups. Understanding these divisions illuminates where procurement authority sits and which technical specifications dominate purchasing criteria.
Product Type:
Buyer sophistication and compliance urgency separate the four product categories, with institutional landlords driving fundamentally different specification logic than residential developers or industrial operators.
- Commercial:Multi-tenancy office retrofits dominate specification volume, with MEES deadlines compelling landlords across Birmingham, Manchester and Leeds to replace aging fluorescent systems with sensor-integrated luminaires. Connected lighting platforms with energy monitoring capabilities attract large estate holders seeking operational visibility across dispersed portfolios.
- Residential:New-build developments face cost ceilings that constrain premium LED adoption, while retrofit demand concentrates in London's private rental sector where EPC rating requirements filter tenant eligibility. Developer procurement favors standardized downlight packages over tunable or connected systems.
- Industrial:High-bay installations in warehousing and logistics facilities prioritize lumen maintenance and thermal management over aesthetic considerations.
- Architectural:Bespoke luminaire design for heritage and landmark projects commands premium margins through specifier relationships.
Commercial leads volumes today; Architectural is gaining share fastest.
Technology:
Control integration depth defines the technology hierarchy, separating basic efficacy upgrades from systems that merge illumination with building data infrastructure.
- Smart LED:Sensor-integrated luminaires with wireless mesh protocols enable daylight harvesting, occupancy detection and circadian tuning. NHS trusts and London financial district offices specify biodynamic systems to differentiate tenant amenities or support patient recovery protocols.
- Linear LED:Suspended and surface-mounted systems replace T5/T8 fluorescent battens in open-plan offices, with efficacy thresholds mandated by Building Regulations Part L driving specification. Regional city commercial stock built before 2000 creates substantial replacement volume.
- Downlights:Recessed modular units dominate residential and hospitality specification where ceiling integration and glare control matter.
- Panel Lights:Edge-lit and back-lit flat panels serve healthcare and educational environments requiring uniform illuminance distribution.
Linear LED anchors retrofit volumes; Smart LED is expanding most quickly.
End User:
Budget authority and specification sophistication vary sharply across end-user categories, with institutional procurement following compliance-driven timelines distinct from commercial operator cycles.
- Offices:REITs and institutional landlords centralise lighting decisions across multi-site portfolios, compressing traditional M&E contractor influence. Connected lighting platforms with space utilisation analytics justify rental premiums in London and Manchester competitive markets.
- Educational:Municipal and academy trust procurement favours lighting-as-a-service models that decouple capital expenditure from operational budgets, unlocking circadian specification in new-build schools.
- Retail:High-street and shopping centre operators balance colour rendering requirements against energy cost reduction imperatives.
- Hospitality:Hotels and restaurants prioritise aesthetic warmth and dimming performance over efficacy metrics.
Offices generate the steepest expansion trajectory; Educational procurement is climbing the fastest.
Installation Type:
Project economics and regulatory timing separate installation modes, with retrofit urgency created by MEES deadlines diverging from new-build specification cycles.
- Retrofit:Landlords facing EPC rating restrictions accelerate complete lighting system replacement in England's regional cities, with electrical contractor capacity constraints delaying project completion. Minimum Energy Efficiency Standards compress implementation timelines across pre-2000 commercial stock.
- New Installation:Building Regulations Part L mandates minimum luminaire efficacy and daylight-responsive controls, embedding LED specification into compliance verification from design stage.
- Replacement:Component-level LED module swaps extend legacy luminaire life in budget-constrained municipal and education sectors.
- DIY:Consumer channel sales of retrofit lamps and fixtures serve residential owner-occupiers outside landlord-regulated segments.
Retrofit dominates current volumes; New Installation is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Scotland's retrofit pipeline trails England's commercial conversion pace, while Wales concentrates demand in public sector estates rather than private landlord portfolios. Regional divergence reflects building stock age, regulatory enforcement timing, and landlord concentration across the UK's constituent nations.
London and the Southeast
REITs and institutional landlords dominate procurement across the capital's Grade A office stock, with MEES compliance deadlines compressing retrofit timelines in Canary Wharf and the City. Building Regulations Part L enforcement by the Department for Levelling Up, Housing and Communities mandates daylight-responsive controls in refurbished commercial premises. Westminster and Southwark host the densest concentration of connected lighting platform deployments, where sensor-integrated luminaires justify rental premiums through space utilisation analytics.
Midlands
Birmingham retains substantial pre-2000 commercial floor space requiring complete lighting system replacement, with regional landlord portfolios accelerating LED conversion ahead of EPC rating restrictions. The West Midlands Combined Authority embeds operational carbon targets into regeneration funding criteria. Coventry and Leicester manufacturing estates drive industrial high-bay specification, where lumen maintenance and thermal management override aesthetic considerations.
North England
Manchester's commercial property market exhibits consolidated procurement by single landlords controlling substantial floor space volumes, compressing traditional M&E contractor influence. Leeds and Sheffield office retrofits concentrate in aging stock built before 2000, creating replacement volume for linear LED systems. Northern Powerhouse investment programmes channel public sector lighting-as-a-service procurement toward municipal and educational estates.
Scotland
Scottish commercial retrofit lags England's pace, with Edinburgh and Glasgow landlord portfolios facing less immediate MEES enforcement pressure. The Scottish Government's building standards division maintains efficacy thresholds distinct from England's Part L framework. Aberdeen's energy sector office stock exhibits deferred LED conversion amid occupational uncertainty, while Dundee and Inverness public sector estates drive panel light specification for healthcare and educational environments.
Wales
Welsh demand concentrates in municipal and NHS trust procurement rather than private commercial retrofit, with Cardiff and Swansea public estates specifying circadian systems for healthcare new-builds. Welsh Government building regulations align with but trail England's MEES timeline. Newport and Wrexham industrial warehousing drives high-bay LED specification, where logistics operators prioritise energy cost reduction over connected platform capabilities.
UK Indoor LED Lighting Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the UK indoor LED lighting value chain. The market exhibits tiered consolidation, with global lighting groups controlling premium commercial specification while regional British manufacturers anchor mid-market retrofit volumes. Three strategic archetypes dominate: connected platform providers capturing recurring service revenue, component suppliers feeding luminaire assemblers, and rapid-customisation specialists serving specifier relationships. Competitive moves centre on strategic partnerships with electrical contractors and portfolio diversification into lighting-as-a-service models.
Among the named players, Signify occupies a position exemplifying the connected platform archetype, while Osram sits within the component supply tier supplying COB arrays and drivers to downstream assemblers. Thorlux Lighting represents the British manufacturing specialist archetype, anchoring regional specification through rapid customisation capabilities for project-specific requirements.
| Leading Market Players |
|---|
| Signify |
| Osram |
| Acuity Brands |
| Zumtobel |
| Legrand |
| GE Current |
| Dialight |
| Thorlux Lighting |
| TRILUX |
| Others |
Pricing and Supply Chain Analysis
Epoxy resin and aluminum ingot price indices cascade through luminaire manufacturing into three-tier pricing structures across premium, standard, and economy levels. LED driver IC foundry costs in Taiwan and South Korea transmit volatility into UK assembler margins, while Building Regulations Part L compliance tiers stratify buyer willingness to pay across commercial retrofit segments.
Pricing Analysis
Capacity additions in China's LED packaging sector are reshaping price floors for mid-market linear luminaires serving England's regional city retrofits. Three-tier pricing separates connected platform providers from component assemblers from import distributors, with efficacy certification grade and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from electrical contractor margin compression in Birmingham and Manchester, where installation bottlenecks force luminaire vendors to absorb logistics costs. Residential developers exhibit highest price sensitivity, while NHS trusts and London REITs prioritize circadian specification over unit economics.
Supply Chain Analysis
Post-Brexit Rules of Origin requirements are reshaping sourcing patterns for UK-based luminaire assemblers previously dependent on Dutch distribution hubs. LED chip supply concentrates in Taiwan, South Korea, and China, with COB substrates and driver ICs drawing from concentrated Asian foundry capacity. Aluminum heat sinks, polycarbonate diffusers, and copper winding wire constitute critical raw material dependencies. Single-source vulnerability in semiconductor substrates exposes UK manufacturers to extended lead time risk. Distribution runs through electrical wholesale networks anchored at Scolmore, CEF, and Rexel, with direct-to-contractor channels gaining share among connected lighting platform providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK indoor LED lighting market represents a late-cycle quality transition where MEES compliance deadlines and circadian specification demand are elevating premium product mix across commercial retrofit. Buyers increasingly prioritize sensor-integrated platforms over basic efficacy upgrades, compressing margins for undifferentiated assemblers.
For Market Incumbents: Extend connected lighting service revenue through lighting-as-a-service contracts that decouple capital expenditure from municipal and educational procurement cycles. Defend specification relationships with M&E contractors in England's regional cities by embedding daylight-responsive control compliance into standard product configurations. Vertical integration into driver IC sourcing mitigates Taiwan foundry concentration risk threatening margin stability. For New Entrants and Emerging Players: Launch via circadian lighting specialization targeting NHS trust new-builds and private healthcare facilities in southern England where melanopic output adjustment commands specification premium. Penetrate Welsh municipal estates through lighting-as-a-service models that align with devolved government procurement frameworks. White-space opportunity concentrates in architectural retrofit for heritage buildings where rapid customization capabilities displace standard product catalogs. For Investors and Strategic Acquirers: Consolidation pressure builds where electrical contractor capacity constraints in regional cities compress retrofit specialist margins below sustainable thresholds. Five-to-ten year viability favors platform providers with recurring software revenue attachment over component assemblers exposed to Asian supply volatility. Acquisition target archetype: British manufacturers with rapid customization capabilities and established specifier relationships in commercial retrofit. Signal to watch: MEES enforcement tightening accelerating landlord portfolio consolidation and centralized procurement authority.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Platform Integration | Sensor-integrated luminaires with wireless mesh protocols capture recurring service revenue from REITs. |
| Circadian Specification Development | Tunable white systems with melanopic adjustment penetrate NHS trusts and London financial district offices. |
| Lighting-as-a-Service Model Deployment | Operational expenditure structures unlock municipal and education sector procurement previously constrained by capital budgets. |
| Rapid Customization Capability Investment | British manufacturing specialists defend architectural specification relationships against standardized import competition. |
| Electrical Contractor Channel Partnership | Direct specification influence with M&E contractors in Birmingham and Manchester secures retrofit volume allocation. |
Research Methodology
Bottom-up commercial retrofit modeling reconciled against top-down LED component import tracking forms the analytical core of this study. Primary interviews with electrical contractors, M&E specifiers, REIT asset managers, NHS estates directors, and luminaire procurement officers combined with secondary validation from BEIS policy frameworks, MHCLG Building Regulations guidance, BSI standards documentation, and UK trade customs data. Triangulation across stakeholder input and regulatory filings ensures demand-side and supply-side estimates converge.
Historical retrofit installation trends and efficacy standard evolution informed projection framework development across the analysis window. Segmentation dimensions modeled include product type, technology integration depth, end-user budget authority, and installation regulatory timing. CAGRs derived from fitting trendlines to disclosed project pipelines and landlord compliance deadline clustering. Industry-specific forecast inputs incorporate MEES enforcement trajectory and Future Homes Standard consultation outcomes.
Several conditions sit outside the modeled scope, including potential semiconductor trade policy shifts, unannounced regulatory timeline accelerations, and macroeconomic disruptions to commercial property investment. Forecasts reflect documented assumptions about compliance enforcement consistency and contractor capacity expansion rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Xenon Market
LED
Africa LED Lighting Market
LED
Russia LED Market
LED
Linear LED Strip Fixture Market
LED
Europe Outdoor LED Lighting Market
LED
UAE LED Lights Market
LED
China Outdoor LED Lighting Market
LED
Middle East LED Lighting Market
LED
LED Control Unit Market
LED
Organic Light Emitting Diode (OLED) Market
LED
Four-Digit 7 Segment LED Displays Market
LED
Mini LED Display Market
LED
Germany Outdoor LED Lighting Market
LED
North America LED Packaging Market
LED
Global LED Phosphor Market
LED
Microled Market