
 North America Commercial LED Lighting Market | 2026-2036
North America Commercial LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
North America Commercial LED Lighting Market Analytics
The US Department of Energy's Appliance and Equipment Standards Program is hardening minimum efficacy requirements for commercial luminaires, compelling facility managers to accelerate LED retrofit timelines. Cree Lighting leverages vertical integration in silicon carbide substrates to sustain cost leadership in high-bay industrial segments. Signify Holding anchors its North American position through direct channel control over large-scale commercial and healthcare retrofit projects.
North America Commercial LED Lighting encompasses solid-state illumination systems utilizing semiconductor diodes emitting visible light when electrical current passes through p-n junctions, typically operating at correlated color temperatures between 2700K and 6500K with system efficacies exceeding 130 lumens per watt for commercial-grade products. These systems serve primarily to reduce energy consumption and maintenance cycles in commercial buildings while enabling granular controls integration. Tubes and panels dominate installed value in office and retail retrofit applications where T8 fluorescent replacement drives volume. Warehouses and industrial sites represent the fastest-growing application segment as high-bay LED systems displace metal halide and fluorescent technologies in fulfillment centers.
The US Department of Energy and Natural Resources Canada jointly shape product eligibility through the ENERGY STAR and DesignLights Consortium qualification programs, which filter market access for utility rebate programs across US states and Canadian provinces. California's Title 24 Building Energy Efficiency Standards impose mandatory daylighting and controls requirements that exceed federal minimums, creating a regulatory laboratory for advanced LED controls adoption. Stakeholders must monitor divergence between federal efficacy rollbacks and state-level building code advancement when allocating R&D and certification budgets.
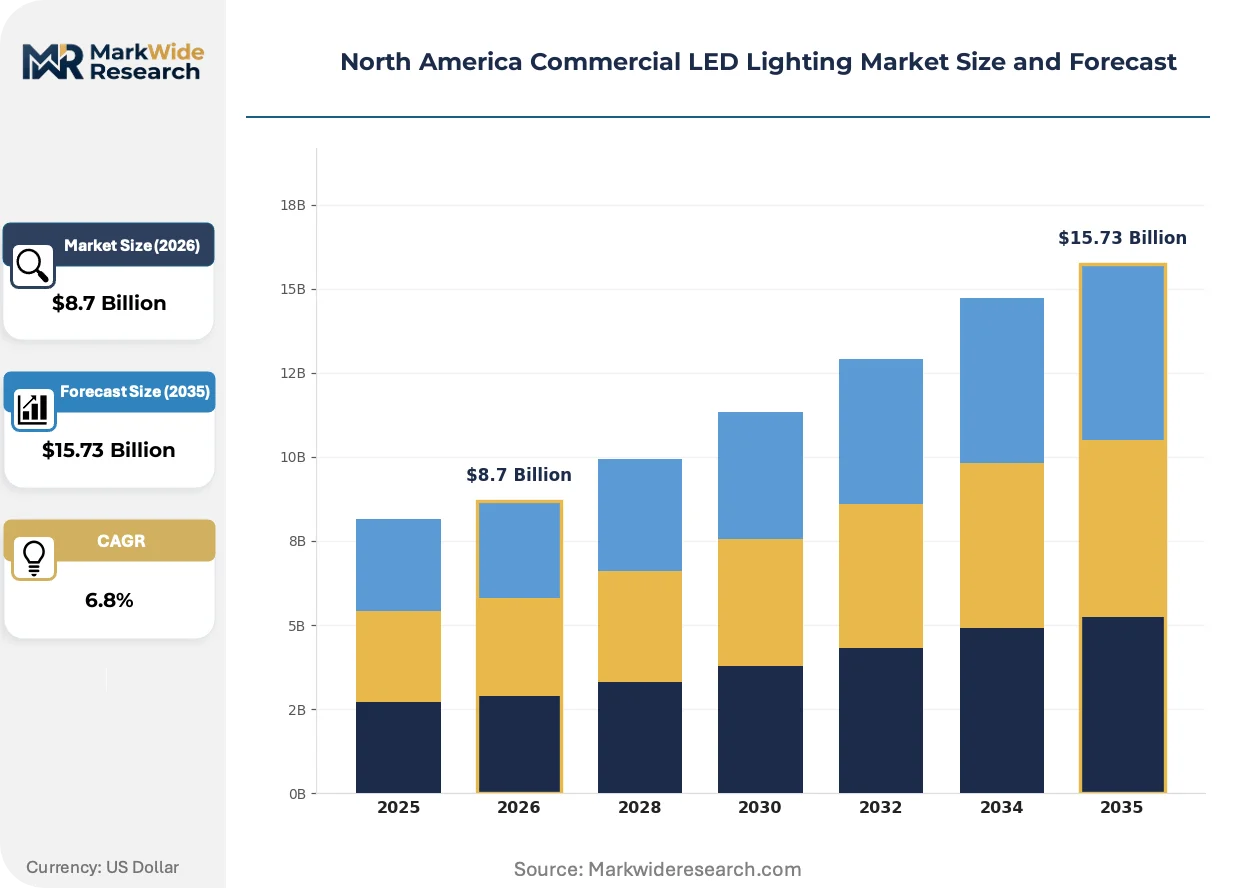
Market Dynamics
Corporate retrofit programs across office portfolios are compressing replacement cycles as facility managers confront the US Department of Energy's tightening efficacy minimums for linear fluorescent replacements. The regulatory pressure is accelerating capital deployment toward solid-state systems that satisfy California's Title 24 jurisdictions where building code stringency exceeds federal baselines.
Growth Catalysts
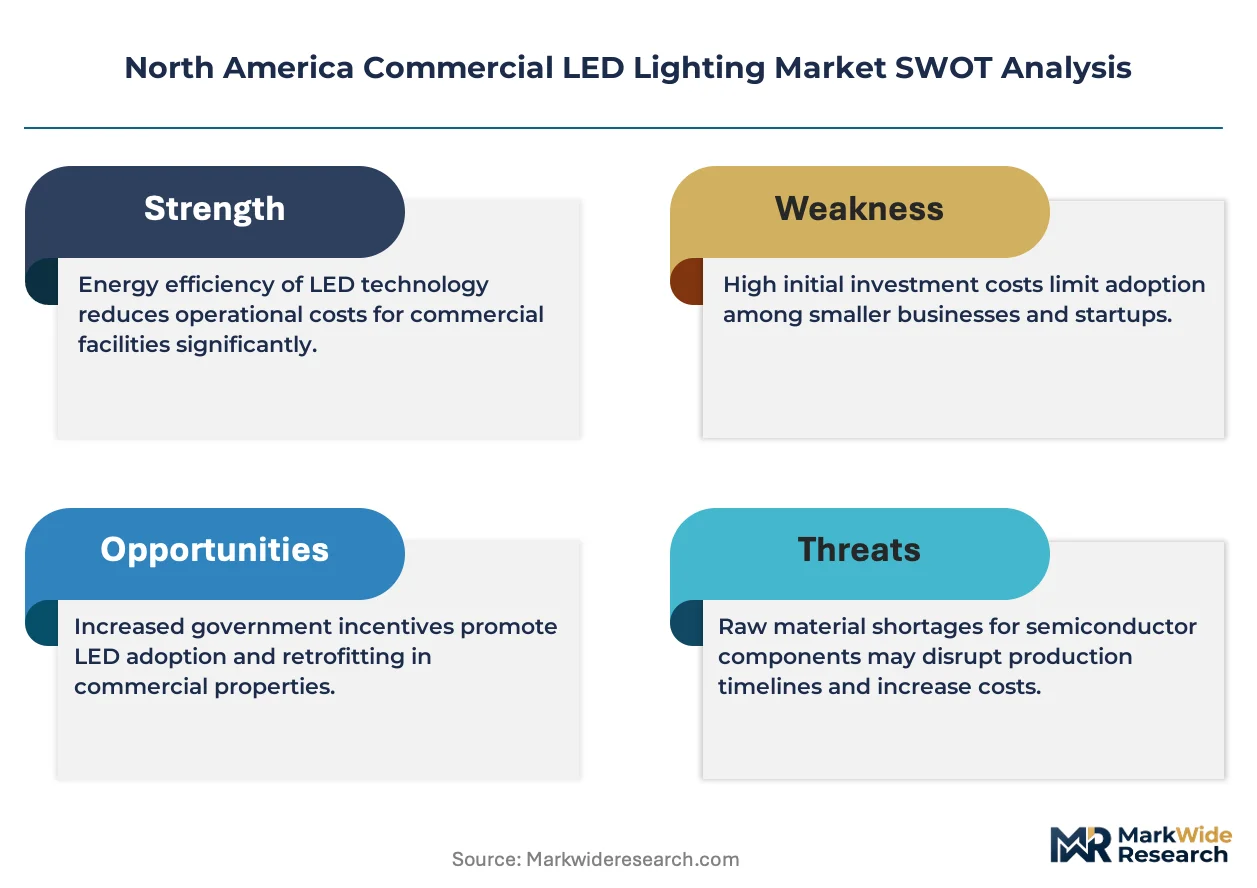
- Utility Rebate Programs:ENERGY STAR and DesignLights Consortium qualification frameworks channel utility incentives across US states and Canadian provinces, lowering effective installed costs for commercial-grade LED retrofits.
- Warehouse Automation Demand:Fulfillment center operators are displacing metal halide and fluorescent high-bay systems with LED arrays to reduce maintenance cycles in 24/7 logistics environments.
- Silicon Carbide Substrate Advances:In-house production of wide-bandgap semiconductor materials is compressing driver costs and thermal management overhead for industrial luminaire manufacturers.
Market Restraints
- Rare Earth Element Concentration:Phosphor supply chains concentrate in Chinese processing facilities, exposing North American fixture assemblers to input cost volatility and export restriction risk.
- Legacy Ballast Infrastructure:Millions of commercial buildings retain magnetic and electronic ballast systems that require complete rewiring for LED tube compatibility, extending payback periods.
- Interstate Regulatory Divergence:The US Department of Energy's efficacy rollbacks clash with California Title 24 advancement, fragmenting product certification requirements and R&D allocation decisions.
Strategic Opportunities
- Healthcare Facility Modernization:Circadian lighting systems with tunable white capability are penetrating hospital and long-term care environments where patient outcomes drive specification.
- Integrated Controls Convergence:LED platforms are merging with building automation and IoT sensor networks, enabling occupancy-based dimming and daylight harvesting in smart building deployments.
- Mexican Manufacturing Expansion:Assembly operations are relocating to Mexican industrial corridors to access USMCA tariff advantages and reduce landed costs for North American distribution.
Industry Challenges
- Controls Integration Complexity:Facility engineering teams lack proficiency in commissioning networked lighting management systems, delaying project completion and utility incentive capture.
- Dual Certification Burden:Manufacturers must maintain parallel UL and CSA testing protocols for US and Canadian markets, extending product launch timelines and compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Commercial LED Lighting Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tubes, Panels, Downlights, Highbays Application: Office Spaces, Retail Environments, Warehouses, Hospitality Installation: New Construction, Retrofit, Renovation, Upgrade End User: Commercial Buildings, Educational Institutions, Healthcare Facilities, Industrial Sites |
| Companies Covered | Cree Lighting, OSRAM Licht AG, Signify Holding, Current Lighting Solutions LLC, US LED Ltd., Acuity Brands Inc., Dialight PLC, Zumtobel Group, Hubbell Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Commercial LED Lighting Market Evolving Landscape
Human-centric and circadian lighting specifications are penetrating commercial specifications as building owners prioritize occupant wellness metrics alongside energy savings. The convergence of solid-state illumination with sensor networks and building automation platforms is redefining how lighting systems deliver value beyond illumination.
Li-Fi visible light communication technology is integrating optical wireless data transmission into commercial LED fixtures, enabling high-bandwidth connectivity in radio-frequency-restricted environments such as hospitals and aircraft manufacturing facilities. Defense contractors and healthcare systems are piloting installations where electromagnetic interference precludes Wi-Fi deployment. The technology is integrating security-sensitive networking capability into existing lighting infrastructure without additional cable runs.
The US Department of Energy's Appliance and Equipment Standards Program is hardening minimum efficacy requirements for commercial luminaires, compelling manufacturers to redesign optical systems and thermal management architectures. Natural Resources Canada maintains alignment through harmonized ENERGY STAR specifications, preserving cross-border product fungibility. Linear fluorescent replacement categories face the most immediate compliance pressure as efficacy floors ratchet upward.
Facility managers are consolidating vendor relationships and demanding extended warranty and performance guarantees from single-source lighting providers. The traditional split between fixture procurement and controls specification is collapsing as owners seek unified accountability for system-level energy outcomes. Healthcare and education verticals in California and New York are most advanced in adopting outcome-based contracting models that tie payments to measured energy reduction.
North America Commercial LED Lighting Market Segmentation
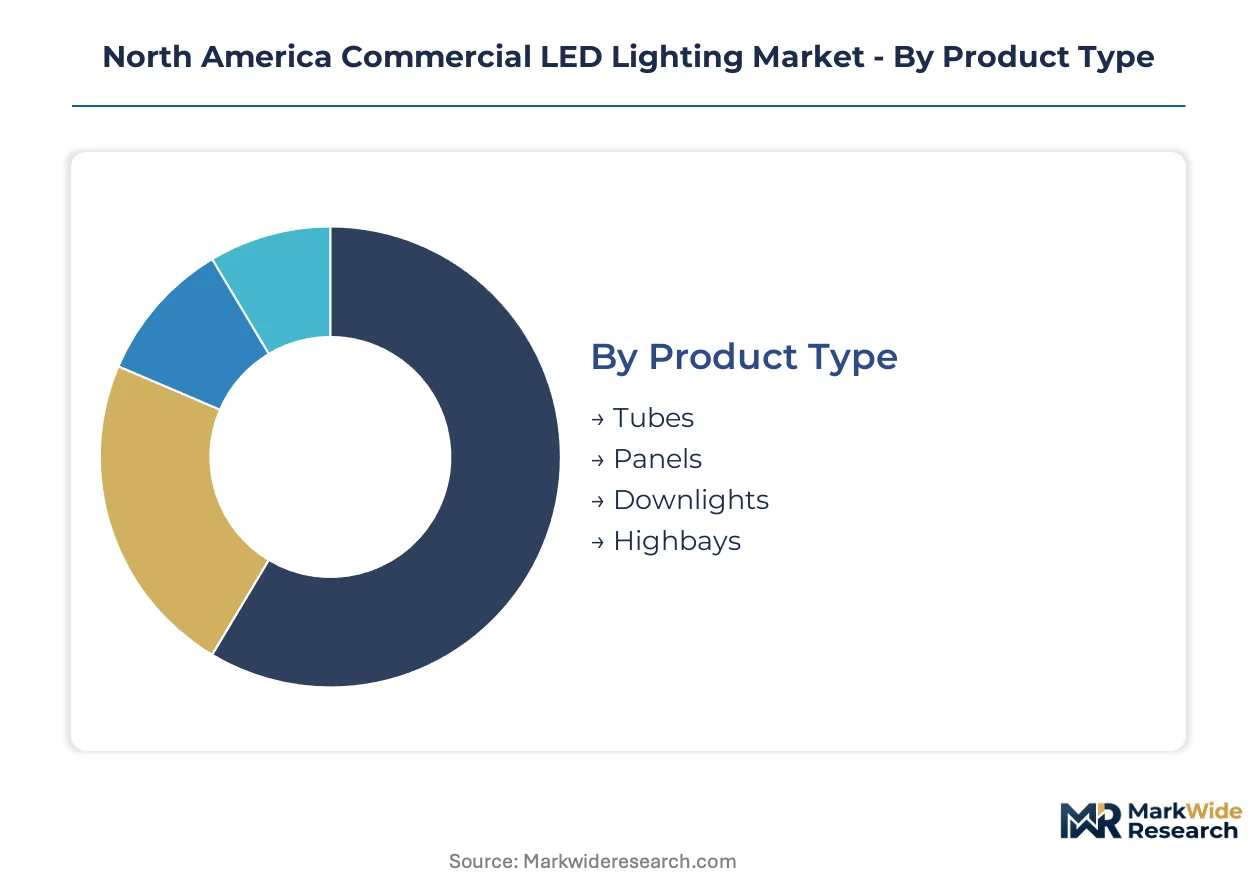
Commercial LED lighting procurement in North America fragments across four structural dimensions that determine specification requirements, rebate eligibility, and installation complexity. Each segmentation axis carries distinct certification burdens and channel access rules that shape vendor positioning.
Product Type:
ENERGY STAR and DesignLights Consortium qualifications apply differentially across form factors, with high-bay industrial products facing the most stringent thermal and photometric testing protocols.
- Tubes:Linear LED tubes designed for T8 and T5 fluorescent retrofit operate at system efficacies above 130 lumens per watt with integrated drivers eliminating external ballast dependency. Demand concentrates in California office portfolios where Title 24 mandates accelerated replacement timelines and utility rebate programs lower effective installed costs.
- Panels:Recessed troffer replacements utilizing edge-lit or direct-backlit LED arrays deliver uniform illumination for dropped ceiling grids in commercial interiors. Procurement clusters in healthcare and education verticals where circadian lighting specifications and tunable white capability drive premium specification.
- Downlights:Compact ceiling-recessed luminaires for accent and general illumination in retail and hospitality environments.
- Highbays:Industrial-grade fixtures for warehouse and manufacturing bay lighting with specialized thermal management for high-ambient-temperature operation.
Leading the category by volume: Tubes. Growing fastest: Highbays.
Application:
End-use environments impose divergent controls integration requirements, with warehouses and offices driving the steepest specification divergence.
- Office Spaces:Open-plan and private office deployments prioritize glare control and networked dimming compatibility with building automation systems. California and New York building codes mandate daylight harvesting and occupancy-based controls that exceed federal minimums, compressing replacement cycles in Class A commercial portfolios.
- Warehouses:High-ceiling logistics and distribution facilities require high-bay arrays with motion-sensing activation and 24/7 operational durability. Fulfillment center operators across the US Midwest and Southeast are displacing metal halide systems to reduce maintenance cycles in automated storage environments.
- Retail Environments:Merchandise display and ambient lighting for brick-and-mortar stores with color rendering index requirements above 90.
- Hospitality:Hotels, restaurants, and entertainment venues requiring dim-to-warm and decorative form factor flexibility.
Dominant by project count: Office Spaces. Steepest expansion trajectory: Warehouses.
Installation:
Project delivery mode determines contractor specialization requirements and utility incentive capture timing, with retrofit commanding distinct electrical licensing protocols.
- Retrofit:Fixture replacement within existing electrical infrastructure without structural modification, typically leveraging existing ceiling grids and conduit runs. Demand concentrates in 1990s-era commercial buildings across the US Sun Belt where original fluorescent installations face simultaneous burnout and efficacy non-compliance.
- New Construction:Integrated LED specification during building erection with native controls wiring and daylighting co-design.
- Renovation:Comprehensive space reconfiguration with modified ceiling planes and relocated electrical distribution.
- Upgrade:Partial system enhancement targeting specific performance deficiencies or code compliance gaps.
Highest volume segment: Retrofit. Fastest-growing modality: New Construction.
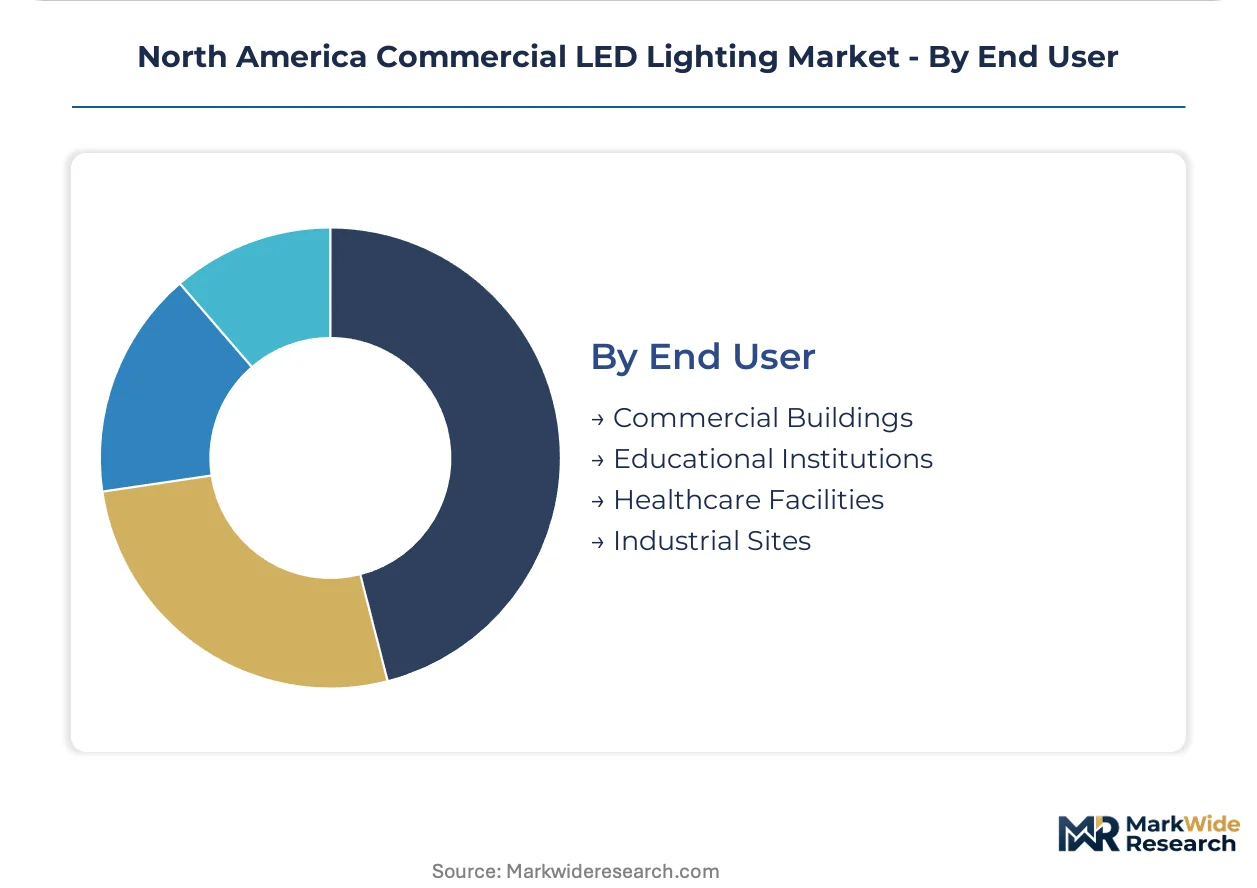
End User:
Institutional procurement operates through distinct specification channels—healthcare via group purchasing organizations, education via state cooperative contracts—that filter vendor access.
- Commercial Buildings:Owner-occupied and multi-tenant office, retail, and mixed-use properties where facility managers balance capital constraints against utility incentive capture. Corporate sustainability mandates across Fortune 500 portfolios are compressing payback threshold requirements and accelerating LED deployment in Class B and C assets.
- Healthcare Facilities:Hospitals and long-term care environments requiring circadian lighting systems with tunable white capability tied to patient outcome metrics. Group purchasing organization contracts and infection control specifications create high barriers to vendor entry in this vertical.
- Educational Institutions:K-12 and higher education facilities procuring through state cooperative purchasing agreements with extended warranty requirements.
- Industrial Sites:Manufacturing and processing facilities with hazardous location ratings and high-ambient-temperature operating conditions.
Largest addressable base: Commercial Buildings. Expanding most quickly: Healthcare Facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North American LED fixture assembly concentrates in Mexican industrial corridors and select US manufacturing zones, while consumption patterns diverge sharply between California's code-stringent jurisdictions and federal-baseline states. The region's regulatory fragmentation—California Title 24 versus DOE federal standards—shapes cross-border production and certification strategies.
United States
Corporate retrofit programs across Sun Belt office portfolios are accelerating T8 fluorescent replacement cycles as facility managers confront DOE efficacy minimums. The Department of Energy's Appliance and Equipment Standards Program tightens compliance thresholds for linear luminaires, compelling redesign of optical and thermal systems. California's Title 24 jurisdictions exceed federal baselines, creating a regulatory laboratory for advanced controls adoption in Los Angeles and San Francisco commercial corridors.
Canada
Natural Resources Canada harmonizes ENERGY STAR specifications with US frameworks, preserving cross-border product fungibility for Ontario and Quebec building stock. Provincial utility rebate programs channel incentives through DesignLights Consortium qualification, lowering installed costs for Toronto and Vancouver retrofit markets. Canadian healthcare systems in Ontario are piloting circadian lighting specifications tied to patient outcome metrics.
Mexico
Assembly operations are relocating to Nuevo León and Baja California industrial corridors to access USMCA tariff advantages and reduce landed costs for North American distribution. Mexican manufacturing serves high-bay industrial segments destined for US fulfillment centers. The country's proximity to Texas logistics hubs supports just-in-time delivery for warehouse automation retrofit demand.
North America Commercial LED Lighting Market Competitive Landscape
The competitive structure tilts toward diversified electrical conglomerates with controls integration capabilities. Market concentration remains moderate, with tier-one players commanding specification influence in healthcare and education verticals while regional specialists capture retrofit volume. Three archetypes dominate: silicon carbide substrate integrators pursuing cost leadership in industrial segments, controls-integrated platform providers, and Mexico-based assembly specialists leveraging tariff arbitrage. Capacity expansion and strategic partnerships represent the dominant competitive vectors as vendors seek unified accountability for system-level energy outcomes.
Among diversified lighting conglomerates, Acuity Brands Inc. and Hubbell Inc. exemplify the controls-integrated platform model, while Signify Holding occupies a position anchoring direct channel control over large-scale commercial retrofit projects. Cree Lighting represents the substrate-integrated cost leadership archetype through captive silicon carbide supply. Current Lighting Solutions LLC and Dialight PLC sit within the industrial-specialist tier targeting high-bay warehouse automation demand.
| Leading Market Players |
|---|
| Cree Lighting |
| OSRAM Licht AG |
| Signify Holding |
| Current Lighting Solutions LLC |
| US LED Ltd. |
| Acuity Brands Inc. |
| Dialight PLC |
| Zumtobel Group |
| Hubbell Inc. |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up specialists in commercial lighting assembly anchor pricing discipline through consolidated procurement leverage while simultaneously compressing supplier payment terms, tightening working capital cycles across the North American distribution network.
Pricing Analysis
Margin tightening in standard-grade LED tubes reflects silicon carbide substrate cost pass-through from captive suppliers. Three-tier pricing structure across premium, standard, and economy levels separates DesignLights Consortium-qualified fixtures from basic retrofit tubes from unlabeled imports. California Title 24 compliance premiums widen price spreads as utility rebate capture depends on certification tier. Warehouse operators exhibit lowest price sensitivity due to maintenance cycle value, while small commercial retrofit contractors face acute cost-down pressure.
Supply Chain Analysis
Single-source vulnerability sits with Chinese rare earth phosphor processing facilities that feed North American LED component fabrication. Driver electronics and thermal management assemblies draw from Mexico, China, and Taiwan, while finished luminaire assembly concentrates in Nuevo León and Baja California corridors. Tariff exposure under USMCA rules of origin creates compliance overhead for cross-border component flows. Distribution runs through electrical wholesale cooperatives and direct specification channels to large commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon carbide wafer capacity constraints prop fixture pricing as substrate supply fails to match retrofit demand acceleration across US Sun Belt office portfolios.
For Market Incumbents: Acquire circadian lighting controls IP to defend specification position against building automation integrators encroaching on healthcare verticals. Expand captive silicon carbide substrate capacity in US manufacturing zones to offset Chinese phosphor supply risk. Deepen backward integration into driver electronics to capture margin compression from Mexican assembly competitors. For New Entrants and Emerging Players: Direct-to-contractor digital platforms bypass incumbent specification lock-in among mid-size commercial retrofit projects. Target Class B office buildings in Texas and Florida where Title 24 stringency remains absent and price competition dominates. Lead with pay-for-performance financing that ties payments to measured energy reduction outcomes. For Investors and Strategic Acquirers: Distressed-cycle entries favor Mexico-based assembly specialists with USMCA tariff qualification and established big-box retail channel relationships. Five-to-ten year viability hinges on controls integration capability rather than commodity fixture volume. Watch for California Title 24 adoption spreading to Washington and New York as the inflection signal for premium specification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Substrate Integration | Cree Lighting's captive wafer supply compresses thermal management costs for high-bay industrial segments. |
| Direct Channel Control Expansion | Signify Holding's large-scale retrofit project ownership locks out specification competitors in healthcare verticals. |
| USMCA Manufacturing Relocation | Mexican assembly corridors reduce landed costs for Midwest fulfillment center automation demand. |
| Controls Platform Convergence | Acuity Brands merges LED fixtures with building automation networks for smart building deployments. |
| Circadian Lighting Certification | Healthcare GPO contracts require tunable white capability tied to patient outcome metrics. |
Research Methodology
Independent corroboration across facility managers at Fortune 500 commercial portfolios, electrical contractor purchasing directors, and utility rebate program administrators underwrites the qualitative findings. Primary fieldwork encompassed specification interviews with healthcare GPO contract managers, lighting controls integrators, and Mexican assembly plant operations leads. Secondary validation drew from US Department of Energy efficacy standard filings, DesignLights Consortium qualified products lists, California Title 24 compliance documentation, and ENERGY STAR certification databases. Bottom-up volume estimates from utility rebate redemption data triangulate against top-down construction spending forecasts.
Rate-of-change decomposition separates volume growth from price realization across the projection horizon. Segmentation modeling spans product form factor, application environment, installation modality, and end-user procurement channel. CAGRs derive from regression analysis against commercial construction permits, retrofit replacement cycle data, and efficacy standard compliance deadlines. Industry-specific forecast inputs include silicon carbide substrate capacity expansion timelines and California Title 24 jurisdictional adoption patterns.
Inputs from utility rebate program administrators and Mexican manufacturing trade associations were available through the study window; gaps in private-label import volume data introduce uncertainty bands around economy-tier market share estimates. Forecasts reflect documented assumptions regarding federal efficacy standard enforcement continuity and USMCA tariff regime stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Mexico LED Lighting Market
LED
Vietnam LED Lighting Market
LED
US and Europe LED Lighting Market
LED
Philippines LED Market
LED
North America Outdoor LED Lighting Market
LED
OLED Blue Emitter Market
LED
LED Display Control Card Market
LED
Single-Digit 7 Segment LED Displays Market
LED
Superluminescent Diodes Market
LED
Linear LED Strip Fixture Market
LED
LED Digital Scoreboard Market
LED
Asia Pacific Indoor LED Lighting Market
LED
Monochrome Outdoor LED Display Market
LED
Global Outdoor LED Lighting Market
LED
Russia LED Market
LED
Dual-Digit 7 Segment LED Displays Market