
 China Outdoor LED Lighting Market | 2026-2036
China Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
China Outdoor LED Lighting Market Insights
The China outdoor LED lighting sector is restructuring around a widening gap between premium smart-connected systems and commodity replacement luminaires. OPPLE Lighting Co., Ltd. leverages its domestic distribution depth to dominate mid-tier municipal tenders across provincial capitals. NVC Lighting Holding Limited anchors its position through captive LED chip sourcing that insulates margin pressure. Signify N.V. competes on intelligent lighting platforms that integrate sensors and remote management for smart city deployments.
China outdoor LED lighting comprises solid-state luminaires utilizing gallium nitride chip-on-board arrays with typical efficacy exceeding 130 lumens per watt, engineered for roadway, landscape, and facade illumination in ambient temperatures from minus 40 to 50 degrees Celsius. Street lights command the largest installed base among product types, though architectural lights carry superior margin pools due to customization intensity and project-specific optics. Medium power ratings sustain the broadest addressable demand as municipalities balance lumen output with energy quota compliance under provincial efficiency mandates.
MEE enforces GB standards for luminous efficacy and electromagnetic compatibility that filter non-compliant imports from regional competitors. BIS-equivalent provincial quality bureaus conduct spot inspections that accelerate consolidation toward certified domestic manufacturers. SAMR monitors pricing conduct in utility-scale tenders to prevent below-cost bidding that degrades service life. Stakeholders must track how sub-national carbon intensity targets reshape procurement specifications before the next five-year planning cycle locks in technology pathways.
Market Dynamics
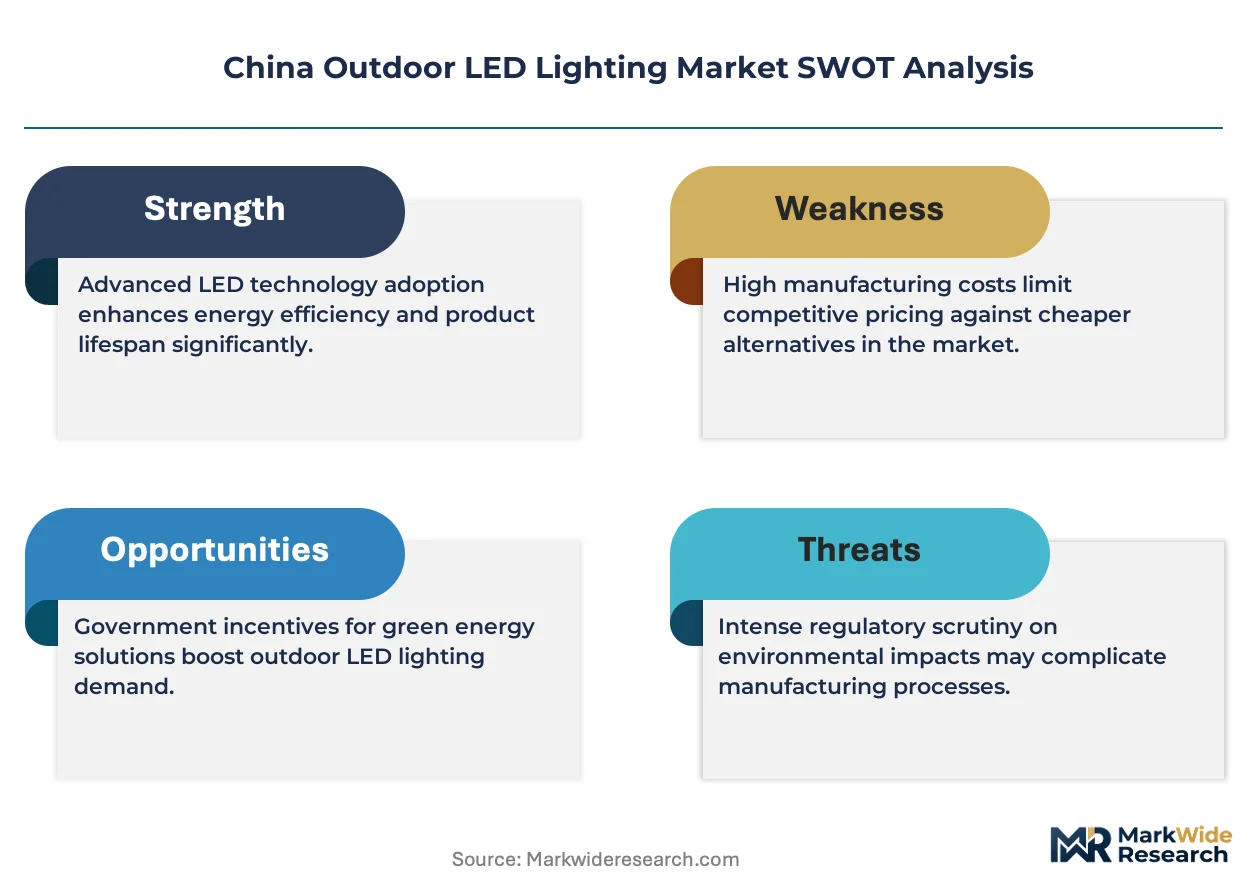
China's outdoor LED lighting sector is bifurcating around MEE-mandated carbon intensity targets that privilege networked, high-efficacy systems over conventional luminaires. Provincial efficiency quotas are forcing procurement offices to weight lifecycle metrics above upfront capital outlays.
Growth Catalysts
- Dual carbon goals:MEE enforcement of provincial carbon intensity targets compels municipal replacements of sodium vapor street lights with solid-state alternatives.
- Smart city infrastructure:Chengdu and Hangzhou deployments of sensor-integrated street lighting create anchor demand for networked control platforms.
- GB standards tightening:Luminous efficacy minimums above 130 lumens per watt filter non-compliant imports from Southeast Asian competitors.
Market Restraints
- Gallium nitride supply concentration:Domestic chip-on-board array production clusters in eastern coastal provinces, exposing procurement timelines to regional logistics bottlenecks.
- Sodium vapor installed base:Legacy street light infrastructure with 15-20 year service cycles delays replacement demand in inland municipalities.
- SAMR pricing oversight:Below-cost bidding investigations in utility-scale tenders constrain margin recovery for certified manufacturers.
Strategic Opportunities
- Central and western provinces:Subsidized efficiency retrofits in Sichuan and Shaanxi municipal budgets lag eastern penetration by 40-60 percentage points.
- Architectural facade integration:Custom optics for cultural heritage illumination command premium positioning absent in commodity street light tenders.
- Photovoltaic-street light convergence:Off-grid solar-LED hybrid systems align with rural electrification mandates in county-level jurisdictions.
Industry Challenges
- Optical engineering talent scarcity:Project-specific lens design for architectural applications requires photonics specialists concentrated in Shenzhen and Hangzhou clusters.
- Legacy control system integration:Municipal IT departments lack protocols to merge new networked luminaires with existing traffic management infrastructure.
- Provincial certification fragmentation:BIS-equivalent quality bureaus apply inconsistent electromagnetic compatibility testing timelines across eastern and central regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Outdoor LED Lighting Market |
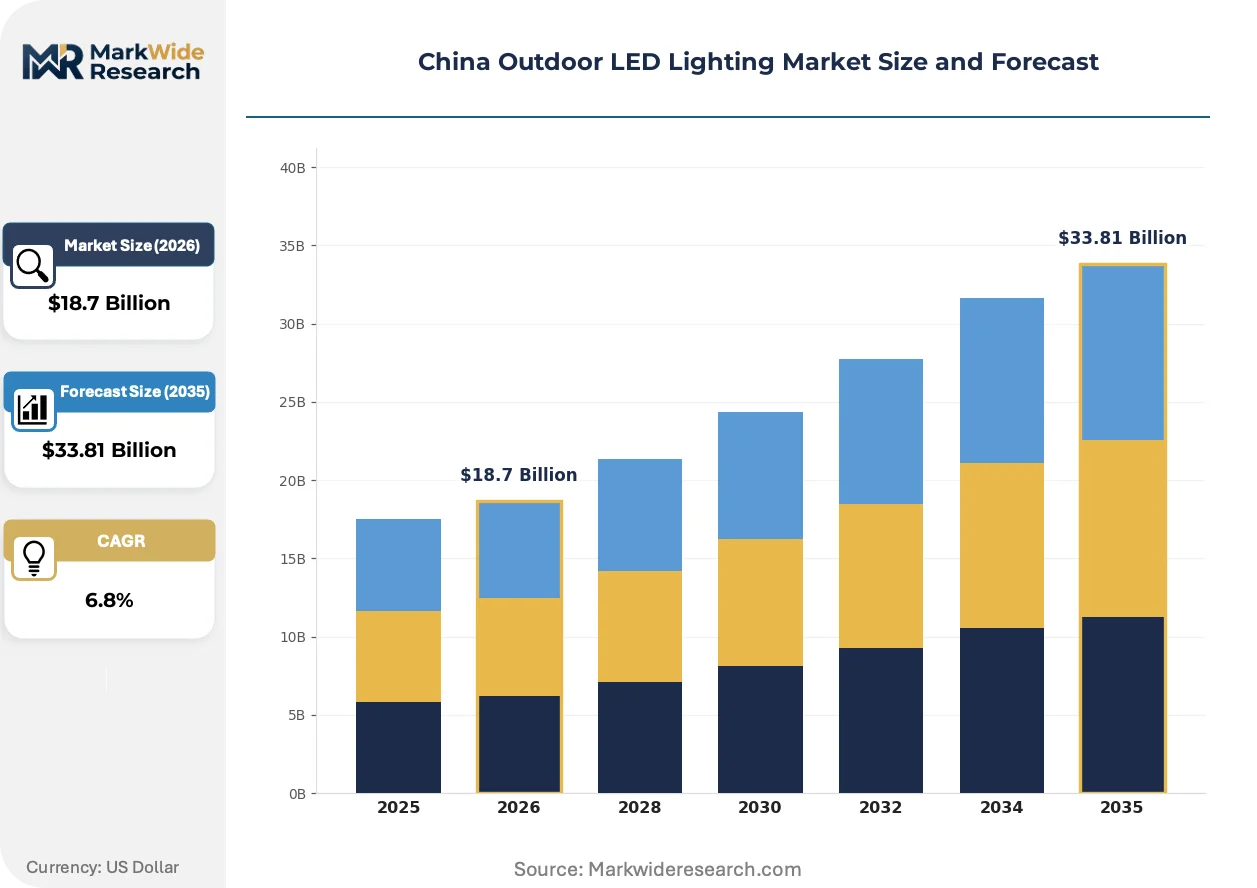
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, Garden Lights, Architectural Lights Installation Type: Fixed, Portable, Suspended, Embedded End User: Municipalities, Commercial Properties, Parks, Transportation Power Rating: Low Power, Medium Power, High Power, Ultra-High Power |
| Companies Covered | OPPLE Lighting Co., Ltd., NVC Lighting Holding Limited, Zhejiang Yankon Group Co., Ltd., Foshan Electrical and Lighting Co., Ltd., Signify N.V., Kingsun Optoelectronics, Sansi LED Holdings Company Ltd, COMLED Lighting, AGC Lighting, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Outdoor LED Lighting Market Trends and Innovations
Connected lighting platforms are compressing the traditional separation between luminaire hardware and municipal data infrastructure. Three developments are restructuring competitive requirements.
Chip-on-board LED arrays with integrated thermal management are unifying optical performance and heat dissipation in single-package designs. Municipal procurement offices in Jiangsu and Zhejiang are specifying these consolidated modules for new roadway installations. The technology is unifying what were previously separate supplier relationships for chips, drivers, and thermal components into single-source tenders.
MEE's GB standards for electromagnetic compatibility are tightening testing protocols for networked street lights with embedded sensors. Manufacturers must now certify simultaneous radio-frequency emission control and power quality compliance. Smart city deployments in first-tier municipalities face the steepest retesting burdens as they integrate traffic monitoring and environmental sensing into shared poles.
Municipal buyers are consolidating vendor lists around lifecycle service capabilities rather than hardware specifications alone. Provincial capitals now require 10-year maintenance commitments bundled with initial supply contracts. This preference shift is most visible in Shandong and Guangdong, where tender documents weight remote diagnostics and predictive replacement above lumen-per-watt metrics.
China Outdoor LED Lighting Market Segmentation
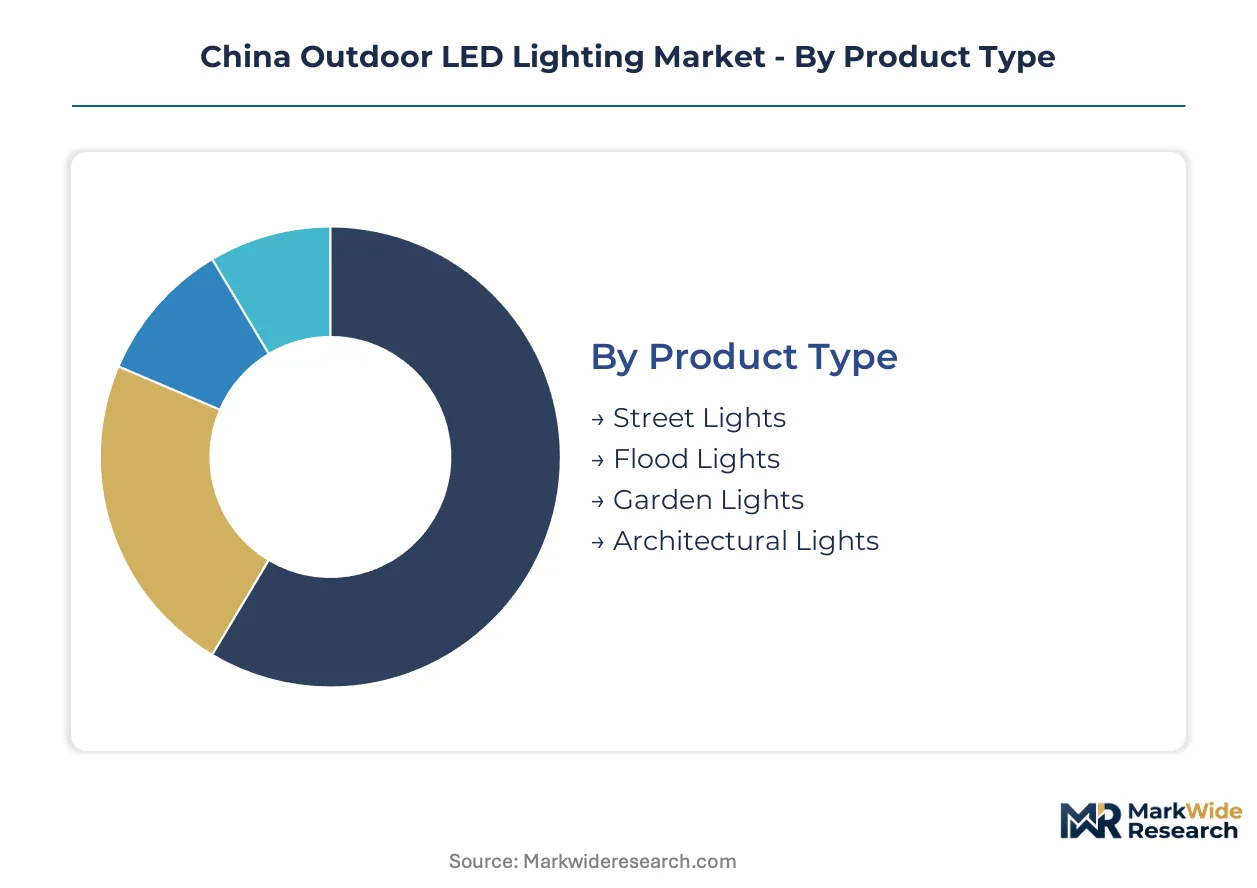
Segmentation in China's outdoor LED lighting market reveals divergent procurement logics across municipal, commercial, and institutional buyers. Each dimension—product configuration, mounting method, end-use application, and energy intensity—carries distinct margin profiles and compliance requirements under MEE efficiency mandates.
Product Type:
Standalone luminaires dominate procurement volumes, while embedded architectural systems command integration premiums with building management platforms.
- Street Lights:Gallium nitride chip-on-board arrays with efficacy exceeding 130 lumens per watt serve as the backbone of municipal dual carbon retrofit programs. Demand clusters in eastern coastal provinces where Jiangsu and Zhejiang procurement offices bundle networked controls with hardware supply.
- Architectural Lights:Custom optics and project-specific thermal engineering illuminate cultural heritage facades and commercial landmarks. Chengdu and Hangzhou smart city budgets allocate disproportionate sums to these installations for urban branding and tourism infrastructure.
- Flood Lights:High-output luminaires for sports venues and industrial perimeters prioritize lumen density over connectivity.
- Garden Lights:Low-wattage decorative fixtures populate residential developments and park pathways with minimal sensor integration.
Volume placements concentrate in Street Lights; the faster expansion belongs to Architectural Lights.
Installation Type:
Mounting configurations segment procurement by labor intensity and infrastructure compatibility, with cost tiers reflecting installation permanence.
- Fixed:Pole-mounted and wall-attached luminaires constitute the municipal standard for roadway and perimeter illumination. SAMR-monitored utility tenders in Shandong and Guangdong specify 10-year service commitments for these installations, bundling hardware with predictive maintenance obligations.
- Embedded:Recessed ground and facade-integrated fixtures demand specialized waterproofing and thermal management for seamless architectural incorporation. Sichuan and Shaanxi heritage district budgets show fastest uptake as county-level jurisdictions modernize cultural tourism infrastructure.
- Portable:Temporary construction and event lighting prioritizes rapid deployment over efficiency certification.
- Suspended:Catenary-mounted systems serve bridge crossings and pedestrian corridors with specialized structural engineering.
Fixed installations capture the dominant procurement volume; embedded systems are climbing the fastest as smart city integration deepens.
End User:
Buyer categories separate by funding source, compliance stringency, and lifecycle service expectations under provincial carbon intensity targets.
- Municipalities:City and county governments drive replacement demand through MEE-mandated sodium vapor phaseouts. Procurement offices in first-tier municipalities now weight remote diagnostics and predictive replacement above upfront capital metrics in tender evaluations.
- Transportation:Highway authorities and rail operators specify ruggedized luminaires for tunnel, platform, and roadway illumination with 24-hour operational duty cycles. GB standards enforcement for electromagnetic compatibility imposes retesting burdens on networked deployments with embedded traffic sensors.
- Commercial Properties:Retail and office developers balance aesthetic customization with energy quota compliance.
- Parks:Landscape and recreational lighting operates under lighter efficiency mandates with greater design flexibility.
Municipalities anchor procurement volume; Transportation infrastructure is gaining share fastest as interprovincial corridor development accelerates.
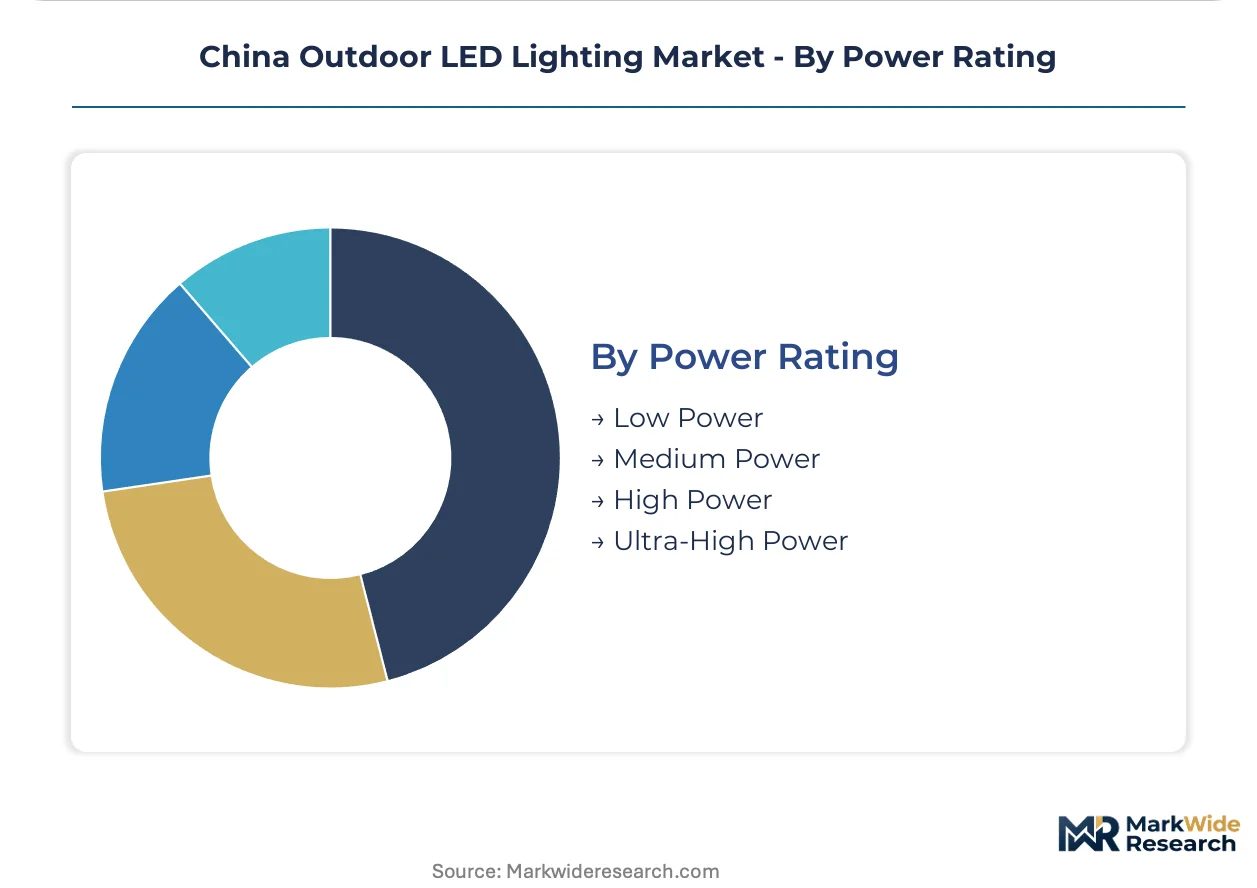
Power Rating:
Energy intensity tiers align with application scale and provincial efficiency quota structures, creating distinct supply relationships.
- Medium Power:Luminaires in the 50-150 watt equivalent range balance lumen output with energy quota compliance for standard roadway and perimeter applications. Eastern coastal provinces concentrate procurement as local governments combine subsidy access with stricter GB standards enforcement.
- High Power:Outputs exceeding 200 watts serve highway interchanges, industrial zones, and large-scale flood applications where lumen density overrides connectivity features. Central and western provincial budgets lag penetration by 40-60 percentage points, creating subsidized retrofit opportunities.
- Low Power:Sub-30 watt fixtures populate residential pathways and decorative installations.
- Ultra-High Power:Specialized sports venue and port illumination demands custom thermal engineering from concentrated Shenzhen and Hangzhou supplier clusters.
Medium Power ratings sustain the broadest addressable demand; High Power systems show the steepest expansion trajectory as inland municipalities advance efficiency retrofits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hangzhou anchors China's outdoor LED lighting demand through its smart city command center that networks 200,000 sensor-integrated luminaires. Municipal procurement offices in the Yangtze River Delta cluster award bundled contracts combining hardware supply with decade-long maintenance commitments.
Guangdong Province
Manufacturing gravity concentrates in Shenzhen and Foshan where chip-on-board array producers serve municipal retrofit programs. SAMR monitors utility-scale tenders to prevent below-cost bidding that degrades product longevity. The Pearl River Delta industrial corridor exports finished luminaires to Southeast Asian markets while absorbing gallium nitride supply from eastern coastal foundries.
Jiangsu Province
Nanjing and Suzhou procurement offices enforce GB standards above 130 lumens per watt in roadway replacement contracts. Provincial efficiency quotas compel sodium vapor phaseouts in county-level jurisdictions. The Yangtze River manufacturing belt hosts captive LED driver production that insulates municipal suppliers from component price volatility.
Zhejiang Province
Hangzhou and Ningbo smart city budgets allocate disproportionate sums to architectural facade illumination for urban branding. MEE-mandated carbon intensity targets accelerate networked control platform deployment. The province's photonics engineering talent pool concentrates in Hangzhou clusters serving project-specific optical design contracts.
Sichuan Province
Chengdu municipal procurement lags eastern penetration by 40-60 percentage points, creating subsidized retrofit opportunities under western development programs. County-level jurisdictions prioritize off-grid solar-LED hybrid systems for rural electrification compliance. The Sichuan-Chongqing economic zone attracts manufacturers seeking lower land costs than coastal competitors.
Shandong Province
Qingdao and Jinan tender documents weight remote diagnostics above upfront capital metrics in 10-year service contracts. Provincial quality bureaus conduct spot inspections that filter non-compliant imports from regional competitors. The Shandong Peninsula's port infrastructure facilitates component import for domestic assembly operations.
China Outdoor LED Lighting Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across China's outdoor LED lighting sector. Foundry-dependent players with captive gallium nitride supply anchor the mid-tier municipal tender segment. Asset-light specialists concentrate on architectural optics and smart city software integration. The vendor base fragments across three strategic archetypes: vertically integrated domestic conglomerates, foreign platform providers, and regional component assemblers. Dominant competitive moves include backward integration into chip-on-board production and geographic expansion into central and western provincial markets.
Within the domestic conglomerate tier, OPPLE Lighting Co., Ltd. and NVC Lighting Holding Limited exemplify scale-driven positioning through distribution depth across provincial capitals. Signify N.V. occupies a position representing foreign platform competition focused on intelligent lighting systems. Zhejiang Yankon Group Co., Ltd. anchors the regional specialist archetype with manufacturing concentration in the Yangtze River Delta. These three company types collectively illustrate how procurement consolidation around lifecycle service capabilities favors players with integrated supply chains and maintenance infrastructure.
| Leading Market Players |
|---|
| OPPLE Lighting Co., Ltd. |
| NVC Lighting Holding Limited |
| Zhejiang Yankon Group Co., Ltd. |
| Foshan Electrical and Lighting Co., Ltd. |
| Signify N.V. |
| Kingsun Optoelectronics |
| Sansi LED Holdings Company Ltd |
| COMLED Lighting |
| AGC Lighting |
| Others |
Pricing and Supply Chain Analysis
Gallium nitride wafer costs cascade through three distinct pricing tiers as chip-on-board arrays move from eastern coastal foundries to municipal procurement offices. MEE efficiency mandates compress margins on commodity luminaires while smart city bundles with decade-long service commitments sustain premium positioning.
Pricing Analysis
Lifecycle service contracts anchor value-based pricing for networked street lighting systems in Jiangsu and Zhejiang tenders. Pricing stratifies across premium smart-connected platforms, standard certified luminaires, and economy replacement sodium vapor alternatives based on GB standards compliance and remote diagnostics bundling. Cost compression in the economy tier intensifies as SAMR investigates below-cost bidding in utility-scale tenders. Municipal procurement offices show lowest price sensitivity for architectural facade systems with project-specific optics, while county-level roadway retrofits exhibit acute sensitivity to upfront capital outlays.
Supply Chain Analysis
Freight costs from Shenzhen and Hangzhou chip-on-board clusters to central and western provinces add 15-20% landed cost premiums versus eastern coastal delivery. Manufacturing concentrates in Guangdong, Jiangsu, and Zhejiang provinces where captive LED driver production insulates municipal suppliers from component volatility. The supply chain rests on gallium nitride substrates, aluminum thermal management housings, and networked control modules. Single-source vulnerability concentrates in eastern coastal photonics engineering talent pools. Distribution runs through provincial tender platforms that bundle hardware with installation and maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards players racing to capture upstream chip-on-board production or downstream lifecycle service infrastructure. Control over gallium nitride supply or predictive maintenance platforms separates consolidators from commodity assemblers.
For Market Incumbents: Deploy captive gallium nitride sourcing to offset margin compression from SAMR pricing oversight in Shandong and Guangdong tenders. Consolidate position by acquiring regional component assemblers in Sichuan and Shaanxi before western development subsidies attract new entrants. Threaten substitute pressure from solar-LED hybrid systems demands pre-emptive bundling of photovoltaic integration capabilities. For New Entrants and Emerging Players: The 40-60 percentage point penetration gap between eastern and central provinces creates entry space for certified manufacturers with provincial quality bureau relationships. Target county-level jurisdictions in Sichuan and Shaanxi with off-grid solar-LED hybrid offerings that bypass legacy sodium vapor infrastructure constraints. Go-to-market leverage rests on partnerships with western development program administrators who control subsidized retrofit budgets. For Investors and Strategic Acquirers: SAMR's expansion of below-cost bidding investigations into central province tenders is the leading indicator that consolidation will accelerate toward certified domestic manufacturers with integrated supply chains. Long-term viability favors players with backward integration into chip-on-board production and established maintenance infrastructure across provincial capitals. Acquisition screening should prioritize regional specialists in the Yangtze River Delta with GB standards certification depth. Watch for MEE's next five-year planning cycle locking in technology pathways as the definitive inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chip-on-Board Production | Captive gallium nitride supply insulates margin pressure from SAMR pricing oversight in utility tenders. |
| Smart City Platform Integration | Networked control bundling with hardware supply secures decade-long service commitments in Jiangsu and Zhejiang. |
| Western Provincial Market Expansion | Sichuan and Shaanxi subsidy programs lag eastern penetration by 40-60 percentage points. |
| Photovoltaic-LED Hybrid Development | Off-grid solar convergence aligns with rural electrification mandates in county-level jurisdictions. |
| Predictive Maintenance Infrastructure Buildout | Remote diagnostics capabilities weight above lumen-per-watt metrics in Shandong tender evaluations. |
Research Methodology
Regulatory filings from SAMR and MEE, provincial tender databases, and customs trade records formed the secondary backbone of this analysis. Primary fieldwork encompassed interviews with municipal procurement officers, photonics engineering directors, LED driver manufacturing plant managers, and smart city platform integration specialists. The research combined bottom-up volume modeling from county-level retrofit programs with top-down value triangulation against provincial efficiency quota budgets.
Historical trendline analysis of sodium vapor replacement cycles and smart city deployment trajectories informed the projection framework. Segmentation modeling spanned product configuration, mounting method, end-use application, and power rating tiers across the analysis window. CAGRs derived from installation base turnover rates and MEE-mandated carbon intensity compliance deadlines. Industry-specific inputs included GB standards enforcement timelines and provincial subsidy program allocations.
Underlying measurement precision varies by segment; street light volume data carries tighter precision than architectural luminaire project pipelines. Forecasts reflect assumptions about MEE regulatory continuity and provincial carbon quota enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
North America LED Packaging Market
LED
LED Floodlight Drivers Market
LED
LED Lighting Controllers Market
LED
Philippines LED Market
LED
GCC LED Lighting Market
LED
Global Industrial and Commercial LED Lighting Market
LED
Vietnam LED Lighting Market
LED
Gan Substrate Market
LED
Four-Digit 7 Segment LED Displays Market
LED
Saudi Arabia LED Lights Market
LED
Germany Automotive LED Lighting Market
LED
UAE LED Lights Market
LED
Japan Indoor LED Lighting Market
LED
Japan LED Lighting Market
LED
France Outdoor LED Lighting Market
LED
LED Display Market