
 Dot-Matrix LED Displays Market | 2026-2036
Dot-Matrix LED Displays Market Size, Share, and Industry Trends Forecast 2026-2036
Dot-Matrix LED Displays Market Analytics
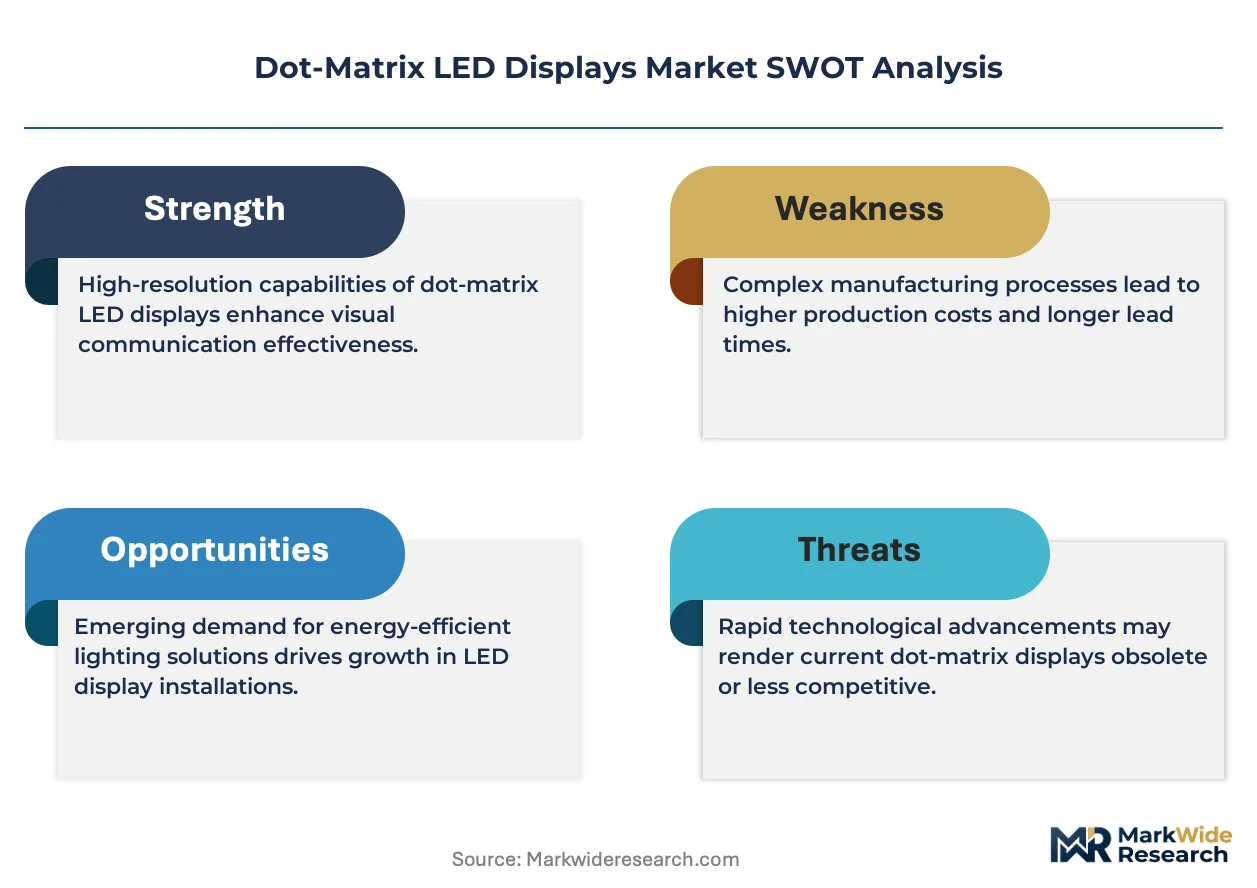
Project finance for municipal digital infrastructure is tilting competitive dynamics toward vendors with balance-sheet capacity to carry long-dated receivables. Daktronics, Inc. leverages its sports-venue specialization to anchor large installation contracts across North American stadiums. Panasonic Corporation sustains manufacturing scale in hybrid display architectures that serve dual indoor-outdoor specifications. Shenzhen Dicolor Optoelectronics Co., Ltd. competes on cost-engineered outdoor modules that dominate price-sensitive procurement cycles in emerging economies.
Dot-matrix LED displays are planar arrays of individually addressable light-emitting diodes arranged in a grid pattern, typically fabricated on printed circuit boards with pixel pitches ranging from coarse 20mm outdoor modules to fine 2mm indoor panels, driven by multiplexed row-column scanning circuits to render alphanumeric characters and low-resolution graphics. Their primary commercial purpose is delivering real-time, high-visibility information in ambient-light conditions where liquid-crystal alternatives wash out. Indoor displays and outdoor displays represent the mature volume base, with transportation displays recording the fastest application expansion as rail and bus agencies modernize passenger information systems. Scoreboards command premium margin pools due to sports-venue durability certifications and broadcast-color calibration requirements that standard signage cannot satisfy.
The U.S. Federal Communications Commission regulates electromagnetic emissions from digital display controllers, while the EU RoHS Directive restricts hazardous substances in LED module substrates, and China's GB standards mandate energy-efficiency labeling for public procurement of electronic display products. These frameworks collectively elevate compliance costs for module suppliers while advantaging vertically integrated manufacturers with in-house testing laboratories. Stakeholders must monitor how municipal sustainability mandates reshape specification requirements for outdoor installations in high-humidity coastal environments.
Market Dynamics
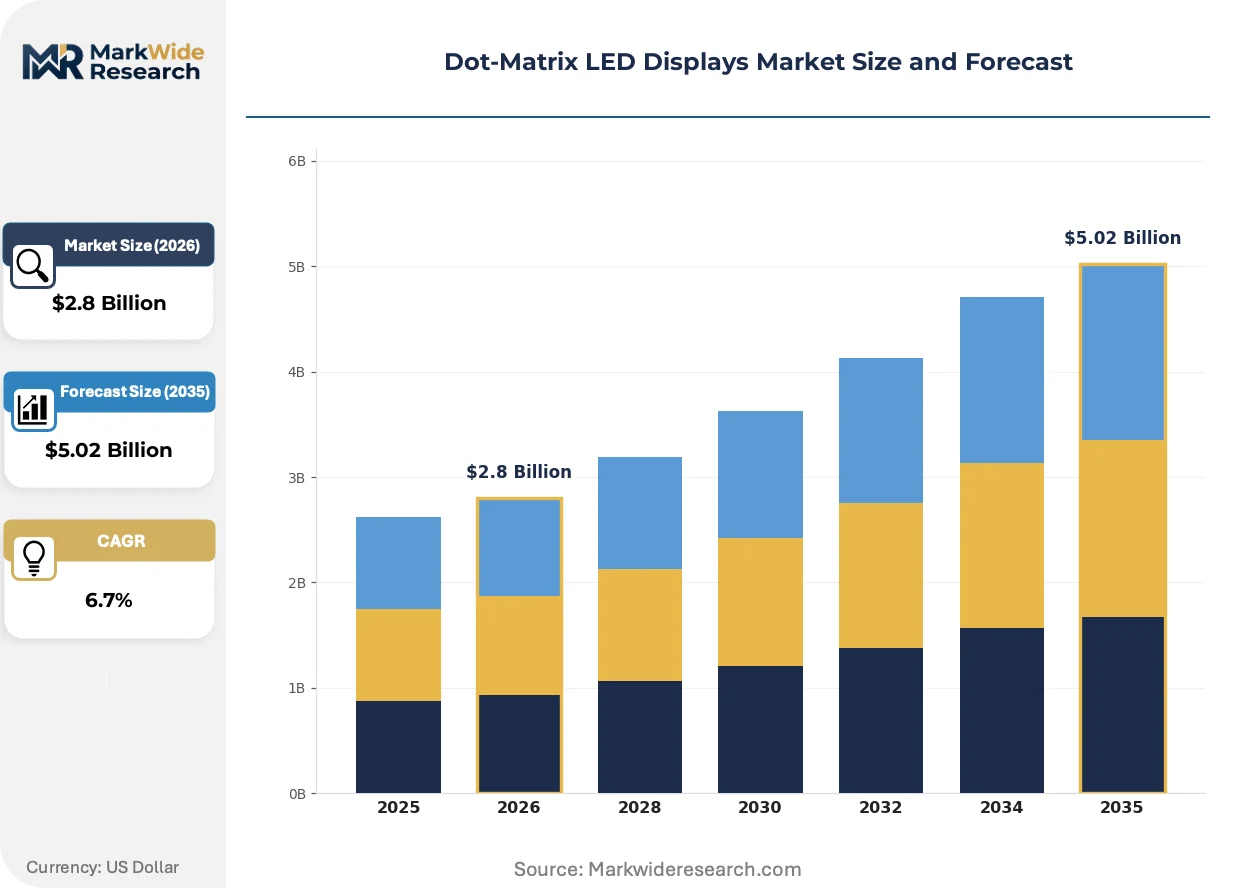
Municipal transit authorities are replacing static signage with networked digital displays, creating concentrated demand pools that favor vendors capable of financing multi-year installation contracts. This procurement transformation is redistributing margin capture toward system integrators with project finance capabilities.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency thresholds for public procurement are accelerating replacement cycles of legacy fluorescent-backlit displays across German and French transit networks.
- Outdoor transportation signage:Rail and bus agencies in India and Brazil are modernizing passenger information systems with IP-rated LED modules for platform arrival displays.
- Fine-pitch indoor manufacturing:Shenzhen and Guangzhou production clusters are achieving cost breakthroughs in sub-4mm pixel pitch modules for retail and corporate lobby applications.
Market Restraints
- Epoxy resin and copper substrate costs:PCB material input volatility compresses module assembler margins during commodity price spikes.
- Driver IC supply concentration:Taiwan and South Korea semiconductor foundries control multiplexing controller production, creating single-source vulnerability for mid-tier display manufacturers.
- Liquid-crystal price competition:Indoor LCD alternatives with LED backlighting satisfy brightness requirements at lower capital cost for climate-controlled environments.
Strategic Opportunities
- India smart city infrastructure:Municipal corporation tenders for urban command centers and transit hubs specify networked LED display networks with centralized content management.
- Stadium and arena scoreboard convergence:Hybrid indoor-outdoor specification modules serve dual broadcast-calibration and weather-resistance requirements from single supplier relationships.
- China GB standards energy labeling:Mandatory efficiency disclosure for public procurement creates first-mover advantage for certified manufacturers in government tender processes.
Industry Challenges
- Multiplexing firmware engineering talent:Row-column scanning algorithm optimization requires specialized embedded systems expertise concentrated in Shenzhen and Taipei labor markets.
- IP65/IP68 certification timelines:Outdoor module enclosure testing for dust and moisture ingress protection extends product development cycles by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dot-Matrix LED Displays Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Displays, Outdoor Displays, Transportation Displays, Scoreboards End User: Advertising, Sports Venues, Retail Stores, Concerts Technology: Analog, Digital, Hybrid, Wireless Application: Signage, Information Displays, Event Management, Traffic Control |
| Companies Covered | Barco N.V., Panasonic Corporation, EKTA, LG Electronics, Shenzhen Dicolor Optoelectronics Co., Ltd., Daktronics, Inc., Toshiba Corporation, Leyard Optoelectronic, HSC LED Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dot-Matrix LED Displays Market Evolving Landscape
Display controller architectures are migrating from proprietary closed systems to open-protocol networked platforms, enabling centralized content management across distributed municipal installations. This software-layer transformation is restructuring supplier value capture toward firmware and cloud-service providers.
Chip-on-board LED packaging is digitizing pixel-level thermal management by embedding driver circuits directly within the diode substrate. Transit authorities in Japan and South Korea are specifying these modules for underground platform displays where maintenance access is restricted. The technology is digitizing how municipalities contract for display infrastructure, shifting procurement toward performance-based service agreements with uptime guarantees.
The EU RoHS Directive's hazardous substance restrictions are forcing substrate material transitions in LED module manufacturing. Industrial consequence includes elevated compliance testing costs for imported products and accelerated adoption of lead-free solder processes. Chinese exporters to European markets are responding by establishing in-house analytical laboratories for substance verification.
Buyer organizations are consolidating vendor relationships through framework agreements that bundle hardware, installation, and decade-long maintenance. Systems integrators with balance-sheet capacity to carry long-dated municipal receivables are displacing pure hardware manufacturers in competitive tenders. This pattern is most visible in U.S. state transportation department procurements for highway variable message signs.
Dot-Matrix LED Displays Market Segmentation
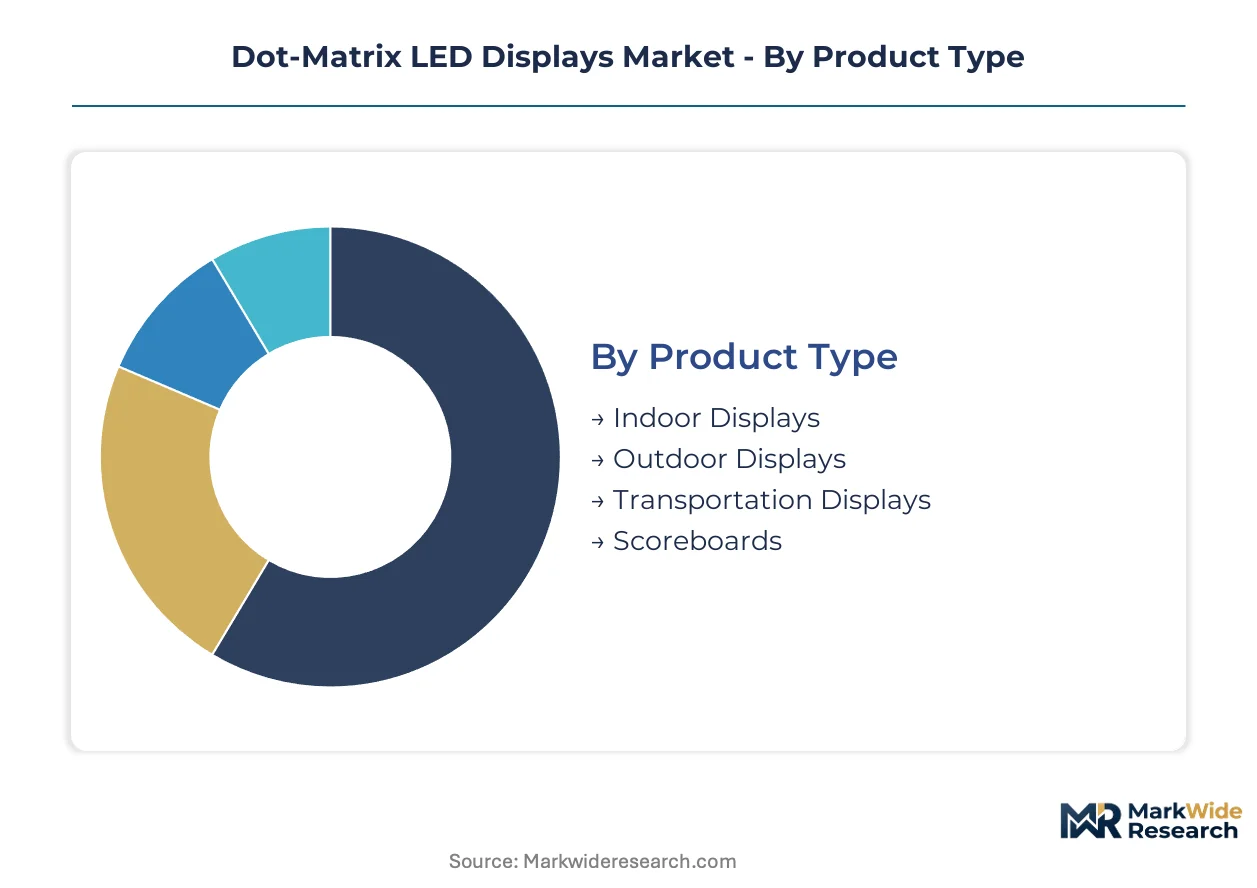
Dot-matrix LED display procurement patterns diverge sharply across deployment environments, with technical specifications and financing structures varying by use-case intensity. Understanding these segment boundaries clarifies why vendor capabilities in one category rarely transfer to adjacent markets.
Product Type:
Use-case spectrum spans climate-controlled interiors to weather-exposed infrastructure, with each tier demanding distinct enclosure engineering and thermal management.
- Indoor Displays:Fine-pitch modules with sub-4mm pixel density serve retail lobbies and corporate environments where viewing distances compress. Demand concentrates in Shenzhen and Guangzhou manufacturing clusters as Chinese producers achieve cost breakthroughs in high-resolution panels.
- Outdoor Displays:Coarse-pitch modules from 10mm to 20mm with IP65-rated enclosures withstand direct precipitation and solar loading. Brazilian and Indian transit agencies are modernizing platform systems with these specifications for passenger information systems.
- Transportation Displays:Networked arrival boards with centralized content management serve rail and bus terminals. These units are expanding most quickly as municipal authorities replace static signage with real-time data feeds.
- Scoreboards:Broadcast-calibrated modules with sports-venue durability certifications command premium positioning. North American stadium operators specify these for dual-purpose indoor-outdoor installations requiring color accuracy under television lighting.
Established volume favors indoor displays; emerging adoption favors transportation displays.
End User:
Customer archetypes range from high-frequency content updaters to single-event deployers, reshaping procurement rhythms and service contract structures.
- Advertising:Digital out-of-home networks require remote content management and uptime guarantees. Media operators in tier-one Chinese cities are consolidating vendor relationships through multi-year framework agreements bundling hardware and maintenance.
- Sports Venues:Arena operators demand hybrid-specification modules with weather resistance and broadcast color calibration. These installations carry extended warranty requirements that favor suppliers with balance-sheet capacity for long-dated receivables.
- Retail Stores:Point-of-sale and window-facing displays prioritize brightness competition with ambient daylight. Fine-pitch indoor modules from Guangdong production clusters dominate this price-sensitive procurement.
- Concerts:Temporary deployment models favor rapid-install truss-mounted panels with rental-oriented durability specifications. Event production companies source these through short-term lease structures rather than capital purchase.
Revenue concentration sits with advertising networks; margin expansion sits with sports venues.
Technology:
Signal architecture choices determine interoperability with municipal IT infrastructure and cloud-based content platforms.
- Analog:Legacy direct-drive circuits persist in budget-constrained retrofit installations where networked management is not required. Demand is fragmenting as procurement shifts toward connected platforms.
- Digital:Multiplexed row-column scanning with embedded driver ICs enables high refresh rates for video content. Taiwan and South Korea semiconductor foundries control controller production, creating supply vulnerability for mid-tier assemblers.
- Hybrid:Combined analog-digital architectures serve dual indoor-outdoor specifications from single supplier relationships. Stadium operators are specifying these to simplify maintenance training and spare parts inventory.
- Wireless:Cellular and mesh-networked controllers enable distributed municipal installations without fiber trenching. Smart city infrastructure tenders in India are specifying these for urban command centers and transit hubs.
Installed base tilts toward digital; procurement momentum tilts toward wireless.
Application:
Functional purpose shapes pixel density requirements, environmental sealing standards, and regulatory compliance burdens.
- Signage:Brand and promotional content delivery in retail and commercial environments. These applications are climbing fastest as static billboards convert to programmable digital surfaces.
- Information Displays:Real-time data feeds for transit arrival, queue management, and public announcements. German and French networks are accelerating replacement cycles under EU Ecodesign efficiency mandates.
- Event Management:Temporary staging for conferences, concerts, and sporting events. Rental-oriented procurement favors lightweight modular panels with rapid rigging systems.
- Traffic Control:Highway variable message signs and intersection advisory boards. U.S. state transportation departments are bundling decade-long maintenance into competitive tenders, displacing pure hardware vendors.
Procurement scale favors signage; regulatory tailwinds favor information displays.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transit authorities and sports venue operators concentrate procurement power across five national markets, each imposing distinct certification burdens and financing conditions on display vendors.
United States
State transportation departments bundle decade-long maintenance contracts into competitive tenders for highway variable message signs. The FCC regulates electromagnetic emissions from digital display controllers. Systems integrators with balance-sheet capacity for long-dated municipal receivables dominate procurement in Texas and California corridors.
Germany
Rail operators Deutsche Bahn and municipal transit agencies accelerate replacement cycles of legacy fluorescent-backlit displays. The EU Ecodesign Directive mandates minimum efficiency thresholds for public procurement. Manufacturing and engineering clusters in Bavaria and Baden-Württemberg supply precision driver IC assemblies to domestic module assemblers.
China
Tier-one manufacturing clusters around Shenzhen and Guangzhou achieve cost breakthroughs in sub-4mm pixel pitch modules for retail and corporate applications. GB standards mandate energy-efficiency labeling for public procurement of electronic display products. Transit authorities in Beijing and Shanghai specify networked LED arrival boards for platform modernization.
India
Municipal corporations issue tenders for urban command centers and transit hubs specifying networked display networks with centralized content management. The BIS certification framework governs electronic product safety and performance standards. Production activity concentrates in Maharashtra and Gujarat industrial zones serving domestic smart city infrastructure.
Brazil
Bus and rail agencies modernize passenger information systems with IP-rated LED modules for platform arrival displays. ANVISA regulates electronic equipment safety for public installations. São Paulo and Rio de Janeiro transit authorities drive procurement volume for weather-resistant outdoor specifications.
Dot-Matrix LED Displays Market Competitive Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement environments. The vendor base spans multinational electronics conglomerates, regional systems integrators, and cost-engineered module specialists. Three strategic archetypes dominate: sports-venue specialists with broadcast-calibration expertise, hybrid indoor-outdoor specification providers, and Shenzhen-based cost optimizers for emerging economy tenders. Competitive moves center on framework agreements bundling hardware and decade-long maintenance, plus backward integration into driver IC sourcing.
Among diversified electronics conglomerates, Panasonic Corporation and Toshiba Corporation occupy positions spanning hybrid display architectures. Sports-venue specialists include Daktronics, Inc., which anchors large installation contracts across North American stadiums. Shenzhen Dicolor Optoelectronics Co., Ltd. exemplifies the cost-engineered module archetype dominating price-sensitive procurement cycles in Brazil and India.
| Leading Market Players |
|---|
| Barco N.V. |
| Panasonic Corporation |
| EKTA |
| LG Electronics |
| Shenzhen Dicolor Optoelectronics Co., Ltd. |
| Daktronics, Inc. |
| Toshiba Corporation |
| Leyard Optoelectronic |
| HSC LED Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Shenzhen-Guangzhou freight corridors connecting Pearl River Delta manufacturing clusters to Brazilian and Indian port terminals transmit epoxy resin and copper substrate cost volatility directly into module assembler margins. This logistics channel concentrates pricing power among vertically integrated manufacturers with captive PCB production, while forcing price-sensitive assemblers toward spot-market procurement that amplifies margin compression during commodity spikes.
Pricing Analysis
Cost-plus contracts with copper and epoxy resin indexation dominate municipal transit procurement across German and French networks. Three-tier pricing structure across premium, standard, and economy levels separates broadcast-calibrated scoreboard modules from fine-pitch retail panels and coarse-pitch outdoor transit units. Pricing pressure stems from LCD alternatives with LED backlighting capturing climate-controlled indoor specifications at lower capital cost. Retail store operators in China's tier-one cities exhibit highest price sensitivity, while North American sports venue operators accept premium positioning for durability certifications.
Supply Chain Analysis
Epoxy resin feedstock and copper-clad laminate supply draws from Chinese petrochemical complexes and Chilean mining operations, with driver IC production anchored in Taiwan and South Korea semiconductor foundries. LED die sourcing rests on epitaxial wafer supply from Japanese and German equipment manufacturers. Single-source vulnerability in multiplexing controller production creates procurement risk for mid-tier display assemblers lacking long-term foundry relationships. Distribution runs through systems integrators bundling hardware, installation, and decade-long maintenance contracts for municipal authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dot-matrix LED display infrastructure sits in early-cycle expansion as Indian and Brazilian smart city mandates accelerate networked digital signage procurement beyond replacement demand. Municipal framework agreements bundling multi-year service commitments create structural advantages for capitalized vendors.
For Market Incumbents: Pre-empt emerging economy price competition by establishing in-house driver IC sourcing through foundry partnerships in Taiwan or South Korea. Secure IP65/IP68 certification pipelines ahead of coastal municipality sustainability mandates tightening enclosure specifications. Backward integration into PCB substrate production defends margin position against epoxy resin volatility.
For New Entrants and Emerging Players: Build out wireless controller capabilities for Indian smart city infrastructure tenders specifying cellular and mesh-networked installations without fiber trenching. Concentrate on urban command center and transit hub segments where procurement favors open-protocol platforms over proprietary systems. Pursue performance-based service agreements with uptime guarantees rather than capital sales.
For Investors and Strategic Acquirers: Firmware-specialist systems integrators with municipal framework agreements and balance-sheet capacity for long-dated receivables represent the most defensible acquisition archetype. Monitor convergence between indoor fine-pitch and outdoor weather-resistant specifications as inflection signal for hybrid module demand acceleration. Long-term viability hinges on cloud-based content management platform ownership rather than hardware manufacturing scale.
| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Partnership for Driver IC Supply | Taiwan and South Korea semiconductor relationships eliminate single-source vulnerability for mid-tier assemblers. |
| IP65/IP68 Certification Pipeline Investment | Accelerated enclosure testing timelines capture coastal municipality tenders before competitors complete validation. |
| Wireless Controller Platform Development | Cellular and mesh-networked capabilities satisfy Indian smart city specifications without fiber infrastructure. |
| Performance-Based Service Agreement Model | Uptime-guaranteed contracts align vendor incentives with municipal operational continuity requirements. |
| Cloud Content Management Integration | Centralized platform ownership shifts value capture from hardware to recurring software and service revenue. |
Research Methodology
Operator-level perspectives from transit authority procurement officers, stadium operations directors, LED module manufacturing plant managers, and systems integration project engineers anchored the qualitative base. These primary insights combined with secondary validation from FCC regulatory filings, EU Ecodesign Directive implementation reports, China GB standards documentation, and Indian BIS certification records. Bottom-up demand modeling across application segments triangulated against top-down supply-side capacity assessments.
Scenario-bracketing framed volume and value outputs across the projection horizon, with segmentation dimensions spanning indoor-outdoor-transportation-scoreboard product types, analog-digital-hybrid-wireless technology architectures, and advertising-sports-retail-concert end-user categories. CAGRs derived from installed base replacement cycles, penetration rate assumptions for emerging economy infrastructure, and input cost trajectory modeling for epoxy resin and copper substrates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Shenzhen-based cost optimizers or accelerated LCD-LED hybrid substitution in climate-controlled environments would shift outcomes. Cross-checking against municipal capital expenditure budgets and smart city tender issuance rates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
UV-C LED Market
LED
France Indoor LED Lighting Market
LED
North America LED Lighting Market
LED
US and Europe LED Lighting Market
LED
India LED Outdoor Lighting Market
LED
LED Panel Market
LED
LED Downlight Market
LED
LED Phosphor Materials Market
LED
High-Brightness LED Market
LED
Saudi Arabia LED Lights Market
LED
China LED Lighting Market
LED
GCC LED Lighting Market
LED
Four-Digit 7 Segment LED Displays Market
LED
Global Chip Scale Package (CSP) LED Market
LED
Japan LED Market
LED
LED Light Market