
 Brightness Meter Market | 2026-2036
Brightness Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Brightness Meter Market Outlook
Buyer concentration across display manufacturers is rebalancing as panel fabrication consolidates among fewer OEMs while independent calibration service providers multiply. X-Rite Incorporated leverages its color science heritage to anchor premium positioning in photography and cinema workflows. Konica Minolta Sensing Americas competes through instrumentation depth in automotive headlamp verification. Sekonic specializes in handheld meters for broadcast and cinematography professionals.
A brightness meter quantifies luminance in candela per square meter using photodiode, CCD, or photomultiplier tube sensors with calibrated optical reception geometry. Portable meters dominate field service deployment due to battery-operated flexibility and ergonomic form factors, though laboratory meters command higher unit margins through NIST-traceable certification chains. Photodiode sensor technology leads volume shipments for industrial testing applications, while CCD-based architectures capture growth in display calibration where spatial uniformity mapping matters.
China's SAMR enforces GB standards for luminance measurement accuracy in consumer electronics, while the EU's Ecodesign Directive and CE marking requirements shape product access for display-related instrumentation. The US FDA regulates brightness validation in medical imaging displays through diagnostic radiology performance standards. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's circular economy requirements reshape manufacturing location decisions and sensor material sourcing.
Market Dynamics
Panel fabrication consolidation among fewer display OEMs is compressing procurement timelines while independent calibration service providers multiply, forcing instrument vendors to defend margin through certification-tier differentiation rather than volume scale.
Growth Catalysts
- GB standards enforcement:China's SAMR mandates luminance measurement accuracy in consumer electronics, compelling domestic and foreign manufacturers to upgrade testing infrastructure.
- Micro-LED manufacturing scale-up:South Korea's display panel corridor demands sub-pixel-level uniformity mapping, driving CCD-based meter adoption for spatial resolution.
- Automotive headlamp verification:Adaptive driving beam regulations in Germany and Japan require precise candela measurements at multiple angles and distances.
Market Restraints
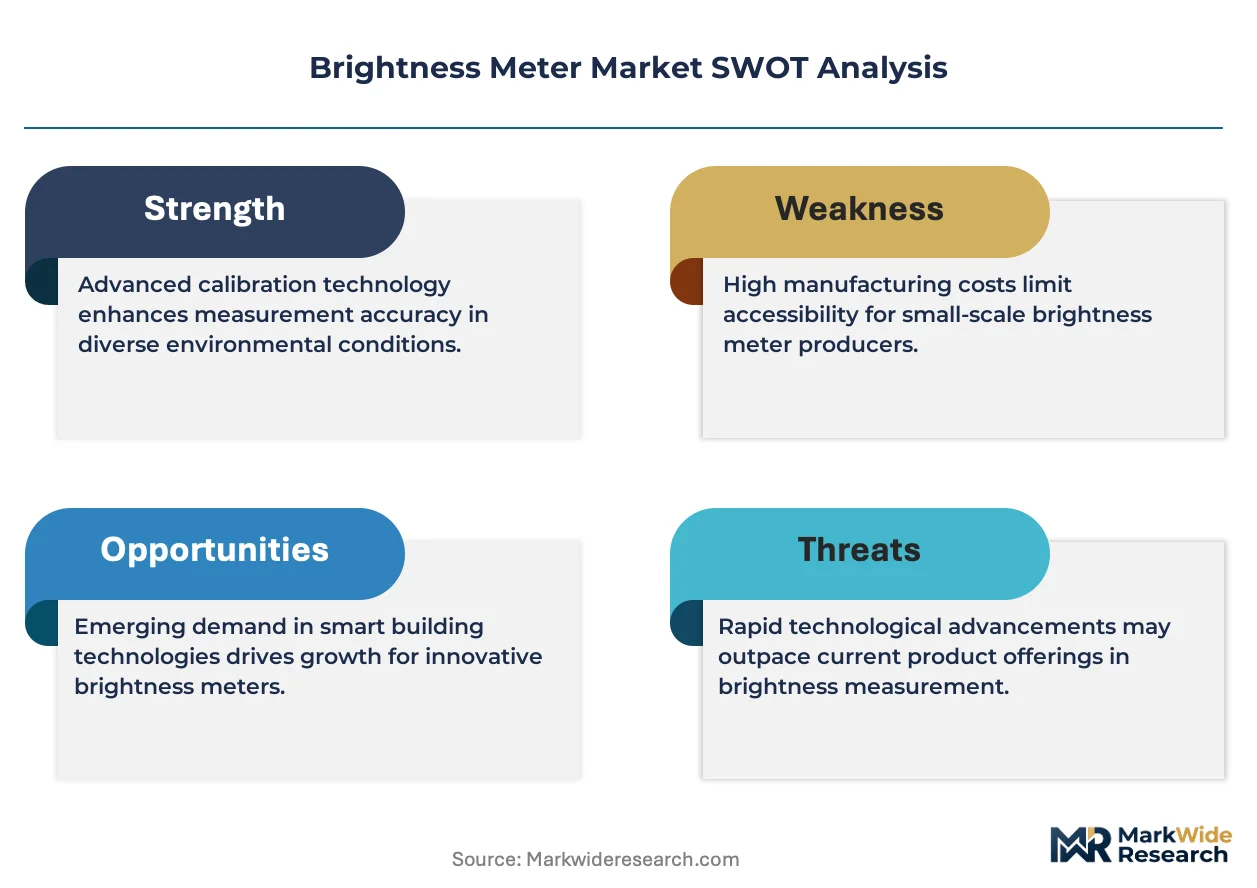
- Photodiode supply concentration:High-sensitivity silicon photodiodes concentrate among Japanese and German component suppliers, exposing meter manufacturers to allocation risk.
- NIST-traceable certification costs:Laboratory-grade meters require expensive recalibration chains, limiting addressable market to Tier-1 facilities.
- Smartphone app substitution:Consumer-grade luminance estimation through camera sensors and software algorithms displaces entry-level handheld meters.
Strategic Opportunities
- Medical imaging display validation:The US FDA's diagnostic radiology performance standards create recurring revenue streams from hospital compliance audits.
- EU Ecodesign Directive expansion:Energy efficiency labeling for displays mandates standardized brightness testing, opening government procurement channels.
- Photodiode-CCD hybrid architectures:Converging sensor technologies enable single-instrument flexibility across field service and laboratory workflows.
Industry Challenges
- Metrology talent scarcity:Expertise in photometric calibration and optical system design concentrates among aging specialists in Japan and Germany.
- Legacy system integration:Automated production lines in Shenzhen-Guangzhou facilities require custom communication protocols for meter data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brightness Meter Market |
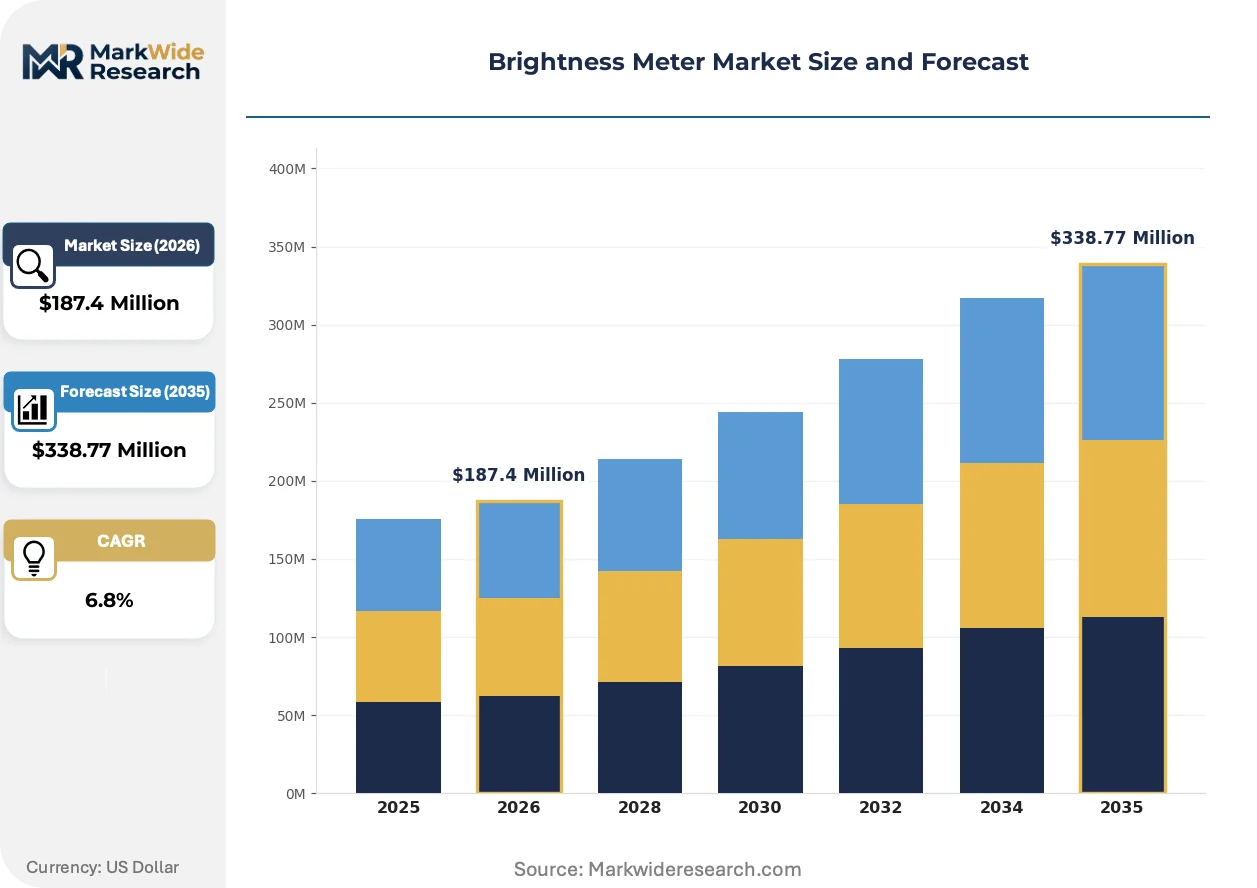
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Fixed Meters, Smartphone Meters, Laboratory Meters Technology: Photodiode Sensors, CCD Sensors, Photomultiplier Tubes, Integrated Circuits Application: Industrial Testing, Laboratory Research, Photography, Display Calibration End User: Manufacturers, Researchers, Photographers, Quality Assurance Experts |
| Companies Covered | EIE Instruments, Lisun Instruments, X-Rite Incorporated, Shenzhen Sanpo Instrument, THE Bharat, Konica Minolta Sensing Americas, FLIR Systems, Sekonic, Testo SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brightness Meter Market Strategic Shifts
Spectral measurement capabilities are migrating from laboratory benches to handheld form factors, compressing the performance gap between field service and certified reference instruments across display manufacturing workflows.
CCD-based spatial mapping is converging with photodiode speed for real-time uniformity analysis. Display calibration studios in South Korea now deploy hybrid architectures that capture full-field luminance distributions in single acquisitions. This convergence is compressing testing cycle times from minutes to seconds during panel final inspection.
China's dual carbon goals and the EU Green Deal's circular economy requirements are reshaping manufacturing location decisions. MEE enforcement of carbon intensity benchmarks for electronics production pushes instrument sourcing toward domestic Chinese suppliers. Vendors are responding with modular designs that simplify component replacement and reduce embodied carbon.
Service unbundling is fragmenting the traditional meter-plus-calibration bundle. Independent calibration laboratories in Taiwan and California now compete directly with manufacturers for annual recertification contracts. This shift is most visible among broadcast and cinematography professionals who prioritize local turnaround over brand loyalty.
Brightness Meter Market Segmentation
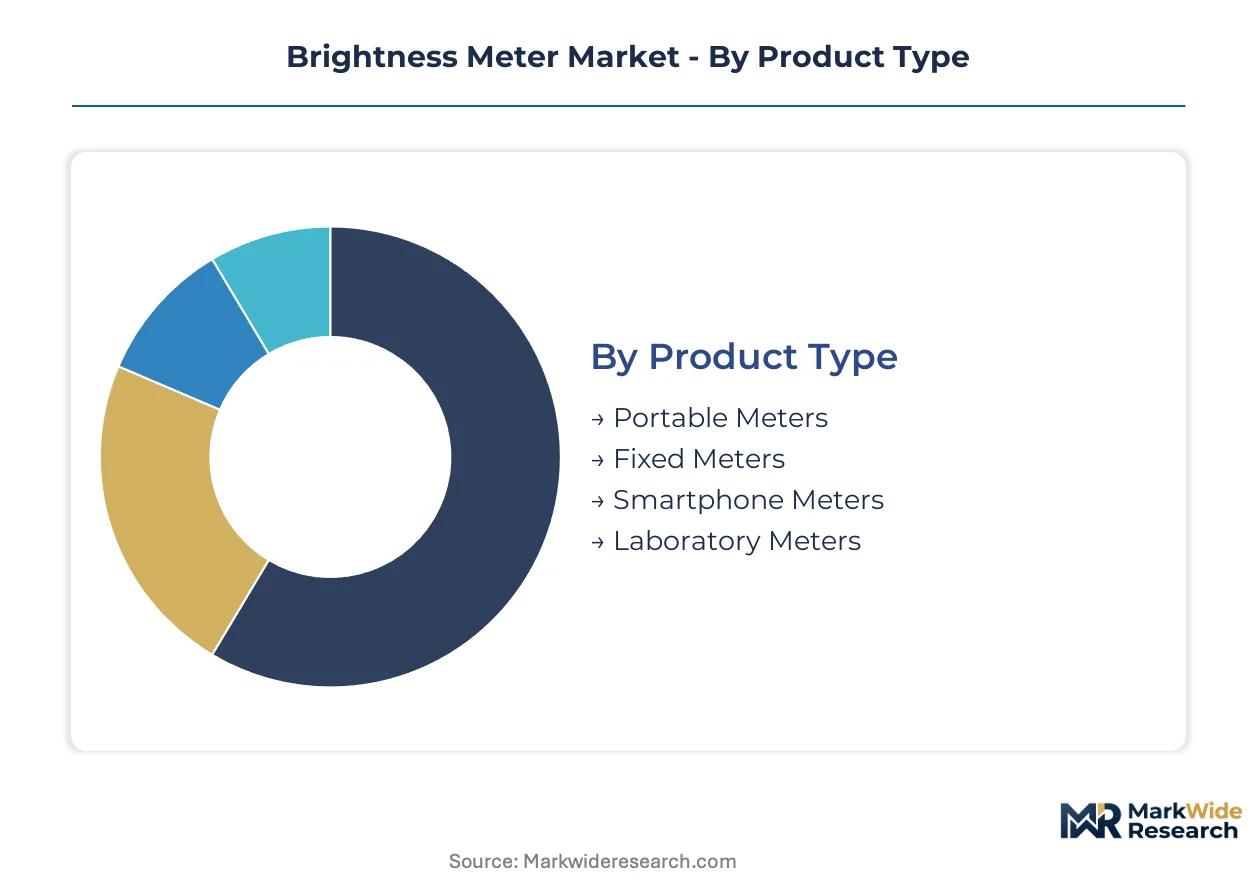
Segmentation in the brightness meter market reveals distinct capital requirements across product tiers and technology architectures. Procurement patterns diverge sharply between field-service portability and laboratory-grade certification chains.
Product Type:
Capital intensity peaks with laboratory meters requiring NIST-traceable calibration infrastructure, while portable variants minimize upfront equipment investment.
- Portable Meters:Battery-operated handheld units with ergonomic form factors dominate field service deployment. Display calibration studios in South Korea's panel corridor favor these for production-line flexibility where mobility outweighs absolute precision.
- Laboratory Meters:Stationary benchtop instruments with certified optical reception geometry command premium positioning through recertification revenue streams. Shenzhen-Guangzhou electronics clusters absorb these for GB standards compliance in consumer electronics validation.
- Fixed Meters:Permanently installed units integrated into automated inspection lines.
- Smartphone Meters:Camera-sensor-based luminance estimation apps displacing entry-level handhelds.
Laboratory meters absorb the bulk of installed capacity; portable meters are expanding most quickly.
Technology:
Technology selection tracks the precision-speed trade-off inherent in photometric measurement workflows.
- Photodiode Sensors:Silicon-based detectors deliver rapid response times for industrial throughput requirements. Volume shipments concentrate in automotive headlamp verification where German and Japanese adaptive driving beam regulations mandate multi-angle candela measurements.
- CCD Sensors:Charge-coupled device architectures enable spatial uniformity mapping across display surfaces. South Korean micro-LED manufacturing demands sub-pixel-level resolution for final inspection protocols.
- Photomultiplier Tubes:Vacuum-tube technology for ultra-low-light detection in specialized research.
- Integrated Circuits:CMOS-integrated photodetector arrays reducing component count.
Photodiode sensors retain the largest installed base; CCD architectures gain share fastest.
Application:
Application segmentation reflects diverging certification requirements between production-line testing and reference-grade research.
- Display Calibration:Luminance uniformity validation for OLED and micro-LED panels. East Asian electronics manufacturing clusters drive procurement as China's SAMR enforces GB standards accuracy thresholds.
- Industrial Testing:High-volume quality control across automotive and consumer electronics. German KBA headlamp regulations and Japanese METI safety standards shape instrument specifications.
- Laboratory Research:Fundamental photometric studies requiring traceable uncertainty budgets.
- Photography:Creative professional workflows prioritizing color science integration.
Industrial testing absorbs the bulk of installed capacity; display calibration is climbing the fastest.
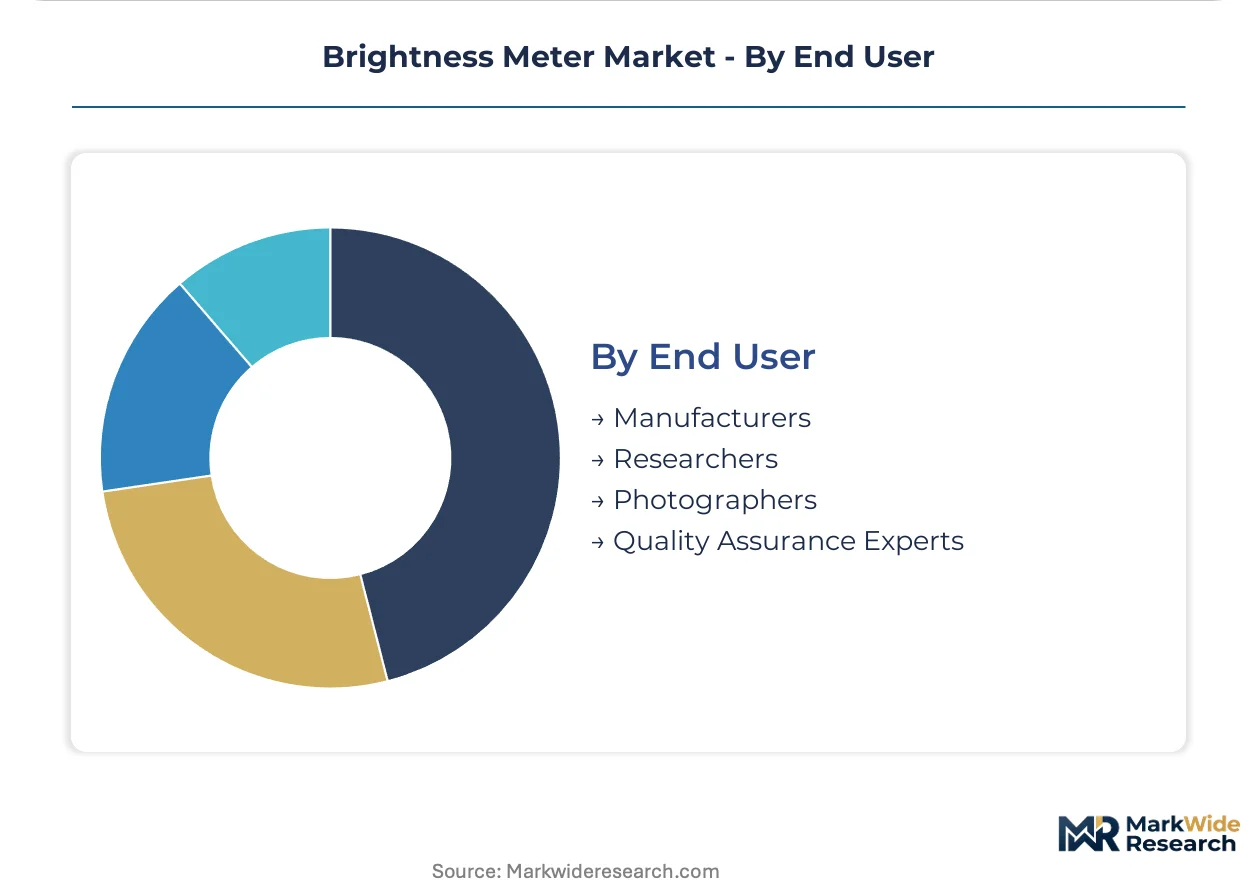
End User:
End-user segmentation captures the organizational capability differential between integrated manufacturers and independent service providers.
- Manufacturers:Integrated display OEMs and tier-one automotive suppliers operating captive metrology laboratories. Panel fabrication consolidation among fewer Korean and Chinese producers compresses procurement timelines while expanding volume scale.
- Quality Assurance Experts:Third-party calibration laboratories and compliance auditors. Independent service providers in Taiwan and California now compete directly with manufacturers for annual recertification contracts.
- Researchers:Academic and government laboratories requiring traceable reference standards.
- Photographers:Individual creative professionals and broadcast cinematographers.
Manufacturers absorb the bulk of installed capacity; quality assurance experts are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-sensitivity silicon photodiodes concentrate among Japanese and German component suppliers, anchoring procurement patterns for instrument manufacturers across three continents. Display calibration studios and automotive testing facilities drive regional demand differentiation.
China
GB standards enforcement by SAMR compels domestic and foreign manufacturers to upgrade testing infrastructure for consumer electronics validation. MEE carbon intensity benchmarks for electronics production push instrument sourcing toward domestic suppliers. The Shenzhen-Guangzhou axis absorbs laboratory-grade meters for compliance testing as panel fabrication scales.
South Korea
Micro-LED manufacturing demands sub-pixel-level uniformity mapping, driving CCD-based meter adoption for spatial resolution in final inspection. Korean display panel corridors concentrate procurement among fewer integrated OEMs. Seoul Capital Area facilities deploy hybrid architectures capturing full-field luminance distributions in single acquisitions.
Germany
Adaptive driving beam regulations from KBA require precise candela measurements at multiple angles and distances for automotive headlamp verification. EU Ecodesign Directive expansion mandates standardized brightness testing for energy efficiency labeling. Bavarian automotive clusters absorb photodiode-based instruments for industrial throughput requirements.
United States
FDA diagnostic radiology performance standards create recurring revenue streams from hospital compliance audits for medical imaging display validation. Independent calibration laboratories in California compete directly with manufacturers for annual recertification contracts. Greater Boston research facilities maintain traceable reference standards for fundamental photometric studies.
Japan
METI safety standards shape instrument specifications for automotive and consumer electronics testing. Japanese photodiode suppliers concentrate high-sensitivity silicon component production, exposing meter manufacturers to allocation risk. Nagoya-area industrial clusters deploy portable meters for production-line flexibility where mobility outweighs absolute precision.
Brightness Meter Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue smartphone-app substitution and modular service unbundling. The vendor base spans instrumentation conglomerates, specialized optical firms, and regional electronics fabricators. Three archetypes dominate: heritage color-science houses, automotive-focused metrology specialists, and handheld broadcast-equipment providers. Competitive moves concentrate on certification-tier differentiation and geographic expansion into East Asian manufacturing clusters.
Among heritage color-science specialists, X-Rite Incorporated exemplifies premium positioning anchored in photography and cinema workflows. Konica Minolta Sensing Americas occupies a position within automotive-focused instrumentation, while Sekonic represents handheld specialization for broadcast and cinematography professionals. Shenzhen Sanpo Instrument and Lisun Instruments sit within Chinese regional fabrication, supplying domestic compliance testing infrastructure.
| Leading Market Players |
|---|
| EIE Instruments |
| Lisun Instruments |
| X-Rite Incorporated |
| Shenzhen Sanpo Instrument |
| THE Bharat |
| Konica Minolta Sensing Americas |
| FLIR Systems |
| Sekonic |
| Testo SE |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between NIST-traceable laboratory instruments and field-service portables manifests in both pricing premiums and supply chain sourcing strategies. Laboratory meters command recertification revenue streams through German and Japanese photodiode suppliers, while portable variants minimize component count via Chinese CMOS integration to defend margin at lower price points.
Pricing Analysis
Warranty and annual recalibration bundling separates laboratory-grade meter vendors from unbundled field-service competitors. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and sensor architecture complexity. Cost compression in portable segments intensifies because smartphone apps displace entry-level handhelds, forcing hardware vendors to absorb calibration service costs. Quality assurance experts exhibit highest price sensitivity due to competitive bidding for annual recertification contracts, while hospital compliance auditors show lowest sensitivity given FDA mandate rigidity.
Supply Chain Analysis
High-sensitivity silicon photodiode supply rests on Japanese and German specialty component producers, exposing meter manufacturers to allocation risk during demand surges. CMOS-integrated photodetector arrays draw from Chinese semiconductor foundries and Taiwanese packaging houses. Single-source vulnerability concentrates in photomultiplier tube vacuum technology where replacement timelines extend beyond production schedules. Distribution runs through direct OEM relationships for integrated manufacturers and independent calibration laboratories for third-party service providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photodiode supply concentration among two geographic clusters props pricing power for instrument vendors able to secure component allocation. This supply-constrained structure rewards stakeholders with secured input relationships.
For Market Incumbents: Anchor premium positioning through captive NIST-traceable calibration laboratory networks that smartphone apps cannot replicate. Deepen backward integration into photodiode sourcing via long-term supply agreements with Japanese component houses to offset allocation risk from emerging Asian entrants. Certification investment in China's GB standards compliance creates switching costs for Shenzhen-Guangzhou panel manufacturers. For New Entrants and Emerging Players: Smartphone-based luminance estimation algorithms offer a technology-first wedge into consumer-grade displacement of entry-level handhelds. Independent calibration service providers in Taiwan and California represent the most penetrable customer segment given their price sensitivity and brand agnosticism. Modular hardware designs with swappable sensor modules enable rapid geographic expansion without full product redesign. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid-architecture specialists given CCD-photodiode convergence catalysts in South Korean micro-LED manufacturing. Long-term viability favors vendors with secured photodiode supply relationships and recurring calibration revenue streams over pure hardware plays. Watch photodiode allocation announcements from Japanese suppliers as inflection indicators for margin compression or expansion across the vendor base.| Strategic Initiative | Industry Significance |
|---|---|
| Photodiode Supply Agreement | Secures component allocation from Japanese suppliers amid demand surges from display manufacturing. |
| Hybrid Sensor Architecture Launch | Captures South Korean micro-LED uniformity mapping requirements with single-instrument flexibility. |
| GB Standards Certification Investment | Unlocks SAMR-mandated procurement channels in Shenzhen-Guangzhou electronics clusters. |
| Calibration Service Unbundling | Competes directly with manufacturers for annual recertification contracts from broadcast professionals. |
| Modular Design Transition | Responds to EU Green Deal circular economy requirements with simplified component replacement. |
Study Parameters
Trade databases, regulatory filings from SAMR and FDA, and instrument shipment customs records formed the secondary backbone for this analysis. Primary interviews with display metrology engineers, calibration laboratory directors, OEM procurement managers, and photodiode component suppliers combined with secondary validation through bottom-up and top-down triangulation approaches.
Bottom-up unit economics and top-down sectoral demand aggregation provided the analytical lens for market sizing. Segmentation dimensions modeled include product type, sensor technology, application vertical, and end-user organizational capability across the projection horizon. CAGRs were derived from installed base turnover rates and technology substitution curves, with specific inputs from OLED and micro-LED manufacturing capacity announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under photodiode supply disruption scenarios or accelerated smartphone app substitution. Forecasts reflect documented assumptions regarding panel fabrication consolidation timelines and regulatory enforcement intensity. Photodiode allocation announcements, GB standards revision schedules, and EU Ecodesign Directive expansion timelines warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Printed Circuit Board Inspection Equipment Market
Test and Measurement
Battery Pack Immersion Cooling System Performance Test Rigs Market
Test and Measurement
Solar Measuring Device Market
Test and Measurement
High-Temperature Furnace Refractory Lining Inspection Systems Market
Test and Measurement
Product Design Verification and Validation Solution Market
Test and Measurement
Liquid Immersion Cooling Fluid Compatibility Test Equipment Market
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Megohmmeters Market
Test and Measurement
Satellite Communications and Direct-to-Device RF Test Platforms Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
United States Probe Station Market
Test and Measurement
Digital Inspection Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Precision Measuring Tools Market
Test and Measurement
Tube Tester Market