
 LED Modular Display Market | 2026-2036
LED Modular Display Market Size, Share, and Industry Trends Forecast 2026-2036
LED Modular Display Market Intelligence
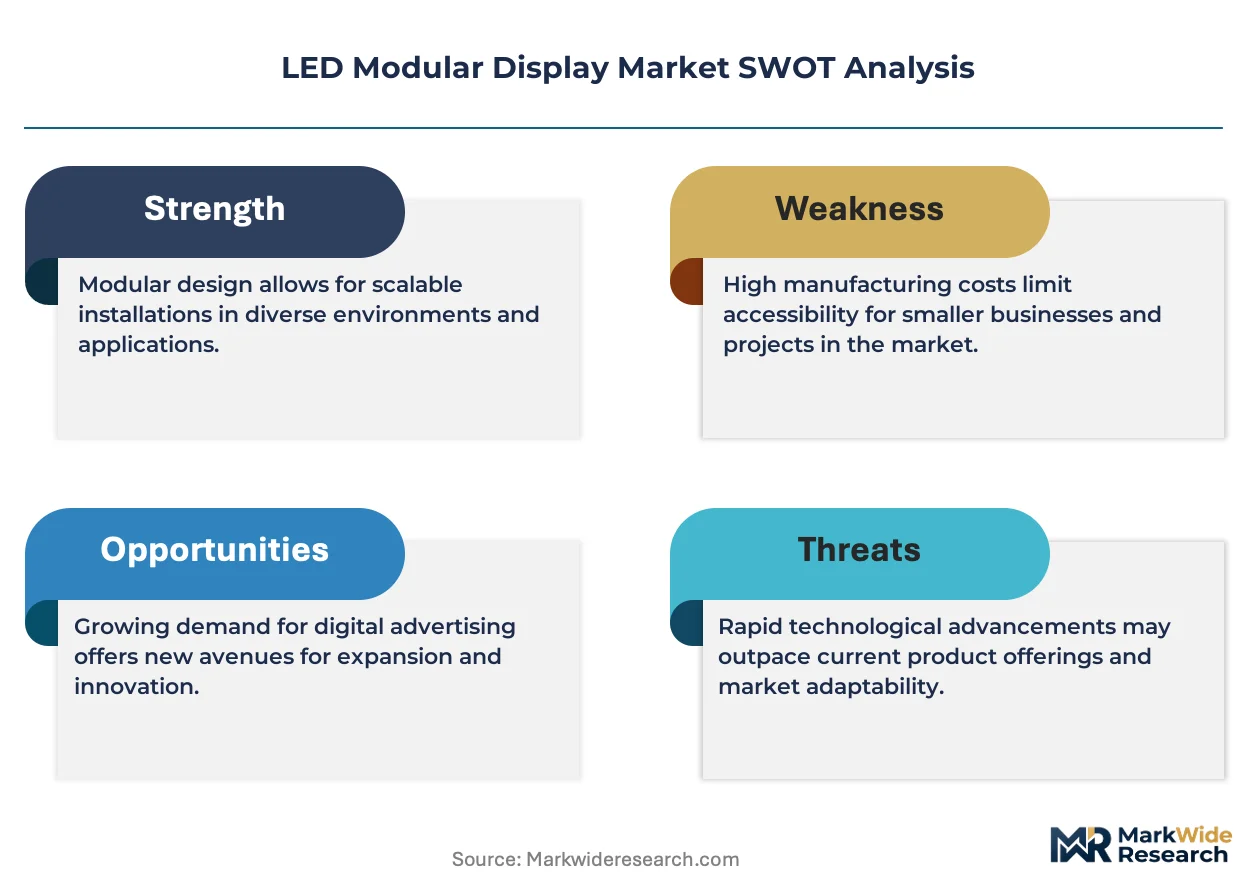
A capability gap in manufacturing advanced pixel pitches is bifurcating the competitive landscape, separating players with heavy R&D investment from those assembling standard modules. Samsung Electronics leverages its semiconductor expertise to lead in fine-pitch technology development. Unilumin Group competes on its vast manufacturing scale and a broad product portfolio across different price points. Daktronics specializes in integrated systems for large-venue applications, particularly dominating sports arenas in the United States.
An LED modular display is a large-format video screen constructed from seamless arrays of individual light-emitting diode panels or cabinets. Its primary function is to deliver dynamic visual content in public, commercial, or event spaces, with performance defined by pixel pitch and brightness. Indoor displays constitute the largest segment by volume, driven by corporate and retail applications. The Micro LED technology segment represents the fastest-growing category, commanding premium pricing due to superior contrast and longevity.
Compliance with regional electronic emissions and safety standards dictates market access. For instance, CE marking is mandatory in Europe under regulations like RoHS, while the FCC Part 15 governs electromagnetic interference in the United States. In China, GB standards for energy efficiency and performance are critical. Navigating the investment trade-off between mature Direct View LED technology and next-generation Micro LED production remains the central strategic decision for manufacturers.
Market Dynamics
The central structural force shaping the market is the bifurcation of manufacturing capabilities. A widening gap separates firms capable of the high-R&D investment for fine-pitch Micro LED from assemblers of commoditized standard-pitch modules, creating distinct competitive tiers.
Growth Catalysts
- Micro LED Proliferation:Adoption of Micro LED technology in premium applications such as corporate command centers, broadcast studios, and luxury retail is creating a high-margin growth segment defined by superior visual performance.
- Smart City Infrastructure:Urban development projects, particularly in Asia and the Middle East, incorporate large-format digital signage for public information, transit systems, and civic advertising, creating large-volume demand.
- Digital Out-of-Home (DOOH) Expansion:The transition from static billboards to dynamic digital displays in high-traffic outdoor locations provides a consistent demand driver for weather-resistant, high-brightness modules.
Market Restraints
- High Capital Investment:The immense cost of establishing and scaling up fabrication facilities for advanced Micro LED and fine-pitch technologies presents a significant barrier to entry for new and smaller manufacturers.
- Input Material Costs:Price volatility and supply constraints for critical raw materials, including gallium nitride (GaN) substrates and specialized driver ICs, can compress manufacturer margins. *Technical Yield Challenges: Low yields in the mass transfer process for assembling sub-1mm pixel pitch displays remain a primary technical hurdle, inflating production costs and limiting scalability for premium products.
Strategic Opportunities
- Rental Market Services:Building out rental and staging divisions to serve the live events, trade show, and concert touring industries offers a recurring revenue stream beyond one-time hardware sales.
- Emerging Geographies:Market entry into underpenetrated regions in Latin America and Southeast Asia, where digital infrastructure is rapidly developing, presents significant expansion potential for mid-range products.
- Transparent Display Applications:Developing transparent LED solutions for retail storefronts, architectural glass facades, and museum exhibits opens a new application frontier that merges digital content with physical environments.
Industry Challenges
- Regulatory Compliance Fragmentation:Adhering to a diverse and evolving set of regional standards, such as FCC Part 15 in the US and CE marking in Europe, requires costly and time-consuming testing for each target market.
- System Integration Complexity:Ensuring seamless interoperability between LED panels, video processors, and third-party content management systems poses a persistent technical challenge for installers and systems integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Modular Display Market |
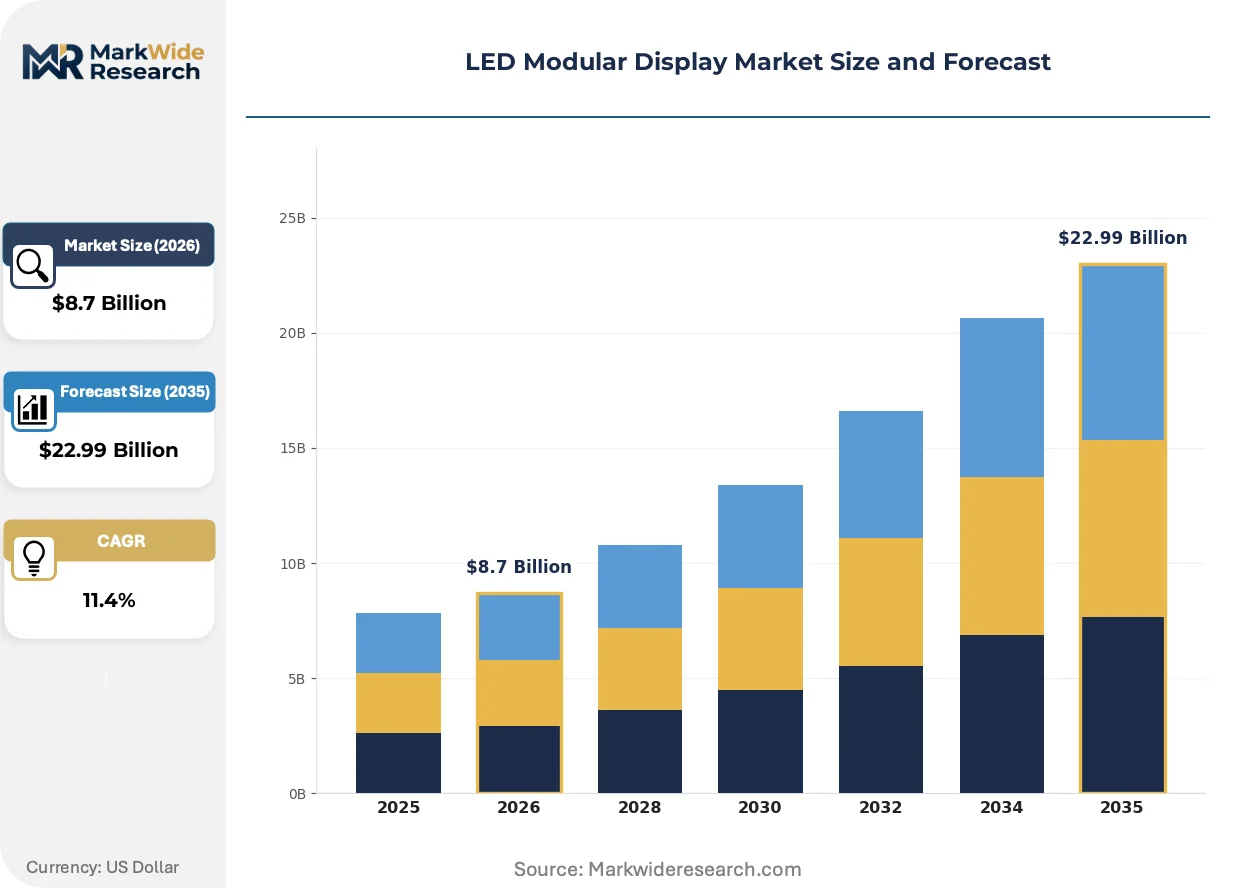
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Displays, Outdoor Displays, Transparent Displays, Rental Displays Technology: Direct View LED, Mini LED, Micro LED, Organic LED Application: Retail Advertising, Events & Conferences, Transportation Hubs, Broadcast End User: Retailers, Corporations, Government, Educational Institutions |
| Companies Covered | Daktronics, LG Electronics, Leyard, LianTronics, Barco, Unilumin Group, Samsung Electronics, Planar Systems, Absen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Modular Display Market Strategic Shifts & Innovations
Technological advancements in pixel density are intersecting with a growing regulatory focus on energy efficiency and product circularity. This dual pressure is compelling manufacturers to innovate not just on visual performance but also on operational sustainability and total cost of ownership.
Chip-on-Board (COB) technology encapsulates multiple LED chips directly onto a printed circuit board substrate. High-end users in broadcast and virtual production are adopting COB for its superior durability and contrast. This technology is miniaturizing the pixel architecture itself, which eliminates failure points associated with individual SMD LEDs and enables the production of more robust, ultra-fine pitch displays.
Heightened enforcement of sustainability mandates, including the EU’s Ecodesign for Electronic Displays regulation, is influencing product design. This directive compels manufacturers to improve energy efficiency and ensure the availability of spare parts for repair. The indoor fixed-installation segment is most affected, with suppliers now engineering modules for easier serviceability to comply with right-to-repair principles.
A shift from capital expenditure to operational expenditure models is altering purchasing behavior in the corporate and live events sectors. Customers increasingly prefer leasing arrangements or comprehensive Display-as-a-Service (DaaS) contracts that bundle hardware, software, content management, and maintenance. This trend is most prominent in North America and Western Europe, challenging the traditional direct sales model.
LED Modular Display Market Segmentation
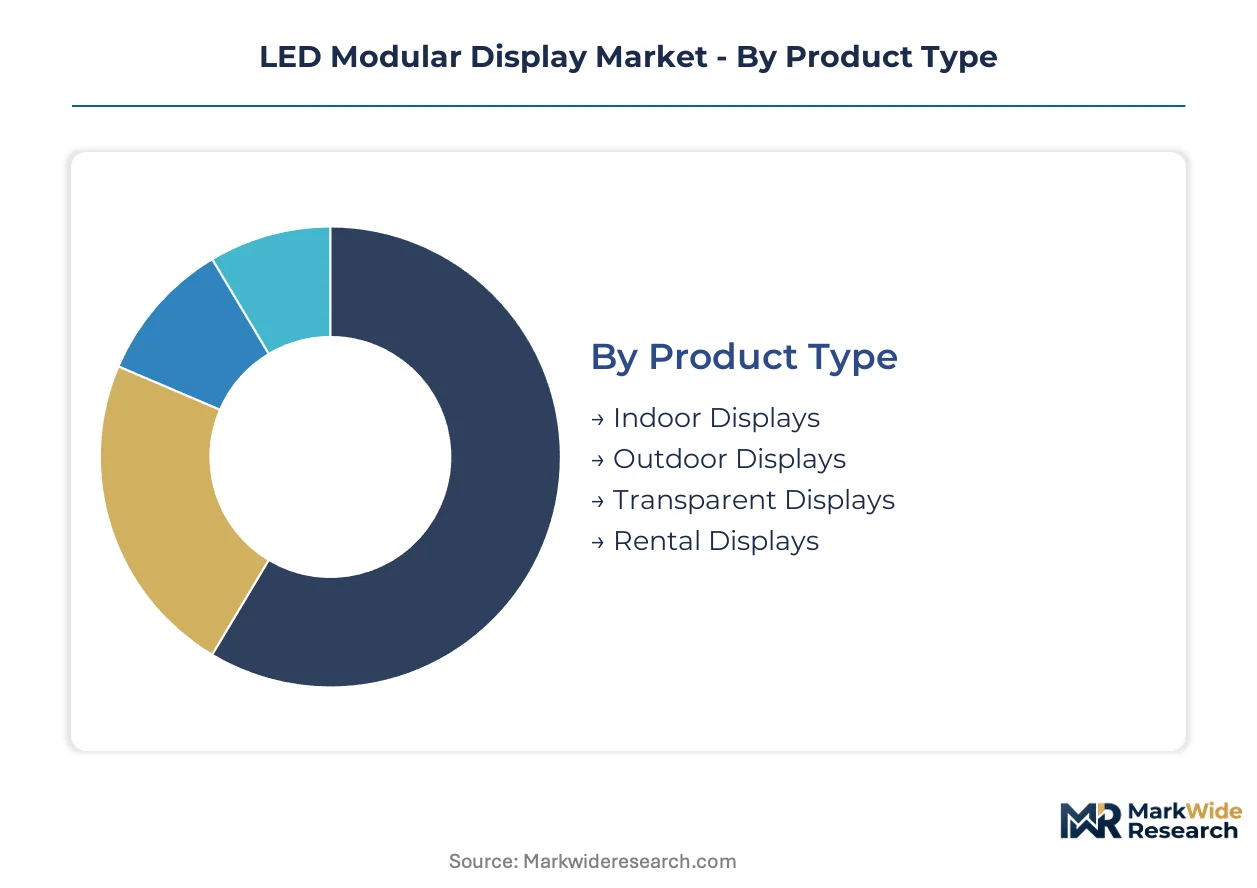
The LED modular display market segments across diverse product types, underlying technologies, varied applications, and distinct end-user categories. Understanding these distinctions helps manufacturers tailor product development, optimize distribution channels, and refine market entry strategies. This granular view reveals specific demand pockets and technological adoption trends across different regions.
Product Type:
The geographic distribution of LED modular display product types reflects varying infrastructure maturity and regulatory environments across continents.
- Indoor Displays:These displays feature finer pixel pitches and lower brightness, optimized for controlled lighting environments like corporate lobbies and retail stores. Demand for indoor displays is robust in urban centers across North America and Europe, driven by corporate branding and experiential retail.
- Outdoor Displays:Engineered for high brightness and weather resistance, these displays withstand direct sunlight and harsh environmental conditions. Digital out-of-home advertising in densely populated cities like Shanghai and New York City relies heavily on outdoor LED modules.
- Transparent Displays:These innovative displays allow light to pass through, integrating digital content with architectural glass facades and retail storefronts. Emerging markets in Asia are exploring transparent display solutions for unique architectural and commercial projects.
- Rental Displays:Designed for rapid assembly and disassembly, these robust modules serve temporary installations at events, concerts, and trade shows. The live events industry in Germany and the United States frequently utilizes rental displays for dynamic visual backdrops.
Indoor Displays hold the largest share; momentum sits with Rental Displays.
Technology:
Technological segmentation highlights the market's progression from established display methods to cutting-edge advancements driving performance enhancements.
- Direct View LED:This mature technology directly integrates individual LEDs onto a circuit board, offering high brightness and scalability for a broad range of applications. Direct View LED remains the foundation of most large-format installations globally, particularly in public information systems.
- Mini LED:Bridging the gap between traditional LED and Micro LED, Mini LED utilizes smaller LED chips for improved contrast and higher pixel density. Manufacturers are integrating Mini LED into professional displays for broadcast and control room applications.
- Micro LED:This premium technology employs microscopic LED chips, enabling superior contrast ratios, deeper blacks, and extended longevity for ultra-fine pixel pitch displays. Corporate command centers in financial hubs like London and Tokyo are adopting Micro LED for critical visualization.
- Organic LED:While offering excellent contrast and flexibility, Organic LED technology faces challenges in brightness and lifespan for large modular display formats. Niche applications requiring flexible or transparent displays are exploring OLED solutions.
Direct View LED technology maintains a significant installed base, while Micro LED is expanding most quickly.
Application:
Application segments differentiate how end-users deploy LED modular displays to engage audiences and deliver information.
- Retail Advertising:LED modular displays provide dynamic visual merchandising, promotional content, and brand storytelling within retail environments and outdoor advertising spaces. Large retail chains in China and the United States leverage LED displays for impactful customer engagement.
- Events & Conferences:These applications require flexible, high-resolution displays for stages, exhibition booths, and presentation backdrops, often supplied through rental services. Major international trade shows in Germany and convention centers in the UAE frequently deploy LED modular displays.
- Transportation Hubs:Digital signage in airports, train stations, and bus terminals provides real-time information, advertising, and wayfinding for travelers. Urban infrastructure projects in India and Saudi Arabia are integrating LED displays into new transportation networks.
- Broadcast:Studios and virtual production sets utilize high-fidelity LED walls for immersive backgrounds and interactive elements, demanding exceptional color accuracy and low latency. Broadcast studios in Los Angeles and Seoul utilize advanced LED technology for film and television production.
Retail Advertising represents a substantial volume driver, with Events & Conferences climbing the fastest due to dynamic demand.
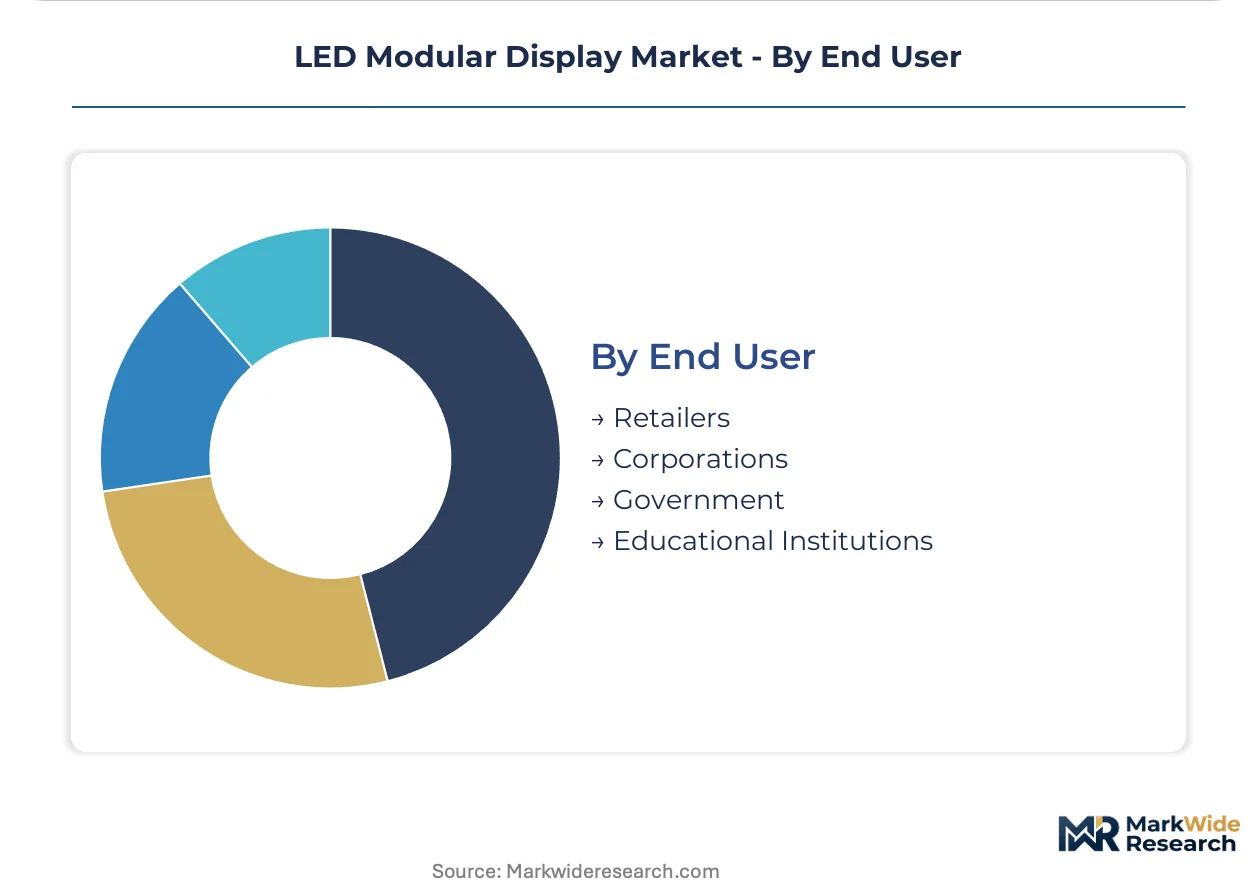
End User:
End-user segments reflect diverse procurement patterns and investment scales, from corporate installations to public sector projects.
- Retailers:This segment includes fashion brands, department stores, and supermarkets deploying LED displays for in-store promotions, window displays, and outdoor advertising. Retailers in Japan are increasingly investing in sophisticated LED solutions for brand differentiation.
- Corporations:Businesses utilize LED modular displays for meeting rooms, lobbies, command centers, and digital signage in corporate campuses. Technology firms in Silicon Valley and financial institutions in Singapore are key corporate adopters.
- Government:Public sector entities deploy LED displays for public information, smart city initiatives, traffic management, and civic advertising. Municipalities in Europe are integrating LED displays into urban development and public safety projects.
- Educational Institutions:Universities and schools use LED screens for auditoriums, sports facilities, and digital information boards across campuses. Educational institutions in Canada are upgrading facilities with modern LED display technology.
Retailers constitute a primary end-user group, and Corporations are gaining share fastest with premium installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for LED modular displays exhibits varying price elasticity across regions. Premium Micro LED installations drive high-margin growth in mature economies, while emerging markets often prioritize cost-effective standard modules. This bifurcation reflects distinct market maturity levels and investment capacities globally.
China
China's market benefits from its vast manufacturing ecosystem and extensive urban infrastructure projects, including smart city initiatives. GB standards for energy efficiency and performance critically influence product design and market access. Commercial districts in Shanghai integrate large-format outdoor displays for civic advertising systems.
United States
The United States market is driven by corporate and retail applications, alongside significant demand from large-venue sports arenas. FCC Part 15 regulations govern electromagnetic interference, ensuring device compatibility in public spaces. New York City's Times Square remains a prime location for high-brightness outdoor LED modules.
Germany
Germany's market sees strong demand from the live events sector, trade shows, and sophisticated corporate installations. CE marking is mandatory for market access under EU regulations, including RoHS. Major international trade shows in Frankfurt frequently deploy LED modular displays for dynamic visual backdrops.
India
Urban infrastructure projects and expanding transportation hubs drive significant demand for LED modular displays in India. BIS standards for quality and safety are increasingly important for market entry and product acceptance. Urban development projects in Delhi integrate LED displays into new transportation networks.
United Arab Emirates
The United Arab Emirates market is characterized by demand from luxury retail, architectural glass facades, and large convention centers. MOHAP regulations influence display use in public health and safety contexts. Dubai's iconic skyscrapers and luxury retail districts frequently feature transparent display solutions.
LED Modular Display Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated competitive landscape. This structure comprises highly capitalized technology developers, large-scale manufacturers, and niche application integrators. Companies pursue competitive advantage through heavy R&D investment in fine-pitch technologies or by leveraging vast manufacturing scale. Strategic partnerships and capacity expansion are dominant competitive moves.
Within the highly capitalized technology developer tier, Samsung Electronics leverages its extensive semiconductor expertise, anchoring its leadership in advanced fine-pitch technology development and premium Micro LED solutions. Unilumin Group exemplifies the archetype of a large-scale manufacturer, offering a broad product portfolio across different price points, from standard modules to more advanced displays, serving diverse global markets and applications. Daktronics, conversely, sits within the niche application integrator segment, specializing in integrated systems for large-venue applications, particularly dominating sports arenas and public outdoor displays in the United States.
| Leading Market Players |
|---|
| Daktronics |
| LG Electronics |
| Leyard |
| LianTronics |
| Barco |
| Unilumin Group |
| Samsung Electronics |
| Planar Systems |
| Absen |
| Others |
Cost & Logistics Intelligence
Project-based contract structures, common in large LED modular display installations, lock in both supply access and price visibility for complex deployments. This model mitigates risks associated with long lead times for specialized components and ensures consistent pricing for custom solutions.
Pricing Analysis
After-sales service and extended warranty contracts drive significant lifetime value for LED modular display manufacturers. The pricing model often follows a project-based approach for custom installations, while standard modules utilize a per-unit transactional structure. Price differentiation stems from the pixel pitch quality, brand premium from companies like Samsung, and the level of post-sale support. Pricing pressure intensifies for commoditized standard-pitch modules due to abundant manufacturing capacity in China. Corporate buyers for premium installations demonstrate lower price sensitivity compared to rental companies procuring for temporary events.
Supply Chain Analysis
Extended inventory holding periods and long lead times characterize the supply chain for advanced LED modular displays. Geographic supply concentration centers in China for manufacturing and South Korea for advanced chip development. The industry relies on critical raw materials such as gallium nitride (GaN) substrates and specialized driver ICs from a limited number of suppliers. Technical yield challenges in Micro LED mass transfer processes present a significant supply chain risk, inflating production costs. Distribution for large installations often runs through system integrators and specialized channel partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is poised for a cyclical recovery, driven by renewed investment in smart city infrastructure and digital out-of-home advertising across global urban centers.
For Market Incumbents: Shield core market share by continuously investing in R&D for next-generation Micro LED technologies, leveraging semiconductor expertise to maintain a technical edge against emerging competitors. Consolidate market position through strategic acquisitions of niche integrators specializing in specific applications like broadcast studios. Control key component supply chains for gallium nitride substrates to mitigate raw material price volatility.
For New Entrants and Emerging Players: Certification fast-tracks, such as accelerated CE marking for European markets, offer a viable entry point. Target underpenetrated regions in Southeast Asia and Latin America with mid-range, cost-effective standard modules. Emphasize comprehensive Display-as-a-Service (DaaS) models, bundling hardware, software, and maintenance, to differentiate from traditional hardware sales. Focus on specialized integration services for rapidly developing digital infrastructure projects.
For Investors and Strategic Acquirers: Capital is best deployed toward innovative Micro LED technology developers with proven intellectual property in mass transfer processes. Long-term viability hinges on the continued premiumization of visual experiences in corporate and luxury retail environments. Watch for significant improvements in manufacturing yields for sub-1mm pixel pitch displays, which will signal scalability and broader market adoption for premium products.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Micro LED R&D | Advances visual performance and secures premium market segments for Samsung Electronics. |
| Expand rental service divisions | Generates recurring revenue streams and diversifies beyond one-time hardware sales for Unilumin Group. |
| Secure GaN substrate supply | Mitigates input material cost volatility for manufacturers of advanced LED modules. |
| Develop transparent display solutions | Unlocks new architectural and retail application frontiers merging digital content with physical spaces. |
| Target smart city infrastructure projects | Captures large-volume demand for public information and civic advertising in urban developments. |
Research Approach
Initial hypotheses were tested against primary input from product managers, R&D directors, procurement officers, and system integrators, then refined. This involved combining in-depth interviews with industry stakeholders and extensive secondary validation. Secondary data sources included industry association reports, government economic data, patent filings, and company financial statements. The analysis employed both bottom-up and top-down triangulation to ensure data accuracy and market sizing consistency.
The forecast framework utilized a variance-decomposition approach, analyzing market dynamics across the analysis window. Segmentation dimensions modeled included product type (indoor, outdoor), technology (Micro LED, Direct View LED), application (retail, events), end-user (corporations, government), and pixel pitch. Compound annual growth rates were derived from historical trends, market drivers, and specific industry inputs like urban development project pipelines and digital advertising spend.
Decision-makers should treat outputs as directional under current macroeconomic and regulatory assumptions; material deviation would warrant model refresh. Forecasts reflect a comprehensive assessment of existing market conditions and anticipated technological advancements. Raw material price volatility or geopolitical trade policies represent key risk factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Micro LED Display Market
LED
LED Light Market
LED
Organic Light Emitting Diode (OLED) Market
LED
Gan Substrate Market
LED
UV-C LED Market
LED
LED High Bay Drivers Market
LED
United States Micro LED Market
LED
South America Indoor LED Lighting Market
LED
Japan Outdoor LED Lighting Market
LED
LED Digital Scoreboard Market
LED
Brazil LED Market
LED
LED Services Market
LED
Arrow LED Displays Market
LED
Superluminescent Diodes Market
LED
Vietnam LED Lighting Market
LED
Bluetooth LED Bulb Market