
 LED Display Market | 2026-2036
LED Display Market Size, Share, and Industry Trends Forecast 2026-2036
LED Display Market Outlook
Direct-to-venue sales channels are reshaping how large-format LED systems reach end users, bypassing traditional AV integrators in major stadium and arena projects. Samsung Electronics leverages its semiconductor supply chain to sustain cost advantages in premium microLED panels. Leyard anchors its position through captive manufacturing in Beijing and Zhuhai, while Absen competes aggressively in European rental staging markets with standardized cabinet platforms.
An LED display is a flat-panel visualization system comprising arrays of light-emitting diodes mounted on printed circuit boards, with pixel pitches ranging from sub-1mm for indoor applications to 16mm or greater for outdoor billboards, designed to produce self-illuminated images without backlighting. The technology serves commercial advertising, broadcast studios, command centers, and immersive entertainment environments where brightness, contrast, and seamless scaling are critical. MicroLED product types command the highest margin pools due to transfer yield challenges and epitaxy costs, while sports applications generate the most consistent volume demand across outdoor and indoor venue categories. Digital technology segments lead unit shipments, though interactive technology is gaining traction in retail and experiential marketing deployments.
FCC certification requirements govern electromagnetic emissions for LED displays deployed in US transportation hubs and public infrastructure, while the EU Green Deal and REACH substance restrictions are raising compliance costs for European-bound products containing certain solder alloys and flame retardants. China's SAMR enforces national GB standards for energy consumption and luminous efficacy, creating a dual-track certification burden for exporters. Stakeholders must monitor evolving carbon-border adjustment mechanisms and regional content requirements that could fragment supply chain strategies.
Market Dynamics
Direct-view LED systems are compressing pixel pitches below 1mm for indoor applications while China's dual carbon mandates force energy-efficiency recertification across export supply chains, creating simultaneous technology and compliance pressures.
Growth Catalysts
- China's dual carbon goals:National GB standards for luminous efficacy are accelerating replacement cycles in outdoor advertising infrastructure. Municipal procurement now prioritizes certified low-carbon displays.
- Sports venue direct deployment:Arena operators are bypassing traditional AV integrators for large-format installations, shortening sales cycles and expanding average project scale.
- MicroLED transfer yield improvements:Advances in mass-transfer bonding are reducing epitaxy waste rates, narrowing the cost gap with premium LCD alternatives for broadcast applications.
Market Restraints
- Epitaxy substrate concentration:Sapphire and silicon carbide wafer supply concentrates among Japanese and Korean material suppliers, creating input cost volatility for microLED fabrication.
- EU REACH substance restrictions:Flame retardant and solder alloy compliance costs are rising for European-bound products, compressing margins on standardized cabinet platforms.
- Technical yield limitations:Sub-0.5mm pixel pitch production remains constrained by chip placement accuracy and defect repair economics.
Strategic Opportunities
- Immersive entertainment underpenetration:Themed attractions and virtual production studios in the United States represent expanding demand for curved and transparent LED volumes.
- Rental staging channel innovation:Standardized cabinet platforms with tool-free assembly are displacing custom-built systems in European live event markets.
- India BIS certification alignment:Convergence with IEC standards is reducing duplicate testing burdens for manufacturers entering the subcontinent's infrastructure modernization wave.
Industry Challenges
- MicroLED assembly technician scarcity:Mass-transfer equipment operation and defect repair require specialized skills that outpace vocational training pipeline expansion.
- FCC certification timeline compression:Electromagnetic emissions testing for transportation hub deployments faces backlog at accredited laboratories, delaying US infrastructure project schedules.
- Legacy control system integration:New direct-view LED installations must interface with existing venue media servers and signal distribution architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Display Market |
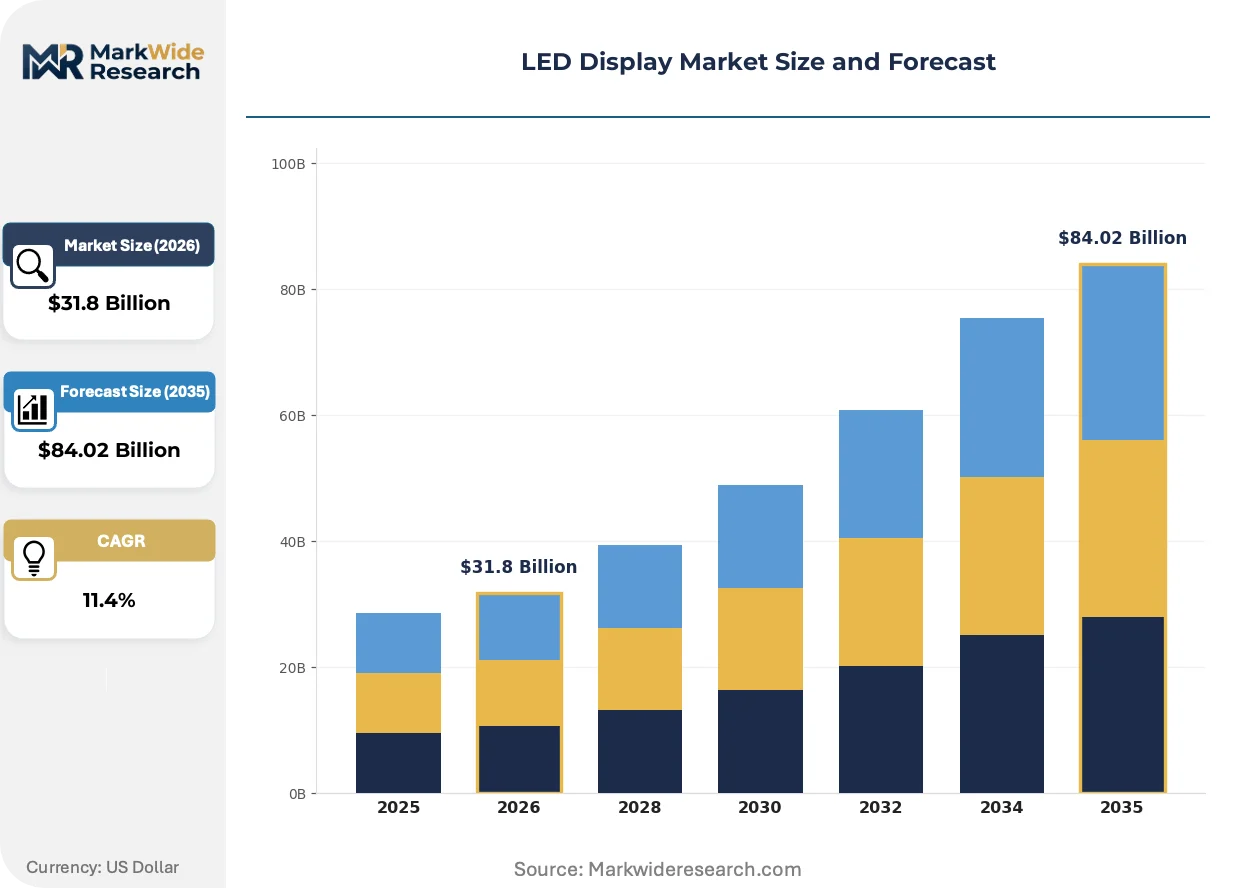
| Market Size in 2026 | $31.8 Billion |
| Market Size in 2035 | $84.02 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LCD, OLED, QLED, MicroLED Application: Advertising, Gaming, Retail, Sports End User: Commercial, Residential, Educational, Transportation Technology: Digital, Analog, Smart, Interactive |
| Companies Covered | Daktronics, Liantronics, Samsung Electronics, ROE Visual, AOTO, Leyard, Unilumin, Absen, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Display Market Strategic Shifts
Active-matrix driving architectures and chip-on-board packaging are converging to reduce module thickness and power density, while regulatory carbon accounting and buyer procurement centralization are reshaping competitive requirements.
Flip-chip COB (chip-on-board) technology eliminates wire bonds between LED dies and substrates, improving thermal dissipation and enabling tighter pixel pitches. Broadcast studios and corporate briefing centers are adopting these modules for seamless video wall configurations. The elimination of wire bond failure modes is rendering obsolete traditional SMD (surface-mount device) architectures in premium indoor segments.
China's SAMR enforcement of national GB standards for energy consumption is creating dual-track certification requirements for exporters serving domestic and international markets simultaneously. Manufacturers must maintain separate product variants or absorb retesting costs. Outdoor billboard and transportation hub segments face the steepest compliance burden as municipalities tighten procurement specifications.
Direct-to-venue sales models are consolidating purchasing authority within arena and stadium operator procurement departments, reducing the role of regional AV integrators in major project specifications. This concentration shifts negotiation leverage toward volume buyers and demands manufacturer investment in field service networks. The United States sports venue market exhibits the most advanced disintermediation, with several major franchises establishing direct supplier relationships for display system lifecycle management.
LED Display Market Segmentation
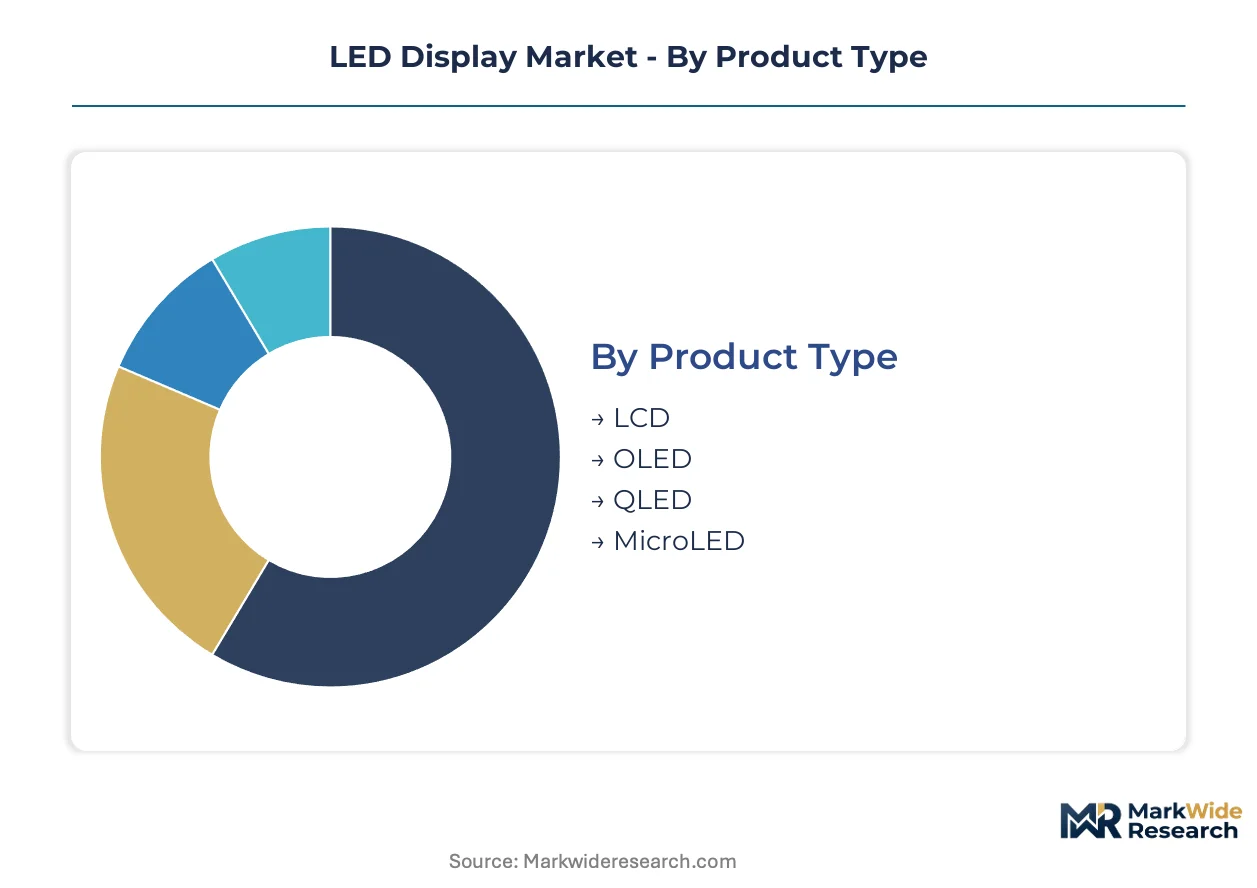
LED display segmentation reveals divergent service intensity across product tiers, with microLED installations demanding specialized calibration protocols while standardized rental platforms minimize field support. Understanding these structural differences shapes vendor resource allocation and margin capture strategies.
Product Type:
After-sales service intensity escalates dramatically from commodity panels to precision microLED systems, creating tiered margin architectures.
- MicroLED:Sub-millimeter pixel pitches require mass-transfer bonding repair capabilities and epitaxy-matched replacement protocols. Broadcast studios in the United States and premium corporate briefing centers absorb elevated service costs for seamless video wall performance. China's dual carbon certification mandates add compliance documentation burdens to maintenance contracts.
- LCD:Backlit liquid crystal modules dominate volume replacement cycles in municipal advertising infrastructure. Standardized driver board architectures reduce technician training requirements for outdoor billboard operators.
- OLED:Organic compound degradation necessitates periodic color calibration in high-ambient retail environments.
- QLED:Quantum dot enhancement layers extend color gamut for gaming monitor segments with moderate service intervals.
MicroLED holds the largest share; momentum sits with LCD replacement cycles driven by China's GB standard enforcement.
Application:
Volume concentration varies sharply across deployment environments, with venue-scale projects commanding direct manufacturer relationships.
- Sports:Arena operators deploy direct-view LED for perimeter ribbon boards and center-hung scoreboards with 24/7 uptime requirements. China's municipal procurement prioritizes certified low-carbon displays for stadium infrastructure, compressing vendor qualification timelines. FCC emissions testing for US transportation-adjacent venues creates laboratory backlog delays.
- Advertising:Outdoor billboard networks face steep energy-efficiency recertification under SAMR enforcement.
- Gaming:High-refresh-rate panels target esports venues with latency-critical specifications.
- Retail:Interactive storefront installations gain traction in European experiential marketing deployments.
Sports commands the dominant revenue position; retail applications are climbing the fastest as immersive brand environments multiply.
End User:
Procurement centralization intensity separates institutional buyers from fragmented residential demand.
- Commercial:Corporate campuses and retail chains consolidate display lifecycle management under centralized procurement departments. Direct-to-venue sales models disintermediate traditional AV integrators for large-format installations in the United States sports market.
- Transportation:Hub operators face FCC electromagnetic emissions certification for public infrastructure deployments.
- Educational:Campus-wide digital signage networks prioritize standardized cabinet platforms with tool-free assembly.
- Residential:Premium home theater microLED remains constrained by transfer yield economics and installation complexity.
Commercial end users represent the steepest expansion trajectory; transportation infrastructure modernization shows the strongest policy tailwinds.
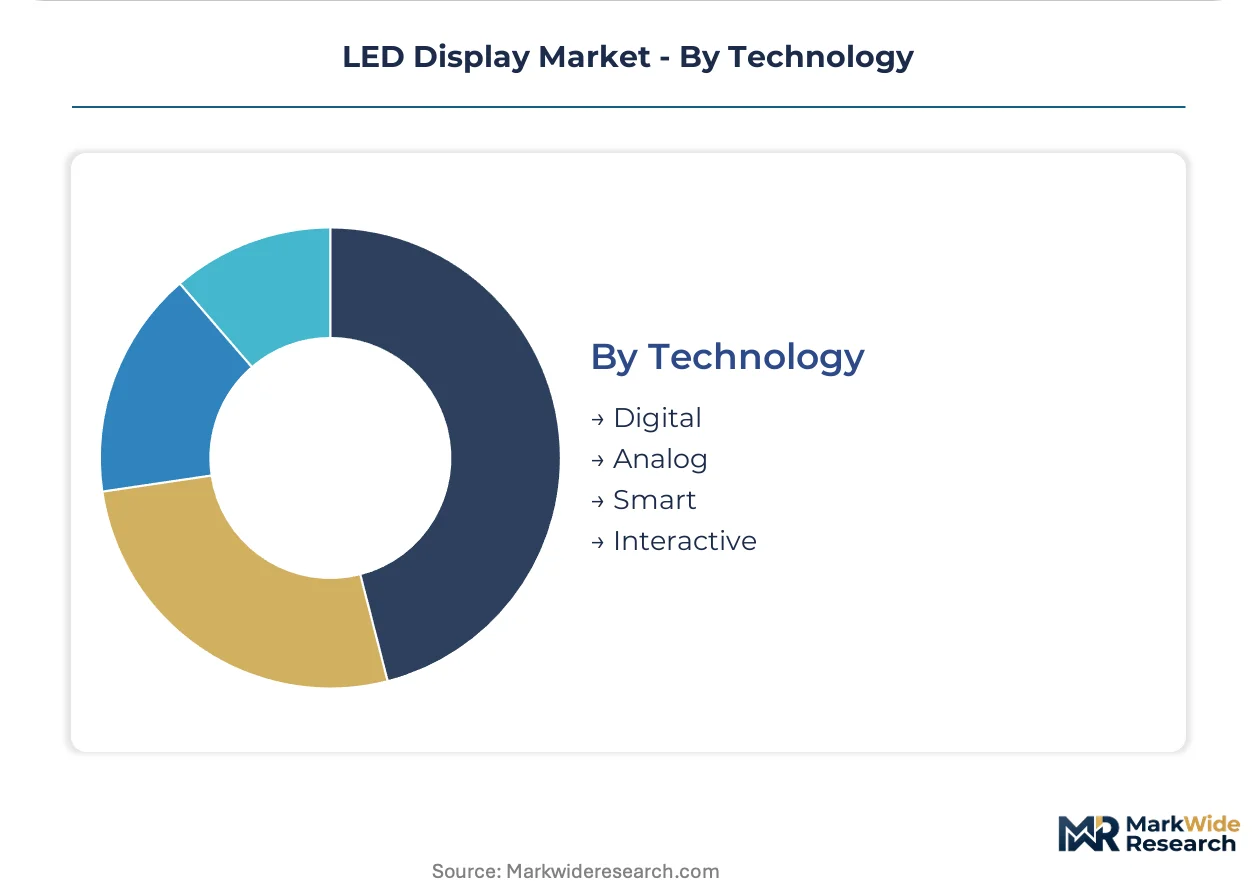
Technology:
Control architecture sophistication determines integration burden with legacy venue media servers.
- Digital:Active-matrix driving architectures lead unit shipments across broadcast and command center applications. Flip-chip COB packaging eliminates wire bond failure modes in premium indoor segments.
- Interactive:Touch-enabled and gesture-responsive panels expand in retail and themed attraction deployments.
- Smart:Network-connected displays with embedded analytics face EU GDPR compliance for audience measurement.
- Analog:Legacy signal distribution architectures persist in retrofit installations requiring backward compatibility.
Digital technology dominates current deployment; interactive systems are gaining share fastest as experiential marketing budgets expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Shenzhen port complex underwrites China's dominance in LED display component throughput, while the Incheon-Seoul logistics corridor anchors South Korean microLED substrate distribution. These infrastructure assets concentrate manufacturing gravity and compress delivery timelines for premium panel exports.
China
Municipal stadium procurement and outdoor advertising digitization absorb the majority of domestic microLED output. SAMR enforcement of GB standards for luminous efficacy forces dual-track certification for exporters serving domestic and international markets simultaneously. Manufacturing clusters in Beijing and Zhuhai host captive epitaxy facilities and mass-transfer bonding operations.
United States
Sports venue direct-deployment models and immersive entertainment studio builds command the highest-value project pipelines. FCC electromagnetic emissions certification creates laboratory backlog delays for transportation hub deployments. The Dallas-Fort Worth metroplex concentrates systems integration expertise for arena-scale installations.
South Korea
Broadcast studio refurbishment cycles and premium corporate briefing center deployments sustain demand for sub-millimeter pixel pitch panels. MFDS-aligned quality protocols streamline medical imaging adjacent applications. Seoul Capital Area fabrication facilities specialize in sapphire substrate processing for microLED epitaxy.
Germany
Industrial automation visualization and automotive showroom digitization represent expanding application vectors. EU REACH substance restrictions on flame retardants and solder alloys elevate compliance documentation burdens for cabinet platform exports. The Bavarian industrial corridor hosts precision electronics assembly operations serving European rental staging markets.
India
Infrastructure modernization across transportation hubs and educational campuses accelerates standardized cabinet platform adoption. BIS certification alignment with IEC standards reduces duplicate testing burdens for incoming manufacturers. The Delhi-NCR and Maharashtra clusters concentrate domestic assembly capacity for cost-optimized outdoor billboard segments.
LED Display Market Competitive Environment
On the supply side, the industry is consolidating around three distinct capability tiers. Semiconductor-backed conglomerates and captive-manufacturing specialists now dominate premium microLED segments, while standardized cabinet fabricators compete on assembly velocity in rental staging markets. Strategic archetypes include epitaxy-integrated panel producers, regional systems integrators with direct-to-venue sales networks, and modular platform specialists optimized for tool-free field assembly. Capacity expansion and backward integration into driver IC supply represent the dominant competitive moves.
Within the semiconductor-anchored tier, Samsung Electronics exemplifies supply chain leverage through captive component sourcing. Leyard occupies a position among Beijing- and Zhuhai-based manufacturers with integrated epitaxy-to-assembly operations. Absen sits within the standardized platform specialist archetype, serving European live event markets with rental-optimized cabinet architectures.
| Leading Market Players |
|---|
| Daktronics |
| Liantronics |
| Samsung Electronics |
| ROE Visual |
| AOTO |
| Leyard |
| Unilumin |
| Absen |
| LG Electronics |
| Others |
Value Chain & Pricing Dynamics
The Incheon-Seoul logistics corridor compresses delivery timelines for sapphire substrate shipments from South Korean epitaxy facilities, concentrating cost advantages among microLED panel producers while forcing price differentiation between captive-manufacturing specialists and standardized cabinet assemblers serving European rental markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates microLED broadcast installations from outdoor billboard LCD replacements and commodity rental staging cabinets. Price differentiation rests on GB standard certification grade and after-sales service bundling for municipal procurement. Cost compression in standardized cabinet tiers intensifies because Absen and Unilumin compete on assembly velocity. Outdoor billboard operators exhibit highest price sensitivity; premium corporate briefing centers absorb elevated service costs.
Supply Chain Analysis
Extended payment terms from Shenzhen-based driver IC suppliers to Beijing and Zhuhai panel assemblers lubricate working capital cycles for export-bound manufacturers. Geographic supply concentrates in China, South Korea, and Japan for sapphire substrates, mass-transfer equipment, and epitaxy gases. Raw material dependencies draw from silicon carbide wafers, indium gallium nitride dies, and flame-retardant PCB laminates. Single-source vulnerability in Japanese sapphire substrate suppliers elevates input cost volatility. Distribution runs through direct-to-venue sales channels for arena-scale projects and AV integrator networks for commercial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against premium LCD and projection alternatives in broadcast and corporate briefing environments. OLED large-format panels threaten to displace direct-view LED in high-ambient retail settings if organic compound degradation economics improve.
For Market Incumbents: Insulate microLED margin pools through captive epitaxy investments in Beijing-Zhuhai manufacturing clusters. Deepen backward integration into driver IC supply to offset Samsung Electronics' semiconductor leverage. Defend against standardized cabinet commoditization by embedding GB standard compliance documentation into maintenance contracts for municipal procurement.
For New Entrants and Emerging Players: Pursue immersive entertainment studio builds in the Dallas-Fort Worth metroplex where systems integration expertise concentrates but microLED supply relationships remain underdeveloped. Target European rental staging markets with tool-free cabinet architectures displacing custom-built systems. Leverage BIS-IEC alignment to shortcut certification timelines for India's transportation hub modernization wave.
For Investors and Strategic Acquirers: Regional systems integrators with direct-to-venue sales networks and established FCC certification relationships represent the most defensible acquisition archetype. Long-term viability hinges on manufacturer control over field service networks as arena operators consolidate lifecycle management. Watch for carbon-border adjustment mechanism implementation as inflection indicator for supply chain fragmentation risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Driver IC Supply | Samsung Electronics leverages captive semiconductor sourcing to sustain cost advantages in microLED panels. |
| GB Standard Certification Investment | SAMR enforcement of luminous efficacy mandates creates dual-track compliance burden for exporters serving domestic and international markets. |
| Direct-to-Venue Sales Network Expansion | Arena operators in the United States sports market bypass traditional AV integrators, shifting negotiation leverage toward volume buyers. |
| Flip-Chip COB Packaging Transition | Elimination of wire bond failure modes renders traditional SMD architectures obsolete in premium indoor broadcast segments. |
| Field Service Network Localization | Direct manufacturer relationships for display lifecycle management demand investment in technician training for mass-transfer bonding repair. |
Study Parameters
A spread of perspectives from arena procurement directors, broadcast studio technical managers, rental staging operators, and SAMR certification consultants converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs export records for Shenzhen port throughput, and FCC equipment authorization databases. Bottom-up project pipeline assessments triangulated against top-down manufacturing capacity estimates across Beijing, Zhuhai, and Seoul Capital Area clusters.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions spanning product type, application environment, end-user procurement centralization, and technology architecture. CAGRs were derived from installation volume trajectories and average selling price compression curves specific to microLED transfer yield improvements. Industry-specific forecast inputs incorporated municipal stadium procurement cycles under China's dual carbon mandates and FCC laboratory backlog timelines for transportation hub deployments.
Macroeconomic conditions sit as an overlay; deviation in infrastructure investment rates, semiconductor capital expenditure cycles, or carbon-border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions about yield improvement rates and certification timeline normalization. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Gan Micro LED Market
LED
High-Brightness LED Market
LED
Asia Pacific LED Lighting Market
LED
Mini LED Market
LED
Arrow LED Displays Market
LED
LED Encapsulation Market
LED
LED and OLED Display Market
LED
Europe Indoor LED Lighting Market
LED
Egypt LED Lighting Market
LED
Europe Outdoor LED Lighting Market
LED
China LED Market
LED
LED Services Market
LED
East Africa LED Lighting Market
LED
LED Lighting Solution Market
LED
LED Street Light Drivers Market
LED
India Indoor LED Lighting Market