
 LED Panel Market | 2026-2036
LED Panel Market Size, Share, and Industry Trends Forecast 2026-2036
LED Panel Market Analytics
Optical engineering talent is rotating from legacy LCD fabrication toward Mini LED and Micro LED wafer-level packaging, tightening the specialist labor pool across East Asia. Samsung Electronics leverages captive semiconductor foundry capacity to secure gallium nitride substrate supply. BOE Technology Group anchors massive domestic procurement through its Beijing-Tianjin-Hebei production network. LG Display competes aggressively in curved automotive display panels where thermal management expertise creates defensible positioning.
An LED panel is a flat-surface solid-state lighting device comprising multiple light-emitting diode chips mounted on a printed circuit board with diffusive optical films, typically operating at color temperatures between 2700K and 6500K and luminous efficacies exceeding 120 lumens per watt. Its primary purpose is to deliver uniform, glare-free illumination for commercial workspaces, residential interiors, and precision industrial inspection environments. Flat panels dominate volume shipments across commercial retrofits, though modular panels capture disproportionate margin pools in command-center and broadcast applications where seamless scalability commands premium positioning. Mini LED backlighting technology is displacing conventional edge-lit configurations in high-end displays, while OLED panels remain constrained to niche architectural accent installations due to cost and burn-in limitations.
The EU Green Deal and Ecodesign Directive mandate minimum efficacy thresholds and phased mercury restrictions that reshape product portfolios for European market access. China's GB standards and dual carbon goals enforce tiered energy-labeling schemes that disqualify legacy fluorescent-replacement panels from public procurement tenders. OSHA workplace illumination requirements and the EU's CSRD disclosure obligations are expanding the addressable market for human-centric circadian lighting systems. Stakeholders must monitor how tightening rare-earth supply constraints and evolving right-to-repair legislation reshape total-cost-of-ownership calculations against first-price procurement metrics.
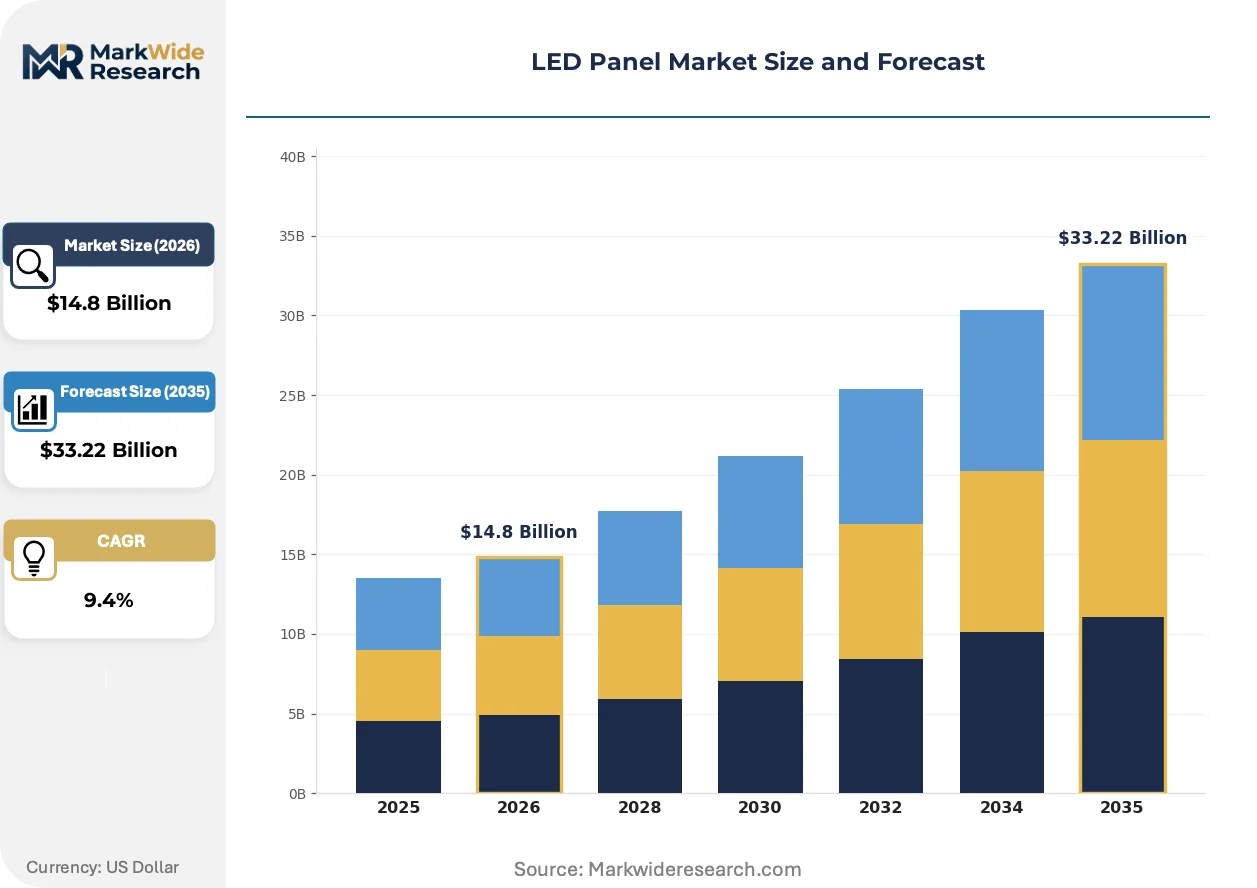
Market Dynamics
The transition from edge-lit to Mini LED backlighting architectures is compressing product lifecycles and forcing wholesale retooling of assembly lines across East Asian manufacturing clusters. This technology migration is reshaping competitive positioning by privileging semiconductor packaging expertise over legacy optical film lamination capabilities.
Growth Catalysts
- EU Green Deal efficacy mandates:The Ecodesign Directive's phased mercury restrictions and minimum lumen-per-watt thresholds are disqualifying fluorescent-replacement panels from public procurement tenders across Germany, France, and the Netherlands.
- Commercial office retrofit waves:Building code tightening in California, New York, and Illinois is accelerating LED panel specification for Class A commercial real estate repositioning projects.
- Gallium nitride substrate availability:Captive semiconductor foundry capacity in South Korea and Taiwan is securing supply chains for high-efficacy chip architectures.
Market Restraints
- Rare-earth phosphor cost volatility:Europium and terbium supply concentration in Chinese refining operations creates input price instability for warm-white panel formulations.
- Micro LED technical immaturity:Mass transfer yield rates below commercial viability thresholds constrain premium display panel substitution timelines.
- Right-to-repair legislative friction:The EU's proposed repairability index requirements threaten sealed-unit panel designs optimized for thermal management.
Strategic Opportunities
- Human-centric circadian lighting:CSRD disclosure obligations and OSHA workplace illumination standards are expanding specification for tunable-white systems in healthcare and education verticals.
- Modular command-center configurations:Broadcast and critical infrastructure operators in the UAE and Saudi Arabia are demanding seamless scalability for 24/7 operations centers.
- Automotive curved display integration:Thermal management expertise from architectural panels is transferring to cockpit display applications where flex-rigid PCB architectures command premium positioning.
Industry Challenges
- Wafer-level packaging talent scarcity:Optical engineering specialists are rotating from legacy LCD fabrication toward Mini LED and Micro LED die-bonding operations, tightening the specialist labor pool.
- Dual certification timeline compression:Simultaneous GB standard compliance for China and CE marking for Europe is extending product development cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LED Panel Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $33.22 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panels, Curved Panels, Smart Panels, Modular Panels Technology: Mini LED, Micro LED, OLED, QLED End User: Residential, Commercial, Industrial, Educational Installation: Ceiling Mount, Wall Mount, Freestanding, Embedded |
| Companies Covered | Samsung Electronics, LG Display, BOE Technology Group, Leyard, Absen, Unilumin, Signify (Philips Lighting), OSRAM, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LED Panel Market Evolving Landscape
Mini LED backlighting architectures are fragmenting the competitive landscape by separating semiconductor packaging capabilities from legacy optical component supply chains. Three distinct trajectories are reshaping how value is captured across the value chain.
Mini LED die arrays are fragmenting the high-end display panel segment by enabling zone-dimmed local contrast ratios exceeding 1,000,000:1. Automotive OEMs and premium television manufacturers are adopting these configurations at 40% year-over-year volume expansion. The technology is fragmenting incumbent supply relationships by requiring direct chip-on-board partnerships rather than module-level procurement.
China's GB standards and dual carbon goals are enforcing tiered energy-labeling schemes that disqualify legacy fluorescent-replacement panels from state-owned enterprise tenders. The MIIT's updated efficiency thresholds are compressing margins for manufacturers dependent on aluminum-substrate designs. Domestic procurement is consolidating toward Beijing-Tianjin-Hebei production network participants with captive gallium nitride capacity.
Building operators are unbundling lighting-system procurement from facilities management contracts, creating direct specification relationships with panel manufacturers. Commercial real estate investment trusts in Germany's industrial corridor are bypassing electrical distributors to negotiate volume frameworks directly with Shenzhen and Seoul-based suppliers. This disintermediation is most visible in Düsseldorf and Frankfurt retrofit clusters where 10,000+ unit projects dominate deployment schedules.
LED Panel Market Segmentation
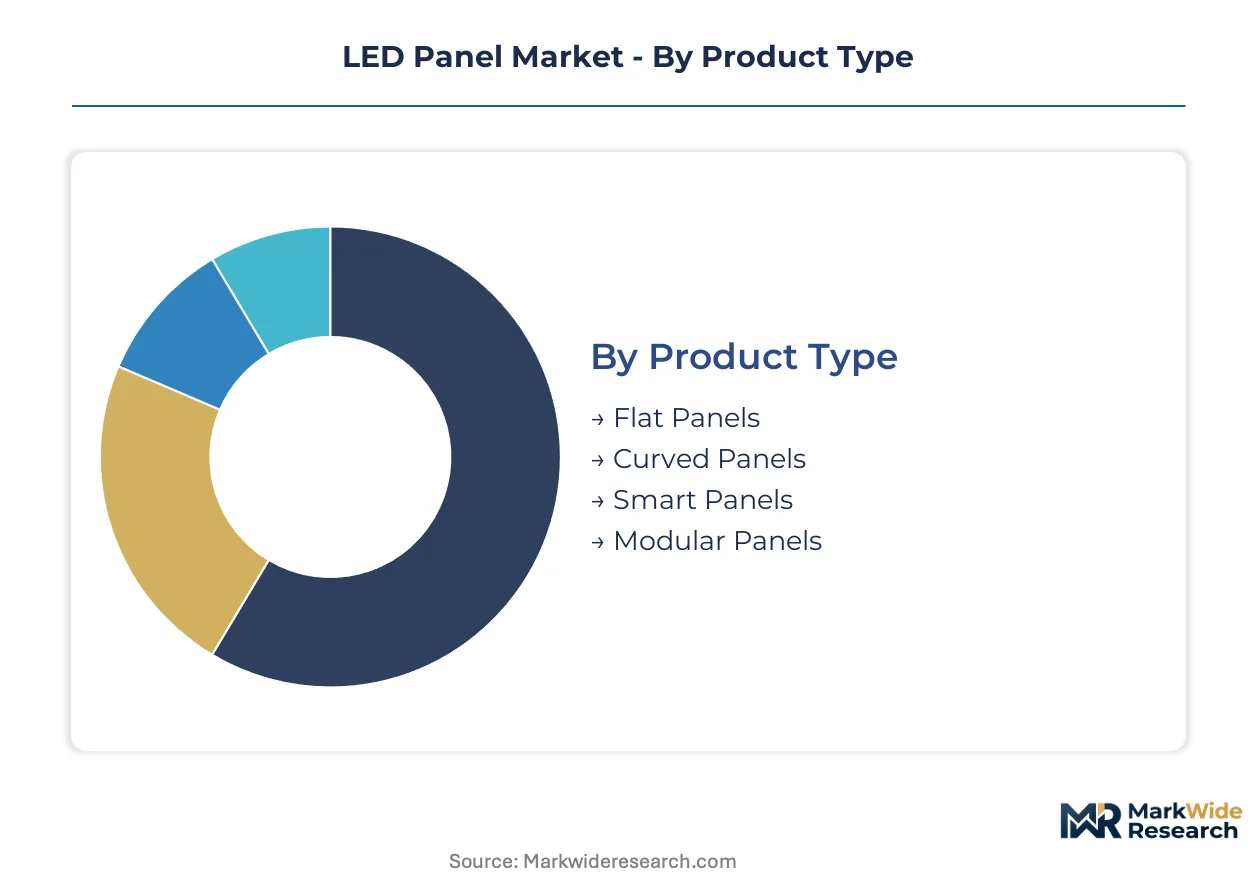
LED panel segmentation reveals how manufacturing capabilities and procurement patterns fragment across application contexts. Understanding these divisions exposes where premium positioning concentrates and where volume commoditization threatens margin sustainability.
Product Type:
Flat panels dominate domestic retrofit volumes across Germany's industrial corridor and China's Pearl River Delta, while modular and smart configurations skew heavily toward export-led premium specifications in UAE and Saudi Arabia command-center deployments.
- Flat Panels:Edge-lit and direct-backlit architectures mounted on aluminum or steel frames, typically 600x600mm or 1200x600mm form factors. Demand concentrates in California and New York commercial office retrofits where Title 24 and Local Law 97 efficacy mandates are accelerating fluorescent replacement timelines.
- Smart Panels:Integrated sensor arrays for occupancy detection, daylight harvesting, and circadian tuning via tunable-white LED engines. Procurement is expanding fastest in Dutch healthcare facilities where CSRD disclosure obligations and human-centric lighting standards are reshaping specification criteria.
- Curved Panels:Flexible PCB substrates enabling concave or convex mounting surfaces for architectural accent applications.
- Modular Panels:Seamless bezel-free tiling systems for broadcast studios and critical infrastructure operations centers.
Flat panels hold the largest share; momentum sits with smart panels as building automation integration deepens.
Technology:
Cost tier fragmentation separates semiconductor-intensive architectures from legacy phosphor-converted white LED platforms, with premium tiers commanding 3-5x pricing multiples in automotive and broadcast verticals.
- Mini LED:Chip-on-board die arrays with local dimming zones exceeding 1,000 per panel, enabling contrast ratios above 1,000,000:1. Volume is climbing fastest in South Korean and Taiwanese captive foundry supply chains serving premium television and automotive cockpit display manufacturers.
- OLED:Organic electroluminescent layers on flexible substrates, delivering infinite contrast but constrained by burn-in risk and luminance degradation. Demand clusters in German architectural accent installations where aesthetic priority overrides total-cost-of-owner
- Micro LED:Gallium nitride micro-die transfer to TFT backplanes, still constrained by mass-transfer yield thresholds below commercial viability.
- QLED:Quantum dot photoluminescent enhancement layers for wide-gamut color reproduction in consumer display applications.
Mini LED captures the steepest expansion trajectory; OLED remains niche despite superior color performance.
End User:
Customer type determines procurement channel structure, with commercial and educational segments consolidating toward direct manufacturer relationships while residential flows through electrical distributor networks.
- Commercial:Class A office, retail, and hospitality installations requiring 50,000-hour rated lifespans and networked controls compatibility. Germany's Düsseldorf and Frankfurt retrofit clusters are bypassing distributors for direct Shenzhen supplier frameworks on 10,000+ unit projects.
- Educational:K-12 and university facilities prioritizing circadian lighting for student cognitive performance. Specification is accelerating under OSHA workplace illumination guidelines and emerging state-level mandates in Illinois and New York.
- Residential:Consumer-grade surface-mounted and recessed ceiling applications with price-sensitive procurement through big-box retail channels.
- Industrial:High-bay and inspection-grade panels with IP65+ ingress protection and vibration-resistant mounting for manufacturing environments.
Commercial commands the dominant revenue pool; educational specification is gaining share fastest as human-centric lighting standards proliferate.
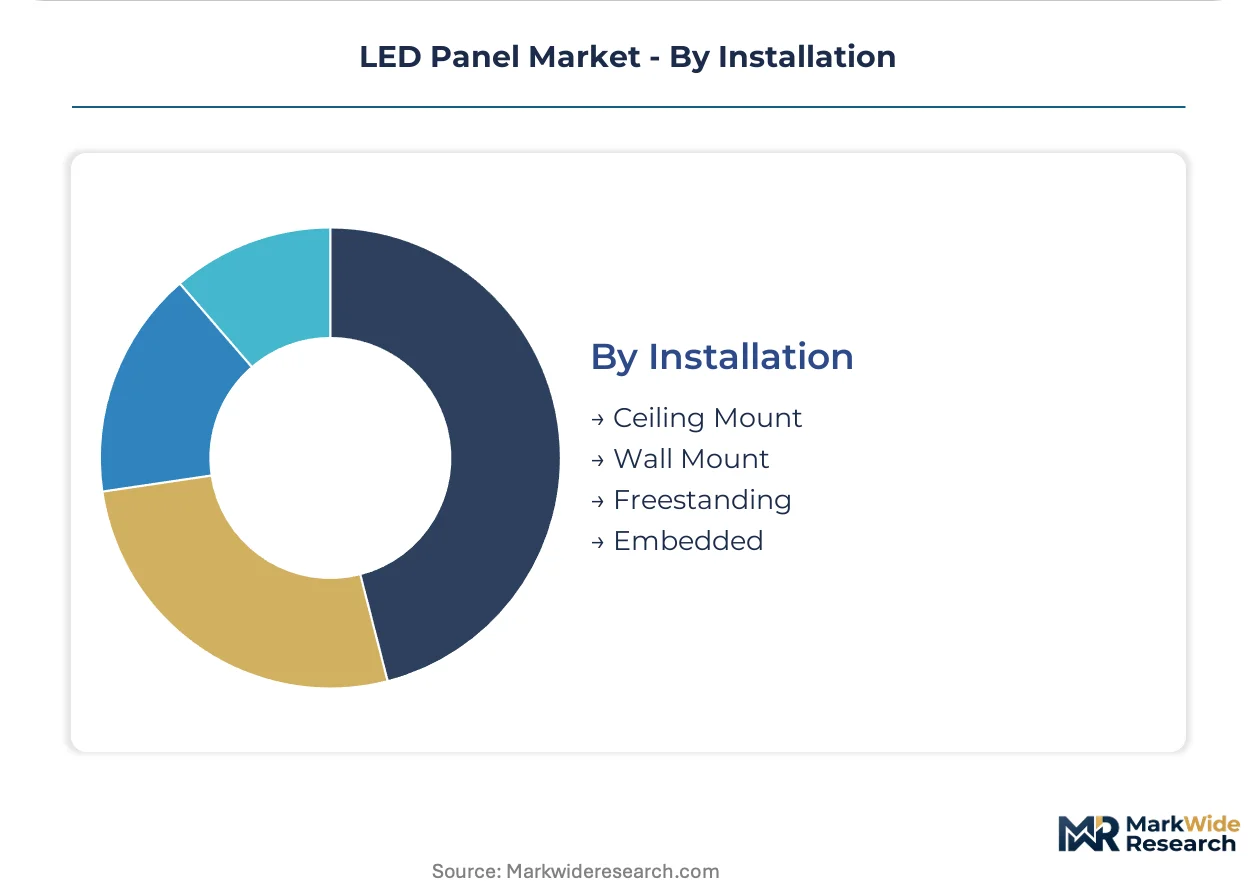
Installation:
Mounting configuration correlates directly with retrofit versus new-construction demand cycles, with ceiling and embedded variants dominating commercial replacement waves while freestanding gains traction in flexible workspace designs.
- Ceiling Mount:T-grid suspension and surface-mounted frames for 2x2 and 2x4 foot ceiling grids. Volume concentrates in US commercial retrofit waves where existing fluorescent troffer infrastructure enables drop-in LED replacement without structural modification.
- Embedded:Plaster-in or drywall-integrated flush mounting for seamless architectural finish. Premium specification is expanding in UAE and Saudi Arabia luxury commercial developments where aesthetic integration commands substantial pricing premiums.
- Wall Mount:Vertical surface mounting for cove lighting and wall-wash applications in retail and gallery contexts.
- Freestanding:Pole-mounted or floor-standing units for temporary and flexible workspace configurations.
Ceiling mount retains the largest installed base; embedded configurations are climbing fastest as new construction prioritizes architectural integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT's GB standards and tiered energy-labeling schemes are consolidating procurement toward Beijing-Tianjin-Hebei production networks with captive gallium nitride capacity. This regulatory architecture is reshaping competitive access across the three dominant manufacturing geographies.
China
Dual carbon goals and state-owned enterprise tender reforms are disqualifying legacy aluminum-substrate panels from public procurement. MIIT's updated efficiency thresholds favor Beijing-Tianjin-Hebei network participants with in-house semiconductor foundry linkages. Pearl River Delta manufacturing clusters are retooling assembly lines for Mini LED die-bonding operations.
Germany
Commercial real estate investment trusts in Düsseldorf and Frankfurt retrofit clusters are bypassing electrical distributors for direct Shenzhen supplier frameworks on large-scale projects. The EU Green Deal's Ecodesign Directive and CSRD disclosure obligations are accelerating specification for tunable-white circadian systems in healthcare and education facilities. Industrial corridor demand concentrates in North Rhine-Westphalia's Class A office repositioning wave.
United States
Title 24 in California and Local Law 97 in New York are tightening efficacy mandates for commercial office retrofits. OSHA workplace illumination requirements are expanding specification for human-centric lighting in Illinois and Texas educational facilities. Drop-in fluorescent replacement volume concentrates in existing 2x2 and 2x4 ceiling grid infrastructure across major metro markets.
South Korea
Captive semiconductor foundry capacity is securing gallium nitride substrate supply chains for high-efficacy chip architectures. Samsung Electronics leverages domestic packaging expertise to anchor premium display panel output. Seoul-based suppliers are capturing automotive cockpit display specifications where thermal management capabilities transfer from architectural applications.
United Arab Emirates
Luxury commercial developments in Dubai and Abu Dhabi are specifying embedded plaster-in panels where aesthetic integration commands substantial pricing premiums. Broadcast and critical infrastructure operators are demanding seamless modular configurations for 24/7 operations centers. Saudi Arabia's NEOM and Red Sea projects are extending Gulf demand for scalable command-center deployments.
LED Panel Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the LED panel market. The vendor base separates into semiconductor-integrated manufacturers with captive foundry access, legacy lighting conglomerates with distribution depth, and specialized display panel fabricators with optical engineering concentration. Three strategic archetypes dominate: foundry-linked Asian electronics groups, European industrial lighting houses with retrofit service capabilities, and Chinese scale producers with state-tender access. Competitive moves concentrate on backward integration into gallium nitride substrate supply and direct procurement relationship cultivation with commercial real estate operators.
Within the semiconductor-integrated tier, Samsung Electronics and LG Display exemplify foundry-linked positioning through their domestic packaging capabilities and display technology heritage. BOE Technology Group anchors the Chinese state-tender vector through its Beijing-Tianjin-Hebei production network concentration. These three entities represent distinct competitive positioning: Korean electronics groups leveraging captive supply chains, and Chinese scale producers consolidating domestic procurement access under MIIT efficiency mandates.
| Leading Market Players |
|---|
| Samsung Electronics |
| LG Display |
| BOE Technology Group |
| Leyard |
| Absen |
| Unilumin |
| Signify (Philips Lighting) |
| OSRAM |
| Panasonic Corporation |
| Others |
Value Network & Pricing Analysis
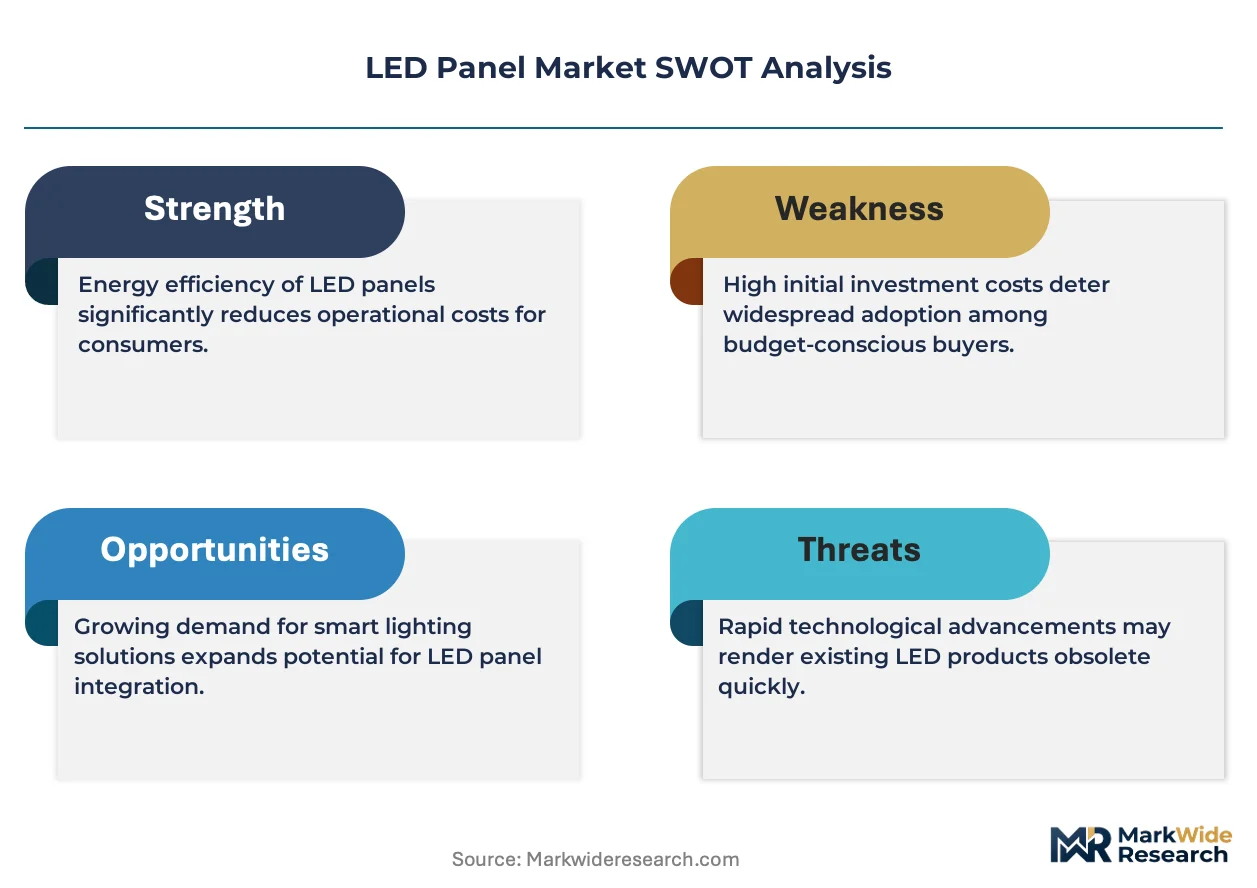
Gallium nitride substrate substitution for legacy aluminum-based architectures simultaneously concentrates supply geography in South Korean and Taiwanese captive foundry networks while compressing pricing economics for mid-tier panel manufacturers lacking semiconductor packaging capabilities. This input transition privileges vertically integrated electronics groups with in-house gallium nitride capacity, widening cost-structure dispersion between premium and standard tiers.
Pricing Analysis
Price spreads between Shenzhen-exported flat panels and Seoul-manufactured Mini LED configurations exceed three-to-one multiples, reflecting semiconductor packaging premiums against commodity edge-lit volumes. Three-tier pricing structure across premium, standard, and economy levels separates foundry-linked manufacturers from aluminum-substrate assemblers from unbranded export traders. Cost compression in standard-tier fluorescent replacements intensifies as China's MIIT efficiency thresholds disqualify legacy designs from state procurement. Commercial real estate investment trusts exhibit lowest price sensitivity, while residential distributor channels face acute margin pressure from big-box retail concentration.
Supply Chain Analysis
Strategic stockpiling of rare-earth phosphors dominates inventory strategy as europium and terbium supply concentrates in Chinese refining corridors, contrasting with just-in-time gallium nitride wafer flows from South Korean foundries. Manufacturing capacity clusters in China, South Korea, and Taiwan, with Beijing-Tianjin-Hebei networks feeding domestic procurement and Seoul-Taichung corridors anchoring premium display output. Raw material dependencies center on gallium nitride substrates, rare-earth phosphor formulations, and optical-grade polycarbonate diffusers. Single-source vulnerability in Chinese rare-earth refining creates structural exposure to export restriction shocks. Distribution runs through electrical distributor networks for residential and small commercial volumes, while direct manufacturer relationships dominate Class A office retrofit procurement in Germany and the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wafer-level packaging talent scarcity defines competitive advantage in this market, with optical engineering specialists migrating from legacy LCD fabrication toward Mini LED die-bonding operations and creating acute capability gaps for mid-tier manufacturers.
For Market Incumbents: Fortify captive semiconductor foundry linkages to secure gallium nitride substrate supply against rare-earth phosphor cost volatility. Deepen direct procurement relationships with German commercial real estate investment trusts in Düsseldorf and Frankfurt retrofit clusters to bypass distributor margin extraction. Prioritize CE marking and GB standard dual certification investment to compress product development cycles threatened by simultaneous compliance timelines. For New Entrants and Emerging Players: Differentiate on human-centric circadian lighting specifications where OSHA workplace illumination guidelines and CSRD disclosure obligations are expanding addressable demand in healthcare and education verticals. Target Dutch healthcare facilities and Illinois K-12 systems as most penetrable specification environments. Pursue modular command-center configurations for UAE and Saudi Arabia broadcast operators demanding seamless scalability, leveraging project-based go-to-market approaches with systems integration partnerships. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed European industrial lighting houses possessing retrofit service capabilities but lacking semiconductor packaging depth. Long-term viability across the analysis window favors foundry-linked Asian electronics groups with gallium nitride captive supply and Chinese scale producers with Beijing-Tianjin-Hebei network access under MIIT efficiency mandates. Monitor mass-transfer yield rate breakthroughs in Micro LED architectures as inflection indicator for premium display panel substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Gallium Nitride Substrates | Captive semiconductor foundry capacity secures supply chains against Chinese rare-earth refining concentration. |
| Dual Certification Investment | Simultaneous CE marking and GB standard compliance compresses product development cycles for cross-border market access. |
| Direct Procurement Relationship Cultivation | Bypassing electrical distributors captures margin pools in German commercial real estate retrofit clusters. |
| Human-Centric Circadian Lighting Development | OSHA workplace standards and CSRD obligations expand specification in Dutch healthcare and Illinois education facilities. |
| Modular Command-Center Configuration Scale-Up | Seamless bezel-free tiling systems command premium positioning in UAE and Saudi Arabia 24/7 operations centers. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with LED panel procurement directors, semiconductor packaging engineers, commercial real estate facilities managers, and lighting specification consultants; and secondary validation through MIIT efficiency standard filings, EU Ecodesign Directive regulatory texts, SEC 10-K disclosures from listed electronics groups, and customs trade data from German and Chinese import registries. Bottom-up volume triangulation from manufacturing capacity assessments was cross-referenced against top-down demand aggregation from retrofit project pipelines.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product architecture, technology tier, end-use vertical, and mounting configuration, with regional regulatory cluster effects integrated as overlay variables. CAGRs were derived from slope-consistency checks against historical efficiency mandate adoption curves and gallium nitride substrate supply expansion trajectories. Forecast inputs incorporated commercial office retrofit permit velocities in California and New York, plus state-owned enterprise tender reform timelines under China's dual carbon goals.
Material uncertainties — rare-earth export restriction shocks, Micro LED mass-transfer yield breakthroughs, and right-to-repair legislative passage — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and foundry capacity expansion schedules. Revision becomes warranted when gallium nitride substrate spot pricing volatility or EU repairability index implementation crosses threshold levels that reshape total-cost-of-ownership calculations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
US Outdoor LED Lighting Market
LED
LED Digital Scoreboard Market
LED
Japan Outdoor LED Lighting Market
LED
Europe Indoor LED Lighting Market
LED
Africa LED Lighting Market
LED
Bluetooth LED Bulb Market
LED
Organic Light Emitting Diode (OLED) Market
LED
LED and OLED Display Market
LED
LED Display Market
LED
LED Panel Light Drivers Market
LED
LED Control Unit Market
LED
France LED Lighting Market
LED
Pixel Pitch LED Market
LED
High Power LED Market
LED
China LED Market
LED
Microled Market