
 Biometrics Infrared LED Market | 2026-2036
Biometrics Infrared LED Market Size, Share, and Industry Trends Forecast 2026-2036
Biometrics Infrared LED Market Intelligence
The asset-light fabless model, which outsources capital-intensive wafer fabrication to third-party foundries, is rewriting the competitive structure for specialized IR LED suppliers. This allows design-focused firms to challenge established integrated device manufacturers. The highly integrated ams-OSRAM International leverages its extensive manufacturing scale to serve high-volume customers. In contrast, Nichia Corporation differentiates through its deep expertise in phosphors and advanced semiconductor materials.
Biometrics infrared LEDs are semiconductor light sources engineered to emit non-visible radiation, typically in the near-infrared spectrum between 850nm and 940nm. This specific wavelength range enables biometric scanners to capture detailed patterns of irises, faces, or veins for identity verification. Near Infrared LED products dominate sales volume, driven by their use in smartphones and access control systems. Within technology, Vertical Cavity Surface Emitting Laser (VCSEL) arrays represent the fastest-growing segment due to superior performance in 3D sensing applications.
Product design must adhere to photobiological safety standards like IEC 62471 to prevent eye damage from high-intensity infrared emissions. Concurrently, the use of biometric data captured by these systems is governed by stringent privacy regulations, including the EU's GDPR, which impacts system deployment in corporate and public sectors. Future development will focus on achieving higher radiant intensity and efficiency while managing thermal output in increasingly compact mobile and wearable devices.
Market Dynamics
The market's competitive structure is being reshaped by the technological migration from traditional near-infrared LEDs to Vertical Cavity Surface Emitting Laser arrays. This shift is driven by the performance requirements of 3D sensing in high-volume consumer electronics, altering both cost structures and supplier capabilities.
Growth Catalysts
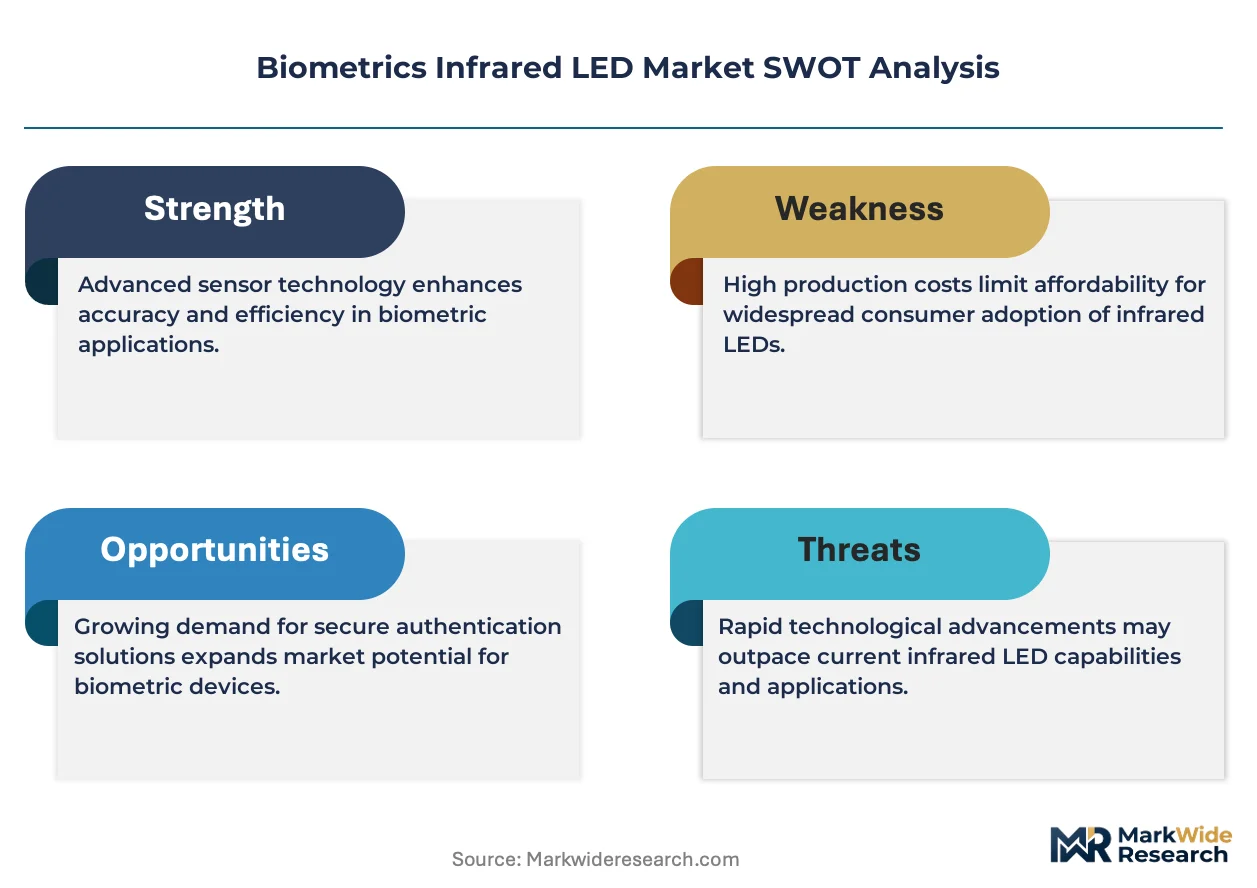
- Consumer Electronics Integration:The proliferation of facial recognition for device unlocking and payment authentication in smartphones serves as the primary volume driver.
- Automotive Sector Adoption:Demand for driver monitoring systems to detect drowsiness and distraction, mandated by entities like Euro NCAP, creates new applications.
- Public Security Mandates:Government investments in biometric border control and national ID programs, particularly in Asia and the Middle East, expand large-scale deployments.
Market Restraints
- Photobiological Safety Compliance:Adherence to stringent eye safety standards like IEC 62471 adds significant testing overhead and design constraints for high-power emitters.
- Thermal Management Demands:The high radiant intensity required for accurate sensing generates substantial heat, posing a key engineering challenge in compact mobile devices.
- Substrate Material Dependency:Reliance on a concentrated supply base for specialized semiconductor materials like gallium arsenide (GaAs) exposes manufacturers to price volatility.
Strategic Opportunities
- Healthcare Biometrics:Untapped demand exists for patient identification systems in hospitals and clinics to reduce administrative errors and enhance security.
- Miniaturization for Wearables:Developing ultra-compact, low-power IR LEDs opens the market for biometric authentication in smartwatches, fitness trackers, and AR glasses.
- Industrial IoT Security:Application in secure access control for restricted areas in manufacturing plants, data centers, and research laboratories represents a growth vector.
Industry Challenges
- System Integration Complexity:Ensuring seamless hardware and software interoperability between the IR LED module, image sensor, and processing unit remains a significant hurdle.
- VCSEL Intellectual Property:Navigating a dense and often litigious patent landscape surrounding Vertical Cavity Surface Emitting Laser technology creates risk for new entrants.
- Standardization Gaps:A lack of uniform performance and testing standards across different biometric modalities can slow adoption and create market fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biometrics Infrared LED Market |
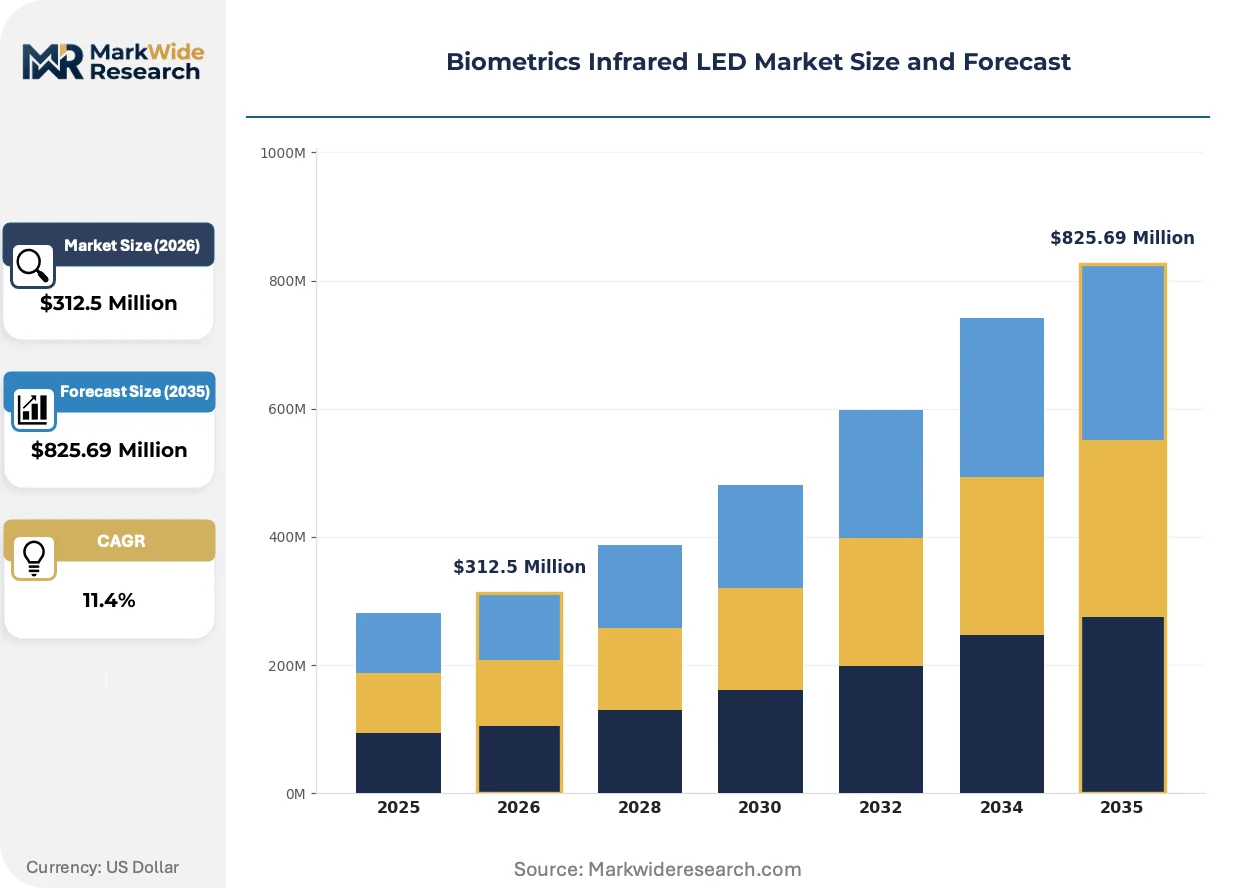
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $825.69 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Visible Infrared LED, Near Infrared LED, Short-Wave Infrared LED, Long-Wave Infrared LED Technology: Gallium Arsenide, Indium Gallium Arsenide, Silicon Photonics, Vertical Cavity Surface Emitting Laser Application: Smartphones, Access Control Systems, Banking Authentication, Employee Attendance Monitoring End User Sector: Consumer Electronics, Security Services, Financial Institutions, Corporate Enterprises |
| Companies Covered | EPILEDS Technologies, EPISTAR Corporation, Everlight Electronics, Excelitas Technologies, Nichia Corporation, ams-OSRAM International, Lumileds Holding, Lextar Electronics Corporation, Kingbright Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biometrics Infrared LED Market Strategic Shifts & Innovations
Component innovation is driven by the dual pressures of enhancing biometric accuracy while simultaneously reducing power consumption and thermal footprint. This dynamic forces a tighter coupling between emitter design, optical engineering, and system-level software to meet mobile device constraints.
Vertical Cavity Surface Emitting Laser (VCSEL) arrays provide highly uniform, narrow-beam illumination essential for structured light and time-of-flight 3D sensing. Smartphone original equipment manufacturers are rapidly adopting this technology for advanced facial recognition features. This adoption is collapsing the technical and cost barriers between simple 2D facial scanning and sophisticated 3D biometric verification.
Data privacy regulations, exemplified by the EU's GDPR, impose strict rules on the collection and processing of biometric identifiers. This directly influences system architecture, requiring features like on-device processing to minimize data transfer and enhance user consent mechanisms. The corporate access control and public sector segments in Europe are most affected, prioritizing compliance in procurement.
A behavioral shift is underway from procuring discrete components to sourcing pre-integrated optical modules. This change disrupts the role of broadline distributors, favoring suppliers offering a validated package of the IR LED, driver IC, and micro-optics. The trend is most pronounced within consumer electronics supply chains centered in China and South Korea.
Biometrics Infrared LED Market Segmentation
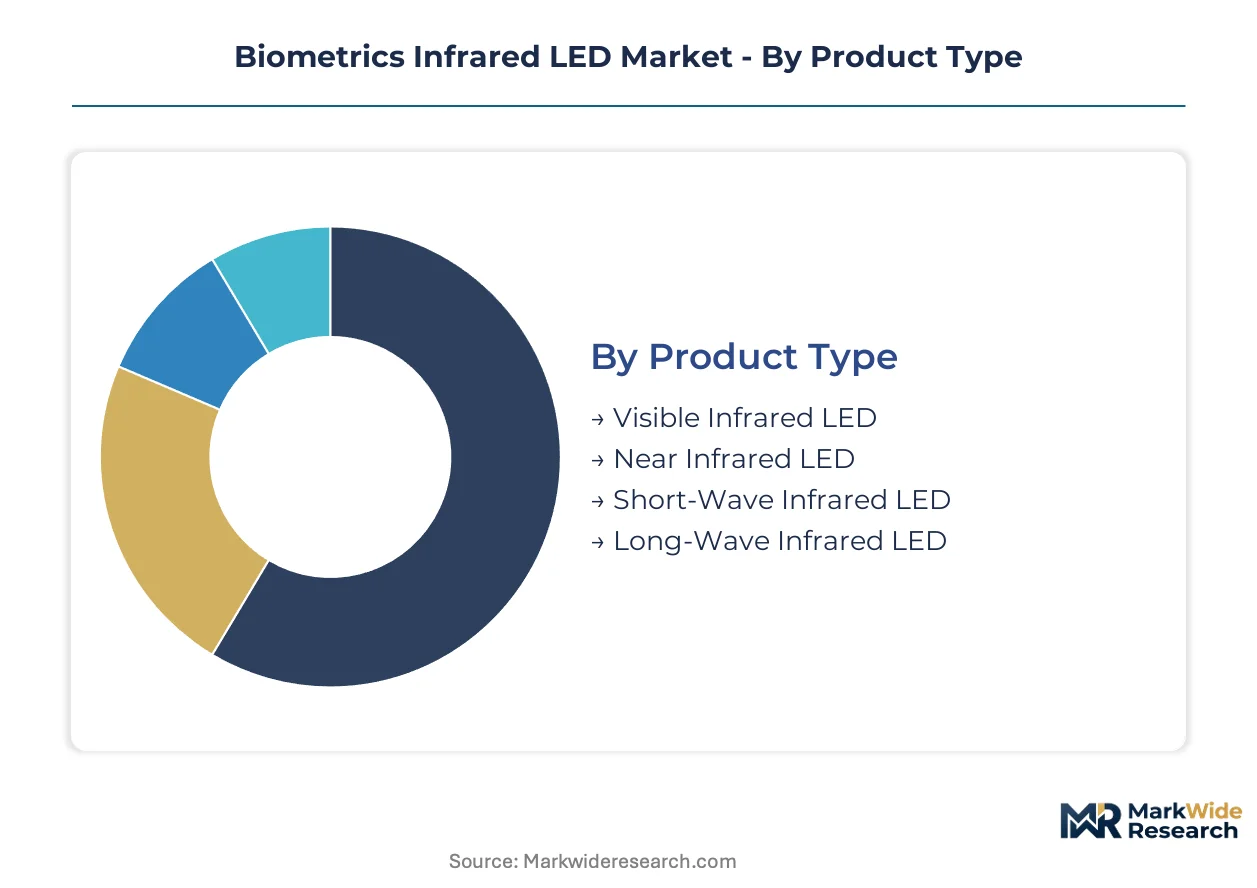
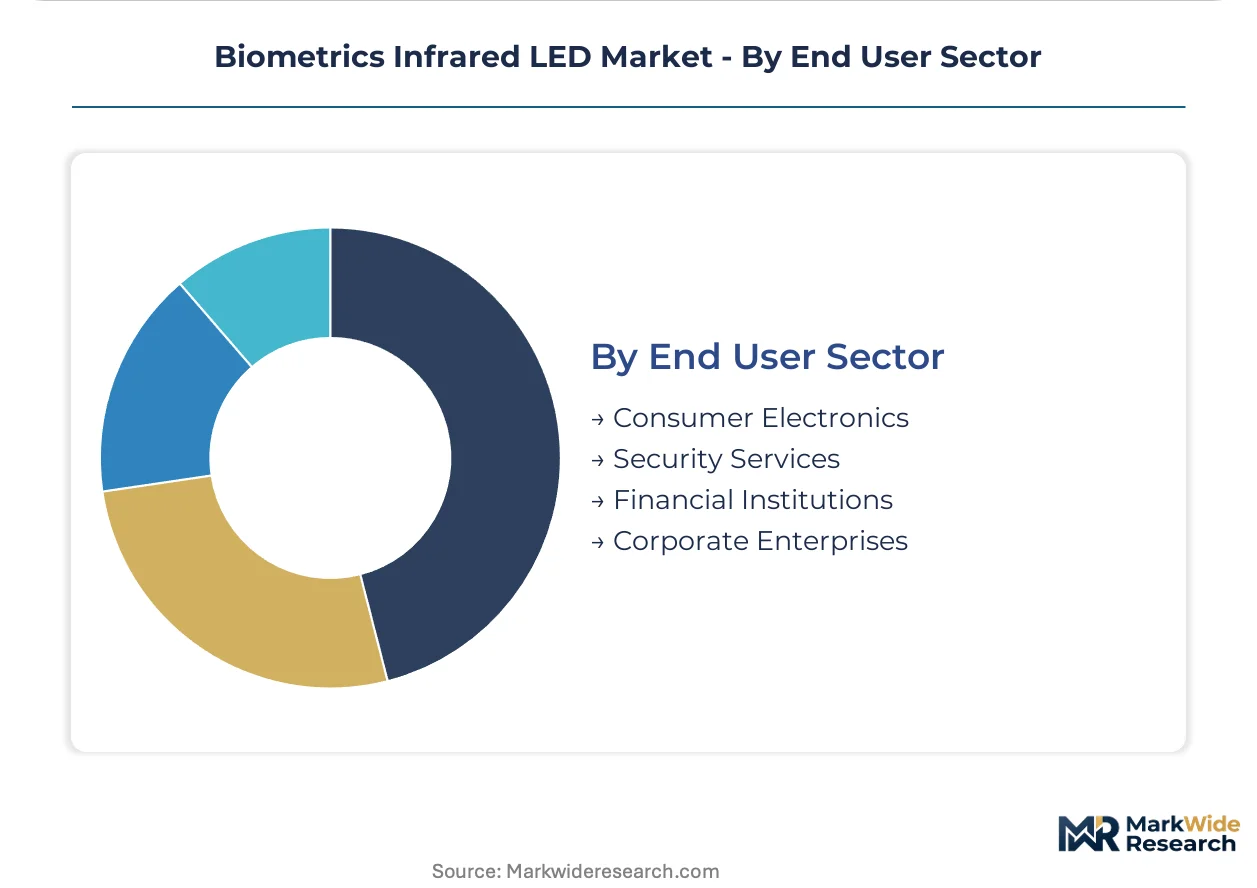
The Biometrics Infrared LED market is segmented to provide a detailed view of the diverse product types, underlying technologies, varied applications, and distinct end-user sectors. This granular breakdown helps identify specific growth pockets and understand the varying adoption rates across different market dimensions.
Product Type:
The Biometrics Infrared LED market's product segmentation reflects a spectrum of maturity, from established emitter types to cutting-edge light sources.
- Near Infrared LED:These semiconductor devices emit non-visible radiation, typically between 850nm and 940nm, enabling detailed pattern capture for iris, face, or vein recognition. Near Infrared LEDs dominate sales volume, primarily driven by their extensive use in smartphones for facial recognition and access control systems.
- Vertical Cavity Surface Emitting Laser:VCSEL arrays provide highly uniform, narrow-beam illumination critical for structured light and time-of-flight 3D sensing applications. Smartphone manufacturers rapidly adopt this technology for advanced facial recognition features, collapsing technical and cost barriers for sophisticated 3D biometric verification.
- Visible Infrared LED:These LEDs emit radiation in the visible spectrum, sometimes used in conjunction with IR for specific biometric capture requirements or user feedback.
- Short-Wave Infrared LED:SWIR LEDs offer unique spectral properties for advanced material analysis or specific biometric applications requiring deeper tissue penetration.
- Long-Wave Infrared LED:LWIR LEDs are used in thermal imaging applications, providing biometric data through heat signatures, particularly in challenging environmental conditions.
Near Infrared LED retains volume leadership; Vertical Cavity Surface Emitting Laser holds the steepest expansion curve.
Technology:
Technology segmentation underscores the application-specific demands driving material and design choices for biometrics infrared LEDs.
- Vertical Cavity Surface Emitting Laser:This technology provides superior performance in 3D sensing applications due to its precise, high-power, and uniform illumination characteristics. VCSEL arrays are crucial for advanced facial recognition and gesture control in consumer electronics.
- Gallium Arsenide:GaAs is a foundational semiconductor material for high-performance infrared LEDs, offering excellent electron mobility and direct bandgap properties for efficient light emission. Reliance on a concentrated supply base for GaAs exposes manufacturers to price volatility, impacting production costs.
- Indium Gallium Arsenide:InGaAs technology is primarily used for detectors and some emitters in the longer near-infrared and short-wave infrared ranges, offering enhanced sensitivity for specific biometric applications.
- Silicon Photonics:This emerging technology integrates optical functions onto silicon chips, promising miniaturization, lower power consumption, and cost reductions for future biometric sensing modules.
Vertical Cavity Surface Emitting Laser technology continues its rapid adoption, while Gallium Arsenide remains fundamental for high-performance devices.
Application:
Application segmentation reveals the primary areas where biometrics infrared LEDs are integrated, driven by distinct security and convenience requirements.
- Smartphones:The proliferation of facial recognition for device unlocking and payment authentication in smartphones serves as the primary volume driver for biometrics infrared LEDs. This application demands compact, high-efficiency emitters.
- Access Control Systems:These systems utilize infrared LEDs for secure entry and exit, verifying identity through iris, face, or vein patterns in corporate, government, and public facilities. Public security mandates drive large-scale deployments.
- Banking Authentication:Financial institutions deploy biometric infrared LED systems for secure transactions, customer identification, and ATM access, enhancing fraud prevention.
- Employee Attendance Monitoring:Biometric solutions using infrared LEDs provide accurate and tamper-proof methods for tracking employee presence in various organizational settings.
Smartphones command the largest share of deployments, with access control systems showing consistent growth in commercial settings.
End User Sector:
End user sector segmentation highlights the diverse institutional and consumer segments adopting biometric infrared LED technology for identity verification.
- Consumer Electronics:This sector, primarily driven by smartphone integration, represents the largest volume market for biometrics infrared LEDs due to widespread adoption of facial recognition. Miniaturization and power efficiency are critical design considerations for these devices.
- Security Services:Government investments in biometric border control, national ID programs, and public safety initiatives drive demand within the security services sector. These applications often require robust, high-reliability systems for large-scale deployments.
- Financial Institutions:Banks and other financial entities implement biometric infrared LED solutions for secure customer authentication, transaction verification, and physical access control.
- Corporate Enterprises:Businesses utilize biometrics infrared LEDs for employee attendance, secure facility access, and data center security, enhancing operational integrity.
Consumer Electronics drives the highest unit volumes, while Corporate Enterprises increasingly implement these systems for secure operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government mandates for public security and incentives for advanced manufacturing are shaping the geographic distribution of biometrics infrared LED demand and supply. These policies influence deployment scales in consumer electronics and national identification programs. The market sees significant activity across key technology and manufacturing hubs globally.
China
China's robust consumer electronics market drives substantial demand for biometrics infrared LEDs in smartphones. The MIIT's industrial policies support domestic VCSEL array production and advanced packaging technologies. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are key for both domestic supply and global exports.
United States
Demand for biometrics infrared LEDs in the United States stems from widespread smartphone adoption and growing interest in automotive driver monitoring systems. HIPAA regulations influence patient identification systems in healthcare, requiring secure data handling. Silicon Valley and other tech hubs foster innovation in miniaturized biometric sensing modules.
Germany
Automotive sector mandates, particularly from Euro NCAP, drive demand for infrared LEDs in driver monitoring systems across Germany. The EU's GDPR significantly impacts corporate access control deployments, prioritizing data privacy and on-device processing. Bavaria and Baden-Württemberg host key automotive and industrial electronics manufacturers.
India
Public security mandates and national ID programs, such as Aadhaar, fuel large-scale deployments of biometrics infrared LEDs in India. The BIS sets standards for electronic components, influencing product quality and reliability for local integration. Bengaluru and Hyderabad are emerging centers for biometric system integration and software development.
Japan
Innovation in compact wearables and advanced robotics creates specific demand for high-efficiency infrared LEDs in Japan. METI policies encourage R&D in next-generation optoelectronics and photonics for industrial applications. Tokyo and Osaka remain critical hubs for precision manufacturing and advanced component development.
Biometrics Infrared LED Market Key Industry Players
On the supply side, the industry is characterized by a tiered structure, encompassing both highly integrated device manufacturers and specialized fabless design houses. Integrated players leverage extensive manufacturing scale, while design-focused firms challenge established incumbents through agile innovation. Strategic archetypes include vertically integrated giants, specialized component providers, and module assemblers. Dominant competitive moves involve technology licensing agreements and strategic partnerships for system integration.
On the integrated solutions vector, ams-OSRAM International, an Austria-based AG, occupies a strong position by leveraging its extensive manufacturing capabilities. Nichia Corporation, a Japan-based Corporation, exemplifies differentiation through its deep expertise in phosphors and advanced semiconductor materials. EPISTAR Corporation, a Taiwan-based Corporation, represents a key player specializing in LED chip manufacturing, supplying various downstream applications.
| Leading Market Players |
|---|
| EPILEDS Technologies |
| EPISTAR Corporation |
| Everlight Electronics |
| Excelitas Technologies |
| Nichia Corporation |
| ams-OSRAM International |
| Lumileds Holding |
| Lextar Electronics Corporation |
| Kingbright Company |
| Others |
Cost & Logistics Intelligence
Gallium arsenide (GaAs) substrate supply concentration in a few key regions impacts margin pools for specialized IR LED manufacturers. This upstream dependency influences pricing power throughout the biometrics infrared LED value chain.
Pricing Analysis
Performance tier and certification level create the primary spread in biometrics infrared LED pricing. High-volume consumer electronics OEMs typically engage in contract-based long-term offtake agreements. Price differentiation stems from factors like radiant intensity, wavelength precision, and adherence to photobiological safety standards like IEC 62471. Pricing pressure intensifies for standard near-infrared LEDs due to commoditization and increased manufacturing scale. Consumer electronics manufacturers exhibit the highest price sensitivity, while public security and healthcare applications prioritize performance and reliability over cost.
Supply Chain Analysis
Reliance on a concentrated supply base for specialized semiconductor materials like gallium arsenide (GaAs) exposes manufacturers to commodity price volatility. China, Taiwan, and Japan serve as primary manufacturing hubs for IR LED components. Key dependencies include high-purity GaAs wafers and advanced packaging materials. Logistics chokepoints, particularly for air freight of sensitive components, represent a structural risk. Distribution runs through direct sales channels to large original equipment manufacturers and specialized electronics distributors serving smaller integrators and module assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biometrics infrared LED market represents a high-growth disruption, driven by the technological inflection of VCSEL arrays enabling advanced 3D sensing.
For Market Incumbents: Pre-empt emerging fabless competitors by investing in next-generation VCSEL array R&D. Acquire specialized intellectual property in advanced optical design and thermal management to maintain a performance edge. Expand manufacturing capacity in key regions like China to serve high-volume consumer electronics demand. Vertical integration into advanced packaging solutions will secure supply and enhance product differentiation against agile design-focused firms.
For New Entrants and Emerging Players: Pursue niche applications in healthcare biometrics, where specific performance requirements allow for premium pricing. Target patient identification systems in hospitals and secure access for industrial IoT environments, leveraging miniaturization and low-power consumption. Develop strategic partnerships with system integrators to offer validated, pre-integrated optical modules. Focus on a go-to-market strategy that emphasizes tailored solutions and robust software interoperability.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-sized firms specializing in VCSEL technology with strong patent portfolios. These companies offer proprietary designs critical for advanced 3D sensing and miniaturization. Long-term viability hinges on the sustained demand for secure authentication across mobile, automotive, and public security sectors. The signal to watch for inflection is increased merger and acquisition activity for specialized IP and design expertise.
| Strategic Initiative | Industry Significance |
|---|---|
| VCSEL Technology Licensing | Accelerates market entry for new players in 3D sensing applications. |
| Advanced Thermal Management R&D | Enables higher radiant intensity in compact mobile and wearable devices. |
| Strategic Partnerships with System Integrators | Facilitates broader market penetration beyond component sales for IR LED suppliers. |
| Expansion of GaAs Wafer Production | Mitigates supply chain risks and reduces material cost volatility for manufacturers. |
| Investment in Photobiological Safety Certification | Ensures compliance with IEC 62471, critical for high-power emitter deployment. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, technical journals, and industry association reports. This approach involved extensive interviews with R&D engineers, product managers, procurement leads at consumer electronics OEMs, and supply chain managers. Secondary data sources included IEC standards documentation, EU GDPR impact assessments, and financial reports from key market players. Bottom-up and top-down triangulation validated market sizing and growth projections.
Forecast inputs consider technological migration from traditional near-infrared LEDs to VCSEL arrays, alongside end-user adoption rates across various applications. The analytical framework modeled segmentation dimensions including product type, technology, application, end-user sector, and regional policy mandates. Compound annual growth rates were derived from historical trends, expert projections, and identified market drivers. Industry-specific forecast inputs included smartphone shipment forecasts and automotive safety mandate timelines.
Macroeconomic conditions sit as an overlay; deviation in global semiconductor supply or consumer spending would shift the trajectory of biometrics infrared LED adoption. Forecasts reflect assumptions regarding technological maturation, regulatory stability, and sustained demand for secure biometric authentication. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global LED Phosphor Market
LED
LED Light Market
LED
Micro LED Display Market
LED
LED Digital Scoreboard Market
LED
Thailand LED Market
LED
LED Lighting Market
LED
LED Mask Market
LED
OLED Blue Emitter Market
LED
High-Intensity LED Logo and Livery Lighting Systems Market
LED
Japan LED Lighting Market
LED
Programmable LED Drivers Market
LED
Outdoor LED Display Market
LED
Small Pitch LED Display Market
LED
LED Driver Market
LED
Egypt LED Lighting Market
LED
Global Waterproof LED Module Market