
 Latin America Optical Imaging Market | 2026-2036
Latin America Optical Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Optical Imaging Market Foresight
Hospital procurement consolidation across Brazil and Mexico is repositioning vendor relationships toward integrated service contracts. Bruker Corporation leverages its spectroscopy heritage to anchor research institution sales across the region. Carl Zeiss AG sustains dominance in retinal imaging through captive service networks in São Paulo and Mexico City. Olympus Corporation specializes in endoscopy systems for surgical assistance applications, competing on optical clarity specifications.
Optical imaging encompasses non-invasive techniques that capture photon-based contrast from biological tissues, typically operating across visible to near-infrared wavelengths with spatial resolutions reaching the sub-micron scale in confocal configurations. These systems serve diagnostic, intraoperative guidance, and preclinical research functions by converting optical signals into structural or functional maps. Spectral domain OCT leads product type demand due to its speed advantages in ocular disease diagnosis workflows, while photoacoustic imaging captures the fastest expansion as research institutions adopt hybrid modalities. Endoscopy systems retain mature margin pools in hospital accounts with long replacement cycles.
ANVISA in Brazil and COFEPRIS in Mexico shape market access through medical device classification and post-market surveillance requirements, with both agencies tightening quality system inspections for imported imaging equipment. The region's national standards bodies align progressively with IEC 60601 safety benchmarks, raising compliance costs for non-compliant vendors. Stakeholders must monitor regulatory reciprocity negotiations between Mercosur and Pacific Alliance frameworks to anticipate harmonized approval pathways.
Market Dynamics
Hospital procurement consolidation across Brazil and Mexico is compressing vendor margins and forcing equipment suppliers to bundle maintenance, training, and consumables into multi-year service contracts rather than standalone hardware sales.
Growth Catalysts
- Spectral domain OCT speed advantages:Ophthalmology departments in São Paulo and Rio de Janeiro are replacing time-domain systems to accelerate patient throughput in glaucoma and macular degeneration screening workflows.
- ANVISA pathway compression:Brazil's streamlined medical device registration for imported imaging equipment is reducing approval timelines and accelerating market entry for advanced confocal microscopy systems.
- Oncology department investment:Leading cancer centers in Mexico City and Monterrey are expanding intraoperative imaging capabilities to support precision tumor margin delineation during resection procedures.
Market Restraints
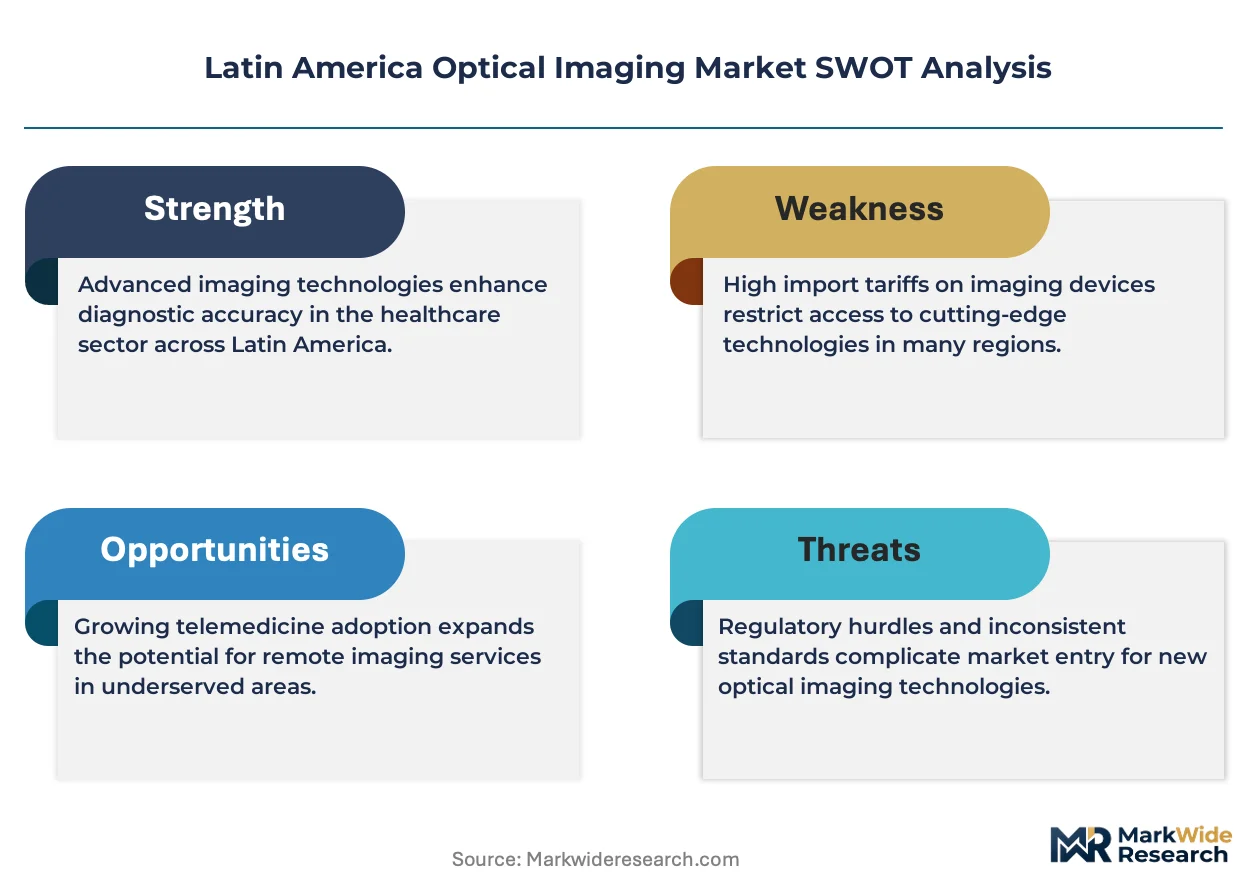
- Import dependency for core optics:Latin American manufacturers lack domestic production of high-precision lenses and laser sources, exposing buyers to currency volatility and extended lead times from German and Japanese suppliers.
- COFEPRIS inspection bottlenecks:Mexico's medical device regulator is intensifying quality system audits for foreign imaging equipment, creating unpredictable delays for new product introductions.
- Fluoroscopy substitution in surgical guidance:Some hospital procurement committees continue favoring established radiological imaging modalities over optical alternatives for intraoperative navigation due to reimbursement familiarity.
Strategic Opportunities
- Colombia's underpenetrated Andean corridor:Medellín and Bogotá university hospitals are expanding research imaging infrastructure with limited incumbent vendor presence, creating first-mover openings for confocal and multiphoton systems.
- Photoacoustic-radiology convergence:Hybrid optical-acoustic imaging platforms are attracting funding from Brazil's FAPESP research foundation for preclinical oncology and cardiovascular applications.
- Telemedicine-enabled remote diagnostics:Satellite-connected OCT screening units are reaching underserved populations in Brazil's northern states through mobile clinic partnerships with state health secretariats.
Industry Challenges
- Biomedical optics specialist scarcity:Brazil and Mexico face acute shortages of trained service engineers capable of maintaining spectral domain OCT and multiphoton microscopy systems, forcing vendors to fly technicians from São Paulo or Mexico City to regional installations.
- IEC 60601-1 third edition compliance costs:Smaller regional distributors struggle to fund electromagnetic compatibility testing and clinical safety documentation required for ANVISA and COFEPRIS approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Optical Imaging Market |
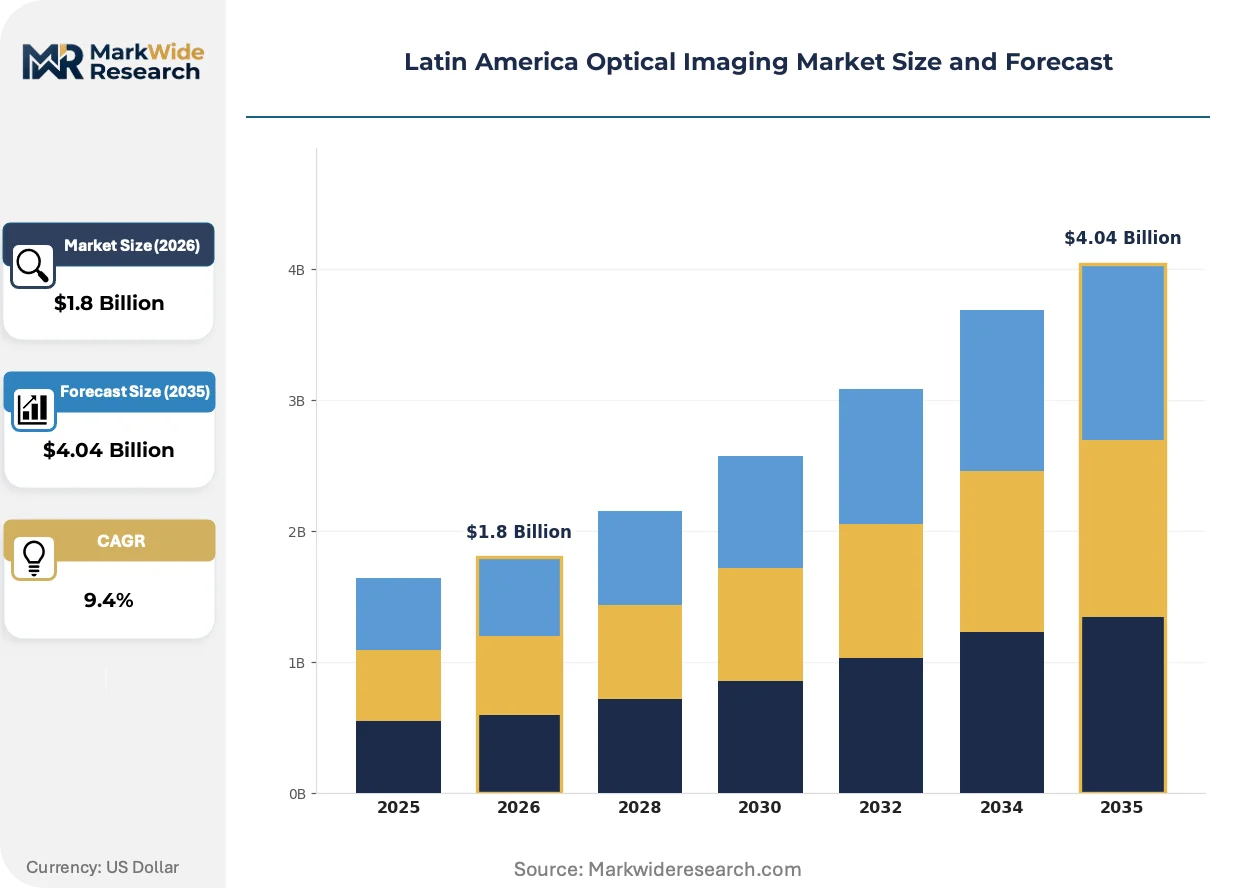
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fundus Cameras, OCT Scanners, Retinal Imaging Devices, Endoscopy Systems Technology: Fluorescence Imaging, Photoacoustic Imaging, Confocal Microscopy, Spectral Domain OCT End User: Hospitals, Research Institutions, Diagnostic Laboratories, Specialty Clinics Application: Ocular Disease Diagnosis, Surgical Assistance, Clinical Research, Patient Monitoring |
| Companies Covered | Bruker Corporation, Carl Zeiss AG, Leica Microsystems, CytoViva Inc, Olympus Corporation, Topcon Corporation, PerkinElmer Inc, Abbott Laboratories, Heidelberg Engineering, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Optical Imaging Market Shifts & Advancements
Optical imaging architecture is pivoting from hardware-centric sales toward integrated data platforms, with vendors embedding AI-assisted diagnostic workflows and cloud-based image management to lock in recurring revenue streams.
Spectral domain OCT is overtaking time-domain configurations in retinal imaging installations across Latin America's leading ophthalmology centers. The technology's superior acquisition speed allows Brazilian clinics to process 40-50 additional patients daily. Hospital procurement committees in São Paulo are now specifying SD-OCT as minimum viable capability in replacement tenders, marginalizing vendors without competitive offerings.
ANVISA's updated medical device registration framework is compressing approval timelines for imported imaging equipment while tightening post-market surveillance obligations. Foreign manufacturers must now maintain local adverse event reporting infrastructure and periodic safety updates. COFEPRIS in Mexico is adopting similar risk-based classification approaches, creating regulatory convergence pressure across the Mercosur-Pacific Alliance corridor.
Consolidated purchasing by Brazilian hospital networks is unbundling traditional equipment-maintenance-consumable bundles. Large southeastern health systems now negotiate optical imaging hardware through centralized tenders while sourcing service contracts separately to regional technical providers. Mexico's IMSS and ISSSTE federal health institutions are piloting similar decoupled procurement models in Mexico City and Guadalajara metropolitan zones.
Latin America Optical Imaging Market Segmentation
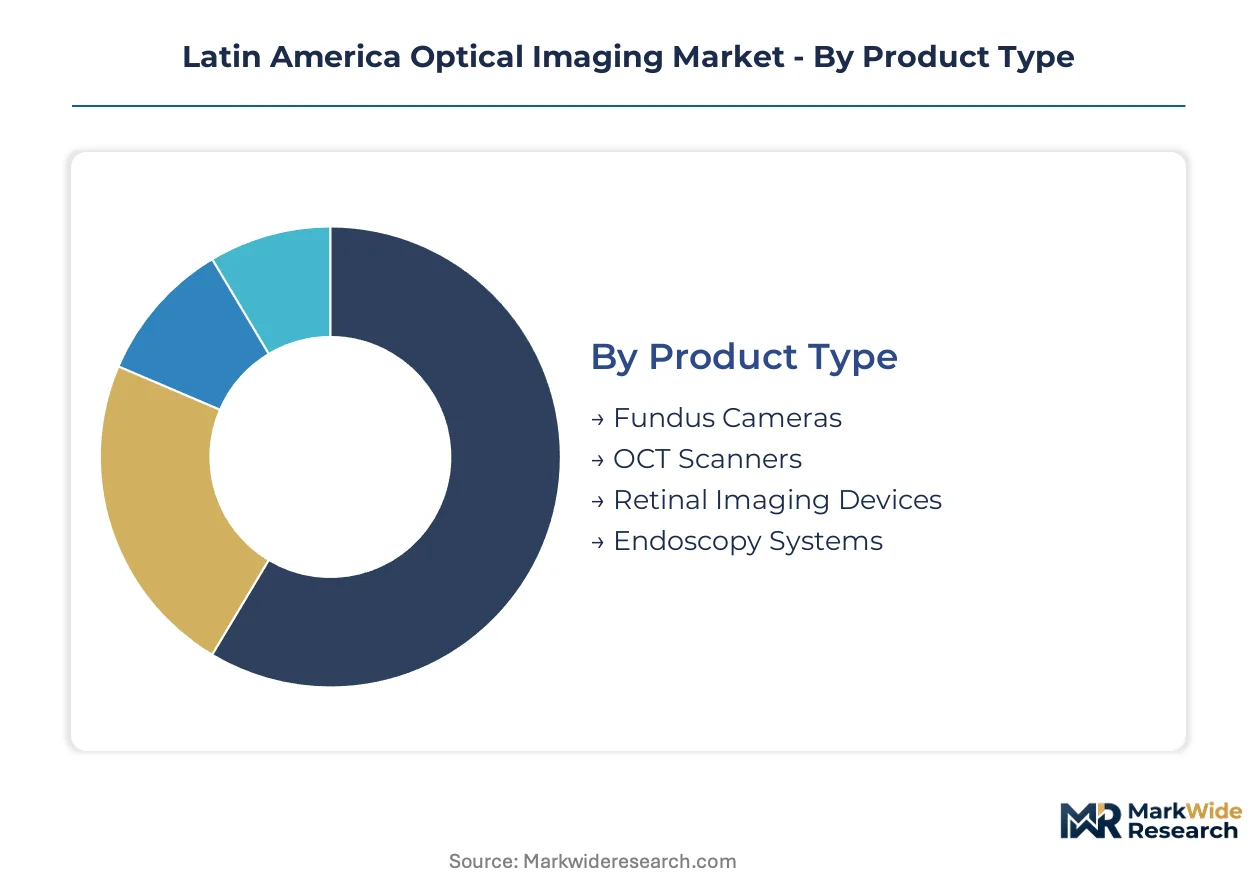
Optical imaging procurement across Latin America fragments along regulatory burden lines, with ANVISA Class III pathways favoring established product categories while research-oriented technologies navigate lighter notification routes. Understanding these segment-specific approval economics shapes vendor portfolio prioritization and distributor capability investments.
Product Type:
ANVISA risk classification tiers directly shape registration costs and timeline economics across hardware categories, with active diagnostic equipment commanding the most intensive quality system audits.
- OCT Scanners:Spectral-domain configurations dominate hospital procurement specifications across São Paulo and Rio de Janeiro ophthalmology departments. Brazilian health networks now mandate SD-OCT minimum capability in replacement tenders, displacing time-domain legacy installations and compressing vendor margins through bundled service contract demands.
- Endoscopy Systems:Rigid and flexible optical scopes for surgical assistance carry mature installed bases across Mexico's IMSS facilities. COFEPRIS quality system inspections for imported laparoscopic and arthroscopic systems have intensified, creating unpredictable approval delays for new market entrants.
- Fundus Cameras:Non-mydriatic retinal imaging units serve primary screening workflows in Brazil's northern state health secretariat mobile clinics.
- Retinal Imaging Devices:Confocal scanning laser ophthalmoscopes concentrate in academic medical centers with research funding from FAPESP and CONACYT.
Leading the category by volume: OCT Scanners. Growing fastest: Retinal Imaging Devices.
Technology:
Cost tier stratification separates capital-intensive hybrid modalities from established single-physics platforms, with research grant funding determining adoption velocity for emerging techniques.
- Spectral Domain OCT:Interferometric depth-resolved imaging at 840nm or 1050nm wavelengths enables 40-50 additional daily patient screenings in high-volume Brazilian glaucoma clinics. Acquisition speed advantages over time-domain predecessors justify premium pricing in hospital network consolidated tenders.
- Photoacoustic Imaging:Hybrid optical-acoustic signal generation captures functional hemoglobin and oxygen saturation maps for preclinical oncology studies. Brazil's FAPESP research foundation is funding platform development for cardiovascular and tumor margin applications, though clinical translation remains grant-dependent.
- Fluorescence Imaging:Exogenous contrast agent-based visualization supports intraoperative tumor delineation in Mexico City cancer centers.
- Confocal Microscopy:Laser scanning reflectance systems anchor dermatology and pathology research infrastructure across Colombian Andean university hospitals.
Highest installed base: Spectral Domain OCT. Steepest expansion trajectory: Photoacoustic Imaging.
End User:
Customer type determines procurement channel access, with consolidated hospital networks extracting service unbundling concessions unavailable to fragmented specialty clinic buyers.
- Hospitals:Large southeastern Brazilian health systems and Mexico's IMSS/ISSSTE federal institutions drive replacement cycles for diagnostic and intraoperative optical systems. Centralized purchasing committees now separate hardware tenders from maintenance contracts, forcing vendors to compete on pure equipment pricing while regional technical providers capture service revenue.
- Research Institutions:University hospitals in Medellín, Bogotá, and São Paulo maintain multiphoton and confocal microscopy infrastructure for preclinical imaging. Limited incumbent vendor presence in Colombia's Andean corridor creates first-mover opportunities for specialized equipment suppliers.
- Diagnostic Laboratories:Independent ophthalmology chains in Brazil's southeastern corridor operate high-throughput SD-OCT screening workflows.
- Specialty Clinics:Small retinal practices in Mexico City metropolitan zones favor refurbished fundus camera installations.
Dominant procurement volume: Hospitals. Fastest capability expansion: Research Institutions.
Application:
Application maturity correlates with reimbursement code establishment, with diagnostic workflows commanding predictable payment streams while intraoperative optical guidance navigates coverage uncertainty.
- Ocular Disease Diagnosis:Glaucoma and age-related macular degeneration screening workflows absorb the majority of spectral-domain OCT installations across Latin American ophthalmology departments. Brazilian clinics leverage speed advantages to process expanded patient volumes without proportional staffing increases.
- Surgical Assistance:Intraoperative optical guidance for tumor margin delineation is expanding in Monterrey and Mexico City cancer centers, though fluoroscopy substitution pressure persists in procurement committees favoring established radiological reimbursement pathways.
- Clinical Research:Photoacoustic and multiphoton imaging protocols support cardiovascular and oncology studies at FAPESP-funded Brazilian institutions.
- Patient Monitoring:Telemedicine-enabled satellite-connected screening units reach underserved populations in Brazil's northern states through state health secretariat partnerships.
Largest application footprint: Ocular Disease Diagnosis. Gaining share fastest: Surgical Assistance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity germanium and indium phosphide feedstock supply from Chilean mining operations anchors optical component sourcing for Latin American imaging manufacturers. Regional demand concentrates in metropolitan hospital corridors where consolidated procurement networks reshape vendor access.
Brazil
São Paulo's southeastern hospital corridor drives replacement demand for spectral domain OCT and confocal microscopy systems. ANVISA's updated medical device registration pathways compress approval timelines for imported scanners while tightening post-market surveillance obligations. Rio de Janeiro ophthalmology departments leverage speed advantages to process expanded patient volumes without proportional staffing increases.
Mexico
Monterrey and Mexico City cancer centers expand intraoperative imaging capabilities for precision tumor margin delineation during resection procedures. COFEPRIS intensifies quality system audits for foreign imaging equipment, creating unpredictable delays for new product introductions. IMSS and ISSSTE federal health institutions pilot decoupled procurement models separating hardware tenders from maintenance contracts.
Colombia
Medellín and Bogotá university hospitals expand research imaging infrastructure with limited incumbent vendor presence in the Andean corridor. The country's national pharmaceutical regulator maintains lighter notification routes for research-oriented technologies compared to active diagnostic equipment. First-mover openings emerge for confocal and multiphoton systems as FAPESP-equivalent research funding flows to cardiovascular and oncology applications.
Argentina
Buenos Aires metropolitan diagnostic laboratories absorb non-mydriatic retinal imaging units for primary screening workflows. The national medical device regulator aligns progressively with IEC 60601 safety benchmarks, raising compliance costs for non-compliant vendors. Specialty clinics in Córdoba favor refurbished fundus camera installations amid currency volatility exposure.
Chile
Santiago's consolidated hospital networks extract service unbundling concessions unavailable to fragmented specialty clinic buyers. The country's national standards body enforces electromagnetic compatibility testing requirements that strain smaller regional distributor budgets. Northern mining corridor mobile clinics deploy satellite-connected screening units through state health secretariat partnerships.
Latin America Optical Imaging Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue hybrid modality development through research foundation partnerships. The vendor base stratifies across three tiers: integrated multinationals with captive service networks, specialized optics manufacturers with spectroscopy heritage, and regional distributors navigating IEC 60601-1 third edition compliance costs. Dominant competitive moves include bundling maintenance and training into multi-year service contracts and embedding AI-assisted diagnostic workflows to capture recurring revenue streams.
Within the integrated multinational tier, Carl Zeiss AG and Olympus Corporation exemplify archetypes leveraging geographic proximity to anchor regional positioning. Bruker Corporation occupies a position representing spectroscopy-heritage specialists targeting research institution sales. Heidelberg Engineering and Topcon Corporation sit within the ophthalmology-focused cluster where spectral domain OCT specifications determine tender viability.
| Leading Market Players |
|---|
| Bruker Corporation |
| Carl Zeiss AG |
| Leica Microsystems |
| CytoViva Inc |
| Olympus Corporation |
| Topcon Corporation |
| PerkinElmer Inc |
| Abbott Laboratories |
| Heidelberg Engineering |
| Others |
Supply & Pricing Matrix
Germanium spot price volatility from Chilean mining operations cascades through optical component fabrication into tiered equipment pricing across Latin American hospital procurement networks. Currency exposure to euro and yen-denominated laser source imports amplifies cost differentials between premium OEM systems and refurbished alternatives.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium vendor tiers from unbundled hardware competitors in Brazilian consolidated tenders. Three-tier pricing structure across premium, standard, and economy levels reflects ANVISA registration tier, captive service network density, and software feature depth. Cost compression in mid-tier spectral domain OCT is intensifying because hospital networks now unbundle service contracts to regional technical providers. Specialty clinics in Argentina's interior exhibit highest price sensitivity, while São Paulo's research institutions absorb premium multiphoton configurations.
Supply Chain Analysis
Dual-sourcing requirements from Brazilian hospital networks mandate qualified suppliers for high-precision lenses from Germany and Japan alongside laser modules from the United States. Optical feedstock draws from Chilean germanium, Chinese rare-earth coatings, and Taiwanese sensor substrates. Single-source vulnerability concentrates in femtosecond laser oscillator production. Distribution runs through São Paulo-based regional distributors with ANVISA-certified warehousing for Class III devices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's optical imaging market operates as a supply-constrained environment where biomedical optics specialist scarcity props pricing power for vendors with captive service networks.
For Market Incumbents: Hedge against fluoroscopy substitution in surgical guidance by embedding AI-assisted diagnostic workflows into spectral domain OCT platforms. Deepen backward integration into laser source refurbishment capabilities in São Paulo to offset import dependency exposure. Defend against emerging spectroscopy-heritage specialists by locking research institutions into multi-year consumable contracts. For New Entrants and Emerging Players: Enter via Colombia's underpenetrated Andean corridor where Medellín and Bogotá university hospitals lack incumbent confocal microscopy vendors. Target photoacoustic imaging preclinical installations funded by FAPESP-equivalent research grants. Pursue telemedicine-enabled mobile clinic partnerships with Brazil's northern state health secretariats as anchor customer acquisition channel. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distributors with ANVISA certification infrastructure and established hospital network relationships in Brazil's southeastern corridor. Long-term viability hinges on positioning for hybrid optical-acoustic modality convergence in oncology applications. Monitor ANVISA-COFEPRIS regulatory reciprocity negotiations as inflection signal for harmonized approval pathway economics.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Fast-Track Registration | Compressed approval timelines accelerate market entry for imported spectral domain OCT systems. |
| Hospital System Partnership | Integrated service contracts with São Paulo health networks lock in recurring maintenance revenue streams. |
| Software Companion Development | AI-assisted diagnostic workflows embedded in cloud platforms differentiate premium vendor tiers. |
| Reimbursement Strategy | Establishment of optical imaging procedure codes in IMSS and ISSSTE expands addressable patient volume. |
| Telemedicine Platform Integration | Satellite-connected screening units reach underserved populations through state health secretariat partnerships. |
Research Methodology
Hospital procurement databases, ANVISA registration filings, and GPO contract repositories formed the secondary backbone, supplemented by primary interviews with biomedical engineers, ophthalmology department heads, hospital purchasing committee members, and regional distributor principals. Bottom-up and top-down triangulation validated equipment installation counts against import customs records and research grant disbursement data.
Historical trendline analysis of spectral domain OCT replacement cycles and photoacoustic imaging grant funding trajectories anchored the projection framework across the analysis window. Segmentation dimensions spanned product type, technology modality, end-user category, and application workflow. CAGRs derived from fitted growth curves incorporating regulatory pathway timelines and currency-adjusted equipment pricing.
Revisions become necessary when ANVISA registration pathway delays, COFEPRIS inspection bottlenecks, or currency volatility shocks materialize beyond modeled ranges. Deviation in FAPESP-equivalent research funding allocations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
Optical Telephoto Lens Market
Optics
Polymeric Optical Fiber Market
Optics
Global Semiconductor Lasers Market
Optics
Glass Scintillator Market
Optics
Beam Combining Optics Market
Optics
Tunable Laser Market
Optics
Photonics Sensor Market
Optics
Lasers Market
Optics
Global Nanophotonics Market
Optics
Asia-Pacific Optical Imaging Market
Optics
Fiber Optic Preform Market
Optics
Interchangeable Lens Market
Optics
Optical Fiber Market
Optics
Fiber-Optic Filters Market
Optics
Fiber Optic Switch Market
Optics
Optical Profilometer Market