
 Asia-Pacific Bulk Acoustic Wave Sensors Market | 2026-2036
Asia-Pacific Bulk Acoustic Wave Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Bulk Acoustic Wave Sensors Market Outlook
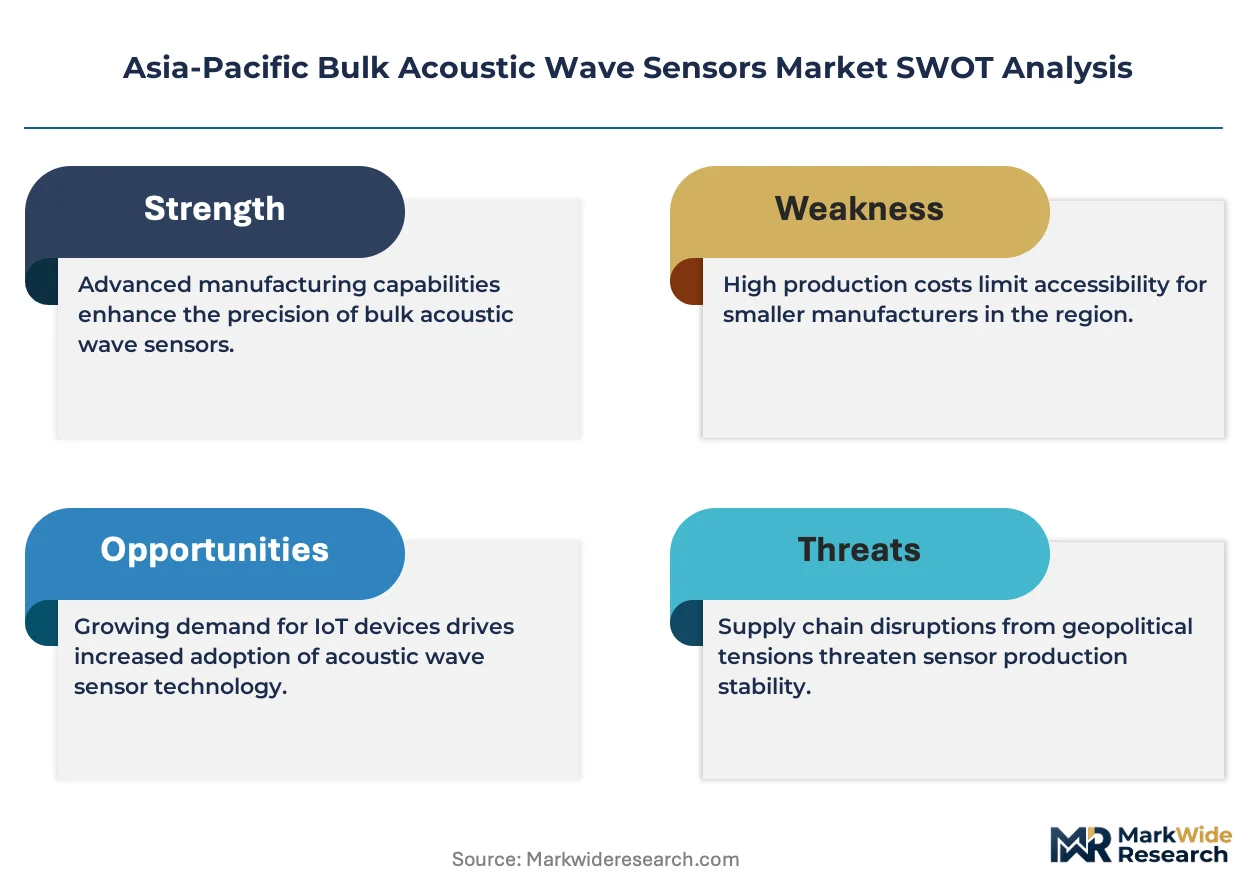
A capital-intensity divergence between integrated IDM-style operators and fabless design houses is unwinding competitive stability in BAW sensor supply. Broadcom sustains captive gallium nitride foundry access that locks in resonator yield consistency for defense and telecom contracts. Qorvo navigates multi-source quartz wafer agreements across Japanese and Taiwanese suppliers, hedging against single-point substrate failures. Murata Manufacturing dominates high-volume ceramic packaging for automotive BAW modules, leveraging its in-house LTCC substrate lines to compress lead times.
Bulk Acoustic Wave Sensors employ piezoelectric thin films—typically aluminum nitride or zinc oxide—deposited over silicon substrates to convert electrical signals into mechanical resonance for frequency filtering and mass sensing applications. These devices achieve quality factors exceeding 10,000 at gigahertz frequencies, enabling sharp bandpass characteristics essential for RF front-ends and gravimetric chemical detection. Quartz substrates anchor the product type landscape with mature supply chains and established temperature stability, though lithium niobate variants are gaining traction in medical devices where electromechanical coupling efficiency outweighs cost premiums. Bulk Acoustic Wave technology itself commands the core revenue pool against MEMS alternatives, as 5G carrier aggregation architectures multiply filter count per handset and industrial vibration monitoring specifications tighten.
China's MIIT enforces GB standards on RF component electromagnetic compatibility, compelling foreign BAW suppliers to qualify domestic test labs before market entry. Japan's METI coordinates JIS standards for automotive sensor reliability under its connected vehicle infrastructure roadmap, while South Korea's MFDS certifies medical-grade BAW gravimetric sensors for point-of-care diagnostic platforms. Stakeholders must monitor how India's PLI scheme for electronics manufacturing alters regional assembly migration patterns and whether Thailand or Vietnam emerge as alternative packaging hubs as Chinese labor costs rise.
Market Dynamics
China's dual carbon goals and Japan's METI semiconductor subsidy program are redirecting sensor fabrication toward domestic cleanroom capacity, fragmenting established supply relationships across the Asia-Pacific region.
Growth Catalysts
- 5G handset proliferation:Smartphone manufacturers in South Korea and China are expanding BAW filter procurement as carrier aggregation architectures multiply filter count per device.
- MIIT electromagnetic compatibility mandates:China's GB standards on RF components compel qualification through domestic test labs, accelerating local certification infrastructure development.
- Automotive sensor reliability standards:Japan's METI coordinates JIS standards for connected vehicle infrastructure, creating specification pull for high-Q resonators in telematics modules.
Market Restraints
- Quartz substrate supply concentration:Japanese and Taiwanese suppliers dominate premium-grade polished wafers, exposing fabless design houses to single-point failure risks during geopolitical friction.
- Thin-film deposition equipment lead times:Physical vapor deposition chambers for aluminum nitride sputtering face 18-24 month delivery backlogs from European and US equipment vendors.
- MEMS alternative performance improvement:Silicon-based resonators are narrowing the quality factor gap at sub-3 GHz frequencies, threatening BAW dominance in cost-sensitive IoT applications.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Assembly incentives are drawing module packaging operations away from coastal China, creating greenfield substrate processing demand.
- Point-of-care diagnostic platforms:South Korea's MFDS certification pathway for medical-grade gravimetric sensors opens clinical mass-sensing applications beyond traditional RF filtering.
- Lithium niobate electromechanical coupling:Medical device manufacturers are adopting higher-efficiency piezoelectric variants where performance premiums justify material costs.
Industry Challenges
- Compound semiconductor process engineering talent:Gallium nitride foundry operations require specialized resonator yield optimization expertise that remains concentrated among veteran IDM engineering teams.
- Multi-source qualification timelines:Qorvo-style hedging strategies demand parallel validation across Japanese and Taiwanese quartz suppliers, stretching NPI cycles.
- LTCC substrate integration complexity:Murata's ceramic packaging dominance forces secondary suppliers to match in-house substrate capabilities or accept margin compression.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Bulk Acoustic Wave Sensors Market |
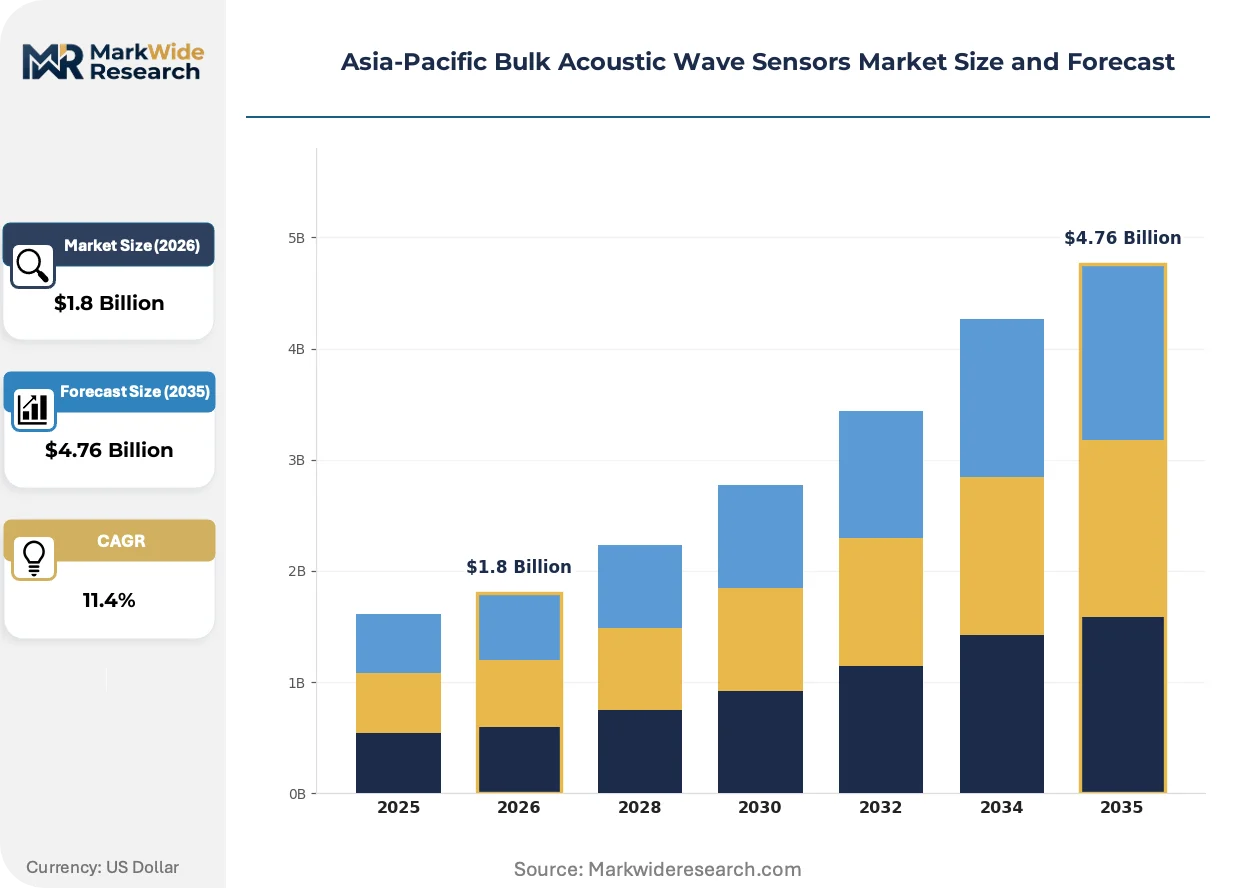
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Quartz, Lithium Niobate, Lithium Tantalate, Other Application: Consumer Electronics, Automotive Sensors, Industrial Equipment, Medical Devices End User: Manufacturers, OEMs, Research Institutions, Government Agencies Technology: Surface Acoustic Wave, Bulk Acoustic Wave, MEMS, Others |
| Companies Covered | Broadcom, Qorvo, Taiyo Yuden, Texas Instruments, Nihon Dempa Kogyo, Murata Manufacturing, Fortiming Corporation, Balluff, Resonant, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Bulk Acoustic Wave Sensors Market Strategic Shifts
Aluminum nitride thin-film deposition techniques and lithium niobate substrate alternatives are actively reshaping resonator performance benchmarks and supply chain configurations across Asia-Pacific fabrication networks.
Lithium niobate BAW resonators achieve electromechanical coupling coefficients roughly three times higher than aluminum nitride equivalents, enabling wider bandwidth filters without sacrificing quality factor. Medical device manufacturers in Japan and South Korea are adopting these variants for gravimetric biosensors where picogram sensitivity determines clinical utility. Aluminum nitride is supplanting zinc oxide in mainstream RF applications as sputtering process maturity drives unit cost convergence.
China's MIIT enforcement of GB standards on RF component electromagnetic compatibility is compelling foreign suppliers to establish domestic test lab partnerships before market entry qualification. The regulation compresses time-to-revenue for non-compliant vendors while accelerating indigenous testing infrastructure buildout. South Korean and Taiwanese filter manufacturers are responding by pre-qualifying products through Beijing and Shanghai certification centers.
Consolidated procurement by Yangtze River Delta foundry clusters is compressing supplier negotiation leverage and standardizing specification requirements across previously fragmented buyer bases. Module assemblers now demand unified thin-film thickness tolerances and temperature coefficient guarantees across quarterly volume commitments. This concentration is most visible in China's smartphone ODM ecosystem, where tier-one manufacturers have reduced qualified BAW filter vendors from twelve to four over eighteen months.
Asia-Pacific Bulk Acoustic Wave Sensors Market Segmentation
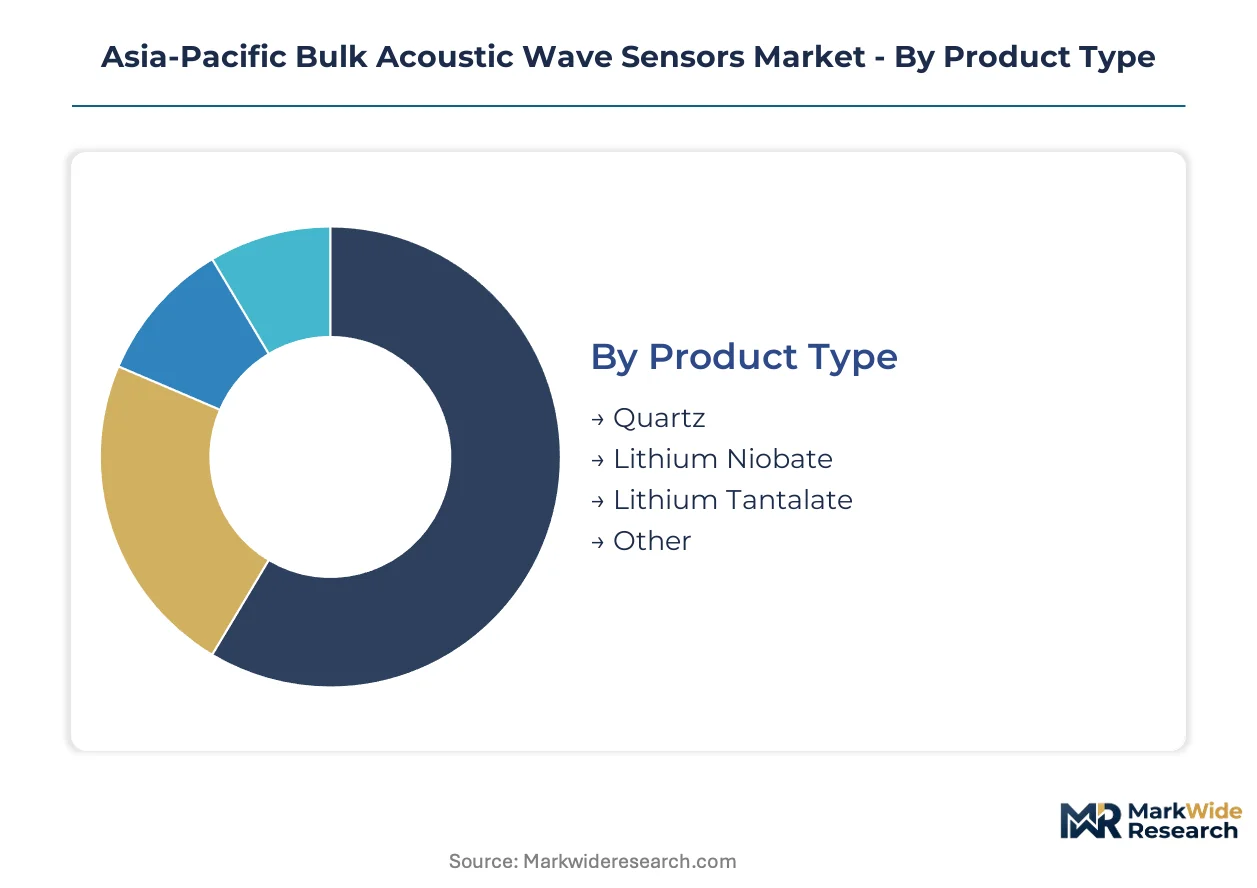
BAW sensor procurement patterns diverge sharply across substrate materials, end-use applications, and technology architectures. Each segmentation dimension carries distinct regulatory, cost, and performance constraints that reshape supplier qualification requirements across the Asia-Pacific fabrication ecosystem.
Product Type:
Japan's METI semiconductor subsidy program and China's MIIT GB standards create divergent material qualification pathways that fragment substrate procurement strategies across the region.
- Quartz:Silicon dioxide crystals with near-zero temperature coefficients anchor high-stability RF filtering for 5G base stations. Yangtze River Delta foundries consume the majority of polished wafer output as domestic smartphone ODMs consolidate vendor panels. Quartz handles the majority of throughput; Lithium Niobate is the fastest mover on share.
- Lithium Niobate:Pyroelectric oxide substrates achieve electromechanical coupling coefficients roughly triple those of aluminum nitride alternatives. Japanese and South Korean medical device manufacturers specify these variants for picogram-sensitive gravimetric biosensors where bandwidth expansion justifies material premiums.
- Lithium Tantalate:Perovskite-structured crystals with intermediate coupling efficiency serve mid-tier telecom filtering applications. Taiwanese substrate polishers have expanded capacity for these wafers to hedge against lithium niobate supply constraints.
- Other:Emerging piezoelectric ceramics and aluminum nitride-on-silicon composites target cost-sensitive IoT resonator applications. Chinese foundries are piloting these materials under MIIT domestic substitution mandates.
Cost tier differentiation separates premium-grade polished crystals from standard-grade material.
Application:
End-use volume concentration determines foundry process development priorities and thin-film deposition equipment allocation across Asia-Pacific cleanroom networks.
- Consumer Electronics:Smartphone RF front-ends dominate BAW filter consumption as carrier aggregation architectures multiply resonator count per handset. South Korean and Chinese ODMs have compressed qualified supplier panels from twelve vendors to four over eighteen months.
- Automotive Sensors:Telematics modules and tire-pressure monitoring systems require JIS-certified resonators under Japan's METI connected vehicle infrastructure roadmap. Murata Manufacturing leverages in-house LTCC substrate lines to compress lead times for these safety-critical applications.
- Industrial Equipment:Vibration monitoring and process control systems deploy BAW gravimetric sensors for chemical detection in manufacturing environments. China's dual carbon goals are redirecting fabrication toward domestic cleanroom capacity for these instruments.
- Medical Devices:Point-of-care diagnostic platforms utilize mass-sensitive resonators for biomolecule detection. South Korea's MFDS certification pathway enables clinical gravimetric applications beyond traditional RF filtering.
Consumer Electronics absorbs the greatest wafer volume; Medical Devices is climbing the fastest on specification premiums.
End User:
Customer type dictates contract structure, volume commitment patterns, and technical support intensity across the Asia-Pacific supplier base.
- Manufacturers:Integrated device foundries and module assemblers purchase bare die and packaged resonators for incorporation into larger subsystems. Yangtze River Delta clusters now demand unified thin-film thickness tolerances across quarterly volume commitments.
- OEMs:Original equipment manufacturers in smartphone and automotive supply chains specify performance parameters while outsourcing fabrication. These buyers navigate 18-24 month lead times for physical vapor deposition chambers from European and US equipment vendors.
- Research Institutions:Universities and national laboratories procure small-batch custom resonators for prototype development. Japan's METI semiconductor subsidy program has expanded domestic academic access to gallium nitride foundry capacity.
- Government Agencies:Defense and aerospace procurement channels require ITAR-compliant supply chains with captive yield consistency. Broadcom sustains dedicated gallium nitride foundry access for these security-sensitive contracts.
Manufacturers command the largest order volumes; Research Institutions are expanding most quickly on subsidy inflows.
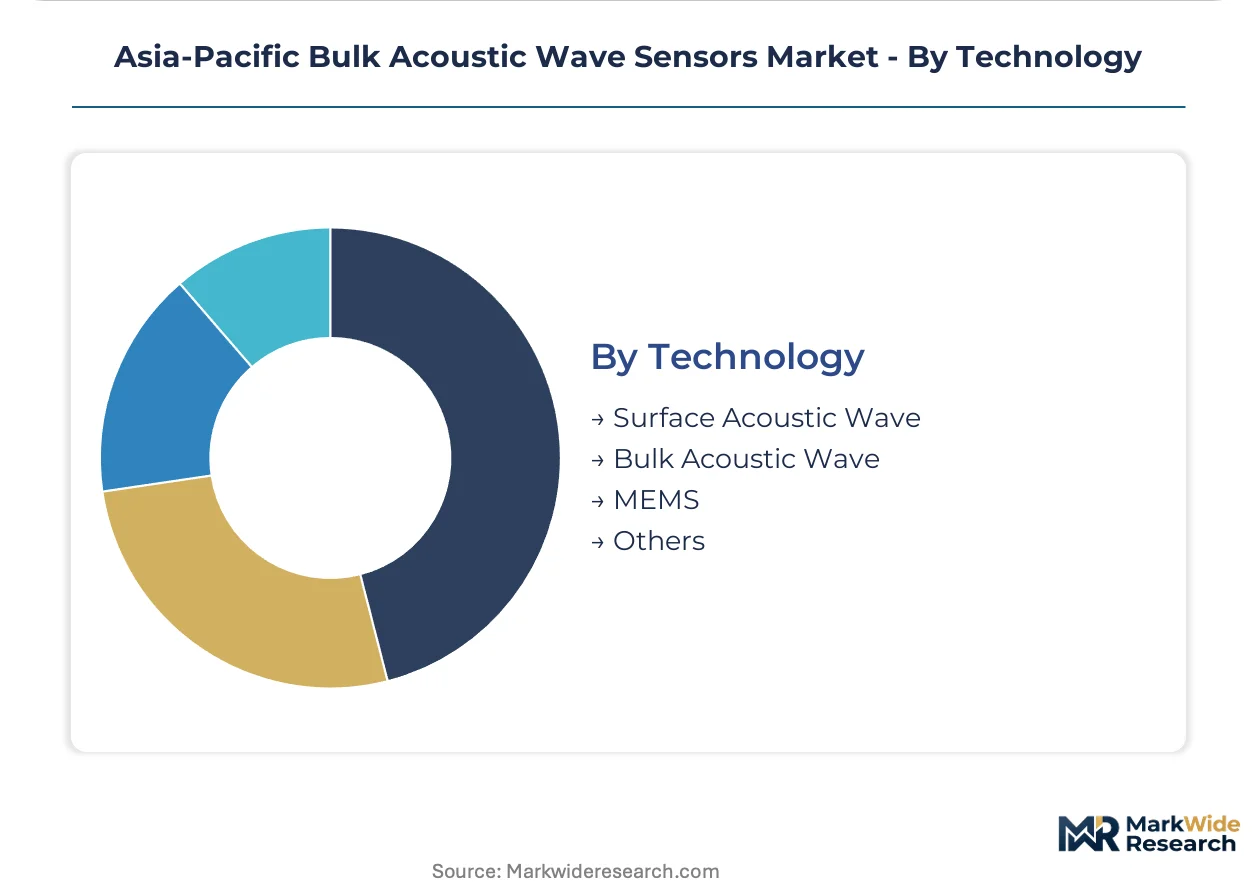
Technology:
Resonator architecture selection involves trade-offs between quality factor, frequency range, and integration complexity that reshape competitive positioning across the Asia-Pacific vendor landscape.
- Surface Acoustic Wave:Interdigital transducers on piezoelectric substrates enable filtering at sub-3 GHz frequencies with moderate selectivity. These devices retain cost advantages in legacy telecom infrastructure where BAW performance exceeds requirements.
- Bulk Acoustic Wave:Thin-film bulk resonators achieve quality factors exceeding 10,000 at gigahertz frequencies for sharp bandpass characteristics. 5G carrier aggregation architectures are multiplying filter count per handset and tightening industrial vibration monitoring specifications.
- MEMS:Silicon-based resonators are narrowing the quality factor gap at sub-3 GHz frequencies through advanced cavity etching. These alternatives threaten BAW dominance in cost-sensitive IoT applications where absolute performance is secondary to unit economics.
- Others:Emerging film bulk acoustic resonator variants and hybrid piezoelectric-MEMS architectures target niche frequency bands. Chinese foundries are developing these technologies under MIIT electromagnetic compatibility mandates to reduce import dependence.
Bulk Acoustic Wave commands the dominant revenue position; MEMS is gaining share fastest on silicon process compatibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across Asia-Pacific diverge sharply by application priority. China deploys BAW sensors predominantly in smartphone RF front-ends, while Japan concentrates on automotive telematics and medical gravimetric platforms. South Korea bridges both consumer electronics and point-of-care diagnostics.
China
Smartphone ODMs in the Yangtze River Delta drive quartz substrate demand for 5G carrier aggregation architectures. MIIT enforces GB standards on RF component electromagnetic compatibility, compelling foreign suppliers to qualify through domestic test labs. Shanghai and Beijing certification centers now anchor pre-qualification workflows for Korean and Taiwanese filter manufacturers.
Japan
Automotive telematics modules and tire-pressure monitoring systems absorb high-Q resonators under METI's connected vehicle infrastructure roadmap. JIS standards for automotive sensor reliability create specification pull that favors domestic fabrication. Murata Manufacturing leverages in-house LTCC substrate lines in Kyoto prefecture to compress lead times for safety-critical applications.
South Korea
Smartphone manufacturers expand BAW filter procurement as carrier aggregation multiplies resonator count per handset. MFDS certifies medical-grade gravimetric sensors for point-of-care diagnostic platforms, opening clinical mass-sensing applications. Seoul-based ODMs have compressed qualified vendor panels from twelve suppliers to four over eighteen months.
Taiwan
Substrate polishers have expanded lithium tantalate wafer capacity to hedge against lithium niobate supply constraints. The island's foundry ecosystem serves as a secondary quartz sourcing node for fabless design houses hedging against single-point failures. Hsinchu Science Park anchors thin-film deposition equipment clusters with 18-24 month lead time management capabilities.
India
PLI scheme incentives for electronics manufacturing are drawing module packaging operations away from coastal China. Greenfield substrate processing demand is emerging in Gujarat and Tamil Nadu as smartphone assembly migrates. The country's national electronics regulator is developing test lab infrastructure to parallel Chinese GB qualification pathways.
Asia-Pacific Bulk Acoustic Wave Sensors Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in Asia-Pacific BAW sensor supply. IDM-style operators with captive gallium nitride foundry access lock in resonator yield consistency for defense and telecom contracts. Fabless design houses navigate multi-source quartz wafer agreements across Japanese and Taiwanese suppliers. The dominant competitive moves involve capacity expansion in domestic cleanroom networks and strategic partnerships with substrate polishers to hedge supply concentration risks.
Within the integrated device manufacturer tier, Broadcom and Qorvo exemplify divergent hedging strategies against substrate supply fragility. Broadcom sustains captive foundry access that secures yield consistency for security-sensitive contracts. Qorvo occupies a position representing multi-source qualification approaches across regional quartz suppliers. Murata Manufacturing anchors the ceramic packaging specialist segment, leveraging in-house substrate capabilities to compress lead times for automotive modules. These three companies collectively illustrate how vertical integration depth, supply chain redundancy, and packaging specialization define competitive positioning in Asia-Pacific BAW fabrication.
| Leading Market Players |
|---|
| Broadcom |
| Qorvo |
| Taiyo Yuden |
| Texas Instruments |
| Nihon Dempa Kogyo |
| Murata Manufacturing |
| Fortiming Corporation |
| Balluff |
| Resonant |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake agreements between Yangtze River Delta foundries and Japanese quartz polishers lock in substrate supply visibility while capping price volatility for aluminum nitride thin-film resonators. These contracts bind volume commitments to MIIT certification timelines, forcing foreign BAW suppliers to absorb domestic test lab qualification costs upfront or surrender pricing power to qualified competitors.
Pricing Analysis
Contract-based long-term offtake dominates procurement between smartphone ODMs and filter manufacturers, with pricing stratifying across JIS-certified automotive tiers, GB-compliant consumer grades, and uncertified industrial variants. Price differentiation hinges on quartz substrate purity grades and MIIT electromagnetic compatibility certification levels. Cost compression in standard-grade resonators intensifies as MEMS alternatives narrow the quality factor gap. Automotive telematics buyers exhibit the least price sensitivity due to JIS reliability mandates, while IoT module assemblers face acute margin pressure from silicon resonator competition.
Supply Chain Analysis
Physical vapor deposition chamber inventories face 18-24 month replenishment cycles from European and US equipment vendors, stretching foundry expansion timelines across the region. Raw material flows draw from Japanese and Taiwanese quartz substrate polishers, Chinese aluminum nitride sputtering targets, and South Korean gallium nitride epitaxy services. Single-source vulnerability concentrates in premium-grade polished wafer supply, where geopolitical friction threatens fabless design house continuity. Distribution runs through Yangtze River Delta module assemblers for consumer electronics, Kyoto-prefecture automotive tier-1s for telematics, and Seoul-based diagnostic OEMs for medical gravimetric platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive moat sustained by regulatory entrenchment—MIIT GB standards, JIS automotive certifications, and MFDS medical pathways create switching costs that lock buyers into qualified supplier relationships.
For Market Incumbents: Fortify captive gallium nitride foundry access or multi-source quartz agreements to defend against MEMS substitution at sub-3 GHz frequencies. Expand LTCC substrate capacity in domestic cleanroom networks to match Murata-style lead time compression for automotive safety-critical modules. Prioritize backward integration into aluminum nitride sputtering target production to hedge European equipment vendor delays. For New Entrants and Emerging Players: Anchor in India's PLI scheme electronics manufacturing incentives to capture packaging operations migrating from coastal China. Target point-of-care diagnostic gravimetric sensors as the most penetrable segment, where MFDS certification pathways remain less congested than smartphone RF filter vendor panels. Pursue lithium niobate substrate partnerships with Japanese polishers to differentiate on electromechanical coupling efficiency for medical device specifications. For Investors and Strategic Acquirers: Fabless design houses with validated multi-source quartz agreements represent the priority acquisition archetype, as their hedged supply structures command premiums during substrate concentration shocks. Long-term viability centers on regulatory qualification moats rather than pure technology performance. Monitor India's national electronics regulator test lab buildout as the inflection signal for alternative Asia-Pacific assembly hub emergence.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Source Quartz Wafer Qualification | Qorvo-style hedging against Japanese-Taiwanese supply concentration reduces single-point failure exposure. |
| Domestic Cleanroom Capacity Expansion | China's dual carbon goals redirect fabrication toward Yangtze River Delta foundry clusters. |
| LTCC Substrate Integration | Murata's in-house ceramic packaging compresses automotive module lead times under JIS standards. |
| MFDS Medical Certification Pathway | South Korea's point-of-care diagnostic approval opens clinical gravimetric applications beyond RF filtering. |
| Aluminum Nitride Sputtering Process Maturation | Thin-film deposition yield improvements drive unit cost convergence against zinc oxide alternatives. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with BAW filter procurement managers at smartphone ODMs, thin-film deposition equipment specialists, and MIIT certification lab directors; and secondary validation through SEC filings of listed resonator manufacturers, Japan METI semiconductor subsidy program disclosures, and China customs trade data for quartz substrate imports. Bottom-up triangulation across foundry capacity announcements and top-down reconciliation against carrier aggregation filter count models anchored volume estimates.
Across the analysis window, the forecasting framework modeled resonator demand by substrate material, application vertical, and technology architecture, with CAGRs derived from equipment procurement lead time trajectories and ODM vendor panel consolidation rates. Inputs included gallium nitride foundry utilization disclosures, lithium niobate substrate polish capacity expansion schedules, and MEMS resonator quality factor improvement curves.
Material uncertainties—geopolitical friction in Taiwan Strait logistics, aluminum nitride target supply interruptions, and MEMS performance breakthroughs—sit outside the modeled envelope. Forecasts reflect documented assumptions about MIIT enforcement consistency and METI subsidy continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Embedded Biometric Sensor Market
Sensors and Controls
Instrumented Load Shackle Market
Sensors and Controls
Aton Management and Monitoring System Market
Sensors and Controls
Multi Touch Sensing Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Global Mid-And-High-Level Precision GPS Receiver Market
Sensors and Controls
Current Transducer Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Magnetic Absorption Data Line Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Water and Wastewater Sensors Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Inertial Sensing Products Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Digital Flow Meter Market