
 Millimeter Wave Equipment Market | 2026-2036
Millimeter Wave Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Millimeter Wave Equipment Market Outlook
Enterprise-grade spectral efficiency is collapsing the cost-per-bit economics of millimeter wave backhaul, pulling carrier procurement toward higher-frequency bands. Qualcomm leverages its modem-RF integration to dominate baseband silicon for 28 GHz and 39 GHz deployments. Ericsson anchors European supply chains through its Radio System portfolio, while Samsung Electronics competes aggressively in Asian 5G infrastructure tenders with integrated antenna-radio units.
Millimeter wave equipment encompasses radio frequency hardware operating between 30 GHz and 300 GHz, utilizing highly directional beamforming arrays with sub-degree steering precision to overcome atmospheric attenuation and deliver multi-gigabit throughput over short distances. The primary commercial purpose centers on solving spectrum scarcity in dense urban wireless networks and enabling high-resolution sensing for defense and automotive applications. Antenna subsystems capture disproportionate margin pools as active phased arrays replace passive designs across 5G and radar platforms. Satellite Communication technology segments are accelerating fastest as low-earth orbit constellations demand inter-satellite links at 71-86 GHz. Imaging Systems remain comparatively nascent outside security screening, constrained by component cost and algorithm maturity.
The FCC governs spectrum licensing and equipment authorization for millimeter wave devices in the United States, with recent rulemakings expanding unlicensed 60 GHz and licensed 24-47 GHz bands to stimulate infrastructure investment. ETSI harmonizes European technical standards for 5G NR and fixed wireless access equipment, while the ITU-R coordinates global spectrum allocations that determine addressable market size for manufacturers. Stakeholders must monitor national spectrum auction calendars and beamforming efficiency benchmarks as primary determinants of procurement priority and vendor selection criteria.
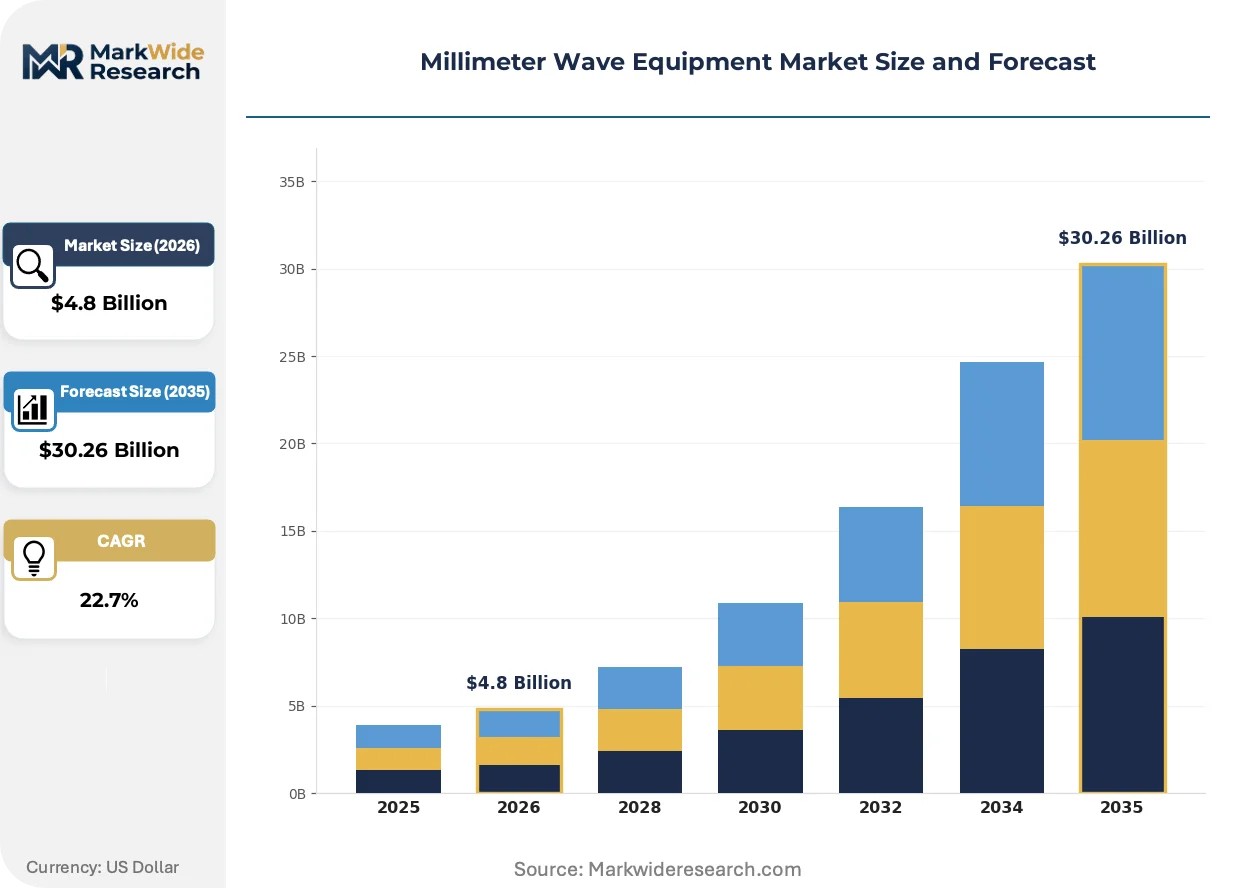
Market Dynamics
Beamforming silicon integration is compressing unit economics for millimeter wave base stations, forcing modular hardware architectures toward single-chip solutions that collapse bill-of-materials complexity and accelerate carrier deployment cycles.
Growth Catalysts
- 5G Backhaul Densification:FCC spectrum allocations in the 24-47 GHz range are unlocking licensed capacity for urban small-cell networks, pulling infrastructure investment toward millimeter wave backhaul as fiber alternatives face right-of-way bottlenecks.
- Defense Radar Modernization:Active electronically scanned array programs are displacing mechanically steered systems across military platforms, creating sustained procurement pipelines for GaN-on-SiC power amplifiers and compact antenna arrays.
- Satellite Inter-Satellite Links:Low-earth orbit constellations are mandating 71-86 GHz terminal hardware for orbital mesh networking, concentrating manufacturing scale in space-qualified packaging and thermal management subsystems.
Market Restraints
- Atmospheric Attenuation Physics:Oxygen absorption peaks at 60 GHz and rain fade above 70 GHz impose hard link-budget constraints that limit outdoor range to sub-kilometer distances regardless of transmit power scaling.
- Compound Semiconductor Supply Concentration:GaN epitaxy capacity concentrates in Japanese and US substrate foundries, exposing equipment manufacturers to single-source risk for high-electron-mobility transistor wafers.
- Sub-6 GHz Substitution:C-band and mid-band 5G deployments are capturing urban coverage scenarios that millimeter wave originally targeted, compressing addressable volume for high-frequency equipment in macro-cell applications.
Strategic Opportunities
- Automotive 4D Imaging Radar:77-81 GHz frequency-modulated continuous-wave sensors are penetrating premium vehicle platforms for high-resolution object detection, opening volume manufacturing paths previously locked in defense contracting.
- India Spectrum Liberalization:TRAI recommendations for E-band and V-band delicensing are creating greenfield fixed wireless access markets where wireline infrastructure remains underpenetrated in tier-2 cities.
- AI-Driven Beam Management:Convergence of machine learning inference at the edge with analog beamforming is enabling real-time link adaptation that extends usable range and reliability in non-line-of-sight conditions.
Industry Challenges
- Phased Array Calibration Expertise:Active antenna systems require sub-degree phase coherence across hundreds of elements, creating acute shortages in RF test engineering and thermal-mechanical design talent.
- Multi-Band Certification Complexity:FCC equipment authorization cycles for modular millimeter wave radios now span 18-24 months as OET-65 exposure compliance and modular approval rules tighten for multi-band configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Millimeter Wave Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transmitters, Receivers, Antennas, Amplifiers Technology: 5G, Satellite Communication, Radar Systems, Imaging Systems Application: Telecommunications, Automotive, Healthcare, Industrial Automation End User: Telecom Operators, Defense Agencies, Research Institutions, Commercial Sectors |
| Companies Covered | Qualcomm, Ericsson, Huawei, Nokia, Keysight Technologies, NEC Corporation, L3Harris Technologies, Aviat Networks, Samsung Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Millimeter Wave Equipment Market Strategic Shifts
Silicon photonics and CMOS beamformer integration are collapsing the traditional boundary between digital baseband and analog front-end, enabling software-defined radio architectures that reconfigure carrier frequency through firmware rather than hardware swaps.
Antenna-in-package technology is bifurcating the transceiver market. Qualcomm and MediaTek are shipping 28 GHz modules with integrated patch arrays for handset and CPE applications, while defense suppliers retain discrete tile architectures for radar platforms requiring higher effective isotropic radiated power. This split is compressing margins in commercial 5G hardware while preserving premium pricing in aerospace and military procurement.
ETSI harmonization of 5G NR millimeter wave conformance specifications is accelerating European equipment certification timelines. The harmonized standards reduce national type-approval fragmentation, enabling vendors to launch across Germany, France, and Italy with single test campaigns. Fixed wireless access CPE manufacturers are the primary beneficiaries, as retail distribution channels demand rapid market entry across multiple member states.
Carrier procurement is consolidating around integrated antenna-radio units that collapse installation complexity and site rental costs. Verizon and AT&T are mandating all-in-one 28 GHz/39 GHz street-level enclosures that eliminate separate baseband hoteling, compressing vendor qualification lists to suppliers with full vertical capability in RF, thermal, and power design. This preference shift is most visible in dense urban US markets where permitting timelines dominate total cost of ownership.
Millimeter Wave Equipment Market Segmentation
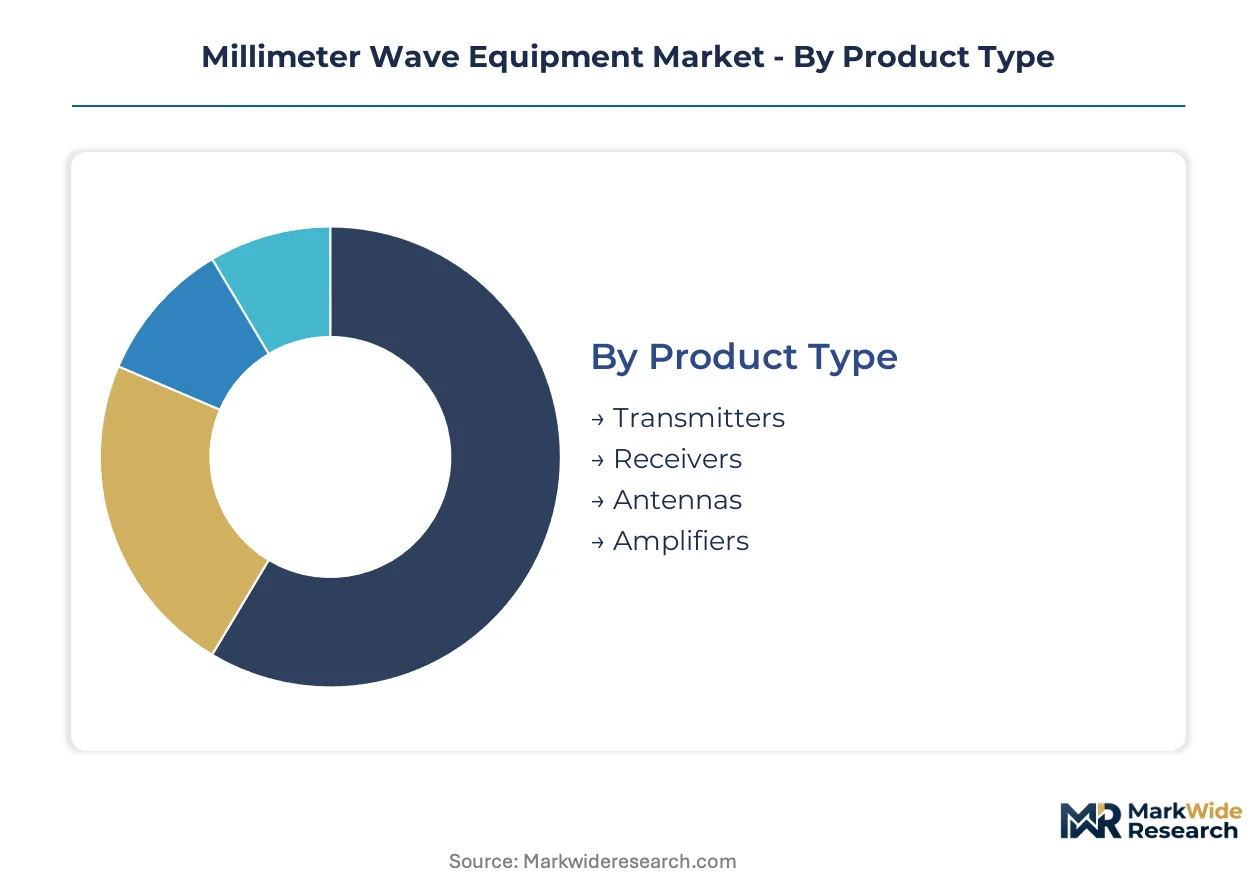
Millimeter wave equipment spans heterogeneous frequency bands, power classes, and integration levels that fragment procurement criteria across defense, telecom, and sensing applications. Vendors must align product architectures with distinct certification regimes, thermal constraints, and beamforming requirements that vary sharply by segment.
Product Type:
Antenna subsystems concentrate domestic manufacturing in the United States and Japan, while transmitters and receivers flow through export-led supply chains anchored in South Korea and Taiwan.
- Transmitters:Power amplifier modules integrating GaN-on-SiC or CMOS beamformer chips generate directional beams at 28 GHz, 39 GHz, and 60 GHz carrier frequencies. Demand clusters in United States urban small-cell deployments where FCC licensing in 24-47 GHz bands drives procurement volume.
- Receivers:Low-noise amplifier front-ends with sub-3 dB noise figures capture weak signals at millimeter wavelengths. Procurement concentrates in European defense radar programs under ETSI harmonized standards, pulling silicon germanium and indium phosphide discrete component demand.
- Antennas:Active phased arrays with 256+ radiating elements dominate 5G base station and radar platforms.
- Amplifiers:Solid-state power amplifiers and traveling-wave tube alternatives span commercial and military power-output requirements.
Antenna subsystems command the established base. The steepest expansion runs through transmitters.
Technology:
5G infrastructure represents the volume anchor, while satellite communication and radar systems capture premium pricing through specialized packaging and qualification requirements.
- 5G:New Radio millimeter wave implementations at 28 GHz and 39 GHz utilize massive MIMO antenna arrays with hybrid analog-digital beamforming. Deployment concentrates in United States carrier densification programs where Verizon and AT&T prioritize integrated antenna-radio units for street-level installation.
- Satellite Communication:Inter-satellite links at 71-86 GHz and 71-76 GHz/81-86 GHz bands demand space-qualified transceivers with radiation-hardened electronics. Low-earth orbit constellation operators in the United States and Europe drive procurement for compact, low-power terminals.
- Radar Systems:Active electronically scanned arrays displace mechanically steered platforms across airborne and naval applications.
- Imaging Systems:Passive radiometric and active FMCW architectures serve security screening and industrial quality inspection.
5G infrastructure commands the established base. Satellite communication shows the steepest expansion trajectory.
Application:
Telecommunications absorbs the majority of commercial volume, while automotive and industrial automation applications are gaining share through new frequency allocations and sensor fusion requirements.
- Telecommunications:Mobile backhaul, fixed wireless access, and fronthaul networks utilize millimeter wave links where fiber deployment faces right-of-way constraints. United States carriers deploy 28 GHz small cells in dense urban corridors, while Indian operators await TRAI E-band and V-band liberalization for tier-2 city expansion.
- Automotive:77-81 GHz frequency-modulated continuous-wave radar sensors enable adaptive cruise control, lane-keeping assistance, and automated emergency braking. German and Japanese premium vehicle platforms integrate 4D imaging radar with elevation resolution for object classification.
- Healthcare:Short-range imaging and therapeutic applications exploit millimeter wave penetration characteristics for dermatology and wound monitoring.
- Industrial Automation:High-resolution radar and imaging systems support precision positioning, collision avoidance, and quality control in manufacturing environments.
Telecommunications commands the established base. Automotive applications are climbing the fastest.
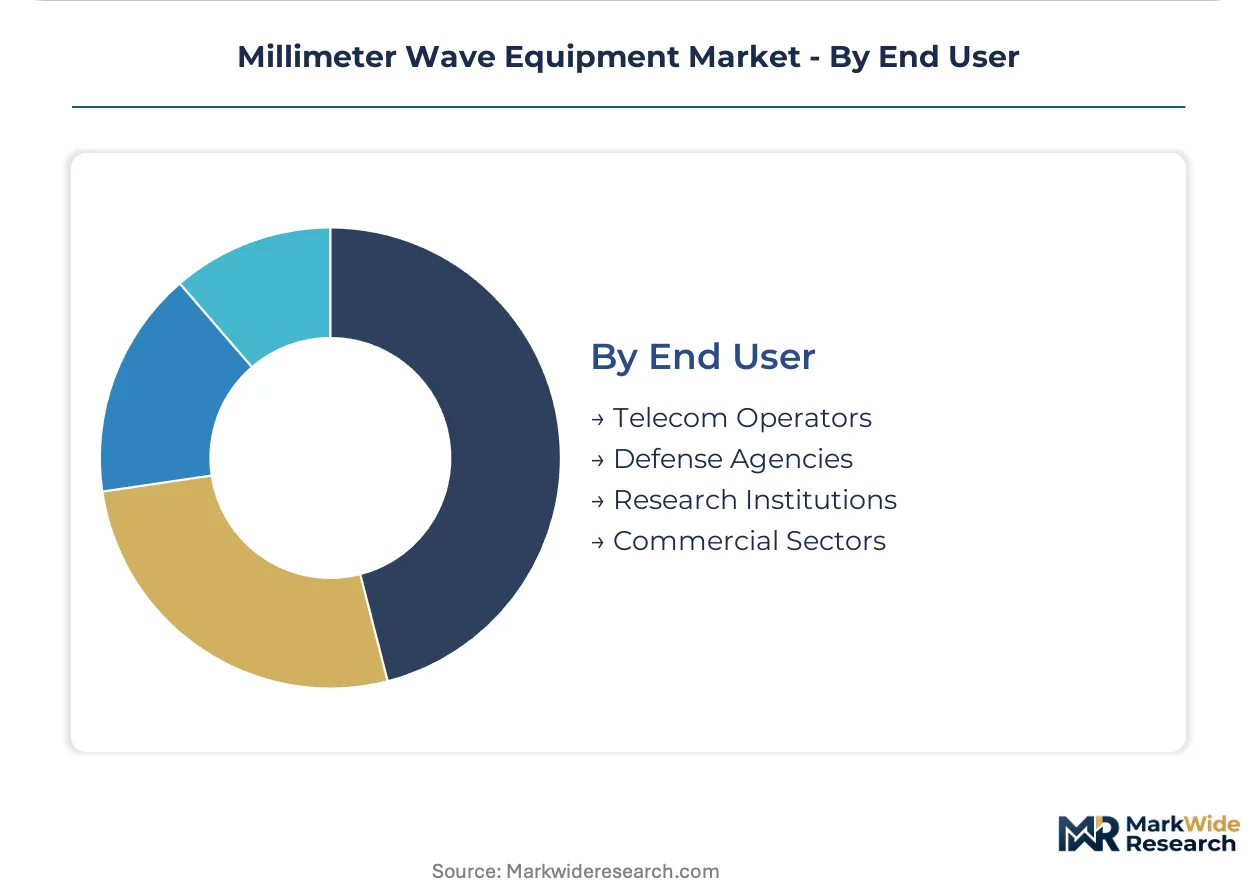
End User:
Defense agencies sustain premium pricing through ruggedization and qualification requirements, while commercial sectors and research institutions drive volume through standardization and cost reduction.
- Telecom Operators:Mobile network operators and fixed wireless access providers procure integrated base stations, customer premises equipment, and backhaul radios. United States carriers mandate all-in-one 28 GHz/39 GHz enclosures that collapse installation complexity and site rental costs in dense urban markets.
- Defense Agencies:Military procurement programs for airborne, naval, and ground-based radar platforms specify GaN-on-SiC power amplifiers and compact active electronically scanned arrays. United States Department of Defense modernization initiatives displace legacy mechanically steered systems.
- Research Institutions:Academic and government laboratories characterize channel propagation, develop new modulation schemes, and prototype advanced antenna architectures.
- Commercial Sectors:Enterprise private networks, stadium and venue connectivity, and industrial IoT deployments utilize unlicensed 60 GHz and lightly licensed 70-80 GHz bands.
Telecom operators command the established base. Defense agencies are gaining share fastest through sustained modernization budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korean component manufacturers export millimeter wave beamformer chips to United States telecom infrastructure deployers, establishing the primary trade corridor for 5G backhaul hardware. This flow concentrates procurement leverage in American carrier densification programs while concentrating manufacturing scale in East Asian foundries. National spectrum allocation calendars and defense modernization budgets now determine regional demand intensity.
United States
Verizon and AT&T drive 28 GHz and 39 GHz small-cell deployment in dense urban corridors, prioritizing integrated antenna-radio units that collapse installation timelines. The FCC governs equipment authorization through OET-65 exposure compliance and modular approval frameworks, with recent rulemakings expanding licensed 24-47 GHz bands. San Diego and Boston anchor defense radar modernization clusters where GaN-on-SiC foundries supply active electronically scanned array programs.
Germany
Automotive 4D imaging radar demand from premium vehicle platforms pulls 77-81 GHz frequency-modulated continuous-wave sensor procurement. ETSI harmonizes 5G NR millimeter wave conformance specifications, reducing national type-approval fragmentation across member states. Stuttgart and Munich concentrate RF engineering talent for antenna-in-package development serving continental fixed wireless access markets.
China
Domestic 5G infrastructure tenders absorb massive MIMO antenna arrays at scale, with MIIT spectrum allocations in 24.75-27.5 GHz and 37-42.5 GHz bands. GB standards govern electromagnetic compatibility and radio transmission equipment certification, tightening modular radio compliance timelines. Shenzhen and Beijing host vertically integrated suppliers controlling patch array manufacturing through captive substrate foundries.
Japan
GaN epitaxy capacity concentrates in substrate foundries serving global defense and telecom amplifier demand, creating single-source supply exposure for equipment manufacturers. METI coordinates national 5G deployment targets and millimeter wave R&D subsidies under integrated innovation strategies. Tokyo and Osaka anchor compound semiconductor clusters where GaN-on-SiC wafer production feeds radar and satellite inter-satellite link programs.
India
TRAI recommendations for E-band and V-band delicensing await implementation, creating anticipated fixed wireless access markets in tier-2 cities where wireline infrastructure remains underpenetrated. The Department of Telecommunications governs spectrum auction calendars and equipment type-approval through WPC certification frameworks. Bangalore and Hyderabad concentrate system integration capabilities for upcoming carrier procurement cycles.
Millimeter Wave Equipment Market Competitive Environment
Listed leaders compete with private specialists across capital intensity and customer access dimensions, producing a tiered structure where scale-driven conglomerates face focused component vendors. The vendor base separates between integrated platform suppliers and discrete subsystem specialists. Three archetypes dominate: semiconductor-integrated modem-RF vendors, antenna-radio unit consolidators, and defense-qualified radar subsystem houses. Competitive moves concentrate on backward integration into compound semiconductor supply and geographic expansion through spectrum-aligned regional partnerships.
Within the integrated platform tier, Qualcomm and Samsung Electronics exemplify modem-RF consolidation strategies, while Ericsson occupies a position bridging European carrier relationships with harmonized standards compliance. These three anchors represent divergent geographic emphases—American, South Korean, and Swedish respectively—reflecting how national spectrum allocation timelines and defense procurement pipelines shape competitive positioning. Specialists in test and measurement instrumentation, including Keysight Technologies, sit within a separate tier serving certification and R&D validation demand across all deployment geographies.
| Leading Market Players |
|---|
| Qualcomm |
| Ericsson |
| Huawei |
| Nokia |
| Keysight Technologies |
| NEC Corporation |
| L3Harris Technologies |
| Aviat Networks |
| Samsung Electronics |
| Others |
Value Chain & Pricing Dynamics
CMOS beamformer substitution for GaN-on-SiC power amplifiers is redrawing procurement economics and supplier geography simultaneously, compressing unit costs in commercial 5G hardware while concentrating premium pricing in defense-qualified discrete architectures.
Pricing Analysis
Next-generation silicon photonics integration commands substantial premiums over legacy hybrid analog-digital beamforming hardware, while prior-generation passive antenna arrays face accelerated price erosion. Three-tier pricing structure across defense-qualified, carrier-grade, and commercial CPE levels reflects certification burden and thermal management complexity. Price differentiation hinges on FCC modular approval status and GaN epitaxy sourcing concentration. Margins are tightening in commercial 5G base stations as Qualcomm and MediaTek integrate antenna-in-package modules, while defense radar subsystems preserve premium pricing through active electronically scanned array qualification requirements.
Supply Chain Analysis
Inbound logistics costs through the Shanghai-Long Beach corridor and container availability constraints at Busan are amplifying lead-time uncertainty for millimeter wave beamformer chip shipments. GaN epitaxy capacity concentrates in Japanese and US substrate foundries, while CMOS beamformer fabrication rests on Taiwan and South Korea logic foundries. Single-source vulnerability in GaN-on-SiC wafer supply exposes equipment manufacturers to allocation risk during defense procurement surges. Distribution runs through carrier-direct procurement for integrated antenna-radio units and tier-one defense contractors for radar subsystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Millimeter wave equipment represents a high-growth disruption as FCC spectrum allocations in 24-47 GHz bands unlock licensed capacity for urban small-cell densification, pulling infrastructure investment toward higher-frequency backhaul solutions.
For Market Incumbents: Consolidate backward integration into compound semiconductor supply to secure GaN epitaxy allocation during defense modernization surges. Lock carrier-direct relationships through integrated antenna-radio unit qualification at Verizon and AT&T before modular approval timelines extend further. Threat substitution from C-band and mid-band 5G deployments compresses addressable volume for high-frequency equipment in macro-cell applications.
For New Entrants and Emerging Players: Anchor in Indian E-band and V-band fixed wireless access markets awaiting TRAI delicensing implementation, where wireline infrastructure remains underpenetrated in tier-2 cities. Target automotive 4D imaging radar sensor platforms at 77-81 GHz for premium German and Japanese vehicle manufacturers. Go-to-market leverage rests on antenna-in-package partnerships with established CMOS foundries.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed antenna subsystem specialists holding defense radar qualification and limited GaN-on-SiC captive supply. Long-term viability over the next decade hinges on satellite inter-satellite link terminal scale and automotive radar sensor fusion convergence. Watch FCC equipment authorization cycle duration as inflection indicator for vendor qualification list compression.
| Strategic Initiative | Industry Significance |
|---|---|
| GaN-on-SiC Capacity Expansion | Secures substrate supply for active electronically scanned array programs at US defense agencies. |
| Antenna-in-Package Integration | Collapses bill-of-materials complexity for Qualcomm and MediaTek 28 GHz handset modules. |
| ETSI Harmonization Compliance | Accelerates European certification timelines for fixed wireless access CPE manufacturers. |
| Satellite Terminal Qualification | Unlocks 71-86 GHz inter-satellite link procurement for low-earth orbit constellation operators. |
| Automotive Radar Partnership | Penetrates 77-81 GHz 4D imaging sensor platforms at German premium vehicle manufacturers. |
Study Parameters
Operator-level perspectives from telecom infrastructure procurement officers, defense radar program managers, compound semiconductor foundry executives, and fixed wireless access equipment vendors anchored the qualitative base. Primary interview insights combined with secondary validation from FCC equipment authorization databases, ETSI harmonized standards filings, MIIT GB certification records, and carrier capex disclosure documents. Bottom-up unit economics modeling triangulated against top-down spectrum allocation-driven demand projections.
Sensitivity analysis across beamforming efficiency benchmarks and national spectrum auction calendars shaped the analytical framework. Segmentation dimensions modeled include frequency band, power class, integration level, and defense versus commercial qualification status. CAGRs derived from carrier densification timelines, satellite constellation deployment schedules, and automotive radar platform adoption curves. Forecast inputs incorporated GaN epitaxy capacity utilization rates and FCC modular approval cycle duration assumptions.
Material uncertainties — regulatory rulemaking delays, compound semiconductor supply disruptions, and sub-6 GHz substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
RF Components
CATV RF Amplifiers Market
RF Components
High-Volume RF Front-End Module Test Systems Market
RF Components
RF Spectrum Analyzer Market
RF Components
Radio Frequency Integrated Circuit (RFIC) Market
RF Components
RF Components Market
RF Components
RF Tunable Filters Market
RF Components
5G Gain Block Amplifier Market
RF Components
High-Frequency RF Evaluation Board Market
RF Components
RF Isolator Market
RF Components
UHF RFID Inlays Market
RF Components
RF Transceiver Chip Market
RF Components
China Small Signal Transistor Market
RF Components
Multiband Booster Market
RF Components
US RFID Tags Market
RF Components
High Reliability Oscillators Market
RF Components
Acoustic Wave Filters Market