
 Sensor Fusion Market | 2026-2036
Sensor Fusion Market Size, Share, and Industry Trends Forecast 2026-2036
Sensor Fusion Market Intelligence
The basis for competitive advantage in sensor fusion is shifting from raw component accuracy to the sophistication of the processing algorithms. NXP Semiconductors leverages its automotive microcontroller portfolio for integrated system-on-chip solutions. STMicroelectronics specializes in high-volume inertial measurement units for consumer electronics. Meanwhile, Robert Bosch GmbH sustains its leadership in the automotive sector through deep integration with vehicle dynamics control systems and extensive R&D in radar and camera technologies.
Sensor fusion is the process of combining data from disparate sources, such as Inertial Measurement Units, cameras, and Lidar, to generate a unified and more accurate environmental model. Its primary purpose is to enhance perception and decision-making in automated systems. Among technologies, Kalman Filtering remains a foundational method, but neural networks are gaining prominence for complex pattern recognition. Advanced Driver Assistance Systems represent the largest application segment by value.
Regulatory frameworks create critical design constraints and market access requirements for sensor fusion systems. In the automotive sector, compliance with standards from the NHTSA in the United States and adherence to the EU's General Safety Regulation are mandatory. China's MIIT also sets specific guidelines for intelligent connected vehicles. Future vendor viability will depend on navigating these fragmented and evolving functional safety and data privacy mandates.
Market Dynamics
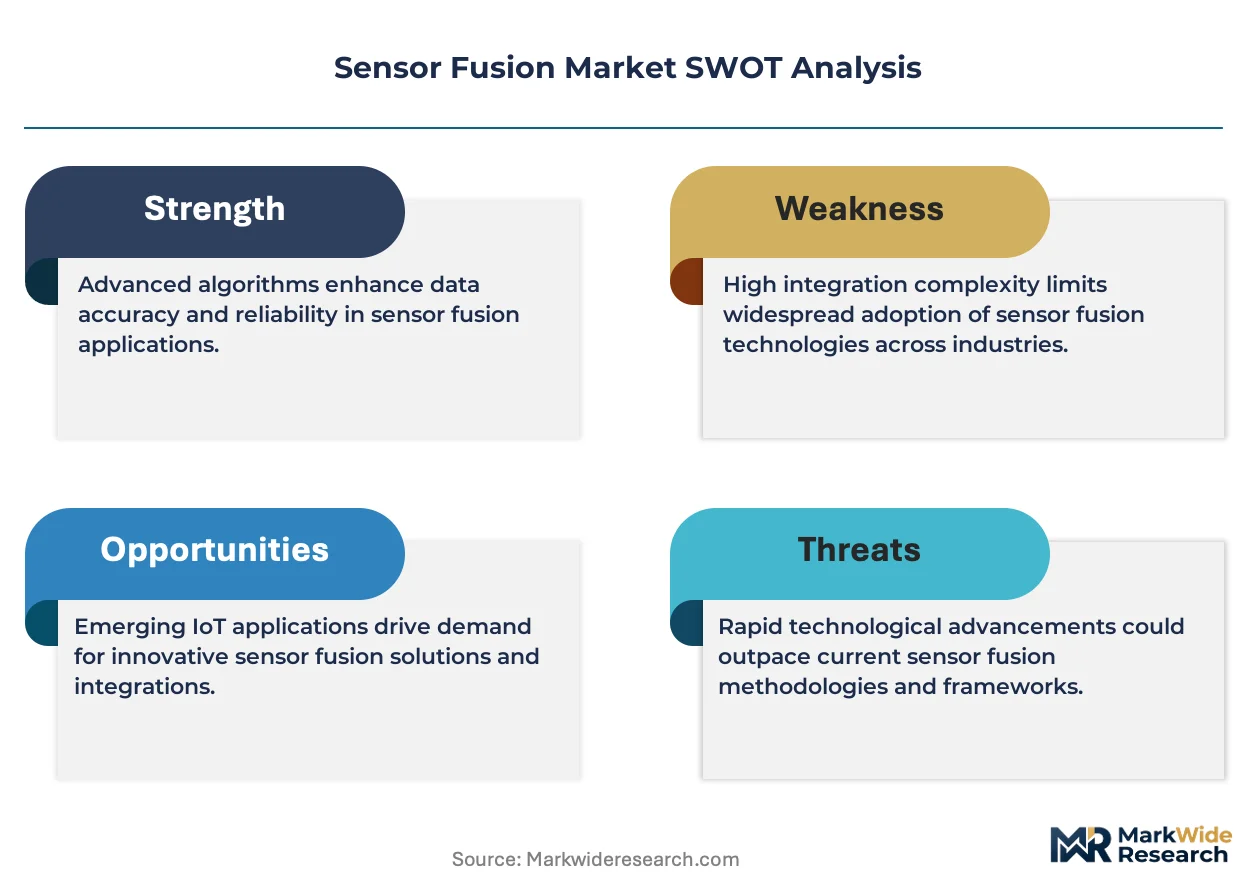
The core competitive dynamic in the sensor fusion market is shifting from the precision of individual hardware components to the sophistication of real-time processing algorithms. The development of advanced neural networks capable of interpreting complex, multi-modal sensor data defines the new frontier for market leadership.
Growth Catalysts
- Advanced Neural Networks:The maturation of deep learning algorithms enables more accurate and reliable interpretation of combined data streams from Lidar, radar, and cameras, which is critical for object detection and classification in complex environments.
- Autonomous Vehicle Sector:Demand for Level 2+ and higher autonomous driving systems in passenger and commercial vehicles necessitates the integration of multiple sensor types to achieve the required levels of safety and perceptual redundancy.
- EU General Safety Regulation:Mandates for advanced safety features, including automated emergency braking and lane-keeping assist, compel automotive manufacturers to adopt sophisticated sensor fusion systems to meet compliance requirements.
Market Restraints
- High-Cost Lidar Systems:The expense associated with high-resolution Lidar sensors remains a significant cost barrier, limiting the deployment of advanced sensor fusion suites to premium vehicle segments and specialized industrial applications.
- Data Processing Latency:Ensuring real-time processing of vast, high-bandwidth data streams from multiple sensors without compromising decision-making speed is a persistent technical hurdle, particularly for safety-critical applications.
- Fragmented Functional Safety Standards:Designing a single system architecture that simultaneously complies with divergent requirements from the NHTSA in the US, the KBA in Germany, and China's MIIT creates significant engineering and validation complexity.
Strategic Opportunities
- Industrial Automation:The application of sensor fusion in robotics for logistics, manufacturing, and warehouse management represents a significant growth area, enabling safer human-robot collaboration and more efficient autonomous navigation.
- Unmanned Aerial Vehicles:Drones for agriculture, inspection, and delivery services require lightweight, low-power sensor fusion modules for precise navigation and obstacle avoidance, creating a distinct market for specialized solutions.
- Sensor Fusion with 5G Connectivity:The convergence of on-board sensor data with low-latency V2X (Vehicle-to-Everything) communication enables cooperative perception, where vehicles share awareness to see beyond their immediate line of sight.
Industry Challenges
- Shortage of AI and ML Engineers:A talent gap exists for engineers with the specialized skills to develop, train, and validate the complex neural network algorithms that form the core of modern sensor fusion systems.
- Validation and Testing Burden:The immense operational cost and time required to validate system safety across millions of simulated and real-world scenarios present a major challenge to vendors seeking regulatory approval.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sensor Fusion Market |
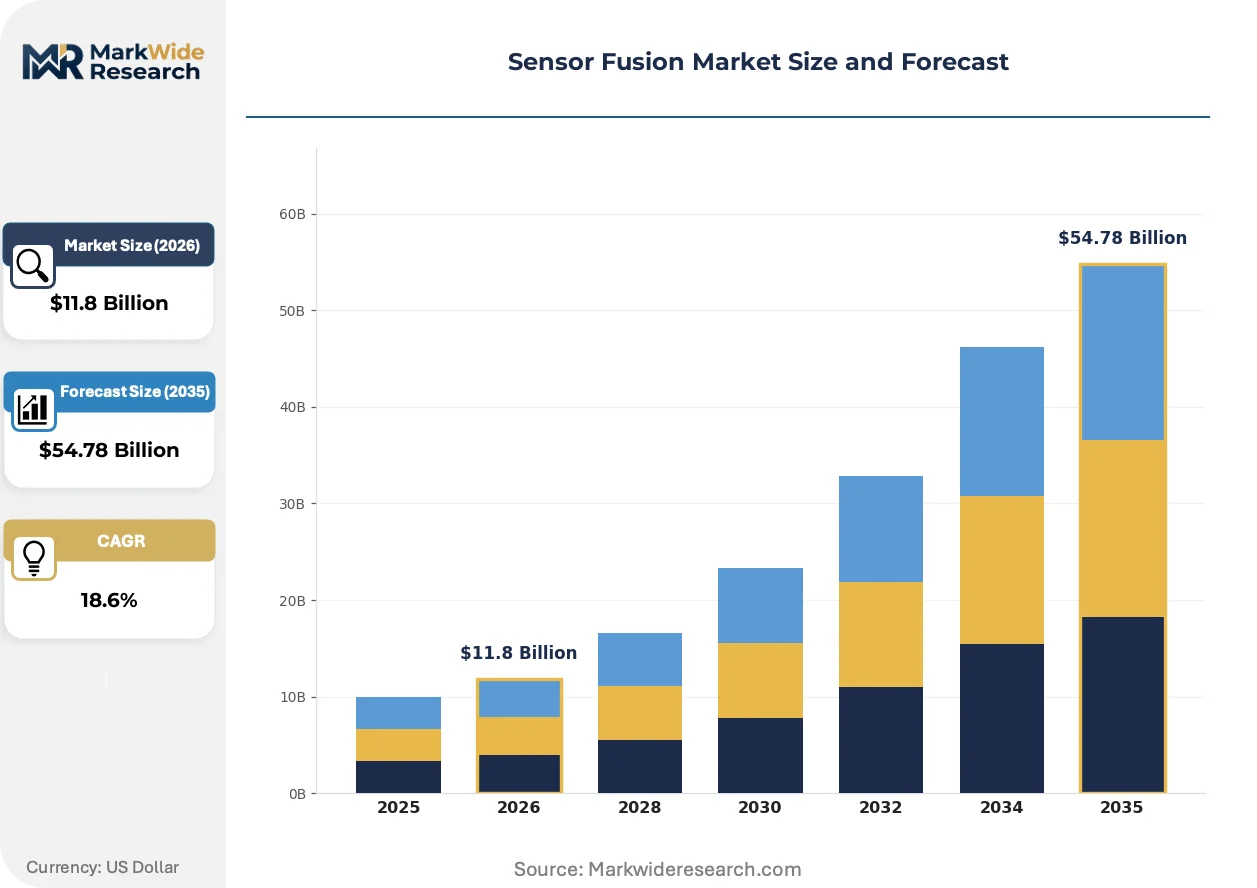
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $54.78 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inertial Measurement Units, Lidar Sensors, Radar Sensors, Ultrasonic Sensors, Camera Modules Technology: Kalman Filtering, Bayesian Networks, Neural Networks, Fuzzy Logic, Dempster-Shafer Theory Application: Advanced Driver Assistance Systems, Robotics Automation, Augmented Reality, Drones Navigation, Predictive Maintenance End User: Autonomous Vehicles, Industrial Robots, Consumer Electronics, Aerospace Manufacturers, Energy Providers |
| Companies Covered | NXP Semiconductors, Analog Devices, STMicroelectronics, Infineon Technologies, Renesas Electronics Corporation, Robert Bosch GmbH, Qualcomm Technologies, Texas Instruments, Bosch Sensortec GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sensor Fusion Market Strategic Shifts & Innovations
Technological evolution is now defined by system-level intelligence rather than individual component gains. This shift is compounded by new regulatory pressures that dictate design priorities for safety and data handling across key automotive markets, forcing a re-evaluation of system architectures.
Edge computing hardware, including specialized System-on-Chips (SoCs), enables data processing directly within sensor modules or local vehicle domains. Automotive Tier-1 suppliers and robotics manufacturers are adopting these SoCs to reduce latency and data transmission bandwidth requirements. This adoption is decentralizing processing power away from a single central computer, creating a more resilient and scalable system architecture.
The European Union's proposed AI Act introduces a risk-based framework for artificial intelligence systems. This legislation classifies autonomous driving systems as high-risk, imposing stringent requirements for data quality, transparency, and human oversight. Automotive OEMs are consequently investing heavily in explainable AI (XAI) and robust data governance protocols to ensure compliance for systems sold in Europe.
A demand-side shift is occurring where buyers prioritize software-defined capabilities and over-the-air (OTA) updateability over static hardware features. This de-emphasizes the traditional model of selling fixed-function hardware boxes, favoring subscription-based models for advanced features. This trend is most prominent in the premium passenger vehicle segment in North America and Europe, where consumers pay for software-enabled performance upgrades.
Sensor Fusion Market Segmentation
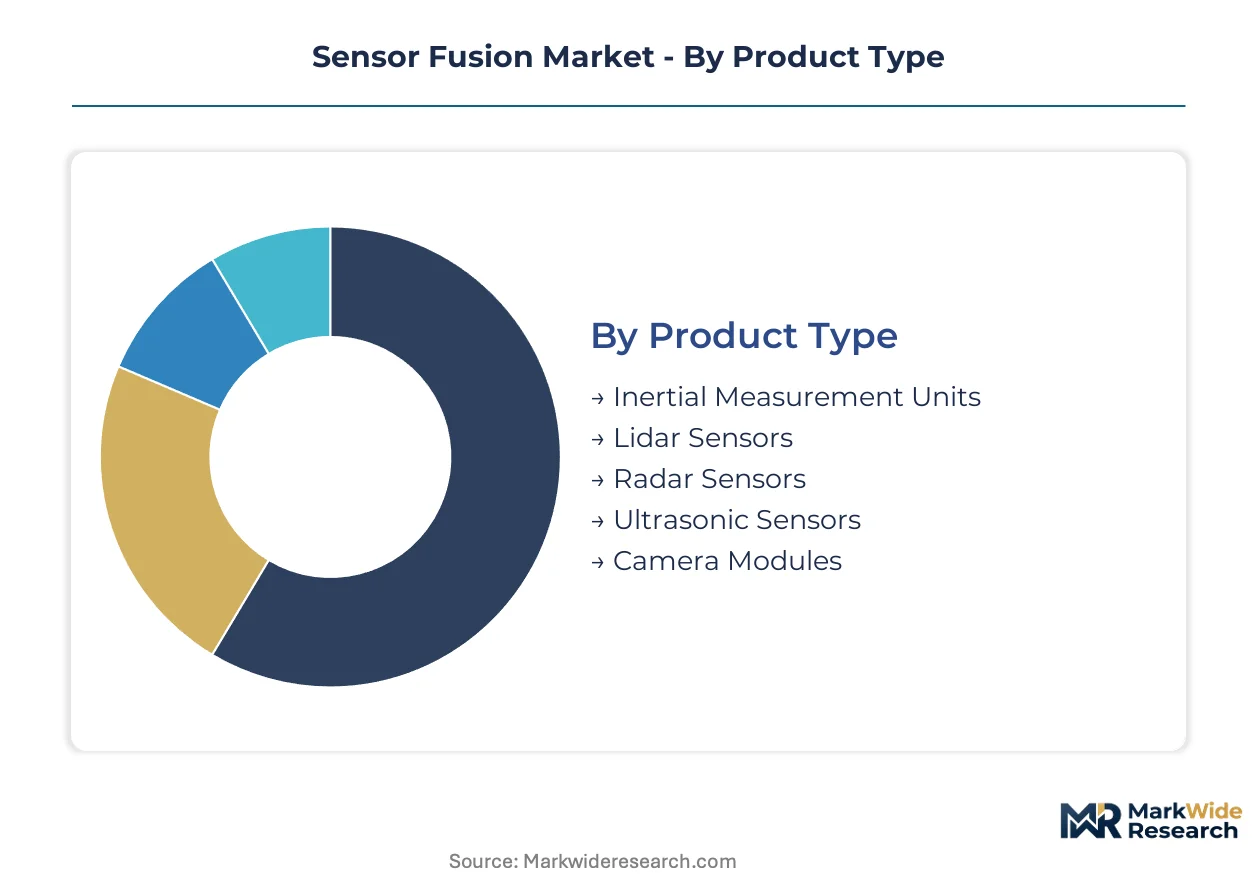
Understanding the Sensor Fusion Market through detailed segmentation reveals the intricate interplay between hardware components, processing algorithms, and diverse end-user demands. This granular analysis highlights how technological advancements and application-specific requirements shape market dynamics and competitive landscapes across different segments.
Product Type:
Supply concentration in sensor fusion components shapes the strategic choices for system integrators.
- Lidar Sensors:These devices emit pulsed laser light to measure distances, generating precise three-dimensional point clouds of the environment. Demand concentrates in autonomous vehicle development for high-resolution mapping and obstacle detection.
- Camera Modules:Optical sensors capture visual image data, providing rich contextual information for object recognition and scene understanding. Their cost-effectiveness and versatility drive integration into Advanced Driver Assistance Systems and consumer electronics.
- Inertial Measurement Units:IMUs combine accelerometers and gyroscopes to track orientation, velocity, and gravitational forces, crucial for precise navigation.
- Radar Sensors:These utilize radio waves to determine distance, velocity, and angle of objects, offering robust performance in adverse weather conditions.
- Ultrasonic Sensors:Employing sound waves, these sensors provide short-range distance measurement, commonly used for parking assistance and collision avoidance at low speeds.
Camera Modules absorb the bulk of installed capacity; Lidar Sensors are expanding most quickly.
Technology:
The diverse functional requirements across sensor fusion applications drive the adoption of specific processing technologies.
- Neural Networks:These advanced deep learning algorithms excel at complex pattern recognition and data interpretation from multiple sensor streams. Their application is critical for autonomous driving systems and compliance with AI Act regulations.
- Kalman Filtering:A foundational method for state estimation, Kalman filtering efficiently reduces noise and predicts system states from noisy measurements. It remains essential for real-time tracking and navigation in robotics and aerospace.
- Bayesian Networks:These probabilistic graphical models represent conditional dependencies among variables, enabling reasoning under uncertainty and decision-making.
- Fuzzy Logic:This approach handles imprecise or vague data, allowing systems to mimic human-like reasoning for control and decision processes.
- Dempster-Shafer Theory:Providing a framework for evidence theory, it manages incomplete or conflicting information by assigning belief functions to propositions.
Advanced algorithms are gaining prominence, while established methods provide foundational stability.
Application:
The varied operational environments and safety requirements of end-user applications dictate the specific sensor fusion configurations.
- Advanced Driver Assistance Systems:These systems enhance vehicle safety through features like automated emergency braking and lane-keeping assist, relying on fused sensor data for perception. Regulatory mandates from NHTSA and EU General Safety Regulation compel their widespread adoption.
- Robotics Automation:Sensor fusion enables autonomous navigation, precise manipulation, and safe human-robot collaboration in industrial robots and automated guided vehicles. This is critical for efficiency in logistics and manufacturing.
- Augmented Reality:This application overlays digital information onto the real world, requiring highly accurate spatial tracking and environmental understanding from fused sensor inputs.
- Drones Navigation:Sensor fusion ensures stable flight, precise positioning, and obstacle avoidance for Unmanned Aerial Vehicles used in agriculture and inspection.
- Predictive Maintenance:By integrating data from various sensors, systems can anticipate equipment failures, optimize maintenance schedules, and reduce operational downtime.
Automotive applications represent the largest segment by value, with industrial sectors exhibiting significant expansion.
End User:
Different end-user segments exhibit distinct value chain structures and varying tolerance for system complexity and cost.
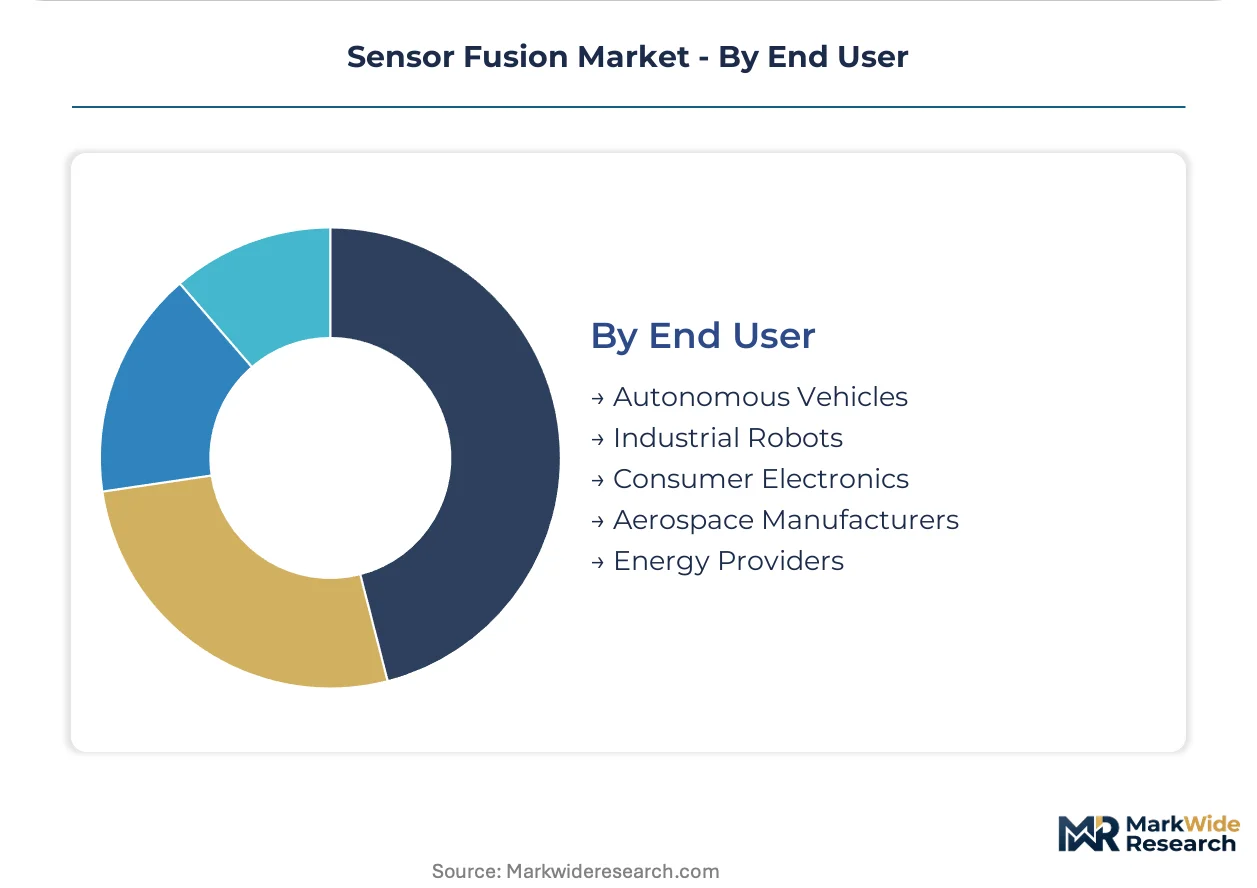
- Autonomous Vehicles:This segment includes Level 2+ to Level 5 self-driving cars, requiring comprehensive sensor fusion for safe and reliable perception. Regulatory compliance and redundant safety systems are paramount for these vehicles.
- Industrial Robots:These encompass collaborative robots (cobots) and Automated Guided Vehicles (AGVs) used in manufacturing and warehousing. Sensor fusion provides precise navigation and ensures safe operation alongside human workers.
- Consumer Electronics:This segment integrates sensor fusion in devices like smartphones, smartwatches, and virtual reality headsets for motion tracking and spatial awareness.
- Aerospace Manufacturers:Sensor fusion is critical for aircraft navigation, flight control, and environmental awareness in both manned and unmanned aerial systems.
- Energy Providers:Sensor fusion supports the monitoring of critical infrastructure, such as power grids and pipelines, and enables autonomous inspection of remote assets.
The automotive sector remains a primary revenue generator, while industrial and specialized applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart, Germany, stands as a central hub for sensor fusion development, driven by its robust automotive industry. This region, along with other key global centers, propels advancements in autonomous driving and industrial automation. Regulatory frameworks and local innovation ecosystems significantly shape market dynamics in these geographies.
United States
Demand for advanced driver assistance systems and Level 2+ autonomous vehicles drives sensor fusion adoption in the United States. NHTSA safety standards compel manufacturers to integrate sophisticated perception systems for regulatory compliance. Silicon Valley and Detroit serve as innovation centers, fostering both software development and automotive integration.
Germany
Germany's premium automotive sector fuels significant demand for high-performance sensor fusion systems in ADAS and autonomous driving. The EU's General Safety Regulation, enforced by the KBA, mandates advanced safety features requiring fused sensor data. Stuttgart and Munich concentrate automotive R&D and manufacturing, pushing technological boundaries.
China
China's rapid embrace of intelligent connected vehicles and industrial robotics is a primary demand driver for sensor fusion. MIIT guidelines for smart vehicles and national GB standards influence system design and market access. The Yangtze River Delta and Shenzhen are key technology and manufacturing hubs for these integrated systems.
Japan
Japanese automotive manufacturers and robotics companies drive substantial demand for precise sensor fusion solutions. METI initiatives support smart mobility and industrial automation, promoting advanced sensor integration. Tokyo and Nagoya anchor significant automotive R&D and production, focusing on system reliability and performance.
South Korea
South Korea exhibits strong demand for sensor fusion in autonomous driving, consumer electronics, and industrial robotics applications. Government support for future mobility and MFDS regulations encourage the development of advanced perception systems. The Seoul Capital Area leads in technology development, while Ulsan focuses on automotive production.
Sensor Fusion Market Key Industry Players
Capital-heavy hardware manufacturers compete with asset-light algorithm developers within the sensor fusion market. This market structure is transitioning from component-centric competition to system-level intelligence, favoring integrated solution providers. Strategic archetypes include specialized sensor producers, full-stack system integrators, and AI software specialists. Companies increasingly pursue strategic partnerships to combine hardware expertise with advanced software capabilities.
Among integrated hardware and software providers, NXP Semiconductors exemplifies a focus on automotive microcontroller portfolios. STMicroelectronics occupies a position as a high-volume inertial measurement unit supplier for diverse applications. Robert Bosch GmbH, a German industrial conglomerate, anchors leadership in automotive radar and camera technologies, reflecting deep integration with vehicle dynamics control systems.
| Leading Market Players |
|---|
| NXP Semiconductors |
| Analog Devices |
| STMicroelectronics |
| Infineon Technologies |
| Renesas Electronics Corporation |
| Robert Bosch GmbH |
| Qualcomm Technologies |
| Texas Instruments |
| Bosch Sensortec GmbH |
| Others |
Cost & Logistics Intelligence
The stark divergence between premium Lidar systems and high-volume camera modules defines the sensor fusion market's pricing and supply chain dynamics. This bifurcation creates distinct pricing power for specialized hardware and processing algorithms, influencing component sourcing strategies globally.
Pricing Analysis
Value-based pricing for sensor fusion systems anchors on achieved safety levels and operational efficiency in autonomous applications. Software sophistication and adherence to functional safety certifications from NHTSA or the EU General Safety Regulation drive significant price differentiation. Pricing pressure stems from hardware commoditization in lower-tier applications, while high R&D investments in neural networks elevate software costs. Mass-market ADAS and consumer electronics exhibit the highest price sensitivity, contrasting with the lower sensitivity in premium autonomous vehicles.
Supply Chain Analysis
Dual-sourcing requirements in the automotive sector drive diversified component procurement for sensor fusion systems. Supply concentration for advanced semiconductors and specialized optical components centers on Taiwan, South Korea, and Japan. Raw material dependencies include rare earth elements for magnets and high-purity silicon for integrated circuits. Single-source vulnerability for cutting-edge AI processors poses a structural risk. Distribution runs primarily through direct sales channels to major automotive OEMs and Tier-1 integrators, with specialized distributors serving industrial automation and consumer electronics segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sensor fusion market is rapidly consolidating, driven by the immense R&D investment required for advanced AI algorithms and the prohibitive costs of functional safety validation. This pressure forces smaller, less capitalized players to exit or seek strategic partnerships.
For Market Incumbents: Lock in long-term supply agreements with major automotive OEMs to secure volume and co-develop next-generation platforms. Deepen vertical integration into AI software development to control the perception stack and differentiate from hardware-only providers. Investment in global R&D centers and robust functional safety certifications, such as ISO 26262, will counter threats from asset-light algorithm specialists. This strategy mitigates margin pressure from commoditized hardware components. For New Entrants and Emerging Players: Enter via niche applications requiring specialized sensor fusion solutions, such as industrial automation for logistics or precision navigation for Unmanned Aerial Vehicles. Target regions like Europe, where stringent EU AI Act compliance creates demand for explainable AI solutions. Offer lightweight, low-power edge-AI sensor fusion modules with pre-validated software stacks as a go-to-market strategy. This approach avoids direct competition with established automotive Tier-1s. For Investors and Strategic Acquirers: Re-rating potential sits with integrated solution providers given the increasing value placed on software and system-level intelligence over individual components. Long-term viability hinges on the widespread adoption of autonomous systems across automotive, industrial, and aerospace sectors. Target acquisition archetypes include AI software specialists with proprietary neural network algorithms or niche sensor manufacturers with unique, high-performance Lidar technologies. The signal to watch is accelerated regulatory harmonization across major automotive markets.| Strategic Initiative | Industry Significance |
|---|---|
| Deepen AI Algorithm R&D | Enhances perception accuracy for autonomous vehicles and meets EU AI Act transparency requirements. |
| Forge OEM Co-Development Partnerships | Secures long-term revenue streams and accelerates integration into next-generation automotive platforms. |
| Invest in Edge Processing SoCs | Reduces data processing latency for safety-critical applications in autonomous driving systems. |
| Expand Functional Safety Certification | Ensures compliance with NHTSA and EU General Safety Regulation, enabling market access. |
| Target Industrial Robotics Integration | Diversifies revenue beyond automotive, leveraging sensor fusion for efficient warehouse automation. |
Research Approach
Independent corroboration across primary interviews, regulatory body publications, and company financial disclosures underwrites the qualitative findings of this analysis. Industry stakeholders, including automotive OEM engineers, AI/ML algorithm developers, and robotics automation specialists, provided critical insights. Secondary validation drew from NHTSA safety reports and EU General Safety Regulation documents. This approach combined bottom-up market sizing with top-down validation for robust data integrity.
Comparable historical periods anchored the forecast window, informing the regression analysis and scenario modeling employed over the projection horizon. Segmentation dimensions included product type, core technology, application, end-user industry, and geographic region. Compound annual growth rates were derived from observed historical growth trends and projected market adoption. Key forecast inputs included autonomous vehicle production forecasts and evolving regulatory mandates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of rapid technological disruption or unforeseen regulatory shifts. Forecasts reflect assumptions regarding current technological trajectories for autonomous systems. Deviation in the pace of AI algorithm development would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Consumer Grade Electrochemical CO Sensor Market
Sensors and Controls
HVAC Sensor Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Printed Antenna Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Level Measuring Equipment Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Global Blind Spot Monitor Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
China PV Monitoring Systems Market
Sensors and Controls
Middle-East and Africa Nanosensors Market