
 Japan Digital Thermometer Market | 2026-2036
Japan Digital Thermometer Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Digital Thermometer Market Insights
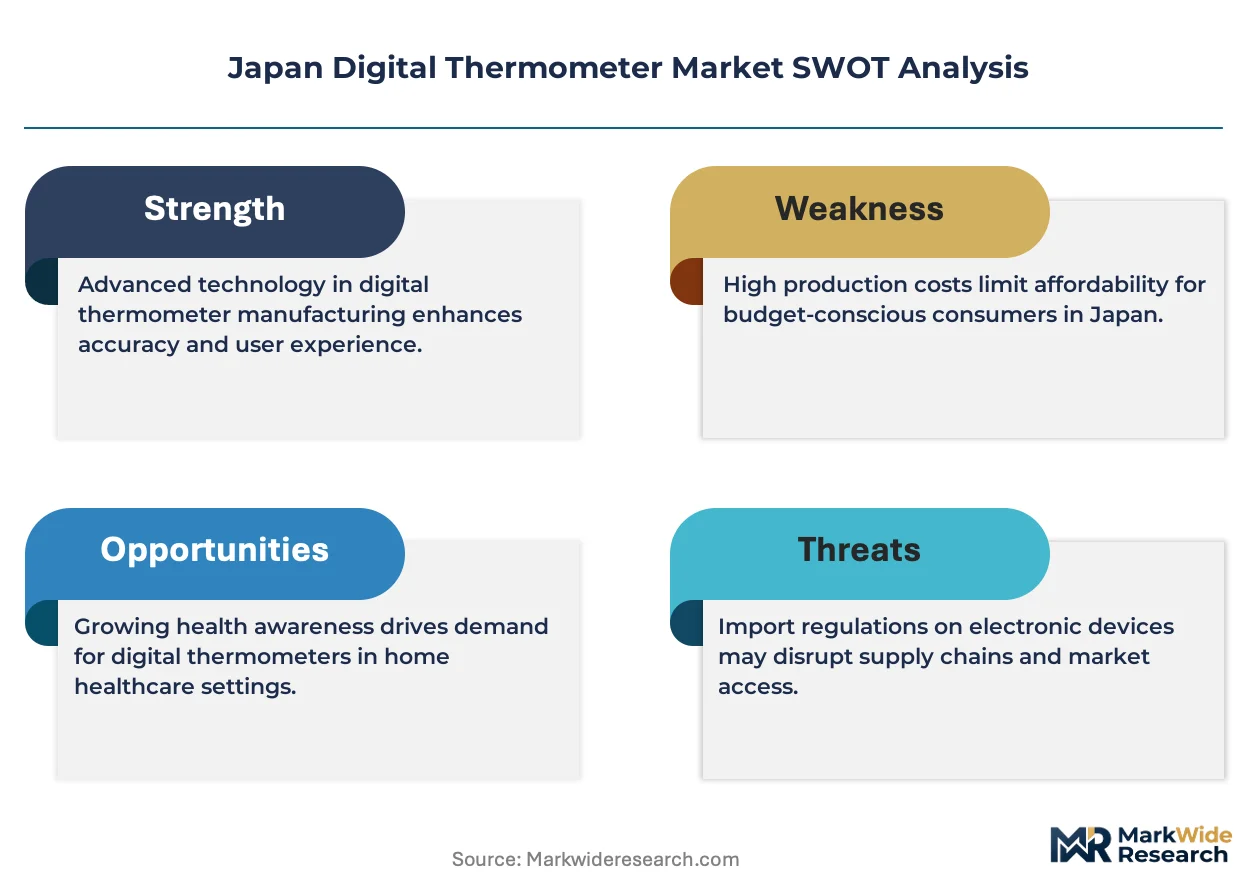
Home healthcare is consolidating as the dominant end-use vertical for digital thermometers in Japan. Omron Healthcare Co., Ltd. leverages its domestic manufacturing footprint to sustain channel control across pharmacy and retail networks. A&D Company, Limited anchors the professional diagnostics segment through precision sensor technology. Terumo Corporation competes in hospital procurement with specialized clinical-grade devices.
A digital thermometer measures body temperature through electronic heat sensors, typically achieving accuracy within 0.1°C via thermistor or infrared detection systems, and serves primary clinical screening and home health monitoring functions. Infrared models lead the product type landscape due to non-contact hygiene protocols in post-pandemic care settings. Bluetooth-enabled devices represent the fastest-growing technology segment as remote patient monitoring platforms expand. The household end-user category holds mature volume while laboratories command premium pricing for calibrated precision instruments.
METI enforces electrical safety standards under the Electrical Appliance and Material Safety Law, while PMDA classifies clinical thermometers as Class II medical devices requiring quality management system certification. JIS standards further specify measurement accuracy ranges that manufacturers must validate before domestic sale. Stakeholders should monitor PMDA guidance on software-as-a-medical-device classifications as firmware updates become standard in connected thermometer models.
Market Dynamics
Japan's digital thermometer market is consolidating around connected health infrastructure as METI and PMDA accelerate software-as-a-medical-device classifications for firmware-enabled devices, forcing manufacturers to restructure quality management systems around real-time update protocols.
Growth Catalysts
- PMDA Class II Medical Device Framework:The Pharmaceutical and Medical Device Act mandates rigorous quality certification that elevates domestic manufacturer credibility and creates barriers against unverified imports, reinforcing channel control for certified suppliers.
- Bluetooth Low Energy Integration:Remote patient monitoring platforms in Tokyo and Osaka metropolitan hospitals are standardizing wireless temperature data transmission, pulling demand toward connected thermometer models with API-compatible firmware.
- Home Healthcare Vertical:Japan's aging demographic concentration in Aichi, Kanagawa, and Fukuoka prefectures is shifting diagnostic device procurement toward household-grade precision instruments with clinical-equivalent accuracy specifications.
Market Restraints
- Thermistor Supply Concentration:Precision temperature sensors for clinical-grade devices depend on concentrated semiconductor foundry capacity in East Asia, exposing Japanese manufacturers to input volatility and extended lead times for calibrated components.
- JIS Certification Timeline:The Japanese Industrial Standards validation process for measurement accuracy ranges imposes six-to-twelve-month pre-market approval cycles that compress first-mover advantages for firmware-innovative products.
- Non-Contact Infrared Substitution:Industrial thermal imaging systems adapted for human screening during public health emergencies created a lower-cost alternative segment that competes with purpose-built medical thermometers in institutional procurement.
Strategic Opportunities
- Hokkaido and Tohoku Underpenetration:Rural prefectures with dispersed elderly populations and lower hospital density present white-space demand for telehealth-integrated home monitoring devices with cellular connectivity fallback.
- METI Smart Wellness Subsidies:The Ministry of Economy, Trade and Industry's regional healthcare digitization grants incentivize municipal governments to procure connected diagnostic fleets for community health centers.
- AI-Augmented Fever Pattern Analysis:Convergence of edge-computing thermometers with machine-learning symptom triage algorithms enables subscription-based diagnostic services that extend device lifetime value beyond hardware margins.
Industry Challenges
- Embedded Systems Firmware Expertise:The shift toward software-as-a-medical-device classification creates acute talent scarcity for engineers capable of navigating PMDA cybersecurity validation protocols while maintaining ISO 13485 quality management compliance.
- Legacy Hospital IT Integration:Provincial medical institutions in Shikoku and Chugoku regions operate on fragmented electronic health record systems that resist standardized API connections, forcing thermometer suppliers to maintain multiple firmware branches.
- Post-Market Surveillance Burden:Real-world performance monitoring requirements under the Pharmaceutical and Medical Device Act impose ongoing data infrastructure costs that disproportionately strain mid-tier manufacturers without captive cloud platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Digital Thermometer Market |
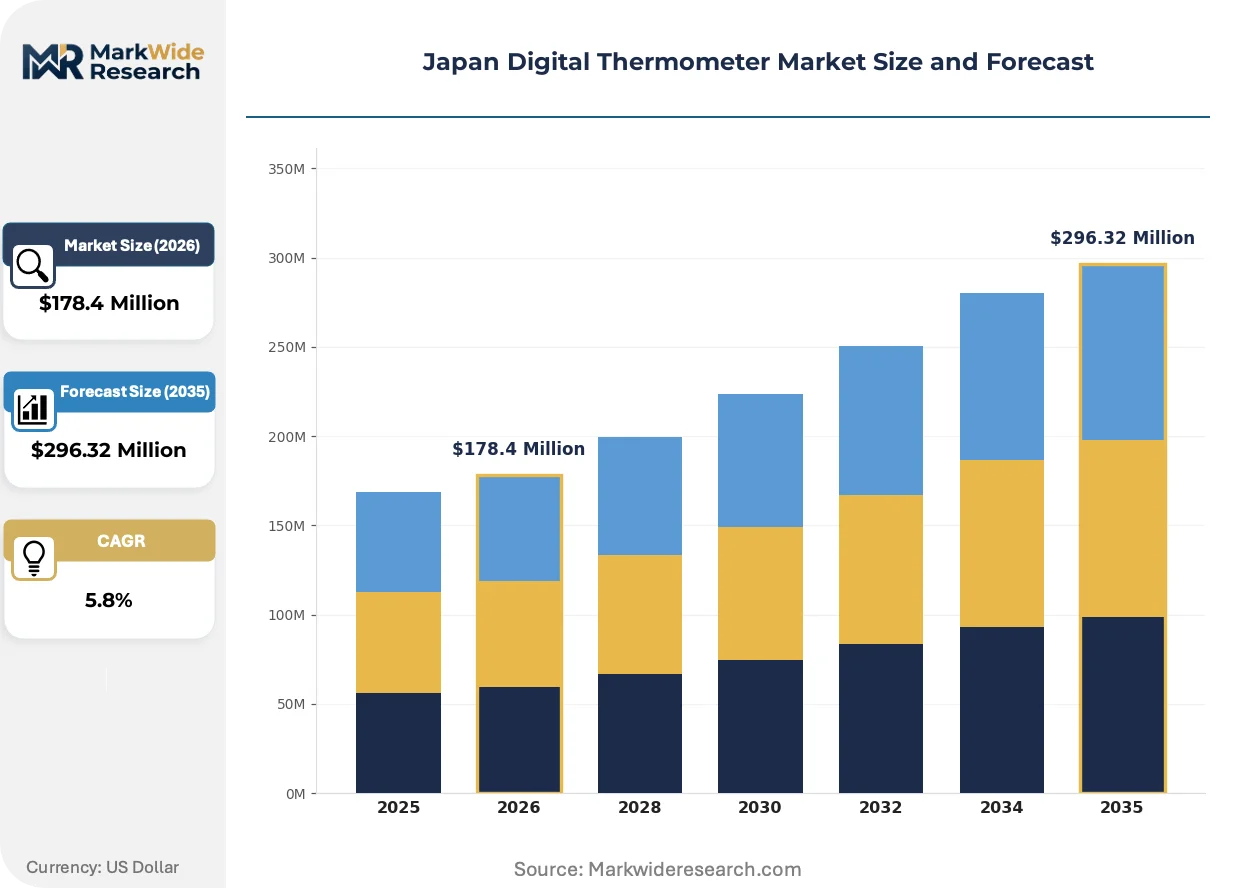
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $296.32 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Infrared, Contact, Flexible, Digital Display End User: Households, Hospitals, Clinics, Laboratories Application: Home Use, Medical Diagnostics, Wellness Monitoring, Research Technology: Bluetooth, Wi-Fi, Non-Contact, Analog |
| Companies Covered | A&D Company, Limited, Philips Healthcare, Omron Healthcare Co., Ltd., 3M Health Care, Braun, Terumo Corporation, Citizen Systems, GE Healthcare, Panasonic Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Digital Thermometer Market Trends and Innovations
Wireless connectivity standards and predictive health algorithms are transforming Japan's digital thermometer market from discrete measurement tools into continuous monitoring nodes within integrated care networks.
Infrared array sensors with multi-point temperature mapping are rewriting clinical screening protocols in Tokyo metropolitan hospitals. Tertiary care centers are replacing single-spot forehead thermometers with spatially resolved thermal imaging for fever detection in high-throughput outpatient settings. This sensor evolution is compressing the distinction between consumer wellness devices and institutional diagnostic equipment.
METI's 2023 Electrical Appliance and Material Safety Law amendments impose stricter electromagnetic compatibility testing on Bluetooth-enabled medical devices. The regulation forces firmware architects to redesign radio frequency shielding and battery management systems, adding engineering validation cycles. Home healthcare OEMs are responding by pre-certifying modular wireless subsystems across product families.
Pharmacy chains in Kansai and Chubu regions are unbundling after-sales calibration services from device sales. Buyers now subscribe to annual JIS traceability verification rather than purchasing replacement units, shifting distributor revenue toward recurring service contracts. This model is most visible in Osaka's consolidated retail networks where inventory turnover pressure favors service-based margin structures.
Japan Digital Thermometer Market Segmentation
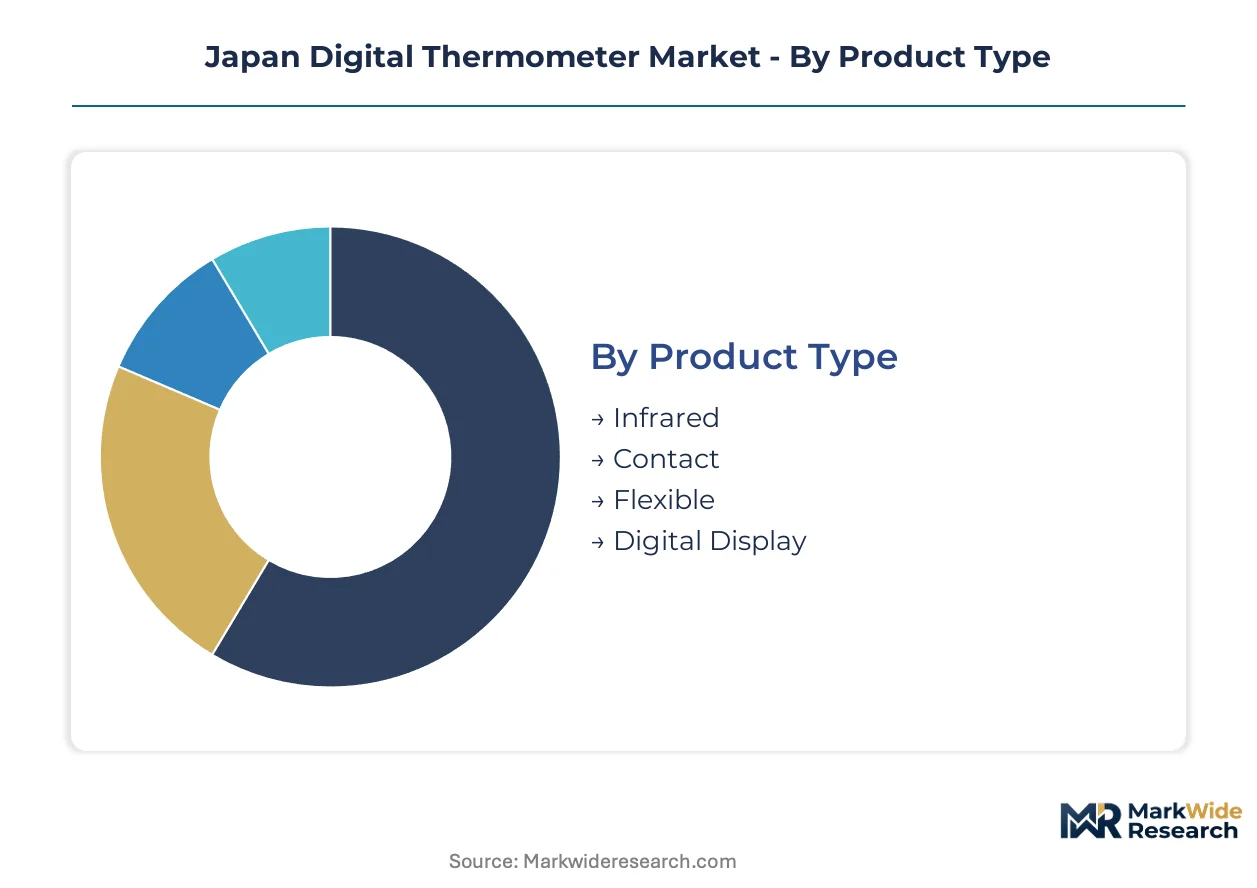
Digital thermometer segmentation in Japan reflects the tension between clinical-grade precision requirements and mass-market accessibility demands. PMDA classification tiers and METI electrical safety standards create natural fault lines across product categories, while regional healthcare infrastructure disparities concentrate demand patterns.
Product Type:
Customization intensity varies sharply across this category, from commodity contact probes to specialized infrared arrays requiring dedicated calibration protocols.
- Infrared:Non-contact thermal detection systems employ thermopile or microbolometer arrays measuring infrared radiation emitted from skin surfaces. Tokyo metropolitan hospitals and Osaka airport screening facilities drive procurement for multi-point spatial resolution models that exceed single-spot consumer specifications. PMDA Class II certification requirements for clinical-grade infrared devices extend validation timelines but lock in premium pricing tiers.
- Contact:Thermistor-based probes with direct tissue contact deliver accuracy within 0.1°C through resistive temperature detection. Household demand concentrates in Aichi and Kanagawa prefectures where aging demographics prioritize clinical-equivalent precision for home monitoring. JIS B 7411 compliance for measurement repeatability separates pharmacy-grade units from unverified imports.
- Flexible:Elongated probe designs with articulating tips adapt to pediatric and geriatric anatomical requirements. Kansai region maternal health clinics represent concentrated procurement channels.
- Digital Display:Integrated LCD or OLED readout modules with backlighting for low-vision accessibility. Standard inclusion across all price tiers limits standalone differentiation.
Most installed capacity flows through Contact segments. Expansion is steepest in Infrared.
End User:
Volume concentration versus margin capture divides this category, with institutional procurement demanding extended warranty terms and household channels prioritizing point-of-sale accessibility.
- Households:Individual consumers purchasing through pharmacy chains, electronics retailers, and direct-to-consumer platforms. Fukuoka and Hokkaido prefectures show elevated per-capita acquisition rates correlating with elderly population density and dispersed primary care access. Bluetooth-enabled models with smartphone integration command price premiums despite equivalent sensor hardware.
- Hospitals:Acute care institutions in Tokyo, Osaka, and Aichi prefectures operating under centralized procurement frameworks. Tertiary medical centers require API-compatible firmware for electronic health record integration, forcing suppliers to maintain dedicated institutional product lines with enhanced cybersecurity validation.
- Clinics:Outpatient and specialty practices with intermediate volume requirements and limited IT infrastructure. Chubu region private practices favor standalone devices without network connectivity to minimize compliance burden.
- Laboratories:Research and reference facilities demanding NIST-traceable calibration certificates and documented uncertainty budgets. Tsukuba science city and Osaka pharmaceutical research corridors concentrate demand.
Households absorb the greatest unit volume. Laboratories deliver the highest per-unit margins.
Application:
Use-case specificity determines firmware complexity and regulatory pathway, from unregulated wellness tracking to PMDA-supervised diagnostic claims.
- Home Use:Self-administered temperature monitoring for fever screening and chronic condition management. METI Electrical Appliance and Material Safety Law governs hardware safety without medical device classification for non-diagnostic claims. Rural Tohoku prefectures with limited clinic access drive demand for cellular-connected models with remote physician consultation integration.
- Medical Diagnostics:Clinician-administered screening with documented results for treatment decisions. PMDA Class II medical device framework mandates quality management system certification and post-market surveillance. Hospital procurement in metropolitan prefectures favors multi-parameter vital sign integration over standalone thermometry.
- Wellness Monitoring:Preventive health tracking without diagnostic intent, circumventing medical device regulations through careful marketing positioning. Corporate occupational health programs in Tokyo and Osaka represent emerging demand clusters.
- Research:Controlled studies requiring calibrated precision and data logging capabilities. Academic medical centers and pharmaceutical developers in Kanagawa and Kyoto prefectures specify custom firmware for protocol compliance.
Medical Diagnostics commands the strictest certification requirements. Home Use is expanding most quickly.
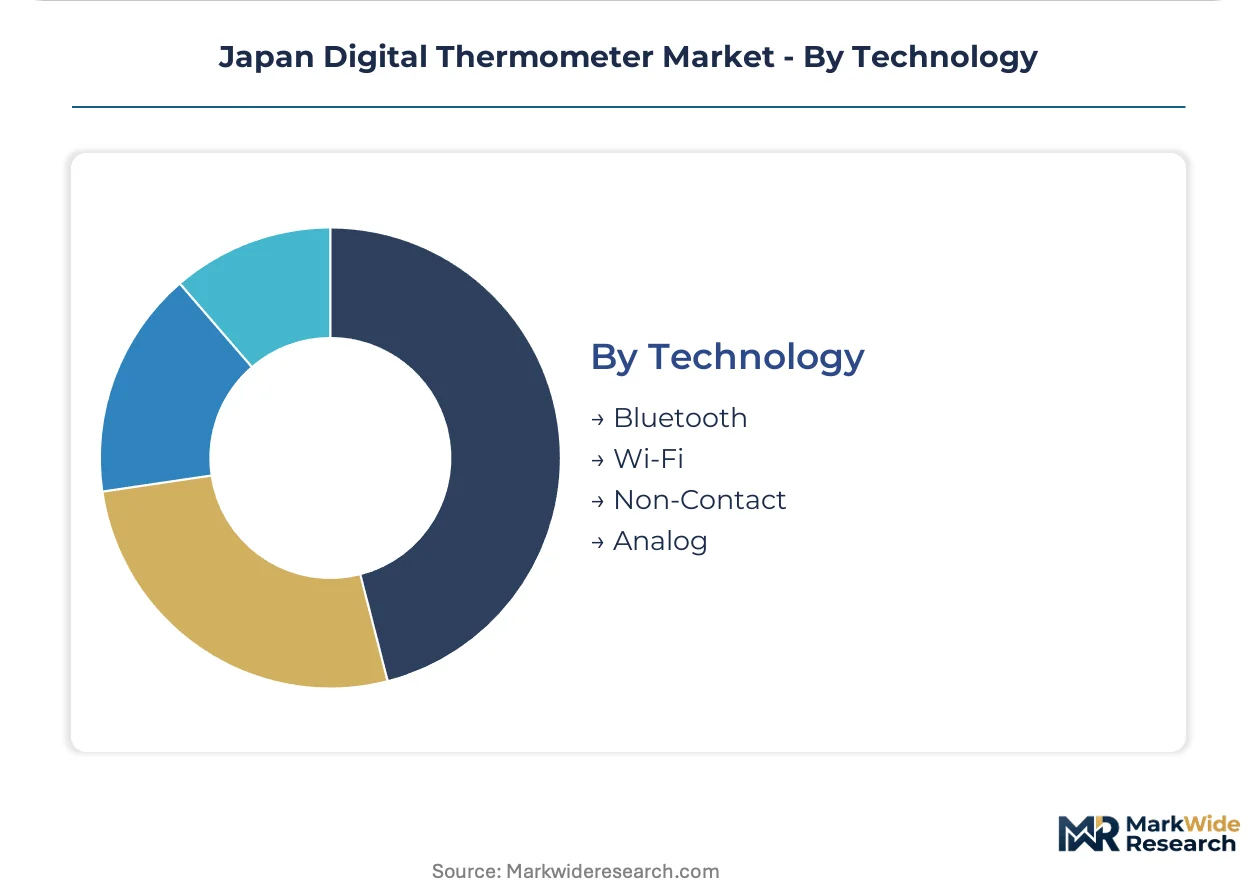
Technology:
Connectivity architecture and sensing modality create distinct engineering investment profiles and regulatory exposure levels.
- Bluetooth:Low-energy wireless protocols enabling smartphone pairing and cloud data transmission. Tokyo and Osaka hospital systems standardizing on Bluetooth-enabled fleets for remote patient monitoring platform integration. METI electromagnetic compatibility amendments impose additional shielding validation cycles.
- Wi-Fi:Direct internet connectivity for standalone operation without intermediary devices. Municipal health centers in Hokkaido deploying Wi-Fi thermometers for community telehealth initiatives under METI Smart Wellness Subsidies.
- Non-Contact:Infrared detection without physical patient contact, encompassing both medical-grade thermopile systems and adapted industrial thermal imagers. Post-pandemic hygiene protocols in Kansai region clinics sustain preference over contact alternatives.
- Analog:Mercury-free liquid crystal or bimetallic strip technologies without electronic components. Legacy procurement in underfunded Shikoku provincial institutions and consumer price sensitivity segments.
Non-Contact holds the largest installed base. Bluetooth shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic production migrates toward prefectures with streamlined PMDA quality management certification pathways, exploiting cost-of-compliance gaps between metropolitan regulatory clusters and provincial manufacturing zones.
Kanto/Tokyo
Tokyo prefecture concentrates hospital procurement for Bluetooth-enabled thermometers with electronic health record integration. METI Smart Wellness Subsidies fund municipal telehealth deployments in Saitama and Chiba satellite cities. The Keihin industrial corridor hosts precision sensor calibration facilities serving Class II medical device manufacturers.
Kansai/Osaka
Osaka anchors pharmacy chain consolidation with subscription-based JIS calibration services replacing device turnover. Hyogo prefecture's Kobe medical device cluster specializes in infrared array manufacturing for tertiary care screening. PMDA regional consultation centers accelerate pre-market approval timelines for domestic applicants.
Chubu/Nagoya
Aichi prefecture's aging demographic density drives household-grade precision instrument demand for home healthcare monitoring. Gifu and Shizuoka electronics subcontractors supply thermistor components under extended quality validation protocols. The Nagoya manufacturing belt maintains captive calibration laboratories reducing third-party certification costs.
Kyushu
Fukuoka prefecture exhibits elevated per-capita thermometer acquisition correlating with dispersed primary care access and elderly population concentration. Kumamoto and Kagoshima municipal governments procure Wi-Fi-enabled community health center fleets under METI regional digitization grants. Local semiconductor foundries face input volatility for precision temperature sensors.
Hokkaido
Hokkaido's rural geography and lower hospital density create white-space demand for cellular-connected home monitoring devices with telehealth integration. Sapporo municipal health centers deploy standalone Wi-Fi thermometers under subsidy programs. Thermistor supply lead times extend due to distance from East Asian semiconductor foundry networks.
Japan Digital Thermometer Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek firmware expertise for software-as-a-medical-device compliance. The vendor base separates into three tiers: domestic precision specialists with captive calibration infrastructure, diversified electronics conglomerates leveraging scale, and foreign entrants navigating JIS certification barriers. Two archetypes prevail—vertically integrated sensor manufacturers and platform-agnostic connectivity providers. Competitive intensity concentrates on M&A for embedded systems talent and geographic expansion into underpenetrated prefectures.
Among domestic healthcare specialists, Omron Healthcare Co., Ltd. and A&D Company, Limited exemplify contrasting positioning archetypes. Omron anchors the pharmacy and retail channel control tier through domestic manufacturing footprint advantages. A&D occupies the professional diagnostics segment anchored by precision sensor technology specialization. Terumo Corporation represents the hospital procurement tier with clinical-grade device focus. Foreign-based multinationals including Philips Healthcare and GE Healthcare sit within the institutional platform integration tier, competing on electronic health record compatibility rather than sensor hardware differentiation.
| Leading Market Players |
|---|
| A&D Company, Limited |
| Philips Healthcare |
| Omron Healthcare Co., Ltd. |
| 3M Health Care |
| Braun |
| Terumo Corporation |
| Citizen Systems |
| GE Healthcare |
| Panasonic Corporation |
| Others |
Pricing and Supply Chain Analysis
PMDA Class II certification tiers bifurcate Japan's digital thermometer landscape into premium clinical-grade and commoditized household segments, with this divergence manifesting in both margin structures and sourcing configurations. Hospital procurement channels absorb extended JIS validation costs through multi-year service contracts, while pharmacy retail chains compress supplier margins through high-volume turnover economics.
Pricing Analysis
Distributor markup layers in Osaka's consolidated pharmacy networks absorb 15-25 point spreads between factory gate and shelf price. Three-tier pricing structure across premium, standard, and economy levels separates PMDA-certified clinical units from METI safety-compliant household devices and unverified imports. Cost compression in the economy tier intensifies because of thermistor input volatility from East Asian foundries. Household consumers in Fukuoka and Hokkaido exhibit highest price sensitivity, while Tokyo tertiary care centers prioritize API compatibility over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from PMDA quality management protocols force Japanese manufacturers to qualify thermistor suppliers across Taiwan, South Korea, and domestic Nagoya subcontractors. Precision temperature sensors draw from concentrated semiconductor foundry capacity, with calibrated probe assemblies resting on lithium battery cell supply from Panasonic and Sony energy divisions. Single-source vulnerability in infrared array microbolometers creates exposure to export control shifts. Distribution runs through pharmacy chain central buying offices and hospital GPO procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's digital thermometer market functions as a geographic-arbitrage play where PMDA certification timelines in Tokyo-Osaka corridors impose six-to-twelve-month delays that rural prefecture municipal buyers circumvent through METI subsidy fast-tracks.
For Market Incumbents: To counter firmware talent scarcity from software-as-a-medical-device reclassification, Omron and A&D should deepen captive calibration infrastructure in Gifu and Shizuoka electronics clusters while acquiring embedded systems boutiques in Sapporo and Fukuoka. Channel control through pharmacy subscription services defends against infrared array substitution from industrial thermal imaging entrants. For New Entrants and Emerging Players: Direct-to-clinic telehealth platforms offer the lowest friction entry vector, with Hokkaido and Tohoku rural health centers representing the most penetrable geography given cellular connectivity fallback demand and dispersed elderly populations. Wi-Fi-enabled community health center fleets under METI Smart Wellness Subsidies provide a named procurement anchor for municipal pilot contracts. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier manufacturers lack captive cloud platforms for post-market surveillance compliance. Long-term viability favors vertically integrated sensor-calibration-service hybrids over pure hardware OEMs. Watch PMDA guidance expansion on AI-augmented fever pattern analysis as the inflection signal for subscription revenue model validation.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-a-Medical-Device Submission | Accelerates market access for Bluetooth-enabled thermometers with firmware update protocols. |
| Hospital System Partnership | Locks in API-compatible EHR integration demand from Tokyo metropolitan tertiary care centers. |
| Backward Integration into Thermistor Calibration | Reduces third-party certification costs and compresses JIS validation timelines for Class II devices. |
| Telehealth Platform Integration | Captures METI Smart Wellness Subsidy flows for rural prefecture municipal procurement. |
| Subscription Calibration Service Launch | Shifts distributor revenue from hardware turnover to recurring JIS traceability verification contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with PMDA regulatory consultants, hospital biomedical engineers, pharmacy chain category managers, and thermistor component procurement leads with secondary validation against METI subsidy disclosures, PMDA medical device registration databases, JIS standard revision notices, and Osaka retail audit data. Bottom-up shipment estimates from Aichi and Kanagawa manufacturing clusters triangulated against top-down healthcare expenditure flows.
Segment-weighting applied product type, end user, application, and technology dimensions across the modeling period, with infrared versus contact modality splits and Bluetooth adoption curves as primary volume drivers. CAGRs derived from regression against aging demographic projections and hospital digitization spend patterns, incorporating firmware-enabled device replacement cycles and JIS certification queue lengths as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for edge-computing AI thermometers would alter the outlook if PMDA accelerates software-as-a-medical-device enforcement. Deviation in thermistor foundry capacity allocation or METI subsidy renewal rates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Timing Device Market
Sensors and Controls
MEMS Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Wireless Pressure Sensors Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Battery Monitor Market
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Africa Robotic Sensors Market