
 Fingerprint Sensor Market | 2026-2036
Fingerprint Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Fingerprint Sensor Market Intelligence
Embedded software and algorithm licensing for authentication accuracy is restructuring the value proposition beyond the physical hardware. Qualcomm Technologies, Inc. leverages its expertise in ultrasonic technology to capture the premium smartphone segment. Shenzhen Goodix Technology Co., Ltd. dominates the high-volume optical sensor space for Android devices in Asia. Synaptics Incorporated competes with a broad portfolio spanning capacitive and optical solutions for multiple end-user applications.
A fingerprint sensor is a biometric device that captures and analyzes the unique epidermal ridge patterns on a person's finger. These sensors convert the physical pattern into a digital signal using methods like capacitance changes or optical imaging at resolutions often exceeding 500 ppi. Capacitive sensors remain the standard for cost-sensitive mobile devices, while ultrasonic sensors represent the fastest-growing product type in premium segments. Within applications, access control and banking terminals offer higher margins compared to the high-volume consumer electronics space.
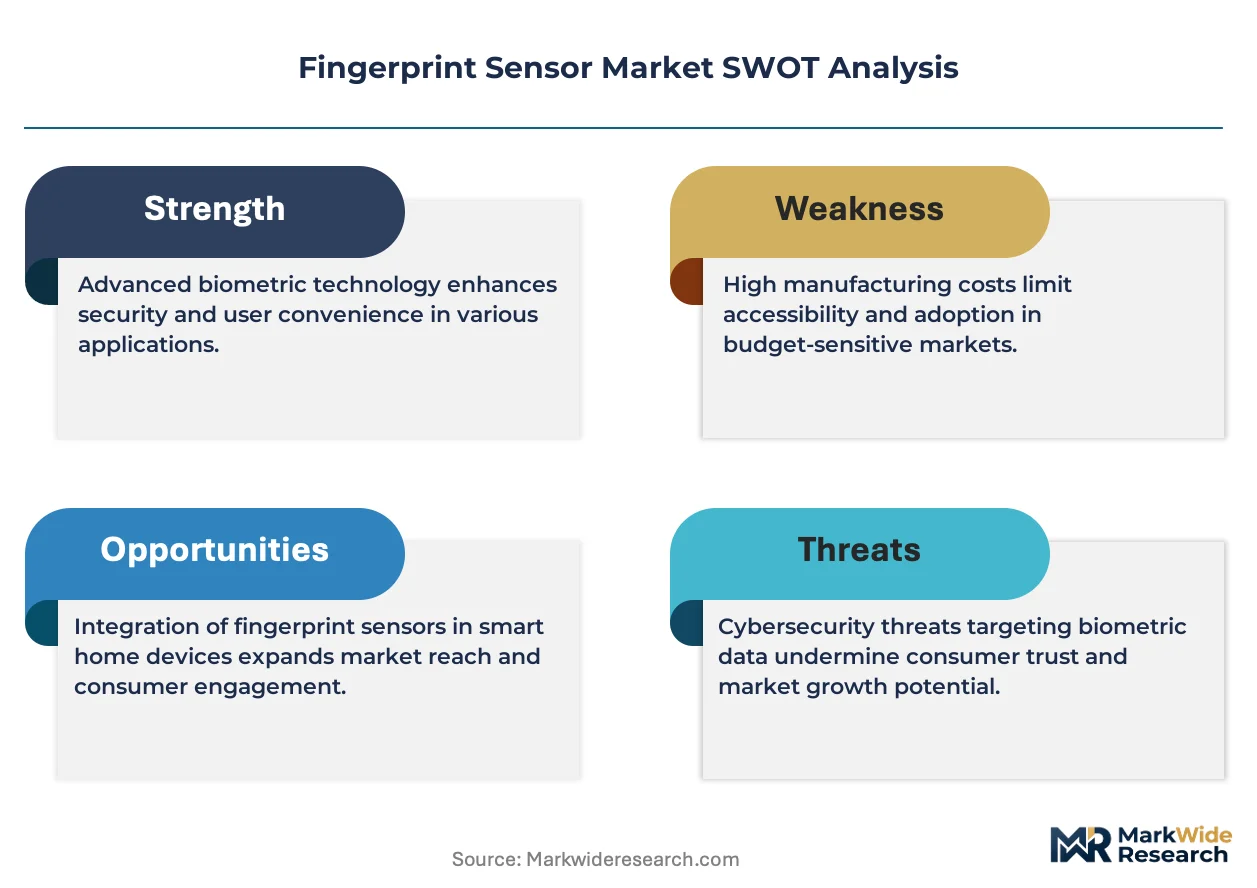
Data privacy regulations, including Europe's GDPR and China's GB standards, dictate how biometric data is stored and processed, influencing sensor software architecture. Concurrently, standards from organizations like the FIDO Alliance shape interoperability and security protocols for authentication across devices and platforms. Vendor differentiation will increasingly depend on the ability to integrate multi-modal biometrics while managing rising manufacturing costs and complex data security requirements.
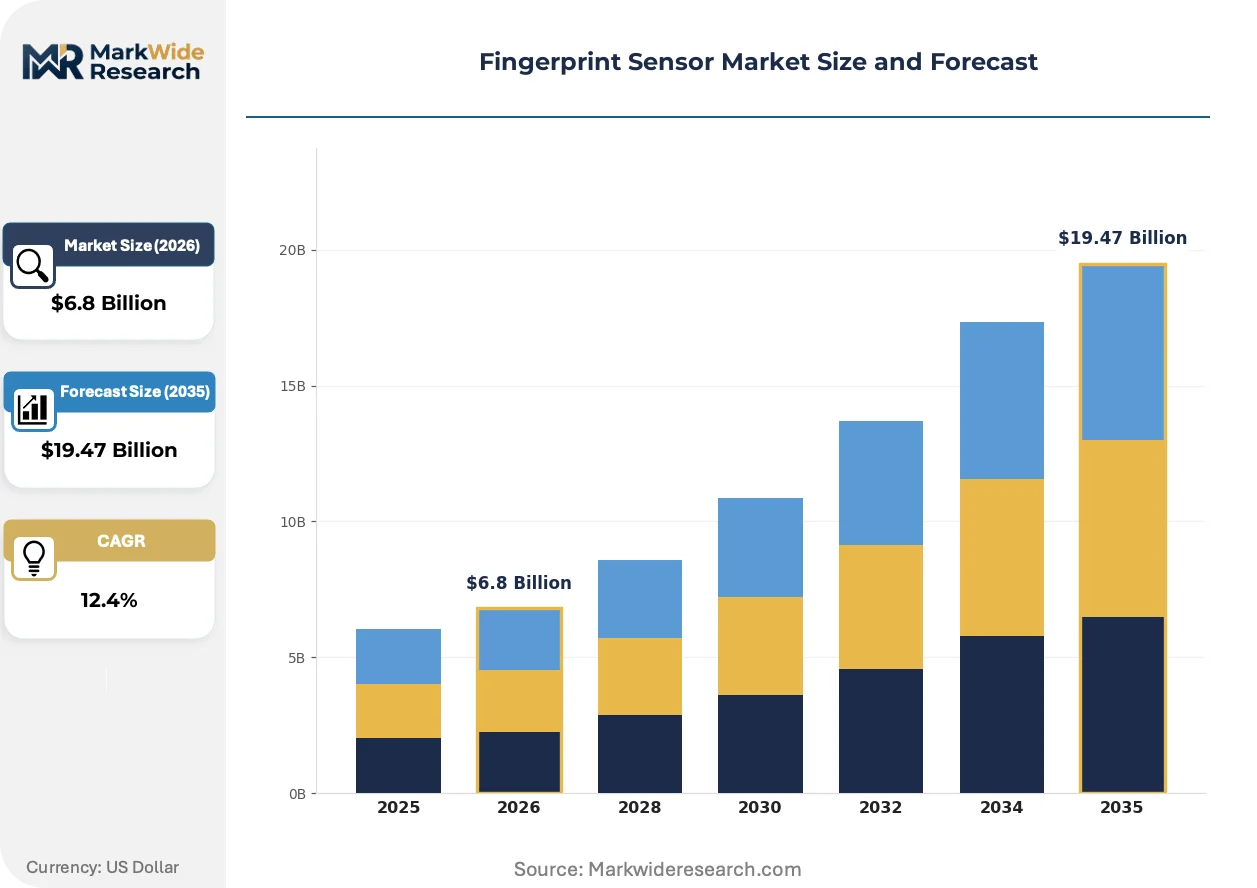
Market Dynamics
The fundamental value proposition in the fingerprint sensor market is shifting from physical hardware sales to the licensing of sophisticated software and algorithms for authentication. This transition prioritizes accuracy, security, and integration over the sensor component itself.
Growth Catalysts
- Under-Display Technology:The migration towards optical and ultrasonic under-display sensors within the consumer electronics sector, especially for smartphones, is expanding the addressable market for premium components.
- Access Control Systems:Demand from the commercial and residential security sectors for biometric access control is creating high-margin opportunities for durable, high-performance capacitive and optical sensors.
- FIDO Alliance Standards:Interoperability frameworks from organizations like the FIDO Alliance are simplifying integration, encouraging wider adoption of fingerprint authentication across web services and enterprise platforms.
Market Restraints
- Manufacturing Costs:The high capital expenditure and complex fabrication processes associated with advanced ultrasonic sensors limit their application in cost-sensitive devices, constraining volume growth.
- Supply Chain Concentration:A high dependency on semiconductor fabrication facilities located in China and South Korea creates significant geopolitical and logistical risks for the global supply chain.
- Technical Performance Limitations:Under-display sensors can exhibit reduced accuracy and speed when used with third-party screen protectors, leading to a negative end-user experience and potential product returns.
Strategic Opportunities
- Automotive Integration:The automotive sector presents a significant opportunity for integrating fingerprint sensors for driver identification, vehicle startup, and personalization of in-cabin settings.
- Emerging Economies:Expanding biometric banking and government ID programs in countries like India and Brazil creates large-scale deployment opportunities for cost-effective and reliable sensor technologies.
- Multi-Modal Biometrics:The convergence of fingerprint biometrics with facial, voice, or iris recognition offers a path to developing highly secure, layered authentication solutions for enterprise and financial applications.
Industry Challenges
- Intellectual Property Complexity:A dense and litigious patent landscape, particularly surrounding ultrasonic and optical under-display technologies, creates significant legal and licensing hurdles for new market entrants.
- Data Regulation Divergence:Sensor and software developers must navigate a complex web of differing data privacy laws, such as Europe's GDPR and China's GB standards, increasing design and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fingerprint Sensor Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $19.47 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical, Capacitive, Ultrasonic, Thermal, Piezoelectric Technology: Swipe, Area, Mass Storage, Multispectral Imaging, CMOS Application: Mobile Devices, Access Control, Time & Attendance, Banking Terminals, Smart Cards End User: Consumer Electronics, Government Agencies, Financial Institutions, Enterprise, Educational Institutions |
| Companies Covered | Egis Technology Inc., IDEX Biometrics ASA, Shenzhen Goodix Technology Co., Ltd., Suprema Inc., NEXT Biometrics Group ASA, Synaptics Incorporated, Qualcomm Technologies, Inc., CrucialTec, Fingerprint Cards AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fingerprint Sensor Market Strategic Shifts & Innovations
The market is defined by a technological push towards seamless aesthetic integration without compromising security. This forces innovation in sensor materials, software algorithms, and data processing architectures to meet evolving device design and regulatory requirements.
Ultrasonic sensors function by transmitting sound waves to map the 3D ridges and valleys of a fingerprint. The premium smartphone segment is rapidly adopting this technology for its security advantages. This evolution is automating secure authentication through solid materials like glass, enabling novel industrial designs previously impossible with capacitive sensors.
Europe's General Data Protection Regulation (GDPR) establishes strict rules for handling personal biometric data. This regulation compels manufacturers to design systems that process and store fingerprint templates locally on a device's secure enclave. The consumer electronics segment is most affected, re-architecting both software and hardware to ensure compliance.
End-users in high-security verticals are moving beyond single-factor authentication, demanding multi-modal systems. This shift disrupts the standalone sensor market, compelling vendors to provide solutions that integrate fingerprint data with biometrics like facial recognition. This pattern is most pronounced in the banking and government sectors for identity verification.
Fingerprint Sensor Market Segmentation
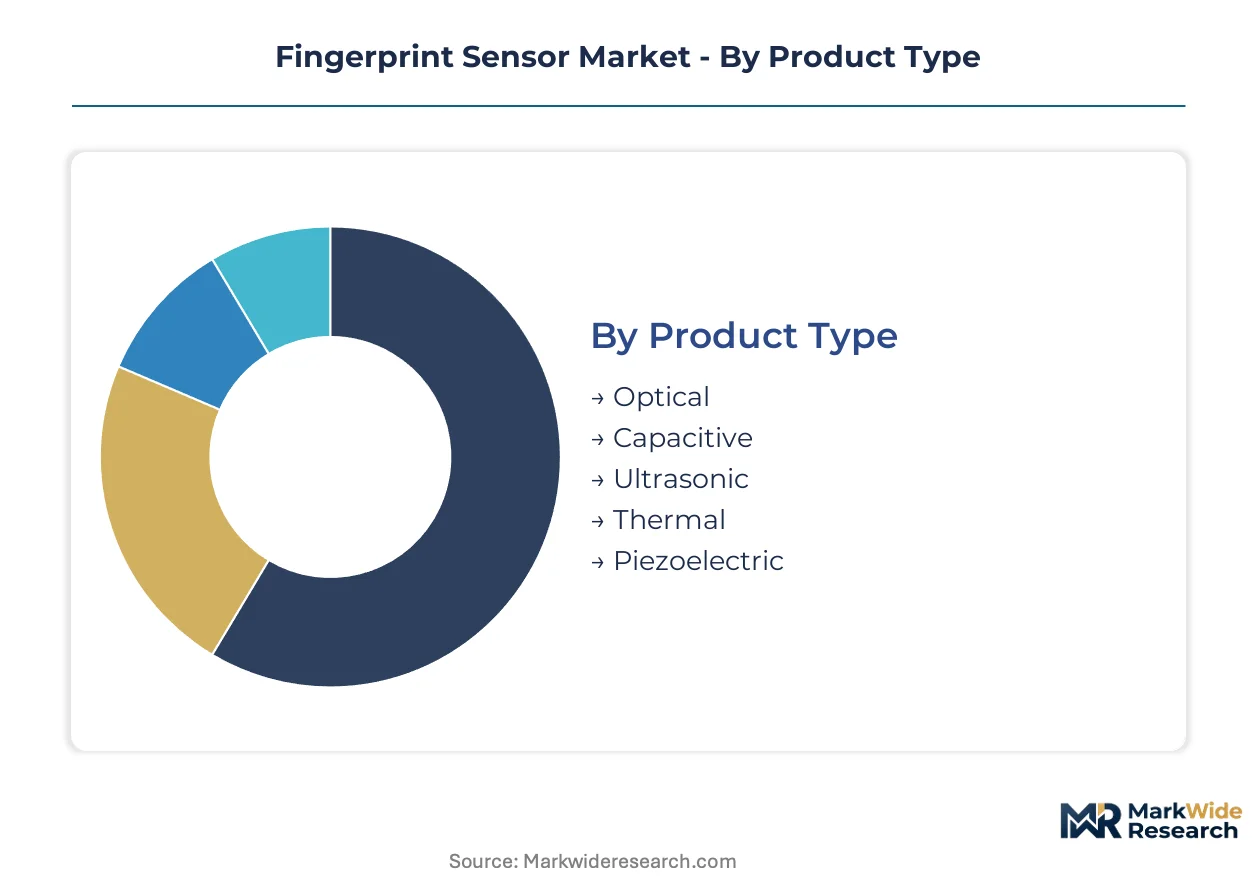
The fingerprint sensor market segments across diverse product types, technologies, applications, and end-user groups. Understanding these divisions reveals the specific growth drivers and regulatory pressures influencing each sub-market. This granular view highlights where innovation and investment are most concentrated.
Product Type:
Compliance with various international standards, such as Europe's CE marking and China's GB standards, dictates design and performance requirements across different sensor product types.
- Ultrasonic:This technology transmits sound waves to map the 3D ridges and valleys of a fingerprint, offering high security. Demand in premium smartphones is driven by seamless under-display integration and enhanced spoofing resistance.
- Capacitive:These sensors detect variations in electrical charge caused by ridge-valley patterns on the finger. Cost-sensitive mobile devices and access control systems in India widely use this mature technology due to its affordability.
- Optical:This type captures a 2D image of the fingerprint using light. High-volume Android devices in Asia frequently integrate this sensor type for basic authentication.
- Thermal:Thermal sensors measure temperature differences between ridges and valleys. This niche technology finds use in specific industrial applications requiring robust performance in challenging environments.
- Piezoelectric:Piezoelectric sensors generate an electrical signal from pressure applied by the finger. These sensors are less common, often appearing in specialized, low-power biometric solutions.
Leading the category by volume: Capacitive. Growing fastest: Ultrasonic.
Technology:
The choice of fingerprint sensor technology often reflects a balance between authentication speed, security level, and overall system cost, influencing adoption across various price tiers.
- Area:This technology captures the entire fingerprint in a single touch, providing quick and user-friendly authentication. Consumer electronics, particularly smartphones, widely deploy area sensors for convenience and speed.
- Multispectral Imaging:Multispectral imaging uses multiple light wavelengths to capture surface and subsurface fingerprint data. High-security applications in financial institutions and government agencies leverage this for enhanced liveness detection.
- Swipe:Swipe technology requires the user to move their finger across a small sensor. This compact and low-cost technology is found in older mobile devices and some embedded systems.
- Mass Storage:This refers to the storage capabilities for numerous fingerprint templates. This feature is critical for access control systems managing a large user base in enterprise environments.
- CMOS:Complementary Metal-Oxide-Semiconductor technology forms the basis for many optical and capacitive sensors. It enables compact, low-power image capture in mobile devices.
The dominant technology for high-volume applications is Area, while Multispectral Imaging offers advanced security features.
Application:
The sheer volume requirements of certain applications, especially in consumer electronics, drive sensor design towards miniaturization and cost efficiency, while others prioritize robust security.
- Mobile Devices:This application integrates fingerprint sensors for user authentication, device unlock, and mobile payments. This segment represents the largest volume market, demanding compact, low-power solutions for smartphones.
- Access Control:Access control utilizes biometrics to restrict entry to physical locations or systems. Commercial and residential security sectors globally adopt these systems for enhanced security over traditional keys.
- Time & Attendance:This application deploys fingerprint sensors for accurate employee clock-in and clock-out verification. Enterprise and manufacturing sectors use these systems to improve workforce management.
- Banking Terminals:Banking terminals incorporate fingerprint authentication for secure transactions and user identification. These terminals offer higher margins due to stringent security and reliability requirements.
- Smart Cards:This emerging application embeds tiny fingerprint sensors directly into payment or identification cards. Smart cards provide enhanced security for financial transactions and personal identity verification.
This segment is characterized by the high-volume demand from Mobile Devices, with Banking Terminals presenting significant margin opportunities.
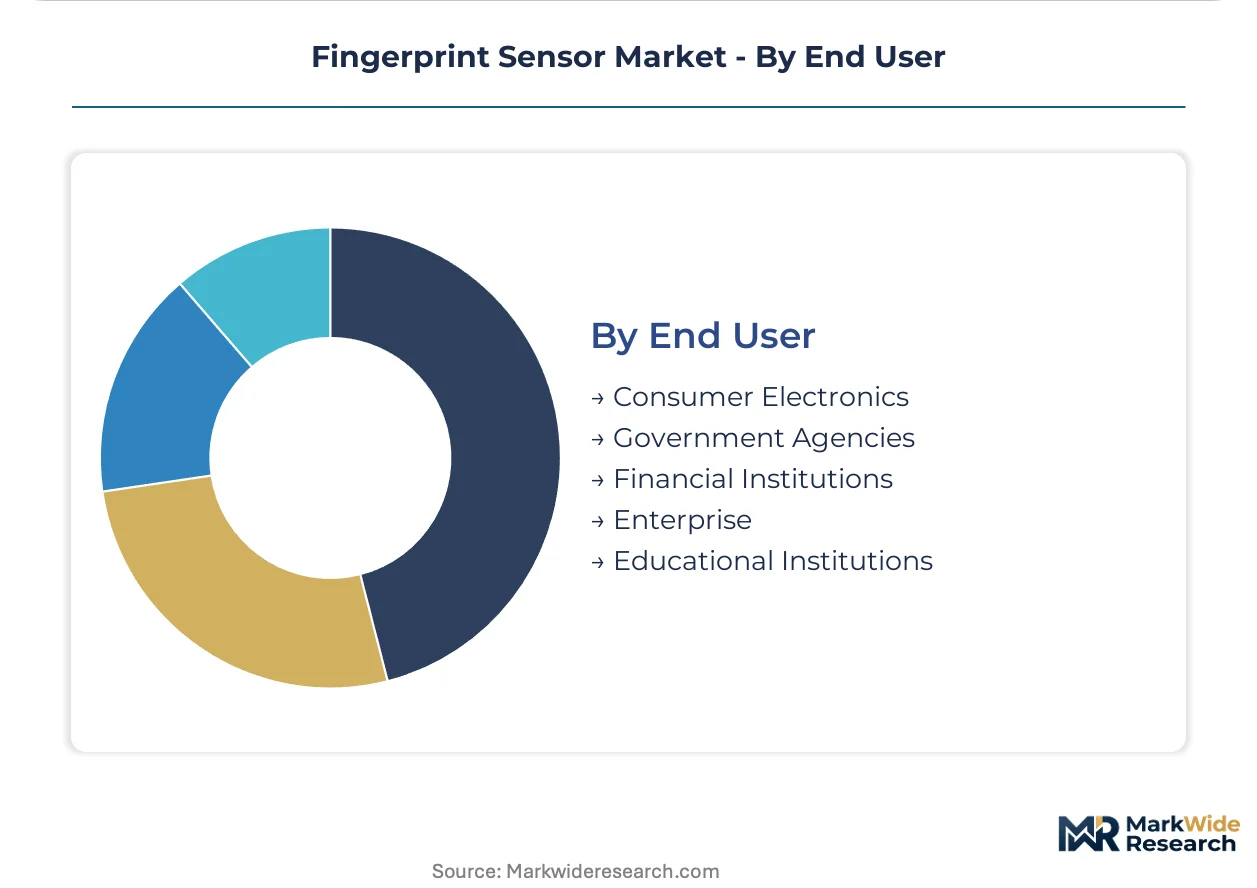
End User:
Different end-user segments exhibit unique procurement patterns and security mandates, influencing the functional specifications and integration requirements for fingerprint sensor solutions.
- Consumer Electronics:Primarily mobile devices, tablets, and laptops, where fingerprint sensors enable secure login and payment. This segment drives innovation in under-display and cost-effective sensor solutions.
- Financial Institutions:Banks and credit unions employ fingerprint biometrics for secure transactions, account access, and fraud prevention. They prioritize robust security and compliance with regulations like GDPR for biometric data.
- Government Agencies:Government agencies utilize fingerprint sensors for national ID programs, border control, and secure access to sensitive data. These applications demand high accuracy and reliability.
- Enterprise:Businesses use fingerprint authentication for employee access to networks, facilities, and time tracking. Cost-effectiveness and ease of integration are key considerations for this sector.
- Educational Institutions:Educational institutions deploy fingerprint biometrics for student attendance, library access, and secure exam authentication. This segment values simplicity and efficient user management.
Consumer Electronics drives the largest volume demand, while Financial Institutions command premium solutions due to stringent security needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fingerprint sensor market exhibits a clear division between concentrated manufacturing hubs and diverse consumption centers. Production of advanced sensor components is highly centralized in East Asia, while demand spans across global consumer electronics, financial services, and government applications. This dynamic shapes regional investment and strategic partnerships.
China
China's vast consumer electronics market drives substantial demand for optical and capacitive fingerprint sensors in mobile devices. GB standards significantly influence local manufacturing processes and data handling protocols for biometric components. Shenzhen serves as a critical hub for high-volume optical sensor production and supply chain integration.
South Korea
South Korea stands as a major manufacturing and innovation center for advanced fingerprint sensor technologies, particularly in the premium smartphone segment. The country's strong intellectual property protection frameworks support the development of cutting-edge ultrasonic sensors. Seoul's tech clusters are central to R&D for under-display biometric solutions.
United States
The United States generates significant demand for high-security fingerprint sensors in financial institutions and government agencies. HIPAA regulations and various federal cybersecurity standards impact the secure processing and storage of biometric data. Silicon Valley companies drive innovation in multi-modal biometrics and software integration.
India
India's expanding biometric banking and government ID programs, such as Aadhaar, create large-scale deployment opportunities for cost-effective capacitive sensors. The BIS (Bureau of Indian Standards) ensures quality and reliability for biometric devices used in public services. Bengaluru's tech ecosystem supports local development of integrated authentication solutions.
Germany
Germany's industrial sector and strong privacy focus generate demand for robust fingerprint sensors in access control systems and automotive applications. GDPR mandates strict data protection for biometric information, influencing sensor design and software architecture. Munich's engineering firms focus on integrating secure biometric solutions into industrial and automotive platforms.
Fingerprint Sensor Market Key Industry Players
Top-tier vendors anchor the premium segment with advanced ultrasonic and optical under-display technologies, while a broader base of manufacturers competes in the high-volume capacitive sensor space. The market structure is tiered, with established players focusing on intellectual property and sophisticated software algorithms. Strategic partnerships for multi-modal biometrics and targeted acquisitions for niche technologies are common competitive moves. Many companies are also expanding their portfolios to address diverse end-user applications beyond consumer electronics.
Within the premium segment for integrated biometric solutions, Qualcomm Technologies, Inc. represents a significant force with its advanced ultrasonic technology. Shenzhen Goodix Technology Co., Ltd., a Chinese entity, exemplifies market leadership in high-volume optical sensors for Android devices across Asia. Synaptics Incorporated, an established player, occupies a position with a broad portfolio spanning various sensor types and end-user applications. These firms collectively demonstrate the industry's focus on both technological specialization and market breadth.
| Leading Market Players |
|---|
| Egis Technology Inc. |
| IDEX Biometrics ASA |
| Shenzhen Goodix Technology Co., Ltd. |
| Suprema Inc. |
| NEXT Biometrics Group ASA |
| Synaptics Incorporated |
| Qualcomm Technologies, Inc. |
| CrucialTec |
| Fingerprint Cards AB |
| Others |
Cost & Logistics Intelligence
Semiconductor fabrication costs for advanced sensor components significantly influence pricing across the fingerprint sensor market, tracing from specialized foundries to premium and cost-sensitive end-user segments.
Pricing Analysis
Cost-down pressure on high-volume capacitive and optical sensors accelerates because of intense competition within the consumer electronics segment. The dominant pricing model is per-unit transactional for hardware, often coupled with licensing fees for embedded software and algorithms. Price differentiation stems from the sensor's security grade, such as FIDO certification, and the brand premium associated with advanced technologies like Qualcomm's ultrasonic solutions. Mobile device manufacturers exhibit the highest price sensitivity, whereas banking terminals and government agencies prioritize performance over cost.
Supply Chain Analysis
Demands for dual-sourcing capacity often arise for critical components, mitigating supply chain risks in the fingerprint sensor market. Geographic supply concentration for advanced sensor manufacturing centers in China and South Korea. Raw material and component dependencies include specialized optical lenses, ultrasonic transducers, and semiconductor wafers. A structural risk exists due to the high dependency on a limited number of fabrication facilities, creating potential single-source vulnerabilities. Distribution runs through direct sales channels to large OEMs and specialized distributors for niche applications like access control systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market for fingerprint sensors is supply-constrained, with high capital expenditure for advanced ultrasonic sensor fabrication facilities propping up premium segment pricing.
For Market Incumbents: Lock in intellectual property through aggressive patenting of under-display and multi-modal biometric technologies. Invest in software and algorithm licensing to capture value beyond physical hardware, countering margin pressure from commodity sensor competition. Form strategic alliances with secure enclave providers to address evolving data privacy regulations like Europe's GDPR. Expand R&D into advanced material science to improve sensor durability and performance in challenging environments.
For New Entrants and Emerging Players: Begin with targeted solutions for underpenetrated segments, such as automotive integration for driver identification or smart cards. Focus on cost-effective capacitive sensors for large-scale government ID programs in emerging economies like India. Develop specialized software for multi-modal biometric integration, offering compliance-as-a-service for complex data privacy requirements. Leverage open standards from the FIDO Alliance to simplify integration and reduce time-to-market for new authentication solutions.
For Investors and Strategic Acquirers: Widespread adoption of FIDO standards is the leading indicator that authentication interoperability is maturing, signaling market readiness for broader biometric integration. Long-term viability remains strong, driven by the persistent need for secure, seamless authentication across diverse applications. Target acquisition archetypes include specialized software companies with robust biometric algorithm portfolios or firms holding critical patents in advanced under-display technologies. Monitor regulatory shifts in data privacy, as compliance frameworks dictate hardware and software design requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Software Licensing Portfolio | Captures value beyond hardware sales and diversifies revenue streams for sensor manufacturers. |
| Invest in Ultrasonic Technology R&D | Enhances security features and enables seamless under-display integration for premium devices. |
| Form Multi-Modal Biometric Partnerships | Addresses demand for layered authentication in high-security applications like banking. |
| Target Emerging Economies for Capacitive Sensors | Unlocks large-scale deployment opportunities in government ID and mobile payment programs. |
| Acquire Niche Algorithm Developers | Strengthens IP position and accelerates development of advanced liveness detection capabilities. |
Research Approach
Multi-period observation of technology adoption rates and regulatory compliance frameworks anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary interviews included mobile device OEMs, biometric solution providers, financial institution security leads, and government ID program managers. Secondary data sources comprised SEC filings of public sensor companies, patent databases, FIDO Alliance publications, and national biometric data regulations. Bottom-up and top-down triangulation validated market size and growth forecasts.
Segment-weighting approaches were applied across product type, technology, application, end-user group, and regional regulatory compliance to construct the forecast framework across the analysis window. Quantitative models derived compound annual growth rates through regression analysis and assessment of market share shifts. Key industry-specific forecast inputs included global smartphone shipment projections and projected access control system deployment rates in commercial and residential sectors.
Underlying measurement precision varies by segment; consumer electronics and mobile devices carry tighter precision than niche industrial applications. Forecasts reflect assumptions regarding technological advancements and market acceptance of new biometric solutions. Deviation in geopolitical stability or data privacy regulation enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Steam Flow Meter Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Machine Control System Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Wind Vane Sensor Market
Sensors and Controls
Depth Sensing Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Photonic Sensors and Detectors Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Tooth Mounted Sensor Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Smart Parking Sensor Market
Sensors and Controls
Global Optogenetics Actuators and Sensors Market