
 Europe Acoustic Sensors Market | 2026-2036
Europe Acoustic Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Acoustic Sensors Market Foresight
Buyer concentration in European automotive tier-one supply chains is rebalancing as electric vehicle platforms fragment orders across multiple sensor vendors. Honeywell International Inc. leverages its aerospace heritage to dominate high-reliability piezoelectric applications. CTS Corporation anchors its position through specialized frequency control manufacturing for industrial monitoring clients. Murata Manufacturing Co. Ltd. competes aggressively on ceramic resonator miniaturization for consumer electronics integrators.
Acoustic sensors convert mechanical vibration or sound pressure into electrical signals through piezoelectric, capacitive, or ultrasonic transduction mechanisms, typically operating across frequency ranges from infrasonic to megahertz scales for precise industrial measurement. Their primary commercial purpose spans process control, structural health monitoring, and human-machine interface detection in noise-critical environments. Piezoelectric technology leads European value capture due to mature ceramic supply chains and established calibration protocols. Ultrasonic segments register the fastest structural expansion as non-destructive testing mandates spread through German and French manufacturing inspection regimes. Environmental sensing applications concentrate margin pools where regulatory compliance drives premium pricing for certified measurement accuracy.
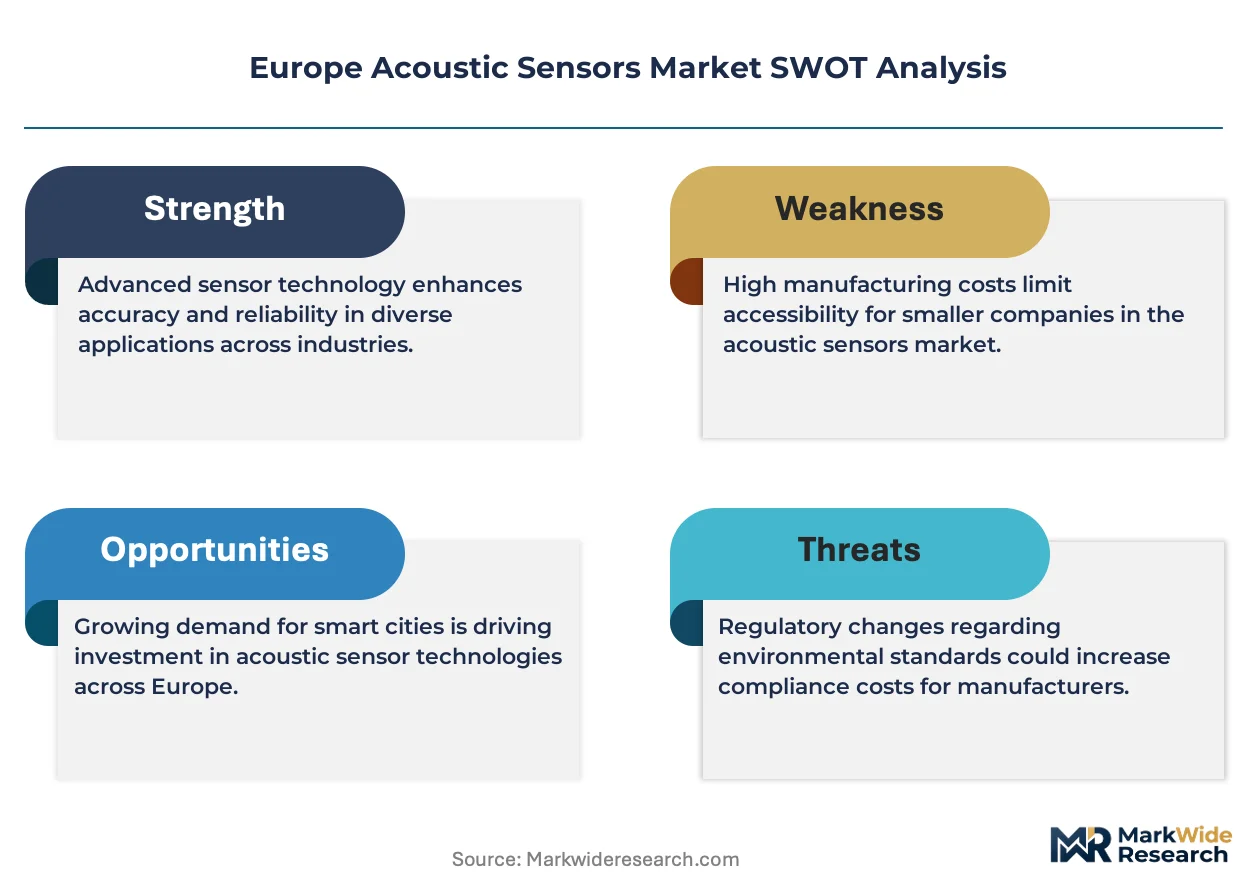
REACH and the EU Green Deal shape material selection across the European acoustic sensor value chain, restricting lead-based piezoelectric formulations and accelerating bio-ceramic substrate development. ECHA substance evaluations and CE marking requirements under the Machinery Directive tighten performance validation for industrial monitoring deployments. Germany's KBA influences automotive safety sensor specifications through type-approval protocols that cascade to tier-two component suppliers. Stakeholders must monitor evolving F-Gas Regulation implications for ultrasonic sensor cooling systems and position procurement strategies around emerging MDR-aligned healthcare acoustic diagnostics requirements.
Market Dynamics
REACH substance restrictions and the EU Green Deal are forcing rapid reformulation of piezoelectric substrates across European acoustic sensor supply chains, compressing lead-based ceramic timelines while bio-ceramic alternatives scale through German and French manufacturing corridors.
Growth Catalysts
- Automotive safety mandates:Germany's KBA type-approval protocols cascade through tier-one supply chains, mandating acoustic sensors for pedestrian detection and cabin monitoring in electric vehicle platforms.
- REACH compliance acceleration:ECHA evaluations of lead-based piezoelectric materials are compressing substitution timelines, creating certified demand for bio-ceramic formulations in precision instrumentation.
- Non-destructive testing expansion:French and German manufacturing inspection regimes are embedding ultrasonic sensors into quality assurance workflows for aerospace and heavy machinery components.
Market Restraints
- Piezoelectric ceramic supply concentration:Specialty substrate production clusters in southern Germany and northern Italy, creating geographic vulnerability for frequency-control component sourcing.
- F-Gas Regulation cooling constraints:Ultrasonic sensor thermal management systems face refrigerant phase-out timelines that compress engineering redesign cycles.
- Optical sensing substitution:Fiber-optic vibration monitoring is displacing acoustic sensors in high-temperature industrial environments where electromagnetic interference resistance is critical.
Strategic Opportunities
- MDR-aligned healthcare diagnostics:The EU Medical Device Regulation creates certified pathways for acoustic sensors in ultrasound imaging and point-of-care diagnostics.
- CSRD reporting integration:Corporate sustainability disclosure requirements are opening demand for environmental acoustic monitoring in industrial compliance applications.
- MEMS-acoustic convergence:Micro-electromechanical systems are merging with traditional piezoelectric architectures for miniaturized consumer and automotive deployments.
Industry Challenges
- Calibration technician scarcity:Precision frequency-control manufacturing requires specialized metrology expertise that concentrates in aging workforce pools across Germany's industrial belt.
- CE marking timeline compression:Machinery Directive conformity assessments for industrial monitoring deployments are extending certification cycles as notified body capacity tightens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Acoustic Sensors Market |
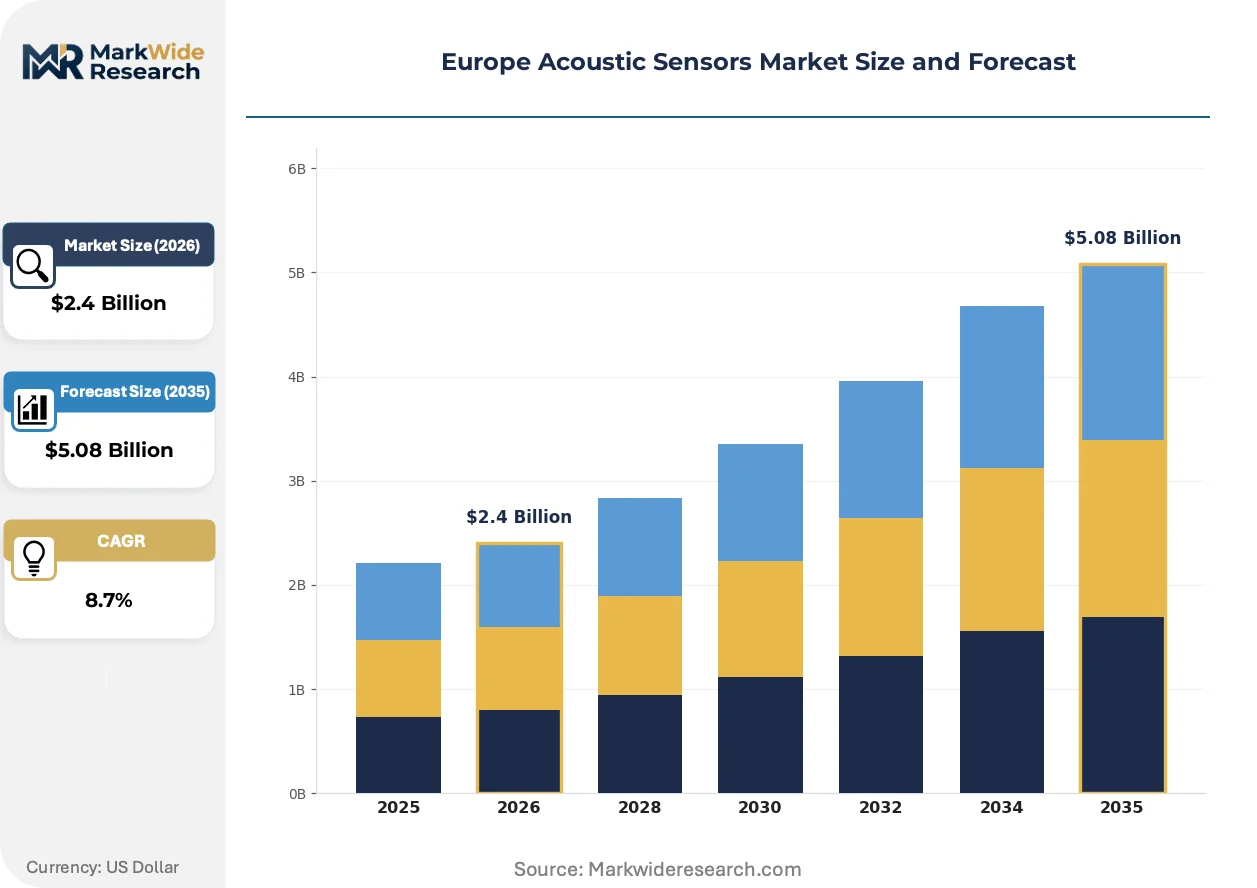
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.08 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microphone, Ultrasonic, Piezoelectric, Capacitive Application: Industrial Monitoring, Consumer Electronics, Automotive Safety, Environmental Sensing End User: Manufacturing, Home Automation, Healthcare, Defense Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Epcos, CTS Corporation, Honeywell International Inc., API Technologies Corp., Kyocera, Murata Manufacturing Co. Ltd., Teledyne Microwave Solutions, Ceramtec, Panasonic Corp., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Acoustic Sensors Market Shifts & Advancements
Bio-ceramic substrate development, regulatory material phase-outs, and procurement model fragmentation are restructuring how acoustic sensor value is captured across European manufacturing and healthcare verticals.
Piezoelectric materials are converging with bio-ceramic formulations as REACH restrictions eliminate lead-based substrates. German ceramic suppliers are accelerating barium titanate and potassium sodium niobate production lines to serve automotive and industrial clients. This convergence is compressing traditional supply relationships as material certification becomes the primary vendor selection filter.
The EU F-Gas Regulation is mandating refrigerant transitions in ultrasonic sensor cooling systems, forcing thermal engineering redesigns across German and French non-destructive testing equipment manufacturers. Industrial inspection OEMs are responding by consolidating supplier relationships with component vendors holding early refrigerant-transition certifications.
Automotive tier-one buyers are fragmenting sensor procurement across multiple vendors as electric vehicle platforms diversify. German and French EV manufacturers are unbundling long-term single-source contracts in favor of dual-qualified suppliers for acoustic safety systems. This pattern is most visible in Stuttgart and Munich manufacturing corridors where platform fragmentation has accelerated vendor qualification timelines.
Europe Acoustic Sensors Market Segmentation
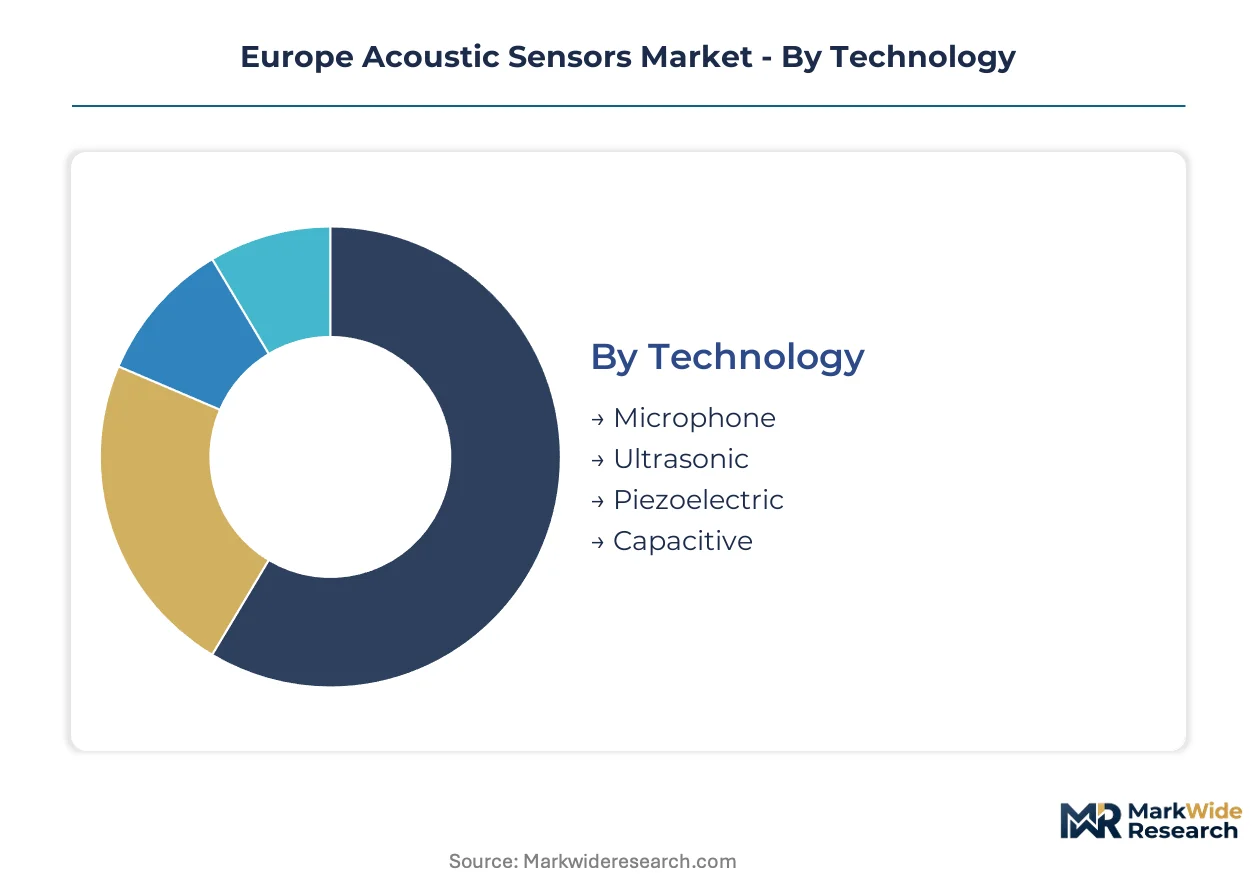
Acoustic sensor segmentation in Europe reflects divergent engineering requirements across automotive safety mandates, REACH-compliant material transitions, and precision instrumentation clusters. Technology choices determine substrate chemistry and calibration protocols, while application verticals dictate frequency range specifications and certification pathways.
Technology:
Standardization dominates microphone and capacitive architectures, whereas piezoelectric and ultrasonic platforms require extensive customization for substrate compliance and thermal management.
- Piezoelectric:Ceramic substrates convert mechanical stress into electrical signals through barium titanate or potassium sodium niobate formulations. German automotive tier-ones and Italian precision instrument manufacturers anchor demand as REACH substance restrictions compress lead-based ceramic timelines.
- Ultrasonic:Transducers operate above human hearing range for non-destructive testing and proximity sensing. French aerospace inspection regimes and German heavy machinery quality assurance workflows are embedding these sensors as F-Gas Regulation mandates force refrigerant transitions in cooling systems.
- Microphone:Capacitive and MEMS architectures capture audible frequency ranges for voice interfaces and noise monitoring. Consumer electronics integrators in Stuttgart and Munich manufacturing corridors drive procurement fragmentation across multiple qualified vendors.
- Capacitive:Electrostatic transduction enables miniaturized surface-mount packages for portable devices. Home automation and wearable applications concentrate volume in low-cost, high-volume production runs.
Leading the category by volume: Piezoelectric. Expanding most quickly: Ultrasonic.
Application:
Cost tiers separate mission-critical automotive safety systems from commoditized consumer electronics, with industrial monitoring occupying the premium middle ground.
- Automotive Safety:Pedestrian detection, cabin monitoring, and emergency call systems require KBA type-approval compliance. German EV platforms are fragmenting procurement across dual-qualified suppliers as long-term single-source contracts dissolve.
- Industrial Monitoring:Vibration analysis, predictive maintenance, and process control demand certified measurement accuracy. German industrial automation belts and French manufacturing corridors concentrate margin pools where regulatory compliance drives premium pricing.
- Environmental Sensing:Noise pollution monitoring and acoustic emission detection serve CSRD reporting requirements. Industrial compliance applications in the EU Green Deal framework open certified pathways for precision instrumentation.
- Consumer Electronics:Voice-activated interfaces and audio capture functions compete on ceramic resonator miniaturization. Italian and German consumer electronics integrators prioritize cost-optimized MEMS-acoustic convergence designs.
Highest margin concentration: Industrial Monitoring. Steepest volume expansion: Automotive Safety.
End User:
Customer type determines procurement complexity, with defense and healthcare requiring extended certification cycles versus manufacturing's volume-driven standardization.
- Manufacturing:Predictive maintenance and quality assurance workflows embed acoustic sensors across German automotive and French aerospace production lines. ECHA substance evaluations and CE marking requirements under the Machinery Directive tighten performance validation.
- Healthcare:Ultrasound imaging and point-of-care diagnostics demand MDR-aligned certification pathways. Bio-ceramic substrate development accelerates as medical device manufacturers position for emerging acoustic diagnostics requirements.
- Defense:Secure communications and perimeter monitoring applications require high-reliability specifications with extended environmental testing protocols.
- Home Automation:Smart speakers and security systems drive cost-sensitive demand for miniaturized microphone arrays with cloud-connected voice processing.
Dominant procurement volume: Manufacturing. Gaining share fastest: Healthcare.
Distribution Channel:
Supply concentration in southern Germany and northern Italy shapes channel preferences, with direct relationships dominating high-specification segments.
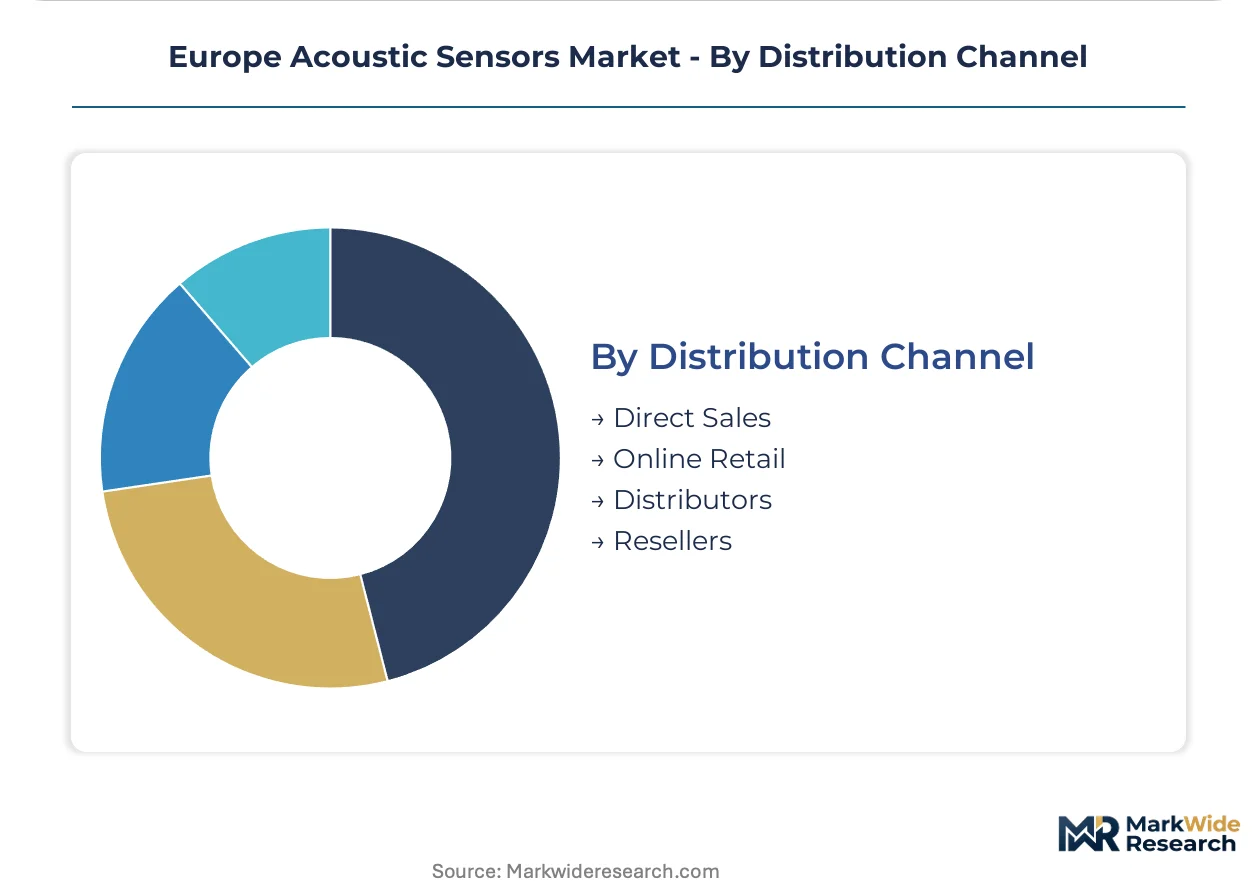
- Direct Sales:Automotive tier-ones and industrial OEMs negotiate multi-year supply agreements with certified substrate vendors. German manufacturing corridors consolidate procurement through established relationships with piezoelectric ceramic specialists.
- Distributors:Broad-line electronics distributors serve mid-volume industrial and healthcare clients requiring technical support and local inventory.
- Online Retail:E-commerce platforms capture prototype and replacement demand from smaller integrators and research institutions.
- Resellers:Value-added resellers bundle acoustic sensors with integration services for home automation and specialized industrial applications.
Primary revenue channel: Direct Sales. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive safety mandates and REACH compliance are concentrating acoustic sensor demand across German manufacturing corridors and Italian precision clusters. Electric vehicle platforms in Stuttgart and Munich are fragmenting procurement patterns while bio-ceramic substrate development accelerates through French and German ceramic suppliers.
Germany
KBA type-approval protocols for pedestrian detection systems are cascading through tier-one automotive supply chains. REACH substance evaluations under ECHA are compressing lead-based piezoelectric substitution timelines. Stuttgart and Munich manufacturing corridors witness accelerated vendor qualification as EV platforms diversify sensor sourcing.
France
Aerospace inspection regimes are embedding ultrasonic sensors into quality assurance workflows for heavy machinery components. F-Gas Regulation mandates are forcing refrigerant transitions in ultrasonic sensor cooling systems. Toulouse and Paris industrial clusters concentrate non-destructive testing equipment manufacturing.
Italy
Precision instrumentation manufacturers are anchoring demand for certified bio-ceramic formulations in frequency-control applications. CE marking requirements under the Machinery Directive tighten performance validation for industrial monitoring deployments. Northern Italian ceramic production clusters face geographic vulnerability in specialty substrate sourcing.
United Kingdom
Healthcare acoustic diagnostics are positioning for MDR-aligned certification pathways under post-Brexit regulatory alignment. CSRD reporting requirements are opening demand for environmental acoustic monitoring in industrial compliance applications. Southeast England research institutions drive prototype procurement through online retail channels.
Switzerland
Swissmedic oversight of medical device quality systems shapes acoustic sensor specifications for ultrasound imaging applications. High-reliability defense and secure communications requirements concentrate in precision manufacturing clusters. Basel and Zurich industrial belts specialize in metrology expertise for frequency-control calibration.
Europe Acoustic Sensors Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue MEMS-acoustic convergence and bio-ceramic material certification. The vendor base stratifies across aerospace heritage specialists, ceramic substrate fabricators, and frequency-control manufacturers. Three archetypes dominate: high-reliability defense-aerospace suppliers, REACH-compliant ceramic specialists, and miniaturization-focused consumer electronics integrators. Competitive moves concentrate on dual-qualification for automotive tier-one procurement and early refrigerant-transition certifications for ultrasonic thermal management.
Within the high-reliability tier, Honeywell International Inc. and Teledyne Microwave Solutions exemplify aerospace heritage positioning. CTS Corporation occupies a position among frequency-control specialists serving industrial monitoring clients. Murata Manufacturing Co. Ltd. sits within the miniaturization-focused archetype for consumer electronics integration. These three anchors represent divergent competitive vectors: defense-aerospace certification depth, industrial calibration protocols, and ceramic resonator scale economies.
| Leading Market Players |
|---|
| Epcos |
| CTS Corporation |
| Honeywell International Inc. |
| API Technologies Corp. |
| Kyocera |
| Murata Manufacturing Co. Ltd. |
| Teledyne Microwave Solutions |
| Ceramtec |
| Panasonic Corp. |
| Others |
Supply & Pricing Matrix
Bio-ceramic substrate development across German and French manufacturing corridors is compressing lead-based piezoelectric timelines while simultaneously fragmenting procurement economics and concentrating supply relationships around certified material vendors. REACH substance restrictions under ECHA are forcing simultaneous cost restructuring in substrate chemistry and vendor qualification protocols.
Pricing Analysis
Volume concentrates in commoditized microphone and capacitive architectures while margins pool in piezoelectric and ultrasonic platforms requiring REACH-compliant certification. Three-tier pricing structure separates premium bio-ceramic formulations from standard lead-free substrates and economy-grade imports. Cost compression in standard-tier sensors is intensifying as automotive tier-ones fragment procurement across dual-qualified vendors. Consumer electronics integrators exhibit highest price sensitivity; healthcare and defense buyers prioritize certified accuracy over unit cost.
Supply Chain Analysis
Calibration technician scarcity across Germany's industrial automation belt is constraining frequency-control manufacturing capacity and extending lead times for precision instrumentation clients. Specialty ceramic substrate production clusters in southern Germany and northern Italy, with barium titanate and potassium sodium niobate feedstock drawing from Spanish and Portuguese mineral processors. Single-source vulnerability concentrates in lead-free piezoelectric formulations where ECHA certification creates vendor lock-in. Distribution runs through direct sales relationships with automotive tier-ones and industrial OEMs, supplemented by broad-line electronics distributors for mid-volume healthcare and research clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's acoustic sensor market is becoming a vertical-integration race as players pursue backward control over bio-ceramic substrate supply to secure REACH-compliant material streams and compress certification timelines.
For Market Incumbents: Acquire specialized ceramic substrate fabricators in Germany and northern Italy to secure lead-free piezoelectric supply chains before ECHA substitution deadlines. Build captive barium titanate processing capacity to defend margin position against emerging bio-ceramic specialists. Optical sensing substitution in high-temperature industrial environments threatens acoustic sensor incumbents; counter by deepening calibration service bundling and predictive maintenance software integration.
For New Entrants and Emerging Players: MEMS-acoustic convergence technology offers a technology-first wedge into Stuttgart and Munich consumer electronics corridors where procurement fragmentation creates vendor entry points. Target MDR-aligned healthcare diagnostics in the United Kingdom and Switzerland where regulatory alignment delays have compressed incumbent response timelines. Pursue white-label partnerships with French non-destructive testing equipment OEMs seeking early refrigerant-transition certifications under F-Gas Regulation mandates.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap ceramic specialists holding ECHA-certified bio-ceramic formulations and established relationships with German automotive tier-ones. Long-term viability hinges on positioning ahead of REACH substance restriction enforcement waves and F-Gas refrigerant phase-out timelines. Watch for inflection in KBA type-approval protocol revisions that cascade procurement qualification requirements through tier-two component suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Ceramic Substrates | Captures REACH-compliant supply security and compresses ECHA certification timelines for automotive clients. |
| Dual-Qualification for Automotive Tier-Ones | Aligns procurement fragmentation in Stuttgart and Munich EV manufacturing corridors. |
| Early Refrigerant-Transition Certification | Secures supplier status with French and German non-destructive testing equipment OEMs under F-Gas Regulation. |
| MDR-Aligned Healthcare Diagnostics Development | Opens certified pathways in ultrasound imaging and point-of-care applications across EU member states. |
| MEMS-Acoustic Convergence R&D Investment | Targets miniaturized consumer and automotive deployments in fragmented procurement environments. |
Research Methodology
Trade association filings, ECHA substance evaluation databases, and KBA type-approval registries formed the secondary backbone, supplemented by customs records for ceramic substrate import flows and machinery directive conformity assessment notices. Primary interviews with piezoelectric ceramic specialists, automotive tier-one procurement directors, industrial monitoring OEM technical leads, and precision instrumentation calibration technicians validated demand assumptions and substitution timeline estimates. Bottom-up sensor shipment analysis across technology and application segments triangulated against top-down manufacturing value-add estimates.
Historical trendline analysis of piezoelectric ceramic production volumes, REACH compliance adoption curves, and automotive safety system content per vehicle informed the projection framework. Segmentation modeling spanned technology type, application vertical, end-user industry, and geographic manufacturing cluster. CAGRs were derived from regression analysis of segment-specific growth drivers across the projection horizon, incorporating ECHA regulatory phase-out schedules and KBA mandate implementation timelines as exogenous constraints.
Several conditions sit outside the modeled scope, including unforeseen ECHA substance list expansions, abrupt F-Gas Regulation enforcement acceleration, and trade policy disruptions affecting ceramic mineral feedstock flows. Forecasts reflect assumptions around regulatory implementation pacing and automotive platform standardization decisions. Material deviation in REACH substitution deadlines, KBA protocol revisions, or bio-ceramic yield rates warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Body Worn Antenna Market
Sensors and Controls
Europe Digital Thermometer Market
Sensors and Controls
Automotive Image Sensors Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
Digital Temperature Gauge Market
Sensors and Controls
Nanopositioning Piezo Actuator Market
Sensors and Controls
Global Ultra Low Power MEMS Sensors Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Portable Air Purifier Market