
 Millimeter Wave Sensors Market | 2026-2036
Millimeter Wave Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Millimeter Wave Sensors Market Foresight
The gap between premium phased-array modules and commodity frequency-modulated continuous-wave chips is consolidating around foundry access and packaging complexity. Texas Instruments leverages its integrated RF-CMOS platform to dominate cost-sensitive automotive radar slots. Infineon Technologies anchors high-reliability industrial sensing through silicon-germanium BiCMOS processes. NXP Semiconductors competes across both tiers by controlling gallium-nitride supply partnerships for defense-grade applications.
Millimeter wave sensors detect electromagnetic radiation in the 30–300 GHz range, using antenna arrays and heterodyne receivers to resolve range, velocity, and angular position with centimeter-scale precision. These devices enable non-contact measurement in environments where optical or infrared systems fail due to fog, dust, or material opacity. Active sensor architectures lead volume shipments in automotive radar, where transmit-receive modules penetrate bumper fascias at 77–81 GHz. Imaging sensors capture the fastest expansion in security screening, driven by airport checkpoint modernization and privacy-preserving body scanners. Hybrid sensor designs concentrate margin pools in defense telecommunications, where multimode operation justifies premium pricing against single-function alternatives.
FCC Part 15 rules govern unlicensed millimeter wave emissions in the United States, while ETSI EN 302 567 harmonizes short-range device parameters across European member states. ETSI mandates are forcing module redesigns for cross-border equipment compliance, particularly in automotive radar and telecommunication backhaul. Stakeholders must monitor spectrum auction outcomes and antenna efficiency thresholds as these determine which packaged solutions qualify for volume deployment.
Market Dynamics
Automotive radar standardization at 77–81 GHz is compressing module architectures toward single-chip integration, forcing foundry capacity reallocation from defense-grade gallium nitride toward silicon-based RF-CMOS platforms.
Growth Catalysts
- FCC Part 15 unlicensed spectrum expansion:The United States regulator opened 60 GHz and 77–81 GHz bands for short-range vehicular sensing, triggering Tier-1 supplier qualification cycles for bumper-integrated modules.
- Silicon-germanium BiCMOS process maturation:Foundry yields at 130 nm and 90 nm nodes now support automotive temperature grades, collapsing cost curves for frequency-modulated continuous-wave chipsets.
- Airport checkpoint modernization mandates:Transportation Security Administration procurement specifications for privacy-preserving body scanners are displacing legacy X-ray backscatter systems in United States federal facilities.
Market Restraints
- Packaging complexity for phased-array modules:Antenna-in-package designs require low-loss substrate materials and thermo-compression bonding, limiting qualified suppliers to three specialized assembly houses in Taiwan and South Korea.
- ETSI EN 302 567 cross-border friction:European harmonized standards mandate stricter spurious emission limits than FCC rules, forcing dual-sku inventory for equipment serving both regulatory domains.
- Optical lidar substitution in premium autonomy:1550 nm fiber-laser systems achieve comparable range resolution in clear weather, capturing specification slots in robotaxi programs above SAE Level 3.
Strategic Opportunities
- Industrial sensing in German manufacturing clusters:Munich and Stuttgart automotive sensor ecosystems are expanding into predictive maintenance for steel rolling mills and paper processing, where dust opacity defeats optical alternatives.
- Convergence with edge AI inference:Raw point-cloud processing is migrating from central vehicle computers into sensor modules, creating demand for millimeter wave-AI coprocessor combinations in smart city traffic monitoring.
- India PLI scheme for automotive electronics:Production-linked incentive allocations for advanced driver-assistance systems are attracting module assembly investments in Tamil Nadu and Gujarat manufacturing corridors.
Industry Challenges
- RF analog design talent scarcity:Heterodyne receiver architecture expertise concentrates among engineers trained in defense telecommunications, creating recruitment bottlenecks for automotive radar startups.
- Antenna pattern certification timelines:ETSI and FCC radiated emission testing protocols require 14–18 months for full module qualification, compressing product launch windows against silicon node transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Millimeter Wave Sensors Market |
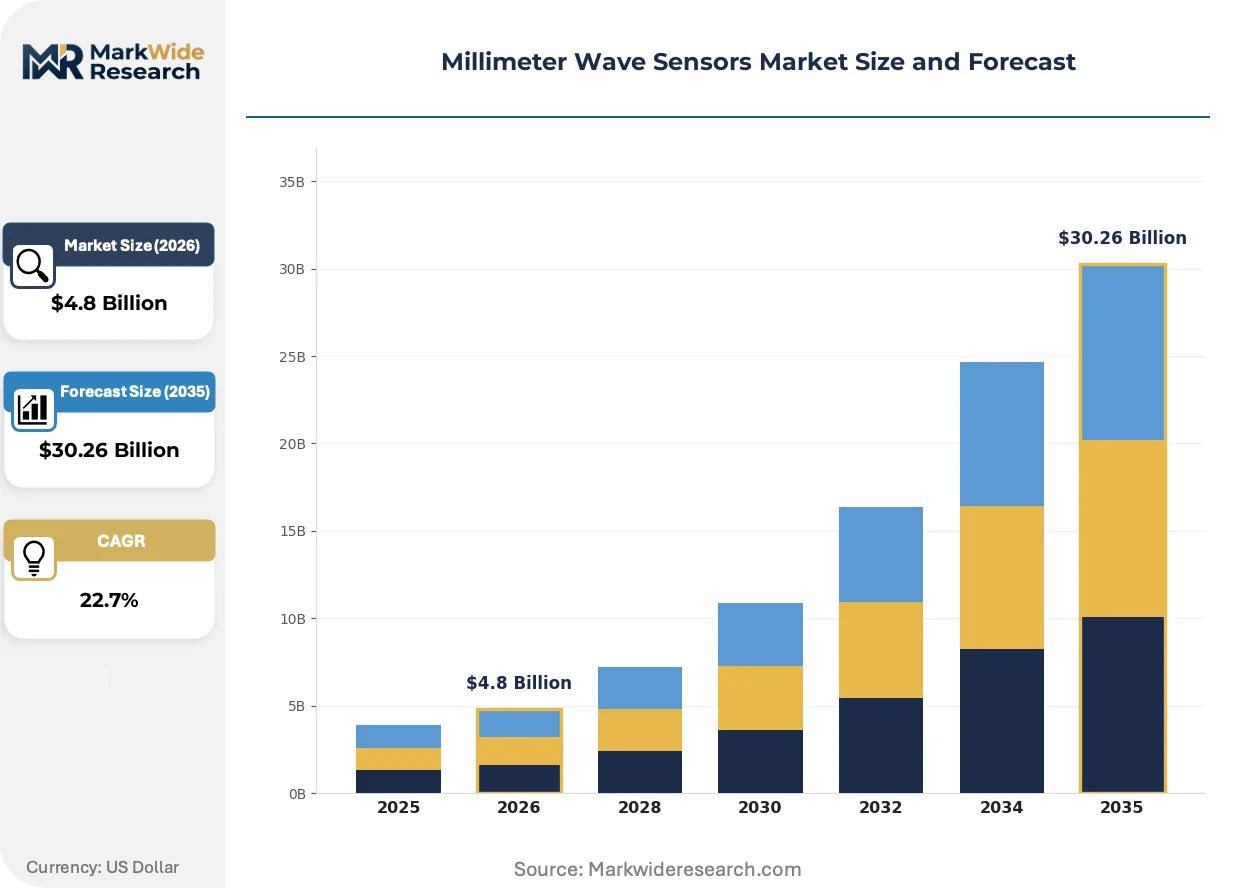
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $30.26 Billion |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
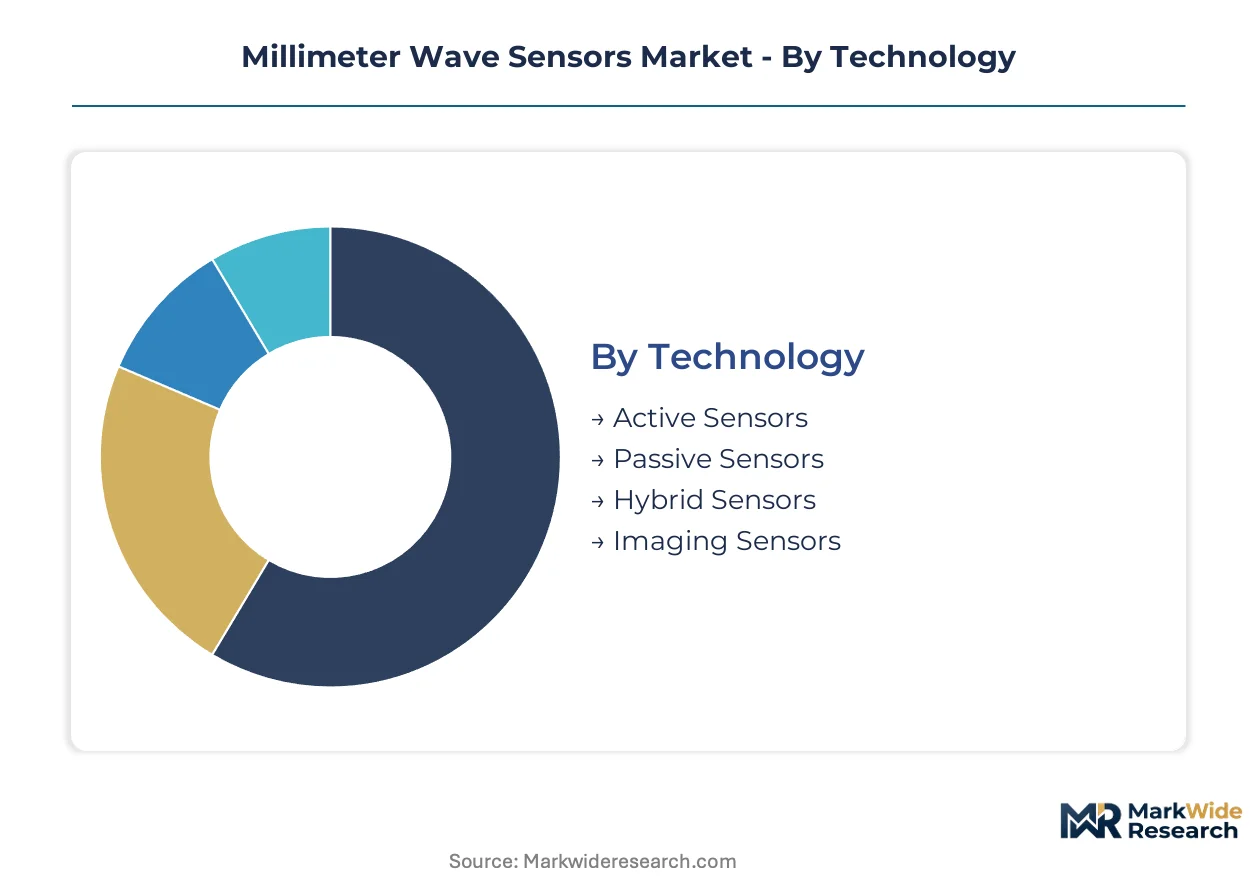
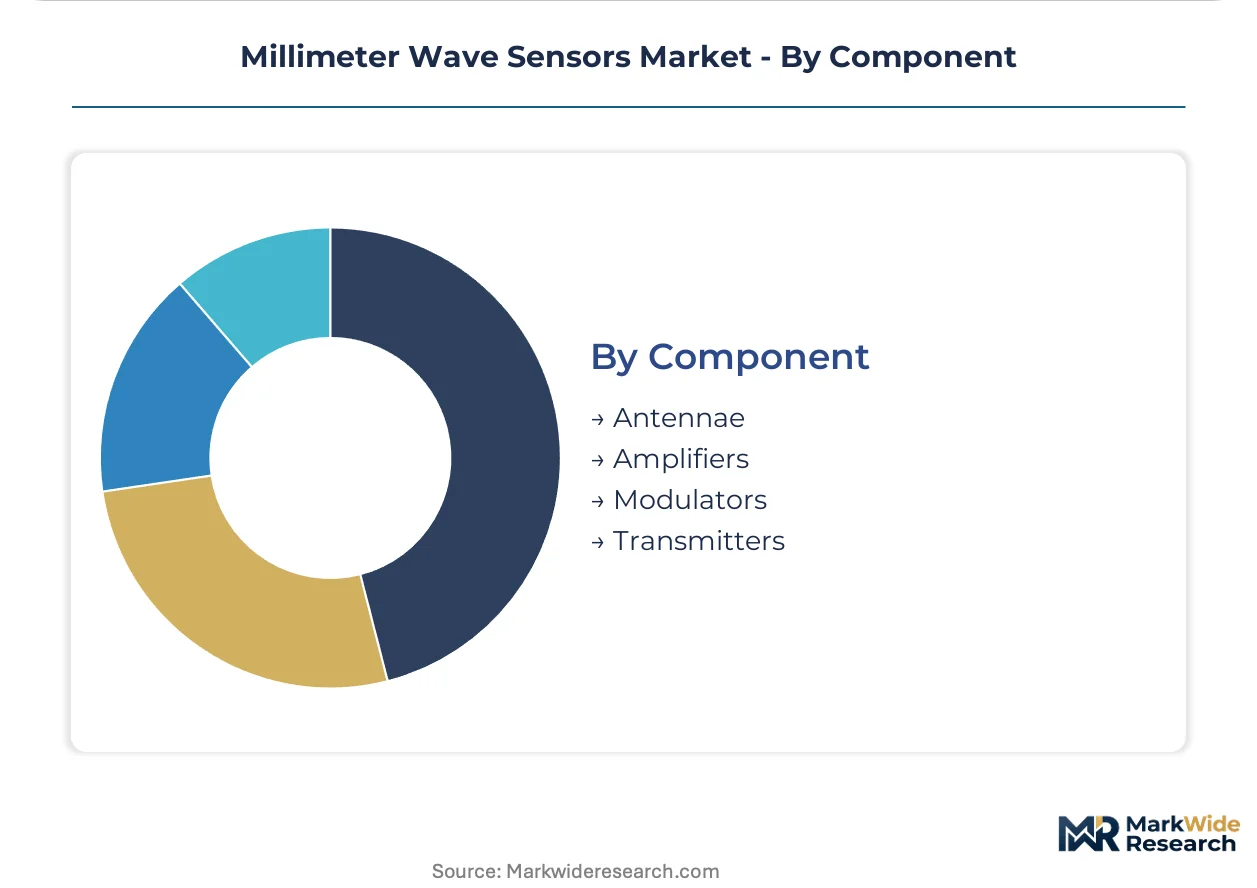
| Segmentation | Technology: Active Sensors, Passive Sensors, Hybrid Sensors, Imaging Sensors Application: Traffic Monitoring, Healthcare Imaging, Security Screening, Automotive Radar End User: Aerospace, Defense, Telecommunications, Automotive Component: Antennae, Amplifiers, Modulators, Transmitters |
| Companies Covered | Texas Instruments, Analog Devices, Infineon Technologies, NXP Semiconductors, Keysight Technologies, Rohde & Schwarz, L3Harris Technologies, Qualcomm Technologies, Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Millimeter Wave Sensors Market Shifts & Advancements
Module miniaturization and software-defined waveform processing are collapsing the traditional boundary between radar front-ends and digital signal chains, enabling new form factors in consumer electronics and medical devices.
Integrated RF-CMOS transceivers from 40 nm and 28 nm foundry nodes are electrifying cost structures in automotive radar. Tier-1 suppliers now qualify single-chip solutions for blind-spot monitoring and cross-traffic alert functions previously served by discrete gallium arsenide modules. This silicon transition is compressing bill-of-materials differentials between premium and standard vehicle trim levels.
ETSI EN 302 567 harmonization mandates are forcing antenna redesigns for European Union market access. Module vendors must demonstrate compliance with stricter effective isotropic radiated power limits and spurious emission masks than United States equivalents. Automotive radar manufacturers are responding with dual-mode firmware that switches power profiles based on GPS-detected regulatory domain.
Buyer procurement patterns are consolidating around qualified module suppliers capable of delivering antenna-in-package assemblies with pre-certified regulatory stacks. Tier-1 automotive electronics divisions are displacing in-house radar development teams in favor of turnkey subsystem sourcing from semiconductor vendors with captive packaging capabilities. This preference shift is most pronounced in German original equipment manufacturer supply chains, where Munich-based engineering centers now specify vendor-locked reference designs.
Millimeter Wave Sensors Market Segmentation
Millimeter wave sensor architectures diverge sharply in certification pathways, with automotive radar modules facing FCC Part 15 and ETSI EN 302 567 dual-qualification burdens while defense-grade hybrid systems navigate ITAR and country-specific export controls. Component-level segmentation determines foundry access, packaging complexity, and ultimately which supplier ecosystems capture margin pools across frequency bands.
Technology:
FCC Part 15 governs unlicensed active sensor emissions at 60 GHz and 77–81 GHz, while ETSI mandates stricter spurious limits for European market access. Defense-grade hybrid architectures trigger ITAR compliance and national security review protocols absent in commercial frequency-modulated continuous-wave designs.
- Active Sensors:Transmit-receive modules penetrate bumper fascias using gallium-nitride or RF-CMOS power amplifiers. German Tier-1 suppliers concentrate procurement for blind-spot monitoring and adaptive cruise control functions where FCC 77–81 GHz allocation enables single-sku North American deployment.
- Imaging Sensors:Phased-array architectures capture range, velocity, and angular position through synthetic aperture processing. Transportation Security Administration procurement specifications for privacy-preserving body scanners are displacing legacy X-ray systems in United States federal checkpoint modernization programs.
- Passive Sensors:Radiometric detection of natural thermal emissions requires cryogenic cooling for sensitivity, limiting deployment to radio astronomy and satellite earth observation.
- Hybrid Sensors:Multimode operation combining active transmission and passive reception commands premium pricing in defense telecommunications backhaul.
Leading the category by volume: Active Sensors. Growing fastest: Imaging Sensors.
Application:
Application segmentation maps directly to wavelength allocation battles, with automotive radar standardization at 77–81 GHz compressing architectures while security screening drives 94 GHz imaging development for material penetration.
- Automotive Radar:Single-chip integration at 40 nm and 28 nm foundry nodes is collapsing cost structures for frequency-modulated continuous-wave chipsets. Tier-1 suppliers now qualify integrated solutions for cross-traffic alert and automated emergency braking functions previously served by discrete gallium arsenide modules.
- Security Screening:Privacy-preserving millimeter wave body scanners eliminate anatomically revealing imagery through automated threat detection algorithms. Airport checkpoint modernization mandates in the United States and European Union are accelerating displacement of legacy X-ray backscatter systems.
- Traffic Monitoring:Smart city deployments fuse millimeter wave point clouds with edge AI inference for vehicle classification and incident detection.
- Healthcare Imaging:Non-contact vital sign monitoring and wound assessment applications remain pre-commercial, constrained by FDA 510(k) pathway complexity for novel diagnostic modalities.
Dominant by procurement value: Automotive Radar. Expanding most quickly: Security Screening.
End User:
End user concentration determines antenna-in-package qualification requirements, with aerospace and defense programs demanding hermetic sealing and radiation tolerance absent in automotive temperature-grade specifications.
- Automotive:Original equipment manufacturers in Germany's Munich-Stuttgart corridor specify vendor-locked reference designs with pre-certified regulatory stacks, displacing in-house radar development teams in favor of turnkey subsystem sourcing.
- Defense:Gallium-nitride supply partnerships and ITAR-controlled assembly houses limit qualified suppliers for electronically scanned array applications in electronic warfare and missile seeker programs.
- Telecommunications:5G backhaul and fixed wireless access drive demand for 28 GHz and 39 GHz phased-array customer premises equipment.
- Aerospace:Satellite inter-satellite links and terrain mapping altimeters require space-qualified packaging and radiation-hardened components.
Highest volume deployment: Automotive. Steepest margin expansion: Defense.
Component:
Component segmentation reflects foundry node bifurcation, with silicon-germanium BiCMOS processes anchoring high-reliability industrial sensing while RF-CMOS platforms electrify cost-sensitive automotive slots.
- Antennae:Antenna-in-package designs require low-loss substrate materials and thermo-compression bonding, concentrating qualified assembly capacity among three specialized houses in Taiwan and South Korea.
- Amplifiers:Power amplifier selection between gallium-nitride, gallium arsenide, and silicon-germanium processes determines efficiency, linearity, and thermal performance tradeoffs for specific frequency bands.
- Transmitters:Integrated voltage-controlled oscillators and frequency synthesizers enable software-defined waveform generation for adaptive modulation schemes.
- Modulators:Chirp generation circuits for frequency-modulated continuous-wave operation integrate at 130 nm and 90 nm silicon-germanium nodes with automotive temperature grade qualification.
Capturing dominant procurement spend: Antennae. Gaining share fastest: Amplifiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich and Stuttgart anchor the automotive sensor cluster that concentrates European procurement for millimeter wave radar modules, while FCC Part 15 spectrum rules in the United States and India's PLI scheme for automotive electronics reshape foundry capacity allocation across three continents.
United States
Transportation Security Administration procurement specifications for privacy-preserving body scanners drive 94 GHz imaging sensor demand at federal checkpoints. FCC Part 15 unlicensed spectrum expansion at 60 GHz and 77–81 GHz enables bumper-integrated radar qualification cycles for Tier-1 suppliers. Dallas-Fort Worth semiconductor engineering centers coordinate RF-CMOS foundry tape-outs for automotive radar single-chip integration.
Germany
Munich-based original equipment manufacturer engineering centers specify vendor-locked reference designs with pre-certified ETSI EN 302 567 regulatory stacks. The country's automotive sensor cluster around Stuttgart expands into predictive maintenance for steel rolling mills and paper processing. ETSI harmonized standards mandate stricter spurious emission limits than FCC equivalents, forcing dual-mode firmware development.
China
MIIT spectrum allocation for 5G backhaul and fixed wireless access at 28 GHz and 39 GHz drives phased-array customer premises equipment demand. The Yangtze River Delta semiconductor foundry ecosystem supports RF-CMOS platform migration from defense-grade gallium nitride. Shanghai packaging houses develop antenna-in-package assemblies for smart city traffic monitoring deployments.
India
Production-linked incentive allocations for advanced driver-assistance systems attract module assembly investments in Tamil Nadu and Gujarat manufacturing corridors. The country's national electronics regulator mandates BIS certification for automotive radar imports. Bengaluru engineering centers develop edge AI inference coprocessors for millimeter wave point-cloud processing in traffic classification systems.
South Korea
Seoul Capital Area assembly houses concentrate qualified capacity for thermo-compression bonding of low-loss substrate materials in antenna-in-package designs. The country's telecommunications regulator coordinates 28 GHz spectrum auctions for 5G fixed wireless access customer premises equipment. Busan-Ulsan industrial zones supply packaging materials for defense-grade hybrid sensor modules.
Millimeter Wave Sensors Market Competitive Landscape
Premium-margin players sit above commodity-margin players across foundry node access and packaging complexity dimensions. The vendor base organizes into three tiers: integrated RF-CMOS platform owners, silicon-germanium BiCMOS specialists, and gallium-nitride supply partnership controllers. Consolidation pressures favor semiconductor vendors with captive antenna-in-package capabilities over fabless module designers. Dominant competitive moves include foundry capacity reallocation toward automotive temperature-grade processes and strategic packaging partnerships with Taiwan and South Korea assembly houses.
Within the integrated platform tier, Texas Instruments and Infineon Technologies exemplify divergent process strategies for cost-sensitive versus high-reliability applications. NXP Semiconductors occupies a bridging position through gallium-nitride supply partnerships for defense-grade requirements. Among test and measurement specialists, Keysight Technologies and Rohde & Schwarz represent European instrumentation anchors for module qualification protocols. These five companies collectively illustrate the competitive spectrum from commodity automotive radar slots to premium defense telecommunications applications.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices |
| Infineon Technologies |
| NXP Semiconductors |
| Keysight Technologies |
| Rohde & Schwarz |
| L3Harris Technologies |
| Qualcomm Technologies |
| Mitsubishi Electric Corporation |
| Others |
Supply & Pricing Matrix
Captive antenna-in-package capabilities anchor both supply security and pricing power for millimeter wave sensor vendors, as Tier-1 automotive buyers disqualify fabless module designers lacking turnkey subsystem credentials. This integration choice concentrates margin capture among semiconductor vendors with qualified Taiwan and South Korea packaging partnerships, while forcing commodity RF-CMOS players into price-based competition for cost-sensitive blind-spot monitoring slots.
Pricing Analysis
Yield-throughput pricing anchors module economics, with antenna-in-package suppliers commanding premiums based on qualified regulatory throughput rather than component cost alone. Three-tier pricing structure across automotive-grade, industrial-grade, and defense-grade certification levels separates vendors by ETSI and FCC qualification completeness. Cost compression in automotive radar stems from foundry migration toward 28 nm RF-CMOS single-chip integration. Tier-1 suppliers exhibit lowest price sensitivity for pre-certified regulatory stacks, while aftermarket distributors face margin erosion from dual-sku inventory burdens.
Supply Chain Analysis
Dual-sourcing mandates from German OEM engineering centers require qualified assembly capacity at minimum two of three specialized Taiwan and South Korea packaging houses. Foundry supply draws from Taiwan, South Korea, and United States for RF-CMOS and silicon-germanium processes, with gallium-nitride substrate supply resting on United States and Japanese specialty vendors. Single-source vulnerability concentrates in thermo-compression bonding equipment for low-loss substrate attachment. Distribution runs through Tier-1 automotive electronics divisions specifying vendor-locked reference designs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Antenna-in-package qualification barriers are consolidating the millimeter wave sensor vendor base, forcing fabless module designers toward acquisition or exit as captive packaging capabilities become non-negotiable for Tier-1 procurement.
For Market Incumbents: Hedge against silicon-germanium BiCMOS margin erosion by securing gallium-nitride supply partnerships for defense-grade hybrid sensor programs. Reinforce foundry capacity allocation toward automotive temperature-grade 28 nm RF-CMOS nodes before node transition windows close. Lock packaging partnerships with Taiwan and South Korea assembly houses through multi-year capacity reservations. For New Entrants and Emerging Players: Tier-2 automotive suppliers in India's Tamil Nadu and Gujarat corridors offer the most penetrable entry channel for module assembly investments under PLI scheme allocations. Target industrial predictive maintenance applications in German steel rolling and paper processing clusters where dust opacity creates optical substitution barriers. Lead with edge AI coprocessor integration for smart city traffic monitoring deployments. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated RF-CMOS platform owners seeking captive antenna-in-package capabilities. Long-term viability favors vendors with dual-qualified ETSI and FCC regulatory stacks spanning automotive and defense telecommunications segments. Watch FCC spectrum auction outcomes and antenna efficiency threshold revisions as inflection signals for module qualification timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Antenna-in-Package Qualification | Captive packaging capabilities unlock Tier-1 automotive procurement slots previously closed to fabless designers. |
| Dual-Mode Firmware Development | GPS-detected regulatory switching enables single-sku deployment across FCC Part 15 and ETSI EN 302 567 domains. |
| Foundry Node Migration | 28 nm RF-CMOS tape-outs collapse bill-of-materials differentials between premium and standard vehicle trim levels. |
| Gallium-Nitride Supply Partnership | Defense-grade hybrid sensor margins depend on ITAR-controlled substrate access unavailable to commodity automotive vendors. |
| Edge AI Coprocessor Integration | Raw point-cloud processing migration into sensor modules creates demand in smart city traffic monitoring deployments. |
Research Methodology
SEC 10-K filings, ETSI harmonized standards documentation, and FCC Part 15 rulemaking dockets formed the secondary backbone for process node and regulatory pathway mapping. Primary interviews with Tier-1 automotive electronics procurement directors, semiconductor foundry planning officers, antenna-in-package assembly house technical leads, and defense telecommunications program managers validated capacity allocation assumptions. Bottom-up module shipment estimates triangulated against top-down frequency allocation and vehicle production forecasts.
Historical trendline analysis across silicon-germanium BiCMOS yield maturation, RF-CMOS node transitions, and phased-array packaging cost curves informed the projection framework. Segmentation dimensions modeled include sensor architecture type, end-use application, foundry process node, and geographic regulatory cluster. CAGRs derived from foundry capacity reallocation timelines and Tier-1 supplier qualification cycle durations. Forecast inputs incorporated ETSI and FCC antenna pattern certification timeline assumptions alongside gallium-nitride substrate supply constraints.
Caveats apply where FCC spectrum auction outcomes or ETSI emission limit revisions could materially shift the outlook for cross-border equipment compliance. Forecasts reflect assumptions regarding foundry yield maturation at 28 nm nodes and thermo-compression bonding capacity expansion in Taiwan and South Korea. Deviation in antenna-in-package qualification timelines or gallium-nitride supply partnership access would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Quantum Sensors Market
Sensors and Controls
Odor Sensor Market
Sensors and Controls
Piezoelectric Actuators Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Industrial Sensors Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Automotive MEMS Sensor Market
Sensors and Controls
Global Accelerometers Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
India Industrial Sensors and Transmitters Market
Sensors and Controls
Glucose Sensor Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Thermistor Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Conveyor Belt Tracking Devices Market