
 Asia-Pacific Nano Radiation Sensors Market | 2026-2036
Asia-Pacific Nano Radiation Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nano Radiation Sensors Market Insights
Buyer concentration in nuclear energy utilities is shifting toward diversified procurement across environmental monitoring agencies and research institutions. Hamamatsu Photonics K.K. leverages its photomultiplier tube heritage to anchor premium optical detection segments. Canon Electron Tubes & Devices Co., Ltd. competes through specialized vacuum tube integration for high-voltage radiation environments. NIHON KESSHO KOGAKU CO., LTD. dominates crystalline scintillator supply for precision dosimetry applications.
Asia-Pacific nano radiation sensors employ nanostructured scintillators, semiconductor quantum dots, and graphene field-effect transistors to detect ionizing radiation at dose rates below one microsievert per hour, serving critical functions in nuclear facility safety and medical radiotherapy calibration. Handheld sensors lead volume deployment in industrial safety inspections across Japan's Fukushima recovery zones, while graphene-based technology captures expanding margin pools due to its room-temperature operability and minimal power requirements. Integrated systems are maturing fastest in South Korean medical proton therapy centers where real-time beam monitoring demands sub-millimeter spatial resolution.
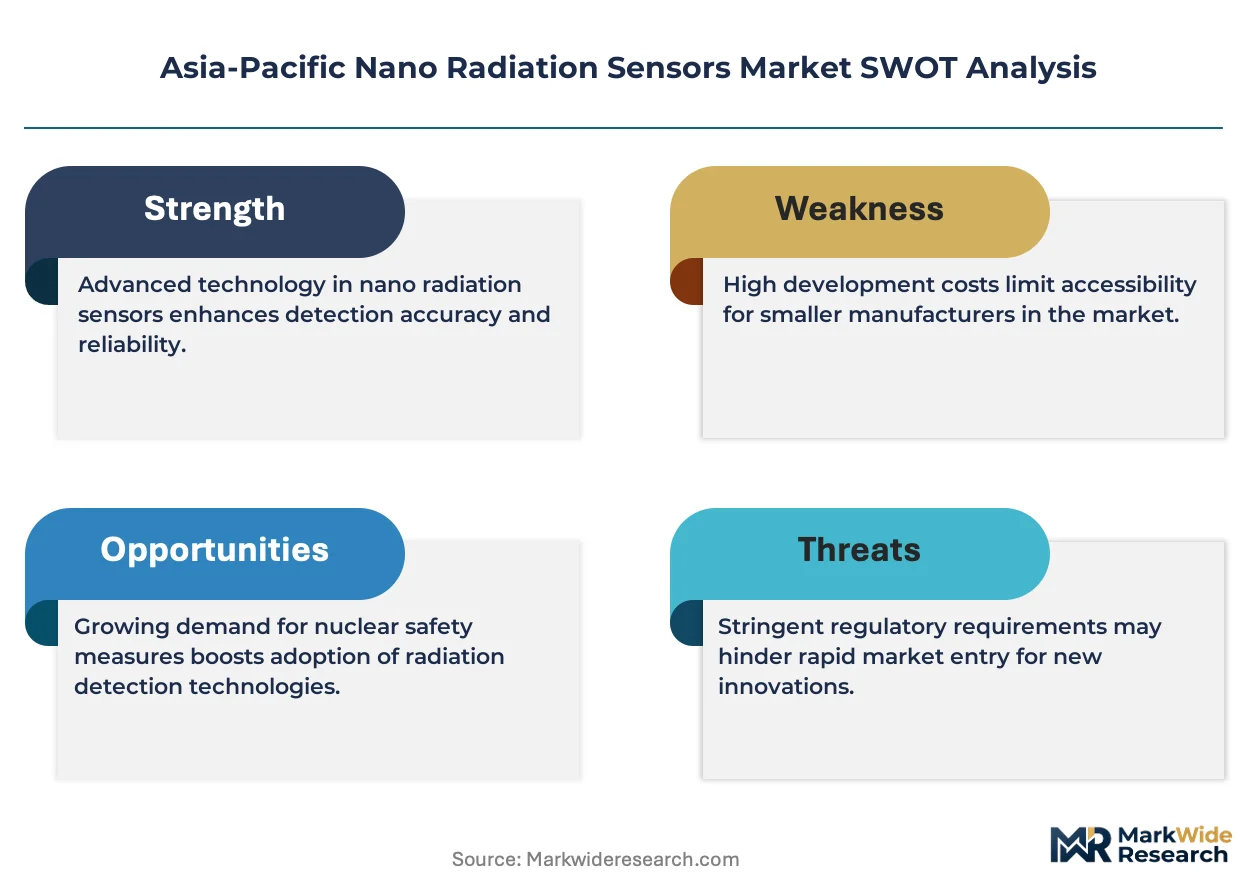
METI's nuclear safety standards in Japan, China's GB standards for radiation protection equipment under SAMR oversight, and South Korea's MFDS medical device certification collectively tighten product qualification thresholds and extend vendor development cycles. Australia's TGA registration pathway for therapeutic radiation devices adds a secondary compliance layer for medical-application entrants. Stakeholders must weigh regulatory divergence against the cost of maintaining multiple national certification portfolios when selecting manufacturing footprints.
Market Dynamics
Semiconductor fabrication facilities across Taiwan and South Korea are scaling procurement of nano-scale dosimetry equipment, while Japan's METI-mandated decommissioning protocols and China's graphene sensor investments compress vendor development timelines across the region.
Growth Catalysts
- Japan's METI nuclear safety standards:Updated decommissioning roadmaps under METI oversight are accelerating demand for high-precision radiation detection in Fukushima recovery zones and decommissioning sites.
- Graphene field-effect transistor arrays:China's concentrated investment in graphene-based sensor networks for environmental monitoring is creating new procurement channels for room-temperature operable devices.
- Medical proton therapy expansion:South Korean medical proton therapy centers require real-time beam monitoring with sub-millimeter spatial resolution, driving integrated system adoption.
Market Restraints
- Multi-jurisdiction certification costs:Divergent qualification requirements across Japan's METI, China's SAMR GB standards, South Korea's MFDS, and Australia's TGA extend vendor development cycles and inflate compliance overhead.
- Crystalline scintillator supply concentration:NIHON KESSHO KOGAKU's dominance in precision dosimetry scintillators creates single-source dependency risks for high-resolution applications.
- Quantum dot stability limitations:Semiconductor quantum dots face thermal degradation and photobleaching constraints that restrict operational lifespan in continuous monitoring deployments.
Strategic Opportunities
- Australian therapeutic radiation device registration:TGA's registration pathway for therapeutic radiation devices offers secondary market entry for medical-application vendors seeking diversification beyond Northeast Asian saturation.
- Environmental monitoring network densification:China's national environmental monitoring expansion creates demand for distributed graphene sensor arrays with minimal power requirements.
- Photomultiplier tube heritage convergence:Hamamatsu Photonics' optical detection expertise positions premium segments for integration with nanostructured scintillators in hybrid detection architectures.
Industry Challenges
- Nanofabrication talent scarcity:Cleanroom process engineering and quantum dot synthesis expertise concentrates in Japanese and South Korean research institutions, constraining regional production scaling.
- Legacy vacuum tube integration complexity:Canon Electron Tubes & Devices' specialized high-voltage vacuum tube architectures require substantial redesign for compatibility with solid-state nano sensor interfaces.
- Extended MFDS medical device certification timelines:South Korea's medical device certification processes delay market entry for novel nano sensor configurations in radiotherapy calibration applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nano Radiation Sensors Market |
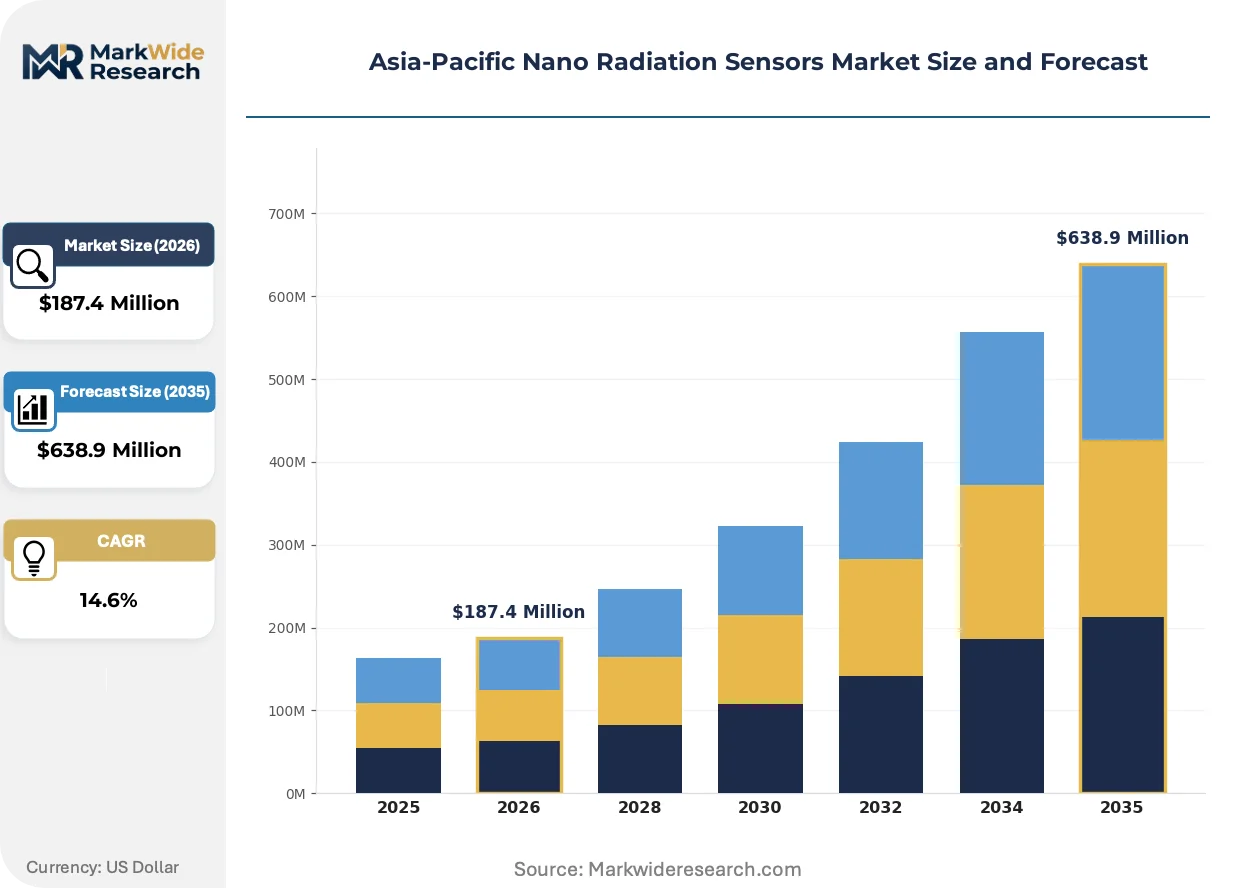
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Sensors, Fixed Sensors, Integrated Systems, Portable Detectors Technology: Optical, Semiconductor, Graphene-Based, Quantum Dot End User: Industrial Safety, Environmental Monitoring, Medical Applications, Research Institutions Application: Nuclear Energy, Radiation Therapy, Dosimetry, Radiation Detection |
| Companies Covered | Hamamatsu Photonics K.K., Canon Electron Tubes & Devices Co., Ltd., NIHON KESSHO KOGAKU CO., LTD., Fuji Electric Co., Ltd., Fortive Corporation, Kromek Group plc, First Sensor AG, Mirion Technologies, Inc., Thermo Fisher Scientific, Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nano Radiation Sensors Market Trends and Innovations
Graphene-based detection architectures and quantum dot scintillation materials are compressing traditional photomultiplier tube dominance, while regulatory divergence across METI, SAMR, and MFDS frameworks forces modular product platform strategies.
Graphene field-effect transistor sensors detect ionizing radiation at dose rates below one microsievert per hour without cryogenic cooling. Taiwan's semiconductor fabs and South Korea's medical proton centers are adopting these devices for continuous environmental and beam monitoring. This technology is expanding into handheld industrial safety inspection segments previously dominated by legacy scintillator-photomultiplier combinations.
METI's updated nuclear safety standards mandate real-time dosimetry with traceable calibration chains for all decommissioning operations. The regulation forces vendors to maintain dual certification portfolios for Japan's domestic market and export destinations. High-precision optical detection segments face the steepest compliance cost escalation as METI protocols diverge from China's SAMR GB standards.
Buyer concentration in nuclear energy utilities is fragmenting toward environmental monitoring agencies and research institutions across the region. Direct vendor relationships with Japan's Fukushima recovery authorities and China's provincial environmental bureaus are displacing traditional utility-centric distribution channels. This pattern is most visible in Japan, where decommissioning project managers now specify nano sensor performance benchmarks independently of reactor operator procurement frameworks.
Asia-Pacific Nano Radiation Sensors Market Segmentation
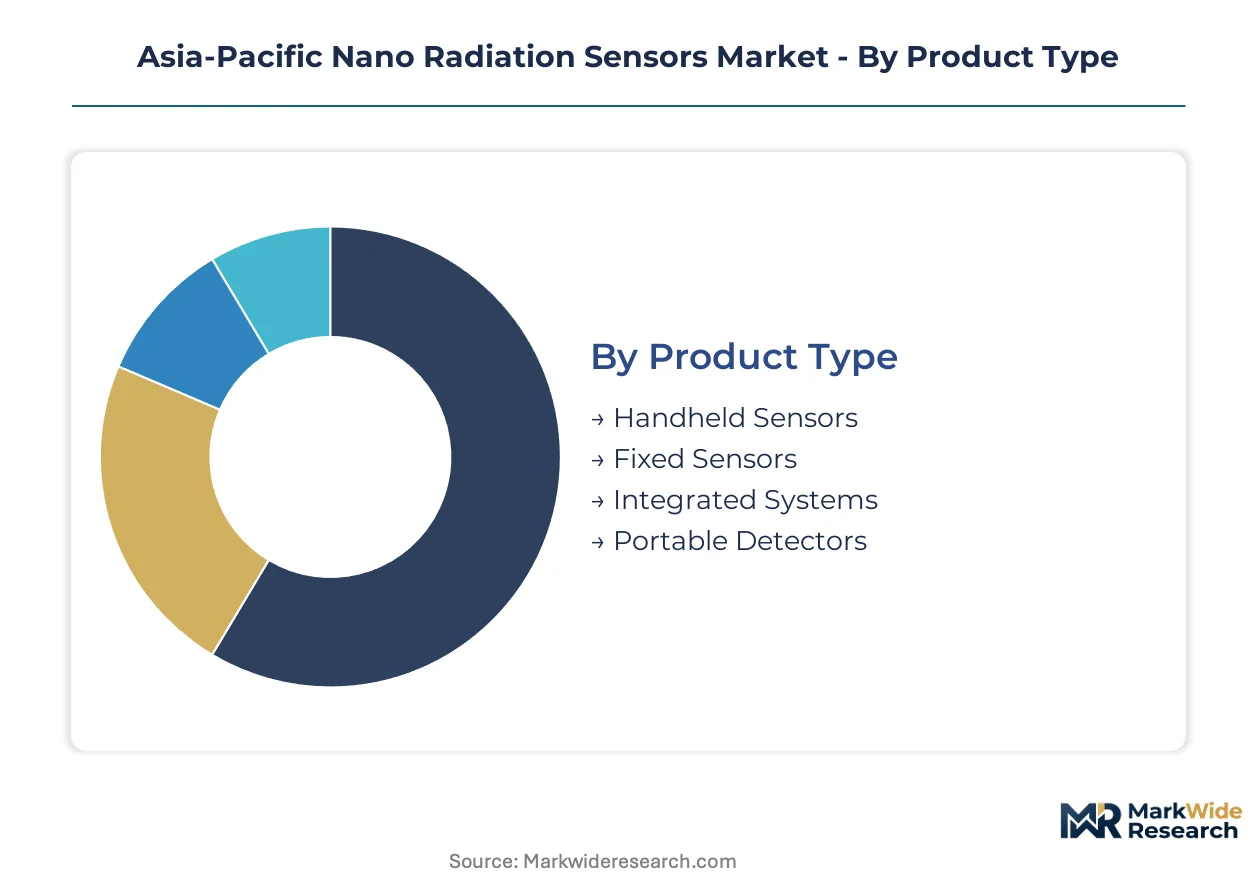
Nano radiation sensor procurement patterns diverge sharply across deployment contexts. Product architecture, underlying detection physics, and end-use certification requirements create distinct investment profiles and margin structures for vendors.
Product Type:
Capital intensity peaks with integrated systems requiring cleanroom fabrication and multi-sensor fusion, while handheld variants demand less upfront tooling but higher per-unit certification overhead.
- Handheld Sensors:Battery-powered units with nanostructured scintillator cores dominate Fukushima recovery zone inspections. Japan's METI decommissioning protocols specify traceable calibration chains that extend procurement cycles for these devices.
- Fixed Sensors:Permanent installations with graphene field-effect transistor arrays anchor China's provincial environmental monitoring networks. SAMR GB standards compliance adds secondary validation layers beyond factory calibration.
- Integrated Systems:Multi-channel architectures with sub-millimeter spatial resolution serve South Korean proton therapy centers. MFDS medical device certification compresses vendor margins through extended validation timelines.
- Portable Detectors:Transportable units bridge industrial safety and research applications across Taiwan's semiconductor fabs.
Most installed capacity flows through Handheld Sensors. Expansion is steepest in Integrated Systems.
Technology:
Manufacturing complexity stratifies sharply between mature optical platforms and emerging quantum architectures requiring specialized synthesis capabilities.
- Optical:Photomultiplier tube-scintillator combinations leverage decades of production heritage. Hamamatsu Photonics anchors premium segments where METI-mandated precision thresholds exclude solid-state alternatives.
- Graphene-Based:Field-effect transistor arrays operate at room temperature without cryogenic infrastructure. China's concentrated investment in environmental monitoring networks creates dedicated procurement channels for these devices.
- Semiconductor:Silicon and compound semiconductor detectors serve high-flux applications in nuclear energy utilities.
- Quantum Dot:Nanocrystal scintillators face thermal degradation constraints that limit continuous monitoring deployments.
Optical platforms retain the largest installed base. Graphene-Based configurations are gaining share fastest.
End User:
Customer procurement sophistication ranges from standardized industrial safety tenders to research institutions demanding customized performance specifications.
- Industrial Safety:Facility managers across Japan's decommissioning sites specify handheld devices with real-time dose rate displays. METI safety standards mandate redundant sensor architectures for high-radiation work zones.
- Environmental Monitoring:China's provincial environmental bureaus procure distributed graphene sensor arrays for national network densification. Minimal power requirements enable solar-powered remote installations.
- Medical Applications:South Korean proton therapy centers require integrated beam monitoring systems with sub-millimeter resolution. MFDS certification timelines delay market entry for novel sensor configurations.
- Research Institutions:University and national laboratory buyers in Taiwan and Japan commission custom quantum dot scintillators for experimental physics programs.
Industrial Safety accounts for the largest equipment volume. Medical Applications show the steepest margin expansion.
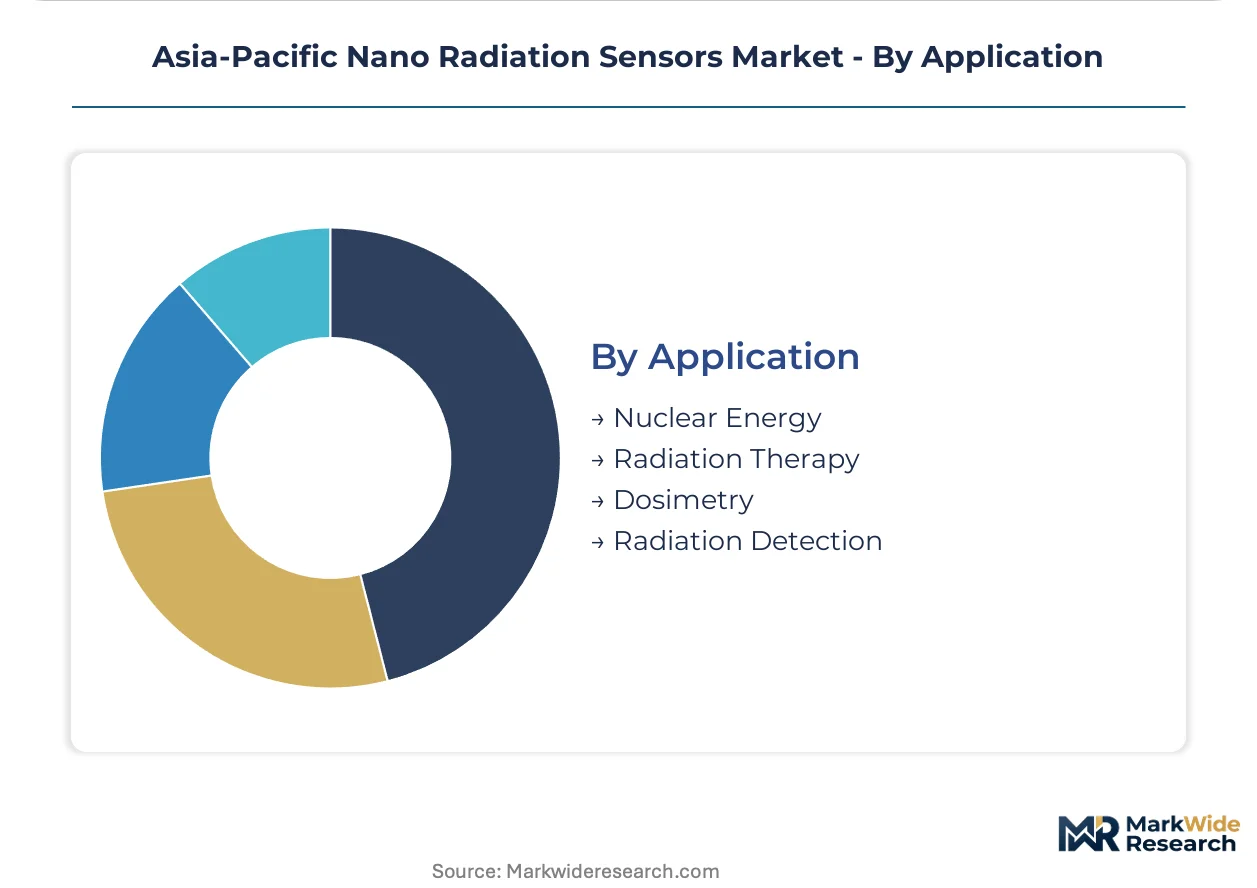
Application:
Regulatory jurisdiction determines certification pathway complexity, with nuclear energy and medical applications facing the most stringent qualification thresholds.
- Nuclear Energy:Reactor operators and decommissioning authorities across Japan demand traceable dosimetry with documented calibration chains. METI oversight extends vendor development cycles through mandatory safety case submissions.
- Radiation Therapy:Proton and heavy-ion therapy centers in South Korea require real-time beam profiling with spatial resolution below one millimeter. MFDS medical device registration adds compliance layers absent from industrial applications.
- Dosimetry:Personal and area monitoring applications span industrial safety and environmental monitoring end users.
- Radiation Detection:General-purpose detection serves research and security screening applications with lower specification thresholds.
Dosimetry commands the broadest installed base. Radiation Therapy exhibits the fastest climb in average selling prices.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's METI decommissioning protocols generate higher per-unit sensor procurement values than China's distributed environmental monitoring networks, though the latter deploys greater absolute device volumes across provincial grids.
Japan
Fukushima recovery zones and nuclear decommissioning sites drive handheld nano dosimetry procurement under METI oversight. Japan's nuclear safety standards mandate traceable calibration chains that extend vendor qualification timelines. Tokyo-based decommissioning project managers now specify sensor performance benchmarks independently of traditional utility procurement frameworks.
China
National environmental monitoring network densification creates sustained demand for graphene field-effect transistor arrays with minimal power requirements. SAMR GB standards for radiation protection equipment impose secondary validation layers beyond factory calibration. Provincial environmental bureaus in eastern coastal regions are displacing traditional distribution channels with direct vendor relationships.
South Korea
Medical proton therapy centers require integrated beam monitoring systems with sub-millimeter spatial resolution for real-time calibration. MFDS medical device certification compresses margins through extended validation timelines for novel sensor configurations. Seoul Capital Area hosts the densest concentration of radiotherapy facilities driving premium system adoption.
Taiwan
Semiconductor fabrication facilities are scaling procurement of nano-scale dosimetry equipment for cleanroom radiation monitoring. The country's national semiconductor regulator maintains stringent fab safety protocols that specify redundant sensor architectures. Hsinchu Science Park clusters the highest density of advanced manufacturing sites requiring continuous environmental surveillance.
Australia
TGA registration pathways for therapeutic radiation devices offer secondary market entry for medical-application vendors seeking geographic diversification. The regulator's compliance framework adds a certification layer absent from industrial safety applications. Sydney and Melbourne medical physics departments anchor research-driven procurement for experimental dosimetry configurations.
Asia-Pacific Nano Radiation Sensors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers, creating a bifurcated structure where photomultiplier heritage anchors premium optical segments while graphene startups capture emerging environmental monitoring channels. The vendor base stratifies into three archetypes: established optoelectronics houses with vacuum tube legacy, crystalline materials specialists controlling scintillator supply, and solid-state entrants commercializing room-temperature operable architectures. Competitive moves concentrate on strategic partnerships for regulatory certification bundling and technology licensing to compress MFDS and METI approval timelines.
Among Japan-based optoelectronics and materials specialists, Hamamatsu Photonics K.K., NIHON KESSHO KOGAKU CO., LTD., and Canon Electron Tubes & Devices Co., Ltd. occupy positions reflecting distinct heritage advantages. Hamamatsu Photonics represents the photomultiplier tube lineage that continues to anchor premium detection segments where METI-mandated precision thresholds apply. NIHON KESSHO KOGAKU exemplifies the crystalline scintillator concentration that creates supply dependencies for high-resolution dosimetry applications. Canon Electron Tubes & Devices sits within the specialized vacuum tube integration tier serving high-voltage radiation environments requiring substantial architectural redesign for solid-state compatibility.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| Canon Electron Tubes & Devices Co., Ltd. |
| NIHON KESSHO KOGAKU CO., LTD. |
| Fuji Electric Co., Ltd. |
| Fortive Corporation |
| Kromek Group plc |
| First Sensor AG |
| Mirion Technologies, Inc. |
| Thermo Fisher Scientific, Inc. |
| Others |
Pricing and Supply Chain Analysis
Decommissioning project managers in Japan's Fukushima recovery zones command substantial pricing power through METI-mandated traceable calibration chains that disqualify uncertified vendors. Their procurement specifications favor premium optical detection systems with documented heritage, compressing margins for solid-state alternatives while sustaining elevated price floors for photomultiplier tube-scintillator combinations.
Pricing Analysis
Capacity additions in Taiwan's semiconductor fabrication corridors are reshaping price floors for nano-scale dosimetry equipment as foundry procurement scales. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified systems with traceable calibration chains from SAMR-compliant environmental monitoring arrays and uncertified research-grade units. Price differentiation hinges on certification tier—MFDS medical device registration commands substantial premiums over industrial safety classifications—and volume scale from national environmental network tenders. Cost compression in handheld sensor segments is intensifying because China's provincial environmental bureaus consolidate procurement through direct vendor relationships. Research institutions exhibit least price sensitivity due to custom quantum dot scintillator specifications, while industrial safety buyers face tightening budgets under utility procurement frameworks.
Supply Chain Analysis
Dual-sourcing requirements from South Korea's proton therapy centers and Japan's decommissioning authorities mandate multi-supplier qualification for crystalline scintillator cores and graphene field-effect transistor arrays. Manufacturing concentrates in Japan, South Korea, and Taiwan, with NIHON KESSHO KOGAKU's crystalline scintillator production and Hamamatsu Photonics' photomultiplier tube heritage anchoring upstream supply. Raw material dependencies include high-purity germanium substrates, graphene monolayers from chemical vapor deposition processes, and rare-earth-doped crystal ingots. Single-source vulnerability concentrates in precision dosimetry scintillators where NIHON KESSHO KOGAKU's technical specifications have displaced alternative suppliers. Distribution runs through direct vendor relationships with decommissioning project managers and provincial environmental bureaus, displacing traditional utility-centric channels across the region.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where buyer procurement is shifting toward premium specifications with METI-mandated traceable calibration chains that exclude commodity alternatives. Vendors must align product architectures with divergent national certification portfolios or face margin compression from disqualification.
For Market Incumbents: Anchor premium positioning through photomultiplier tube heritage convergence with nanostructured scintillators, defending against graphene-based solid-state substitution in environmental monitoring segments. Deepen backward integration into crystalline scintillator supply to mitigate NIHON KESSHO KOGAKU dependency risks. Prioritize METI certification maintenance over SAMR GB standard compliance where margin pools concentrate in decommissioning applications. For New Entrants and Emerging Players: Launch via TGA registration pathways for therapeutic radiation devices, exploiting Australia's secondary market entry with lower competitive density than Northeast Asian saturation. Target medical proton therapy beam monitoring in South Korea's Seoul Capital Area where MFDS certification barriers filter incumbent competition. Pursue white-space in graphene sensor arrays for China's provincial environmental network densification, leveraging room-temperature operability against cryogenic infrastructure requirements. For Investors and Strategic Acquirers: Diversified optoelectronics conglomerates with vacuum tube legacy are the most active acquirer in this space, seeking graphene startup capabilities to complement photomultiplier heritage. Long-term viability hinges on regulatory certification bundling strategies that compress METI, SAMR, and MFDS approval timelines. Monitor MFDS medical device certification timeline divergence as inflection indicator for novel sensor configuration market entry feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Certification Bundling | Compresses METI, SAMR, and MFDS approval timelines for multi-market vendors. |
| Backward Integration into Crystalline Scintillators | Mitigates NIHON KESSHO KOGAKU single-source dependency for high-resolution dosimetry. |
| Graphene Field-Effect Transistor Commercialization | Captures China's environmental monitoring procurement with room-temperature operability. |
| Photomultiplier Tube Heritage Convergence | Positions Hamamatsu Photonics for hybrid detection architectures in premium segments. |
| TGA Therapeutic Device Registration | Opens Australian diversification pathway beyond Northeast Asian market saturation. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with decommissioning project managers, proton therapy center biomedical engineers, semiconductor fab safety officers, and provincial environmental bureau procurement leads combined with secondary validation from METI safety case submissions, MFDS medical device registration databases, SAMR GB standard compliance records, and TGA therapeutic device filings. Trade data from Japan Customs and Korea Customs Service anchored import-export analysis for nano radiation sensor components.
Input-output matrices mapped graphene field-effect transistor production capacity against environmental monitoring network deployment targets across the projection horizon. Segmentation dimensions modeled include product architecture, underlying detection physics, end-use certification requirements, and national regulatory jurisdiction. CAGRs were derived from installation base expansion rates calibrated against procurement cycle durations. Industry-specific forecast inputs incorporated METI decommissioning roadmap milestones and China's national environmental monitoring densification targets.
Several conditions sit outside the modeled scope, including military and defense radiation detection applications, consumer-grade dosimetry devices, and non-ionizing radiation sensor categories. Forecasts reflect assumptions regarding continued METI oversight of decommissioning operations and sustained Chinese state investment in environmental monitoring infrastructure. Deviation in graphene synthesis cost curves or quantum dot stability breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
MEMS Accelerometer and Gyroscope Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Canada Digital Thermometer Market
Sensors and Controls
Tactile Indicators Market
Sensors and Controls
Gimbal Market
Sensors and Controls
Smart Glove Market
Sensors and Controls
Refrigeration Gauge Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
Digital Angle Gauge Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
Europe Emission Monitoring System Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
Force Sensor Market