
 Submarine Sensor Market | 2026-2036
Submarine Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Submarine Sensor Market Intelligence
The modularization of sensor suites, allowing for mission-specific configurations, is rebalancing buyer preferences away from single, monolithic systems. This shift favors firms with broad portfolios like Thales Group, which can offer fully integrated solutions across multiple platforms. Lockheed Martin Corporation leverages its deep systems integration expertise to compete for large, complex naval contracts. Atlas Elektronik specializes in advanced sonar systems, particularly for European naval clients.
Submarine sensors are sophisticated electronic and electro-optical devices engineered for reliable operation in high-pressure, saline underwater environments. These systems are designed to detect acoustic, magnetic, or optical signatures to provide critical situational awareness and gather scientific data. Within sensor types, sonar remains the dominant category for core navigation and threat detection applications. However, fiber optic technologies are gaining significant share due to their immunity to electromagnetic interference and high sensitivity, especially in communication and environmental monitoring.
Product development adheres to stringent military specifications and international standards, such as those from the ISO for reliability. Export controls managed by entities like the United States Department of Defense influence market access. European Union directives like RoHS also impact material selection for sensor components. The critical decision for manufacturers revolves around balancing investment in quantum systems against modernizing existing piezoelectric platforms.
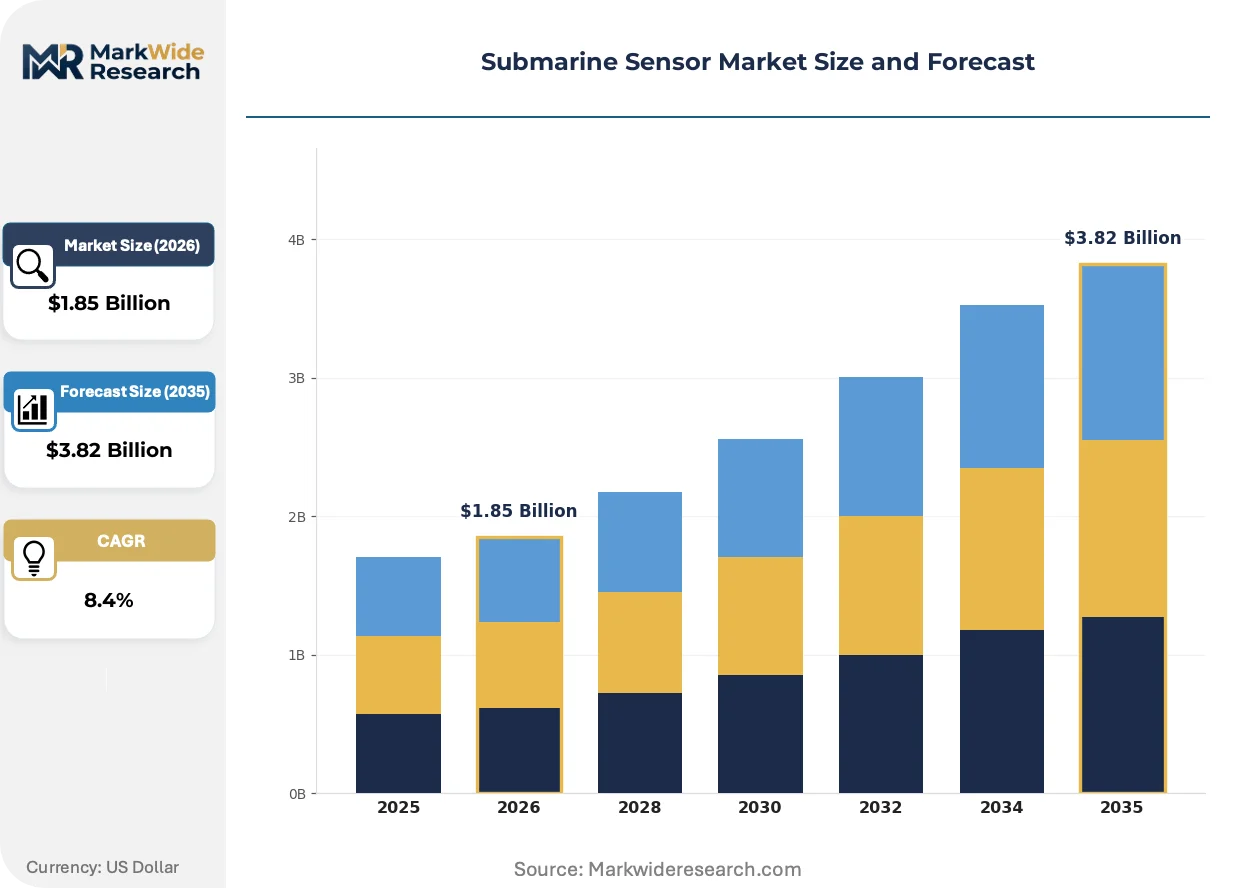
Market Dynamics
The convergence of naval modernization programs and expanding commercial offshore exploration for seabed resources defines the market's structural dynamic. This dual-use demand accelerates investment in next-generation detection technologies for deep-sea and littoral zone operations.
Growth Catalysts
- Naval Modernization:Defense budget growth in Australia and India is funding new submarine sensor suites to enhance anti-submarine warfare capabilities in the Indo-Pacific.
- Offshore Energy Growth:The expansion of offshore wind farms necessitates advanced acoustic sensors for detailed seabed mapping and environmental assessments.
- UUV Proliferation:Increased use of unmanned underwater vehicles creates demand for miniaturized, low-power sensor payloads for autonomous missions.
Market Restraints
- Export Controls:Regulations like the United States' International Traffic in Arms Regulations (ITAR) restrict the sale of advanced sensor technologies, limiting market access for manufacturers in certain nations.
- Material Scarcity:The supply chain for high-purity piezoelectric ceramics and specific rare earth elements is concentrated, creating price volatility and supply risks.
- Acoustic Propagation Limits:Sonar performance is inherently constrained by variable water salinity, temperature, and pressure in littoral zones, degrading signal clarity.
Strategic Opportunities
- Quantum Sensing:Developing quantum magnetometers offers unprecedented sensitivity for passive detection, creating opportunities in both defense and geophysical survey applications.
- AI-Enhanced Processing:Integrating machine learning algorithms into sensor fusion engines can automate target recognition and improve classification accuracy in cluttered acoustic environments.
- Environmental Monitoring:Expanding sensor suites to include chemical detectors addresses a growing need for persistent underwater monitoring related to pollution tracking.
Industry Challenges
- Systems Integration:Ensuring interoperability between new modular sensors and legacy combat management systems on older submarines presents a significant technical hurdle.
- Specialized Talent Scarcity:A shortage of engineers with expertise in underwater acoustics and quantum physics constrains product development and field support.
- Prolonged Qualification:Adherence to rigorous military specifications from bodies like the United States Department of Defense results in long development-to-deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Submarine Sensor Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.82 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Sensor Type: Sonar, Magnetic, Acoustic, Optical, Pressure, Electromagnetic Technology: Fiber Optic, Piezoelectric, Ultrasonic, MEMS, Capacitive, Quantum Application: Navigation, Threat Detection, Environmental Monitoring, Communication Assistance, Structural Health Monitoring, Oceanographic Data Collection End User: Navy, Research Institutions, Offshore Exploration, Salvage Operations, Underwater Archaeology, Defense Contractors |
| Companies Covered | L3Harris Technologies Inc., Atlas Elektronik, Lockheed Martin Corporation, Safran Electronics & Defense, Leonardo DRS Inc, Thales Group, Raytheon Technologies Company, BAE Systems Plc, Northrop Grumman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Submarine Sensor Market Strategic Shifts & Innovations
The evolution from single, platform-centric sensors toward distributed, networked sensing architectures is fundamentally altering underwater domain awareness. This transition prioritizes data fusion and collaborative signal processing across multiple platforms for a more complete operational picture.
AI-powered algorithms are embedded into sensor hardware to analyze vast streams of acoustic and non-acoustic data in real time. Naval operators and oceanographic researchers are adopting these systems to manage data from high-resolution sensors. This embedded intelligence is automating the process of target detection and classification, reducing operator cognitive load.
European Union directives such as RoHS are influencing material selection by restricting substances like lead. This requires manufacturers to redesign sonar transducers and associated electronics with compliant, alternative materials. The hydrophone segment is particularly impacted, driving R&D into lead-free piezoelectric ceramics that maintain performance.
Naval acquisition is shifting from monolithic sensor systems toward procuring modular, open-architecture sensor suites. This change allows end-users to reconfigure submarines with mission-specific payloads, like towed arrays for anti-submarine warfare. This trend is most visible in modernization programs for United States and European navies.
Submarine Sensor Market Segmentation
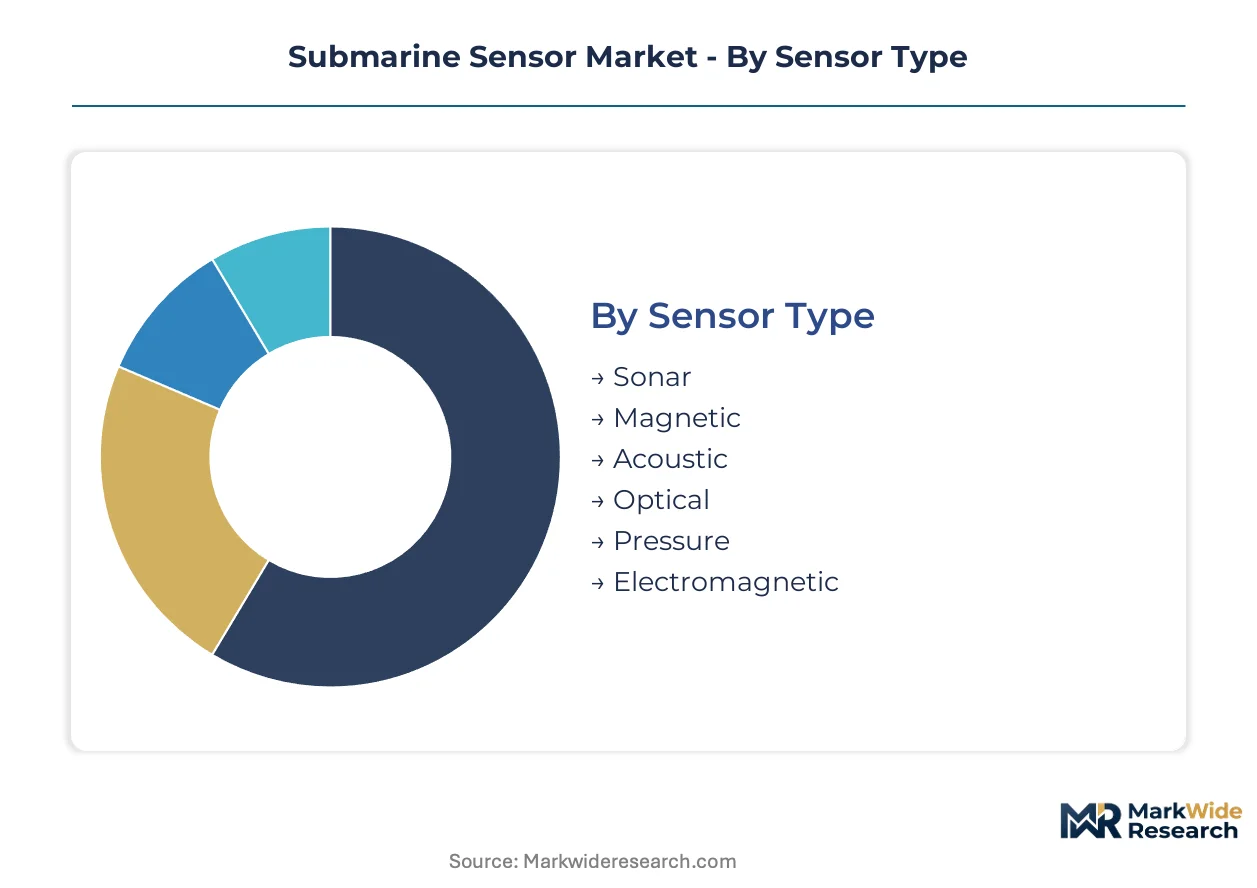
The Submarine Sensor Market segments across various dimensions, reflecting the diverse operational requirements and technological advancements within underwater domain awareness. Understanding these distinct categories allows manufacturers to tailor product development and strategic investments towards specific defense, scientific, or commercial applications.
Sensor Type:
Buyer preferences in this category are primarily differentiated by the physical phenomena detected and the operational environment, dictating the sensor's fundamental purpose.
- Sonar:These active or passive systems emit and receive acoustic pulses to detect and localize underwater objects, forming the bedrock of submarine navigation and anti-submarine warfare for global navies. Demand concentrates in the United States and European naval modernization programs due to its critical role in threat detection and seabed mapping.
- Acoustic:Specialized passive hydrophones and arrays listen for sound signatures from vessels, marine life, or geological activity, providing stealthy detection and environmental data collection. The Indo-Pacific region drives demand for enhanced acoustic arrays to monitor maritime traffic and improve situational awareness.
- Magnetic:Magnetometers measure disturbances in the Earth's magnetic field caused by ferrous objects, enabling passive detection of submarines and unexploded ordnance for defense and survey missions.
- Optical:Cameras and light-based sensors provide high-resolution visual data for identification, inspection, and mapping in clear water conditions, particularly for research institutions.
- Pressure:These sensors accurately measure hydrostatic pressure to determine depth, crucial for safe submarine operation and precise oceanographic profiling.
- Electromagnetic:Systems detecting electromagnetic fields are used for mine detection and communication, offering alternative detection modalities in specific scenarios.
Sonar leads volumes today; Acoustic is gaining share fastest.
Technology:
The impact on sensor performance and integration capabilities defines buyer choices within this technology segment.
- Fiber Optic:These sensors leverage light transmission for high sensitivity, immunity to electromagnetic interference, and compact size, making them ideal for communication and environmental monitoring applications. Demand from offshore energy projects in Europe is accelerating due to their reliability in harsh conditions.
- Piezoelectric:Utilizing materials that convert mechanical stress into electrical charge, these form the core of traditional sonar transducers, offering robust performance in established naval platforms. Manufacturers are balancing investment in new piezoelectric ceramics against quantum systems for defense clients.
- Ultrasonic:Employing high-frequency sound waves, ultrasonic sensors are used for short-range detection, obstacle avoidance, and precise imaging in confined underwater spaces.
- MEMS:Micro-Electro-Mechanical Systems enable the miniaturization of sensors, facilitating their integration into unmanned underwater vehicles for autonomous missions.
- Capacitive:These sensors detect changes in electrical capacitance for proximity sensing, level detection, and precise displacement measurement in various underwater instruments.
- Quantum:Emerging quantum sensing technologies promise unprecedented sensitivity for passive detection of magnetic anomalies and subtle acoustic signatures, attracting significant research funding.
Fiber Optic technologies are expanding most quickly; Piezoelectric platforms maintain significant market presence.
Application:
The primary operational goals and data requirements drive the differentiation across various applications for submarine sensors.
- Threat Detection:Sensors identifying hostile vessels, mines, or other underwater threats are paramount for naval defense and anti-submarine warfare, securing significant defense budget allocations. Naval modernization programs in Australia and India prioritize advanced threat detection suites.
- Navigation:Systems providing precise positioning, depth, and obstacle avoidance are fundamental for safe and efficient submarine operations, integrating with combat management systems. The United States Navy continuously upgrades navigation sensor suites for its submarine fleet.
- Environmental Monitoring:These sensors collect data on water quality, temperature, salinity, and marine life, supporting scientific research and regulatory compliance for offshore industries.
- Communication Assistance:Sensors facilitating underwater acoustic communication or aiding in surface-to-sub communication are essential for operational coordination and data transfer.
- Structural Health Monitoring:Sensors assessing the integrity of submarine hulls, offshore platforms, or underwater infrastructure help prevent failures and extend operational lifespans.
- Oceanographic Data Collection:Comprehensive sensor suites gather detailed information about ocean currents, seabed topography, and geophysical characteristics for scientific and commercial mapping.
Threat Detection applications hold the largest share; Environmental Monitoring is experiencing the steepest expansion trajectory.
End User:
Organizational mandates and funding sources fundamentally shape procurement patterns across the end-user landscape.
- Navy:National defense forces are the largest end-users, procuring sophisticated sensor suites for submarines to enhance anti-submarine warfare, intelligence gathering, and maritime security operations. The United States Department of Defense drives substantial investment in advanced naval sensor technology.
- Offshore Exploration:Companies involved in oil and gas, and increasingly offshore wind, utilize sensors for detailed seabed mapping, resource identification, and infrastructure inspection. European offshore wind farm developers are a significant segment for acoustic and optical sensors.
- Research Institutions:Academic and government research bodies deploy sensors for oceanographic studies, climate change monitoring, and marine biology investigations.
- Salvage Operations:Specialized companies use sensors to locate sunken vessels, retrieve valuable objects, and assess underwater damage following maritime incidents.
- Underwater Archaeology:Researchers and heritage organizations employ sensors for mapping ancient shipwrecks and submerged historical sites.
- Defense Contractors:These firms integrate various sensor components into larger systems for government clients, often acting as prime system integrators for complex naval projects.
The Navy segment contributes the most to revenue; Offshore Exploration is rapidly expanding its sensor procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The submarine sensor industry scaled significantly with early naval defense programs, initially focused on acoustic detection for maritime security. These foundational advancements laid the groundwork for modern underwater sensing capabilities. This historical development concentrated expertise in nations with substantial naval forces and oceanographic research interests.
United States
Naval modernization programs drive substantial demand for advanced sensor suites, particularly for threat detection and navigation. The United States Department of Defense (DoD) continuously funds upgrades for its submarine fleet, ensuring technological superiority. Silicon Valley and defense contractors in Virginia develop next-generation sensor technologies for critical naval applications.
United Kingdom
British naval defense initiatives prioritize sophisticated sonar and acoustic systems for enhanced maritime domain awareness. The UK Ministry of Defence influences procurement decisions, focusing on anti-submarine warfare capabilities. Plymouth hosts significant marine technology clusters, specializing in underwater sensor integration and research.
India
Indian defense budget growth fuels significant investment in new submarine sensor suites, especially for Indo-Pacific operations. The PLI scheme supports domestic manufacturing of advanced defense electronics and related components. Visakhapatnam's naval dockyards are central for sensor integration, maintenance, and operational readiness.
Australia
Australian naval modernization programs enhance anti-submarine warfare capabilities and maritime surveillance in the Indo-Pacific region. The Australian Defence Force procures advanced detection technologies for its modern submarine fleet. Adelaide's Osborne Naval Shipyard is a key hub for submarine construction and sensor installation activities.
Germany
German firms specialize in advanced sonar systems, particularly for European naval clients and commercial offshore applications. European Union directives like RoHS significantly impact material selection for sensor components. Kiel, a major naval base, features research institutions actively developing underwater acoustic solutions.
Submarine Sensor Market Key Industry Players
Premium-margin players sit above commodity-margin players across the technological sophistication spectrum, particularly for defense-grade systems requiring stringent military specifications. The market exhibits a tiered structure, with a few large integrators and numerous specialized component providers. Strategic archetypes include large defense contractors, specialized sensor manufacturers focusing on niche applications, and emerging quantum technology developers. Dominant competitive moves involve strategic partnerships for complex systems integration and continuous investment in R&D for next-generation detection capabilities.
Within the large defense contractor archetype, Thales Group and Lockheed Martin Corporation represent major system integrators offering fully integrated solutions across multiple platforms. These global entities leverage extensive expertise to compete for large, complex naval contracts, providing comprehensive sensor suites. Atlas Elektronik, a German-based firm, exemplifies specialization in advanced sonar systems, particularly for European naval clients, focusing on core detection capabilities. These entities collectively anchor the market by providing complex, mission-critical technologies and driving innovation in underwater sensing.
| Leading Market Players |
|---|
| L3Harris Technologies Inc. |
| Atlas Elektronik |
| Lockheed Martin Corporation |
| Safran Electronics & Defense |
| Leonardo DRS Inc |
| Thales Group |
| Raytheon Technologies Company |
| BAE Systems Plc |
| Northrop Grumman Corporation |
| Others |
Cost & Logistics Intelligence
European Union directives like RoHS gate qualified material supply, directly influencing premium-tier pricing for compliant submarine sensor components. This mandate drives investment in alternative, high-performance materials for specialized applications.
Pricing Analysis
Project-based pricing dominates the submarine sensor market, reflecting the bespoke nature of large naval contracts and complex system integration requirements. Price differentiation stems from adherence to stringent military specifications and the high degree of customization for mission-specific configurations. Pricing pressure arises from material scarcity for high-purity piezoelectric ceramics, impacting component costs. Research institutions exhibit the highest price sensitivity, while navies prioritize performance and reliability above cost.
Supply Chain Analysis
Dual-sourcing requirements are becoming standard practice for critical components within the submarine sensor supply chain to mitigate risks. Geographic supply concentration for advanced sensor components centers on the United States, Germany, and China for specific rare earth elements. The market relies heavily on high-purity piezoelectric ceramics and specialized fiber optic technologies. Single-source vulnerability for specialized materials creates price volatility, with distribution running through direct sales channels to national navies and prime defense contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The submarine sensor market presents a geographic-arbitrage play due to regulatory differentials, such as United States export controls, which restrict technology transfer. This creates distinct market access and cost structures across regions.
For Market Incumbents:Deploy continuous R&D investment to maintain technological leadership in quantum sensing and AI-enhanced processing. Deepen systems integration expertise to ensure interoperability between new modular sensors and legacy combat management systems, countering specialized talent scarcity. Pursue strategic partnerships for complex naval contracts to mitigate prolonged qualification timelines. This strategy defends against emerging quantum technology developers.
For New Entrants and Emerging Players:Price-point gaps exist in the commercial offshore exploration sector for advanced environmental monitoring sensors. Target miniaturized, low-power sensor payloads for unmanned underwater vehicles, leveraging the UUV proliferation trend. Focus on developing chemical detectors for pollution tracking, which represents a growing need. Go-to-market via partnerships with European offshore wind farm developers.
For Investors and Strategic Acquirers:Roll-up economics work for specialized sensor manufacturers because of the market's tiered structure and high barriers to entry for defense-grade systems. The long-term viability of this market remains strong, driven by persistent naval modernization and expanding commercial offshore exploration over the next decade. Target specialized component providers or emerging quantum technology developers. Defense budget growth in the Indo-Pacific region is a key signal to watch for accelerated investment.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Enhanced Processing Integration | This improves classification accuracy in cluttered acoustic environments, reducing operator cognitive load. |
| Quantum Sensing R&D | This offers unprecedented sensitivity for passive detection in defense and geophysical survey applications. |
| Modular Sensor Suite Development | This allows mission-specific configurations, rebalancing buyer preferences away from monolithic systems. |
| Lead-Free Piezoelectric Ceramic R&D | This ensures compliance with European Union RoHS directives while maintaining sonar performance. |
| Deep Systems Integration Expertise | This competes for large, complex naval contracts requiring interoperability with legacy combat systems. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to build a robust understanding of the Submarine Sensor Market. Primary insights were gathered from naval procurement officers, R&D engineers specializing in underwater acoustics, offshore energy project managers, and prime defense contractors. Secondary validation drew from United States Department of Defense reports, ISO standards, European Union directives, and naval modernization program documents. A rigorous bottom-up and top-down triangulation approach ensured data accuracy.
Segment-weighting formed the core of the analytical framework, projecting volume and value across the analysis window. The model incorporated dimensions such as sensor type, underlying technology, application, end user, and regional defense spending. Compound annual growth rates were derived from historical trends and projected investment patterns. Key industry-specific inputs included naval budget allocations and offshore exploration project pipelines.
Caveats apply where geopolitical shifts, rapid technological breakthroughs in quantum sensing, or global economic downturns could materially shift the outlook. Forecasts reflect a range of underlying assumptions regarding defense spending and commercial investment. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Middle East and Africa Wearable Sensors Market
Sensors and Controls
Tunnel Sensor Market
Sensors and Controls
Sensor Development Kit Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
Semiconductor Sensor Market
Sensors and Controls
Automation Control Components and Devices Market
Sensors and Controls
Middle East Robotic Sensors Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Europe Sensors Market