
 United States Gas Sensors Market | 2026-2036
United States Gas Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gas Sensors Market Analytics
MEMS-based sensing architectures and solid-state chemiresistive platforms is reconfiguring how manufacturers achieve ppm-level detection thresholds without heated filaments. Honeywell International Inc. leverages its distributed sensing networks to anchor industrial facility contracts across the Gulf Coast. MSA Safety Incorporated sustains dominance in portable personal monitors through channel control with fire departments and utility operators. Amphenol Advanced Sensors specializes in miniaturized electrochemical cells for automotive cabin air systems.
United States gas sensors are transducer devices that convert chemical gas concentrations into quantifiable electrical signals, typically operating across detection ranges from parts-per-billion to percentage-level concentrations using catalytic bead, electrochemical, or optical absorption principles. Their primary commercial purpose centers on preventing toxic exposure, explosive atmosphere ignition, and environmental non-compliance across regulated workplaces. Electrochemical sensors capture the largest installed base due to proven specificity for carbon monoxide and hydrogen sulfide, while infrared segments command premium pricing for hydrocarbon leak detection in upstream oil and gas. Wireless technology deployments are expanding fastest as utilities retrofit fixed-point monitors with mesh-network telemetry to reduce cabling costs and enable predictive maintenance.
OSHA permissible exposure limit enforcement and EPA methane emissions rules under the Clean Air Act directly shape product certification requirements and replacement demand cycles for industrial end users. NHTSA cabin air quality guidelines and California Air Resources Board mobile source regulations further extend sensor mandates into automotive and environmental monitoring applications. Stakeholders must monitor evolving EPA methane performance standards and state-level net-zero commitments that will redefine minimum detection thresholds and calibration protocols.
Market Dynamics
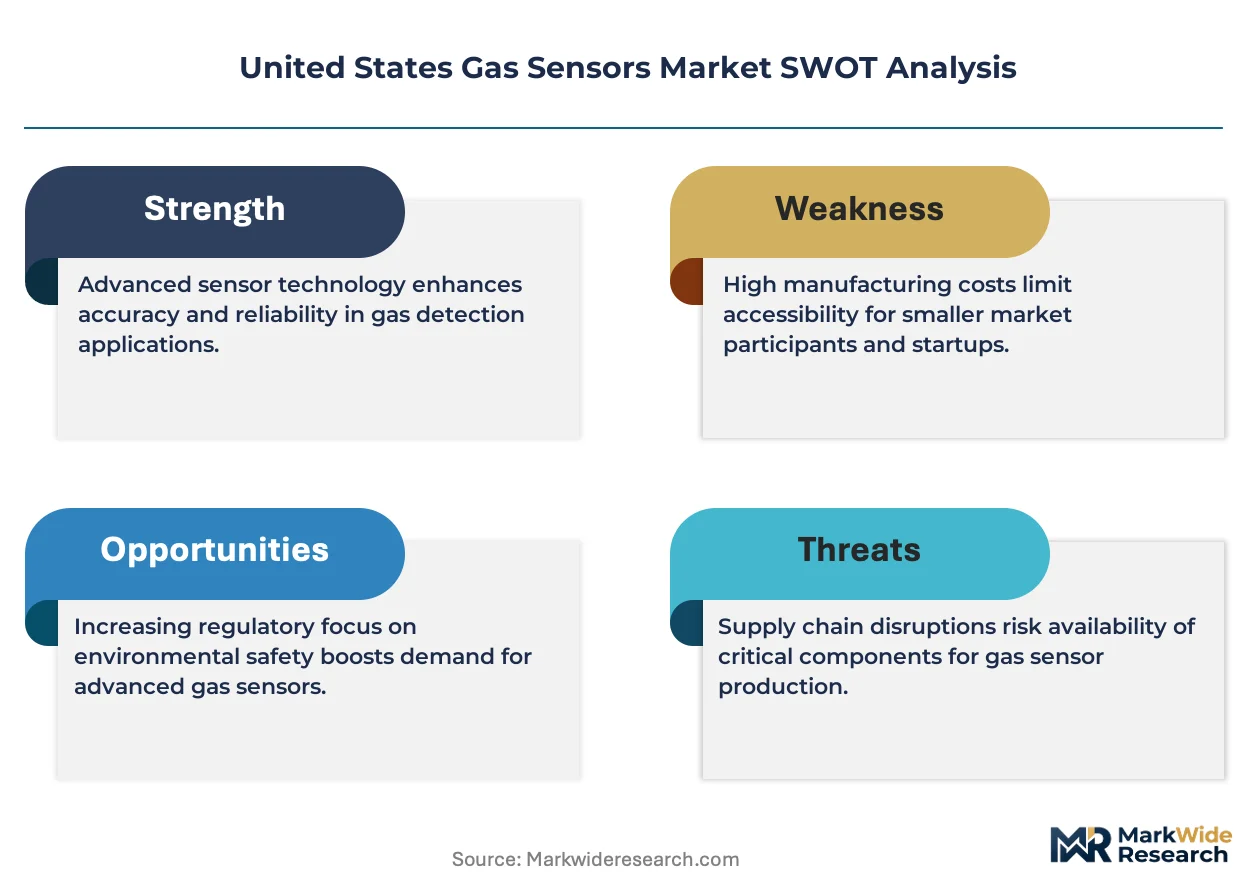
OSHA's tightening permissible exposure limits for hydrogen sulfide and benzene derivatives are compressing replacement cycles across Gulf Coast petrochemical corridors, forcing facility operators to retire legacy catalytic bead sensors ahead of scheduled maintenance windows.
Growth Catalysts
- EPA methane performance standards:Upstream oil and gas operators in the Permian Basin must deploy optical gas imaging and fixed-point monitors to detect leaks above specified thresholds, creating sustained replacement demand for infrared sensing platforms.
- Electrochemical miniaturization:Solid-state chemiresistive architectures now achieve parts-per-billion sensitivity without heated filaments, opening deployment in confined-space wearables previously dominated by larger form factors.
- Texas Gulf Coast concentration:Refinery cluster density around Houston-Beaumont-Port Arthur generates economies of scale for sensor calibration services and accelerates technology refresh rates compared to dispersed industrial regions.
Market Restraints
- Palladium and platinum volatility:Catalytic bead sensors depend on noble metal coatings whose spot-market price swings directly compress manufacturer margins and destabilize long-term supply agreements.
- Single-source infrared detector supply:Thermopile and pyroelectric cores for hydrocarbon detection concentrate among a handful of European and Japanese component houses, exposing buyers to allocation risk during demand surges.
- Cross-interference limitations:Electrochemical cells struggle with humidity drift and cross-sensitivity in multi-gas environments, restricting deployment in complex atmospheric monitoring applications.
Strategic Opportunities
- Appalachian shale basin expansion:Pennsylvania and Ohio wellpad automation remains underpenetrated for continuous methane monitoring, presenting whitespace for wireless mesh-network deployments.
- California Air Resources Board mobile source rules:Heavy-duty truck cabin air quality mandates are extending sensor requirements into commercial vehicle HVAC systems, a category with minimal incumbent presence.
- Edge-AI convergence:On-sensor inference engines paired with low-power MEMS platforms enable predictive maintenance alerts without cloud dependency, differentiating offerings in utility substation monitoring.
Industry Challenges
- Calibration technician scarcity:Electrochemical sensor drift correction requires certified personnel whose training pipeline has not kept pace with installation base expansion, extending service response times.
- IECEx/ATEX certification timelines:Hazardous location approvals for new sensing platforms average fourteen months, delaying revenue recognition for product iterations targeting explosive atmosphere applications.
- Legacy 4-20mA integration friction:Wireless retrofit deployments must bridge analog control systems whose signal conditioning architectures were not designed for digital telemetry handshakes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gas Sensors Market |
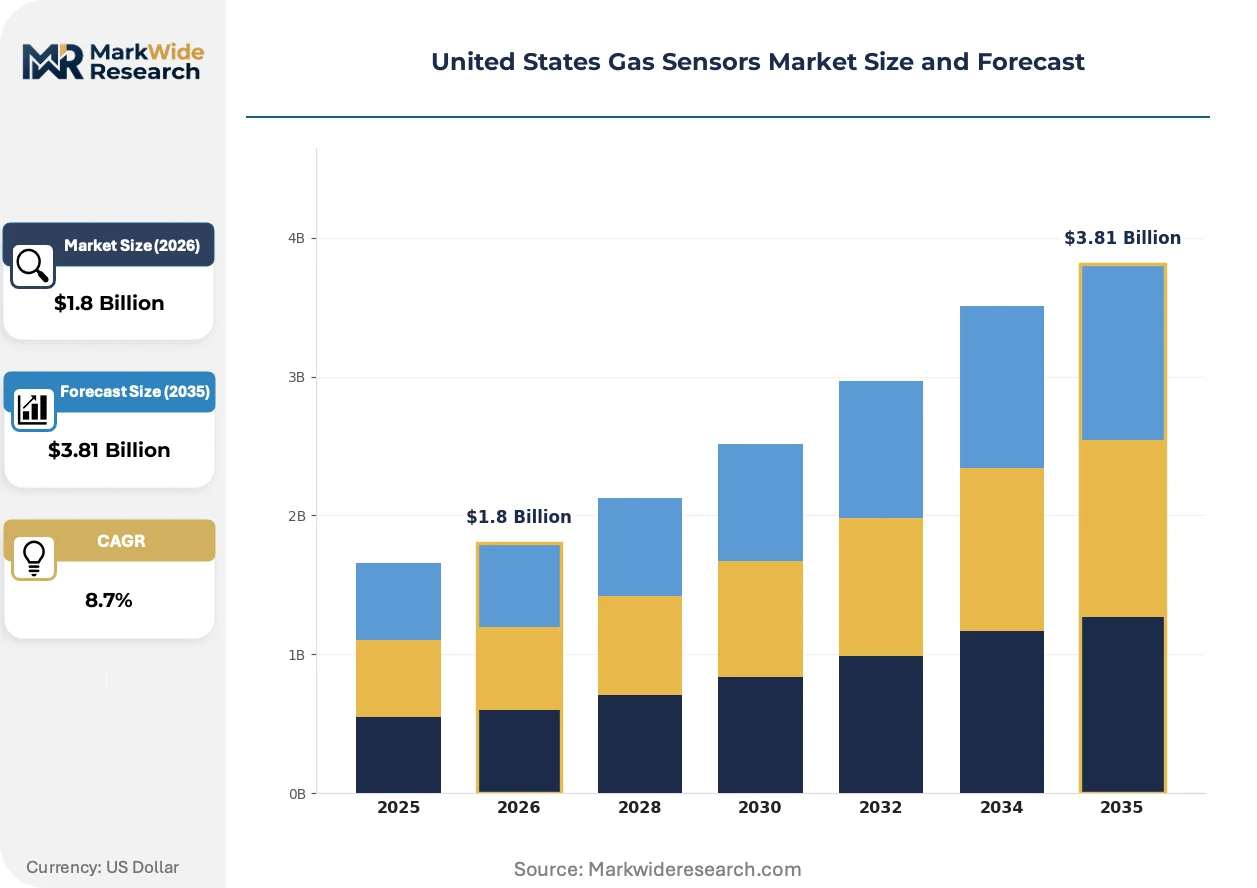
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrochemical, Infrared, Metal Oxide Semiconductor, Photoionization End User: Industrial, Automotive, Residential, Environmental Monitoring Application: Air Quality Monitoring, Emission Testing, Leak Detection, Combustion Control Technology: Wireless, Portable, Fixed, Internet of Things |
| Companies Covered | Honeywell International Inc., MSA Safety Incorporated, Amphenol Advanced Sensors, Emerson Electric Co., Figaro USA Inc., Dragerwerk AG & Co. KGaA, Siemens AG, ABB Ltd., Teledyne Technologies Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gas Sensors Market Evolving Landscape
Sensor architectures are converging around solid-state platforms that eliminate heated filaments and enable battery-powered continuous monitoring in previously inaccessible deployment contexts.
MEMS-based metal oxide semiconductor arrays are migrating from laboratory demonstration to field deployment in industrial hygiene applications. Downstream chemical operators in Louisiana and Texas are piloting these platforms for personal exposure monitoring. The technology is migrating from fixed-point infrastructure toward wearable form factors that compress total cost of ownership through reduced calibration frequency.
EPA's supplemental methane proposal under the Clean Air Act is mandating quarterly monitoring at compressor stations and storage facilities. This regulatory pressure is forcing operators to abandon intermittent manual surveys in favor of continuous emissions monitoring systems. Upstream gathering and boosting segments in the Permian and Bakken formations are responding fastest, driving demand for solar-powered remote sensing nodes.
Buyer contracting patterns are consolidating around multi-year sensor-as-a-service agreements that bundle hardware, calibration, and data analytics. Industrial facility operators in the Gulf Coast corridor are displacing capital purchase models with per-month-per-point pricing. This shift is most visible among midstream pipeline operators seeking to transfer obsolescence risk to vendors while securing guaranteed uptime commitments.
United States Gas Sensors Market Segmentation
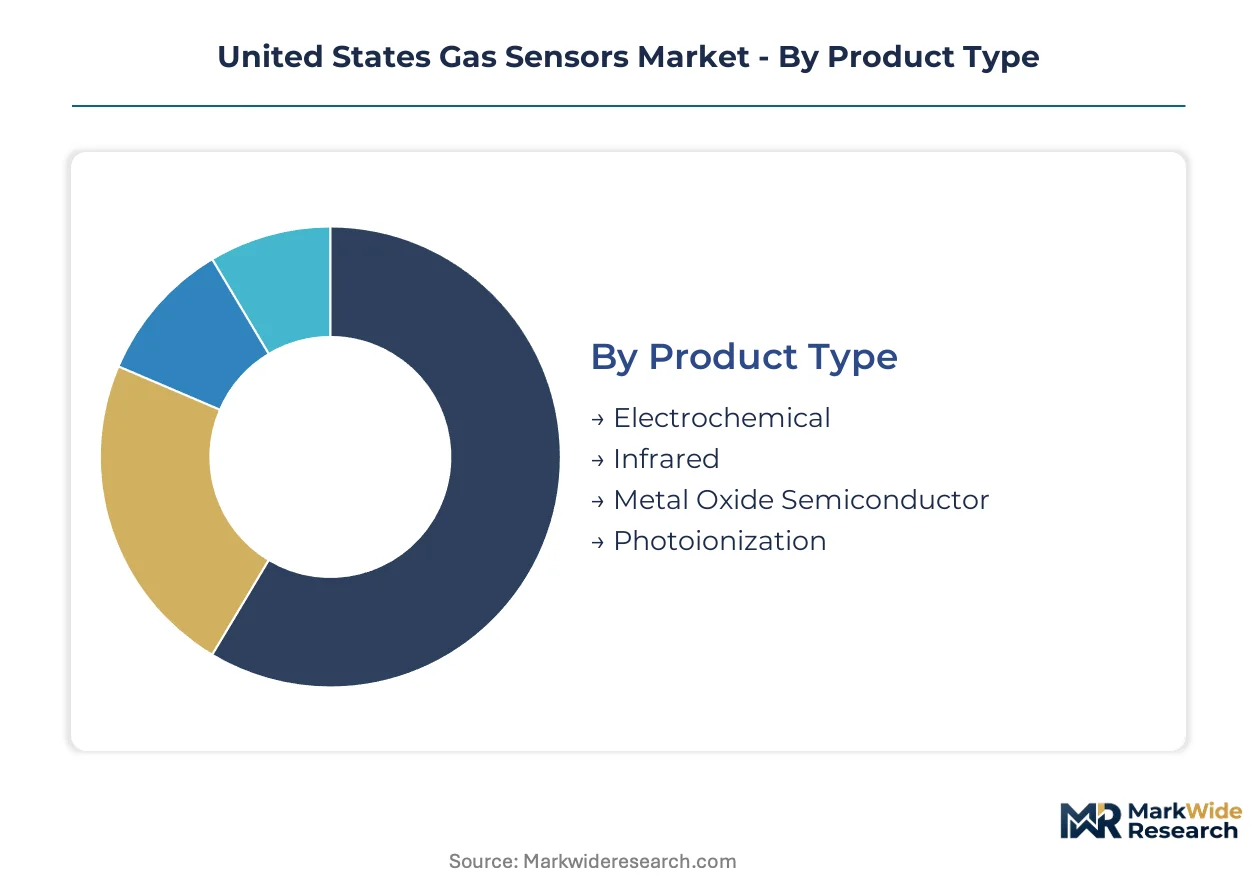
Gas sensor procurement patterns diverge sharply across detection principles and deployment contexts. Electrochemical specificity versus infrared range sensitivity creates fundamentally different value propositions for toxic exposure versus hydrocarbon leak scenarios.
Product Type:
Cost tier stratification separates proven electrochemical platforms from premium infrared systems and emerging solid-state alternatives.
- Electrochemical:Amperometric cells with liquid electrolyte matrices deliver ppm-level specificity for carbon monoxide and hydrogen sulfide. Gulf Coast petrochemical operators specify these for confined-space entry protocols under OSHA permissible exposure limit enforcement.
- Infrared:Non-dispersive absorption spectroscopy measures hydrocarbon concentrations without oxygen dependence. Permian Basin upstream operators deploy these for EPA methane performance standard compliance at compressor stations and tank batteries.
- Metal Oxide Semiconductor:Tin dioxide sensing layers on MEMS substrates achieve sub-ppm sensitivity at reduced power budgets. Pennsylvania shale wellpads are piloting solar-powered nodes for continuous perimeter monitoring.
- Photoionization:Ultraviolet lamp ionization detects volatile organic compounds with 10.6 eV photon energy. California air quality districts specify these for benzene and toluene perimeter monitoring around refineries.
Electrochemical sensors anchor the installed base across industrial safety applications. Infrared platforms are climbing the fastest as methane regulations tighten detection thresholds.
End User:
Application maturity varies dramatically across regulated workplaces, mobile platforms, consumer premises, and ambient monitoring networks.
- Industrial:Process safety and occupational hygiene mandates drive replacement cycles in petrochemical, refining, and midstream pipeline operations. Texas Gulf Coast facility density generates concentrated demand for calibration services and bulk procurement agreements.
- Automotive:Cabin air quality systems and powertrain emissions monitoring integrate miniaturized electrochemical and metal oxide sensors. NHTSA guidelines and California Air Resources Board mobile source rules are extending mandates into heavy-duty truck HVAC systems.
- Residential:Carbon monoxide and natural gas alarms for single-family and multi-tenant housing. Building code adoption varies by state, with California and New York leading mandatory installation requirements.
- Environmental Monitoring:Ambient air quality stations and fence-line monitoring networks for regulatory compliance. EPA criteria pollutant monitoring protocols specify reference-grade instrumentation with documented traceability.
Industrial end users command the replacement revenue. Automotive integration is expanding most quickly as cabin air mandates proliferate.
Application:
Functional deployment contexts range from continuous ambient surveillance to intermittent source testing and emergency response.
- Air Quality Monitoring:Fixed-site stations and mobile mapping platforms measuring ozone, nitrogen dioxide, and particulate precursors. California South Coast Air Quality Management District operates the densest urban sensor network.
- Emission Testing:Stack monitoring and vehicle inspection protocols for regulatory certification. EPA Method 21 and state implementation plans specify instrument performance standards.
- Leak Detection:Fugitive emissions identification in oil and gas production, storage, and transmission. Optical gas imaging and fixed-point sensor arrays are displacing manual survey methods under supplemental methane rules.
- Combustion Control:Oxygen and carbon monoxide feedback for burner optimization in power generation and industrial boilers. Cogeneration facilities in the Northeast specify zirconium oxide and tunable diode laser platforms.
Leak detection applications are gaining share fastest as quarterly monitoring mandates replace intermittent inspection schedules. Air quality monitoring retains the largest installed instrument base.
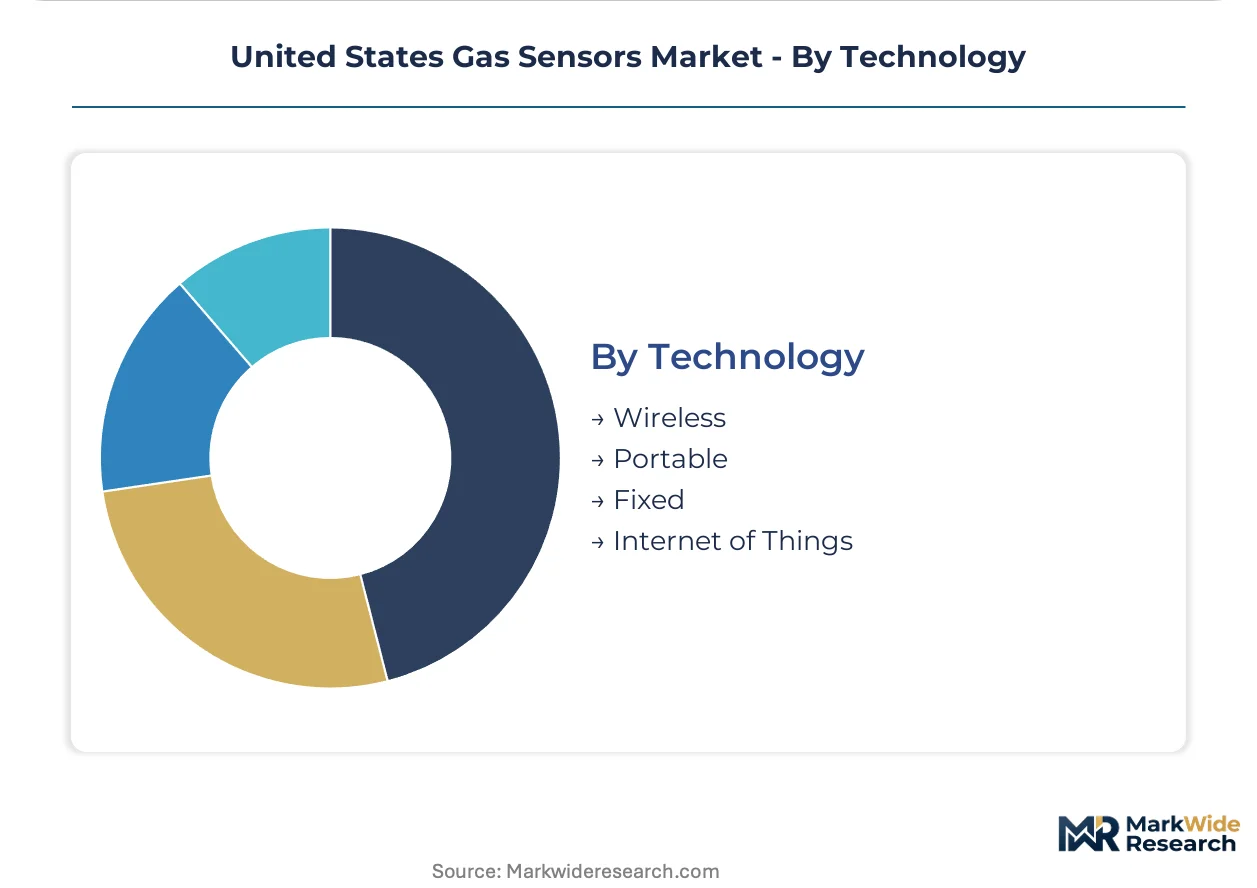
Technology:
Connectivity architecture and form factor portability define procurement tradeoffs between legacy infrastructure and predictive maintenance capabilities.
- Wireless:Mesh-network telemetry eliminating signal cabling and enabling cloud-connected analytics. Appalachian shale operators are deploying solar-powered nodes across dispersed wellpad footprints.
- Portable:Personal monitors and handheld survey instruments for confined-space entry and emergency response. MSA Safety and Industrial Scientific dominate fire department and utility procurement channels.
- Fixed:Permanently installed point detectors and open-path systems for continuous area monitoring. Gulf Coast refineries specify these for process unit perimeter protection.
- Internet of Things:Edge-computing platforms with on-sensor inference and low-power wide-area connectivity. Utility substation pilots are validating predictive maintenance alerts without cloud dependency.
Fixed installations represent the established revenue base. Wireless platforms are expanding most rapidly as retrofit demand accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States gas sensor manufacturers export sensing platforms to Canadian oil sands operators and Mexican petrochemical complexes along integrated North American supply chains. Cross-border calibration service agreements and harmonized OSHA-equivalent standards sustain equipment flows.
Texas Gulf Coast
Refinery cluster density around Houston-Beaumont-Port Arthur compresses replacement cycles for catalytic bead and infrared platforms. EPA methane performance standards and OSHA hydrogen sulfide exposure limits force quarterly sensor swaps. Port Arthur process units deploy continuous emissions monitoring systems at perimeter fence lines.
California
Air quality management districts operate the densest urban sensor networks for ozone and nitrogen dioxide surveillance. California Air Resources Board mobile source rules extend cabin air mandates into heavy-duty truck HVAC systems. South Coast AQMD maintains reference-grade instrumentation across Los Angeles Basin monitoring stations.
Pennsylvania Shale Basins
Appalachian wellpad automation remains underpenetrated for continuous methane monitoring despite EPA supplemental methane proposals. Pennsylvania Department of Environmental Protection leak detection requirements lag Permian Basin stringency. Marcellus drilling pads in Washington and Greene counties pilot solar-powered wireless mesh nodes.
Midwest Industrial Corridor
Ohio River Valley chemical manufacturers specify electrochemical sensors for confined-space entry protocols under OSHA permissible exposure limits. Indiana and Illinois refineries maintain legacy 4-20mA infrastructure requiring wireless retrofit bridges. Whiting refinery complex near Chicago anchors regional calibration service demand.
Gulf of Mexico Offshore
Platform decommissioning and deepwater production sustain demand for explosion-proof fixed-point detectors. Bureau of Safety and Environmental Enforcement well control rules mandate redundant gas detection at drilling facilities. Port Fourchon supply base concentrates pre-deployment sensor testing and certification services.
United States Gas Sensors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. Industrial facility operators consolidate multi-year sensor-as-a-service agreements with vendors bearing calibration infrastructure density. Fire departments and utility operators maintain portable monitor procurement relationships through established safety equipment distributors. Dominant competitive moves include geographic densification of service networks and portfolio expansion from hardware into predictive analytics platforms.
Within the diversified industrial conglomerate tier, Honeywell International Inc. and Emerson Electric Co. occupy positions anchored by distributed sensing networks and process automation integration. MSA Safety Incorporated exemplifies the channel-controlled specialist archetype through fire department and utility procurement relationships. Amphenol Advanced Sensors represents miniaturization-focused component supply to automotive cabin air systems. These three players illustrate divergent strategic postures: infrastructure-anchored systems integration, safety-channel dominance, and automotive-tier component supply.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Amphenol Advanced Sensors |
| Emerson Electric Co. |
| Figaro USA Inc. |
| Dragerwerk AG & Co. KGaA |
| Siemens AG |
| ABB Ltd. |
| Teledyne Technologies Incorporated |
| Others |
Value Network & Pricing Analysis
Houston Ship Channel freight corridors transmit palladium and platinum price volatility directly into catalytic bead sensor manufacturing costs, compressing margins for domestic producers while amplifying price differentiation between electrochemical legacy platforms and solid-state next-generation architectures. This logistics-cost passthrough concentrates pricing power among infrared detector suppliers who command premium positioning for EPA-mandated methane monitoring systems.
Pricing Analysis
Current-generation electrochemical sensors trade at standard-tier price points against prior-generation catalytic bead platforms in economy positioning and next-generation solid-state MEMS architectures capturing premium placement. Pricing stratifies across premium, standard, and economy tiers based on certification grade for hazardous location approvals and volume scale of multi-year sensor-as-a-service agreements. Cost compression in standard-tier electrochemical cells is intensifying because palladium spot-market swings destabilize long-term supply contracts. Industrial facility operators in Gulf Coast petrochemical corridors demonstrate least price sensitivity due to regulatory replacement mandates, while residential carbon monoxide alarm buyers exhibit highest elasticity.
Supply Chain Analysis
Export control restrictions on advanced infrared detector technology limit thermopile and pyroelectric core flows from European and Japanese component houses to domestic sensor integrators. Manufacturing concentration centers on Japan, Germany, and the United States for precision optical components while China dominates MEMS substrate fabrication and South Korea supplies specialized semiconductor packaging. Raw material dependencies include palladium and platinum for catalytic coatings, tin dioxide nanopowders for metal oxide sensing layers, and lithium-ion cells for wireless node power systems. Single-source vulnerability concentrates in thermopile detector supply, exposing buyers to allocation risk during demand surges. Distribution runs through industrial safety equipment distributors for portable monitors and direct vendor relationships for fixed-point infrastructure deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States gas sensors market functions as a defensive-moat industry where regulatory entrenchment creates durable competitive positioning. OSHA permissible exposure limit enforcement and EPA methane performance standards generate mandatory replacement demand that insulates established players from demand volatility.
For Market Incumbents: Build calibration infrastructure density as the primary defensive moat by expanding certified technician networks across Texas Gulf Coast and Appalachian shale basins to capture sensor-as-a-service recurring revenue. Invest in IECEx/ATEX certification pipelines to accelerate hazardous location approval timelines and defend against emerging solid-state competitors. Vertical integration into noble metal coating supply buffers margin pressure from palladium price volatility. For New Entrants and Emerging Players: Pursue whitespace in Pennsylvania and Ohio wellpad automation where continuous methane monitoring penetration lags Permian Basin standards. Target solar-powered wireless mesh network deployments for dispersed shale footprints where incumbent service density remains thin. Lead with edge-AI inference engines as differentiation in utility substation predictive maintenance pilots. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates seeking to divest non-core sensing divisions lacking calibration service infrastructure. Long-term viability hinges on regulatory mandate durability rather than technology disruption risk. Monitor EPA supplemental methane proposal implementation timelines as the critical inflection signal for infrared platform demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Expansion | Densifying certified technician networks across Gulf Coast petrochemical corridors captures recurring sensor-as-a-service revenue streams. |
| Wireless Mesh Network Deployment | Solar-powered telemetry nodes in Appalachian shale basins displace manual survey methods under tightening EPA methane rules. |
| Edge-AI Platform Integration | On-sensor inference engines enable predictive maintenance alerts without cloud dependency in utility substation monitoring. |
| Backward Integration into Noble Metal Supply | In-house palladium coating capacity buffers margin compression from spot-market volatility in catalytic bead production. |
| IECEx/ATEX Certification Acceleration | Compressing fourteen-month hazardous location approval timelines unlocks faster revenue recognition for explosive atmosphere products. |
Research Methodology
Initial hypotheses were tested against primary input from plant safety managers at Gulf Coast refineries, calibration service technicians, utility substation engineers, and industrial procurement officers, then refined through secondary validation against EPA enforcement databases, OSHA permissible exposure limit documentation, and SEC filings from publicly traded sensor manufacturers. Bottom-up unit economics for sensor replacement cycles were triangulated with top-down regulatory mandate impact modeling across the projection horizon.
Demand-supply balance framing anchored the analytical framework throughout the modeling period, with segmentation across detection principle, end-use industry, connectivity architecture, and geographic regulatory cluster. CAGRs were derived from replacement cycle compression analysis under tightening OSHA and EPA standards, incorporating inputs from methane emissions monitoring mandate expansion and electrochemical sensor drift correction frequency requirements.
Sensitivities concentrate around EPA methane performance standard revision timelines and state-level net-zero commitment acceleration. Forecasts reflect assumptions regarding regulatory enforcement continuity and noble metal price stability. Material shifts in OSHA permissible exposure limit stringency or breakthrough solid-state sensitivity thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Global E-Nose Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
North America Occupancy Sensors Market
Sensors and Controls
Acoustic Respiration Sensors Market
Sensors and Controls
Temperature Monitoring System Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
Bee Hive Monitoring Sensor Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
Asia Pacific Fingerprint Sensor Market
Sensors and Controls
Middle East and Africa Touch Sensor Market
Sensors and Controls
MEMS-Based Oscillator Market
Sensors and Controls
Home Automation Sensors Market
Sensors and Controls
NB-IoT Smart Meter Market