
 Gimbal Market | 2026-2036
Gimbal Market Size, Share, and Industry Trends Forecast 2026-2036
Gimbal Market Analysis
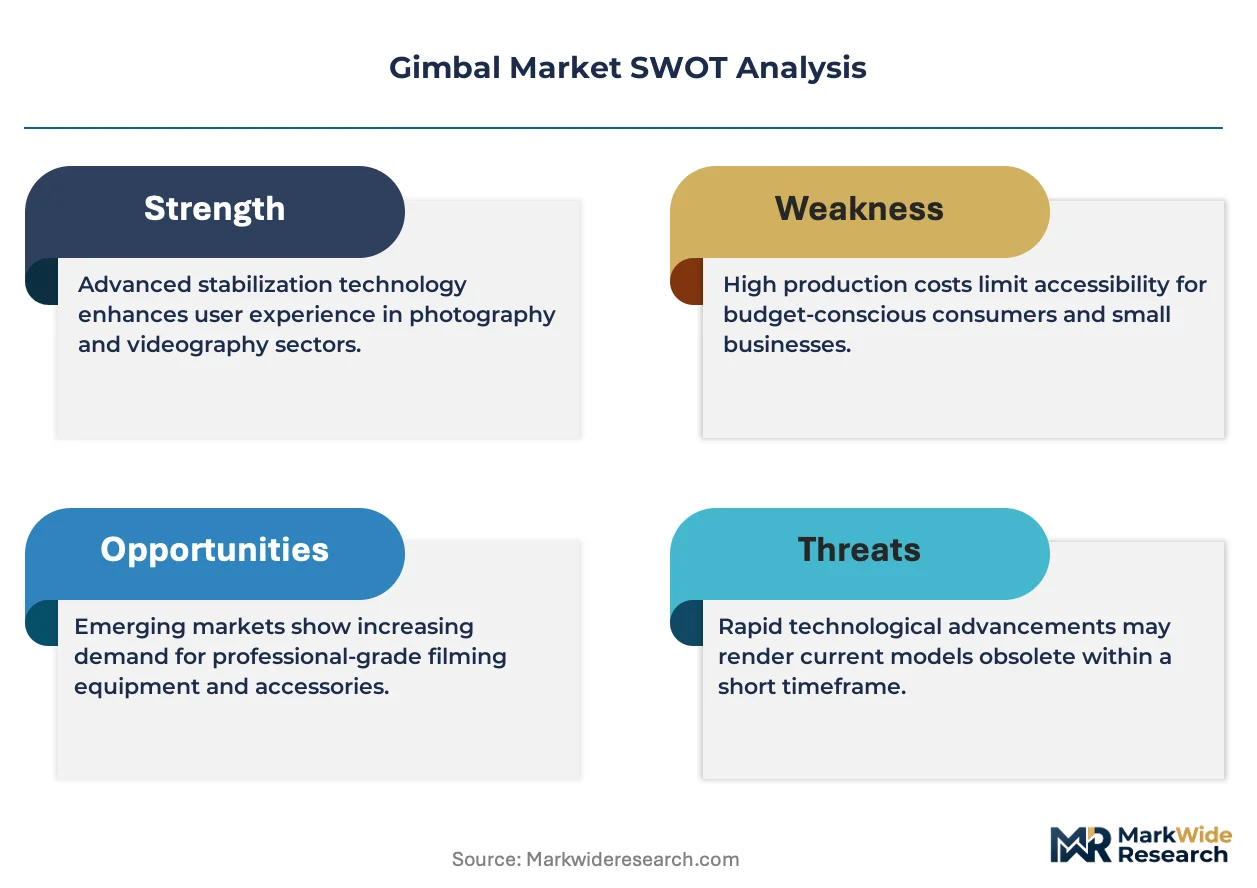
CE marking requirements under the EU's Radio Equipment Directive is repositioning the cost-of-entry calculus for electronic gimbal manufacturers seeking European market access. DJI leverages its Shenzhen-based vertical manufacturing to sustain price competitiveness across professional and consumer tiers. Freefly Systems specializes in high-end cinema rigs, anchoring its brand among Hollywood production houses and commercial cinematographers.
A gimbal is a pivoted support system that permits rotation around a single axis, with modern variants employing brushless motors, inertial measurement units, and gyroscopic sensors to maintain camera stability within 0.01-degree precision. Electric gimbals dominate volume shipments due to their balance of cost and performance, while robotic gimbals represent the fastest-expanding technology segment as automated cinematography gains traction in broadcast and live event production. Three-axis stabilization commands the largest application share across drone stabilization and professional videography, where payload capacity and wind resistance determine purchasing decisions.
The FCC in the United States enforces electromagnetic compatibility standards that constrain transmitter power and frequency allocation in wireless gimbal systems, while China's MIIT imposes network access licenses on Bluetooth-enabled models sold domestically. Japan's METI promotes JIS standards for precision mechanical components that influence supplier qualification for premium brands. Stakeholders must monitor how divergent radio certification timelines across these jurisdictions affect product launch sequencing and inventory allocation.
Market Dynamics
Brushless motor miniaturization and Shenzhen's component ecosystem are compressing production cycles while professional cinematography demands push precision thresholds toward sub-0.01-degree stabilization tolerances.
Growth Catalysts
- Drone cinematography expansion:Commercial aerial videography mandates three-axis stabilization for wind compensation above 30 knots, driving replacement cycles in broadcast and inspection fleets.
- CE marking harmonization:The EU's Radio Equipment Directive streamlines cross-border certification for wireless gimbal systems, reducing redundant testing costs for manufacturers targeting multiple member states.
- Live event automation:Robotic camera arms in sports broadcasting and concert production require precision gimbal heads for pre-programmed motion sequences.
Market Restraints
- Rare earth magnet volatility:Neodymium price swings in Chinese processing facilities transmit directly to brushless motor cost structures, squeezing margin on mid-tier consumer models.
- Shenzhen supply concentration:Over 70 percent of brushless motor and IMU sourcing clusters in Guangdong province creates geographic vulnerability to port congestion or power rationing.
- Bluetooth coexistence interference:2.4 GHz spectrum saturation in dense urban environments degrades wireless gimbal responsiveness, limiting reliable operating range.
Strategic Opportunities
- India content creator surge:YouTube and short-form video platforms in tier-2 Indian cities drive first-time gimbal adoption among non-professional videographers seeking production value.
- AI-driven subject tracking:Computer vision algorithms embedded in gimbal firmware enable autonomous framing for solo operators in documentary and wedding videography.
- FCC Part 15 unlicensed expansion:New frequency allocations for ultra-wideband positioning allow millimeter-precise camera tracking without set infrastructure in studio environments.
Industry Challenges
- Embedded firmware talent scarcity:Kalman filter optimization and real-time sensor fusion expertise concentrates in aerospace and automotive sectors, poaching from gimbal engineering teams.
- Multi-jurisdiction certification lag:Sequential FCC, CE, and MIIT approval timelines stretch product launches across 14-18 months, freezing inventory capital.
- Legacy camera mount incompatibility:Proprietary quick-release plates from cinema camera manufacturers fragment accessory ecosystems, forcing gimbal makers to maintain multiple SKUs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gimbal Market |
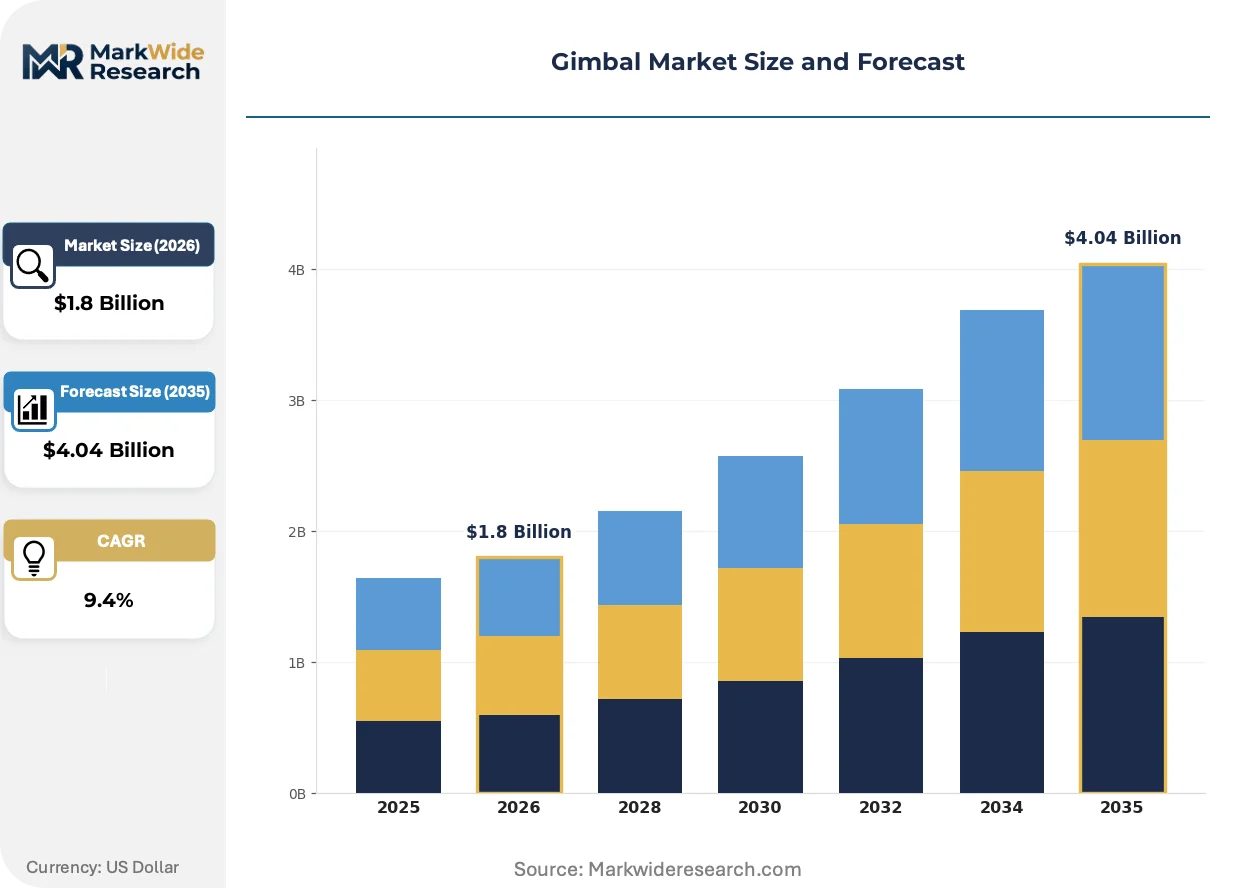
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Mechanical, Electric, Magnetic, Hybrid Application: Photography, Videography, Drone Stabilization, Virtual Reality End User: Professional Creators, Hobbyists, Commercial Users, Cinematographers Technology: 3-Axis, 2-Axis, Smartphone Stabilizers, Robotic Gimbals |
| Companies Covered | Glidecam Industries, Moza, DJI, Hohem Technology, Freefly Systems, Zhiyun, Gudsen Technology, EVO Gimbals, FeiyuTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gimbal Market Emerging Trajectories
Active stabilization hardware is converging with computational imaging pipelines, shifting competitive advantage from mechanical precision toward software-defined motion control and edge AI processing.
Carbon fiber composite construction is integrating into high-payload cinema gimbals to achieve 40 percent weight reduction without sacrificing torsional rigidity. Hollywood production houses and commercial rental fleets are adopting these platforms for handheld operation across 12-hour shooting days. This material transition is compressing the performance gap between premium rigs and mid-tier systems, forcing incumbents to differentiate through software ecosystems rather than hardware specifications alone.
Japan's METI has revised JIS B 0153 precision mechanical standards to include gyroscopic stabilization systems, mandating documented calibration protocols for equipment used in broadcast transmission. Domestic manufacturers must submit third-party verification of angular drift rates below 0.005 degrees per hour. Premium brands serving NHK and commercial broadcasters are responding by establishing captive calibration facilities in Yokohama and Osaka to maintain supplier qualification status.
Direct-to-creator distribution through TikTok Shop and specialized videography platforms is displacing traditional camera retail channels for entry-level gimbal sales. Shenzhen-based brands are building native storefronts with integrated tutorial content, collapsing the education-to-purchase funnel from weeks to minutes. This channel compression is most visible in Southeast Asian markets where mobile-first commerce dominates and physical specialty retail infrastructure remains underdeveloped.
Gimbal Market Segmentation
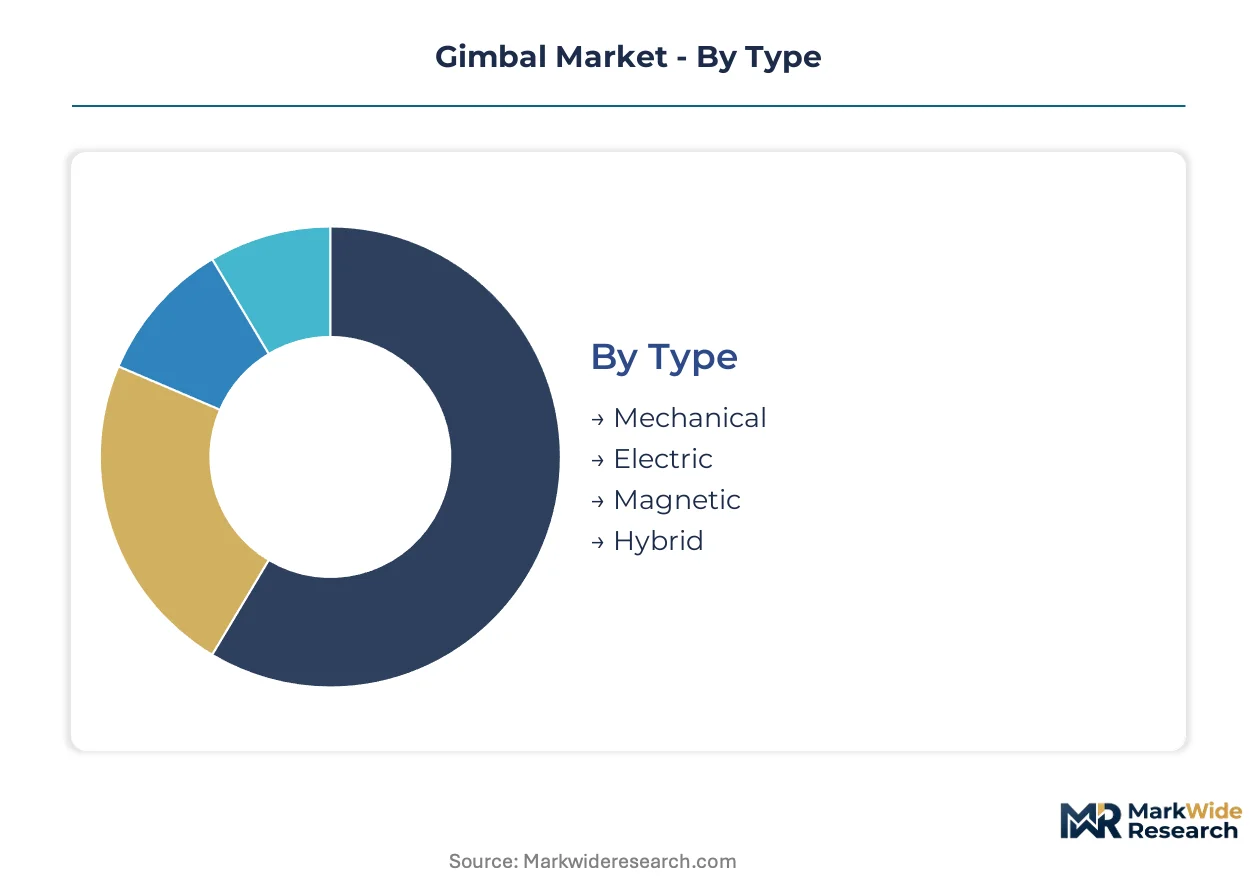
Segmentation in the gimbal market exposes divergent engineering requirements across stabilization technologies and user workflows. Professional cinematography demands sub-0.01-degree precision tolerances, while consumer applications prioritize portability and automated subject tracking over absolute accuracy.
Type:
Capital intensity varies sharply across stabilization architectures, with electric systems requiring the most substantial upfront investment in brushless motor R&D and IMU calibration infrastructure.
- Electric:Brushless motor arrays paired with gyroscopic sensors and inertial measurement units deliver active stabilization within 0.01-degree precision. Demand concentrates in professional videography and drone cinematography, where wind compensation above 30 knots mandates three-axis electric architectures. Shenzhen's component ecosystem compresses production cycles while maintaining performance thresholds.
- Mechanical:Passive pivot systems relying on counterweights and bearing assemblies offer stabilization without power consumption. Hobbyists in emerging markets favor these platforms for their immunity to battery failure during extended outdoor shoots.
- Magnetic:Electromagnetic levitation mechanisms enable frictionless rotation with minimal mechanical wear. Research laboratories and specialized broadcast applications absorb limited current volume.
- Hybrid:Combined mechanical-electric architectures balance power efficiency with active correction capabilities. Commercial inspection fleets deploy hybrid systems where battery weight constraints intersect with stabilization requirements.
Electric systems absorb the bulk of installed capacity; robotic gimbals are expanding most quickly as automated cinematography gains traction in broadcast and live event production.
Application:
Workflow integration requirements shape purchasing decisions, with drone stabilization demanding the most stringent environmental resilience specifications.
- Videography:Professional content creation drives replacement cycles in broadcast, wedding documentation, and commercial production. Three-axis stabilization with payload capacities exceeding 4.5 kilograms anchors purchasing criteria for cinema camera operators.
- Drone Stabilization:Aerial cinematography mandates wind resistance above 30 knots and rapid angular correction for flight-induced vibration. Commercial inspection fleets and broadcast operators in China and the United States dominate procurement volume.
- Photography:Still-image stabilization prioritizes compact form factors and rapid deployment. Travel photographers and social media creators favor smartphone-integrated and mirrorless-compatible systems.
- Virtual Reality:360-degree capture requires specialized gimbal architectures that minimize mechanical obstruction in the capture sphere. Immersive content studios and real estate visualization firms constitute the primary demand base.
Videography commands the largest revenue share; drone stabilization is climbing the fastest as commercial aerial imaging penetrates inspection and agricultural monitoring verticals.
End User:
Price elasticity diverges dramatically across user categories, with commercial operators accepting 10-15x premiums over hobbyist price ceilings for equivalent mechanical specifications.
- Professional Creators:YouTube studios, independent filmmakers, and wedding videographers balance production value against equipment portability. Tier-2 Indian cities and Southeast Asian markets are driving first-time adoption through TikTok Shop and mobile-first commerce channels.
- Cinematographers:Hollywood production houses and commercial rental fleets demand carbon fiber construction for 40 percent weight reduction across 12-hour shooting days. NHK and premium broadcasters in Japan require documented calibration protocols under revised JIS B 0153 standards.
- Commercial Users:Industrial inspection, agricultural monitoring, and security operations prioritize durability and extended temperature operating ranges over stabilization precision.
- Hobbyists:Entry-level smartphone stabilizers and compact mirrorless systems dominate purchasing patterns. Direct-to-creator distribution through tutorial-integrated storefronts collapses education-to-purchase timelines from weeks to minutes.
Professional creators represent the deepest installed base; cinematographers are gaining share fastest as carbon fiber platforms compress the performance gap between premium and mid-tier systems.
Technology:
Sensor fusion complexity escalates with axis count, with 3-axis systems demanding the most sophisticated Kalman filter implementation and real-time gyroscopic compensation.
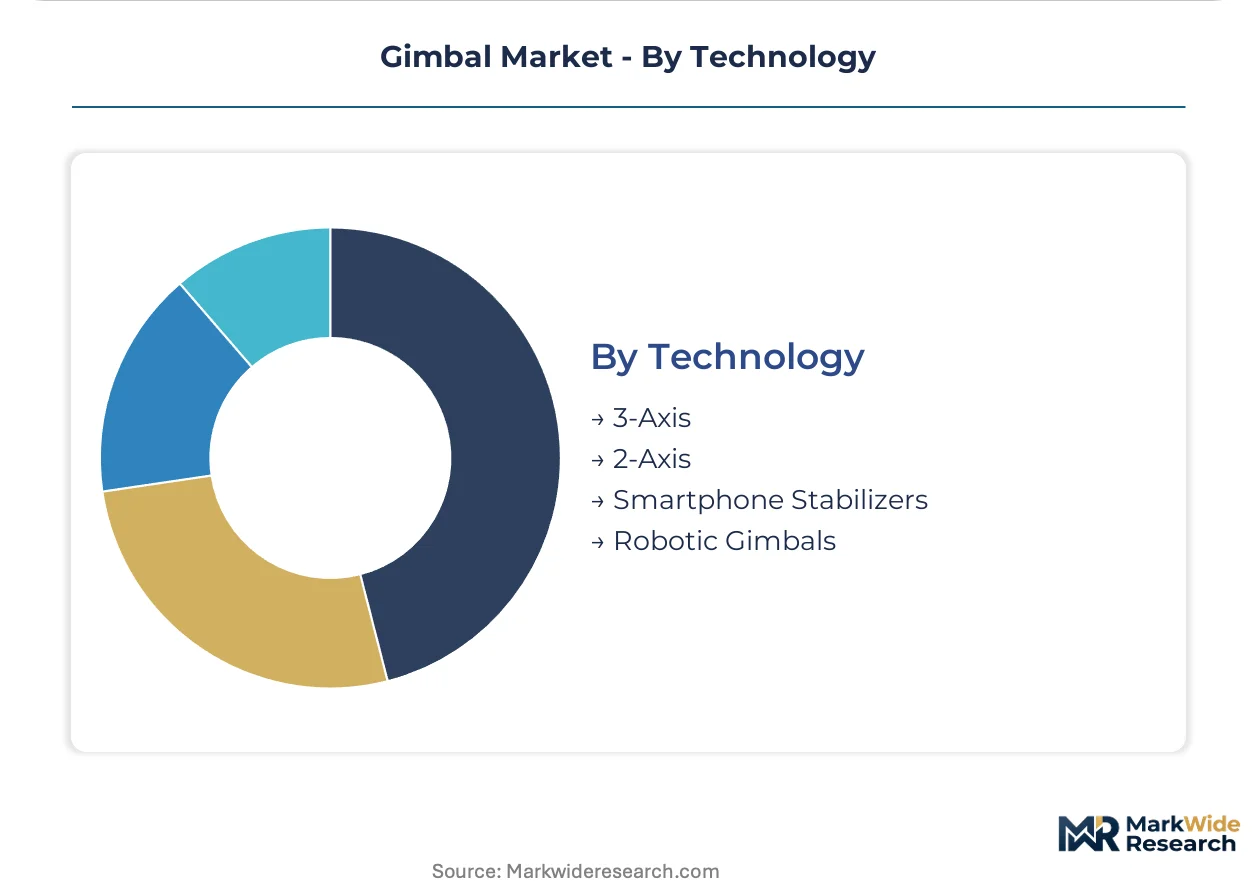
- 3-Axis:Pan, tilt, and roll correction via independent brushless motor arrays. Professional videography and drone stabilization anchor demand, with payload capacity and wind resistance determining procurement decisions across broadcast and inspection fleets.
- Robotic Gimbals:Pre-programmed motion sequences and AI-driven subject tracking enable solo operator workflows in sports broadcasting and concert production. Computer vision algorithms embedded in firmware support autonomous framing for documentary applications.
- Smartphone Stabilizers:Compact single-hand operation with integrated Bluetooth control. Content creators in tier-2 Indian cities and Southeast Asian markets drive volume through mobile-first commerce penetration.
- 2-Axis:Limited pan-tilt correction without roll stabilization. Budget-conscious hobbyists and legacy drone platforms sustain residual demand.
3-axis systems hold the dominant technology position; robotic gimbals are gaining share fastest as live event automation and AI-driven subject tracking reshape broadcast production workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen's Qianhai Free Trade Zone accelerates component clustering for brushless motor and IMU production, concentrating upstream supply for global gimbal assembly networks.
United States
Hollywood production houses and commercial rental fleets in Los Angeles drive demand for carbon fiber cinema rigs with sub-0.01-degree precision. The FCC enforces electromagnetic compatibility standards under Part 15 that constrain transmitter power in wireless gimbal systems. Austin's tech corridor hosts firmware development operations for AI-driven subject tracking algorithms.
China
Commercial drone cinematography and live event automation in Beijing and Shanghai propel three-axis electric system procurement. MIIT imposes network access licenses on Bluetooth-enabled models sold domestically, extending certification timelines. Shenzhen's hardware ecosystem in Guangdong province feeds global supply chains with compressed production cycles.
Japan
NHK and premium broadcasters in Tokyo require documented calibration protocols under revised JIS B 0153 standards for gyroscopic stabilization. METI promotes precision mechanical component standards that influence supplier qualification. Yokohama and Osaka host captive calibration facilities maintaining domestic manufacturer compliance status.
Germany
Industrial inspection fleets and agricultural monitoring operators in Bavaria prioritize durability and extended temperature ranges. CE marking requirements under the EU's Radio Equipment Directive streamline cross-border certification for wireless systems. Munich's engineering clusters support precision mechanical R&D for professional cinematography applications.
India
YouTube studios and wedding videographers in tier-2 cities drive first-time adoption through TikTok Shop and mobile-first commerce channels. BIS certification requirements apply to electronic stabilizers sold domestically. Bengaluru's content creator economy anchors demand for smartphone-compatible entry-level systems.
Gimbal Market Vendor Landscape
Shenzhen-based producers anchor the volume tier; California specialists hold premium positioning for cinema-grade applications. The vendor structure fragments across three performance tiers with limited cross-tier mobility. Archetypes include vertically integrated hardware conglomerates, software-defined motion control specialists, and regional assembly operations serving price-sensitive emerging markets. Competitive moves center on backward integration into brushless motor production and strategic partnerships for AI firmware licensing.
Within the premium cinema tier, Freefly Systems and DJI exemplify divergent specialization strategies. Glidecam Industries represents legacy mechanical stabilization expertise transitioning toward hybrid architectures. Zhiyun occupies a position bridging consumer accessibility with professional feature sets, while FeiyuTech anchors the smartphone stabilizer segment through direct-to-creator distribution channels.
| Leading Market Players |
|---|
| Glidecam Industries |
| Moza |
| DJI |
| Hohem Technology |
| Freefly Systems |
| Zhiyun |
| Gudsen Technology |
| EVO Gimbals |
| FeiyuTech |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between CE-marked professional systems and uncertified consumer imports creates divergent margin structures that propagate backward into component sourcing strategies. Shenzhen manufacturers serving European broadcasters absorb third-party testing costs for Radio Equipment Directive compliance, while direct-to-creator channels for smartphone stabilizers bypass formal certification entirely, compressing both price floors and supplier qualification thresholds.
Pricing Analysis
Short-lead-time premiums dominate procurement negotiations, with Hollywood rental houses paying 15-20 percent markups for carbon fiber cinema rigs available within 48 hours against 6-week factory-direct timelines. Pricing stratifies across professional, prosumer, and entry-level tiers, with CE certification and JIS B 0153 calibration protocols commanding measurable premiums over uncertified alternatives. Cost compression in the prosumer segment is intensifying because neodymium price volatility transmits directly through brushless motor bill-of-materials. Hobbyists purchasing through TikTok Shop exhibit highest price sensitivity, while cinematographers accepting 12-hour shooting-day ergonomics prioritize weight reduction over unit cost.
Supply Chain Analysis
Direct-to-creator distribution channels handle volume demand from Southeast Asian and Indian markets, collapsing traditional camera retail margins. Component sourcing draws from China's Guangdong province for brushless motors and IMUs, Japan for precision gyroscopic sensors, and South Korea for advanced semiconductor foundry services. Single-source vulnerability concentrates in Shenzhen's Qianhai Free Trade Zone, where over 70 percent of global gimbal assembly capacity clusters within 50 kilometers. Distribution runs through specialized videography platforms, mobile commerce storefronts, and legacy camera retail for professional cinematography procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brushless motor and IMU fabrication capacity constraints in Guangdong province prop pricing power for qualified suppliers, creating durable margin structures for vertically integrated incumbents while raising entry barriers for assembly-only competitors.
For Market Incumbents: Lock in captive calibration facilities in Yokohama and Osaka to maintain JIS B 0153 supplier qualification for NHK and premium broadcaster contracts. Secure multi-year offtake agreements with Guangdong rare earth processors to insulate against neodymium price volatility threatening mid-tier consumer margins. Firmware talent poaching from aerospace and automotive sectors demands accelerated Kalman filter optimization training programs. For New Entrants and Emerging Players: Enter via AI-driven subject tracking modules licensable to established hardware platforms, avoiding capital-intensive brushless motor R&D. Tier-2 Indian cities present the most penetrable geography, with wedding videographers and YouTube studios seeking production value without Hollywood-tier equipment investments. Native TikTok Shop storefronts with integrated tutorial content collapse education-to-purchase timelines from weeks to minutes. For Investors and Strategic Acquirers: Re-rating potential sits with software-defined motion control specialists given convergence of active stabilization hardware with computational imaging pipelines. Long-term viability favors firms controlling edge AI processing firmware rather than carbon fiber mechanical platforms facing commodity compression. Watch for FCC Part 15 ultra-wideband frequency allocation finalization as inflection indicator for millimeter-precise tracking adoption in studio environments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brushless Motors | Captive Guangdong production insulates margin against neodymium price volatility. |
| AI Firmware Licensing Partnerships | Subject tracking algorithms differentiate hardware platforms beyond mechanical specifications. |
| CE Marking Fast-Track Investment | Radio Equipment Directive compliance accelerates European market access timelines. |
| Direct-to-Creator Distribution Buildout | TikTok Shop native storefronts capture Southeast Asian and Indian first-time adoption. |
| Captive Calibration Facility Establishment | Yokohama and Osaka facilities secure JIS B 0153 qualification for NHK contracts. |
Methodological Framework
Trade databases, customs filings, and regulatory submission records formed the secondary backbone, supplemented by hyperscaler capex disclosures and component import manifests. Primary interviews with firmware engineering directors, broadcast equipment procurement managers, wedding videography studio operators, and Shenzhen manufacturing executives combined with secondary validation. Bottom-up and top-down triangulation cross-checked unit shipment estimates against bill-of-materials cost structures and regional adoption patterns.
Bottom-up modeling aggregated segment-level volume and value outputs across the projection horizon, while top-down approaches tested aggregate market sizing against macroeconomic indicators. Segmentation dimensions included stabilization technology, application workflow, end-user price elasticity, and axis-count sensor fusion complexity. CAGRs derived from regression analysis of historical adoption curves adjusted for regulatory timeline impacts and component cost trajectories. Forecast inputs incorporated FCC, CE, and MIIT certification lag distributions and rare earth magnet price correlation coefficients.
Revisions become necessary when multi-jurisdiction approval timelines extend beyond 18 months or when Guangdong power rationing disrupts brushless motor output. Forecasts reflect documented assumptions regarding firmware talent availability and Bluetooth coexistence interference mitigation rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Brazil Electric Power Steering (EPS) Sensor Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
Room Pressure Monitor Market
Sensors and Controls
Sensor Signal Conditioner (SSC) Ics Market
Sensors and Controls
Mexico Smart Ventilation Fans Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
APAC Pressure Sensors Market
Sensors and Controls
SCR Dosing Control Modules Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Aeroderivative Sensor Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Body Worn Antenna Market