
 Europe Human Machine Interface Market | 2026-2036
Europe Human Machine Interface Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Human Machine Interface Market Intelligence
CE marking under the EU Machinery Directive is unwinding the competitive landscape for industrial HMI suppliers. Siemens AG leverages its embedded automation stack to dominate large-scale manufacturing deployments across the continent. ABB Ltd anchors its position through deep integration with robotics and process control systems. Schneider Electric SE differentiates via energy management-linked interface platforms that extend its building automation footprint.
A Human Machine Interface constitutes the hardware and software layer enabling bidirectional interaction between operators and machines, typically incorporating touch-sensitive display matrices, industrial-grade processors, and real-time communication protocols such as OPC UA or EtherCAT for deterministic control. The primary purpose centers on reducing cognitive load while accelerating response times in high-stakes operational environments. Touchscreen interfaces lead the product type category due to their ubiquity in both consumer-facing and industrial settings, while voice recognition represents the fastest-expanding segment as natural language processing migrates into hands-critical applications. Cloud-based technology deployments are capturing disproportionate investment as manufacturers seek remote diagnostics and predictive maintenance capabilities.
The EU AI Act and GDPR impose stringent requirements on data processing transparency and user consent within intelligent HMI systems, compelling vendors to redesign architecture for edge-local inference. ECHA's REACH restrictions on hazardous substances in electronics further constrain material selection for display assemblies and circuit substrates. The F-Gas Regulation drives thermal management redesigns for outdoor and high-temperature HMI installations. Stakeholders must weigh compliance investment against the fragmentation risk of divergent national implementation timelines for cyber resilience mandates.
Market Dynamics
The EU Cyber Resilience Act is forcing HMI vendors to rebuild software architectures around hardware-backed authentication, creating a compliance-driven technology refresh cycle that favors suppliers with embedded security stacks over standalone interface providers.
Growth Catalysts
- Electric vehicle cockpit procurement:German automotive OEMs are expanding HMI orders for next-generation EV interiors, prioritizing large-format touch surfaces and haptic feedback systems.
- Cloud-based predictive maintenance:Industrial manufacturers are migrating HMI deployments to edge-cloud hybrid architectures for remote diagnostics and downtime reduction.
- REACH compliance redesigns:ECHA restrictions on hazardous substances are accelerating material substitution programs for display assemblies and circuit substrates.
Market Restraints
- Semiconductor input volatility:Industrial-grade processor and display driver shortages continue to constrain production schedules and inflate bill-of-material costs.
- Supplier concentration risk:High-performance touchscreen controller ICs depend heavily on Taiwanese foundry capacity, exposing European integrators to geopolitical supply disruptions.
- GDPR inference limitations:The EU AI Act and GDPR jointly restrict cloud-based data processing for intelligent HMI systems, forcing costly edge-local compute deployments.
Strategic Opportunities
- Polish industrial automation corridor:Manufacturing investment in Lower Silesia and the Warsaw region is outpacing local HMI supplier presence, creating first-mover advantages for entrants.
- Voice recognition integration:Natural language processing migration into hands-critical applications opens new segments in surgical robotics and cleanroom manufacturing.
- F-Gas thermal redesigns:The F-Gas Regulation mandates new cooling architectures for outdoor and high-temperature HMI installations, rewarding vendors with advanced thermal engineering capabilities.
Industry Challenges
- OPC UA certification timelines:Real-time communication protocol compliance for deterministic industrial control is extending product validation cycles by six to nine months.
- Legacy EtherCAT integration:Brownfield manufacturing facilities require complex protocol bridging to connect modern touchscreen interfaces with existing fieldbus infrastructures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Human Machine Interface Market |
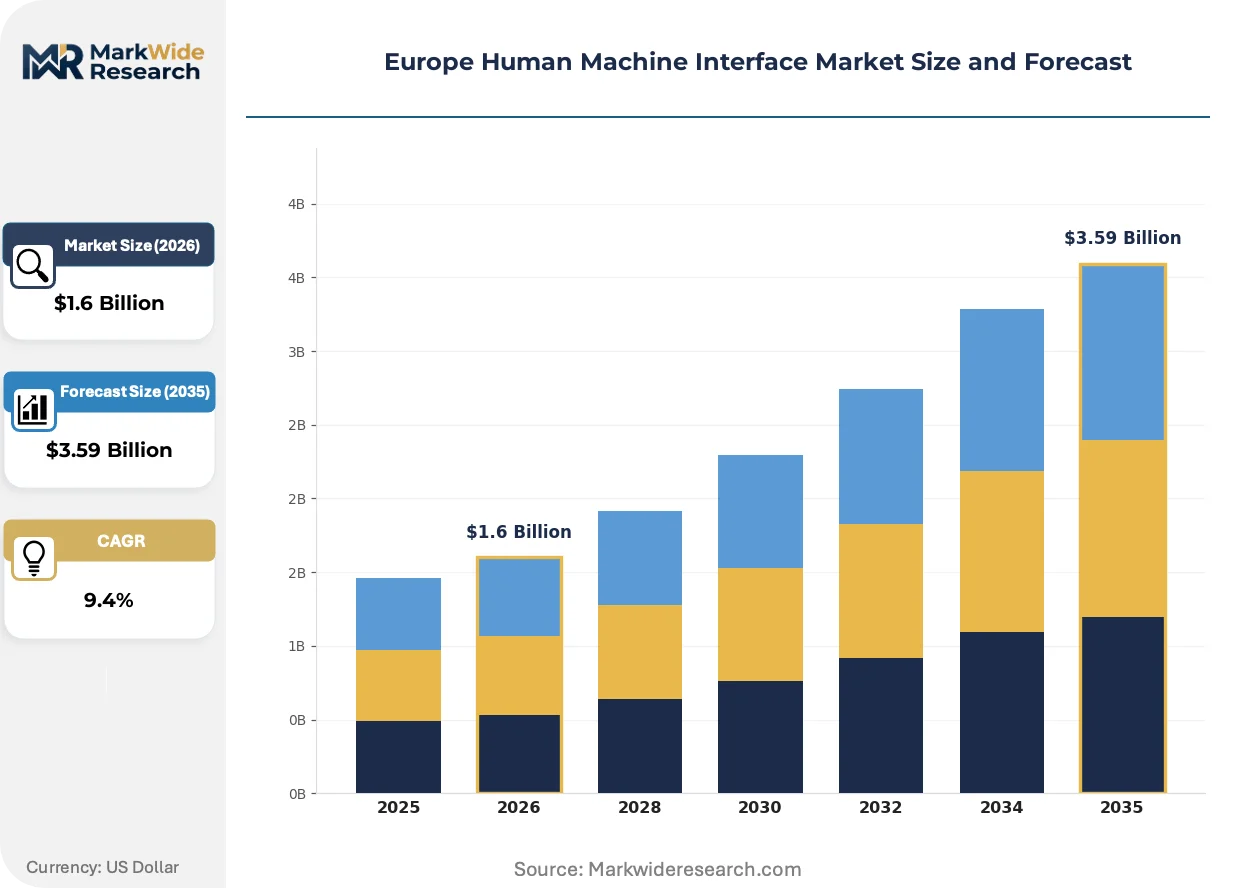
| Market Size in 2026 | $1.6 Billion |
| Market Size in 2035 | $3.59 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Touchscreen, Keypad, Button, Voice Recognition Technology: Embedded, Standalone, Software-Based, Cloud-Based End User: Automotive, Consumer Electronics, Healthcare, Industrial Automation Application: Smart Homes, Wearable Devices, HVAC Systems, Gaming |
| Companies Covered | Siemens AG, ABB Ltd, Rockwell Automation Inc., Honeywell International Inc., Schneider Electric SE, Emerson Electric Co., OMRON Corporation, Yokogawa Electric Corporation, General Electric Co., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Human Machine Interface Market Strategic Shifts & Innovations
Three intersecting developments are restructuring how operators interact with industrial and automotive systems across the continent, compressing hardware footprints while expanding software-defined functionality.
Haptic feedback actuator arrays are replacing mechanical switches in safety-critical automotive and medical applications. Tier-1 suppliers in Stuttgart and Munich are qualifying piezoelectric and electrostatic solutions for production volumes. This transition is miniaturizing cockpit control surfaces while preserving tactile confirmation for eyes-forward operation.
The EU AI Act's risk-based classification system imposes documentation and transparency obligations on HMI systems incorporating machine learning. Industrial automation vendors must now maintain algorithmic audit trails for operator-facing decision support tools. German machinery OEMs are most affected, with engineering teams rearchitecting inference pipelines for edge-local execution to avoid cloud data transfer restrictions.
Subscription-based HMI software licensing is displacing perpetual purchase models among mid-sized European manufacturers. Cloud platform providers are capturing recurring revenue streams that hardware integrators previously monopolized. This shift is most visible in the Netherlands and Denmark, where industrial software-as-a-service penetration exceeds continental averages by a significant margin.
Europe Human Machine Interface Market Segmentation
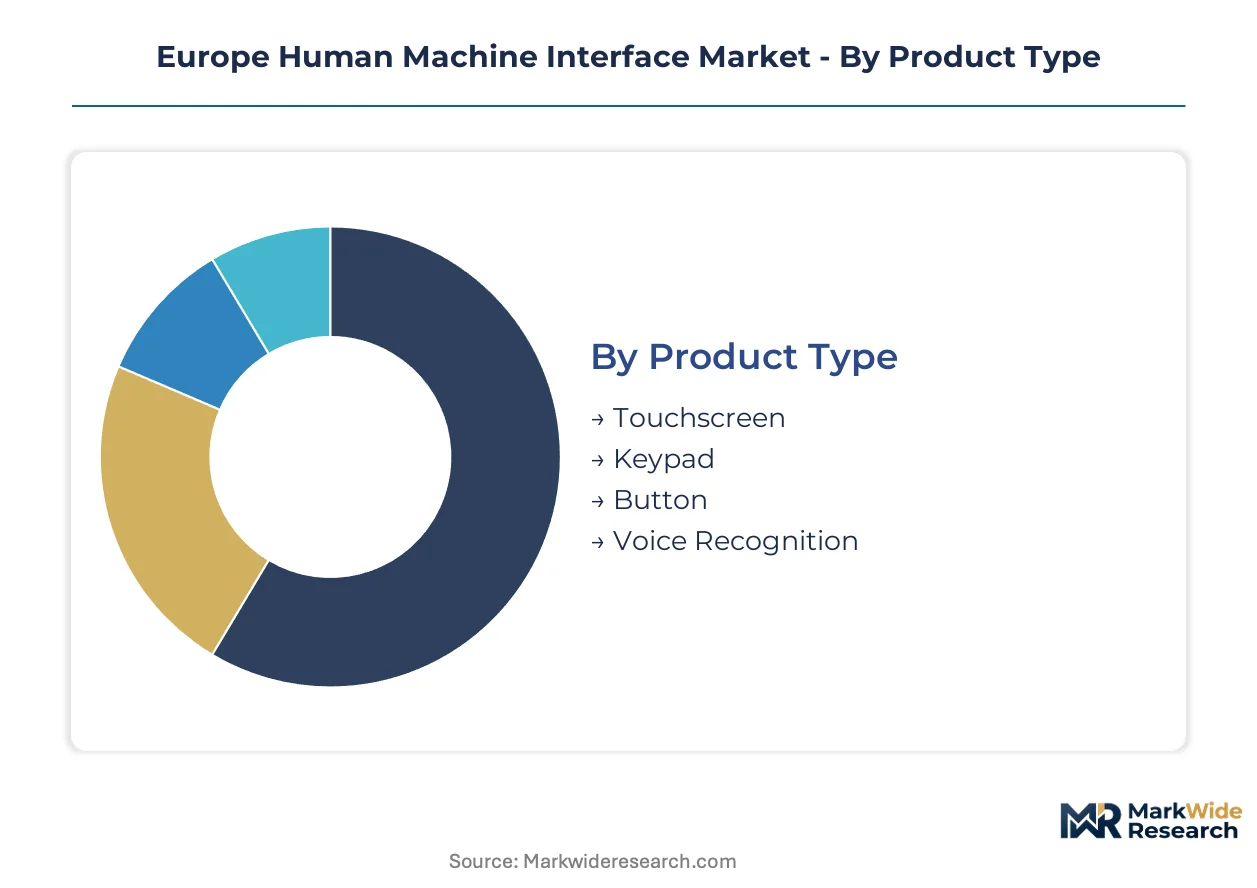
HMI procurement patterns diverge sharply across European end-uses, with automotive and industrial buyers prioritizing deterministic control protocols while consumer segments chase interface novelty. Segmentation clarity enables vendors to align R&D spend against compliance requirements and margin profiles that vary by application.
Product Type:
Voice recognition faces the most acute substitution pressure from multimodal gesture systems, while touchscreen and keypad formats defend entrenched positions through operator familiarity and regulatory acceptance.
- Touchscreen:Capacitive and resistive display matrices dominate operator panels across manufacturing floors and vehicle cockpits. German automotive OEMs in Stuttgart and Munich are qualifying haptic-feedback touch surfaces for EV interiors to preserve tactile confirmation without mechanical switches.
- Voice Recognition:Natural language processing engines enable hands-critical operation in surgical robotics and cleanroom environments. Lower Silesian manufacturing clusters in Poland are piloting voice-controlled assembly line interfaces to reduce contamination risks in pharmaceutical production.
- Keypad:Membrane and mechanical key matrices persist in heavy industrial settings where glove compatibility and environmental sealing outweigh interface sophistication.
- Button:Discrete mechanical actuators retain niche demand for safety-critical emergency stops and hardwired interlocks where software failure modes are unacceptable.
Touchscreen anchors the volume base while voice recognition gains share at the steepest rate.
Technology:
Cost tier stratification separates embedded deployments with long validation cycles from cloud-based offerings with recurring revenue potential.
- Embedded:Industrial-grade processors running real-time operating systems execute deterministic control through OPC UA or EtherCAT protocols. Siemens AG leverages embedded automation stacks for large-scale manufacturing deployments across Germany's industrial corridor.
- Cloud-Based:Edge-cloud hybrid architectures enable remote diagnostics and predictive maintenance for distributed asset fleets. Dutch and Danish manufacturers lead continental adoption of subscription-based HMI software licensing.
- Standalone:Self-contained interface hardware with localized processing serves brownfield facilities requiring protocol bridging to legacy fieldbus infrastructures.
- Software-Based:Virtualized HMI layers running on general-purpose compute hardware reduce capital intensity for mid-sized European manufacturers.
Embedded systems retain the largest installed base while cloud-based deployments expand most quickly.
End User:
Application maturity varies by sector, with industrial automation demanding decades-long support commitments and consumer electronics cycling through interface generations annually.
- Automotive:Electric vehicle cockpit procurement concentrates HMI investment around large-format displays and haptic feedback systems. KBA certification requirements extend validation timelines for German Tier-1 suppliers.
- Industrial Automation:Process control and robotics integration drives demand for ruggedized panels with extended temperature ranges and chemical resistance. ABB Ltd anchors market position through deep robotics system integration.
- Healthcare:Surgical and diagnostic equipment interfaces face EU MDR documentation obligations and GDPR constraints on patient data processing.
- Consumer Electronics:Smartphone and appliance interfaces prioritize cost minimization and rapid design iteration over industrial-grade reliability.
Industrial automation generates the most stable revenue streams while automotive applications climb the fastest.
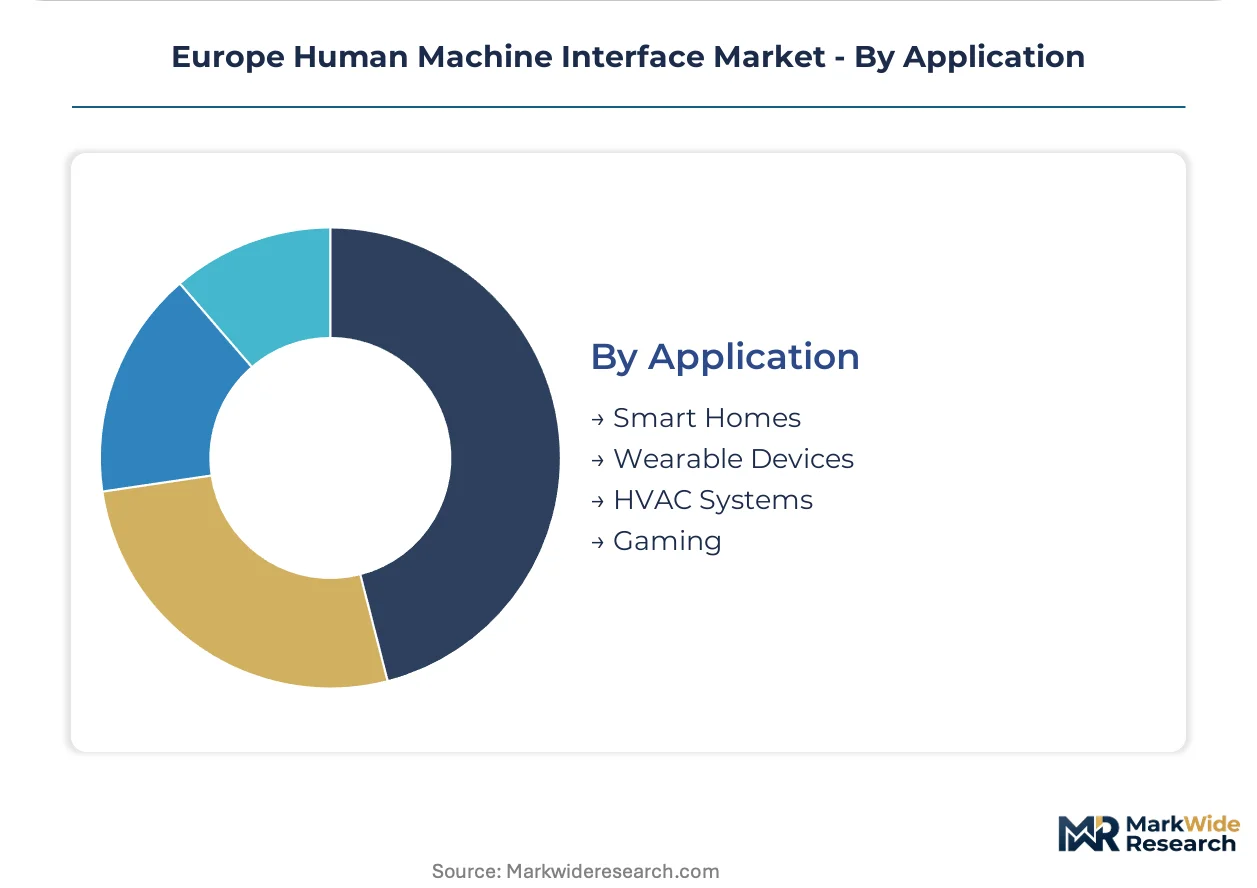
Application:
Customer type fragmentation separates enterprise buyers with centralized procurement from residential consumers with dispersed decision-making.
- HVAC Systems:Building automation interfaces integrate energy management dashboards that extend Schneider Electric's footprint across commercial real estate portfolios.
- Smart Homes:Residential control panels and mobile applications converge around voice assistant ecosystems with limited interoperability.
- Wearable Devices:Compact displays and haptic feedback arrays serve fitness and medical monitoring applications with severe power and space constraints.
- Gaming:High-refresh-rate displays and force-feedback controllers prioritize latency reduction and immersive feedback over industrial reliability standards.
HVAC systems anchor commercial demand while smart home applications attract the most venture investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Cyber Resilience Act mandates are accelerating technology refresh cycles across member states, concentrating procurement in countries with established industrial automation ecosystems. National implementation timelines vary, fragmenting compliance investment patterns.
Germany
Electric vehicle cockpit procurement from Stuttgart and Munich anchors HMI demand, with Tier-1 suppliers qualifying haptic-feedback touch surfaces. KBA certification requirements extend validation timelines for automotive interfaces. The industrial corridor from Munich to Stuttgart concentrates manufacturing automation deployments.
Poland
Manufacturing investment in Lower Silesia and the Warsaw region outpaces local supplier presence, creating first-mover opportunities. ECHA REACH restrictions on hazardous substances accelerate material substitution programs for display assemblies. Pharmaceutical production clusters in Lower Silesia pilot voice-controlled assembly lines to reduce contamination risks.
Netherlands
Industrial software-as-a-service penetration exceeds continental averages, driving subscription-based HMI licensing adoption. GDPR constraints on cloud-based data processing force edge-local compute architectures. Rotterdam and Eindhoven anchor distributed asset fleet management deployments.
France
Building automation interfaces integrate energy management dashboards across commercial real estate portfolios. EU AI Act risk-based classification imposes documentation obligations on machine learning-enabled operator tools. The Île-de-France region concentrates predictive maintenance platform development.
Italy
Robotics and process control integration sustains demand for ruggedized panels with extended temperature ranges. CE marking under the EU Machinery Directive unwinds competitive positioning for industrial suppliers. Lombardy and Emilia-Romagna anchor brownfield manufacturing facilities requiring protocol bridging.
Europe Human Machine Interface Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with embedded automation stacks. Siemens AG leverages its embedded automation stack to dominate large-scale manufacturing deployments across the continent. ABB Ltd anchors its position through deep integration with robotics and process control systems. Schneider Electric SE differentiates via energy management-linked interface platforms that extend its building automation footprint. Strategic moves center on compliance-driven technology refresh cycles and edge-cloud hybrid architecture partnerships.
Among Germany-based industrial technology groups, Siemens AG exemplifies the embedded automation archetype through its manufacturing corridor dominance. ABB Ltd represents the robotics-integrated tier with process control system anchoring. Schneider Electric SE occupies the building automation-linked position, extending energy management capabilities into commercial real estate portfolios. These three conglomerates sit within the premium-tier vendor category, distinguished by pre-built compliance stacks for EU Cyber Resilience Act mandates.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Schneider Electric SE |
| Emerson Electric Co. |
| OMRON Corporation |
| Yokogawa Electric Corporation |
| General Electric Co. |
| Others |
Cost & Logistics Intelligence
Material substitution away from indium tin oxide toward silver nanowire and metal mesh alternatives is redrawing procurement geography from East Asian display foundries toward European specialty chemical suppliers, compressing input cost volatility while elevating qualification expenses for Tier-1 automotive contracts.
Pricing Analysis
Certification level (CE marking under the EU Machinery Directive, KBA automotive approval, EU MDR medical device classification) creates the primary spread between premium and standard tiers. Pricing stratifies across three performance levels: automotive-grade haptic-feedback panels command substantial premiums over industrial embedded displays, while economy-tier membrane keypads face acute cost compression from commoditized Asian imports. Dutch and Danish manufacturers exhibit lowest price sensitivity due to software-as-a-service bundling, whereas Polish industrial integrators prioritize unit economics in competitive tendering.
Supply Chain Analysis
Strategic stockpiling of industrial-grade processors and display driver ICs has displaced just-in-time preferences as Taiwanese foundry capacity constraints persist. Supply geography centers on Taiwan for high-performance touchscreen controllers, Germany for embedded automation stacks, and South Korea for OLED display matrices. Raw material dependencies span rare earth elements for haptic actuators, copper-clad laminates for circuit substrates, and fluorinated gases for thermal management systems. Single-source vulnerability concentrates in Taiwanese 12-inch wafer fabrication. Distribution runs through direct OEM relationships for automotive and industrial automation, with value-added resellers serving mid-sized manufacturing accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European HMI demand is recovering from semiconductor procurement cycles, with electric vehicle platform refreshes and industrial automation capex rebounds providing cyclical momentum through the projection horizon.
For Market Incumbents: Compound defensive moats through backward integration into embedded security stacks for EU Cyber Resilience Act compliance, while acquiring voice recognition specialists to preempt surgical robotics entrants. Threat substitution from multimodal gesture interfaces demands accelerated haptic feedback R&D in Stuttgart and Munich engineering centers.
For New Entrants and Emerging Players: Anchor in Poland's Lower Silesian manufacturing corridor where local HMI supplier presence lags investment inflows. Pharmaceutical cleanroom voice-control applications offer the most penetrable white space. Go-to-market execution should leverage system integrator partnerships rather than direct OEM pursuit.
For Investors and Strategic Acquirers: Capital is best deployed toward edge-compute HMI specialists with pre-built GDPR-compliant inference architectures. Long-term viability hinges on differentiation from cloud-platform commoditization. Acquisition targets should demonstrate thermal engineering capabilities for F-Gas Regulation compliance. The signal to monitor is Tier-1 automotive qualification timelines extending beyond nine months.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Cloud Hybrid Architecture Partnership | Enables predictive maintenance revenue streams for Dutch industrial SaaS providers. |
| Haptic Feedback Technology Licensing | Accelerates qualification timelines for Munich-based EV cockpit suppliers. |
| EU Cyber Resilience Act Compliance Stack | Differentiates embedded automation vendors from standalone interface providers. |
| Voice Recognition Platform Integration | Opens surgical robotics and pharmaceutical cleanroom segments in Lower Silesia. |
| Backward Integration into Display Substrates | Reduces REACH compliance exposure for German industrial HMI manufacturers. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive platform engineers, industrial automation procurement leads, pharmaceutical manufacturing directors, and building automation system integrators. Secondary validation drew from KBA certification databases, ECHA REACH substance restriction filings, EU AI Act implementation guidance, and SEC disclosures from listed industrial technology groups. Bottom-up volume estimates triangulated against top-down spending analysis across Germany's industrial corridor, Poland's emerging automation clusters, and the Netherlands' SaaS-leading manufacturing base.
Across the analysis window, the forecasting framework modeled demand by product type (touchscreen, voice recognition, keypad, button), technology deployment (embedded, cloud-based, standalone, software-based), end-user sector (automotive, industrial automation, healthcare, consumer electronics), and application (HVAC systems, smart homes, wearable devices, gaming). CAGRs were derived from regression analysis of historical procurement patterns against electric vehicle production schedules and industrial capex cycles. Industry-specific inputs included OPC UA adoption rates, EU Cyber Resilience Act implementation timelines, and F-Gas Regulation thermal redesign requirements.
Decision-makers should treat outputs as directional under assumptions of sustained electric vehicle cockpit investment and stable Taiwanese semiconductor foundry capacity; material deviation would warrant model refresh. Specific risk factors encompass geopolitical disruption to display controller supply, accelerated EU AI Act enforcement, and substitution toward gesture-based interfaces. Revision becomes warranted when automotive qualification timelines exceed twelve months or cloud-platform commoditization compresses software margins below embedded hardware parity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Refrigeration Leak Detector Market
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Europe Bulk Acoustic Wave Sensors Market
Sensors and Controls
Europe Pressure Transmitter Market
Sensors and Controls
Time of Flight (Tof) Sensor Market
Sensors and Controls
Global Internet of Things Sensors Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Absolute Pressure Sensor Market
Sensors and Controls
Air Flow Monitoring System Market
Sensors and Controls
Japan Sensor Market
Sensors and Controls
Photodiode Sensors Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Pressure Transmitter and Transducer Market