
 VOC Sensors and Monitors Market | 2026-2036
VOC Sensors and Monitors Market Size, Share, and Industry Trends Forecast 2026-2036
VOC Sensors and Monitors Market Analysis
ISO 16000 certification for indoor air quality measurement is bifurcating the competitive landscape between qualified and unqualified suppliers. Honeywell International Inc. leverages its building automation platform to bundle VOC detection into integrated HVAC control systems. Sensirion AG specializes in miniaturized metal oxide semiconductor designs that anchor its position within wearable and IoT device channels. Aeroqual competes through reference-grade outdoor monitoring stations that dominate environmental agency procurement frameworks.
VOC sensors and monitors detect volatile organic compounds through electrochemical reaction, photoionization, or semiconductor resistance change, typically measuring concentrations from parts-per-billion to parts-per-million for regulatory compliance and health protection. Photoionization technology leads industrial safety applications due to its broad detection range and rapid response time, while metal oxide semiconductor segments capture the fastest expansion through cost-sensitive smart home and consumer electronics integration. Stationary monitors command the deepest margin pools in environmental monitoring networks where calibration protocols and data telemetry requirements sustain premium pricing.
The EPA enforces National Ambient Air Quality Standards that mandate continuous VOC tracking near major emission sources, while OSHA sets permissible exposure limits that drive workplace monitor installation. The EU Green Deal's zero-pollution ambition tightens Industrial Emissions Directive thresholds, forcing manufacturing sites across member states to retrofit detection infrastructure. Stakeholders must monitor how convergence between air quality regulation and building energy codes reshapes procurement criteria for integrated sensor platforms.
Market Dynamics
The convergence of building energy codes with indoor air quality mandates is restructuring procurement criteria, forcing facility managers to specify integrated sensor platforms rather than standalone detection units.
Growth Catalysts
- EPA National Ambient Air Quality Standards:Continuous VOC tracking requirements near major emission sources compel industrial facilities to install permanent monitoring infrastructure.
- Smart building automation:Commercial real estate developers embed VOC detection into HVAC control systems to meet tenant wellness certifications and reduce liability exposure.
- Metal oxide semiconductor miniaturization:Cost-sensitive integration into consumer electronics and wearables opens volume channels previously inaccessible to gas sensing technologies.
Market Restraints
- Calibration drift:Electrochemical and photoionization sensors require frequent recalibration protocols that elevate total cost of ownership beyond initial hardware expenditure.
- Reference-grade supply concentration:Environmental agency procurement frameworks favor established outdoor monitoring station suppliers, creating barriers for new entrants seeking certification.
- Sensor cross-sensitivity:Semiconductor designs struggle to distinguish target VOCs from humidity and interfering gases, limiting deployment in uncontrolled environments.
Strategic Opportunities
- EU Green Deal zero-pollution ambition:Tightened Industrial Emissions Directive thresholds across member states force manufacturing retrofits, expanding addressable market for continuous emission monitors.
- IoT platform convergence:Integration of VOC data streams with building management systems and cloud analytics creates recurring revenue models beyond hardware sales.
- Workplace exposure monitoring:OSHA permissible exposure limit enforcement drives portable monitor adoption in chemical processing, painting, and confined space operations.
Industry Challenges
- ISO 16000 certification complexity:Indoor air quality measurement standards bifurcate supplier qualifications, requiring substantial investment in testing protocols and laboratory accreditation.
- Legacy system integration:Stationary monitor deployment in existing industrial facilities demands custom engineering to interface with established SCADA and data telemetry architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | VOC Sensors and Monitors Market |
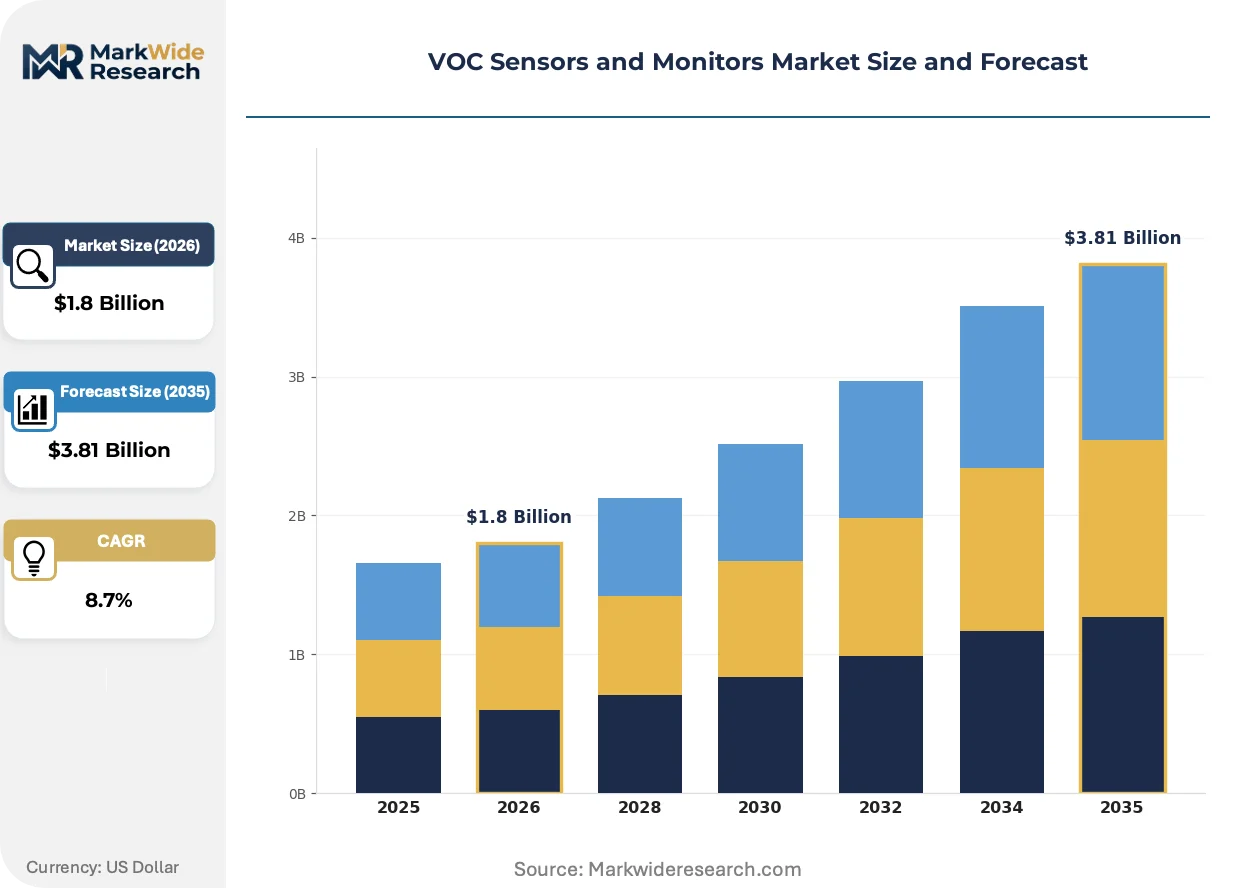
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Sensors, Stationary Monitors, Fixed Detection Systems, Smart Devices Technology: Electrochemical, Photoionization, Metal Oxide Semiconductor, Infrared End User: Manufacturing, Healthcare, Environmental Monitoring, Automotive Application: Indoor Air Quality, Outdoor Air Quality, Industrial Emissions, Research Labs |
| Companies Covered | Honeywell International Inc., Siemens AG, ABB Ltd., Bosch Sensortec GmbH, Sensirion AG, Aeroqual, Renesas Electronics Corporation, Alphasense, Ion Science Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
VOC Sensors and Monitors Market Emerging Trajectories
Sensor architecture is bifurcating between reference-grade precision for regulatory compliance and miniaturized low-cost designs for ubiquitous environmental awareness, with each trajectory demanding distinct R&D investment profiles.
Photoionization detection is fragmenting the industrial safety segment as manufacturers adopt broadband UV lamp designs that detect hundreds of compounds simultaneously. Chemical processing operators and hazmat response teams favor these units for rapid site characterization. The technology is fragmenting traditional electrochemical market share by collapsing the need for multiple single-gas sensors into one portable instrument.
REACH authorization procedures and F-Gas Regulation phase-down schedules in Europe are accelerating demand for non-refrigerant-based detection methods in cooling system monitoring. Industrial refrigeration operators face compliance deadlines that retrofit existing leak detection infrastructure. Germany's Federal Immission Control Act implementation tightens further, mandating continuous emissions tracking across chemical processing clusters near population centers.
Facility managers now specify outcome-based sensor performance contracts rather than capital equipment purchases. Large commercial real estate portfolios in the United States delegate monitoring responsibility to HVAC service providers who guarantee air quality thresholds. This reconfiguration compresses vendor selection criteria toward platform reliability and data analytics capability rather than hardware specifications alone.
VOC Sensors and Monitors Market Segmentation
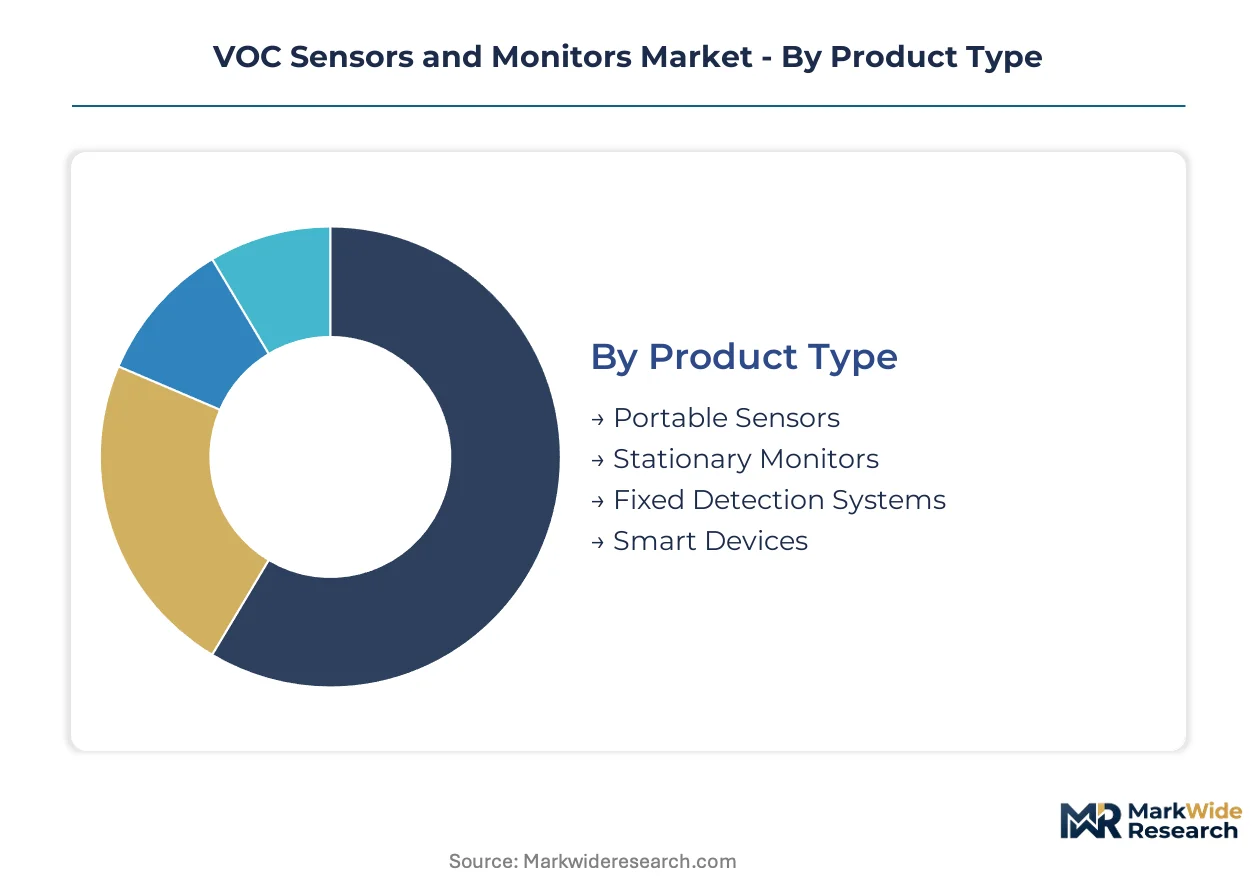
VOC sensor architectures diverge sharply between reference-grade precision for regulatory compliance and miniaturized designs for ubiquitous environmental awareness. Channel strategy varies dramatically across these tiers, with environmental agencies procuring through certified frameworks while consumer electronics flow through OEM supply chains.
Product Type:
Portable units dominate contractor and safety officer procurement through industrial distributors, while stationary systems sell through systems integrators to facility managers.
- Stationary Monitors:Permanent installations with automated calibration protocols and telemetry integration serve continuous emissions tracking mandates. Demand concentrates in German chemical processing clusters under Federal Immission Control Act requirements, where facilities must demonstrate uninterrupted compliance data streams.
- Portable Sensors:Handheld units with rapid response capabilities enable OSHA-compliant workplace exposure assessments and hazmat response characterization. Site safety managers in US chemical processing and painting operations drive replacement cycles tied to lamp and sensor consumable schedules.
- Fixed Detection Systems:Hardwired perimeter installations with SCADA integration protect against fugitive emissions in refinery and petrochemical fence-line monitoring.
- Smart Devices:Miniaturized consumer-grade units with Bluetooth connectivity feed data into wellness apps and smart home platforms.
By volume, Smart Devices leads. By growth pace, Stationary Monitors is expanding most quickly.
Technology:
Cost tier stratification separates premium detection methods from commodity sensing approaches, with calibration requirements and detection limits determining price positioning.
- Photoionization:Broadband UV lamp designs detect hundreds of compounds simultaneously with parts-per-billion sensitivity. Industrial safety managers favor these for rapid site characterization, collapsing multi-sensor arrays into single portable instruments.
- Metal Oxide Semiconductor:Miniaturized designs with resistance-change transduction anchor cost-sensitive IoT and wearable channels. Sensirion AG specializes in these architectures for consumer electronics integration where humidity compensation algorithms address cross-sensitivity limitations.
- Electrochemical:Amperometric cells with selective membranes target specific toxic compounds in confined space and workplace monitoring applications.
- Infrared:Non-dispersive absorption spectroscopy serves refrigerant leak detection as Europe's F-Gas Regulation phases down fluorinated gas reliance.
By installed base, Electrochemical leads. By revenue per unit, Photoionization commands premium positioning.
End User:
Application maturity varies across customer types, with environmental monitoring representing established demand and healthcare emerging as a specification battleground.
- Environmental Monitoring:Regulatory compliance networks with reference-grade calibration requirements sustain deep margin pools. EPA National Ambient Air Quality Standards enforcement compels continuous tracking infrastructure near major emission sources.
- Manufacturing:Process control and worker safety applications span chemical processing, coating operations, and semiconductor fabrication where OSHA permissible exposure limits drive monitor installation.
- Healthcare:Infection control and surgical suite air quality applications are gaining specification traction through ISO 16000 certification requirements.
- Automotive:Cabin air quality monitoring and EV battery off-gassing detection integrate with vehicle HVAC control systems.
By contract value, Environmental Monitoring leads. By specification velocity, Healthcare is climbing the fastest.
Application:
Customer procurement criteria diverge between indoor wellness specifications and outdoor regulatory mandates, reshaping vendor qualification requirements.
- Industrial Emissions:Fence-line and stack monitoring with certified data telemetry serves enforcement actions and permit compliance. EU Green Deal zero-pollution ambition tightens Industrial Emissions Directive thresholds across member states.
- Indoor Air Quality:Building automation integration with wellness certification alignment drives commercial real estate specification. Honeywell bundles detection into HVAC control systems to meet tenant wellness standards.
- Outdoor Air Quality:Reference-grade stations with meteorological parameter correlation dominate environmental agency procurement frameworks.
- Research Labs:Chromatography-grade precision with compound-specific identification supports academic and forensic applications.
By deployment scale, Indoor Air Quality leads. By regulatory tailwind, Industrial Emissions shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial facility managers and commercial real estate developers constitute the concentrated buyer archetypes, with procurement decisions increasingly favoring integrated sensor platforms over standalone units. Environmental compliance officers in chemical processing clusters drive reference-grade demand, while HVAC contractors specify miniaturized designs for smart building retrofits.
United States
EPA enforcement of National Ambient Air Quality Standards compels continuous VOC tracking infrastructure near petrochemical complexes along the Gulf Coast. OSHA permissible exposure limit compliance drives portable monitor adoption in painting operations and confined space work across Texas and Louisiana industrial corridors. Houston's chemical processing cluster mandates fence-line monitoring with certified data telemetry for permit renewal.
Germany
The Federal Immission Control Act mandates uninterrupted emissions tracking across chemical processing sites in the Rhine-Ruhr industrial region. REACH authorization procedures and F-Gas Regulation phase-down schedules accelerate demand for non-refrigerant-based detection methods in cooling system monitoring. BASF and Bayer facility clusters near Ludwigshafen and Leverkusen retrofit continuous emission monitors to meet tightened EU Green Deal thresholds.
China
MEE enforcement of ambient air quality standards drives stationary monitor deployment in Yangtze River Delta manufacturing zones. Dual carbon goals compel industrial facilities in Jiangsu and Zhejiang provinces to upgrade emissions tracking infrastructure. Shanghai's chemical industrial park requires real-time VOC monitoring with cloud-based data transmission for regulatory reporting.
Japan
METI building energy codes convergence with indoor air quality mandates restructures procurement for commercial real estate in Greater Tokyo. JIS standards for sensor performance create qualification barriers for imported equipment in Osaka-Kobe industrial zones. Automotive manufacturers in Aichi prefecture integrate cabin air quality monitoring with vehicle HVAC control systems for export compliance.
South Korea
MFDS workplace exposure guidelines drive portable sensor adoption in semiconductor fabrication facilities across Gyeonggi province. Smart city initiatives in Seoul and Busan embed VOC detection into urban air quality monitoring networks. Samsung and SK Hynix production clusters near Suwon require sub-parts-per-billion detection precision for cleanroom contamination control.
VOC Sensors and Monitors Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with building automation platforms alongside specialized sensor designers focused on miniaturization. Market structure exhibits tiered consolidation, with reference-grade environmental monitoring dominated by established outdoor station suppliers and consumer electronics channels fragmented across semiconductor specialists. Strategic archetypes include integrated building systems providers, precision environmental instrument manufacturers, and MEMS-scale sensor designers. Competitive moves center on platform bundling to capture HVAC specification and technology licensing to accelerate IoT channel penetration.
Among diversified industrial technology providers, Honeywell International Inc. and Siemens AG exemplify the integrated systems archetype, anchoring positions through building automation platform breadth. Sensirion AG occupies a specialist position within the miniaturized semiconductor tier, representing the cost-sensitive consumer electronics and wearable device channel. Aeroqual sits within the reference-grade environmental monitoring segment, exemplifying suppliers focused on certified outdoor station procurement frameworks.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| ABB Ltd. |
| Bosch Sensortec GmbH |
| Sensirion AG |
| Aeroqual |
| Renesas Electronics Corporation |
| Alphasense |
| Ion Science Ltd. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German reference-grade calibration laboratories anchors price floors across the VOC sensor tier structure, concentrating supply-side power among ISO 17025-accredited facilities while forcing cost-sensitive metal oxide semiconductor producers toward Asian foundry partnerships. This scale asymmetry bifurcates procurement economics between environmental compliance officers who absorb premium pricing for certified telemetry integration and facility managers who source miniaturized designs through electronics distributors.
Pricing Analysis
Cost-plus contracts with semiconductor wafer indexation dominate metal oxide procurement, while reference-grade stations command project-based pricing with multi-year service attachments. Price differentiation rests on ISO 16000 certification tier and calibration protocol complexity. Cost compression in consumer-grade channels is intensifying because MEMS foundry overcapacity in Taiwan feeds component oversupply. HVAC integrators show least price sensitivity due to bundled platform economics, whereas independent facility managers exhibit acute sensitivity to per-sensor capital outlay.
Supply Chain Analysis
Strait of Malacca transit underwrites photodiode and UV lamp supply security for photoionization manufacturers, with single-source vulnerability concentrated in Japanese broadband UV arc lamp production. German and Swiss precision optics workshops anchor reference-grade optical bench assembly, while Taiwanese and Chinese MEMS foundries feed consumer electronics integration. Supply chain risk centers on export license restrictions for high-purity tungsten electrodes. Distribution runs through industrial instrumentation distributors for portable units and building automation systems integrators for stationary deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
VOC sensor markets exhibit defensive moat characteristics rooted in regulatory entrenchment, where EPA and EU certification timelines create structural barriers that compound with each emissions standard revision.
For Market Incumbents: Consolidate calibration service networks to capture recurring revenue from drift-prone electrochemical and photoionization installations. Acquire ISO 17025-accredited laboratories in German chemical processing clusters to preempt competitor certification fast-tracks. Metal oxide semiconductor substitution in portable safety applications represents the primary technology threat requiring platform bundling response. For New Entrants and Emerging Players: ISO 16000 fast-track partnerships with European notified bodies unlock healthcare specification velocity ahead of established environmental monitoring suppliers. White-space concentrates in wearable VOC exposure trackers for industrial hygiene contractors and sub-parts-per-billion cleanroom monitors for South Korean semiconductor fabrication. Channel entry through HVAC service provider outcome-based contracts bypasses direct competition with Honeywell and Siemens platform bundling. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among calibration-service-anchored stationary monitor suppliers with environmental agency framework contracts. Long-term viability favors precision environmental instrument manufacturers with backward integration into sensor element production. Watch EU Green Deal implementation pace as inflection indicator for Industrial Emissions Directive retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Captures recurring revenue from EPA-mandated drift protocols at industrial facilities. |
| MEMS Foundry Partnership | Secures wafer allocation for Sensirion-scale miniaturization in consumer electronics channels. |
| ISO 16000 Certification Investment | Unlocks healthcare specification against Honeywell's HVAC-dominated building automation position. |
| IoT Platform Integration | Converts hardware sales to SaaS-tiered data analytics subscriptions with facility managers. |
| EU Green Deal Alignment | Positions continuous emission monitors for German Federal Immission Control Act retrofit waves. |
Methodological Framework
Initial hypotheses were tested against primary input from environmental compliance officers, HVAC systems integrators, semiconductor fabrication facility managers, and industrial safety equipment distributors and refined through secondary validation against EPA enforcement records, EU ETS emissions database extracts, SEC 10-K instrumentation segment disclosures, and German Federal Immission Control Act permit filings. Bottom-up sensor shipment tallies triangulated against top-down building automation capex allocations.
Variance decomposition across technology tier, end-use vertical, and regional regulatory cluster shaped the analytical framework over the projection horizon. CAGRs derived from segment-level unit economics modeling with inputs including calibration service attach rates, MEMS wafer pricing trajectories, and environmental agency procurement cycle timing. Cross-segment elasticity captured substitution effects between photoionization and electrochemical portable units.
Decision-makers should treat outputs as directional under sustained EPA enforcement intensity and EU Green Deal implementation pace; material deviation in regulatory stringency timelines would warrant model refresh. Practitioners should keep alternative scenarios live as F-Gas Regulation phase-down schedules and REACH authorization procedures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Water Detection Sensors Market
Sensors and Controls
North America MEMS and Sensors Market
Sensors and Controls
Doppler Lidar Market
Sensors and Controls
Corrosion Monitoring Market
Sensors and Controls
Sensor Based Sorting System Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Piezoelectric Polymers Market
Sensors and Controls
Ambient Light Sensor Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Americas Sensor Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Global Pyrometer Market
Sensors and Controls
Safety Sensors Market