
 Odor Detection Equipment Market | 2026-2036
Odor Detection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Odor Detection Equipment Market Analytics
IP65-rated and ATEX-certified specification tiers is rotating the market upward as industrial buyers reject consumer-grade alternatives in hazardous environments. Alpha MOS leverages proprietary metal oxide sensor arrays to dominate European food and beverage quality assurance. Shimadzu Corporation anchors Asian demand through integrated gas chromatography-olfactometry systems for research institutions. Airsense Analytics specializes in portable chemical sensor platforms for military and first-responder applications.
Odor detection equipment encompasses instruments that quantify, identify, or characterize volatile organic compounds and odorant molecules through sensor arrays or spectroscopic methods, typically achieving detection thresholds in parts-per-billion ranges for hydrogen sulfide, ammonia, and mercaptan species. These systems serve industrial safety compliance, environmental emissions tracking, and product quality verification where human olfactory panels prove inconsistent or impractical. Electronic noses and fixed sensor networks capture the deepest margin pools in environmental monitoring and waste management applications, while portable devices compete aggressively on price in hospitality and light manufacturing segments. Infrared and photoionization technologies lead growth trajectories as they displace legacy electrochemical cells in high-humidity or corrosive atmospheres.
EPA enforcement of Clean Air Act amendments and OSHA permissible exposure limit standards directly shapes product certification requirements and procurement specifications for US industrial buyers. EMA ambient air quality frameworks and REACH chemical registration protocols in Europe mandate traceable odor emission documentation, forcing equipment vendors to integrate calibration audit trails. China's MEE dual carbon monitoring directives and GB standards for odor pollutant measurement create parallel compliance pathways for manufacturers serving domestic environmental agencies. Stakeholders must monitor divergence between regional certification regimes to avoid redundant engineering cycles and locked-out market access.
Market Dynamics
Fixed sensor networks are displacing portable units in hazardous industrial corridors as buyers prioritize continuous monitoring over spot-checking for hydrogen sulfide and mercaptan species. Municipal wastewater authorities and semiconductor fabs drive this infrastructure pivot.
Growth Catalysts
- EU ambient air quality directives:Municipal wastewater treatment authorities in Germany and the Netherlands are expanding procurement of fixed sensor networks to comply with stricter emission documentation requirements.
- Metal oxide semiconductor arrays:Food quality control lines are adopting these sensor configurations to replace electrochemical methods in high-throughput manufacturing environments.
- East Asian manufacturing corridors:Semiconductor fabs and petrochemical complexes in this geography deploy electronic noses for process gas monitoring at scale.
Market Restraints
- Precious metal catalyst costs:Platinum and palladium price volatility directly impacts metal oxide sensor manufacturing economics and margin stability.
- Calibration drift in high-humidity atmospheres:Electrochemical cells suffer accelerated degradation in corrosive environments, forcing premature replacement cycles.
- Fragmented certification regimes:Divergence between EPA, EMA, and GB standards creates redundant engineering cycles and locked-out market access for vendors.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Domestic production incentives create localized supply chain advantages for sensor assembly and calibration services.
- Convergence of infrared spectroscopy with AI-driven pattern recognition:This technology pairing enables real-time odor fingerprinting without chromatographic separation delays.
- First-responder chemical detection:Military and emergency services represent underpenetrated demand for portable platforms with ATEX certification.
Industry Challenges
- Cross-disciplinary calibration expertise:Vendors struggle to recruit engineers fluent in both sensor physics and regulatory audit trail documentation.
- ATEX and IP65 certification timelines:Hazardous environment approvals extend product launch cycles by 8-14 months in European markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Odor Detection Equipment Market |
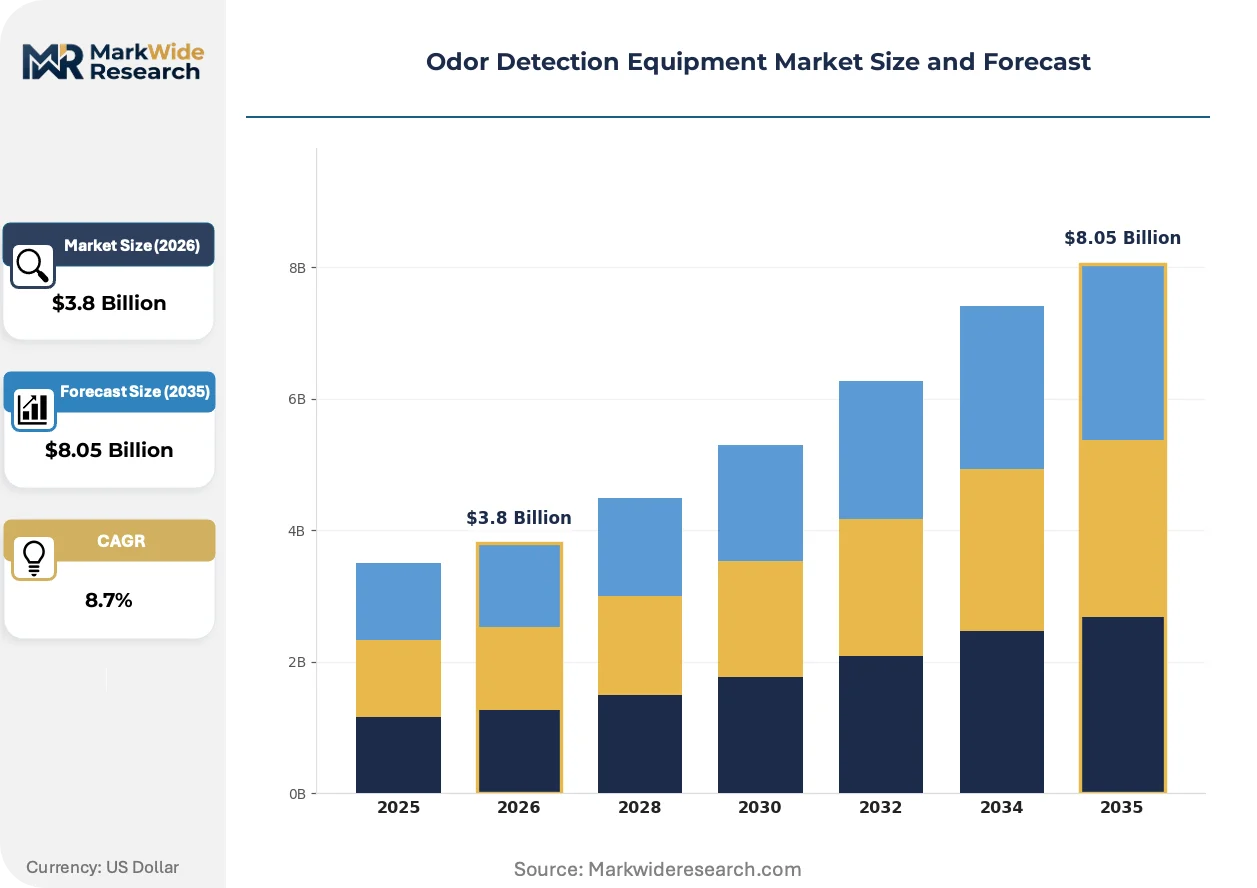
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Devices, Fixed Sensors, Chemical Sensors, Electronic Noses Technology: Electrochemical, Photoionization, Metal Oxide, Infrared Application: Environmental Monitoring, Food Quality Control, Industrial Safety, Waste Management End User: Manufacturing, Healthcare, Hospitality, Research Institutions |
| Companies Covered | Alpha MOS, Airsense Analytics, Shimadzu Corporation, Electronic Sensor Technology, Sensigent, The eNose Company, Odotech Inc., Scentroid, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Odor Detection Equipment Market Evolving Landscape
Infrared and photoionization detection methods are compressing electrochemical market share through superior performance in corrosive atmospheres. Buyers now specify humidity-resistant architectures as standard procurement criteria.
Miniaturized photoionization detectors are supplanting electrochemical cells in food quality control lines. Beverage manufacturers and packaging facilities adopt these units for volatile organic compound screening at conveyor speeds. The shift is compressing maintenance intervals and enabling inline process integration without chromatographic bottlenecks.
REACH chemical registration protocols in Europe mandate traceable odor emission documentation with calibration audit trails. Equipment vendors must integrate tamper-evident data logging to serve industrial buyers under ECHA compliance timelines. Food processing and waste management segments face the steepest documentation burden.
Service unbundling is reshaping buyer-vendor relationships in environmental monitoring. Municipal authorities now separate hardware procurement from calibration contracts, favoring third-party metrology labs over manufacturer-captive service networks. This pattern concentrates in German and Dutch wastewater treatment authorities with mature outsourcing frameworks.
Odor Detection Equipment Market Segmentation
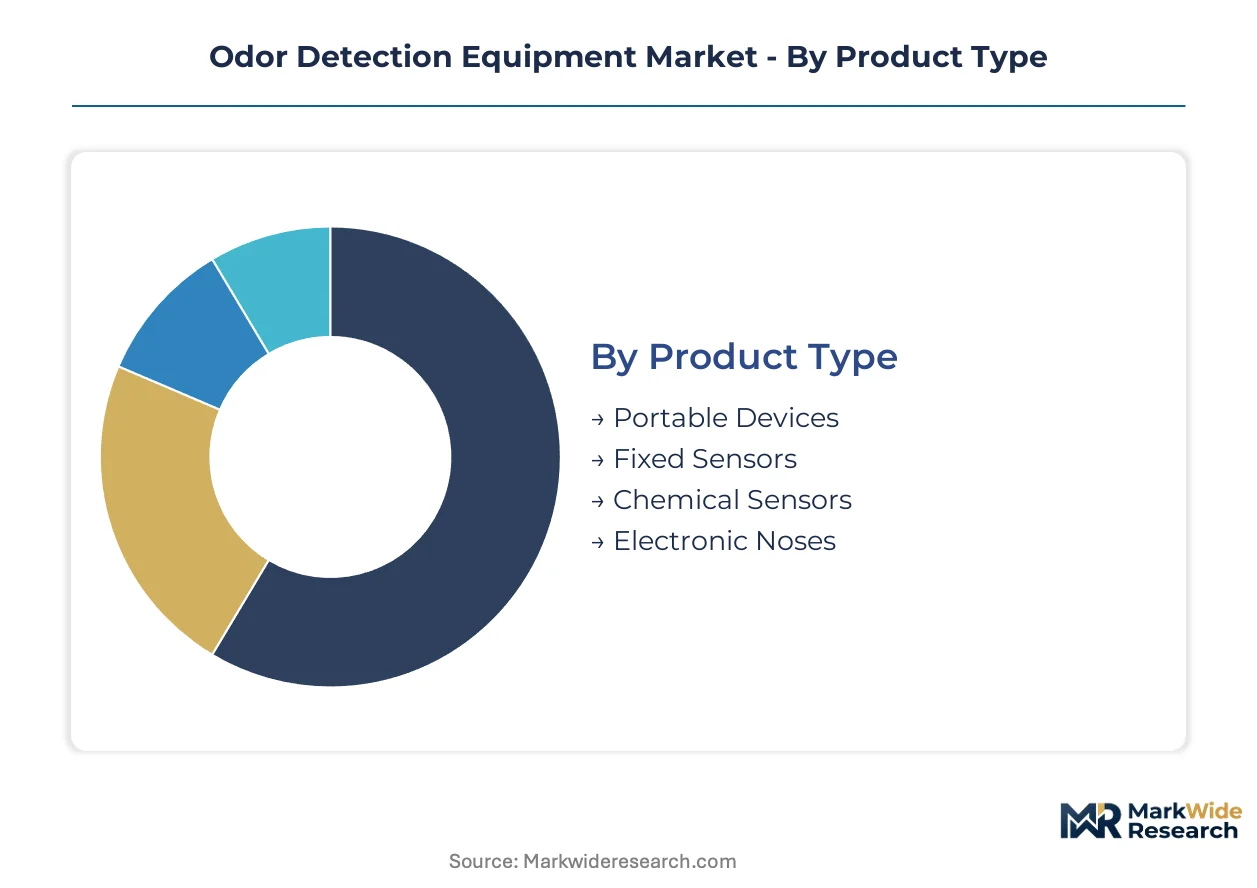
Segmentation in odor detection equipment reveals how technology substitution and regulatory pressure reshape procurement patterns across industrial buyers. Understanding where portable formats displace fixed infrastructure, or where spectroscopic methods overtake electrochemical cells, exposes margin concentration and vendor vulnerability.
Product Type:
Portable devices face the most acute substitution pressure from smartphone-integrated sensors and low-cost gas detection wearables in light industrial settings.
- Portable Devices:Handheld units with photoionization or electrochemical cores serve first responders and facility maintenance crews requiring mobility. Demand concentrates in German municipal wastewater authorities and Dutch environmental agencies procuring ATEX-certified units for field inspection protocols.
- Fixed Sensors:Networked installations with continuous data logging dominate semiconductor fabs and petrochemical corridors in East Asia. These systems command premium pricing through integration with plant distributed control systems and automated alarm thresholds.
- Chemical Sensors:Array-based platforms detect specific VOC signatures through selective coatings. Food packaging lines in France and Belgium deploy these for quality assurance checkpoints.
- Electronic Noses:Pattern recognition systems with metal oxide or polymer sensor arrays replicate human olfactory discrimination. Research institutions in Japan and South Korea drive adoption for flavor chemistry and cosmetic formulation testing.
Fixed sensors retain volume leadership; electronic noses hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium spectroscopic methods from commoditized electrochemical cells facing margin compression.
- Electrochemical:Amperometric cells with liquid electrolyte matrices measure hydrogen sulfide and ammonia at parts-per-million thresholds. High-humidity degradation limits deployment in coastal Chinese petrochemical facilities and Southeast Asian wastewater plants.
- Photoionization:UV lamp ionization chambers detect VOCs with 10.6 eV photon energy, achieving parts-per-billion sensitivity without chromatographic separation. Beverage manufacturers in Germany and the Netherlands adopt miniaturized variants for inline quality screening.
- Metal Oxide:Semiconductor films of tin dioxide or zinc oxide change resistance upon analyte adsorption. Food quality control lines favor these for rapid response times and minimal maintenance in high-throughput environments.
- Infrared:Non-dispersive or photoacoustic spectroscopy identifies molecular absorption bands for specific odorant species. German automotive suppliers and French chemical manufacturers specify these for regulatory compliance documentation under REACH protocols.
Electrochemical technologies retain installed base dominance; infrared spectroscopy is climbing the fastest.
Application:
Customer type maturity divides established environmental compliance buyers from emerging quality-conscious segments in food and hospitality.
- Environmental Monitoring:Continuous emission measurement systems track odorant plumes from industrial stacks and wastewater treatment facilities. German municipalities and Dutch provincial authorities drive procurement under tightened EU ambient air quality directives.
- Food Quality Control:Inline sensors screen packaging integrity and spoilage indicators at conveyor speeds. French dairy processors and Belgian chocolate manufacturers deploy electronic noses to replace human sensory panels.
- Industrial Safety:Personal and area monitors enforce OSHA permissible exposure limits for hydrogen sulfide in confined spaces. US refineries and chemical plants mandate these for turnaround maintenance operations.
- Waste Management:Landfill gas and composting facility operators measure mercaptan and sulfur compound emissions. Chinese municipal authorities under MEE dual carbon directives expand sensor network deployment.
Environmental monitoring retains procurement volume leadership; food quality control is gaining share fastest.
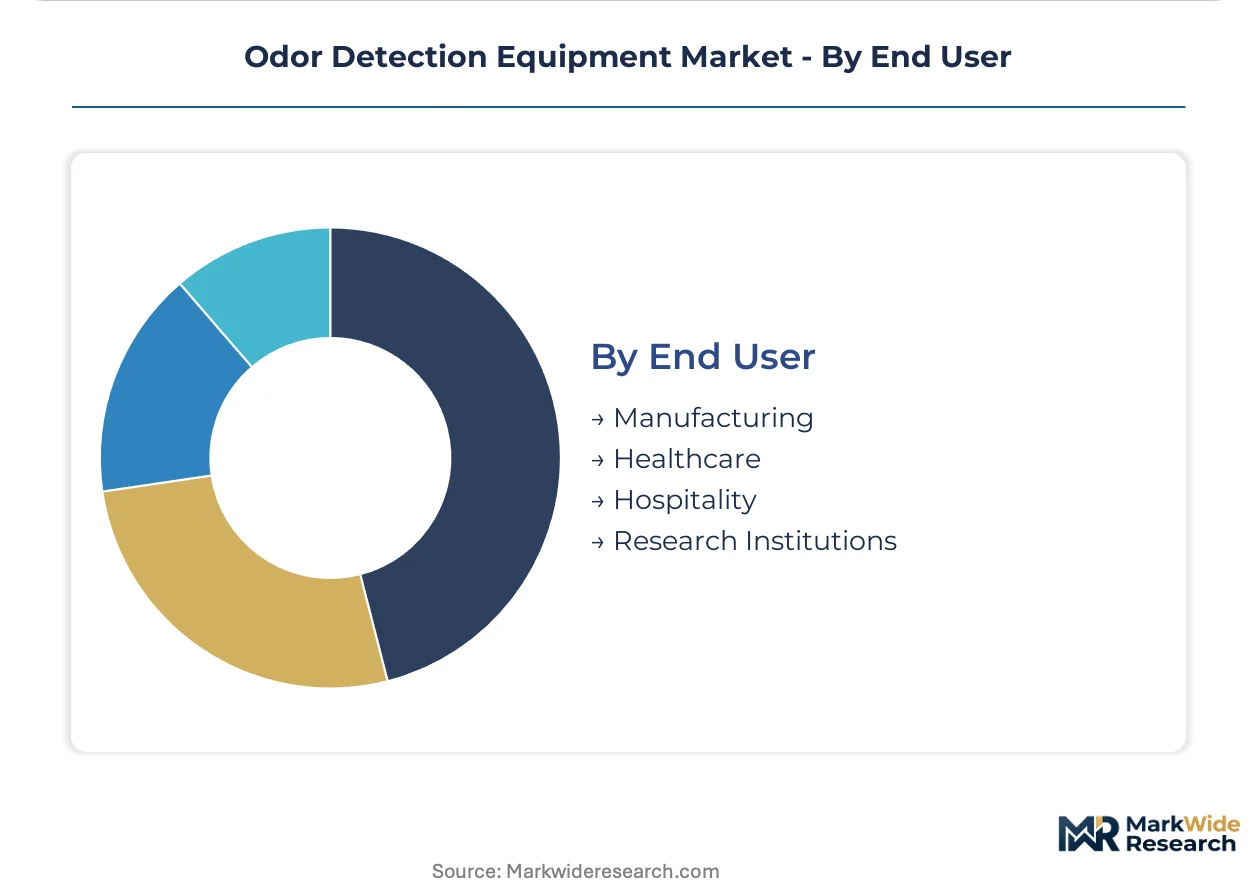
End User:
Supply concentration in sensor manufacturing clusters shapes regional vendor access and certification requirements.
- Manufacturing:Semiconductor fabs and petrochemical complexes require process gas monitoring with sub-ppb detection thresholds. East Asian manufacturing corridors in Taiwan, South Korea, and eastern China concentrate demand.
- Healthcare:Hospitals and pharmaceutical cleanrooms monitor anesthetic gas leaks and sterilant residuals. Japanese medical device manufacturers and German hospital networks specify ISO-calibrated systems.
- Hospitality:Hotels and commercial kitchens address guest complaints through spot-checking protocols. Price-sensitive buyers in this segment favor portable electrochemical units over fixed infrastructure.
- Research Institutions:Universities and national laboratories employ gas chromatography-olfactometry for fundamental odor chemistry studies. French INRA facilities and Japanese national institutes anchor demand for integrated analytical platforms.
Manufacturing retains volume leadership; healthcare holds the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German sensor manufacturers export fixed network systems to Dutch wastewater authorities under tightened EU emission documentation requirements. East Asian fabs in Taiwan and South Korea import spectroscopic detection platforms for sub-ppb process gas monitoring.
United States
Petrochemical complexes along the Gulf Coast deploy continuous emission monitors for hydrogen sulfide compliance. EPA enforcement of Clean Air Act amendments mandates traceable calibration audit trails for refinery turnaround operations. Houston-area facilities drive procurement of ATEX-certified portable units for confined space entry protocols.
Germany
Municipal wastewater authorities in North Rhine-Westphalia and Bavaria expand fixed sensor networks for mercaptan detection. REACH protocols under ECHA require tamper-evident data logging for odor emission documentation. The Ruhr industrial corridor concentrates demand for infrared spectroscopy systems serving chemical manufacturers.
Netherlands
Provincial environmental agencies procure portable photoionization detectors for field inspection workflows. EU ambient air quality directives force documentation of volatile organic compound plumes from port logistics facilities. Rotterdam's petrochemical cluster deploys electronic noses for stack emission verification.
China
Semiconductor fabs in Shanghai and Beijing-Tianjin-Hebei install metal oxide sensor arrays for process contamination control. MEE dual carbon monitoring directives mandate odor pollutant measurement at municipal landfill sites. Yangtze River Delta manufacturing corridors drive volume procurement of fixed network infrastructure.
Japan
Research institutions in Kanto and Kansai regions acquire integrated gas chromatography-olfactometry platforms for flavor chemistry studies. METI industrial standards shape certification requirements for food quality control equipment deployment. Osaka-area pharmaceutical cleanrooms specify ISO-calibrated systems for sterilant residual monitoring.
Odor Detection Equipment Market Competitive Landscape
Listed leaders compete with private specialists across technology licensing and geographic coverage dimensions. The vendor base stratifies into three tiers: diversified analytical instrument conglomerates, sensor-focused mid-cap specialists, and venture-backed electronic nose developers. Strategic moves concentrate on M&A for calibration service networks and backward integration into precious metal catalyst supply.
Within the diversified analytical tier, Thermo Fisher Scientific exemplifies scale-driven portfolio breadth. Shimadzu Corporation anchors Asian demand through research institution relationships. Alpha MOS and Airsense Analytics occupy distinct specialization positions in food quality assurance and portable chemical detection respectively.
| Leading Market Players |
|---|
| Alpha MOS |
| Airsense Analytics |
| Shimadzu Corporation |
| Electronic Sensor Technology |
| Sensigent |
| The eNose Company |
| Odotech Inc. |
| Scentroid |
| Thermo Fisher Scientific |
| Others |
Value Network & Pricing Analysis
Capacity utilization at German and Japanese sensor foundries shapes price floors across the odor detection equipment market, concentrating margin leverage in vendors with captive metal oxide semiconductor fabrication while forcing tier-two assemblers toward cost-plus contracting with municipal buyers.
Pricing Analysis
Next-generation infrared spectroscopy systems command substantial premiums over legacy electrochemical units, while miniaturized photoionization detectors occupy a compressing mid-tier. Three-tier pricing structure across premium, standard, and economy levels separates ATEX-certified fixed networks from portable field units and unbranded wearables. Pricing pressure stems from platinum and palladium catalyst volatility in metal oxide sensor production. Municipal wastewater authorities in Germany and the Netherlands exhibit lowest price sensitivity due to compliance mandates, while hospitality buyers in Southeast Asia drive aggressive commoditization of portable electrochemical devices.
Supply Chain Analysis
Inventory lead times for UV lamp ionization chambers and tin dioxide semiconductor films stretch procurement cycles for European and North American equipment assemblers. Manufacturing concentrates in Germany, Japan, and South Korea for precision sensor arrays, with China dominating discrete component packaging. Raw material dependencies center on palladium catalysts, sapphire optical windows, and specialized polymer sensor coatings. Single-source vulnerability runs through Ukrainian neon gas supplies for infrared laser sources. Distribution runs through authorized technical distributors with calibration service capabilities rather than direct OEM sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
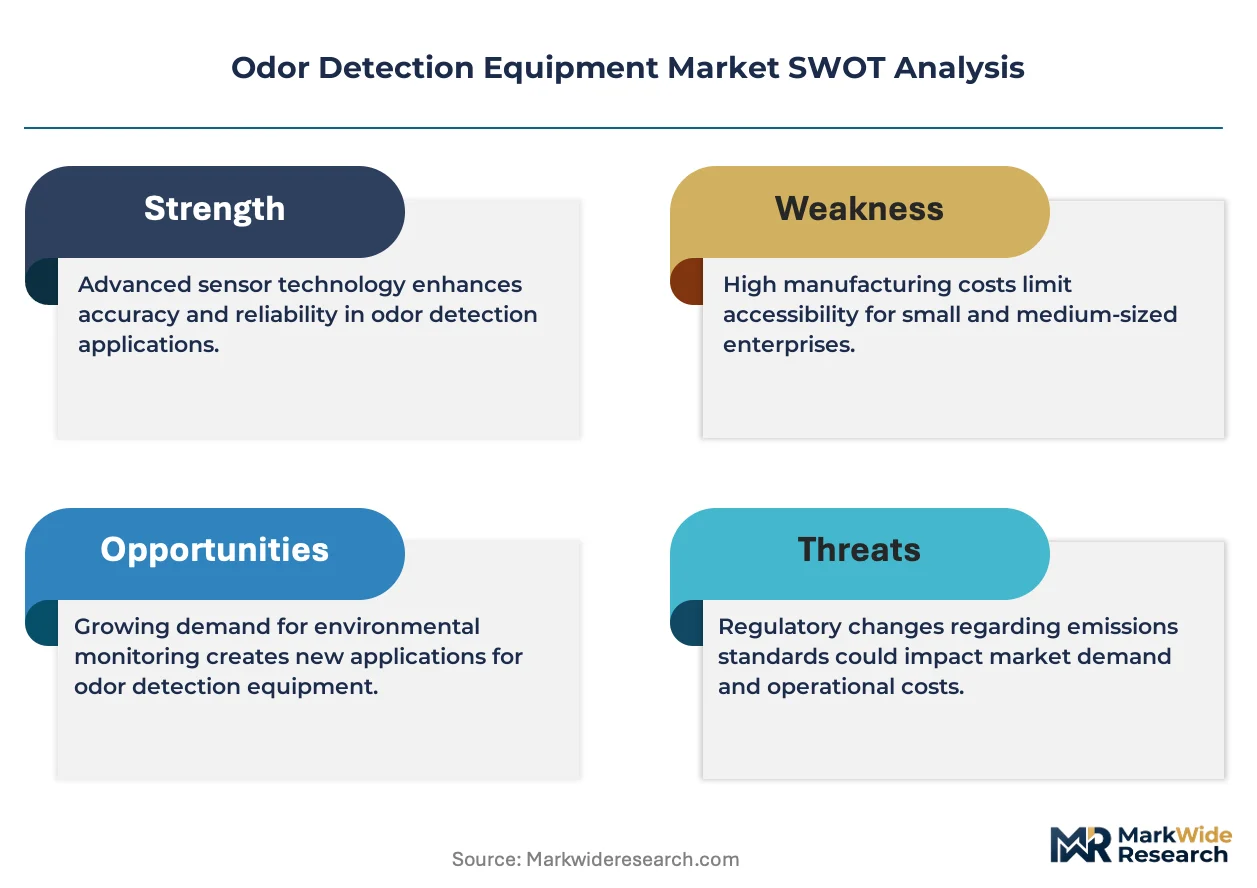
The odor detection equipment market sits at an inflection where AI-driven pattern recognition converges with spectroscopic hardware, compressing chromatographic bottlenecks while REACH and MEE regulatory enforcement hardens compliance documentation requirements into structural demand drivers.
For Market Incumbents: Fortify calibration service networks through backward integration into third-party metrology labs, particularly in German and Dutch wastewater authority markets where procurement unbundling accelerates. Deepen sensor physics R&D partnerships with East Asian semiconductor fabs to secure tin dioxide and zinc oxide film supply commitments before precious metal volatility intensifies.
For New Entrants and Emerging Players: Lead with portable ATEX-certified platforms targeting first-responder and military chemical detection applications, an underpenetrated segment where incumbents lack specialized form factor expertise. Establish go-to-market alliances with French and Belgian food packaging OEMs seeking inline electronic nose integration without chromatographic separation delays.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among calibration service providers and sensor-as-a-service platforms serving municipal environmental monitoring contracts. Five-to-ten year viability favors vendors with dual certification pathways for EPA and EMA regimes. Signal to monitor: divergence between China's GB standards and European REACH protocols forcing redundant engineering investments.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precious Metal Catalyst Supply | Mitigates palladium price volatility for metal oxide sensor manufacturers serving REACH-compliant European buyers. |
| AI-Driven Pattern Recognition Platform Launch | Enables real-time odor fingerprinting without chromatographic delays for food quality control lines in France and Belgium. |
| Calibration Service Network Acquisition | Captures unbundled procurement spend from German municipal wastewater authorities separating hardware from metrology contracts. |
| ATEX Certification Investment for Portable Units | Unlocks first-responder and military demand segments where incumbent portfolios lack hazardous environment mobility. |
| Joint Venture with East Asian Semiconductor Fabs | Secures tin dioxide film capacity for electronic nose production serving process gas monitoring in Taiwan and South Korea. |
Research Methodology
Operator-level perspectives from plant engineers at semiconductor fabs, procurement leads at municipal wastewater authorities, technical directors at food packaging OEMs, and calibration service managers anchored the qualitative base. Primary interview findings triangulated against secondary sources including EPA enforcement actions, ECHA REACH registration databases, MEE dual carbon policy directives, and customs records for sensor component trade flows. Bottom-up unit demand estimates across portable, fixed, and electronic nose product categories reconciled with top-down market value assessments.
Sensitivity analysis tested forecast outputs against platinum price volatility scenarios, regulatory enforcement intensity variations, and technology substitution rates for electrochemical versus spectroscopic methods. Segmentation modeling incorporated product type, detection technology, application vertical, and end-user industry dimensions across the projection horizon. CAGRs derived from installed base growth, replacement cycle compression, and average selling price trajectories for IP65-rated versus consumer-grade equipment tiers.
The analysis sits within stated boundaries; outcomes outside sustained EU ambient air quality directive enforcement or accelerated East Asian fab construction would require recalibration. Forecasts reflect documented assumptions regarding precious metal catalyst availability and certification timeline stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
MEMS-Based IMU Market
Sensors and Controls
China Digital Thermometer Market
Sensors and Controls
Ozone Meter Market
Sensors and Controls
Europe Gas Sensors Market
Sensors and Controls
Middle-East and Africa Nanosensors Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Smart Condition Monitoring Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Infrared Sensors Market
Sensors and Controls
Gesture Control Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Ultrasonic Sensors Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
GNSS Devices Market
Sensors and Controls
Chest Sensors Market