
 Asia-Pacific Thermocouple Temperature Sensors Market | 2026-2036
Asia-Pacific Thermocouple Temperature Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Thermocouple Temperature Sensors Market Outlook
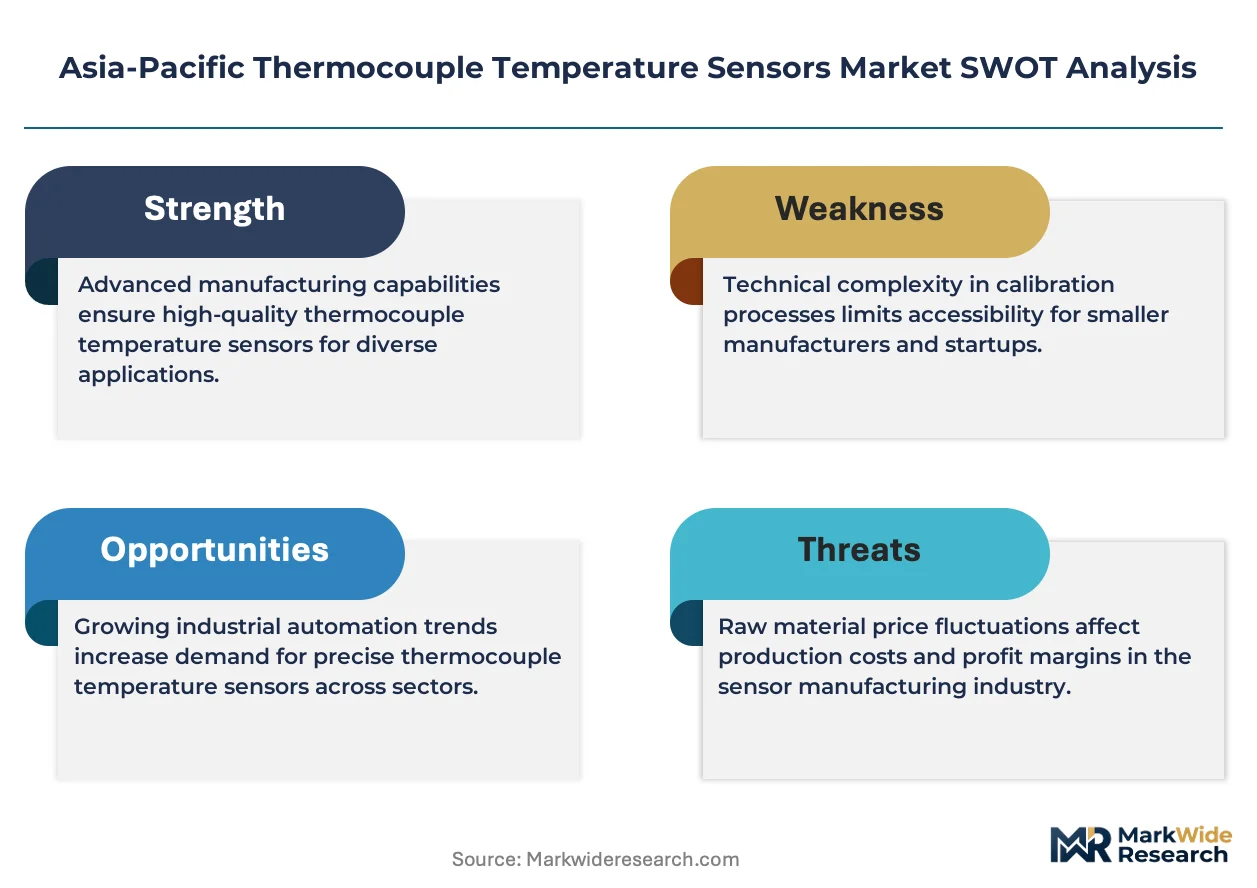
China's GB standards alignment with IEC 60584 is repositioning the cost-of-entry calculus for sensor suppliers targeting heavy industry. Honeywell International Inc. leverages its flame safety and combustion control portfolio to anchor premium positioning in Chinese petrochemical complexes. TE Connectivity sustains manufacturing scale across Southeast Asian cable and connector facilities. Siemens AG dominates process automation integration, bundling thermocouple modules into distributed control systems for regional refineries.
Thermocouple temperature sensors generate measurable electromotive force from the Seebeck effect at dissimilar metal junctions, typically operating across ranges from minus 200 degrees Celsius to 1800 degrees Celsius depending on conductor pairing. These devices serve as primary temperature transducers in furnaces, reactors, and exhaust streams where RTDs or semiconductor sensors cannot survive. Mineral-insulated thermocouples command the largest application share due to mechanical durability in vibrating process equipment, while wireless technology segments attract the fastest upgrade cycles as plants retrofit legacy analog loops. Advanced thermocouples with noble metal sheathing capture the highest margin pools in semiconductor crystal growth and aerospace turbine testing.
Japan's METI enforces JIS C 1602 calibration protocols that restrict market access for uncertified imports, while India's BIS operates phased mandatory certification for industrial thermocouples under its Compulsory Registration Order. Australia's TGA and South Korea's MFDS maintain overlapping standards for pharmaceutical manufacturing environments, creating compliance complexity for multi-country suppliers. Stakeholders must monitor divergence between Chinese GB standards and IEC harmonization timelines when allocating regional product development resources.
Market Dynamics
China's MIIT is tightening industrial energy-efficiency mandates, forcing steelmakers across India and Southeast Asia to expand pyrometric monitoring infrastructure. This regulatory pressure is accelerating sensor procurement cycles and reshaping supplier qualification requirements.
Growth Catalysts
- Mineral-Insulated Sheathing:Japanese automotive testing facilities now specify MI thermocouples for vibration resistance in engine dynamometer cells. This material specification is displacing traditional wire-wound configurations.
- India's BIS Compulsory Registration Order:Phased mandatory certification for industrial thermocouples is filtering out uncertified imports and creating structured demand for compliant suppliers.
- Wireless Retrofit Cycles:Plants across Southeast Asian cable manufacturing corridors are replacing legacy analog loops with wireless transmitter modules to reduce cabling costs.
Market Restraints
- Noble Metal Price Volatility:Platinum-rhodium alloy costs fluctuate with South African mining output, compressing margins for Type S and Type R thermocouple producers.
- Supply Concentration Risk:Japanese mineral-insulated cable production clusters around three prefectures, creating vulnerability to seismic disruption or logistics bottlenecks.
- Infrared Pyrometer Substitution:Non-contact temperature measurement is displacing thermocouples in steel reheat furnace applications above 1200 degrees Celsius where optical access permits.
Strategic Opportunities
- Indonesian Smelter Expansion:Nickel processing investments in Sulawesi and Maluku are generating demand for high-temperature thermocouples in rotary kiln and electric furnace installations.
- GB-IEC Harmonization:China's alignment of national standards with IEC 60584 is reducing technical barriers for suppliers certified to international protocols.
- Pharmaceutical Cold Chain:Australia's TGA and South Korea's MFDS overlapping validation requirements are creating bundled sensor opportunities for multi-country equipment suppliers.
Industry Challenges
- Calibration Technician Scarcity:JIS C 1602 certification requirements in Japan and BIS registration in India outpace regional training program output, extending deployment timelines.
- Legacy System Integration:Southeast Asian refineries running 1990s-era distributed control systems face protocol incompatibility when installing digital thermocouple transmitters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Thermocouple Temperature Sensors Market |
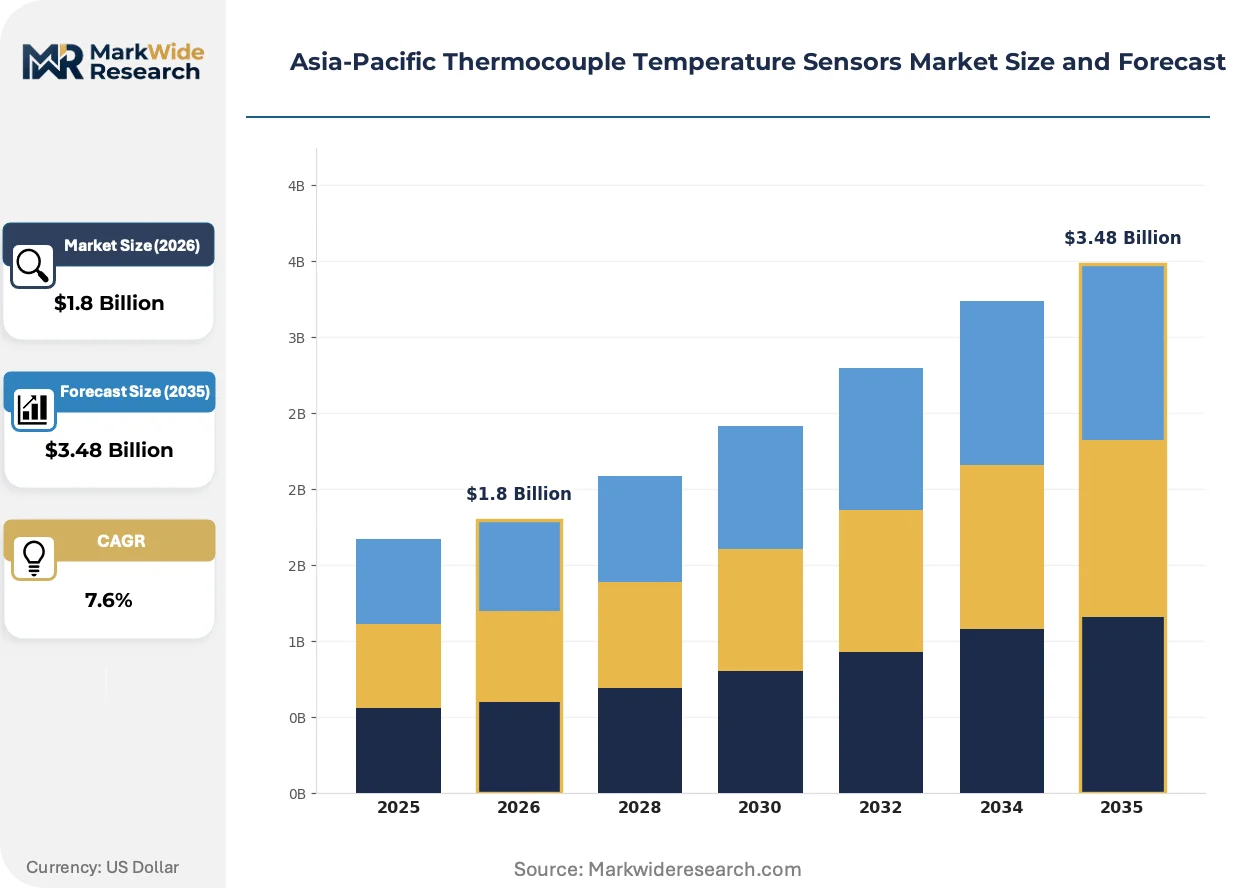
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Thermocouples, Mineral-Insulated Thermocouples, Advanced Thermocouples, High-Temperature Thermocouples Technology: Analog, Digital, Wireless, Infrared Application: Industrial Process Control, HVAC Systems, Food Processing, Automotive Testing End User: Chemical Industry, Oil & Gas, Energy Sector, Manufacturing |
| Companies Covered | Honeywell International Inc., KEYENCE CORPORATION, Panasonic Corporation, TE Connectivity, Siemens AG, Microchip Technology Inc., Maxim Integrated, ABB, Omron Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Thermocouple Temperature Sensors Market Strategic Shifts
Wireless connectivity and noble metal sheathing advances are compressing replacement cycles and opening premium application tiers. These shifts favor suppliers with integrated transmitter manufacturing and calibration laboratory networks.
Mineral-insulated thermocouples with compacted magnesium oxide insulation is overtaking conventional wire-wound designs in vibrating process equipment. Steel mills in India and Vietnam specify MI construction for rolling mill pyrometry. This construction is overtaking legacy designs because mechanical durability reduces unplanned furnace shutdowns.
China's GB standards alignment with IEC 60584 is repositioning import compliance requirements. Heavy industry procurement offices in Shandong and Jiangsu now accept IEC-certified test reports for tender qualification. Regional sensor distributors are consolidating product lines around dual-certified inventory.
Buyer preference for bundled calibration services is restructuring channel economics. Japanese automotive OEMs now specify five-point NIST-traceable certificates with every thermocouple shipment. Calibration-capable distributors in Thailand and Malaysia are capturing margin previously retained by third-party laboratories.
Asia-Pacific Thermocouple Temperature Sensors Market Segmentation
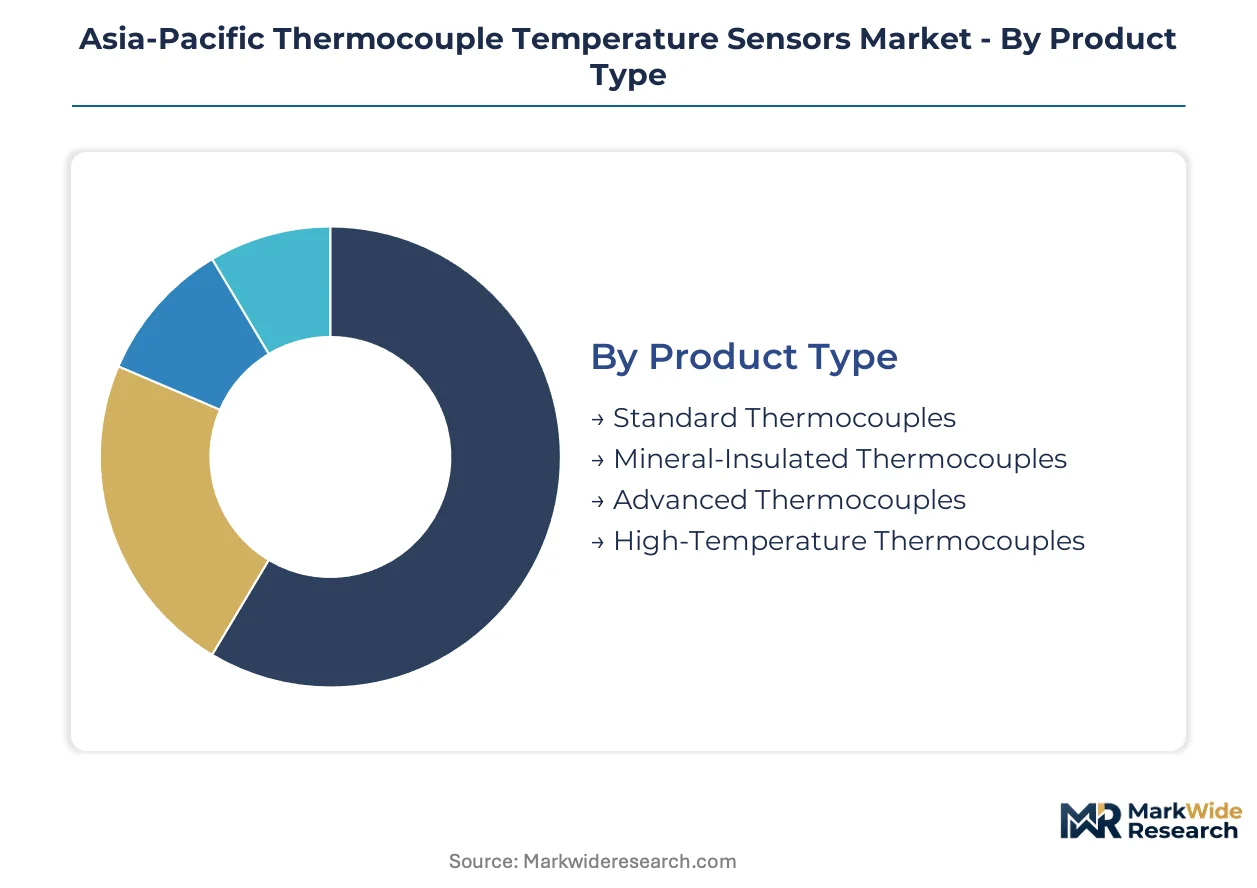
Segmentation reveals how thermocouple specifications map to distinct procurement budgets and replacement cycles across Asia-Pacific heavy industry. Upgrade decisions hinge on temperature range, vibration exposure, and integration with legacy control architectures.
Product Type:
Replacement cycles accelerate where mineral-insulated construction displaces wire-wound alternatives in vibrating process equipment.
- Standard Thermocouples:Basic wire-wound designs with ceramic or fiberglass insulation serve laboratory calibration and light industrial monitoring. Indian steel rerollers specify these for low-vibration zones where cost sensitivity dominates procurement decisions.
- Mineral-Insulated Thermocouples:Compacted magnesium oxide insulation sheathed in stainless steel or Inconel withstands mechanical shock and thermal cycling. Japanese automotive testing facilities now mandate MI construction for engine dynamometer cells, displacing traditional configurations where vibration-induced failures previously caused unplanned shutdowns.
- Advanced Thermocouples:Noble metal sheathing and specialized junction designs target semiconductor crystal growth and aerospace turbine testing. South Korean foundries specify platinum-rhodium variants for precision heat treatment.
- High-Temperature Thermocouples:Tungsten-rhenium and iridium-rhodium pairings operate above 1800 degrees Celsius in vacuum and inert atmospheres. Indonesian nickel smelters in Sulawesi deploy these for rotary kiln monitoring.
Volume placements concentrate in Mineral-Insulated Thermocouples; the faster expansion belongs to Advanced Thermocouples.
Technology:
Cost tiers separate analog legacy installations from digital retrofit projects and wireless greenfield deployments.
- Analog:Millivolt signal transmission dominates existing 4-20 mA loop infrastructure. Southeast Asian cable manufacturers retain analog thermocouples where control system replacement budgets remain constrained.
- Digital:Smart transmitters with HART or Foundation Fieldbus protocols enable remote diagnostics and drift compensation. Australian pharmaceutical plants specify digital outputs for TGA-compliant batch documentation.
- Wireless:Battery-powered ISA100 or WirelessHART modules eliminate conduit runs in sprawling process units. Thai petrochemical complexes are retrofitting wireless transmitters to reduce cabling costs in corrosion-prone coastal environments.
- Infrared:Non-contact pyrometers displace thermocouples in steel reheat furnaces above 1200 degrees Celsius where optical access permits. Chinese Shandong steelmakers substitute infrared where slag buildup previously degraded contact sensors.
Installed base weighting favors Analog; Wireless is climbing the fastest among upgrade investments.
Application:
Application segmentation tracks how temperature measurement requirements diverge across process intensity and regulatory exposure.
- Industrial Process Control:Furnace, reactor, and heat exchanger monitoring in continuous process industries. Vietnam's expanding steel sector drives procurement for rolling mill pyrometry.
- HVAC Systems:Building automation and district heating networks. South Korean smart city projects specify thermocouples for geothermal heat pump monitoring.
- Food Processing:Pasteurization, sterilization, and cold chain validation. Australia's TGA and South Korea's MFDS impose overlapping calibration requirements that favor multi-certified suppliers.
- Automotive Testing:Engine dynamometer, exhaust gas, and battery thermal runaway testing. Japanese OEMs require five-point NIST-traceable certificates with every shipment.
Procurement volume centers on Industrial Process Control; Food Processing shows the steepest expansion trajectory from regulatory tightening.
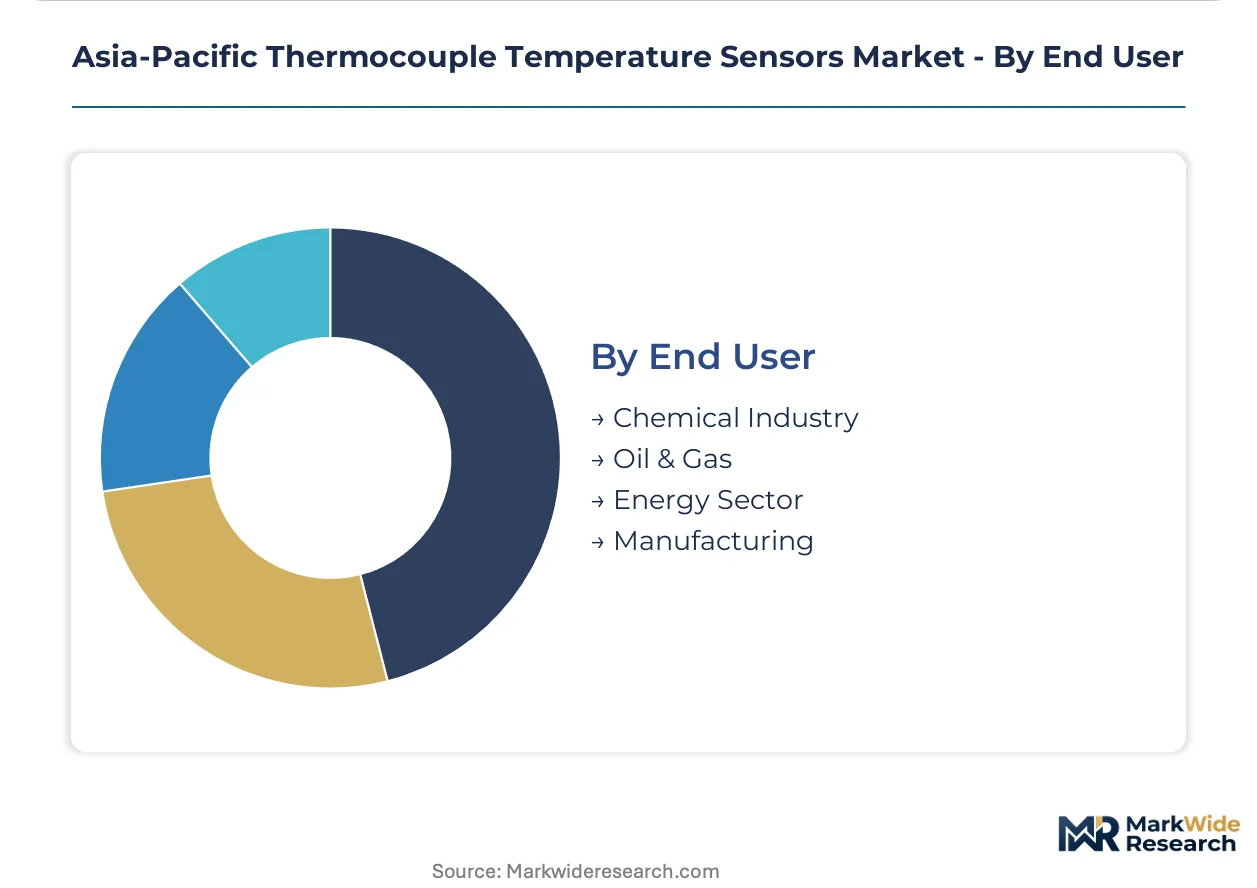
End User:
Customer type segmentation reflects capital expenditure cycles and safety-critical application density.
- Chemical Industry:Reactor temperature control and exothermic process monitoring. Malaysian petrochemical corridors specify MI thermocouples for naphtha cracker furnaces.
- Oil & Gas:Refinery process heaters, flare stack monitoring, and LNG liquefaction. Singapore's Jurong Island refining cluster drives demand for high-reliability assemblies.
- Energy Sector:Coal-fired boilers, gas turbines, and nuclear containment. India's CEA mandates specific thermocouple grades for thermal power plant safety systems.
- Manufacturing:Heat treatment, forging, and additive manufacturing. Chinese machine tool builders integrate thermocouples for metal 3D printer chamber control.
Contract flow concentrates in Oil & Gas; Manufacturing is gaining share fastest from industrial automation investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial parks in Batam and Batu Kawan anchor sensor assembly concentration as Southeast Asian smelter investments accelerate thermocouple procurement cycles across the region.
China
Shandong and Jiangsu steelmakers drive MI thermocouple demand for rolling mill pyrometry. MIIT's tightened energy-efficiency mandates force continuous furnace monitoring upgrades. Procurement offices in these provinces now accept IEC-certified test reports for tender qualification, reducing technical barriers for dual-certified suppliers.
Japan
Automotive OEMs in Aichi and Kanagawa prefectures specify five-point NIST-traceable certificates with every thermocouple shipment. METI enforces JIS C 1602 calibration protocols that restrict market access for uncertified imports. Japanese mineral-insulated cable production clusters around three prefectures, creating seismic vulnerability in the supply base.
India
BIS operates phased mandatory certification for industrial thermocouples under its Compulsory Registration Order, filtering out uncertified imports. Steel rerollers in Gujarat and Maharashtra specify standard wire-wound designs for low-vibration zones where cost sensitivity dominates. India's CEA mandates specific thermocouple grades for thermal power plant safety systems.
Indonesia
Nickel processing investments in Sulawesi and Maluku generate demand for high-temperature thermocouples in rotary kiln and electric furnace installations. The country's national industrial regulator monitors smelter environmental compliance, extending sensor deployment timelines. Indonesian smelter operators prioritize tungsten-rhenium pairings for vacuum atmosphere monitoring above 1800 degrees Celsius.
South Korea
MFDS maintains validation requirements for pharmaceutical manufacturing environments that overlap with Australia's TGA standards. Foundries in Gyeonggi-do specify platinum-rhodium variants for precision heat treatment. Smart city projects in Seoul specify thermocouples for geothermal heat pump monitoring, diversifying demand beyond heavy industry.
Asia-Pacific Thermocouple Temperature Sensors Market Competitive Environment
Japanese producers anchor one tier; German and American multinationals hold process automation integration. The vendor base splits between consolidated instrumentation groups and specialized cable fabricators. Three archetypes dominate: diversified industrial conglomerates bundling sensors into control systems; mineral-insulated cable specialists with captive magnesium oxide compaction; and calibration-capable distributors capturing service margin. Competitive moves concentrate on backward integration into noble metal sheathing and geographic expansion through Southeast Asian cable manufacturing partnerships.
Within the diversified instrumentation tier, Honeywell International Inc. and Siemens AG exemplify bundled offering strategies. Honeywell leverages flame safety and combustion control portfolio breadth to anchor premium positioning in Chinese petrochemical complexes. Siemens dominates process automation integration, embedding thermocouple modules into distributed control systems for regional refineries. TE Connectivity represents scale-driven manufacturing archetypes, sustaining production across Southeast Asian cable and connector facilities.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| KEYENCE CORPORATION |
| Panasonic Corporation |
| TE Connectivity |
| Siemens AG |
| Microchip Technology Inc. |
| Maxim Integrated |
| ABB |
| Omron Corporation |
| Others |
Value Chain & Pricing Dynamics
Japanese automotive OEM procurement clusters anchor premium pricing for NIST-traceable calibration bundles, while Indian steel rerollers drive spot-market transactions for standard wire-wound configurations. This buyer-archete concentration forces suppliers to maintain parallel pricing architectures serving compliance-heavy and cost-sensitive segments simultaneously.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to mineral-insulated thermocouples from Japanese cable fabrication clusters facing seismic disruption risk. Pricing stratifies across JIS-certified premium tiers, BIS-registered standard tiers, and uncertified economy imports for laboratory calibration. Cost compression in the standard tier intensifies as Chinese suppliers achieve IEC 60584 dual certification and compete on Shandong steelmaker tenders. Indian steel rerollers exhibit highest price sensitivity, while Japanese automotive testing facilities absorb premium pricing for vibration-resistant MI construction and bundled five-point calibration certificates.
Supply Chain Analysis
Specialized magnesium oxide compaction technicians concentrate in three Japanese prefectures, constraining global mineral-insulated cable output expansion. Raw material sourcing draws from South African platinum-rhodium mines, Chinese magnesium oxide processors, and German precision alloy foundries. Single-source vulnerability concentrates in noble metal sheathing supply, where South African mining output fluctuations transmit directly to Type S and Type R thermocouple cost structures. Distribution runs through calibration-capable distributors in Thailand and Malaysia capturing service margin previously retained by third-party laboratories, with direct OEM relationships dominating Japanese and South Korean automotive channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's BIS Compulsory Registration Order constructs a cost-of-compliance barrier filtering uncertified imports and rewarding early certification investment with structural demand capture. This regulatory moat advantages suppliers with established calibration laboratory networks and dual GB-IEC certification capability.
For Market Incumbents: Lock in channel control through exclusive calibration service partnerships with Japanese automotive OEMs requiring five-point NIST-traceable certificates. Deepen backward integration into noble metal sheathing production to offset South African platinum-rhodium price volatility compressing Type S and Type R margins. Infrared pyrometer substitution in steel reheat furnaces above 1200 degrees Celsius threatens contact sensor volume; defend position by bundling wireless transmitter modules for legacy analog loop retrofit cycles in Southeast Asian cable manufacturing corridors. For New Entrants and Emerging Players: Indonesian nickel smelter operators in Sulawesi and Maluku represent an underserved buyer archetype demanding tungsten-rhenium high-temperature thermocouples for rotary kiln monitoring above 1800 degrees Celsius. Australian pharmaceutical manufacturers facing TGA validation requirements overlap with South Korean MFDS standards, creating bundled multi-country sensor opportunities with limited incumbent penetration. Enter through calibration-capable distributor partnerships in Thailand and Malaysia, capturing service margin through NIST-traceable certificate bundling rather than competing on hardware pricing alone. For Investors and Strategic Acquirers: The window for entry favors mineral-insulated cable specialists with captive magnesium oxide compaction capability and established JIS C 1602 calibration protocols. Long-term viability hinges on GB-IEC harmonization completion reducing technical barriers for dual-certified suppliers targeting Chinese heavy industry procurement. Watch for BIS registration timeline acceleration in India as the signal indicating structural demand consolidation toward compliant supplier bases and margin expansion for certified market participants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Noble Metal Sheathing | South African platinum-rhodium volatility threatens Type S and Type R margin pools without captive alloy supply. |
| Calibration Laboratory Network Expansion | Japanese automotive OEMs mandate five-point NIST-traceable certificates, shifting margin from hardware to service bundling. |
| Dual GB-IEC Certification Investment | Shandong and Jiangsu steelmakers now accept IEC-certified test reports, reducing technical barriers for compliant entrants. |
| Wireless Transmitter Module Development | Thai petrochemical complexes retrofit coastal installations to eliminate corrosion-prone conduit runs and reduce cabling costs. |
| Southeast Asian Distribution Partnerships | Calibration-capable distributors in Thailand and Malaysia capture margin previously retained by third-party testing laboratories. |
Study Parameters
Trade association filings, customs export records, and national standards body certification databases formed the secondary backbone for supply-side calibration. Primary interviews with maintenance directors at Indian steel rerollers, Japanese automotive testing facility engineers, Indonesian nickel smelter operations managers, and Thai petrochemical procurement leads validated demand-side segmentation assumptions. Bottom-up unit economics triangulated against top-down industrial automation capex flow analysis produced volume and value estimates across the projection horizon.
Bottom-up modeling anchored in mineral-insulated cable fabrication capacity, noble metal sheathing output, and wireless transmitter module shipment data. Segmentation dimensions included product construction type, signal transmission technology, application intensity tier, and end-user industry vertical. CAGRs derived from regression analysis against industrial energy-efficiency mandate implementation timelines and smelter investment cycle phasing. Forecast inputs incorporated MIIT enforcement trajectory for Chinese steelmakers and BIS registration order phase-in schedules for Indian industrial thermocouple procurement.
Revisions become necessary when noble metal price volatility exceeds historical bands, seismic disruption affects Japanese magnesium oxide compaction clusters, or infrared pyrometer substitution accelerates beyond steel reheat furnace applications into adjacent high-temperature process monitoring. Material deviation in these triggers warrants pause and re-evaluation of installed base assumptions and replacement cycle projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Hydrogen Pressure Sensor Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Position Sensor Market
Sensors and Controls
Smart Control Socket Market
Sensors and Controls
2D Gesture Recognition Market
Sensors and Controls
ECG Sensor Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Europe Sensors Market
Sensors and Controls
Specialty Control Plasma Market
Sensors and Controls
Ingestible Sensor Market
Sensors and Controls
Chemical Sensors Market
Sensors and Controls
Accelerometer and Gyroscope Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Active Vibration Control Market
Sensors and Controls
Digital Angle Gauge Market