
 2D Gesture Recognition Market | 2026-2036
2D Gesture Recognition Market Size, Share, and Industry Trends Forecast 2026-2036
2D Gesture Recognition Market Analysis
Buyer concentration across automotive OEMs is rebalancing as tier-one suppliers fragment touchless HMI procurement across multiple gesture recognition vendors. Intel Corporation leverages its RealSense depth-sensing portfolio to anchor optical sensor deployments in industrial automation. Microsoft Corporation competes through Azure Kinect integration for enterprise collaboration platforms. Qualcomm Technologies Inc. specializes in low-power vision processors for embedded automotive interfaces.
2D gesture recognition captures and interprets planar hand movements through camera-based or sensor-based input systems, typically operating at frame rates between 30-60 fps with spatial resolutions of 640x480 to 1920x1080 pixels for real-time human-machine interaction. The technology serves commercial purposes ranging from consumer electronics navigation to sterile medical environment control where physical contact poses contamination risks. Optical Sensors dominate hardware shipments due to mature CMOS supply chains and cost scalability, while Software Solutions capture expanding margin pools as algorithm licensing models replace perpetual device sales. Integrated Systems are gaining fastest in automotive interfaces where OEMs demand pre-validated sensor-processor-software bundles to reduce development cycles.
The EU AI Act classifies biometric gesture data as high-risk AI, compelling vendors to implement conformity assessments before CE marking deployment in European consumer devices. The FDA regulates touchless surgical interface systems under medical device software guidelines, requiring clinical validation for gesture-controlled operating room equipment. Stakeholders must monitor evolving national biometric privacy laws as fragmented compliance obligations multiply deployment costs across jurisdictions.
Market Dynamics
Automotive OEM consolidation around touchless HMI platforms is compressing vendor qualification timelines while fragmenting procurement across tier-one suppliers, forcing gesture recognition providers to restructure R&D roadmaps around pre-validated system bundles.
Growth Catalysts
- EU AI Act compliance mandates:High-risk biometric classification accelerates conformity assessment investments, creating first-mover advantages for vendors with established CE marking pathways.
- Sterile medical environment protocols:FDA-regulated surgical interfaces drive demand for contactless control systems in operating rooms where contamination risks prohibit physical touch.
- CMOS sensor cost curves:Mature optical supply chains enable 640x480 to 1920x1080 resolution deployments at consumer electronics price points, expanding addressable hardware volumes.
Market Restraints
- Biometric data fragmentation:GDPR Article 9 special category processing requirements multiply legal review costs across Germany, France, and Italy deployments.
- Frame rate limitations:30-60 fps capture speeds constrain real-time responsiveness in high-velocity automotive gesture applications.
- Software margin compression:Algorithm licensing models face downward pressure from open-source computer vision libraries commoditizing basic gesture classification.
Strategic Opportunities
- Industrial automation retrofit:Legacy manufacturing lines in Japan and South Korea present untapped demand for depth-sensing gesture overlays on existing equipment.
- Azure Kinect ecosystem migration:Enterprise collaboration platforms seek integrated sensor-processor bundles as Microsoft discontinues standalone hardware sales.
- Low-power automotive interfaces:Embedded vision processors enable always-on gesture wake functions without draining electric vehicle battery systems.
Industry Challenges
- Computer vision talent scarcity:Deep learning optimization for edge deployment requires specialized firmware engineers in short supply across Stuttgart and Munich clusters.
- Multi-jurisdiction certification lag:Simultaneous FDA medical device and EU AI Act conformity assessments extend product launch timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2D Gesture Recognition Market |
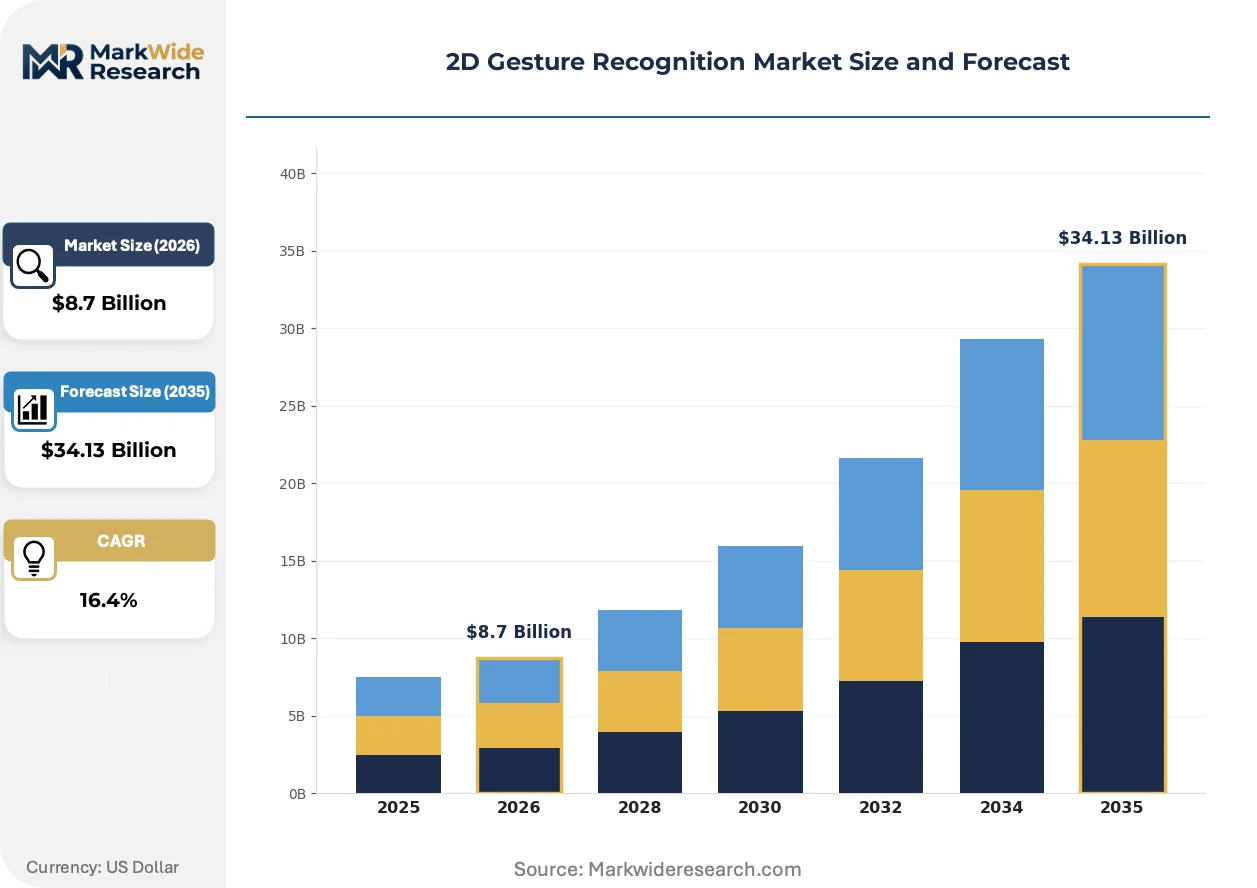
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Optical Sensors, Ultrasonic Sensors, Infrared Sensors, Electric Field Sensors Application: Smart TVs, Gaming Consoles, Virtual Reality, Automotive Interfaces End User: Households, Educational Institutions, Enterprises, Research Labs Product Type: Software Solutions, Hardware Devices, Integrated Systems, Development Kits |
| Companies Covered | Intel Corporation, Apple Inc., Microsoft Corporation, Qualcomm Technologies Inc., Microchip Technology Inc., Infineon Technologies AG, Cognitec Systems, Advanced Micro Devices Inc., NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2D Gesture Recognition Market Emerging Trajectories
Edge inference architectures are redistributing computational load away from cloud-dependent gesture pipelines, enabling real-time response latencies critical for safety-sensitive automotive and medical deployments.
Time-of-flight depth sensing is decentralizing gesture recognition from fixed workstation installations to mobile and embedded environments. Automotive tier-one suppliers in Germany are integrating these sensors into steering wheel and center console modules at accelerated qualification cycles. The shift compresses hardware margins while expanding software licensing attach rates for gesture classification algorithms.
GDPR Article 35 data protection impact assessments are mandating privacy-by-design architectures for biometric gesture systems deployed in European consumer electronics. Vendors must demonstrate lawful basis for processing special category data before CE marking, forcing algorithm developers to implement on-device processing that eliminates cloud transmission of raw skeletal data. Medical device manufacturers face overlapping obligations from the EU AI Act and MDR, requiring dual conformity documentation.
Subscription-based algorithm licensing is displacing perpetual software sales in enterprise gesture deployments. Industrial automation buyers in Japan prefer recurring payment models that bundle continuous model retraining for evolving production line gestures. The transition concentrates vendor revenue visibility but demands sustained customer success investments to prevent churn in the first renewal cycle.
2D Gesture Recognition Market Segmentation
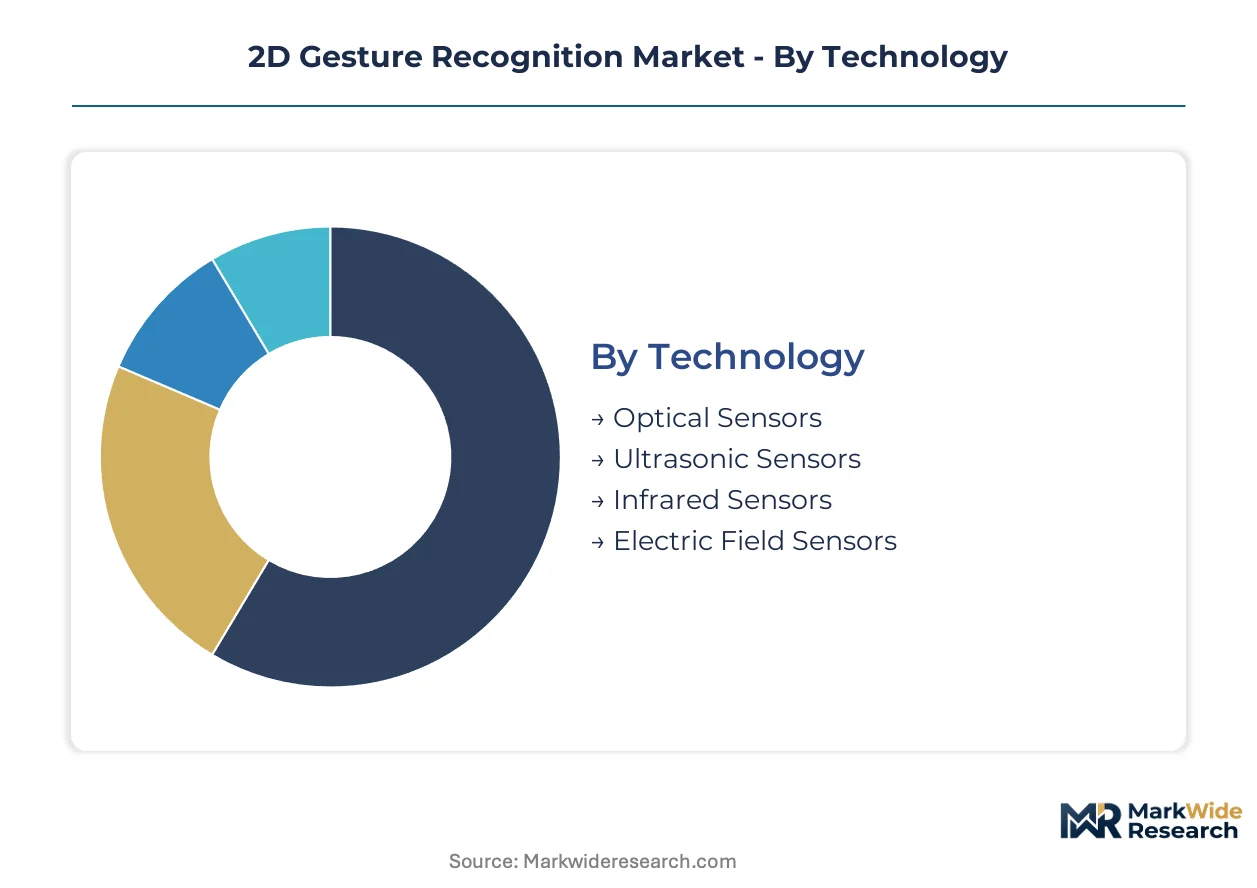
Technology heterogeneity in 2D gesture recognition creates distinct procurement patterns across end-use verticals. Each segmentation axis reveals where margin pools concentrate versus where volume commoditization pressures dominate.
Technology:
Optical sensing architectures anchor hardware economics through mature CMOS supply chains, while alternative modalities compete on specific environmental tolerances.
- Optical Sensors:CMOS-based camera systems capture planar hand movements at 30-60 fps with 640x480 to 1920x1080 spatial resolution. German automotive OEMs in Stuttgart and Munich specify these for production-line touchless HMI due to cost scalability and established CE marking pathways.
- Ultrasonic Sensors:Piezoelectric transducer arrays detect gestures through time-of-flight acoustic ranging, enabling operation in low-light industrial environments. Japanese manufacturing retrofits favor this modality where optical interference from ambient particulate would degrade CMOS performance.
- Infrared Sensors:Structured IR illumination penetrates opaque surfaces for through-glass gesture detection in automotive center console modules.
- Electric Field Sensors:Capacitive field perturbation sensing enables proximity detection without line-of-sight requirements in compact consumer electronics form factors.
Mature deployment sits with Optical Sensors. Newer deployment is concentrated in Ultrasonic Sensors.
Application:
End-use fragmentation forces vendors to maintain parallel qualification tracks across consumer, enterprise, and regulated medical environments.
- Smart TVs:Living-room gesture navigation demands low-latency algorithms processed on embedded SoCs rather than cloud-dependent pipelines. South Korean electronics manufacturers drive volume specifications for 3-5 meter range recognition.
- Gaming Consoles:Controller-free input systems require sub-50ms motion-to-photon latency for competitive multiplayer responsiveness. Microsoft Azure Kinect discontinuation has fragmented procurement across alternative depth-sensing vendors.
- Virtual Reality:Inside-out hand tracking eliminates external base station requirements for standalone headsets.
- Automotive Interfaces:Driver distraction regulations from Germany's KBA and NHTSA mandate gaze-aware gesture activation before command execution.
Volume concentration tracks Smart TV deployments. Value expansion is climbing the fastest in Automotive Interfaces.
End User:
Procurement authority varies dramatically across buyer types, from centralized IT purchasing in Enterprises to fragmented consumer decision-making in Households.
- Households:Price-sensitive consumer adoption depends on out-of-box calibration simplicity and ambient lighting tolerance. GDPR Article 9 compliance for biometric data processing creates friction in European consumer onboarding flows.
- Educational Institutions:K-12 and university deployments prioritize durability and multi-user profile management for shared device access.
- Enterprises:Corporate collaboration platforms demand IT-administered security policies with on-premise processing to prevent cloud data egress. Subscription-based algorithm licensing dominates procurement over perpetual sales.
- Research Labs:Academic and industrial R&D facilities purchase development kits for custom gesture vocabulary training on specialized manipulation tasks.
Standardized purchasing sits with Enterprises. Experimental deployment is expanding most quickly in Research Labs.
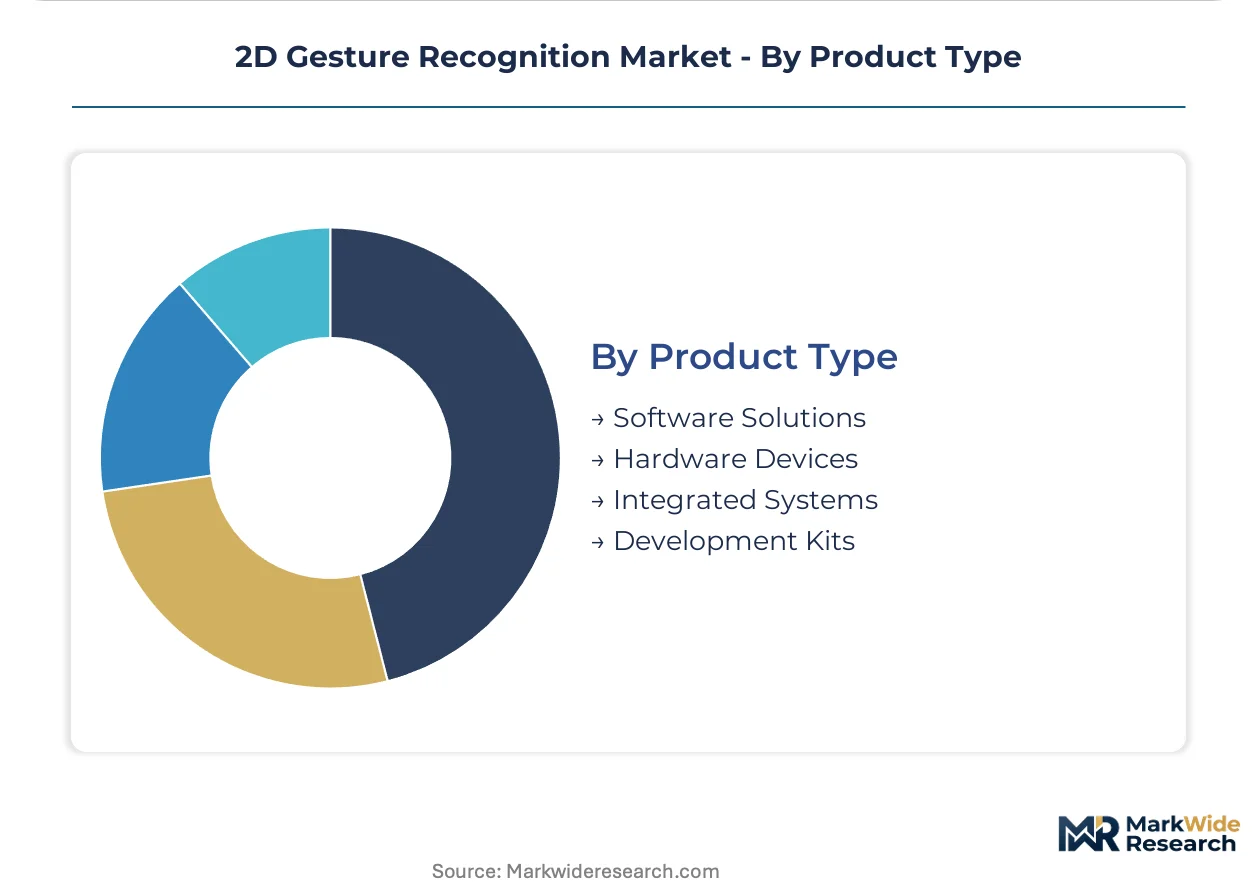
Product Type:
Margin structure inverts across the hardware-software boundary as algorithm licensing displaces device-centric revenue models.
- Software Solutions:Gesture classification SDKs and runtime licenses deploy across heterogeneous sensor hardware through abstraction APIs. FDA-regulated surgical interface vendors in the US specify these for medical device software validation pathways.
- Hardware Devices:Standalone cameras and sensor modules face margin compression from open-source computer vision libraries commoditizing basic gesture detection.
- Integrated Systems:Pre-validated sensor-processor-software bundles reduce automotive OEM development cycles through single-vendor qualification. EU AI Act high-risk biometric classification accelerates demand for pre-certified integrated offerings.
- Development Kits:Reference designs and evaluation platforms enable gesture vocabulary customization before production commitment.
Revenue visibility concentrates in Software Solutions. Procurement acceleration is gaining share fastest in Integrated Systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon wafer fabrication capacity in South Korea and Taiwan feeds sensor supply chains for 2D gesture recognition hardware. Automotive electronics clusters in Germany and consumer electronics manufacturing in China concentrate demand for optical and time-of-flight modules. Regulatory fragmentation across GDPR, EU AI Act, and FDA jurisdictions shapes deployment timelines.
United States
FDA-regulated surgical interfaces and NHTSA driver distraction standards propel touchless HMI demand in medical and automotive verticals. The FDA requires clinical validation for gesture-controlled operating room equipment under medical device software guidelines. California's Bay Area hosts computer vision R&D labs optimizing edge inference architectures for sub-50ms latency.
Germany
Automotive OEMs in Stuttgart and Munich specify pre-validated sensor-processor-software bundles for production-line deployment. The EU AI Act classifies biometric gesture data as high-risk AI, compelling conformity assessments before CE marking. KBA regulations mandate gaze-aware gesture activation before command execution in driver interfaces.
China
Consumer electronics manufacturers drive volume specifications for 640x480 to 1920x1080 resolution optical sensors at price-sensitive tiers. MIIT standards govern embedded vision processor certification for smart TV and gaming console integration. The Yangtze River Delta concentration of CMOS foundries enables cost scalability for gesture hardware shipments.
Japan
Industrial automation retrofits favor ultrasonic sensors where optical interference from ambient particulate degrades CMOS performance. METI programs support manufacturing line modernization with touchless control overlays. The Nagoya automotive cluster evaluates time-of-flight depth sensing for steering wheel module integration.
South Korea
Electronics manufacturers specify 3-5 meter range recognition for living-room gesture navigation on embedded SoCs. The MFDS regulates medical device software for touchless surgical interfaces under harmonized standards. Seoul Capital Area R&D facilities optimize low-power vision processors for always-on gesture wake functions.
2D Gesture Recognition Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue specialized depth-sensing modalities and edge inference architectures. The vendor base stratifies across semiconductor incumbents with sensor portfolios, software specialists licensing classification algorithms, and integrated system providers bundling pre-validated offerings. Three archetypes dominate: optical sensor suppliers leveraging mature CMOS supply chains, algorithm developers monetizing through subscription licensing, and automotive-focused integrators compressing OEM qualification cycles. Competitive moves concentrate on strategic partnerships for pre-certified system bundles and technology licensing to fragmenting tier-one suppliers.
Within the semiconductor archetype, Intel Corporation and Qualcomm Technologies Inc. anchor positions through depth-sensing and low-power vision processor portfolios respectively. Microsoft Corporation exemplifies the platform-integrator model through Azure Kinect ecosystem relationships. Infineon Technologies AG represents European-based sensor specialization with automotive qualification expertise. These three occupy distinct competitive vectors without direct product overlap.
| Leading Market Players |
|---|
| Intel Corporation |
| Apple Inc. |
| Microsoft Corporation |
| Qualcomm Technologies Inc. |
| Microchip Technology Inc. |
| Infineon Technologies AG |
| Cognitec Systems |
| Advanced Micro Devices Inc. |
| NXP Semiconductors |
| Others |
Supply Flow & Price Mechanics
CMOS wafer price indices cascading from South Korean and Taiwanese foundries stratify gesture recognition hardware into three tiers: automotive-grade modules with extended temperature warranties, standard consumer electronics SKUs, and unbundled sensor components for industrial retrofitters.
Pricing Analysis
Extended warranty and algorithm retraining bundling separates premium integrated systems from standard hardware-only shipments. Pricing stratifies across premium, standard, and economy tiers based on EU AI Act pre-certification status and volume procurement scale. Cost compression in consumer-grade optical sensors intensifies because open-source computer vision libraries commoditize basic gesture detection. Educational institutions exhibit highest price sensitivity due to constrained capital budgets, while automotive OEMs prioritize qualification speed over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based CMOS foundry capacity for high-resolution image sensors. Hardware production draws from South Korea, Taiwan, and China's Yangtze River Delta for silicon wafer fabrication, lens assembly, and final module integration. Tariff exposure on semiconductor components threatens margin stability for European and North American system integrators. Distribution runs through tier-one automotive suppliers and direct enterprise sales teams for pre-validated bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
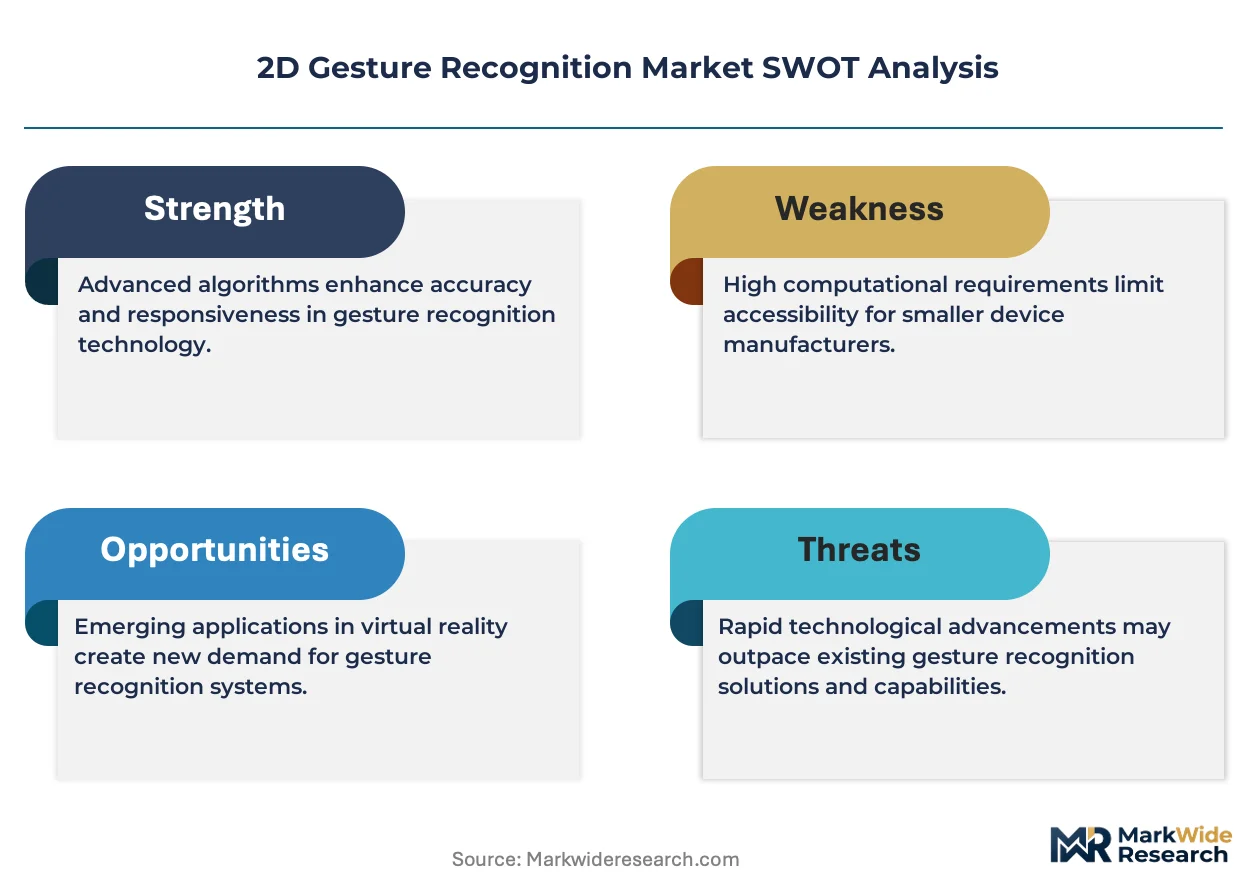
This market consolidates around vendors with established CE marking pathways, as EU AI Act compliance costs force sub-scale algorithm developers toward acquisition or exit.
For Market Incumbents: Deepen backward integration into CMOS sensor design to capture margin pools escaping to Taiwanese foundries. Fortify automotive qualification pipelines against emerging ultrasonic sensor entrants from Japanese industrial automation vendors. Prioritize on-device processing architectures that eliminate GDPR Article 35 data protection impact assessment friction. For New Entrants and Emerging Players: FDA medical device software guidelines in the United States open a window for surgical interface specialists lacking European conformity assessment resources. Target industrial automation retrofits in Japan's Nagoya automotive cluster where ultrasonic modalities outperform optical alternatives. Pursue subscription-based algorithm licensing to bypass hardware margin compression. For Investors and Strategic Acquirers: Distressed-cycle entries favor computer vision software specialists with FDA 510(k) clearances in California's Bay Area. Long-term viability hinges on edge inference patent portfolios rather than cloud-dependent gesture pipelines. Watch for EU AI Act enforcement actions against non-compliant consumer electronics as an inflection signal for pre-certified integrated system demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Pre-Certification Investment | CE marking acceleration compresses OEM qualification timelines for Stuttgart and Munich automotive clusters. |
| Edge Inference Architecture Development | On-device processing eliminates GDPR Article 9 special category data transmission risks. |
| Ultrasonic Sensor Portfolio Expansion | Time-of-flight acoustic ranging captures Japanese manufacturing retrofit demand. |
| Subscription Licensing Model Transition | Recurring revenue visibility concentrates vendor-customer relationships in enterprise segments. |
| Automotive Tier-One Supplier Partnership | Pre-validated bundles reduce development cycles for touchless HMI deployments. |
Methodological Framework
Multi-period observation of CMOS sensor shipment volumes, algorithm licensing deal announcements, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with automotive platform engineers, biomedical device regulatory leads, industrial automation procurement managers, and edge inference firmware architects. Secondary validation drew from FDA 510(k) clearance databases, EU AI Act implementation guidance, SEC semiconductor capex disclosures, and German KBA technical documentation. Bottom-up sensor unit estimates and top-down gesture system revenue aggregates were triangulated against foundry utilization reports.
Input-output matrices mapped technology adoption curves across optical, ultrasonic, infrared, and electric field modalities against end-use verticals including automotive, medical, consumer electronics, and industrial automation. CAGRs were derived from segmented growth rate differentials applied across the projection horizon. Forecast inputs incorporated electric vehicle touchless HMI penetration assumptions and sterile surgical environment protocol adoption rates.
The model assumes a particular technology adoption path; alternative pathways for time-of-flight depth sensing would alter the outlook if automotive OEMs accelerate steering wheel module integration ahead of schedule. Forecasts reflect assumptions about EU AI Act enforcement intensity and FDA medical device software validation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Wireless Temperature Sensor Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Vacuum Pressure Sensors Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Global Thermocouple Temperature Sensors Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Asia-Pacific Current Transducer Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Asia-Pacific Machine Control System Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
South Korea Sensors Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
US Vibration Sensors Market