
 Collision Sensors Market | 2026-2036
Collision Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Collision Sensors Market Outlook
Fleet operators is rotating toward integrated collision avoidance systems as automotive OEMs consolidate procurement under long-term platform contracts. Continental AG leverages in-house radar and lidar manufacturing to control sensor module supply chains. Robert Bosch GmbH sustains broad patent coverage across ultrasonic and camera fusion architectures. Denso Corporation anchors production capacity in Toyota City and adjacent industrial corridors.
Collision sensors detect proximity, velocity, and object classification through electromagnetic or acoustic emission and reception, typically operating at 24 GHz or 77 GHz for automotive radar with detection ranges from 0.2 to 250 meters depending on modality. Their primary commercial purpose is to enable automatic emergency braking, adaptive cruise control, and parking assistance in vehicles and mobile equipment. Radar sensors dominate volume in highway-speed applications where all-weather reliability matters most, while lidar sensors capture premium positioning in robotaxi and Level 4 automation programs where centimeter-level ranging justifies cost. Camera systems compete on software-extensible platforms that allow over-the-air algorithm updates through machine learning pipelines.
NHTSA mandates automatic emergency braking on new light vehicles in the United States, while Euro NCAP scoring protocols in Europe reward multi-sensor fusion configurations that exceed baseline regulatory thresholds. Japan's METI coordinates standards harmonization through JIS frameworks to accelerate domestic OEM export compatibility. Stakeholders must monitor divergence between SAE automation level definitions and regional type-approval processes that fragment sensor validation requirements.
Market Dynamics
Automotive OEMs are consolidating sensor procurement under long-term platform contracts, compressing supplier margins while demanding multi-modal fusion capabilities that integrate radar, lidar, and camera architectures into unified collision avoidance systems.
Growth Catalysts
- NHTSA Automatic Emergency Braking Mandate:The United States regulator now requires automatic emergency braking on all new light vehicles, creating baseline demand for radar and camera modules across passenger and commercial fleets.
- Euro NCAP Scoring Protocols:European safety rating incentives reward multi-sensor fusion configurations that exceed regulatory minimums, pushing OEMs toward premium sensor suites.
- Industrial Corridor Clustering:Production concentration in Toyota City, Stuttgart, and Detroit enables just-in-time sensor module delivery to adjacent vehicle assembly plants.
Market Restraints
- Semiconductor Wafer Constraints:77 GHz radar MMICs and lidar SPAD arrays depend on specialized foundry capacity concentrated in Taiwan and South Korea.
- Lidar Cost Structure:Solid-state lidar modules remain priced at multiples of radar alternatives, limiting deployment to premium vehicle segments and robotaxi fleets.
- SAE-Euro NCAP Divergence:Misalignment between American automation level definitions and European type-approval processes fragments sensor validation requirements.
Strategic Opportunities
- Japan METI Standards Harmonization:JIS framework coordination accelerates domestic OEM export compatibility, reducing duplicate certification costs.
- Agricultural Autonomy:Collision avoidance systems for autonomous tractors and harvesters represent underpenetrated demand outside passenger vehicle applications.
- Over-the-Air Algorithm Updates:Camera-based platforms with machine learning pipelines enable continuous performance improvement without hardware replacement.
Industry Challenges
- Sensor Fusion Engineering Talent:Shortage of engineers capable of integrating radar point clouds, lidar voxels, and camera image streams into unified perception stacks.
- Functional Safety Certification:ISO 26262 ASIL-D compliance for highway-speed automatic braking extends development timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collision Sensors Market |
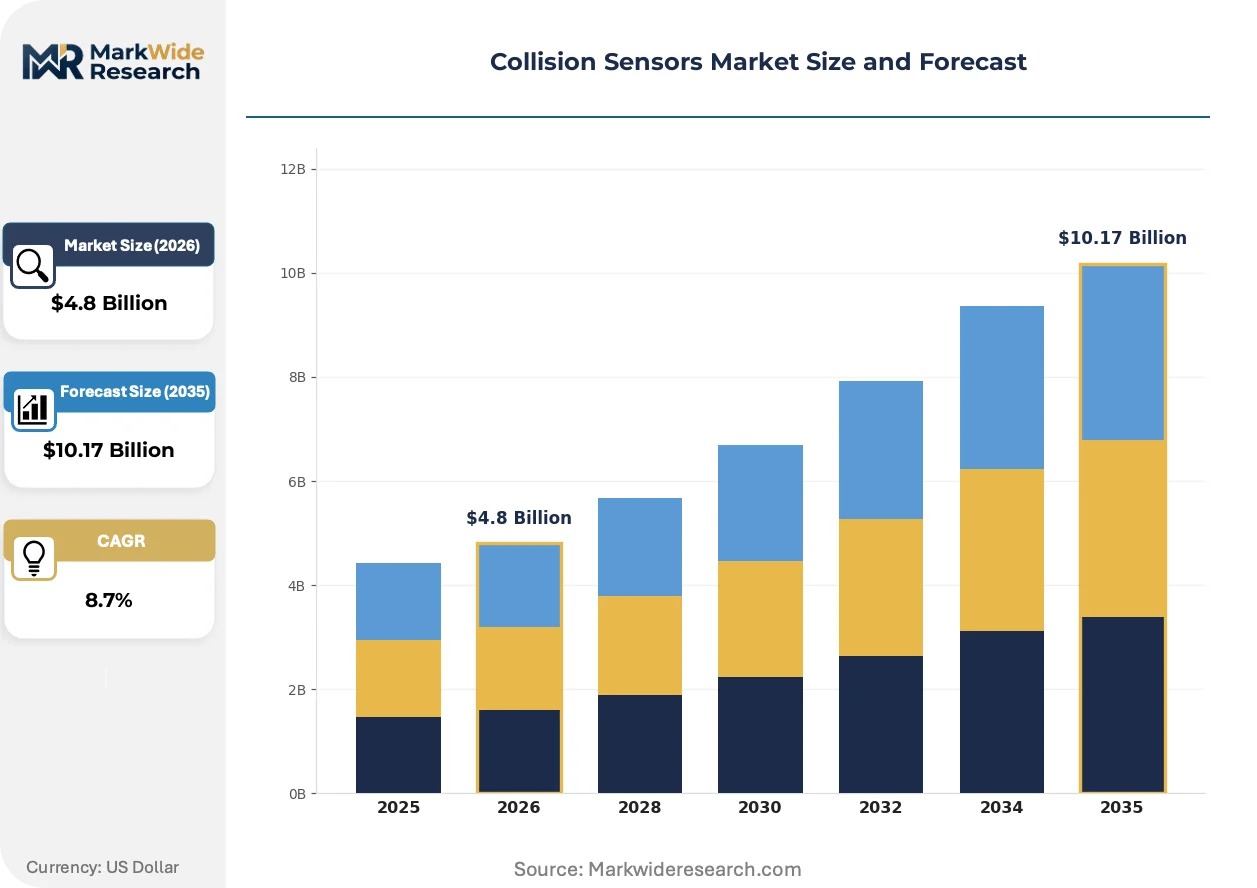
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Sensors, Radar Sensors, Lidar Sensors, Camera Systems End User: Automotive OEMs, Aftermarket Installers, Fleet Operators, Insurance Companies Technology: Image Processing, Machine Learning, Signal Processing, Wireless Communication Installation Type: Integrated Systems, Standalone Devices, Embedded Sensors, External Add-ons |
| Companies Covered | Continental AG, Robert Bosch GmbH, Denso Corporation, ZF Friedrichshafen AG, Aptiv PLC, NXP Semiconductors N.V., Infineon Technologies AG, Texas Instruments Inc., Murata Manufacturing Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collision Sensors Market Strategic Shifts
Sensor modality convergence is redefining competitive advantage, with software-defined perception platforms enabling algorithmic differentiation independent of hardware refresh cycles.
4D imaging radar is supplanting conventional 3D radar in highway-speed applications by delivering elevation data alongside range, azimuth, and Doppler velocity. Continental and Bosch are deploying these modules in premium European sedan platforms. The technology is supplanting entry-level lidar in all-weather highway automation by achieving comparable object classification at substantially lower unit cost.
EU AI Act risk classification rules now categorize autonomous emergency braking as high-risk AI, imposing documentation and human oversight requirements on training data governance. This classification extends development timelines for European-market sensor suites. Tier-one suppliers are responding by segregating AI training pipelines between regulatory jurisdictions.
Fleet operators now specify outcome-based sensor performance contracts tied to collision frequency reduction rather than hardware specifications. This procurement model shift compresses supplier margins while transferring operational risk to sensor vendors. North American commercial trucking fleets are pioneering these arrangements through long-term leasing structures.
Collision Sensors Market Segmentation
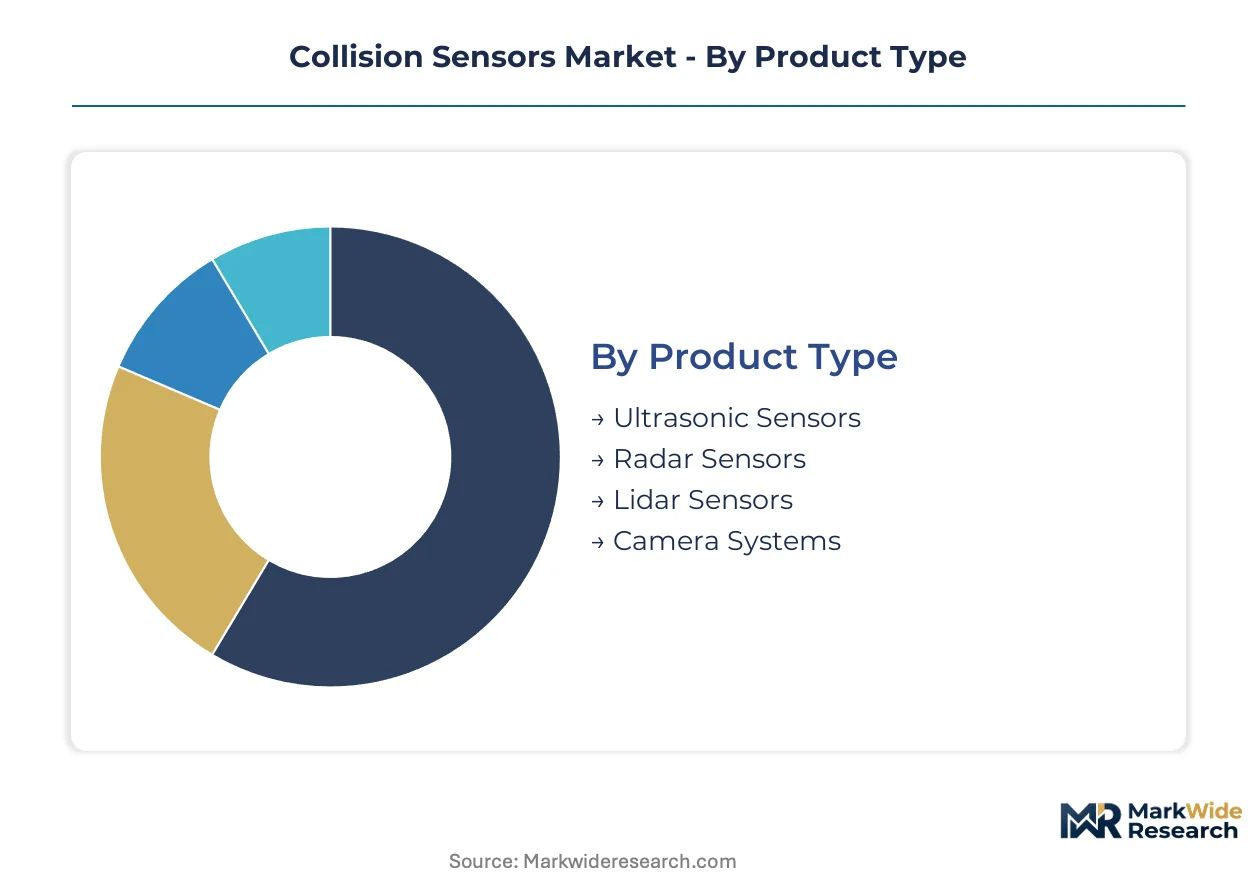
Collision sensor procurement flows through distinct channel architectures that shape how each segment captures value. Understanding these pathways reveals why certain technologies dominate OEM contracts while others thrive in retrofit markets.
Product Type:
Radar and camera modules move through long-term platform contracts with automotive OEMs, while lidar and ultrasonic sensors split between factory integration and aftermarket retrofit channels.
- Radar Sensors:77 GHz and 24 GHz modules emit electromagnetic pulses to detect object range, velocity, and azimuth in all-weather conditions. Highway-speed automatic emergency braking systems in Germany, Japan, and the United States absorb the majority of volume, with NHTSA mandates cementing baseline demand across light vehicle fleets.
- Camera Systems:CMOS and CCD image sensors paired with machine learning pipelines enable lane departure warning and traffic sign recognition. European OEMs concentrate procurement under Euro NCAP scoring protocols that reward multi-sensor fusion configurations exceeding regulatory minimums.
- Lidar Sensors:Solid-state and mechanical scanning modules deliver centimeter-level ranging for robotaxi and Level 4 automation programs.
- Ultrasonic Sensors:Acoustic proximity detection for parking assistance and low-speed maneuvering dominates entry-level vehicle segments.
By volume, radar sensors lead. By growth pace, lidar sensors are climbing the fastest.
End User:
Cost tier stratification separates premium sensor suites bound for luxury OEM platforms from price-sensitive aftermarket retrofit demand.
- Automotive OEMs:Tier-one suppliers deliver radar, lidar, and camera modules under multi-year platform contracts spanning vehicle generations. Toyota City, Stuttgart, and Detroit industrial corridors enable just-in-time sensor module delivery to adjacent assembly plants.
- Fleet Operators:Commercial trucking and logistics companies specify outcome-based performance contracts tied to collision frequency reduction rather than hardware specifications. North American long-haul fleets pioneered these arrangements through leasing structures that transfer operational risk to sensor vendors.
- Aftermarket Installers:Independent service centers retrofit collision avoidance systems to existing vehicle populations.
- Insurance Companies:Usage-based policy incentives drive policyholder adoption of telematics-integrated collision sensors.
Automotive OEMs command the largest revenue share. Fleet operators are expanding most quickly.
Technology:
Application maturity varies sharply, with signal processing representing decades-old automotive heritage while machine learning pipelines require continuous algorithm governance.
- Signal Processing:Analog-to-digital conversion, filtering, and Fourier transform algorithms extract object data from raw radar returns. Legacy highway-speed automatic braking systems in the United States and Germany rely on these deterministic methods for ISO 26262 ASIL-D functional safety certification.
- Machine Learning:Convolutional neural networks and transformer architectures enable camera-based object classification with over-the-air update capability. The EU AI Act now categorizes autonomous emergency braking as high-risk AI, imposing documentation requirements on European-market training data governance.
- Image Processing:Edge detection, stereo depth estimation, and optical flow computation support real-time scene understanding.
- Wireless Communication:V2X protocols enable vehicle-to-vehicle and vehicle-to-infrastructure collision warnings.
Signal processing retains volume leadership. Machine learning shows the steepest expansion trajectory.
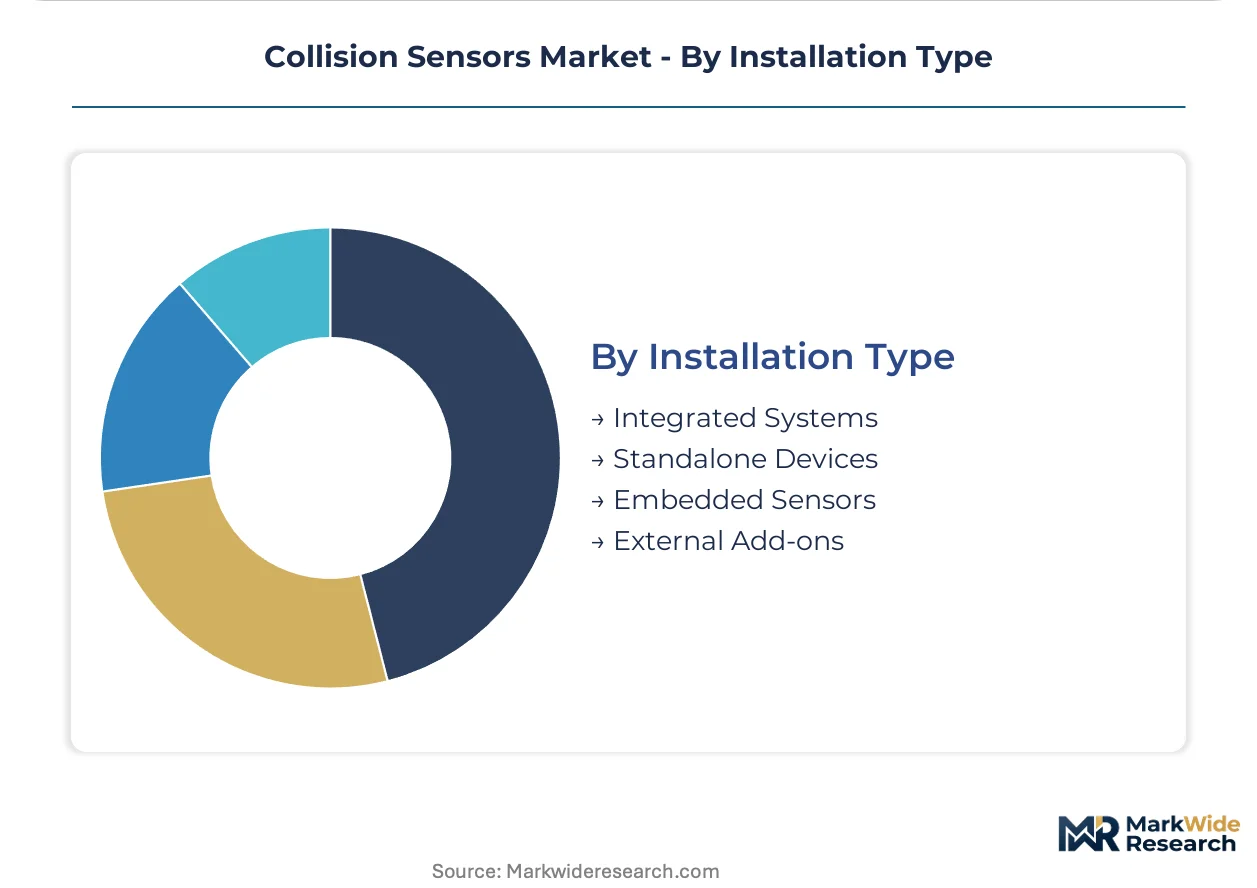
Installation Type:
Supply concentration favors integrated systems manufactured adjacent to vehicle assembly, while standalone devices serve dispersed aftermarket demand.
- Integrated Systems:Radar, camera, and lidar modules engineered into vehicle bumpers, windshields, and rooflines during original assembly. Stuttgart-based tier-one suppliers co-locate manufacturing with Mercedes-Benz and BMW final assembly to compress logistics costs.
- Embedded Sensors:Micro-electromechanical components fused into steering columns, side mirrors, and door panels. Japanese OEMs in Toyota City anchor production capacity for these applications.
- Standalone Devices:Portable or dash-mounted units for retrofit installation.
- External Add-ons:License plate frames, bumper-mounted pods, and roof-mounted arrays for commercial vehicle retrofit.
Integrated systems dominate value capture. Embedded sensors are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput anchors Germany's automotive sensor export corridor to global vehicle assembly networks. Japan's Chubu Centrair International Airport freight terminal supports just-in-time component delivery across East Asian manufacturing zones. The Detroit-Windsor Ambassador Bridge crossing enables seamless radar module transit between Michigan assembly plants and Ontario tier-one suppliers.
United States
NHTSA automatic emergency braking mandates drive baseline radar and camera module demand across light vehicle fleets. The regulator's crash-avoidance compliance thresholds tighten annually, forcing OEMs toward multi-sensor fusion configurations. Detroit's industrial corridor concentrates tier-one manufacturing adjacent to Ford, General Motors, and Stellantis final assembly plants.
Germany
Euro NCAP safety rating protocols reward premium sensor suites exceeding baseline regulatory minimums. The KBA federal motor transport authority enforces type-approval standards that fragment validation requirements from American SAE definitions. Stuttgart's manufacturing belt hosts Continental AG and Robert Bosch GmbH production facilities within kilometers of Mercedes-Benz and BMW headquarters.
Japan
METI coordinates JIS standards harmonization to accelerate domestic OEM export compatibility across European and North American markets. The ministry's framework reduces duplicate certification costs for sensor vendors serving multiple jurisdictions. Toyota City's industrial corridor anchors Denso Corporation production capacity adjacent to Toyota Motor Corporation vehicle assembly.
China
MIIT mandates advanced driver-assistance system penetration targets for domestic passenger vehicle sales. The ministry's GB standards framework governs electromagnetic compatibility and functional safety certification for radar modules. Yangtze River Delta manufacturing clusters in Shanghai and Jiangsu province concentrate lidar startup production near NIO and XPeng headquarters.
South Korea
MFDS automotive safety guidelines align with Euro NCAP protocols to support Hyundai and Kia export competitiveness. The regulator's harmonization efforts reduce sensor validation duplication for vehicles bound for European markets. Seoul Capital Area semiconductor foundries supply specialized MMIC capacity for 77 GHz radar modules deployed in highway-speed applications.
Collision Sensors Market Competitive Environment
Listed leaders compete with private specialists across patent coverage and manufacturing scale. The vendor base clusters around three strategic archetypes: diversified automotive tier-one suppliers with captive semiconductor fabrication, specialized sensor module manufacturers with deep OEM relationships, and semiconductor foundries supplying MMIC and SPAD components. Competitive positioning hardens through backward integration into radar chip design and strategic partnerships for lidar volume manufacturing.
Among diversified tier-one suppliers, Continental AG and Robert Bosch GmbH exemplify the integrated manufacturing archetype, while Denso Corporation anchors the Asia-Pacific production corridor. These three entities represent distinct geographic concentrations—German engineering heritage, Stuttgart industrial clustering, and Toyota City supply chain proximity—rather than interchangeable competitive positions. Their collective presence defines the competitive terrain without implying equivalent strategic postures.
| Leading Market Players |
|---|
| Continental AG |
| Robert Bosch GmbH |
| Denso Corporation |
| ZF Friedrichshafen AG |
| Aptiv PLC |
| NXP Semiconductors N.V. |
| Infineon Technologies AG |
| Texas Instruments Inc. |
| Murata Manufacturing Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
ISO 26262 ASIL-D certification gates both supplier qualification and price stratification simultaneously, separating premium-tier sensor modules from commodity alternatives while concentrating procurement leverage among OEMs with multi-year platform contracts. NHTSA and Euro NCAP compliance thresholds further segment pricing power, as tier-one suppliers command sustained margins on highway-speed automatic braking systems while aftermarket installers compete on cost for parking-assistance retrofits.
Pricing Analysis
Volume-discount tiering structures dominate collision sensor procurement, with automotive OEMs extracting graduated price concessions based on platform-scale commitments spanning vehicle generations. Price differentiation rests on certification grade and geographic delivery cost, with ASIL-D validated modules commanding substantial premiums over parking-assistance alternatives. Cost compression in ultrasonic and entry-level radar tiers is intensifying because semiconductor foundry capacity constraints limit supplier bargaining power. Fleet operators exhibit the least price sensitivity due to outcome-based contracting, while aftermarket installers face severe margin pressure from hardware commoditization.
Supply Chain Analysis
Taiwan and South Korea anchor wafer fabrication for 77 GHz radar MMICs and lidar SPAD arrays, while Germany and Japan concentrate module assembly adjacent to OEM final assembly plants. Raw material dependencies include silicon carbide substrates, indium phosphide lasers, and specialized automotive-grade epoxy resins. Single-source vulnerability in Taiwan-based foundry capacity for radar front-end chips exposes tier-one suppliers to geopolitical disruption. Distribution runs through just-in-time pipelines co-located with Stuttgart, Detroit, and Toyota City industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
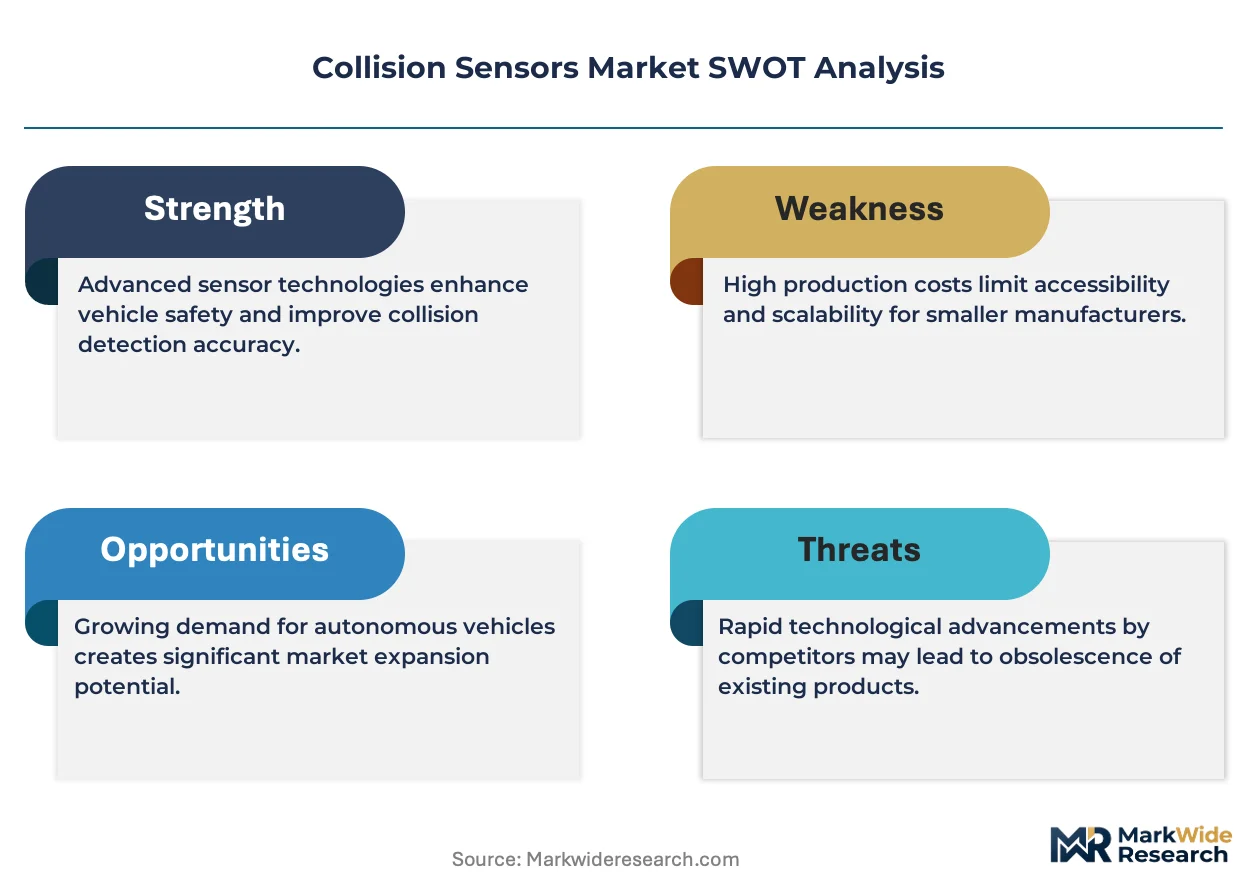
4D imaging radar is displacing entry-level lidar in highway-speed applications, forcing incumbents to defend sensor fusion value propositions against software-defined perception platforms that enable algorithmic differentiation without hardware refresh.
For Market Incumbents: Fortify backward integration into radar chip design to offset foundry dependency, while deepening ASIL-D certification moats against emerging software-centric competitors. Capacity expansion in Toyota City and Stuttgart industrial corridors preserves just-in-time delivery advantages. Patent coverage across ultrasonic and camera fusion architectures sustains licensing leverage against modular sensor startups. For New Entrants and Emerging Players: Differentiate on agricultural autonomy applications, where collision avoidance systems for autonomous tractors and harvesters remain underpenetrated relative to passenger vehicle saturation. Target fleet operator outcome-based contracts in North American commercial trucking, bypassing OEM platform lock-in. Channel partnerships with telematics integrators enable rapid deployment without tier-one supplier certification timelines. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across solid-state lidar manufacturing, favoring acquirers with semiconductor fabrication expertise over pure-play hardware assemblers. Long-term viability in this market hinges on software-defined update capabilities and multi-sensor fusion engineering talent pools. Watch for inflection signals in JIS-Euro NCAP regulatory harmonization progress, which would compress duplicate certification costs and accelerate cross-border M&A rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEM consolidation of sensor suites under long-term contracts reduces supplier fragmentation. |
| Software-Defined Vehicle Investment | Over-the-air algorithm updates enable continuous perception improvement without hardware replacement. |
| Geographic Manufacturing Footprint | Co-location with Toyota City, Stuttgart, and Detroit assembly plants compresses logistics costs. |
| Sensor Fusion Engineering Acquisition | Talent scarcity in integrating radar point clouds, lidar voxels, and camera streams limits organic buildout. |
| Charging Infrastructure Partnership | Collision sensor integration with V2X protocols enables vehicle-to-infrastructure safety networks. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of NHTSA regulatory filings, Euro NCAP test protocols, and vehicle production databases, combining structured interviews with tier-one supplier procurement directors, OEM platform engineers, and aftermarket distribution heads. Automotive semiconductor trade data, IHS Markit registration statistics, and METI JIS framework documentation provided external validation. Bottom-up sensor module shipment estimates and top-down OEM platform content analysis were cross-referenced for triangulation.
Segmentation dimensions modeled include sensor modality, vehicle propulsion architecture, content per vehicle tier, OEM procurement channel, and regional production cluster across the analysis window. CAGRs were derived from installed base projections and technology substitution curves, incorporating NHTSA mandate phase-in schedules and Euro NCAP scoring protocol evolution as demand drivers. Machine learning pipeline governance requirements under the EU AI Act were factored into European-market sensor suite development timelines.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor foundry capacity expansion or accelerated SAE-Euro NCAP regulatory convergence would require recalibration. Forecasts reflect documented assumptions regarding OEM platform contract structures and fleet operator outcome-based procurement adoption. Recalibration cycles align with material shifts in NHTSA compliance thresholds, foundry capacity allocation, and JIS harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
Middle East and Africa Bulk Acoustic Wave Sensors Market
Sensors and Controls
Multi-Function Timer Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
North America Fingerprint Sensor Market
Sensors and Controls
Condition Monitoring System Market
Sensors and Controls
Factory Automation Sensor Market
Sensors and Controls
GCC Air Purifiers Market
Sensors and Controls
Chest Sensors Market
Sensors and Controls
Asia-Pacific Sensors Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
China Pressure Sensors Market
Sensors and Controls
Digital Thermohygrometers Market
Sensors and Controls
Meteorological Devices Market