
 Asia-Pacific Wireless Brain Sensors Market | 2026-2036
Asia-Pacific Wireless Brain Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Wireless Brain Sensors Market Insights
CE marking under the EU MDR is rotating as the de facto quality benchmark that Asia-Pacific exporters must meet before supplying European-linked hospital networks in Australia and Singapore. EMOTIV leverages its San Francisco-APAC dual headquarters structure to sustain regulatory dual-tracking across FDA and TGA pathways. NeuroSky anchors consumer-grade EEG headset production through Shenzhen contract manufacturers, while BrainCo dominates K-12 cognitive training deployments across Chinese provincial education bureaus.
Wireless brain sensors are non-invasive or implantable biopotential acquisition systems that capture neural electrical activity through scalp electrodes or cortical arrays, typically sampling at 256–2048 Hz with Bluetooth 5.0 or proprietary low-energy radio transmission to eliminate tethered laboratory constraints. Their primary purpose is to enable ambulatory neurophysiological monitoring for clinical diagnostics, neurorehabilitation, and human-computer interaction research outside controlled hospital environments. Wearable sensors lead volume shipments due to lower regulatory barriers and expanding direct-to-consumer channels, while brain-computer interface applications represent the fastest-expanding value pool as gaming and assistive-technology developers fund higher-margin electrode arrays. Electroencephalography technology occupies the mature core of installed clinical systems, whereas functional near-infrared spectroscopy is gaining adoption in neonatal and motion-artifact-sensitive settings across Japanese university hospitals.
TGA Australia's medical device framework and Japan's PMDA QMS ordinance shape product registration timelines and post-market surveillance obligations for wireless neural devices entering these markets. China's NMPA revised its innovative medical device fast-track pathway to include brain-computer interface hardware, accelerating domestic company approvals while raising compliance costs for foreign entrants. India's CDSCO medical device rules now classify wireless brain sensors as Class C or D depending on invasiveness, forcing manufacturers to localize clinical evidence generation. Stakeholders must monitor how divergent electromagnetic compatibility standards between Japan's JIS and China's GB testing regimes fragment regional product platform strategies.
Market Dynamics
China's NMPA fast-track pathway for brain-computer interface hardware is compressing approval timelines for domestic manufacturers while elevating compliance barriers for foreign entrants, fundamentally restructuring competitive positioning across the Asia-Pacific region.
Growth Catalysts
- Neurorehabilitation expansion:Japanese and South Korean hospitals are scaling neurofeedback programs for stroke recovery, creating institutional demand for ambulatory EEG systems.
- CDSCO quality tightening:India's tightened medical device rules for wireless neural interfaces are filtering out substandard imports and rewarding certified suppliers with hospital network access.
- Shenzhen-Beijing clustering:Brain-computer interface startups concentrating in China's tier-one cities are generating talent pools and component ecosystems that lower R&D costs for adjacent hardware developers.
Market Restraints
- Electromagnetic compatibility fragmentation:Divergent JIS and GB testing regimes force manufacturers to maintain separate product platforms for Japan and China, inflating engineering overhead.
- Clinical evidence localization:India's Class C/D classification mandates in-country trials, extending time-to-revenue for foreign entrants without established investigator networks.
- Electrode array material costs:High-purity platinum-iridium alloys and biocompatible polymers for implantable sensors face concentrated supply from specialty chemical producers in Germany and the US.
Strategic Opportunities
- Provincial education bureaus:Cognitive training deployments in China's K-12 system represent an underpenetrated channel with lower regulatory barriers than clinical markets.
- TGA-FDA dual tracking:Australia's medical device framework alignment with FDA pathways enables simultaneous market entry across Commonwealth and North American hospital networks.
- fNIRS-neonatal convergence:Functional near-infrared spectroscopy adoption in Japanese university hospitals for motion-sensitive monitoring opens adjacent pediatric applications.
Industry Challenges
- Neuroelectrical signal processing expertise:Shortage of firmware engineers capable of real-time artifact rejection at 256–2048 Hz sampling rates bottlenecks product development cycles.
- Post-market surveillance obligations:Japan's PMDA QMS ordinance demands continuous adverse event reporting that strains quality management infrastructure for mid-scale manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Wireless Brain Sensors Market |
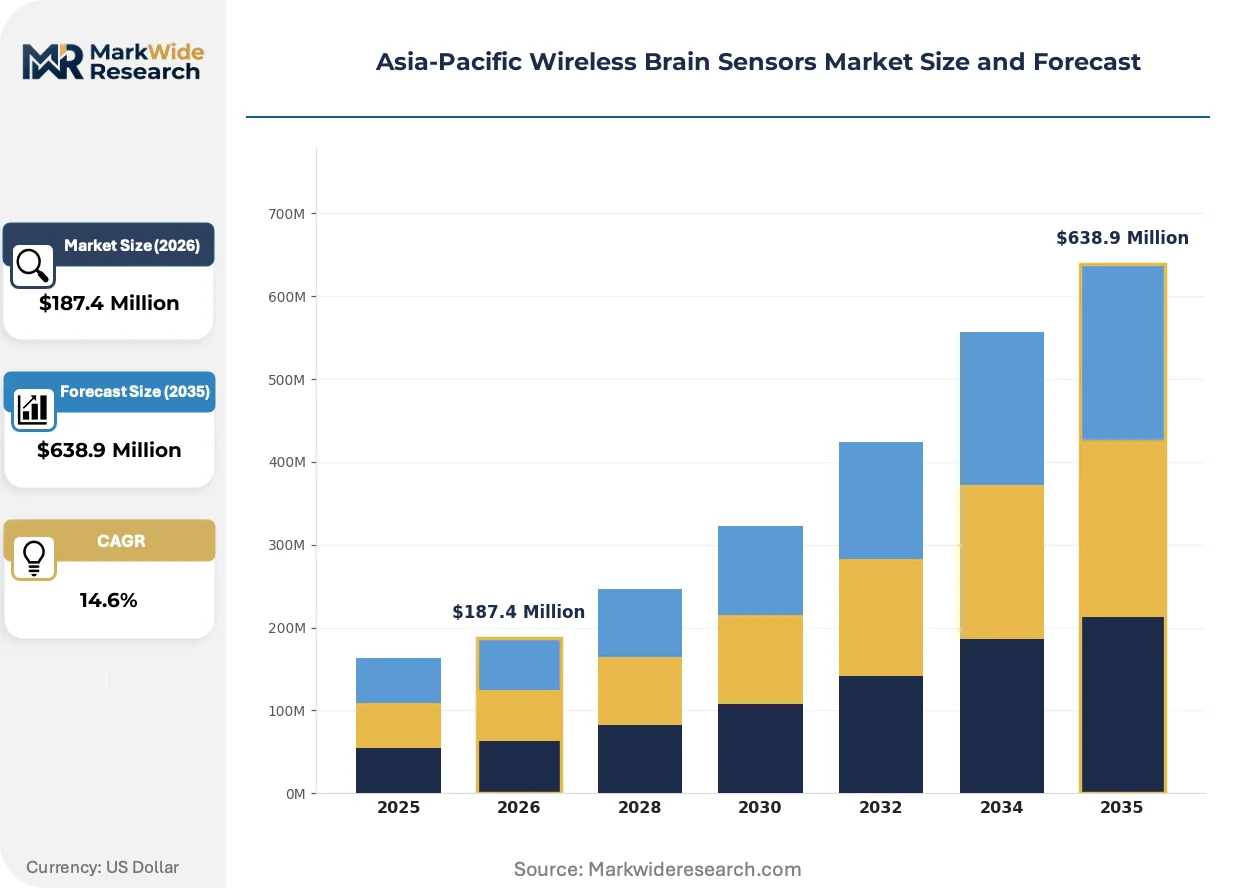
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Wearable Sensors, Implantable Sensors, Portable Monitors, Diagnostic Devices Application: Neurofeedback, Sleep Monitoring, Brain-Computer Interface, Cognitive Enhancement End User: Healthcare Providers, Research Institutions, Patients, Athletic Professionals Technology: Electroencephalography, Functional Near-Infrared Spectroscopy, Magnetoencephalography, Others |
| Companies Covered | Neuroelectrics, Natus Medical Incorporated, EMOTIV, Hangzhou Zhongheng Electric, Koninklijke Philips, NeuroSky, Brain Products GmbH, BrainCo, Advanced Brain Monitoring, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Wireless Brain Sensors Market Trends and Innovations
Bluetooth 5.0 and proprietary low-energy radio transmission protocols are eliminating tethered laboratory constraints, enabling ambulatory neural monitoring that expands addressable use cases beyond traditional hospital settings.
Dry electrode arrays with active shielding are displacing conductive gel-based systems in consumer and clinical wearable segments. Rehabilitation centers in Seoul and Tokyo are piloting these systems for home-based stroke recovery programs. The shift is compressing per-session setup time from fifteen minutes to under sixty seconds, expanding viable patient throughput for outpatient neurofeedback providers.
China's NMPA revised its innovative medical device fast-track pathway to explicitly include brain-computer interface hardware in 2024. Domestic manufacturers now access abbreviated review timelines while foreign entrants face elevated clinical evidence requirements. Tier-one city hospitals in Shenzhen and Beijing are prioritizing NMPA-cleared devices in procurement specifications, tilting competitive dynamics toward local suppliers.
Direct-to-consumer channels are capturing share from traditional medical device distributors across the Asia-Pacific region. Neurotechnology startups in Beijing and Singapore are bypassing hospital procurement committees through e-commerce platforms and subscription-based hardware leasing. The model is most visible in China's tier-one cities, where cognitive training applications for K-12 students bypass clinical regulatory pathways entirely.
Asia-Pacific Wireless Brain Sensors Market Segmentation
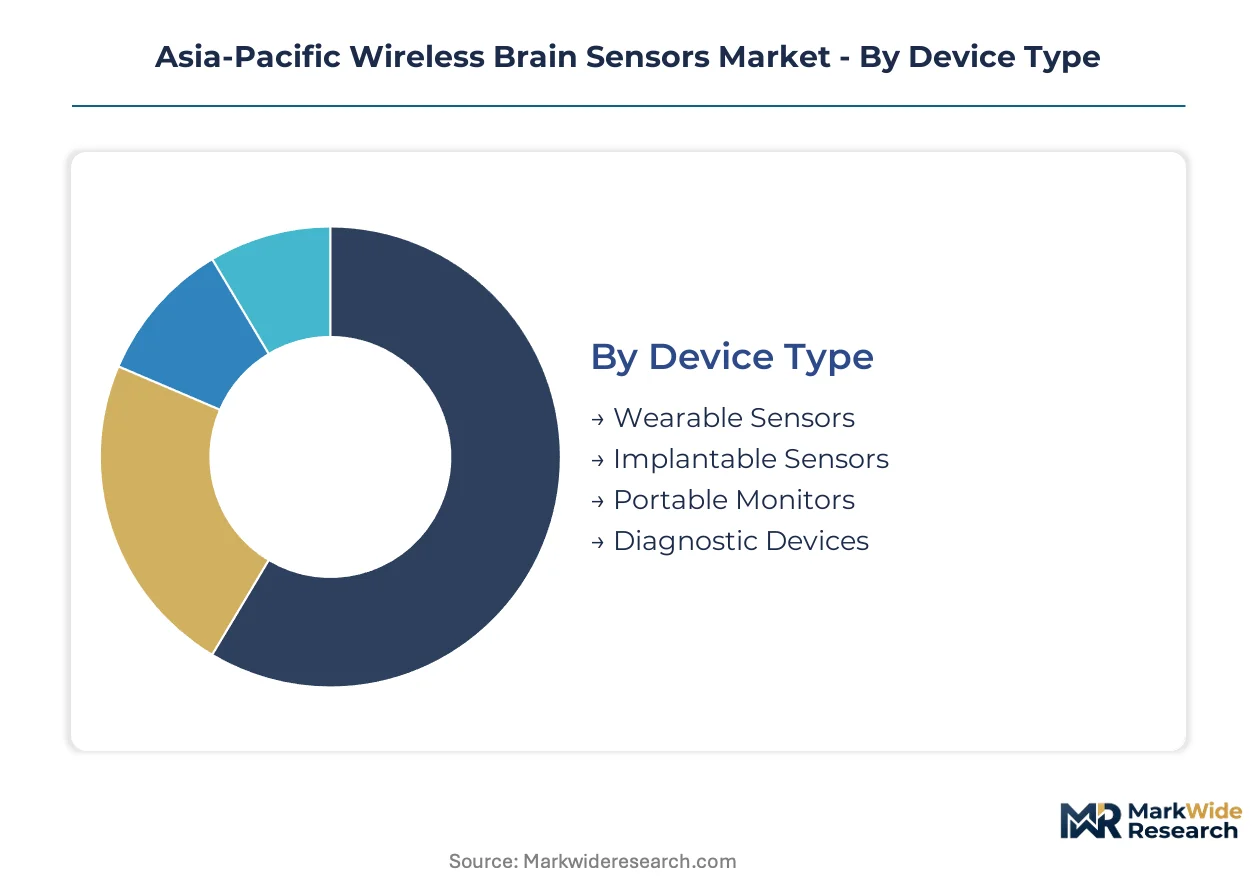
Segmentation reveals how margin pools concentrate across device architectures and use cases in the Asia-Pacific wireless brain sensors landscape. Understanding these divisions exposes where regulatory pathways diverge and which customer segments command pricing power.
Device Type:
Margin pools concentrate in implantable sensors due to biocompatibility certification barriers and concentrated supply of platinum-iridium electrode materials.
- Wearable Sensors:Non-invasive scalp-mounted systems with dry electrode arrays and active shielding. Demand clusters in China's tier-one cities where K-12 cognitive training programs bypass clinical regulatory pathways entirely.
- Implantable Sensors:Cortical arrays requiring biocompatible polymers and hermetic sealing. Japanese university hospitals drive procurement for motion-sensitive neurorehabilitation applications where tethered laboratory constraints are unacceptable.
- Portable Monitors:Ambulatory units sampling at 256–2048 Hz with Bluetooth 5.0 transmission. South Korean stroke rehabilitation centers are scaling home-based neurofeedback deployments.
- Diagnostic Devices:Clinical-grade systems with proprietary low-energy radio protocols. India's CDSCO Class C/D classification mandates are filtering hospital network access toward certified suppliers.
Wearable sensors hold installed capacity. Implantable sensors are rotating up the share rankings.
Application:
Volume concentrates in neurofeedback while value creation shifts toward brain-computer interface hardware.
- Neurofeedback:Real-time neural electrical activity feedback for stroke recovery and attention training. Seoul and Tokyo rehabilitation centers are piloting home-based programs with dry electrode systems.
- Sleep Monitoring:Overnight EEG acquisition for sleep disorder diagnosis. Australian TGA-cleared devices are penetrating direct-to-consumer channels through e-commerce platforms.
- Brain-Computer Interface:Assistive technology and gaming control systems. China's NMPA fast-track pathway is compressing approval timelines for domestic manufacturers while elevating barriers for foreign entrants.
- Cognitive Enhancement:Performance optimization for education and athletic training. BrainCo dominates Chinese provincial education bureau deployments with lower regulatory barriers than clinical markets.
Neurofeedback maintains the largest installed base. Brain-computer interface applications are climbing the fastest.
End User:
Pricing power diverges sharply between institutional procurement committees and direct-to-consumer channels.
- Healthcare Providers:Hospitals and clinics requiring PMDA QMS compliance in Japan and TGA registration in Australia. Japan's continuous adverse event reporting demands strain quality management infrastructure.
- Research Institutions:University laboratories and neuroscience centers. Japanese university hospitals are driving functional near-infrared spectroscopy adoption for neonatal and motion-artifact-sensitive monitoring.
- Patients:Direct purchasers through e-commerce and subscription leasing. Beijing and Singapore startups are bypassing hospital procurement entirely in China's tier-one cities.
- Athletic Professionals:Sports teams and individual performers seeking cognitive performance data. This segment remains underpenetrated relative to education and healthcare channels.
Healthcare providers command the premium tier. Patient-direct channels are gaining share fastest.
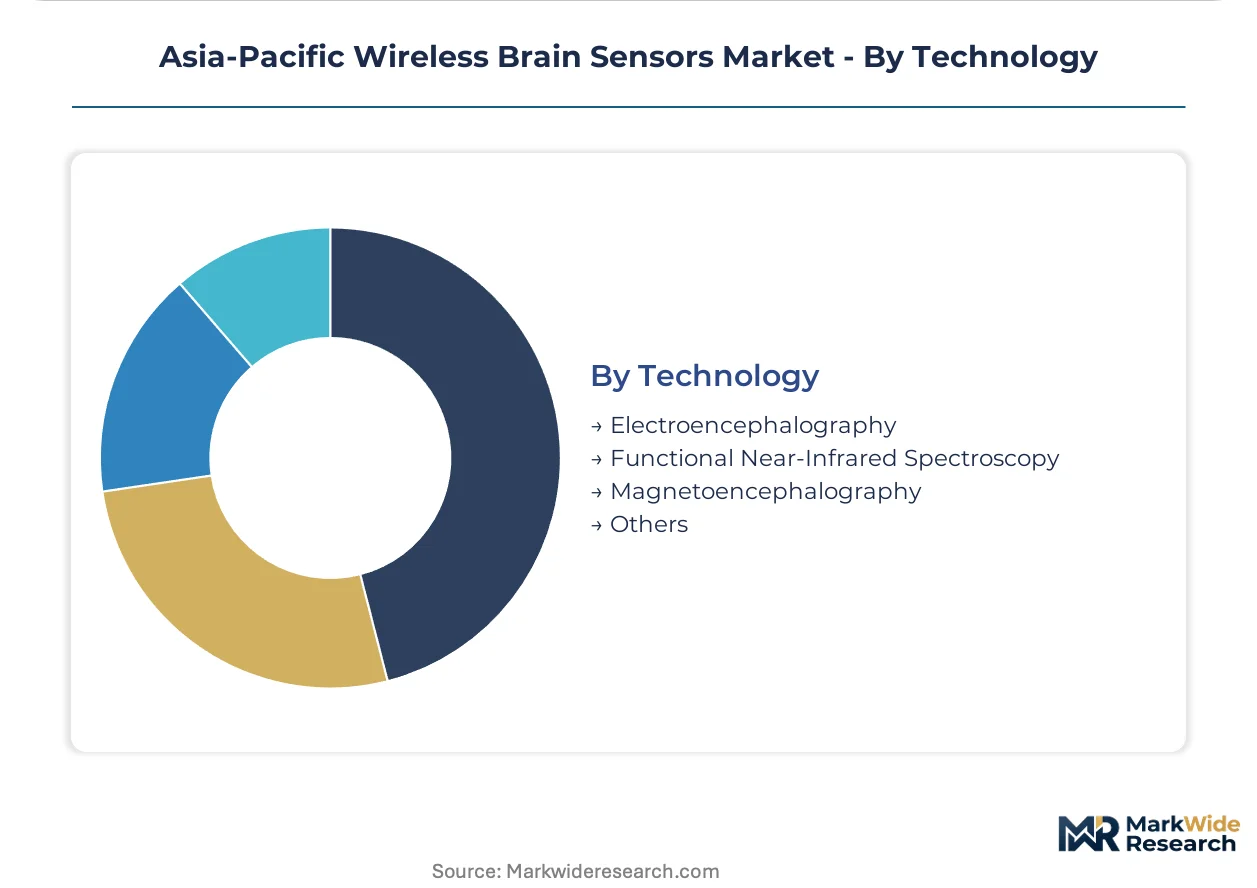
Technology:
Electroencephalography dominates clinical installed base while functional near-infrared spectroscopy captures motion-sensitive niches.
- Electroencephalography:Mature scalp electrode technology sampling neural electrical activity. Shenzhen contract manufacturers anchor consumer-grade headset production for NeuroSky and adjacent brands.
- Functional Near-Infrared Spectroscopy:Optical hemodynamic monitoring resistant to motion artifacts. Japanese university hospitals are expanding pediatric and neonatal applications where EEG signal quality degrades.
- Magnetoencephalography:Superconducting quantum interference device arrays detecting magnetic fields from neural currents. High capital costs and cryogenic cooling requirements limit deployment to elite research centers.
- Others:Emerging modalities including functional ultrasound and electrocorticography. These remain experimental with minimal regulatory clearance pathways in the Asia-Pacific region.
Electroencephalography holds installed capacity. Functional near-infrared spectroscopy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NMPA fast-track pathways and CDSCO classification mandates are redirecting investment flows across national boundaries while fragmenting electromagnetic compatibility requirements.
China
Shenzhen and Beijing brain-computer interface clusters are absorbing venture capital for hardware development. NMPA's 2024 fast-track inclusion of BCI hardware compresses domestic approval timelines while foreign entrants face elevated clinical evidence barriers. Provincial education bureaus in Guangdong and Jiangsu are procuring cognitive training systems outside clinical regulatory pathways.
Japan
PMDA QMS ordinance continuous adverse event reporting demands strain quality management infrastructure for mid-scale manufacturers. METI funding for neurorehabilitation devices supports hospital-based neurofeedback program expansion. Kanto region university hospitals are piloting functional near-infrared spectroscopy for neonatal monitoring applications.
South Korea
Seoul rehabilitation centers are scaling home-based stroke recovery programs with dry electrode EEG systems. MFDS medical device registration aligns with international standards but requires Korean-language labeling and local representative offices. Busan-Ulsan manufacturing corridors are attracting component suppliers for wireless neural acquisition hardware.
India
CDSCO Class C/D classification for wireless neural interfaces mandates in-country clinical trials that extend time-to-revenue for foreign entrants. Hospital networks in Maharashtra and Karnataka are filtering procurement toward CDSCO-certified suppliers. Delhi-NCR research institutions are generating clinical evidence for regulatory submissions.
Australia
TGA medical device framework alignment with FDA pathways enables simultaneous Commonwealth and North American market entry. Direct-to-consumer channels through e-commerce platforms are penetrating sleep monitoring segments. New South Wales and Victoria research hospitals are adopting ambulatory EEG systems for outpatient neurophysiology.
Asia-Pacific Wireless Brain Sensors Market Competitive Landscape
Listed leaders compete with private specialists across regulatory dual-tracking capabilities, creating a tiered structure where scale advantages clash with nimble compliance adaptation. The vendor base separates into three archetypes: multinational health technology conglomerates with established regulatory infrastructure, venture-backed neurotechnology specialists with regional headquarters strategies, and contract manufacturers serving consumer-grade segments. Competitive moves concentrate on geographic expansion through regulatory pathway alignment and portfolio diversification into adjacent neural monitoring modalities.
Within the neurotechnology specialist tier, EMOTIV exemplifies the dual-headquarters archetype spanning San Francisco and Asia-Pacific regulatory jurisdictions. NeuroSky anchors consumer-grade production through Shenzhen manufacturing relationships. BrainCo occupies a position representing the education-focused deployment model across Chinese provincial procurement channels.
| Leading Market Players |
|---|
| Neuroelectrics |
| Natus Medical Incorporated |
| EMOTIV |
| Hangzhou Zhongheng Electric |
| Koninklijke Philips |
| NeuroSky |
| Brain Products GmbH |
| BrainCo |
| Advanced Brain Monitoring |
| Others |
Pricing and Supply Chain Analysis
Sixty-day electrode array lead times from German specialty chemical producers compress margin buffers for Asia-Pacific manufacturers while amplifying pricing power for certified suppliers holding biocompatibility documentation. This inventory pressure cascades into tiered procurement contracts where NMPA-cleared domestic vendors command premium positioning against foreign entrants facing extended CDSCO trial timelines.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA/TGA-grade devices capturing hospital procurement premiums while consumer-grade EEG headsets compete on Shenzhen manufacturing scale. Three-tier pricing structure across premium, standard, and economy levels reflects electromagnetic compliance testing costs—JIS-certified units for Japan trade at 15-20% above GB-compliant equivalents for China. Cost compression in the consumer wearable tier intensifies as dry electrode technology commoditizes, though implantable platinum-iridium arrays resist erosion due to concentrated metallurgical supply. Provincial education bureaus in China exhibit highest price sensitivity, while Japanese university hospitals prioritize signal fidelity over unit economics.
Supply Chain Analysis
Strategic stockpile preferences dominate for platinum-iridium alloys and biocompatible polymers given six-month replenishment cycles from German and US specialty producers, whereas Shenzhen contract manufacturers run just-in-time for consumer-grade headset assembly. Component sourcing concentrates in China for PCB fabrication and Bluetooth modules, Japan for precision electrode manufacturing, and South Korea for display integration. Single-source vulnerability sits with high-purity metallurgical feedstock given limited qualified suppliers for implantable-grade materials. Distribution runs through hospital procurement committees for clinical-grade systems and direct-to-consumer e-commerce for cognitive training applications, with subscription-based hardware leasing emerging as a hybrid channel in tier-one Chinese cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory pathway fragmentation across NMPA, PMDA, CDSCO, and TGA jurisdictions creates specialized compliance niches that reward focused entrants over generalized competitors. Direct-to-consumer channel expansion for K-12 cognitive training bypasses institutional procurement bottlenecks entirely.
For Market Incumbents: Compound regulatory dual-tracking capabilities by establishing parallel FDA-TGA submission pathways that accelerate Commonwealth market access while CDSCO localization requirements extend. Defend against Shenzhen-based BCI startups through exclusive hospital system partnerships in Japan's Kanto region and Australia's New South Wales research corridors. Prioritize backward integration into electrode array metallurgy to offset platinum-iridium supply concentration risk. For New Entrants and Emerging Players: Differentiate on fNIRS-neonatal convergence applications where motion-artifact resistance commands pricing premiums in Japanese university hospital procurement. Target Australia's sleep monitoring segment through TGA-cleared direct-to-consumer channels with subscription hardware leasing models that bypass traditional distributor markups. White-space exists in South Korean home-based stroke rehabilitation deployments where dry electrode systems reduce per-session setup burden. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across the consumer wearable sub-segment as Shenzhen contract manufacturing scales, while implantable sensor development requires sustained R&D commitment. Five-to-ten year viability favors venture-backed neurotechnology specialists with established NMPA fast-track approvals and provincial education bureau relationships over pure hardware commodity plays. Acquisition target archetype: dual-headquartered firms with San Francisco-APAC regulatory infrastructure. Signal to watch: CDSCO Class C/D certification attainment rates among mid-scale foreign entrants as proxy for market access friction.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Fast-Track Pathway Navigation | Domestic manufacturers gain abbreviated review timelines while foreign entrants face elevated clinical evidence barriers. |
| Dual-Headquarters Regulatory Infrastructure | San Francisco-APAC structures enable simultaneous FDA and TGA submission tracking for Commonwealth market penetration. |
| Dry Electrode Array Manufacturing Scale-Up | Shenzhen contract manufacturers reduce per-unit costs for consumer-grade headsets while compressing setup time for clinical applications. |
| Provincial Education Bureau Partnership | K-12 cognitive training deployments in Guangdong and Jiangsu bypass clinical regulatory pathways entirely. |
| Platinum-Iridium Supply Agreement | Long-term offtake contracts with German specialty chemical producers hedge against electrode array material cost volatility. |
Research Methodology
A standing panel of neurotechnology product managers, hospital biomedical engineers, regulatory affairs specialists, and GPO contracts managers provided ongoing calibration against shifting NMPA and CDSCO requirements. Primary interviews with Shenzhen contract manufacturing executives and Tokyo rehabilitation center clinicians combined with secondary validation from FDA 510(k) filings, TGA ARTG registrations, PMDA QMS ordinance updates, and hospital procurement database extracts. Bottom-up shipment estimates from electrode array suppliers triangulated against top-down neurofeedback program expansion metrics across Japanese and South Korean hospital networks.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window, with segmentation modeling spanning device architecture, application use case, end-user procurement channel, and regional regulatory cluster. CAGRs derived from installed base growth rates for EEG systems and venture funding trajectories for BCI hardware startups. Forecast inputs incorporated NMPA fast-track approval velocity, CDSCO trial completion timelines, and provincial education bureau procurement cycle data.
The analysis sits within stated boundaries; outcomes outside sustained NMPA policy continuity or abrupt platinum-iridium supply disruption would require recalibration. Forecasts reflect documented assumptions regarding electromagnetic compatibility standard convergence and hospital neurofeedback program expansion rates. Revision becomes warranted when CDSCO classification enforcement intensity crosses thresholds that fundamentally alter foreign entrant market access economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Steam Trap Monitor Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Printed Antenna Market
Sensors and Controls
Sensor Signal Conditioner (SSC) Ics Market
Sensors and Controls
APAC Acoustic Sensors Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Global Printed Sensor Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
Wired Occupancy Sensors Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
RTD Temperature Sensors Market
Sensors and Controls
High-Performance IMU Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
IR Emitter and Receiver Market
Sensors and Controls
Tactile Indicators Market