
 GPS Tracking Device Market | 2026-2036
GPS Tracking Device Market Size, Share, and Industry Trends Forecast 2026-2036
GPS Tracking Device Market Analysis
Subscription-based fleet financing and hardware-as-a-service leasing models are rewriting capital barriers for mid-size logistics buyers who previously avoided upfront GPS device procurement. Geotab leverages its open-platform ecosystem to sustain enterprise retention across North American fleet portfolios. Samsara competes through integrated video telematics and cloud-based fleet management, while Verizon Connect anchors its position via cellular network density and bundled connectivity contracts.
GPS tracking devices are electronic positioning instruments that receive satellite signals from constellations including GPS, GLONASS, Galileo, and BeiDou to calculate real-time latitude, longitude, and velocity data for remote monitoring of mobile or stationary assets. These devices transmit location information through cellular, satellite, or Bluetooth communication modules to centralized software platforms, enabling route optimization, geofence alerts, and asset recovery across commercial and consumer applications. Fleet trackers occupy the largest revenue pool as commercial carriers prioritize vehicle utilization and driver compliance, while asset trackers represent the fastest-expanding category as construction and shipping firms deploy ruggedized units for high-value equipment monitoring. Cellular technology dominates connectivity architecture due to lower module costs and mature carrier infrastructure, though satellite-based tracking retains premium positioning for remote-zone applications lacking terrestrial coverage.
The U.S. Federal Motor Carrier Safety Administration enforces ELD compliance for interstate commercial drivers, directly mandating GPS-integrated logging devices and shaping hardware specifications nationwide. The European Union's GDPR and vehicle data privacy frameworks constrain how location data is stored and shared, compelling manufacturers to embed encryption and consent-management features. Stakeholders must monitor evolving cybersecurity certification requirements and spectrum allocation decisions for satellite positioning signals as these regulatory layers increasingly determine product design priorities and market access conditions.
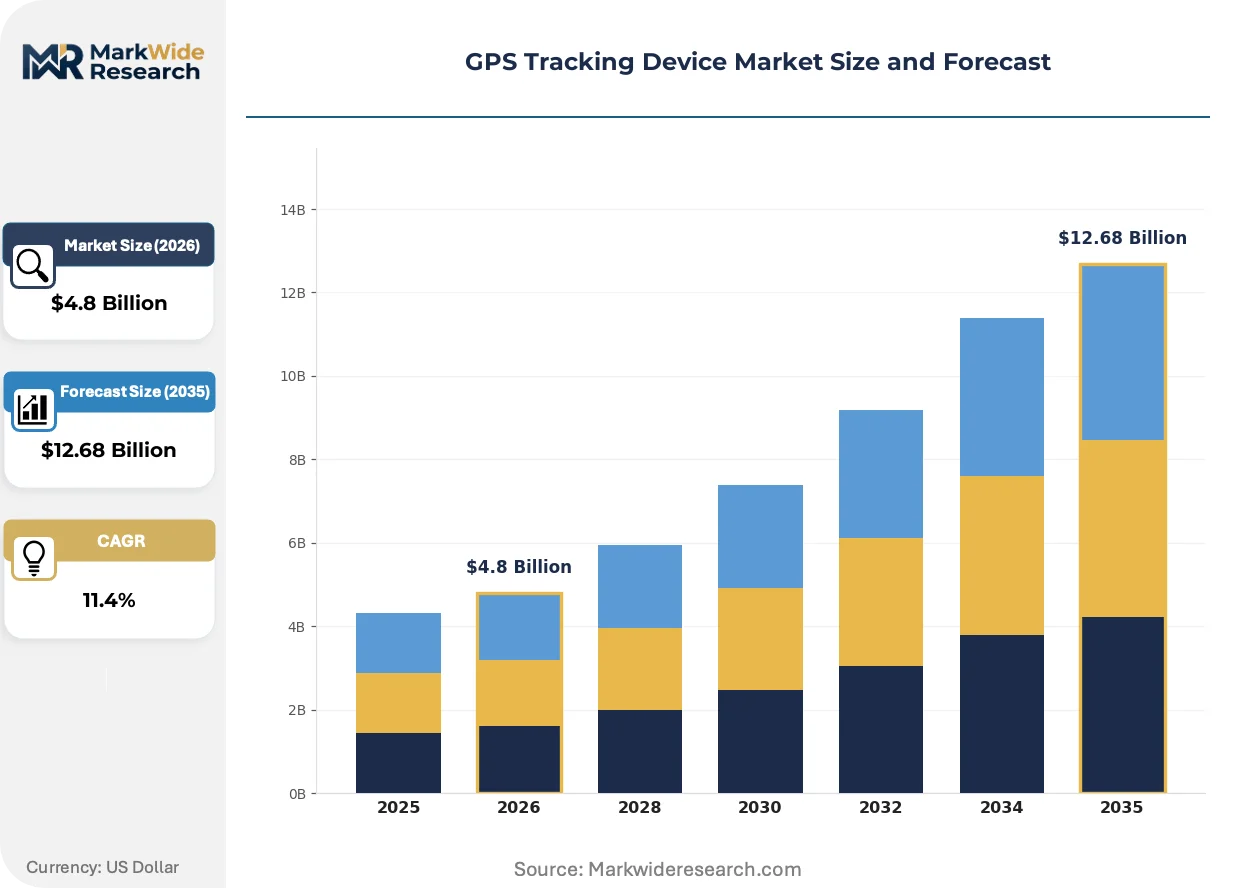
Market Dynamics
The GPS tracking device market is restructuring around subscription-based financing models that eliminate upfront hardware procurement barriers for mid-size fleet operators. Hardware-as-a-service leasing is compressing traditional equipment sales cycles and shifting vendor relationships toward recurring revenue platforms anchored by cellular connectivity contracts.
Growth Catalysts
- ELD Mandate Enforcement:The U.S. Federal Motor Carrier Safety Administration requires electronic logging devices for interstate commercial drivers, compelling GPS-integrated hardware deployment across trucking fleets nationwide.
- Construction Equipment Monitoring:Asset-intensive industries are deploying ruggedized trackers for high-value machinery recovery and utilization optimization, expanding addressable device volumes beyond vehicle pools.
- Multi-Constellation Positioning:Devices integrating GPS, GLONASS, Galileo, and BeiDou signals deliver superior accuracy in urban canyons and remote terrain, elevating performance specifications for precision-dependent applications.
Market Restraints
- Semiconductor Module Volatility:Cellular modem and GNSS chip supply concentrates among a limited supplier base, exposing manufacturers to input cost swings and allocation constraints.
- GDPR Data Friction:The European Union's privacy framework imposes encryption and consent-management requirements that inflate firmware development costs and complicate cross-border fleet deployments.
- Bluetooth Low Energy Substitution:Short-range wireless tags are capturing indoor asset tracking volumes previously addressed by cellular GPS units, compressing pricing power in facility-bound applications.
Strategic Opportunities
- India Fleet Formalization:Commercial vehicle oversight is tightening under the country's national transport regulator, creating first-mover positioning for ELD-compliant device vendors in an underpenetrated logistics market.
- Video-Telematics Convergence:Integrated dashcam and positioning hardware is penetrating insurance-linked fleet safety programs, opening premium pricing tiers for dual-function units.
- EU Green Deal Alignment:Carbon reporting mandates for commercial transport are elevating route optimization software bundled with GPS hardware, creating regulatory-tied sales channels.
Industry Challenges
- Firmware Security Certification:Cybersecurity labeling requirements from the FCC and analogous bodies are extending product validation timelines and demanding specialized engineering talent scarce among mid-tier manufacturers.
- Legacy Fleet Integration:Older commercial vehicles lack CAN bus compatibility, forcing expensive retrofit wiring harnesses or OBD-II adapter dependencies that degrade installation economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GPS Tracking Device Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.68 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Trackers, Fleet Trackers, Vehicle Trackers, Asset Trackers Technology: RFID, Satellite, Cellular, Bluetooth End User: Logistics, Automotive, Healthcare, Security Application: Supply Chain Management, Emergency Services, Pet Tracking, Theft Recovery |
| Companies Covered | GPX Intelligence, Meitrack, Samsara, Linxup, Logistimatics, Geotab, LandAirSea, Tracki, Verizon Connect, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GPS Tracking Device Market Emerging Trajectories
Edge computing architectures are migrating position processing from cloud platforms to device-level chipsets, reducing latency for real-time geofence alerts while compressing cellular data transmission costs. This shift is redrawing hardware specification priorities and vendor competitive positioning.
AI-powered predictive maintenance algorithms embedded directly in GPS trackers are rendering obsolete reactive service scheduling based on mileage intervals alone. Heavy-duty fleet operators are piloting these units to forecast component failures from vibration and engine load signatures. The structural consequence is a compression of aftermarket service revenue pools traditionally captured by dealer networks.
The European Union's Cyber Resilience Act is mandating security-by-design requirements for connected devices including GPS trackers, compelling manufacturers to embed hardware root-of-trust modules and automated update mechanisms. Industrial fleet procurement specifications are beginning to require CE marking with cybersecurity attestation, filtering non-compliant vendors from enterprise tenders. German automotive logistics clusters are responding fastest, integrating these requirements into supplier qualification scorecards.
Mid-size logistics buyers are consolidating vendor relationships around platform ecosystems that unify GPS tracking with fuel card management and driver behavior scoring. Single-point procurement is displacing best-of-breed device sourcing that dominated the 2015-2020 period. This concentration is most visible in United States regional trucking fleets, where technology managers prioritize API interoperability over hardware feature differentiation.
GPS Tracking Device Market Segmentation
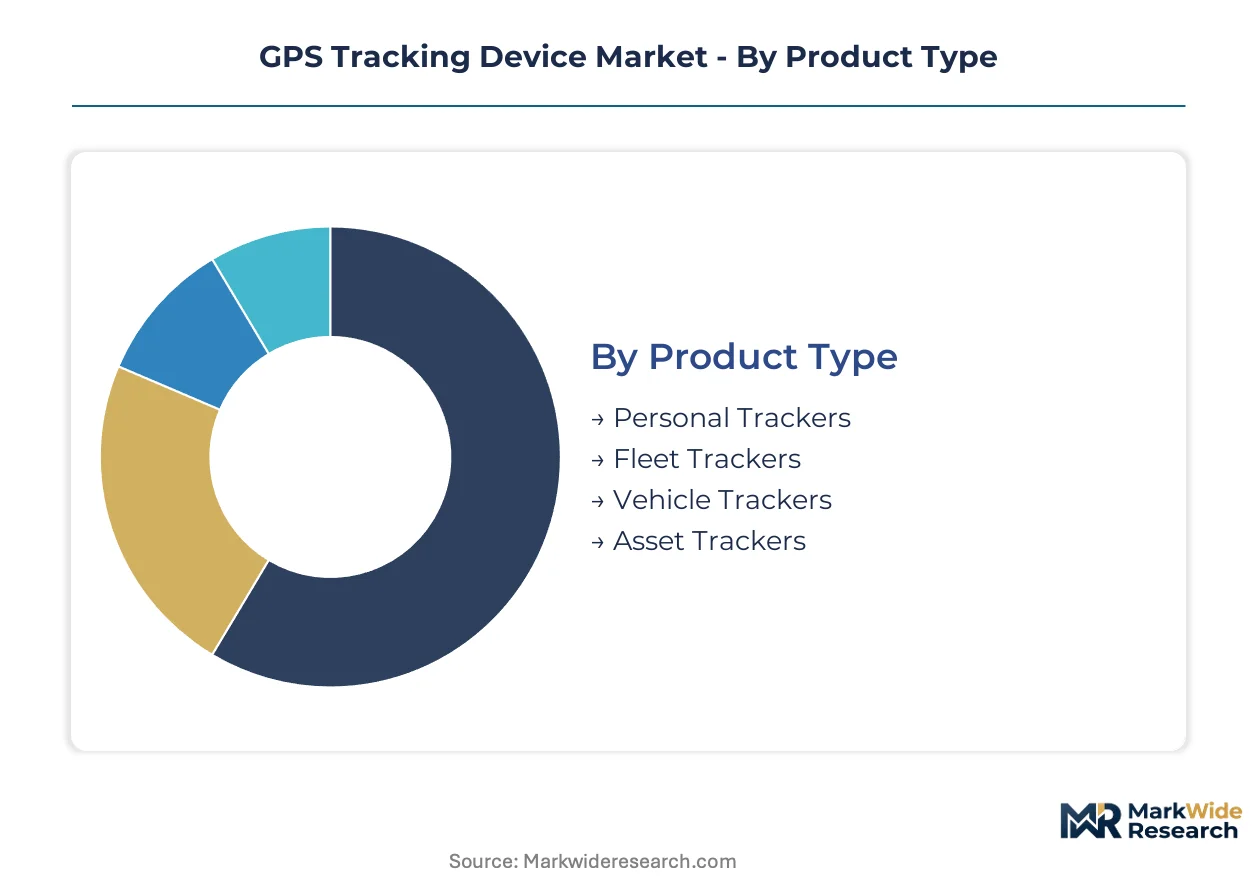
GPS tracking device segmentation reveals divergent replacement cycles across hardware categories. Fleet operators refresh cellular-enabled units every 3-5 years while asset trackers in construction environments endure 7-10 year lifespans. Understanding these temporal patterns shapes inventory planning and service revenue forecasting for device vendors.
Product Type:
Replacement velocity varies sharply across this category, with fleet-facing hardware cycling fastest and consumer-grade devices turning slowest.
- Fleet Trackers:Ruggedized commercial units integrate CAN bus interfaces and ELD compliance firmware for Hours of Service logging. Demand concentrates among United States interstate carriers responding to FMCSA enforcement, with Canada and Mexico cross-border fleets adopting compatible specifications. Cellular connectivity dominates installations.
- Asset Trackers:Weather-sealed devices with extended battery configurations monitor construction equipment, shipping containers, and agricultural machinery. German construction firms and Australian mining operators drive specification requirements for IP67 ratings and satellite fallback capability.
- Vehicle Trackers:Consumer and light-commercial units prioritize compact form factors and OBD-II plug-and-play installation. Insurance telematics programs in the United Kingdom and South Africa shape demand for driver behavior scoring integration.
- Personal Trackers:Wearable or pocket-sized devices target child safety, elderly monitoring, and outdoor recreation segments. Japanese and South Korean consumer electronics channels move the highest volumes.
Fleet trackers anchor the volume base while asset trackers gain share at the steepest rate.
Technology:
Cost tier structures separate premium satellite infrastructure from mass-market cellular deployments.
- Cellular:LTE-M and NB-IoT modules deliver lowest total cost of ownership for urban and suburban fleet applications. Mature carrier infrastructure in Germany, China, and the United States supports this dominance.
- Satellite:Iridium and Globalstar transceivers command 5-8x hardware premiums for ocean, desert, and polar zone coverage. Maritime logistics and remote mining operations in Canada, Brazil, and Australia absorb these costs.
- Bluetooth:Low-energy beacons capture indoor and short-range asset tracking previously addressed by GPS. Warehouse and healthcare facility deployments in France and the Netherlands favor this technology for battery longevity.
- RFID:Passive and active radio-frequency identification serves yard management and inventory gate-tracking without position calculation. Retail and manufacturing clusters in Italy and Spain maintain installed bases.
Cellular technology captures the broadest deployment base as satellite connectivity defends premium positioning.
End User:
Application maturity separates compliance-driven logistics procurement from emerging healthcare adoption.
- Logistics:Trucking fleets, last-mile delivery operators, and freight forwarders mandate real-time visibility for customer service and regulatory documentation. ELD mandates in the United States and expanding Hours of Service rules in the European Union structure procurement.
- Automotive:OEM telematics systems and aftermarket theft recovery installations drive consumer-facing demand. Insurance-linked pricing programs in the United Kingdom and South Africa accelerate adoption.
- Security:Cash-in-transit, high-value cargo, and executive protection services require covert installation and tamper alerts. Private security firms in Brazil and South Africa specify these capabilities.
- Healthcare:Patient wandering prevention, medical equipment tracking, and emergency response coordination represent nascent demand. Japanese aged-care facilities and German hospital networks pilot these applications.
Logistics commands the dominant revenue share as healthcare applications expand most quickly.
Application:
Customer type differentiation separates enterprise procurement from consumer purchase patterns.
- Supply Chain Management:End-to-end shipment visibility across multimodal transport requires API integration with TMS and WMS platforms. Retail and manufacturing procurement teams in the United States, Germany, and China specify these capabilities.
- Theft Recovery:Stolen vehicle and equipment recovery services rely on covert installation and law enforcement liaison networks. Insurance underwriters in the United Kingdom and Australia mandate these features for premium discounts.
- Emergency Services:First responder location tracking and disaster victim identification demand ruggedized hardware with satellite redundancy. Public safety agencies in Canada and France drive specifications.
- Pet Tracking:Consumer subscription services attach lightweight collars to companion animals for geofence alerts. Urban pet ownership trends in Japan and South Korea sustain this segment.
Supply chain management generates the largest enterprise revenue pool while theft recovery services achieve the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FMCSA's ELD mandate reshaped fleet hardware procurement across North American interstate carriers, while parallel Hours of Service enforcement in Canada and the European Union extended compliance-driven demand. Cellular infrastructure maturity and satellite positioning coverage gaps determine regional deployment economics.
United States
Interstate trucking fleets drive the largest installed base of ELD-compliant GPS hardware under FMCSA enforcement. The Department of Transportation's electronic logging requirements specify device certification standards that filter vendor participation. Dallas-Fort Worth logistics clusters concentrate fleet management technology procurement for cross-border Mexican freight corridors.
Germany
Automotive logistics operators and construction equipment lessors mandate ruggedized asset trackers with CE cybersecurity attestation under the Cyber Resilience Act. The EU Green Deal's carbon reporting requirements for commercial transport elevate route optimization software bundled with positioning hardware. Stuttgart industrial corridors integrate these specifications into supplier qualification protocols for outbound vehicle distribution.
China
Domestic logistics formalization and commercial vehicle oversight tightening under MIIT directives expand fleet tracker deployments. BeiDou constellation integration into multi-GNSS chipsets reduces dependency on foreign satellite signals for precision positioning. Yangtze River Delta manufacturing clusters produce cost-optimized cellular modules for domestic and export markets.
India
National transport regulator mandates for commercial vehicle tracking create first-mover positioning for ELD-compliant device vendors in an underpenetrated logistics market. The country's PLI scheme for electronics manufacturing attracts module assembly investment. Maharashtra and Gujarat logistics corridors pilot fleet formalization programs linking toll collection to installed tracking hardware.
Brazil
Cash-in-transit security services and high-value cargo protection sustain demand for covert installation and tamper-alert capabilities. ANVISA-equivalent transport oversight bodies expand commercial fleet registration requirements. São Paulo industrial districts concentrate security firm procurement for armored vehicle tracking systems.
GPS Tracking Device Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered market strata. Cellular network operators and open-platform ecosystems anchor the consolidated upper tier, while regional hardware fabricators populate fragmented mid-market segments. Two strategic archetypes dominate: connectivity-integrated platform providers and standalone device manufacturers with vertical specialization. M&A activity concentrates around video-telematics convergence targets, and strategic partnerships link hardware vendors with insurance underwriters for usage-based pricing programs.
Among North American platform providers, Samsara and Geotab exemplify ecosystem-centric positioning that unifies GPS tracking with complementary fleet management functions. Verizon Connect occupies a position anchored by cellular network density and bundled connectivity contracts. These three entities represent the connectivity-integrated archetype that mid-size logistics buyers increasingly favor over best-of-breed device sourcing.
| Leading Market Players |
|---|
| GPX Intelligence |
| Meitrack |
| Samsara |
| Linxup |
| Logistimatics |
| Geotab |
| LandAirSea |
| Tracki |
| Verizon Connect |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters anchor global cellular module production, concentrating cost leverage for GPS device vendors while downstream pricing power fragments across subscription-model fleet operators and transactional hardware buyers.
Pricing Analysis
Certification level creates the primary spread between premium CE-cybersecurity-attested units and baseline FCC-certified hardware. Three-tier pricing structure across premium, standard, and economy levels reflects firmware encryption depth and CAN bus integration complexity. Cost compression in economy tiers is intensifying because Bluetooth Low Energy tags capture indoor tracking volumes previously served by cellular GPS units. Mid-size logistics buyers exhibit highest price sensitivity, while emergency services and security firms absorb premium positioning for satellite redundancy and tamper-proofing.
Supply Chain Analysis
Extended payment terms from Yangtze Delta module fabricators and supply-chain finance facilities from Shenzhen distributors ease working capital constraints for mid-tier device assemblers. Production concentrates in China, Taiwan, and South Korea for GNSS chipsets and cellular modems. Semiconductor lithography and rare-earth magnet sourcing for ruggedized enclosures rest on concentrated Asian supplier bases. Single-source vulnerability in 14nm chip fabrication exposes manufacturers to allocation constraints. Distribution runs through cellular carrier bundling contracts and open-platform API ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GPS tracking hardware is commoditizing while platform economics capture retained value, as fleet buyers consolidate around unified ecosystems bundling positioning, fuel management, and driver scoring through API interoperability rather than best-of-breed device procurement.
For Market Incumbents: Pre-empt platform disintermediation by embedding edge-computing chipsets that process geofence alerts locally, reducing cloud dependency and cellular data costs that erode subscription margins. Deepen backward integration into BeiDou-GLONASS multi-constellation chip design to escape Qualcomm-Mediatek modem pricing power. Secure FMCSA ELD certification renewals ahead of cybersecurity labeling requirements that will filter non-compliant vendors from federal fleet tenders. For New Entrants and Emerging Players: Pursue India's underpenetrated logistics corridors where national transport regulator mandates create first-mover positioning for ELD-compliant hardware without entrenched vendor relationships. Target construction equipment monitoring in Australian mining and German infrastructure projects, where asset tracker replacement cycles extend 7-10 years and service revenue pools remain uncontested. Lead with hardware-as-a-service financing that eliminates upfront procurement barriers for mid-size fleet operators. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because fleet management platforms convert device sales into sticky subscription streams with 90%+ annual retention. Acquisition targets should display open-platform API architectures and existing cellular carrier distribution partnerships rather than standalone hardware feature differentiation. The signal to watch is FCC cybersecurity labeling enforcement timelines, which will accelerate vendor consolidation by raising compliance costs above mid-tier balance sheet capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Video-Telematics Convergence | Integrated dashcam-positioning hardware penetrates insurance-linked fleet safety programs with premium dual-function pricing. |
| Platform Ecosystem Integration | API interoperability with fuel card and TMS systems displaces best-of-breed sourcing among mid-size logistics buyers. |
| Edge Computing Migration | On-device position processing reduces latency for geofence alerts while compressing cellular data transmission costs. |
| CE Cybersecurity Attestation | EU Cyber Resilience Act compliance filters non-certified vendors from German automotive logistics procurement scorecards. |
| India Market Entry | National transport regulator mandates for commercial vehicle tracking create first-mover positioning in formalizing logistics corridors. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across fleet management technology procurement, cellular module manufacturing, and logistics platform engineering. Primary interviews with fleet operations directors, OEM telematics platform architects, and semiconductor distribution channel managers were validated against secondary sources including FCC equipment authorization databases, EU Cyber Resilience Act implementation guidance, and carrier IoT connectivity disclosure filings. Bottom-up device shipment estimates triangulated against top-down fleet penetration models across the analysis window.
Calibration against historical ELD mandate deployment curves and construction equipment replacement cycles shaped the projection framework. Segmentation modeling captured product type, connectivity technology, end-user vertical, and application purpose across the modeling period. CAGRs were derived from logistic diffusion curves fitted to regulatory compliance deadlines and fleet formalization timelines. BeiDou constellation integration rates and cellular LPWAN network buildout schedules served as industry-specific forecast inputs.
Sensitivities concentrate around semiconductor supply allocation constraints, GDPR enforcement variance across EU member states, and Bluetooth Low Energy substitution velocity in facility-bound asset tracking. Forecasts reflect documented assumptions regarding regulatory compliance timelines and carrier infrastructure investment. Macroeconomic contraction in commercial transport, accelerated cybersecurity certification requirements, or satellite positioning signal degradation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Control Knobs for Panel Potentiometer Market
Sensors and Controls
Insulation Monitoring Devices (IMD) Market
Sensors and Controls
Meteorological Equipment Market
Sensors and Controls
Global Intelligent Flow Meter Market
Sensors and Controls
Acoustic Breathing Sensor Market
Sensors and Controls
United States Scintillator Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
PID Controller Market
Sensors and Controls
Middle East and Africa MEMS and Sensors Market
Sensors and Controls
Thermal Anemometer Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
MEMS Energy Harvesting Devices Market
Sensors and Controls
Doppler Wind Lidar System Market
Sensors and Controls
Mexico Digital Thermometer Market