
 Milk Protein Concentrate Market | 2026-2036
Milk Protein Concentrate Market Size, Share, and Industry Trends Forecast 2026-2036
Milk Protein Concentrate Market Intelligence
Sports nutrition is hardening as the dominant demand vertical for milk protein concentrates, displacing traditional dairy commodity offtake. Fonterra leverages its New Zealand sourcing base to control premium concentrate supply chains. Glanbia anchors North American sports nutrition channels through specialized whey and casein blends. Arla Foods Ingredients differentiates via fractionation technology leadership in high-purity milk protein isolates.
Milk protein concentrate denotes a dried dairy ingredient containing elevated protein fractions, typically manufactured through ultrafiltration and diafiltration of skim milk to achieve protein concentrations ranging from 42% to 85% on a dry basis, with retained micellar casein and whey protein ratios approximating native milk composition. The ingredient functions primarily as a nutritional fortifier, texturizer, and emulsifier across formulated foods. Casein-dominant concentrates command margin pools in infant formula applications where micellar integrity governs digestibility standards. Whey protein fractions represent the fastest-growing product type as sports nutrition brands reformulate for leucine density and rapid absorption kinetics. Food manufacturers sustain the largest volume channel, though nutraceutical companies are repositioning procurement toward direct ingredient relationships.
FDA protein labeling requirements and EFSA health claim frameworks jointly shape product standardization and market access thresholds for concentrate suppliers. USDA dairy grading protocols and ISO 17025 laboratory accreditation further constrain which processors qualify for institutional and export contracts. Stakeholders must monitor evolving protein quality scoring methodologies and regional clean-label enforcement intensity to align fractionation investments with forthcoming specification regimes.
Market Dynamics
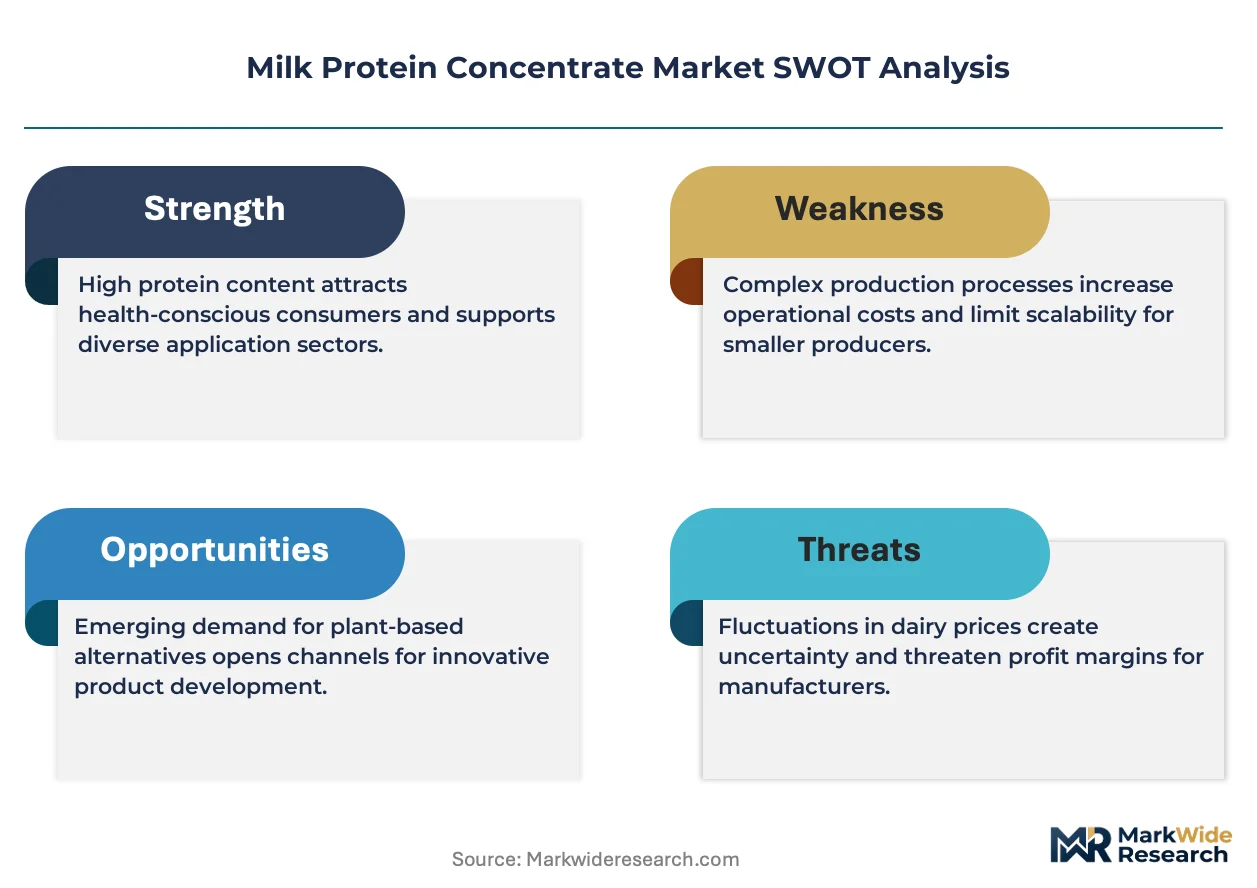
Sports nutrition brands are consolidating procurement around higher-protein concentrates, compressing traditional dairy commodity channels while forcing fractionation investments toward leucine-optimized micellar casein and whey isolates.
Growth Catalysts
- Clean-label mandates:FDA protein labeling requirements and EFSA health claim frameworks are tightening purity thresholds, forcing suppliers to upgrade ultrafiltration capabilities and opening margin pools for certified-clean processors.
- Sports nutrition procurement:Functional food manufacturers in the United States and Germany are expanding direct ingredient relationships with concentrate suppliers, bypassing traditional dairy traders to secure supply chain transparency.
- Fractionation technology:Advanced diafiltration systems are enabling protein concentration ranges from 42% to 85% on a dry basis, allowing customized micellar casein-to-whey ratios for infant formula and clinical nutrition applications.
Market Restraints
- Input cost volatility:Skim milk powder prices fluctuate with New Zealand and EU dairy auction cycles, compressing margins for concentrate processors lacking backward integration into fluid milk supply.
- Supply concentration risk:Premium micellar casein production clusters in New Zealand and Denmark, creating geographic single-source vulnerabilities for infant formula manufacturers requiring digestibility-certified ingredients.
- Technical limitation:Heat-induced denaturation during spray-drying degrades whey protein bioactivity, constraining leucine density in finished sports nutrition products and requiring expensive low-temperature processing alternatives.
Strategic Opportunities
- Underpenetrated clinical nutrition:Hospital and aged-care feeding protocols in Japan and South Korea are adopting protein-fortified textures, creating demand for emulsifier-grade concentrates with specific viscosity profiles.
- Regulatory tailwind:China's SAMR is expanding permitted protein content claims for functional foods, enabling concentrate suppliers to reposition ingredients from commodity inputs to health-positioned fortifiers.
- Precision fermentation convergence:Hybrid formulations combining traditional dairy proteins with fermentation-derived fractions are opening novel application spaces in personalized nutrition and allergen-reduced infant formulas.
Industry Challenges
- ISO 17025 accreditation timelines:Laboratory certification delays for protein quality scoring methodologies are extending contract qualification periods, freezing supplier switching decisions for 12-18 months.
- Fractionation capex intensity:Membrane replacement cycles and diafiltration water recovery systems require sustained capital deployment, disadvantaging smaller processors against integrated dairy cooperatives with captive infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milk Protein Concentrate Market |
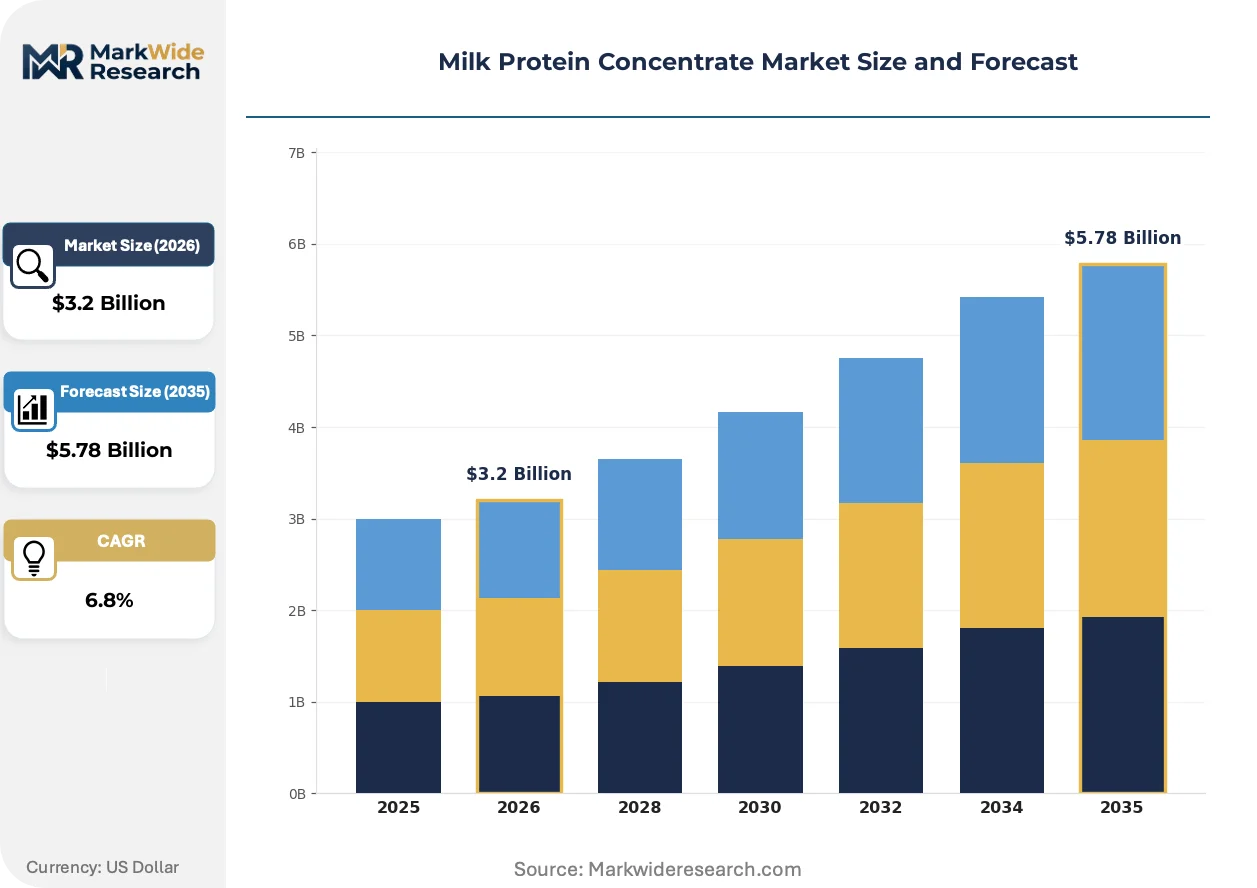
| Market Size in 2026 | $3.2 Billion |
| Market Size in 2035 | $5.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein, Milk Protein Isolate, Milk Protein Concentrate Application: Food & Beverage, Sports Nutrition, Dairy Products, Infant Formula End User: Sports Enthusiasts, Health-conscious Consumers, Food Manufacturers, Nutraceutical Companies Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Idaho Milk Products, Actus Nutrition, Fonterra, FrieslandCampina Ingredients, Tirlán, Glanbia, Wisconsin Whey Protein, Pirancanjuba Group, Arla Foods Ingredients, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milk Protein Concentrate Market Strategic Shifts & Innovations
Membrane filtration advances and shifting procurement relationships are restructuring how concentrate suppliers capture value, with technology ownership and regulatory compliance emerging as the primary competitive differentiators.
Microfiltration-coupled ultrafiltration is unifying protein separation and bacterial removal into single-pass operations, reducing thermal exposure and preserving native protein structures. Sports nutrition brands in Germany and the United States are adopting these cold-processed concentrates at premium price positions. This unification is compressing the supplier base toward processors with proprietary membrane configurations and in-house diafiltration engineering capabilities.
EFSA's evolving health claim substantiation requirements are forcing concentrate suppliers to invest in clinical trial infrastructure for protein quality scoring validation. The industrial consequence is a bifurcation between commodity-grade suppliers and research-capable processors capable of supporting brand-specific claim applications. Infant formula manufacturers in Europe are responding by consolidating procurement around EFSA-prequalified ingredient portfolios, locking out uncertified competitors from premium contract channels.
Direct sourcing contracts are displacing spot-market dairy commodity purchases among North American functional food manufacturers, with buyers demanding batch-level protein composition data and supply chain traceability documentation. This pattern is most visible in United States sports nutrition channels, where brands are bypassing distributors to negotiate multi-year concentrate supply agreements with defined micellar casein specifications and locked-in fractionation capacity.
Milk Protein Concentrate Market Segmentation
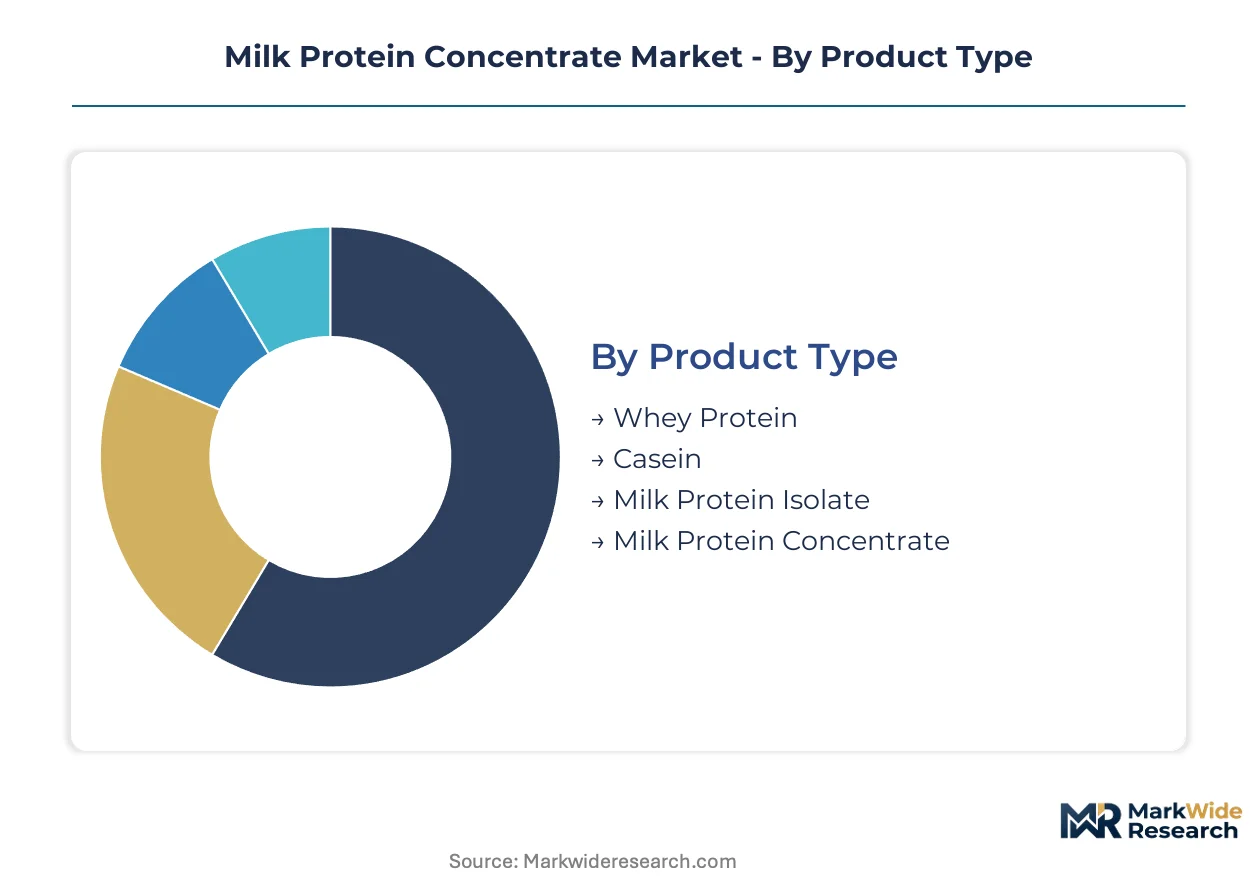
Milk protein concentrates fragment across protein chemistry, end-use functionality, and procurement relationships. Each segmentation axis reveals distinct margin structures and technical qualification barriers that concentrate value capture among specialized processors.
Product Type:
Standardization dominates at commodity grades while customization intensifies toward isolate and fractionated variants with defined micellar integrity specifications.
- Whey Protein:Rapid-absorption fractions with elevated leucine density command premium positioning in sports nutrition formulations. Demand concentrates in United States and Germany where brands reformulate for post-workout recovery kinetics and bypass traditional dairy traders for direct supplier contracts.
- Casein:Micellar structures retained through low-temperature ultrafiltration govern digestibility certification for infant formula applications. Production clusters in New Zealand and Denmark, creating geographic supply vulnerabilities for manufacturers requiring batch-traceable micellar integrity.
- Milk Protein Isolate:Higher purity grades achieve protein concentrations above 85% through advanced diafiltration, serving clinical nutrition and premium fortification.
- Milk Protein Concentrate:Intermediate protein levels from 42% to 85% serve cost-sensitive food manufacturing as emulsifiers and texturizers in processed dairy applications.
Most installed capacity flows through Milk Protein Concentrate. Expansion is steepest in Whey Protein.
Application:
Volume scale concentrates in mature food manufacturing while margin pools shift toward health-positioned categories with regulatory claim substantiation requirements.
- Sports Nutrition:Leucine-optimized concentrates with rapid absorption profiles anchor protein powder and ready-to-drink formulations. Procurement is hardening around direct supplier relationships in United States channels, with brands demanding locked-in fractionation capacity and batch-level composition data.
- Infant Formula:Micellar casein concentrates require digestibility certification under FDA and EFSA frameworks, constraining qualified suppliers to processors with clinical trial infrastructure and ISO 17025 laboratory accreditation.
- Food & Beverage:Emulsifier-grade concentrates with specific viscosity profiles serve texture modification in processed foods, representing the largest volume channel but compressing margins through commodity procurement patterns.
- Dairy Products:Standardized concentrates fortify yogurt, cheese, and ice cream applications with protein enrichment and water-binding functionality.
Food & Beverage absorbs the greatest volume. Sports Nutrition climbs the fastest.
End User:
Procurement sophistication separates institutional buyers with technical qualification requirements from consumer-facing channels with brand-positioning priorities.
- Food Manufacturers:Sustained volume demand for emulsifier and texturizer applications in processed foods, with procurement patterns shifting from spot-market purchases toward multi-year supply agreements with defined specifications.
- Nutraceutical Companies:Direct ingredient relationships with concentrate suppliers are replacing distributor intermediation, driven by clean-label documentation requirements and supply chain traceability mandates.
- Sports Enthusiasts:End-consumer demand for leucine density and rapid absorption kinetics is transmitting upstream to reformulate concentrate procurement specifications.
- Health-conscious Consumers:Clean-label preferences are tightening purity thresholds and favoring certified-clean processors with EFSA-prequalified ingredient portfolios.
Food Manufacturers command the deepest volume. Nutraceutical Companies are gaining share fastest.
Distribution Channel:
Channel selection reflects buyer scale and technical qualification intensity, with direct relationships displacing intermediation where specification complexity increases.
- Direct Sales:Multi-year supply agreements with locked-in fractionation capacity dominate sports nutrition and infant formula procurement in United States and Germany, bypassing traditional dairy commodity channels entirely.
- Online Retail:E-commerce penetration concentrates in sports nutrition and health-conscious consumer segments, enabling brand-direct relationships with concentrate suppliers for specialty formulations.
- Supermarkets:Mass-market distribution serves standardized concentrate products in food manufacturing and dairy applications with commodity-grade specifications.
- Health Stores:Specialty retail channels access premium-positioned concentrates with clean-label certifications and batch-traceable documentation.
Supermarkets move the largest aggregate volume. Direct Sales expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping concentrate production geography as processors migrate toward jurisdictions with lower cost-of-compliance gaps for clean-label certification. FDA and EFSA purity thresholds create divergent compliance burdens that favor established dairy cooperatives with captive laboratory infrastructure.
United States
Sports nutrition brands in California and Texas are locking multi-year direct supply agreements for leucine-optimized concentrates. FDA protein labeling requirements under 21 CFR 101.36 tighten batch-level documentation standards. Idaho and Wisconsin processing clusters anchor North American micellar casein output for infant formula applications.
Germany
Functional food manufacturers in Bavaria and North Rhine-Westphalia bypass traditional dairy traders for transparent procurement relationships. EFSA health claim substantiation frameworks under Regulation 1924/2006 force clinical trial investments for protein quality scoring. Hamburg and Frankfurt logistics hubs consolidate EU distribution for certified-clean concentrate grades.
China
SAMR's expansion of permitted protein content claims for functional foods is repositioning concentrates from commodity inputs to health-positioned fortifiers. Yangtze River Delta food manufacturers in Shanghai and Jiangsu province demand batch-traceable documentation for premium infant formula sourcing. Domestic processors in Shandong and Heilongjiang are upgrading ultrafiltration capacity to meet import-substitution targets.
New Zealand
Fonterra's Canterbury and Waikato processing clusters control premium micellar casein supply chains for global infant formula manufacturers. MPI dairy export certification requirements constrain qualified suppliers to ISO 17025-accredited laboratories. South Island fractionation facilities leverage grass-fed sourcing narratives for clean-label positioning in United States and German markets.
Denmark
Arla Foods Ingredients' Jutland processing sites specialize in high-purity milk protein isolates through advanced diafiltration engineering. Danish Veterinary and Food Administration enforcement of EU purity thresholds creates barrier-to-entry for uncertified competitors. Aarhus and Esbjerg harbor infrastructure supports cold-chain concentrate exports to Asian clinical nutrition channels.
Milk Protein Concentrate Market Key Industry Players
Capacity expansion dominates the current landscape as integrated dairy cooperatives deploy fractionation infrastructure to capture sports nutrition margin pools. The supplier base concentrates around processors with proprietary membrane configurations and captive fluid milk supply. Three archetypes define competitive positioning: New Zealand-based grass-fed specialists, European fractionation technology leaders, and North American direct-channel integrators. M&A activity and strategic partnerships are consolidating procurement relationships away from spot-market intermediation.
Within the integrated cooperative tier, Fonterra and Arla Foods Ingredients exemplify divergent geographic strategies for premium concentrate positioning. Glanbia anchors North American sports nutrition channel access through specialized whey and casein blend capabilities. FrieslandCampina Ingredients and Tirlán occupy positions bridging European food manufacturing volume demand with clean-label certification infrastructure. Idaho Milk Products and Wisconsin Whey Protein represent United States-based processors leveraging regional dairy supply density for backward integration into fluid milk procurement.
| Leading Market Players |
|---|
| Idaho Milk Products |
| Actus Nutrition |
| Fonterra |
| FrieslandCampina Ingredients |
| Tirlán |
| Glanbia |
| Wisconsin Whey Protein |
| Pirancanjuba Group |
| Arla Foods Ingredients |
| Others |
Cost & Logistics Intelligence
EFSA clean-label certification requirements and FDA protein labeling mandates under 21 CFR 101.36 jointly gate access to premium-tier pricing pools, forcing concentrate processors to deploy ISO 17025-accredited laboratory infrastructure as a prerequisite for qualified supply relationships with infant formula and sports nutrition manufacturers.
Pricing Analysis
Distributor margin compression in traditional dairy commodity channels is accelerating direct-to-manufacturer contract structures, with sports nutrition brands in the United States and Germany negotiating multi-year offtake agreements at 15-25% discounts to spot-market equivalents. Three-tier pricing structure across premium, standard, and economy levels stratifies by protein concentration grade and micellar integrity certification, with EFSA-prequalified isolates commanding substantial premia over commodity-grade concentrates. Price differentiation hinges on batch-level composition documentation and locked-in fractionation capacity. Pricing pressure stems from skim milk powder auction volatility in New Zealand and EU dairy markets. Food manufacturers exhibit highest price sensitivity due to commodity procurement patterns, while infant formula producers accept premium positioning for digestibility-certified micellar casein.
Supply Chain Analysis
ISO 17025 laboratory accreditation and EFSA health claim substantiation requirements create qualification backlogs that freeze supplier switching decisions for 12-18 months, concentrating qualified supply among integrated dairy cooperatives with captive certification infrastructure. Geographic supply concentrates in New Zealand, Denmark, and the United States, with Fonterra's Canterbury clusters and Arla's Jutland facilities anchoring premium micellar casein output. Raw material dependencies center on fluid milk supply density, membrane filtration equipment, and diafiltration water recovery systems. Single-source vulnerability runs through New Zealand's dominance in grass-fed, digestibility-certified micellar casein for global infant formula manufacturers. Distribution runs through direct sales channels for specification-intensive applications, with Hamburg and Frankfurt logistics hubs consolidating EU distribution for certified-clean grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EFSA compliance costs in Europe run substantially higher than FDA-aligned certification pathways in the United States, creating margin expansion opportunities for processors with multi-jurisdictional laboratory infrastructure.
For Market Incumbents: Cement backward integration into fluid milk supply in Idaho and Wisconsin to offset skim milk powder auction volatility threatening margin stability. Lock multi-year direct supply agreements with United States sports nutrition brands to preempt emerging fractionation technology entrants from capturing locked-in capacity. Prioritize EFSA prequalification investments to defend premium contract channels against uncertified competitors facing extended ISO 17025 accreditation timelines.
For New Entrants and Emerging Players: The price-point gap between EFSA-certified premium isolates and commodity-grade concentrates creates white-space entry at mid-tier certification levels for regional food manufacturers in China and South Korea. Target clinical nutrition applications in Japanese hospital feeding protocols where emulsifier-grade specifications remain underpenetrated by established players. Pursue precision fermentation hybrid formulations as a differentiated go-to-market angle for allergen-reduced infant formula positioning.
For Investors and Strategic Acquirers: Roll-up economics work for regional processors with captive fluid milk supply and pending ISO 17025 accreditation because EFSA and FDA regulatory convergence is extending contract qualification periods and freezing incumbent switching advantages. Long-term viability centers on processors with proprietary membrane configurations and in-house diafiltration engineering. Watch for SAMR's expansion of permitted protein content claims in China as an inflection signal for health-positioned fortifier repositioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluid Milk Supply | Idaho and Wisconsin dairy cooperatives secure margin protection against New Zealand auction volatility. |
| ISO 17025 Laboratory Accreditation Investment | EFSA-prequalified processors capture 12-18 month supplier switching freezes in infant formula channels. |
| Direct Sales Channel Expansion | United States sports nutrition brands bypass distributors for locked-in fractionation capacity agreements. |
| Precision Fermentation Hybrid Development | SAMR's expanded claim permissions enable novel allergen-reduced infant formula positioning in China. |
| Multi-Jurisdictional Certification Infrastructure | Processors with FDA and EFSA alignment arbitrage compliance cost differentials between United States and European markets. |
Research Approach
Direct dialogue with concentrate procurement managers at sports nutrition brands, infant formula manufacturers, and clinical nutrition distributors anchored qualitative insights, cross-referenced with FDA 21 CFR 101.36 filing databases, EFSA health claim substantiation records, USDA dairy grading protocols, and New Zealand MPI export certification registries. Bottom-up volume estimates from fractionation capacity utilization rates triangulated against top-down demand projections from functional food formulation trends.
Output projections across the analysis window derived from segmented modeling of protein concentration tiers, application-specific purity requirements, and regional regulatory framework clusters. CAGRs were computed from installed capacity expansion announcements, membrane technology deployment timelines, and direct procurement relationship formation rates. Industry-specific inputs included diafiltration water recovery system adoption curves and EFSA clinical trial investment disclosures.
Caveats apply where SAMR regulatory acceleration, EFSA purity threshold revisions, or New Zealand dairy auction cycle disruptions could materially shift the outlook. Forecasts reflect assumptions about membrane replacement cycle economics and ISO 17025 accreditation pipeline clearance rates. A model refresh is warranted upon material change in China's functional food claim permission trajectory or EFSA protein quality scoring methodology adoption.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Milk Protein Crisps Market
Dairy Products
Global Goat Cheese Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Dairy Concentrates Market
Dairy Products
Global Cream Cheese Market
Dairy Products
Natural Cheese Market
Dairy Products
Europe Dairy Market
Dairy Products
Global Yogurt Market
Dairy Products
Greek Yogurt Market
Dairy Products
North America Casein and Caseinate Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
United States Camel Dairy Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Non-Fat Milk Market