
 Global Goat Cheese Market | 2026-2036
Global Goat Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Global Goat Cheese Market Foresight
Artisanal AOP and farmstead designation tiers is bifurcating the competitive landscape into premium credential holders and commodity processors. Saputo Inc. leverages multi-plant dairy infrastructure across North America to secure volume consistency. Laura Chenel's Chèvre, Inc. anchors California's Sonoma County terroir identity in domestic distribution. Lactalis Group dominates European retail shelf space through consolidated cold-chain logistics.
Goat cheese denotes fresh or ripened curd produced from caprine milk, typically containing 45-55% moisture in soft varieties and undergoing lactic acid or mixed coagulation at 20-32°C for texture development. Its commercial purpose centers on delivering lower-lactose, higher-medium-chain-fatty-acid alternatives to bovine cheese for health-conscious and gastronomic buyers. Fresh product type leads volume throughput in retail and foodservice channels due to shorter production cycles and broader consumer familiarity. Foodservice application captures expanding margin pools as chefs incorporate chèvre into composed dishes and tasting menus. Online sales channels represent the fastest-growing route, bypassing traditional distributor markups through direct-to-consumer fulfillment.
EFSA enforces microbiological criteria for raw-milk cheeses under EU regulation 2073/2005, while FDA administers pasteurization requirements and interstate commerce standards in the United States. ISO 22000 and HACCP frameworks govern hazard management for exporters seeking multi-jurisdiction market access. Stakeholders must monitor evolving allergen labeling mandates and carbon-footprint disclosure rules that will reshape supplier qualification criteria and packaging material selections.
Market Dynamics
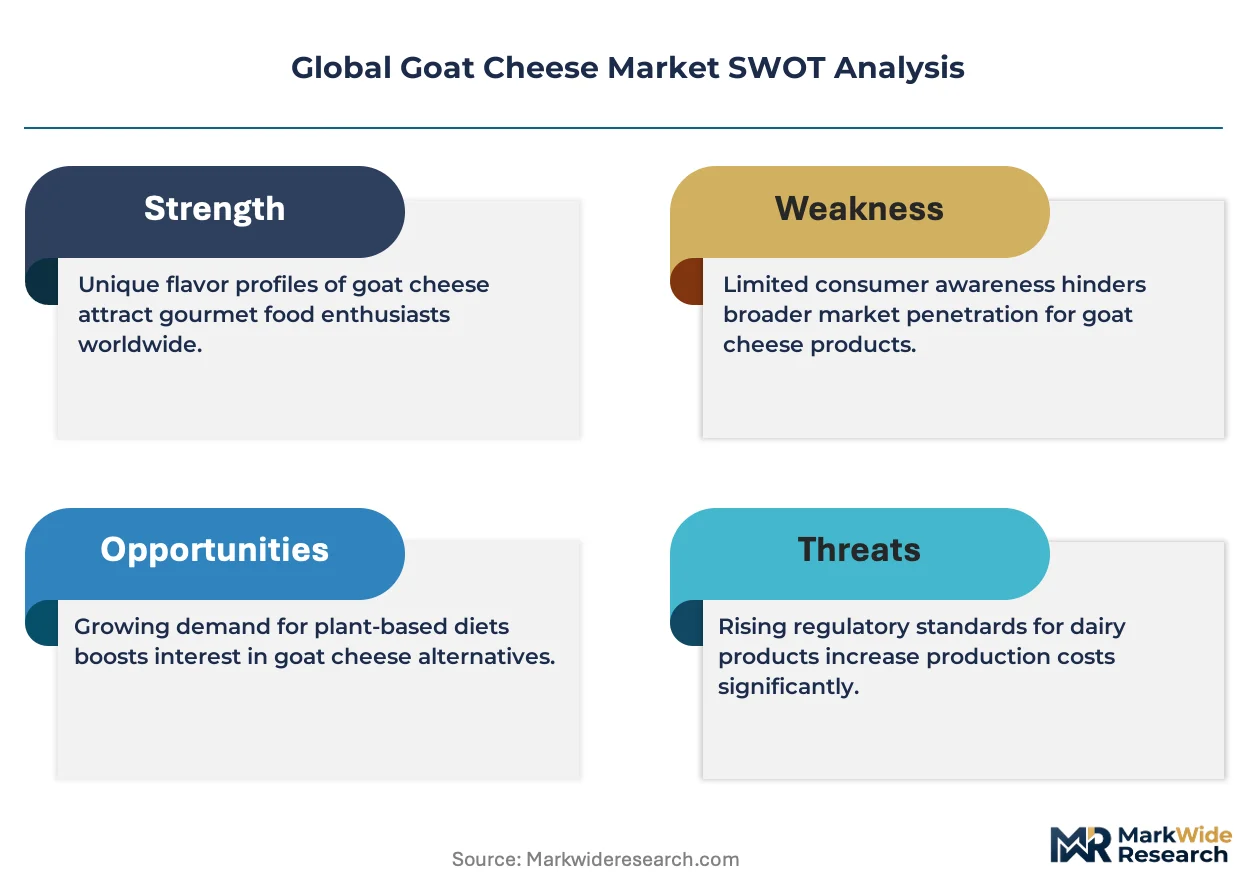
The goat cheese market is bifurcating under pressure from EU hygiene mandates tightening raw-milk protocols, forcing processors to choose between costly facility upgrades or exit from protected designation categories.
Growth Catalysts
- EFSA Microbiological Standards:Stricter enforcement under EU regulation 2073/2005 is accelerating consolidation among compliant AOP credential holders, squeezing informal producers from retail shelf space.
- Foodservice Menu Integration:Fine-dining chefs in California and Provence are composing tasting-menu dishes around aged chèvre, expanding premium price realization beyond commodity retail tiers.
- Caprine Dairy Clustering:Production gravity concentrates in Spain's Castilla-La Mancha, Greece's Thessaly, and Portugal's Alentejo, generating pooled logistics efficiencies and shared cold-chain infrastructure.
Market Restraints
- Raw-Milk Input Volatility:Seasonal caprine lactation cycles and fodder cost spikes constrain year-round volume consistency for soft-ripened varieties.
- Supply-Side Geographic Concentration:Mediterranean basin drought frequency threatens pasture availability across southern France, Spain, and Greece simultaneously.
- Plant-Based Substitution:Fermented nut and oat curd alternatives from precision fermentation startups capture lactose-intolerant and vegan-adjacent consumer segments.
Strategic Opportunities
- Direct-to-Consumer E-Commerce:Artisanal producers bypass traditional distributor markups through Shopify-enabled fulfillment, capturing margin pools previously allocated to wholesale intermediaries.
- Carbon-Footprint Labeling Mandates:Early compliance with emerging EU packaging disclosure rules positions premium brands for preferred retailer placement ahead of enforcement deadlines.
- Middle Eastern Market Entry:Gourmet retail expansion in Dubai and Riyadh creates demand for halal-certified goat cheese variants with extended ambient stability for hot-climate distribution.
Industry Challenges
- AOP Certification Timeline Compression:Farmstead applicants face 18-24 month qualification windows against tightening EFSA documentation requirements, delaying revenue recognition.
- Multi-Jurisdiction HACCP Integration:Exporters must reconcile ISO 22000 frameworks with FDA pasteurization mandates and national allergen labeling variations, multiplying compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Goat Cheese Market |
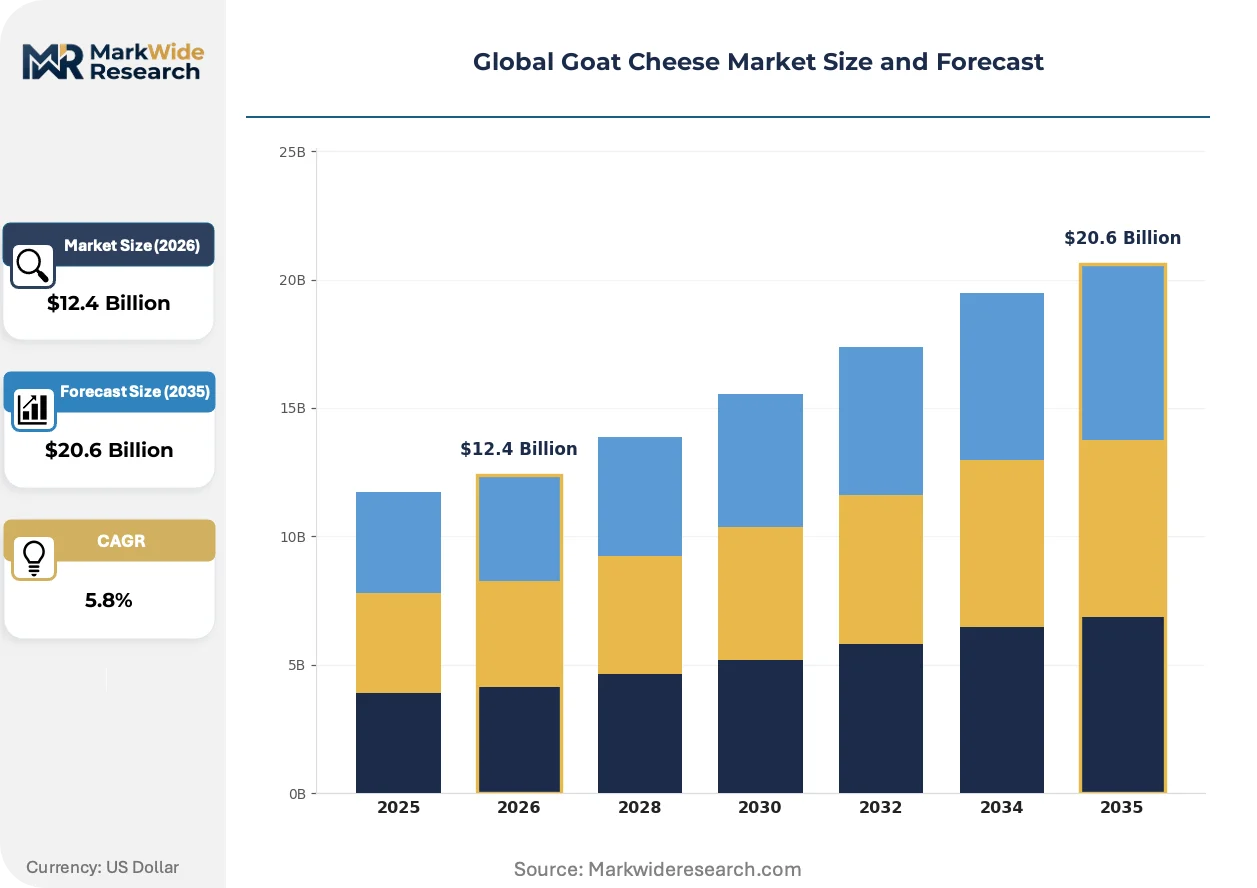
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $20.6 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh, Aged, Flavored, Soft, Semi-Hard, Hard Application: Retail, Foodservice, Specialty Stores, Online Sales, Gourmet Shops Packaging Type: Vacuum Pack, Plastic Container, Aluminum Foil, Wax Coated, Tubs End User: Cheese Distributors, Gourmet Retailers, Food Manufacturers, Catering Companies |
| Companies Covered | Saputo Inc., Laura Chenel's Chèvre, Inc., Lactalis Group, Savencia Fromage & Dairy, Vermont Creamery, LLC., Cypress Grove Chevre, Inc., St Helen's Farm Ltd., Redwood Hill Farm & Creamery, Inc., Haystack Mountain Creamery, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Goat Cheese Market Shifts & Advancements
Automation in curd handling and ripening-room climate control is redrawing capital requirements for artisanal scale, while regulatory transparency mandates and channel disintermediation reshape how value flows to producers.
Precision fermentation for dairy proteins is fragmenting traditional livestock-based supply assumptions. Synthetic biology startups in California and the Netherlands are producing casein and whey without caprine herds, attracting venture funding from food-tech investors. Early adopters in plant-based manufacturing are piloting hybrid formulations, though flavor-matching aged chèvre complexity remains unresolved.
EFSA's evolving stance on raw-milk cheese safety is tightening cold-chain documentation requirements across EU member states. The regulation forces exporters to implement blockchain-traceable temperature logging from farm to retail. Small-scale French and Italian producers are forming cooperative compliance pools to share third-party audit costs.
Chefs and specialty retailers are compressing procurement cycles through direct relationships with named farmstead producers. Traditional two-step distributor relationships in New York and Paris are yielding to quarterly buying trips and Instagram-driven discovery. This pattern concentrates volume with terroir-storytelling brands while commoditizing unbranded bulk chèvre.
Global Goat Cheese Market Segmentation
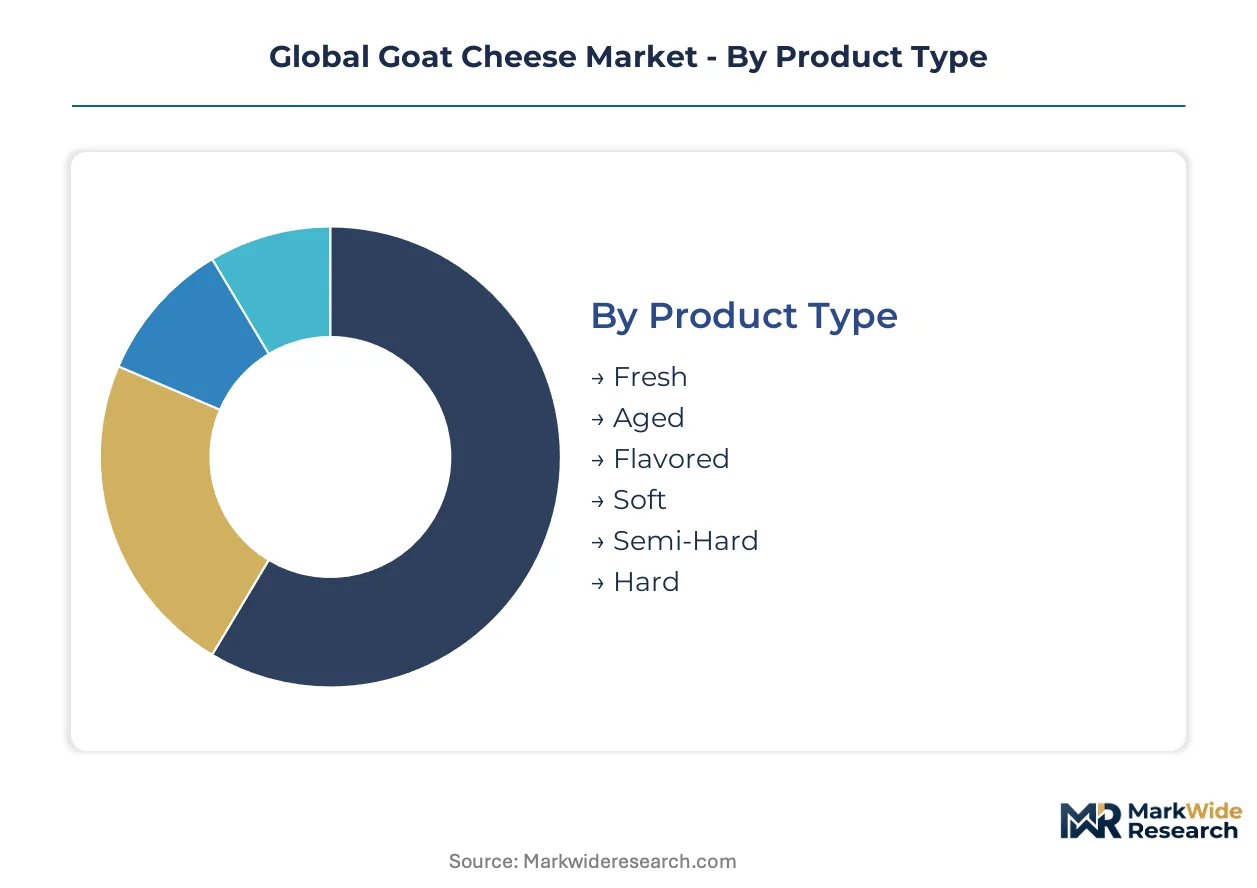
Goat cheese flows through highly differentiated channel economics where moisture content, aging protocols, and packaging shelf-life dictate margin capture. Segmentation reveals how artisanal credential holders and commodity processors occupy parallel but non-competing revenue pools.
Product Type:
Channel mix varies sharply by moisture and aging state, with fresh varieties dominating high-velocity retail while aged formats command premium placement in foodservice and specialty channels.
- Fresh:Soft curd with 45-55% moisture content, produced through lactic acid coagulation at 20-22°C. Foodservice chefs in California and Provence specify fresh chèvre for composed salads and warm applications where melt behavior matters. Seasonal lactation cycles constrain year-round supply consistency.
- Aged:Surface-ripened or interior-ripened varieties with moisture below 45%, developing proteolytic flavor complexity over 3-12 weeks. Fine-dining tasting menus in France and the United States drive price realization for farmstead AOP designations. EFSA raw-milk documentation requirements extend production timelines.
- Flavored:Inclusions of herbs, ash, or fruit integrated during curd formation.
- Soft:High-moisture bloomy-rind styles with brief aging periods.
- Semi-Hard:Pressed curd with controlled moisture expulsion.
- Hard:Extended-aged varieties with granular texture and concentrated flavor.
Fresh dominates installed base. Aged is where expansion concentrates.
Application:
Margin tiering separates high-touch specialty channels from volume-driven retail, with digital direct-to-consumer emerging as a structural bypass of traditional distributor economics.
- Retail:Supermarket and mass-market placement requiring pasteurized supply chains and standardized portioning. Spain's Mercadona and France's Carrefour anchor volume throughput for compliant processors. Private-label compression limits branded margin capture.
- Foodservice:Restaurant, hotel, and institutional procurement with specification flexibility for raw-milk and farmstead credentials. Chefs in New York and Paris compose dishes around named-producer provenance. Menu integration drives premium price realization beyond retail tiers.
- Specialty Stores:Curated assortments emphasizing terroir storytelling and seasonal availability.
- Online Sales:Direct-to-consumer fulfillment bypassing wholesale markups through Shopify-enabled logistics.
- Gourmet Shops:High-service retail with cutting and wrapping capabilities.
Retail commands volume share. Online sales are climbing the fastest.
Packaging Type:
Carbon-footprint disclosure mandates and extended distribution requirements are reshaping material selection, with shelf-life extension becoming critical for hot-climate export viability.
- Vacuum Pack:Oxygen-exclusion barrier enabling 60-90 day refrigerated shelf life for semi-hard and hard varieties. Exporters to Dubai and Riyadh rely on vacuum technology for halal-certified ambient stability. EU packaging disclosure rules elevate material traceability requirements.
- Plastic Container:Rigid formats for fresh and soft varieties with modified atmosphere options. Greek and Portuguese processors favor this format for pooled logistics efficiency across Mediterranean retail networks. Recyclability standards tighten under emerging mandates.
- Aluminum Foil:Traditional wrapping for surface-ripened styles requiring gas exchange.
- Wax Coated:Natural barrier for aged wheels with aesthetic shelf appeal.
- Tubs:Portion-controlled formats for foodservice and deli counter applications.
Vacuum pack leads export suitability. Plastic container anchors domestic throughput.
End User:
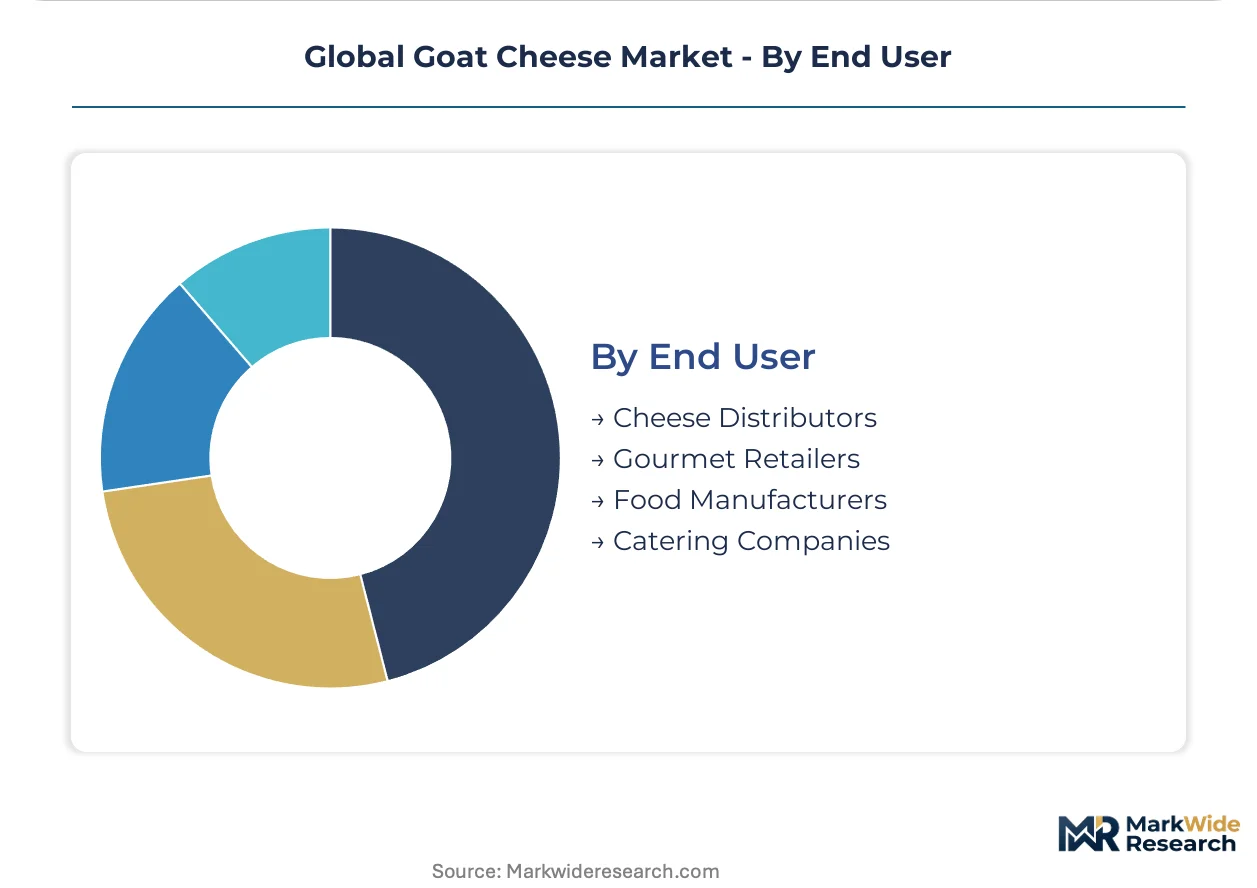
Procurement sophistication varies by buyer type, with gourmet retailers and catering companies demanding named-farm traceability while distributors and manufacturers prioritize volume consistency.
- Cheese Distributors:Wholesale intermediaries consolidating supply from multiple farmstead and industrial sources. Cold-chain infrastructure investments in Spain's Castilla-La Mancha and Portugal's Alentejo serve distributor consolidation points. Margin pressure from direct-to-consumer disintermediation.
- Gourmet Retailers:Curated assortments emphasizing AOP credentials and seasonal limited releases. Retailers in France and the United States conduct quarterly buying trips to named producers. Instagram-driven discovery concentrates volume with terroir-storytelling brands.
- Food Manufacturers:Industrial buyers integrating goat cheese into processed applications.
- Catering Companies:Event and institutional foodservice with specification flexibility for premium formats.
Distributors dominate volume aggregation. Gourmet retailers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Caprine dairy output clusters in Mediterranean basins where pastoral traditions intersect with cold-chain modernization. France, Spain, Greece, and Portugal anchor European supply, while the United States and emerging Middle Eastern markets reshape demand geography through gourmet retail expansion and halal certification requirements.
France
Farmstead AOP designations in Poitou-Charentes and the Loire Valley command premium placement at Paris gourmet retailers. EFSA regulation 2073/2005 enforcement tightens raw-milk documentation timelines, compressing small-producer compliance windows. Producers in the Massif Central are forming cooperative audit pools to share third-party certification costs.
Spain
Mercadona's private-label expansion drives pasteurized volume throughput for Castilla-La Mancha processors. The country's national food safety agency aligns veterinary inspection protocols with EU hygiene mandates for export eligibility. Murcia's caprine cooperatives are consolidating cold-chain infrastructure to serve Andalusian retail networks.
United States
Sonoma County terroir branding anchors California's artisanal positioning in domestic foodservice channels. FDA pasteurization requirements for interstate commerce constrain raw-milk distribution beyond state lines. Vermont and Wisconsin processors are investing in automated curd handling to scale farmstead output without credential dilution.
Greece
Thessaly's traditional feta-adjacent producers are diversifying into aged chèvre formats for German export markets. Fodder cost volatility from Aegean drought cycles strains year-round lactation consistency. Thessaloniki-based distributors are pooling logistics with Portuguese counterparts for shared Mediterranean retail access.
United Arab Emirates
Dubai's gourmet retail expansion creates demand for halal-certified goat cheese with extended ambient stability. MOHAP import documentation requirements govern veterinary clearance and label Arabic translation. Riyadh-based foodservice distributors are conducting quarterly sourcing trips to French AOP farmsteads for named-producer placement.
Global Goat Cheese Market Competitive Landscape
Concentration sits with diversified dairy conglomerates holding multi-plant infrastructure and consolidated cold-chain networks. The competitive terrain bifurcates between premium credential holders commanding AOP shelf space and commodity processors capturing private-label volume. Strategic archetypes include terroir-anchored farmstead specialists, scale-driven industrial dairies, and direct-to-consumer e-commerce natives. Dominant competitive moves encompass cooperative compliance pooling for small producers and backward integration into captive caprine herd management.
Within the diversified dairy tier, Saputo Inc. and Lactalis Group exemplify scale-driven infrastructure plays spanning North American and European retail networks respectively. Among terroir-anchored specialists, Laura Chenel's Chèvre, Inc. occupies a position representing California Sonoma County provenance in domestic foodservice channels. These three entities collectively illustrate how market position derives from either geographic diversification depth or single-origin narrative intensity.
| Leading Market Players |
|---|
| Saputo Inc. |
| Laura Chenel's Chèvre, Inc. |
| Lactalis Group |
| Savencia Fromage & Dairy |
| Vermont Creamery, LLC. |
| Cypress Grove Chevre, Inc. |
| St Helen's Farm Ltd. |
| Redwood Hill Farm & Creamery, Inc. |
| Haystack Mountain Creamery |
| Others |
Supply & Pricing Matrix
Multi-plant dairy infrastructure utilization rates above 80 percent in Castilla-La Mancha and Sonoma County simultaneously compress unit costs and elevate price floors for compliant processors. Scale concentration among AOP credential holders and commodity private-label suppliers bifurcates margin capture, with EFSA compliance costs acting as a selective barrier that protects premium tier pricing power while squeezing informal producers toward exit.
Pricing Analysis
EFSA regulation 2073/2005 dictates the pricing tier structure by imposing documentation and microbiological testing burdens that stratify producers across premium AOP farmstead, compliant industrial, and informal commodity levels. Price differentiation rests on certification grade and cold-chain infrastructure investment, with raw-milk credential holders commanding placement at Paris and New York gourmet retailers while pasteurized volume flows through Mercadona and Carrefour private-label channels. Cost compression in the commodity tier is intensifying because Mediterranean drought cycles constrain year-round milk supply consistency. Foodservice buyers in Provence and California exhibit the lowest price sensitivity due to menu integration premiums, while mass-market retail procurement teams in Spain and Portugal drive hardest on per-kilogram negotiations.
Supply Chain Analysis
Seasonal lactation cycles compress inventory turns to 8-12 weeks for fresh varieties while aged formats extend lead times to 3-4 months. Supply concentrates in France, Spain, and Greece, with Castilla-La Mancha processors drawing from pooled caprine cooperatives and Thessaly producers sourcing fodder from Aegean pasture networks. Raw material dependencies include alfalfa hay, veterinary pharmaceuticals, and ripening-room climate control equipment. Single-source vulnerability sits with Mediterranean basin drought frequency threatening simultaneous pasture degradation across southern France, Spain, and Greece. Distribution runs through consolidated cold-chain networks anchored by Lactalis Group logistics in Europe and regional distributor pools in North America, with direct-to-consumer Shopify fulfillment emerging as a parallel channel bypassing wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA regulatory fragmentation and direct-to-consumer channel disintermediation fragment competitive terrain, creating white-space niches for compliant niche producers and e-commerce-native entrants as demand concentrates in terroir-storytelling brands and halal-certified export formats.
For Market Incumbents: Compound AOP credential value through cooperative compliance pooling that shares third-party audit costs across Massif Central and Loire Valley producers, while extending cold-chain infrastructure into Dubai and Riyadh halal-certified distribution before carbon-footprint labeling mandates harden retailer qualification criteria. Precision fermentation startups threaten long-term livestock-based supply assumptions; backward integration into captive caprine herd management secures volume consistency against fodder cost volatility. For New Entrants and Emerging Players: AOP certification fast-track through 18-24 month farmstead qualification windows targets the most penetrable white-space in Middle Eastern gourmet retail, where MOHAP import documentation requirements favor early movers with extended ambient stability formulations. Direct-to-consumer Shopify fulfillment bypasses traditional distributor markups and captures margin pools previously allocated to wholesale intermediaries, with Instagram-driven discovery concentrating volume among terroir-storytelling brands. For Investors and Strategic Acquirers: Mid-scale farmstead specialists with existing AOP credentials and underutilized cold-chain capacity present acquisition targets positioned for premium retailer placement ahead of EU packaging disclosure enforcement. Long-term viability over the projection horizon hinges on carbon-footprint compliance positioning and halal certification capabilities for hot-climate export markets. The signal to watch is cooperative audit pool formation rates among French and Italian small producers, indicating consolidation pressure acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cooperative Compliance Pooling | Shared third-party audit costs reduce EFSA documentation burdens for Massif Central producers. |
| Halal Certification Investment | MOHAP clearance unlocks Dubai and Riyadh gourmet retail placement with ambient stability requirements. |
| Direct-to-Consumer Platform Launch | Shopify fulfillment bypasses wholesale markups and captures margin pools from distributor intermediation. |
| Carbon-Footprint Labeling Early Compliance | EU packaging disclosure positioning secures preferred retailer placement ahead of enforcement deadlines. |
| Backward Integration into Captive Herds | In-house caprine supply secures volume consistency against Mediterranean drought-driven fodder volatility. |
Research Methodology
Desk research of EFSA regulatory filings, EU trade customs databases, and FDA interstate commerce standards preceded structured interviews with AOP farmstead producers, cold-chain logistics operators, and gourmet retail category buyers across France, Spain, and California. Primary fieldwork with cheese distributors in Thessaloniki and Dubai supplemented secondary validation from agricultural cooperative reports and national food safety agency protocols. Bottom-up volume modeling across fresh, aged, and flavored product types triangulated against top-down value projections from retail audit data and foodservice procurement disclosures.
Variance decomposition across the projection horizon isolates drivers by product moisture content, aging protocol, packaging shelf-life extension, and channel mix between retail, foodservice, and direct-to-consumer fulfillment. Segmentation dimensions span certification grade, geographic production cluster, and halal compliance status. CAGRs derive from fitted growth curves calibrated to historical lactation cycle patterns and gourmet retail expansion trajectories in Middle Eastern markets. Forecast inputs incorporate EFSA enforcement timeline assumptions and precision fermentation technology adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained EFSA regulatory tightening or accelerated precision fermentation cost parity would require recalibration. Forecasts reflect documented assumptions regarding Mediterranean climate stability and caprine herd productivity trends. Drought frequency escalation or synthetic biology breakthroughs in casein production represent specific risk factors that could revise trajectory. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
United Kingdom Milk Protein Market
Dairy Products
Paneer Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
GCC Casein Market
Dairy Products
Natural Cheese Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Whole Milk Powder Market
Dairy Products
US Cheese Market
Dairy Products
Global Reduced Fat Butter Market
Dairy Products
Reconstituted Milk Market
Dairy Products
Gruyere Market