
 Global Yogurt Market | 2026-2036
Global Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Yogurt Market Outlook
ISO 22000 certification is rotating as the baseline food safety management standard that determines which manufacturers secure retail shelf space in developed markets. Danone leverages its integrated dairy supply chain across Western Europe to sustain premium positioning in Greek yogurt segments. Chobani anchors its competitive stance through specialized probiotic strain development and direct-store-delivery networks in North America. Nestlé competes by extending its infant nutrition expertise into functional adult yogurt formulations with clinically validated bacterial cultures.
Yogurt is a fermented milk product produced by bacterial fermentation of lactose into lactic acid, typically containing live and active cultures of Lactobacillus bulgaricus and Streptococcus thermophilus at minimum concentrations of 10^7 CFU per gram at manufacture, serving as a shelf-stable or refrigerated source of protein, calcium, and gut microbiome support for human consumption. Greek yogurt dominates margin pools due to its straining process that yields protein concentrations roughly double those of conventional stirred varieties, while non-dairy yogurt represents the fastest-expanding product type as oat and coconut bases displace soy formulations in allergen-sensitive households. Single-serve cups retain the largest packaging share in household channels, though pouches gain traction in health clubs and on-the-go consumption occasions where portability commands price premiums.
The FDA enforces Grade A Pasteurized Milk Ordinance standards for interstate dairy products in the United States, while EFSA governs nutrition and health claims on probiotic labeling across European markets, and China's SAMR implements GB standards for fermented dairy safety and additive limits. These frameworks collectively elevate compliance costs for cross-border entrants but simultaneously protect incumbent producers with established quality systems and local laboratory partnerships. Stakeholders must monitor evolving strain-specific health claim approvals and carbon-footprint disclosure requirements as regulators link dairy processing permissions to documented environmental impact reductions.
Market Dynamics
Cold-chain infrastructure expansion is compressing distribution timelines and enabling live-culture products to penetrate previously unreachable retail tiers, fundamentally altering competitive positioning around shelf-life guarantees and regional coverage depth.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Mandatory carbon-footprint disclosure and sustainable sourcing requirements are creating compliance-based competitive moats for producers with integrated dairy operations.
- Post-workout recovery applications:Health clubs and fitness centers now stock refrigerated yogurt bars, expanding consumption occasions beyond traditional breakfast and snack segments.
- Probiotic strain IP development:Clinically validated bacterial cultures are enabling differentiated health claims that command retail price premiums and secure pharmacy channel placement.
Market Restraints
- Milk powder input volatility:Greek yogurt's straining process requires concentrated milk solids, exposing margin structures to global dairy commodity swings.
- Single-country cold-chain concentration:Tier-one Chinese cities anchor demand growth, creating geographic vulnerability to regional logistics disruptions.
- EFSA health claim authorization delays:Strain-specific probiotic benefits face multi-year scientific review timelines, constraining marketing differentiation in European markets.
Strategic Opportunities
- India's organized retail expansion:Cold-chain penetration into secondary cities creates first-mover advantages for ISO 22000-certified entrants.
- SAMR GB standard alignment:China's fermented dairy safety framework rewards producers with pre-established laboratory partnerships and documented quality systems.
- Oat base convergence with barista formulations:Barista-grade oat yogurt textures are displacing coconut bases in allergen-sensitive café channels.
Industry Challenges
- ISO 22000 certification timelines:Multi-stage audit processes delay retail shelf access for new entrants in developed markets.
- Live culture viability maintenance:Temperature excursion risks during last-mile delivery compromise the 10^7 CFU per gram regulatory threshold.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Yogurt Market |
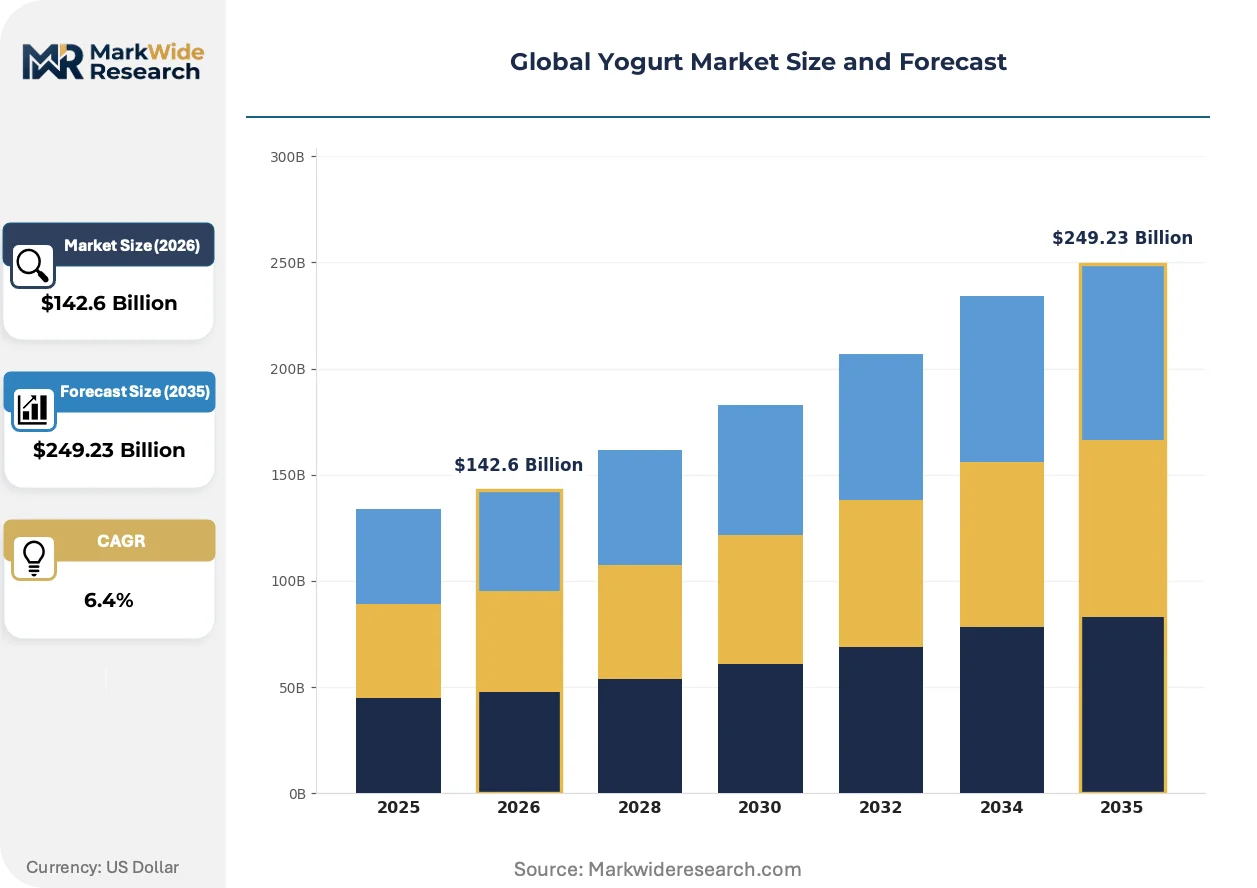
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $249.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Greek Yogurt, Low-Fat Yogurt, Non-Dairy Yogurt, Whole Milk Yogurt Sweetness Level: Unsweetened, Low-Sugar, Regular, High-Sugar Packaging Type: Single-Serve Cups, Multi-Pack Containers, Bulk Containers, Pouches End User: Households, Restaurants, Cafes, Health Clubs |
| Companies Covered | Danone, Chobani, Nestlé, China Mengniu Dairy Company Limited, FAGE International, Inner Mongolia Yili Industrial Group, Arla Foods, FrieslandCampina, Yakult Honsha, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Yogurt Market Strategic Shifts
Fermentation science and packaging engineering are converging to extend probiotic viability windows while regulatory frameworks harden around environmental accountability and substantiated health claims.
Precision fermentation platforms are bifurcating the ingredient supply base. Startups deploy biomass fermentation to produce dairy-identical proteins without lactose, while incumbents retrofit existing facilities for hybrid formulations. Health-conscious households in Germany and the Netherlands are accelerating adoption, forcing conventional processors to defend shelf space through accelerated R&D partnerships.
CSRD sustainability disclosure mandates are reshaping capital allocation across European dairy operations. Scope 3 emissions tracking now extends to feed crop cultivation and manure management, elevating compliance costs for cross-border suppliers. Greek yogurt producers with captive milk supply in France and the Netherlands are consolidating advantage through documented carbon intensity reductions.
Single-serve pouch formats are displacing traditional cups in on-premise fitness and corporate wellness channels. Health clubs in Tokyo, London, and New York now specify tamper-evident, spoon-free packaging as procurement criteria. This format rotation compresses manufacturing changeover schedules and demands co-packing partnerships with flexible packaging specialists.
Global Yogurt Market Segmentation
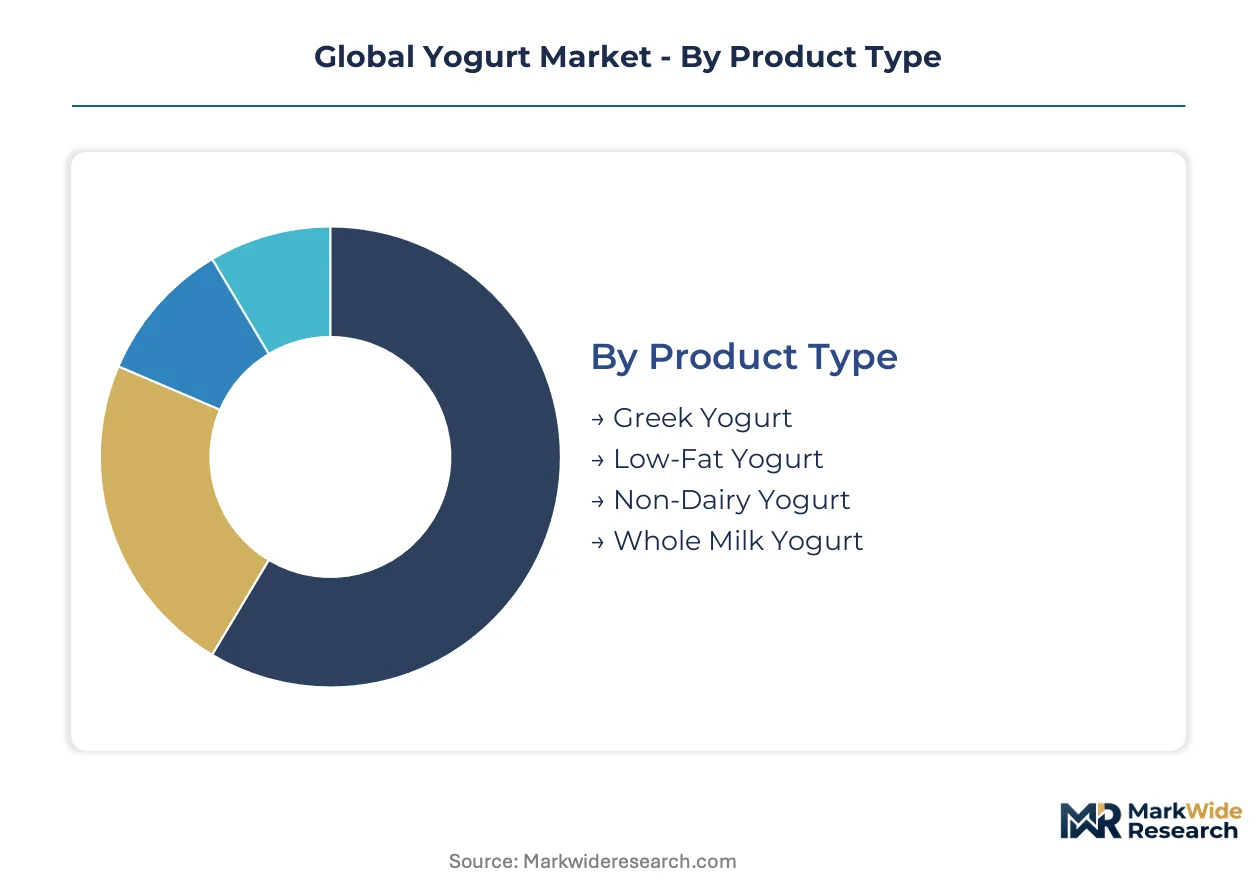
Yogurt segmentation maps directly to channel economics and margin architecture. Product type determines cold-chain investment intensity, while packaging format dictates placement across retail, foodservice, and fitness channels. Understanding these segment boundaries reveals where pricing power concentrates and where commodification pressures operate.
Product Type:
Channel-mix dynamics split sharply across product types, with premium formats commanding pharmacy and specialty retail placement while conventional varieties flow through mainstream grocery.
- Greek Yogurt:Strained to achieve protein concentrations roughly double conventional stirred varieties, this format anchors margin pools in developed markets. Demand concentrates in US coastal metro areas and German urban centers where fitness-oriented consumers prioritize post-workout recovery applications.
- Non-Dairy Yogurt:Oat and coconut bases are displacing soy formulations in allergen-sensitive households across the Netherlands and Sweden. This segment is climbing the fastest as precision fermentation platforms expand biomass-derived protein supply without lactose content.
- Low-Fat Yogurt:Retains volume leadership in conventional grocery channels across France and Italy where traditional dietary patterns persist.
- Whole Milk Yogurt:Premium positioning in artisanal retail and farmers market channels in Vermont and Provence clusters.
Greek yogurt dominates installed base. Non-dairy yogurt is where expansion concentrates.
Sweetness Level:
Cost tier stratification separates premium unsweetened formulations from economy high-sugar varieties, with regulatory pressure on added sugars compressing the latter's shelf space.
- Unsweetened:Clean-label positioning with zero added sugars attracts pharmacy channel placement and diabetic consumer segments in Japan and Switzerland. EFSA and FDA scrutiny on sugar reduction claims reinforces this tier's expansion trajectory.
- Low-Sugar:Stevia and monk fruit formulations penetrate corporate wellness programs and health club channels in London and New York where procurement specifications now exclude high-sugar options.
- Regular:Standard formulations maintain household penetration across middle-income demographics in Spain and Poland.
- High-Sugar:Confectionery-positioned varieties face declining retail authorization under EU Green Deal nutritional profiling criteria.
Unsweetened dominates installed base. Low-sugar is where expansion concentrates.
Packaging Type:
Application-specific formats align with consumption occasion fragmentation, from household pantry stocking to immediate on-premise consumption.
- Single-Serve Cups:Retain largest packaging share in household channels across the United States and Germany. Tamper-evident lids and resealable designs support lunchbox and commuter consumption patterns.
- Pouches:Spoon-free formats gain traction in Tokyo, London, and New York health clubs where portability commands price premiums and procurement criteria specify fitness-appropriate packaging.
- Multi-Pack Containers:Volume efficiency drives adoption in family households across suburban France and Ontario province.
- Bulk Containers:Foodservice portioning for restaurant and cafe channels in Melbourne and Barcelona clusters.
Single-serve cups dominate installed base. Pouches are where expansion concentrates.
End User:
Customer type determines margin capture, with institutional channels offering volume scale and household channels providing pricing flexibility.
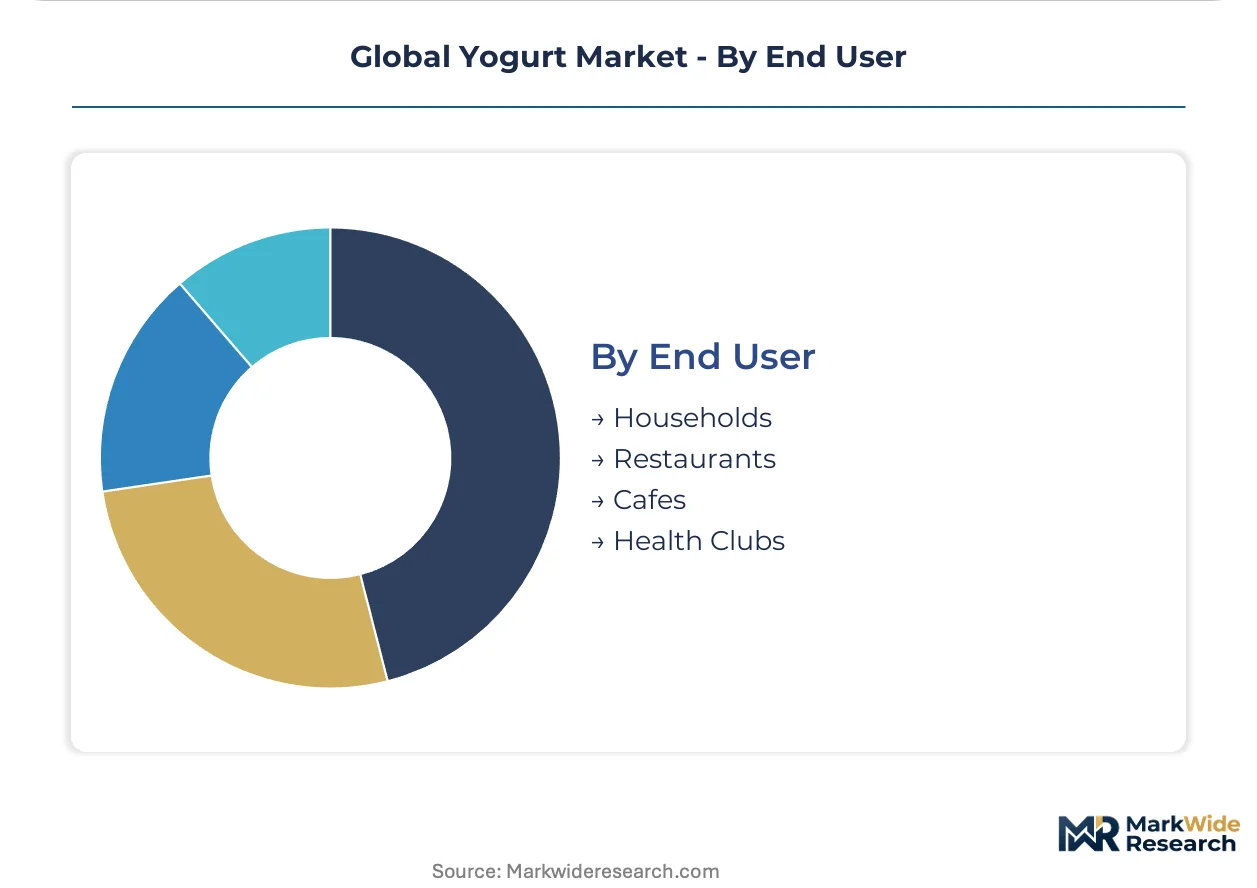
- Households:Core consumption occasion spanning breakfast, snacking, and recipe integration across all developed markets. Refrigerated retail placement and promotional sensitivity characterize this segment's procurement patterns.
- Health Clubs:Post-workout recovery positioning creates premium pricing architecture in fitness centers across Manhattan, Shibuya, and Canary Wharf. Cold-chain infrastructure investments enable live-culture product viability in these non-traditional channels.
- Restaurants:Ingredient and dessert applications in casual dining across Sydney and Singapore.
- Cafes:Barista-grade oat yogurt textures in specialty coffee channels across Stockholm and Portland.
Households dominate installed base. Health clubs are where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fitness-oriented consumers in coastal United States metros and German urban centers drive premium Greek yogurt demand, while cold-chain expansion unlocks secondary city penetration in India and China's interior provinces.
United States
Post-workout recovery applications dominate Manhattan and Los Angeles health club procurement, with refrigerated yogurt bars now standard amenity offerings. FDA enforcement of Grade A Pasteurized Milk Ordinance standards elevates compliance costs for interstate entrants. New York and California coastal clusters anchor Greek yogurt consumption where protein-conscious consumers command price premiums.
China
Tier-one city demand concentrates in Beijing and Shanghai where Mengniu and Yili extend cold-chain distribution networks into premium retail channels. SAMR implementation of GB standards for fermented dairy safety rewards producers with documented laboratory partnerships and quality systems. Guangzhou and Shenzhen clusters show fastest pouch-format adoption for on-the-go consumption occasions.
Germany
Unsweetened and low-sugar formulations penetrate pharmacy and corporate wellness channels in Berlin and Munich under EFSA nutrition claim scrutiny. EU Green Deal Farm to Fork Strategy mandates carbon-footprint disclosure across dairy supply chains, favoring integrated producers. Bavaria and Baden-Württemberg regions host precision fermentation startups challenging conventional biomass supply.
India
Organized retail expansion into Bangalore and Hyderabad secondary cities creates first-mover openings for ISO 22000-certified entrants with viable cold-chain infrastructure. FSSAI fermented dairy safety frameworks align with international standards, reducing technical barriers for quality-focused foreign producers. Maharashtra and Gujarat dairy belts concentrate domestic supply capacity serving urban demand corridors.
Japan
Diabetic consumer segments and aging demographics drive unsweetened yogurt placement in Tokyo and Osaka pharmacy channels with clinically validated strain claims. METI standards on functional food substantiation constrain marketing differentiation timelines. Kanto and Kansai metropolitan clusters dominate live-culture product distribution where temperature integrity commands logistics investment.
Global Yogurt Market Competitive Environment
Player mix skews toward integrated dairy conglomerates with captive milk supply, creating tiered competition between global scale operators and regional specialists. Market structure consolidates around three strategic archetypes: multinational nutrition conglomerates leveraging infant formula expertise into adult functional segments, integrated European dairy cooperatives with documented sustainability credentials, and Asia-Pacific pure-plays exploiting cold-chain infrastructure gaps. Dominant competitive moves include backward integration into biomass fermentation platforms and strategic co-packing partnerships for flexible pouch manufacturing.
Within the integrated dairy tier, Danone, Chobani, and Nestlé occupy positions that exemplify divergent strategic vectors. Danone anchors European premium positioning through Western European supply chain integration. Chobani represents North American specialist concentration around proprietary strain development and direct-store-delivery density. Nestlé exemplifies cross-category nutrition expertise migration from infant formulations into clinically validated adult probiotic offerings. China Mengniu Dairy Company Limited and Inner Mongolia Yili Industrial Group sit within the Asia-Pacific expansion archetype, leveraging domestic cold-chain scale to defend against multinational entrants.
| Leading Market Players |
|---|
| Danone |
| Chobani |
| Nestlé |
| China Mengniu Dairy Company Limited |
| FAGE International |
| Inner Mongolia Yili Industrial Group |
| Arla Foods |
| FrieslandCampina |
| Yakult Honsha |
| Others |
Value Chain & Pricing Dynamics
Scale economies in Greek yogurt straining operations concentrate margin leverage among integrated dairy processors with captive milk supply across France and the Netherlands, compressing price floors for contract-dependent competitors while elevating premium capture for probiotic IP holders.
Pricing Analysis
Cost-plus contracts indexed to Global Dairy Trade milk powder benchmarks dominate Greek yogurt procurement, with protein concentration tiers separating premium formulations from standard stirred varieties. Price differentiation rests on ISO 22000 certification grade and live-culture viability guarantees at the 10^7 CFU per gram threshold. Margins are tightening due to concentrated milk solids input volatility and cold-chain logistics cost escalation. Health club channels show least price sensitivity, while conventional grocery buyers in Spain and Poland exhibit highest promotional responsiveness.
Supply Chain Analysis
Inventory velocity and lead-time compression now define competitive positioning as live-culture viability windows shrink to 72-hour distribution cycles. Milk solids supply concentrates in France, the Netherlands, and New Zealand, with precision fermentation biomass emerging from Germany and California. Raw material dependencies center on skim milk powder, probiotic strain cultures, and oat protein isolates. Single-country cold-chain concentration in China's tier-one cities creates geographic vulnerability to regional logistics disruptions. Distribution runs through direct-store-delivery networks for fresh formats and third-party cold-chain operators for retail multiplex.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward health club procurement committees and organized retail category managers as consolidation among fitness channel operators concentrates volume negotiation leverage against fragmented dairy processors.
For Market Incumbents: Fortify cold-chain infrastructure density in India's secondary cities before ISO 22000-certified entrants establish laboratory partnerships. Deepen backward integration into biomass fermentation platforms to offset milk powder cost volatility. Defend against precision fermentation startups by accelerating proprietary strain IP development and direct-store-delivery network expansion. For New Entrants and Emerging Players: Anchor in India's Bangalore and Hyderabad corridors where organized retail expansion outpaces incumbent cold-chain coverage. Target health club channels in Tokyo and London where spoon-free pouch specifications command price premiums. Pursue co-packing partnerships with flexible packaging specialists to bypass capital-intensive manufacturing barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated dairy cooperatives with documented EU Green Deal carbon-footprint compliance and captive feedstock supply. Long-term viability over a multi-year horizon favors processors with pharmacy channel placement and clinically validated strain portfolios. Monitor EFSA strain-specific health claim authorization timelines as inflection indicators for marketing differentiation capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Enables live-culture viability in India's secondary cities where FSSAI standards reduce technical barriers. |
| Precision Fermentation Platform Investment | Produces dairy-identical proteins without lactose, displacing conventional biomass in German and Dutch households. |
| Probiotic Strain IP Development | Secures pharmacy channel placement in Tokyo and Osaka under METI functional food substantiation frameworks. |
| Flexible Pouch Manufacturing Partnership | Meets health club procurement specifications in Manhattan, Shibuya, and Canary Wharf fitness centers. |
| ISO 22000 Certification Acceleration | Determines retail shelf access in developed markets where audit timelines delay new entrant market entry. |
Study Parameters
Operator-level perspectives from dairy procurement managers, cold-chain logistics directors, health club facility operators, and pharmacy category buyers anchored the qualitative base. Secondary validation drew from FDA Grade A Pasteurized Milk Ordinance filings, EFSA health claim authorization databases, SAMR GB standard documentation, and Global Dairy Trade auction data. Bottom-up volume modeling triangulated against top-down macroeconomic demand projections.
Sensitivity analysis tested forecast outputs across alternative cold-chain penetration scenarios and milk powder price volatility bands. Segmentation dimensions modeled encompassed product type, packaging format, sweetness level, and end-user channel across the projection horizon. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and technology adoption S-curves. Strain-specific health claim approval timelines and EU Green Deal carbon disclosure mandates served as key industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of sustained cold-chain infrastructure investment and stable dairy commodity input costs; material deviation in either would warrant model refresh. Specific risk factors include EFSA authorization delays constraining European marketing differentiation and regional logistics disruptions affecting China's tier-one city concentration. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
South America Dairy Protein Market
Dairy Products
Non-Fat Milk Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
North America Flavored Milk Market
Dairy Products
Global Butter Market
Dairy Products
India Milk Protein Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Dairy Protein Market
Dairy Products
Clotted Cream Market
Dairy Products
Low Calorie Whipped Cream Market
Dairy Products
Russia Whey Protein Market
Dairy Products
India Dairy Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Sheep Milk Cheese Market
Dairy Products
Nigeria Yogurt Drinks Market