
 North America Casein and Caseinate Market | 2026-2036
North America Casein and Caseinate Market Size, Share, and Industry Trends Forecast 2026-2036
North America Casein and Caseinate Market Analytics
Modular ingredient bundling is recalibrating how food processors procure casein derivatives, shifting from single-specification bulk orders to blended protein systems that combine micellar casein with hydrolysates. FrieslandCampina Ingredients leverages its European dairy science heritage to anchor premium positioning in North American sports nutrition channels. Milk Specialties Global dominates domestic micellar casein production through its Minnesota-based fractionation network. AMCO Proteins specializes in custom caseinate formulations for meat binding applications, occupying a defensible niche against commodity suppliers.
Casein denotes a family of phosphoproteins precipitated from skim milk through acid or rennet treatment, comprising alpha, beta, and kappa fractions with molecular weights ranging from nineteen to twenty-four kilodaltons; caseinates result from alkali neutralization of acid casein to improve solubility and emulsification in processed foods. Sodium caseinate leads application volumes due to its superior foaming and water-binding properties in coffee whiteners and whipped toppings. Calcium caseinate captures expanding share in ready-to-drink nutritional supplements where mineral fortification aligns with aging-population dietary protocols. Casein hydrolysate represents the fastest-growing product type as enzymatic pre-digestion accelerates absorption kinetics for clinical nutrition and elite athletic recovery segments.
FDA dairy identity standards and USDA Agricultural Marketing Service grading protocols govern casein purity, labeling, and interstate commerce, while state-level dairy departments in Wisconsin and California enforce additional fluid milk sourcing traceability that cascades into caseinate supply chains. The EPA Clean Water Act permitting requirements for dairy processing effluent constrain expansion economics for new fractionation facilities, particularly in water-stressed regions of the Southwest. Stakeholders must monitor evolving FDA bioengineered food disclosure regulations and their potential classification implications for precision-fermentation-derived casein alternatives entering commercial channels.
Market Dynamics
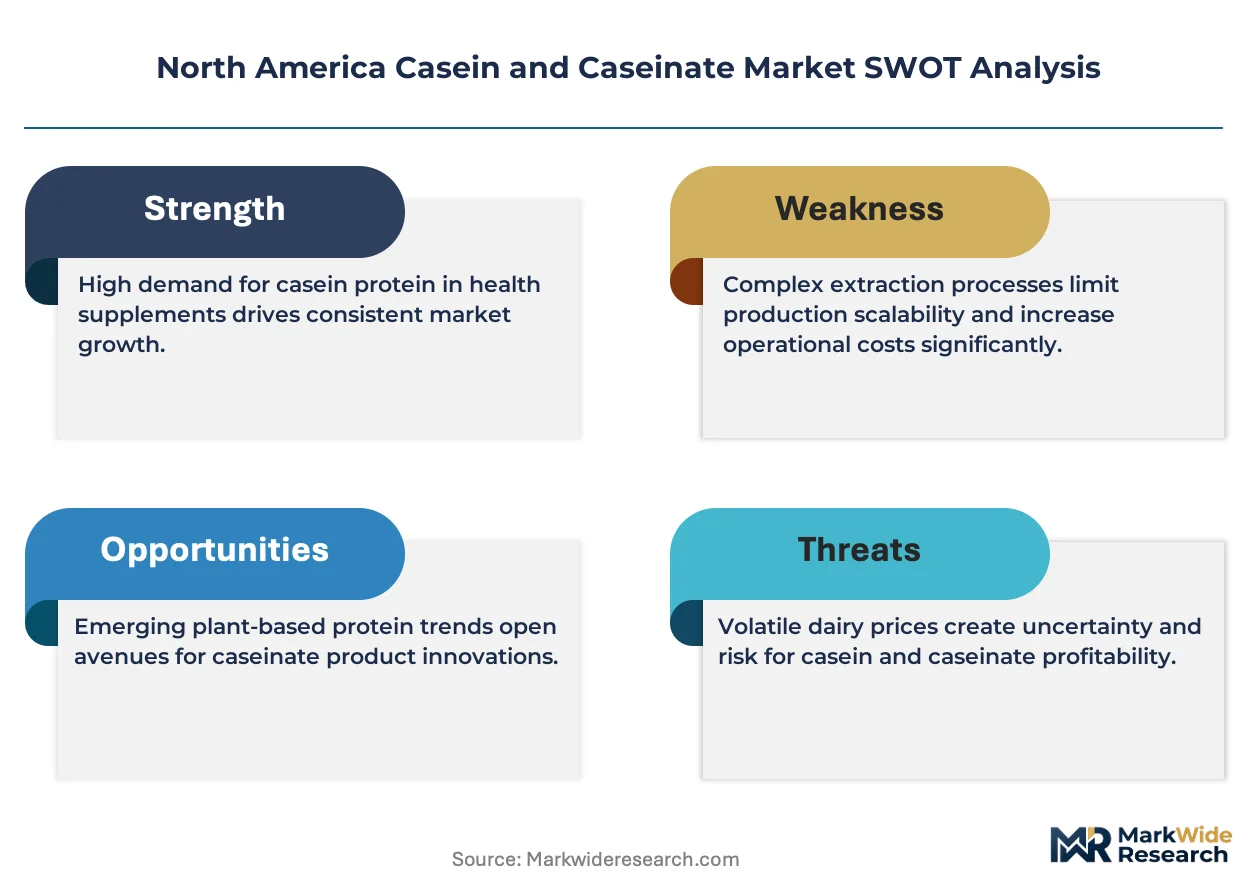
FDA and USDA purity benchmarks are tightening simultaneously with EPA effluent constraints on dairy fractionation facilities, compressing margins for commodity caseinate suppliers while advantaging integrated processors with captive whey-casein separation infrastructure.
Growth Catalysts
- Sports Nutrition Formulation Evolution:Sustained amino acid release properties of micellar casein are electrifying demand from endurance athletes and bodybuilders seeking overnight recovery protocols. Ready-to-drink protein beverages now specify casein hydrolysate content for absorption kinetics.
- USDA Dairy Identity Standards:Tightened food-grade purity benchmarks for caseinate derivatives are disqualifying marginal importers and consolidating procurement toward domestic fractionators with verified fluid milk traceability.
- Midwest Dairy Belt Concentration:Whey and casein fractionation capacity clustering near Wisconsin and Minnesota cheese production hubs is reducing logistics costs for industrial food processors sourcing bulk sodium caseinate.
Market Restraints
- Fluid Milk Input Volatility:Regional drought cycles and feed cost spikes in California and Wisconsin dairy corridors transmit directly to acid casein production economics, compressing processor margins unpredictably.
- EPA Clean Water Act Permitting:Effluent discharge constraints for dairy processing facilities in Southwest water-stressed zones block greenfield fractionation expansion regardless of demand pull from nutritional supplement manufacturers.
- Precision Fermentation Substitution:Microbial-derived dairy proteins from fermentation bioreactors threaten to displace commodity caseinate in vegan-formulated sports nutrition and clinical nutrition applications.
Strategic Opportunities
- Mexico Nutraceutical Underpenetration:Aging-population dietary fortification protocols in Mexican urban centers remain underserved by calcium caseinate suppliers, creating first-mover positioning for mineral-fortified ready-to-drink entrants.
- IRA Clean Energy Manufacturing Credits:Biogas capture installations at dairy processing facilities can offset EPA compliance costs while qualifying for federal tax incentives that improve caseinate production economics.
- Enzymatic Hydrolysis Convergence:Integration of membrane filtration with targeted protease systems is enabling custom peptide fractionation for elite athletic recovery segments previously served by generic protein isolates.
Industry Challenges
- Dairy Protein Fractionation Expertise Gap:Skilled technicians capable of optimizing micellar casein yield from continuous centrifugation systems command premium wages that strain mid-tier processor operating models.
- FDA Bioengineered Disclosure Uncertainty:Pending classification protocols for precision-fermentation-derived casein alternatives create labeling compliance risk for blended protein systems containing both dairy and biotech inputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Casein and Caseinate Market |
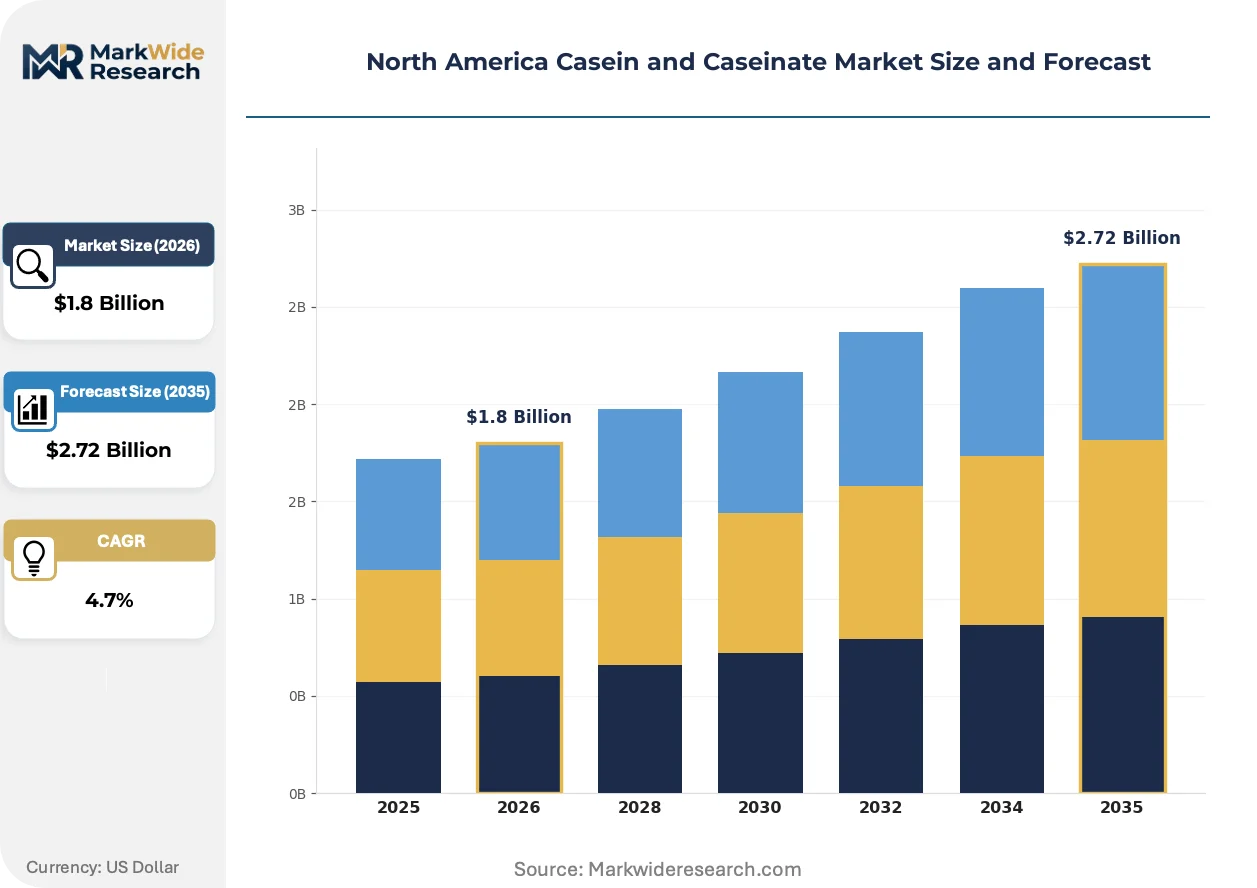
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Micellar Casein, Sodium Caseinate, Calcium Caseinate, Casein Hydrolysate Application: Dairy Products, Bakery Products, Nutritional Supplements, Meat Products End User: Beverage Manufacturers, Food Processors, Dietary Supplement Providers, Pharmaceutical Companies Distribution Channel: Direct Sales, Supermarkets, Online Retailers, Specialty Stores |
| Companies Covered | Arla Foods amba, Farbest-Tallman Foods Corporation, Fonterra Co-operative Group Limited, FrieslandCampina Ingredients, Milk Specialties Global, Dairy Farmers of America, AMCO Proteins, Erie Foods International, Idaho Milk Products, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Casein and Caseinate Market Evolving Landscape
Electrification of separation technology and enzymatic processing is reshaping how casein derivatives achieve functional differentiation, while regulatory disclosure requirements and procurement consolidation are rewriting commercial terms between fractionators and downstream formulators.
Membrane filtration cascades combined with ceramic microfiltration is electrifying micellar casein isolation from skim milk, enabling protein concentration above ninety percent without denaturation. Sports nutrition contract manufacturers in the United States Midwest are retrofitting spray-drying lines to handle these high-viscosity concentrates. The technology is electrifying premium positioning for domestic suppliers against European import competition.
USDA Agricultural Marketing Service grading protocols now mandate enhanced traceability documentation for fluid milk entering caseinate supply chains, with Wisconsin and California state dairy departments enforcing additional sourcing verification. Interstate commerce friction has intensified for processors lacking integrated herd-to-facility tracking systems. Sodium caseinate suppliers serving coffee whitener manufacturers face the steepest compliance timeline compression.
Ingredient bundling contracts are consolidating procurement decisions at North American food processors, replacing single-specification bulk orders with multi-protein systems combining micellar casein, hydrolysates, and texturizing agents. Blended protein specifications now dominate RFPs from meat analog and nutritional bar manufacturers. This consolidation pattern is most visible in Minnesota and Iowa processing corridors where dairy and plant-protein supply chains intersect.
North America Casein and Caseinate Market Segmentation
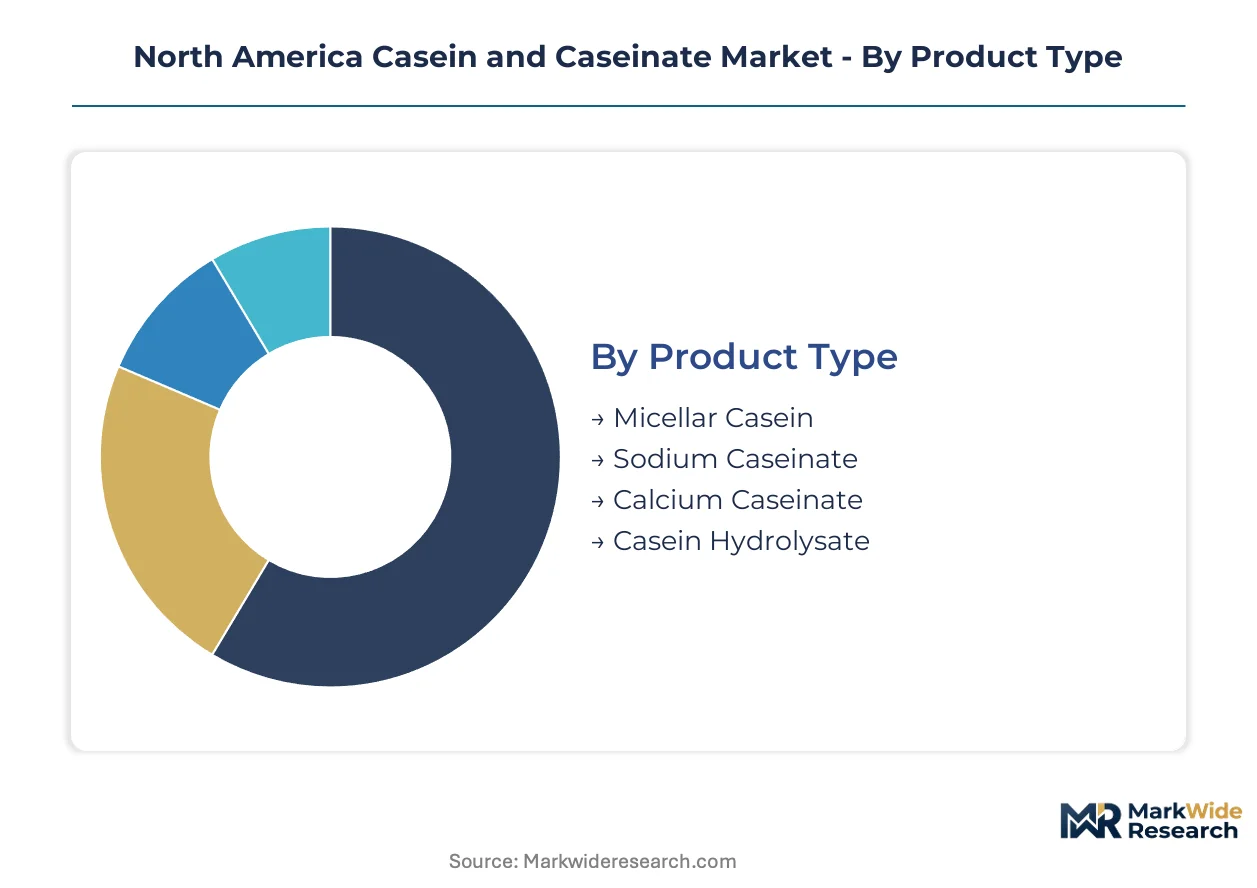
Casein derivative procurement in North America stratifies sharply between commodity bulk orders and precision-formulated ingredient systems. Food processors and supplement manufacturers demand specification granularity that rewards fractionators with flexible production infrastructure.
Product Type:
Customization intensity spans from standardized commodity powders to enzymatically modified fractions with absorption kinetic specifications.
- Micellar Casein:Native protein structure preserved through membrane filtration maintains slow-release amino acid profiles. Sports nutrition contract manufacturers in Minnesota and Wisconsin specify this fraction for overnight recovery formulations targeting endurance athletes.
- Sodium Caseinate:Alkali-neutralized derivative delivering superior foaming and emulsification. Coffee whitener and whipped topping producers in the US Midwest source this grade for its water-binding stability in low-pH beverage systems.
- Calcium Caseinate:Mineral-fortified variant capturing ready-to-drink supplement demand. Aging-population dietary protocols drive formulation interest among clinical nutrition providers.
- Casein Hydrolysate:Pre-digested peptide fractions enabling rapid absorption. Enzymatic hydrolysis investments concentrate among suppliers serving elite athletic recovery segments.
Leading the category by volume: Sodium Caseinate. Growing fastest: Casein Hydrolysate.
Application:
End-use concentration patterns reveal divergent margin profiles across mature food manufacturing versus emerging functional nutrition channels.
- Dairy Products:Standardized caseinate incorporation into processed cheese and yogurt applications. Wisconsin and California dairy processors specify food-grade purity benchmarks for recombined milk products.
- Bakery Products:Emulsification and moisture retention in commercial bread and pastry systems. Industrial bakers in the US Midwest procure sodium caseinate for dough conditioning protocols.
- Nutritional Supplements:Protein fortification spanning ready-to-mix powders and ready-to-drink beverages. This segment commands premium pricing for micellar casein and hydrolysate specifications.
- Meat Products:Binding and texturizing functionality in processed meat and meat analog formulations. AMCO Proteins occupies specialized positioning for custom caseinate meat-binding systems.
Dominant volume share: Dairy Products. Steepest expansion trajectory: Nutritional Supplements.
End User:
Procurement sophistication tiers separate commodity-scale food manufacturers from specification-intensive pharmaceutical and supplement formulators.
- Beverage Manufacturers:Coffee whitener and protein drink producers sourcing sodium caseinate for emulsion stability. FDA dairy identity standards govern label claims for these applications.
- Food Processors:Industrial-scale buyers of standardized caseinates for bakery, dairy, and meat system integration. Procurement consolidation favors suppliers with captive fractionation infrastructure.
- Dietary Supplement Providers:Sports nutrition and clinical nutrition formulators demanding micellar casein and hydrolysate with absorption kinetic documentation. FrieslandCampina Ingredients and Milk Specialties Global compete for this high-specification segment.
- Pharmaceutical Companies:Clinical nutrition and enteral feeding applications requiring GMP-compliant production. Traceability documentation from fluid milk source to finished caseinate is mandatory.
Highest procurement volume: Food Processors. Fastest specification evolution: Dietary Supplement Providers.
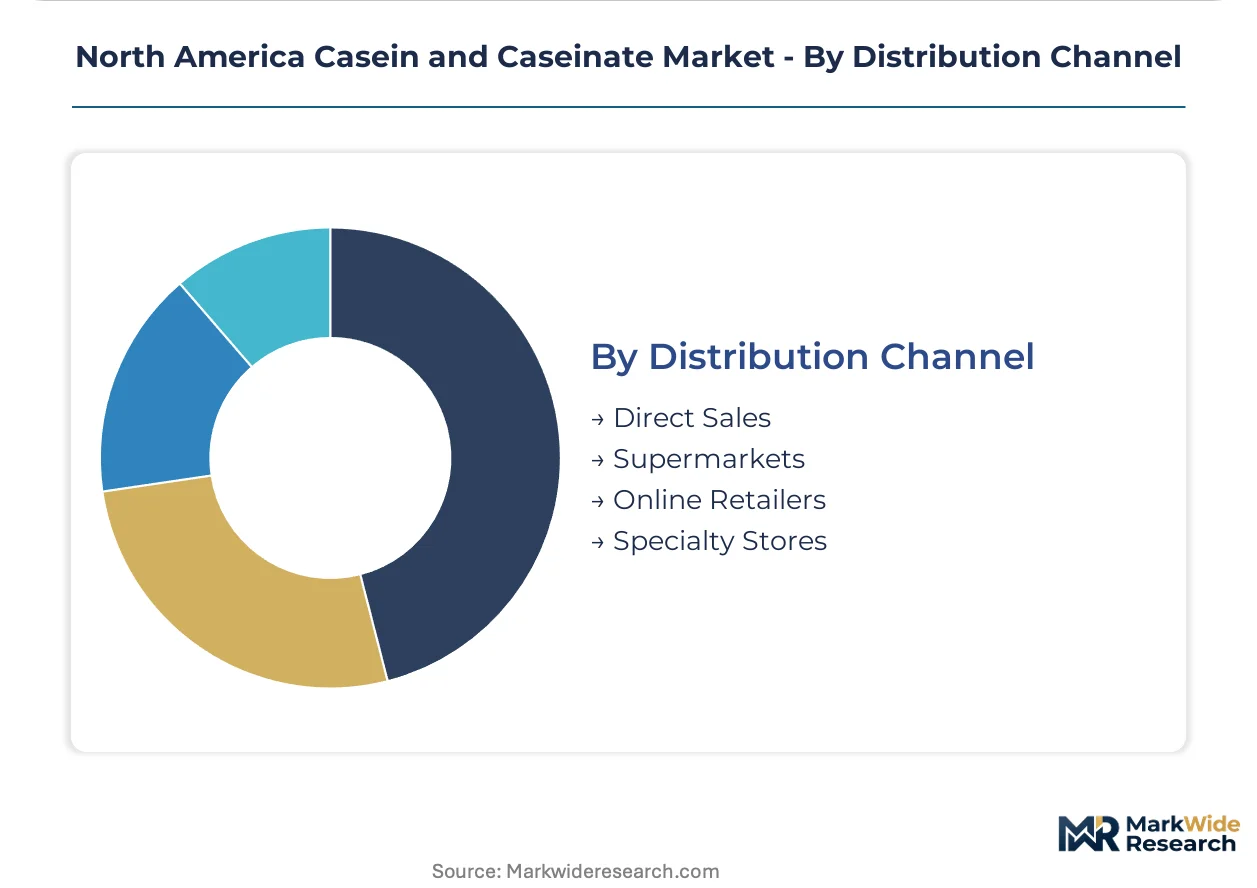
Distribution Channel:
Channel selection correlates with order scale, formulation complexity, and required technical support intensity.
- Direct Sales:Bulk procurement relationships between fractionators and industrial food processors. Minnesota-based Milk Specialties Global leverages this channel for micellar casein volume contracts.
- Supermarkets:Consumer-facing retail of finished products containing caseinate ingredients. Not a direct channel for ingredient sales.
- Online Retailers:E-commerce platforms serving small-scale supplement manufacturers and specialty food producers. Growing channel for sample quantities and custom formulation ingredients.
- Specialty Stores:Regional distributors serving niche meat processing and artisan dairy operations. Limited volume but high-margin technical service relationships.
Primary volume channel: Direct Sales. Expanding most quickly: Online Retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States produces the majority of North American casein and caseinate output, yet Mexican nutraceutical demand is expanding faster than domestic supply can capture. Canada maintains specialized fractionation capacity serving cross-border pharmaceutical applications. This production-consumption asymmetry is reshaping trade flows across the continent.
United States
Wisconsin and Minnesota cheese production hubs anchor the Midwest dairy belt fractionation network, where whey-casein separation infrastructure clusters near fluid milk supply. FDA dairy identity standards and USDA Agricultural Marketing Service grading protocols govern interstate commerce, tightening purity documentation requirements. Minnesota-based Milk Specialties Global dominates micellar casein output through its captive centrifugation systems.
Canada
Clinical nutrition and enteral feeding applications drive demand for GMP-compliant caseinate from pharmaceutical formulators in Ontario and Quebec. Health Canada and the Canadian Food Inspection Agency enforce traceability protocols that exceed baseline FDA requirements for fluid milk sourcing. Quebec's dairy processing corridor maintains specialized capacity for pharmaceutical-grade sodium caseinate.
Mexico
Aging-population dietary fortification protocols in Mexico City and Monterrey urban centers remain underserved by calcium caseinate suppliers, creating first-mover positioning opportunities. COFEPRIS pharmaceutical regulations and NOM food safety standards govern import and labeling of nutritional ingredients. Northern border states concentrate cross-border logistics infrastructure for US-sourced caseinate distribution.
California
Regional drought cycles and feed cost volatility in the Central Valley dairy corridor transmit directly to acid casein production economics, compressing processor margins unpredictably. California Department of Food and Agriculture enforces additional fluid milk sourcing traceability beyond federal baselines. EPA Clean Water Act permitting constraints block greenfield fractionation expansion in water-stressed Southwest zones.
North America Casein and Caseinate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a market structure that rewards captive fractionation infrastructure. The vendor base stratifies into three tiers: integrated dairy cooperatives with upstream milk supply control, independent protein processors with flexible hydrolysis capabilities, and commodity traders lacking production assets. Dominant competitive moves include backward integration into fluid milk sourcing and enzymatic hydrolysis technology licensing for custom peptide fractionation.
Within the premium functional ingredients tier, FrieslandCampina Ingredients leverages its European dairy science heritage to anchor positioning in North American sports nutrition channels, while Milk Specialties Global exemplifies the domestically integrated processor archetype through its Minnesota-based fractionation network. AMCO Proteins occupies a defensible specialist position against commodity suppliers.
| Leading Market Players |
|---|
| Arla Foods amba |
| Farbest-Tallman Foods Corporation |
| Fonterra Co-operative Group Limited |
| FrieslandCampina Ingredients |
| Milk Specialties Global |
| Dairy Farmers of America |
| AMCO Proteins |
| Erie Foods International |
| Idaho Milk Products |
| Others |
Value Network & Pricing Analysis
Ingredient bundling contracts from Midwest food processors are forcing fractionators to absorb formulation complexity costs, compressing commodity caseinate margins while rewarding suppliers with captive micellar casein infrastructure and enzymatic hydrolysis capabilities.
Pricing Analysis
Margin tightening in sodium caseinate reflects USDA purity documentation burdens and EPA effluent compliance costs that commodity suppliers cannot pass through to coffee whitener manufacturers. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade specifications separates GMP-certified Canadian output from standard Midwest production. Cost-down pressure on unbranded caseinate accelerates because Mexican importers demand COFEPRIS-aligned traceability without premium absorption capacity. Beverage manufacturers exhibit highest price sensitivity; pharmaceutical formulators in Ontario and Quebec show least.
Supply Chain Analysis
Single-source vulnerability sits with Wisconsin and Minnesota fluid milk supply, where drought-induced feed cost spikes transmit directly to acid casein production economics. Raw material dependencies encompass skim milk solids, alkali neutralization agents, and protease enzymes for hydrolysis. Supply chain risk centers on EPA Clean Water Act permitting constraints that block greenfield fractionation expansion in Southwest water-stressed zones regardless of demand pull. Distribution runs through direct sales contracts between fractionators and industrial food processors, with online retailers capturing sample-quantity growth from specialty supplement manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EPA effluent constraints on dairy processing facilities are capping fractionation capacity expansion across the Southwest, propping pricing power for incumbent Midwest suppliers with existing permits and integrated herd-to-facility infrastructure.
For Market Incumbents: Deploy enzymatic hydrolysis licensing to capture custom peptide fractionation premiums from elite athletic recovery segments previously served by generic isolates. Backward integration into fluid milk sourcing through cooperative supply agreements insulates against California and Wisconsin drought volatility that threatens acid casein production economics. Precision fermentation substitution from microbial-derived dairy proteins demands defensive certification investments in FDA-aligned traceability documentation.
For New Entrants and Emerging Players: Membrane filtration convergence with targeted protease systems offers technology-first positioning against established spray-drying incumbents. Mexico's aging-population calcium caseinate underpenetration in Mexico City and Monterrey urban corridors represents the most penetrable white-space target for mineral-fortified ready-to-drink entrants. Go-to-market execution should leverage COFEPRIS regulatory alignment as a competitive differentiator against US suppliers lacking Latin American compliance infrastructure.
For Investors and Strategic Acquirers: The window for entry favors fractionators with captive centrifugation systems and verified fluid milk traceability exceeding baseline USDA requirements. Long-term viability across the analysis window hinges on positioning for precision-fermentation hybridization rather than pure dairy dependency. Acquisition target archetype: mid-tier enzymatic hydrolysis specialists with flexible peptide fractionation capabilities. Signal to watch: FDA bioengineered disclosure regulations classifying fermentation-derived casein alternatives and their labeling implications for blended protein systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Hydrolysis Licensing | Enables custom peptide fractionation for elite athletic recovery segments demanding absorption kinetic documentation. |
| Backward Integration into Fluid Milk | Secures Wisconsin and Minnesota cooperative supply agreements against drought-induced feed cost volatility. |
| COFEPRIS Regulatory Alignment | Unlocks Mexico City and Monterrey distribution for calcium caseinate mineral fortification protocols. |
| Membrane Filtration Retrofit | Captures micellar casein premiums above ninety percent protein concentration without denaturation. |
| Biogas Capture Installation | Qualifies for IRA Clean Energy Manufacturing Credits while offsetting EPA compliance costs at dairy processing facilities. |
Research Methodology
Document review covered FDA dairy identity standards, USDA Agricultural Marketing Service grading protocols, EPA Clean Water Act permitting databases, and COFEPRIS pharmaceutical regulations, complemented by interviews with fractionation plant managers, sports nutrition formulation scientists, dairy cooperative procurement leads, and clinical nutrition GMP compliance officers. Secondary validation drew from SEC 10-K filings of listed dairy processors, customs trade data for casein derivatives, and state-level dairy department sourcing documentation from Wisconsin and California. Bottom-up volume modeling triangulated against top-down value projections across the analysis window.
Cross-referencing historical production capacity utilization against panel input from Minnesota and Wisconsin fractionation operators anchored the forecast framework. Segmentation dimensions encompassed product type tier, application end-use, and pharmaceutical versus food-grade certification level. CAGRs derived from regression analysis of installed membrane filtration capacity and enzymatic hydrolysis investment pipelines. Industry-specific inputs included fluid milk solids pricing volatility indices and EPA permitting approval timelines for dairy processing effluent discharge.
Several conditions sit outside the modeled scope, including unannounced precision fermentation commercialization timelines, abrupt shifts in FDA bioengineered disclosure classification, and extreme drought scenarios exceeding historical California Central Valley patterns. Forecasts reflect documented assumptions about regulatory stability and feed cost transmission mechanisms. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Skimmed Milk Powder Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Global Lipolyzed Butter Fat Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
High Protein Yogurt Market
Dairy Products
Anhydrous Milk Fat (Butter Oil) Market
Dairy Products
Reduced Lactose Whey Market
Dairy Products
North America Sour Cream Market
Dairy Products
Dairy Protein Market
Dairy Products
North America Milk Powder Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
Dairy Products Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Kefir Market
Dairy Products
United Arab Emirates Dairy Market