
 Bulk Food Ingredients Market | 2026-2036
Bulk Food Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Food Ingredients Market Analysis
Multi-source procurement of grains, pulses, and oilseeds is expanding as food manufacturers diversify supply bases beyond traditional origination points. Cargill, Incorporated leverages its global origination network to sustain volume commitments across volatile harvest cycles. Archer Daniels Midland Company anchors North American grain flows through its inland elevator system. Bunge Limited competes in South American oilseed processing with integrated crushing and export terminal assets.
Bulk food ingredients comprise unprocessed or minimally processed agricultural commodities—wheat berries, dried legumes, shelled nuts, and oilseeds—traded in volumes exceeding standard retail units, typically specified by moisture content, defect tolerances, and test weight parameters. These inputs serve as foundational raw materials for industrial food production, requiring standardization to meet batch consistency in manufacturing environments. Grains and pulses dominate procurement volumes among product type segments, though seeds and nuts command premium positioning in health-oriented applications. Powder and flake forms capture expanding share from whole formats as food manufacturers pursue hydration efficiency and reduced handling costs in bakery and confectionery operations. Snacks and baked goods applications absorb the largest share of bulk grain flows, while sauces and confectionery segments concentrate demand for specialized milled fractions and modified starches.
The FDA enforces Food Safety Modernization Act rules governing preventive controls for bulk ingredient handling and storage facilities across the United States. The EU Green Deal and F-Gas Regulation impose sustainability traceability requirements on imported agricultural commodities entering European processing channels. India's FSSAI mandates micronutrient fortification standards for wheat flour and edible oils distributed through public nutrition programs. Stakeholders must monitor evolving contaminant thresholds and origin certification protocols that determine market access eligibility for bulk ingredient shipments.
Market Dynamics
Fortification mandates and clean-label reformulation are forcing bulk ingredient buyers to requalify suppliers against stricter compositional and traceability specifications.
Growth Catalysts
- FSSAI fortification mandates:India's mandatory micronutrient standards for wheat flour and edible oils are expanding procurement volumes from certified bulk grain handlers.
- Clean-label formulation:European snack and bakery manufacturers are reformulating with single-source, minimally processed grains to meet EU Green Deal traceability requirements.
- Soybean processing clusters:Brazil's interior agricultural states are concentrating crushing capacity to serve both domestic food manufacturers and export channels.
Market Restraints
- Input cost volatility:Fertilizer and energy price swings transmit directly into grain and oilseed production economics, compressing processor margins.
- Supply concentration risk:Black Sea corridor disruptions have exposed dependency on concentrated origination points for wheat and sunflower oil.
- Regulatory friction:REACH and F-Gas Regulation compliance costs are rising for European importers sourcing outside the EU.
Strategic Opportunities
- Pulse protein extraction:Lentil and chickpea fractionation technology is opening plant-based meat and dairy alternative applications.
- Direct-to-manufacturer channels:Food processors are bypassing traditional merchant aggregators to contract directly with cooperative elevators.
- Carbon certification premiums:EU Green Deal border adjustment mechanisms are creating price premiums for verifiably low-carbon grain shipments.
Industry Challenges
- Moisture management expertise:Bulk handlers face acute shortages of grain conditioning specialists capable of maintaining specification tolerances across climate zones.
- Legacy system integration:Traceability platforms required by FDA Food Safety Modernization Act rules must interface with decades-old elevator management software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Food Ingredients Market |
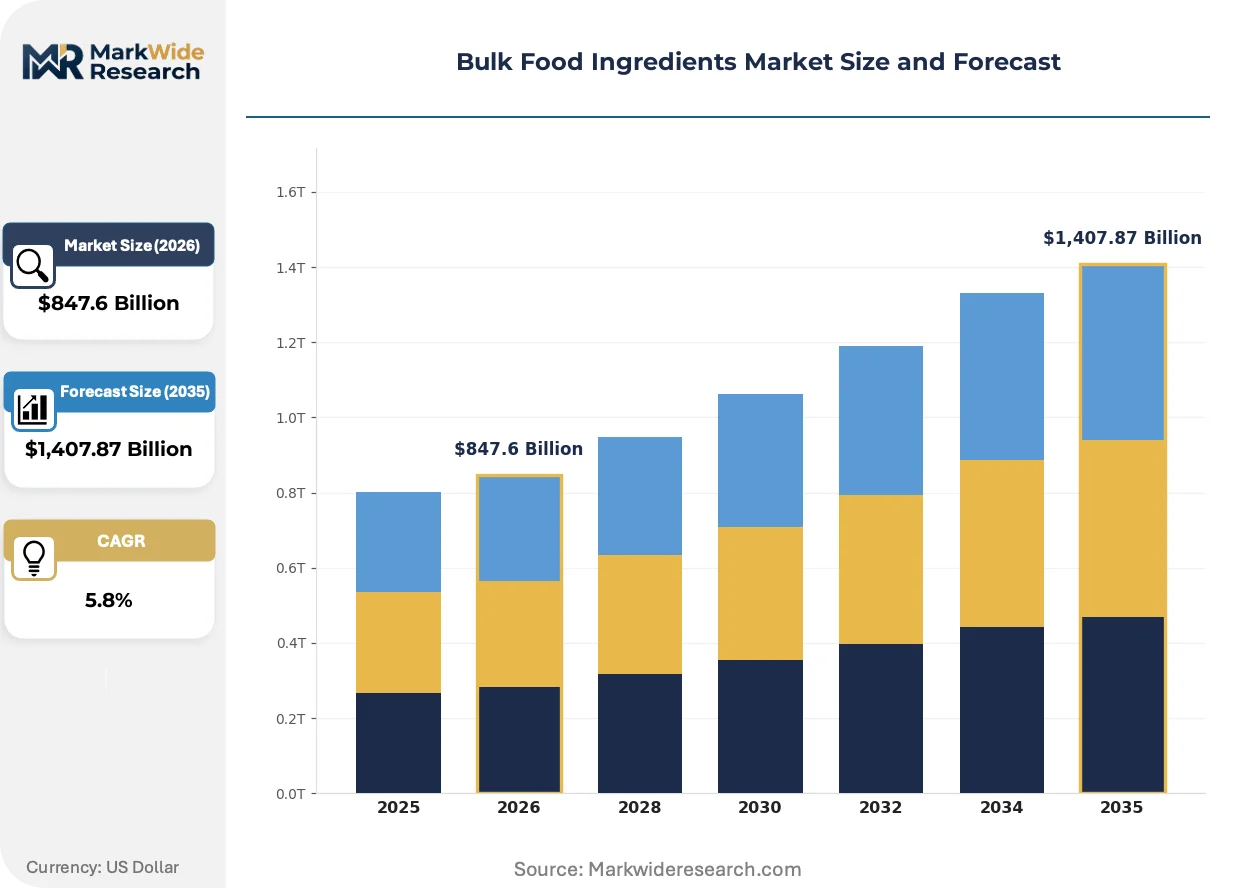
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $1,407.87 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grains, Pulses, Nuts, Seeds End User: Food Manufacturers, Catering Services, Retailers, Bakeries Form: Whole, Powder, Flakes, Granules Application: Snacks, Baked Goods, Sauces, Confectionery |
| Companies Covered | Olam Group, Bunge Limited, Cargill, Incorporated, International Flavors & Fragrances Inc., Associated British Foods plc, Archer Daniels Midland Company, Ingredion Incorporated, DuPont de Nemours, Inc., Tate & Lyle PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Food Ingredients Market Emerging Trajectories
Digital origination platforms and precision agriculture data streams are compressing information asymmetries between bulk ingredient buyers and farm-level suppliers.
Near-infrared spectroscopy is expanding into rapid compositional testing at elevator intake points. Large flour millers are deploying handheld units to verify protein and moisture content before unloading, cutting laboratory turnaround from hours to minutes. This compression of quality verification timelines is expanding into contract specifications that bind price to real-time assay results.
The EU Green Deal and F-Gas Regulation are imposing sustainability traceability requirements on imported agricultural commodities entering European processing channels. Food manufacturers must now document carbon intensity and land-use change status for soybean and palm oil shipments. Bakery and confectionery segments are responding by shifting procurement toward certified sustainable origination programs with third-party audit chains.
Buyer concentration among multinational food manufacturers is compressing supplier rosters and extending contract durations. Snack and cereal producers are reducing their approved vendor lists from dozens to single-digit strategic partnerships. This consolidation is most visible in North American wheat procurement, where three processors now account for the majority of forward-contracted hard red winter volumes.
Bulk Food Ingredients Market Segmentation
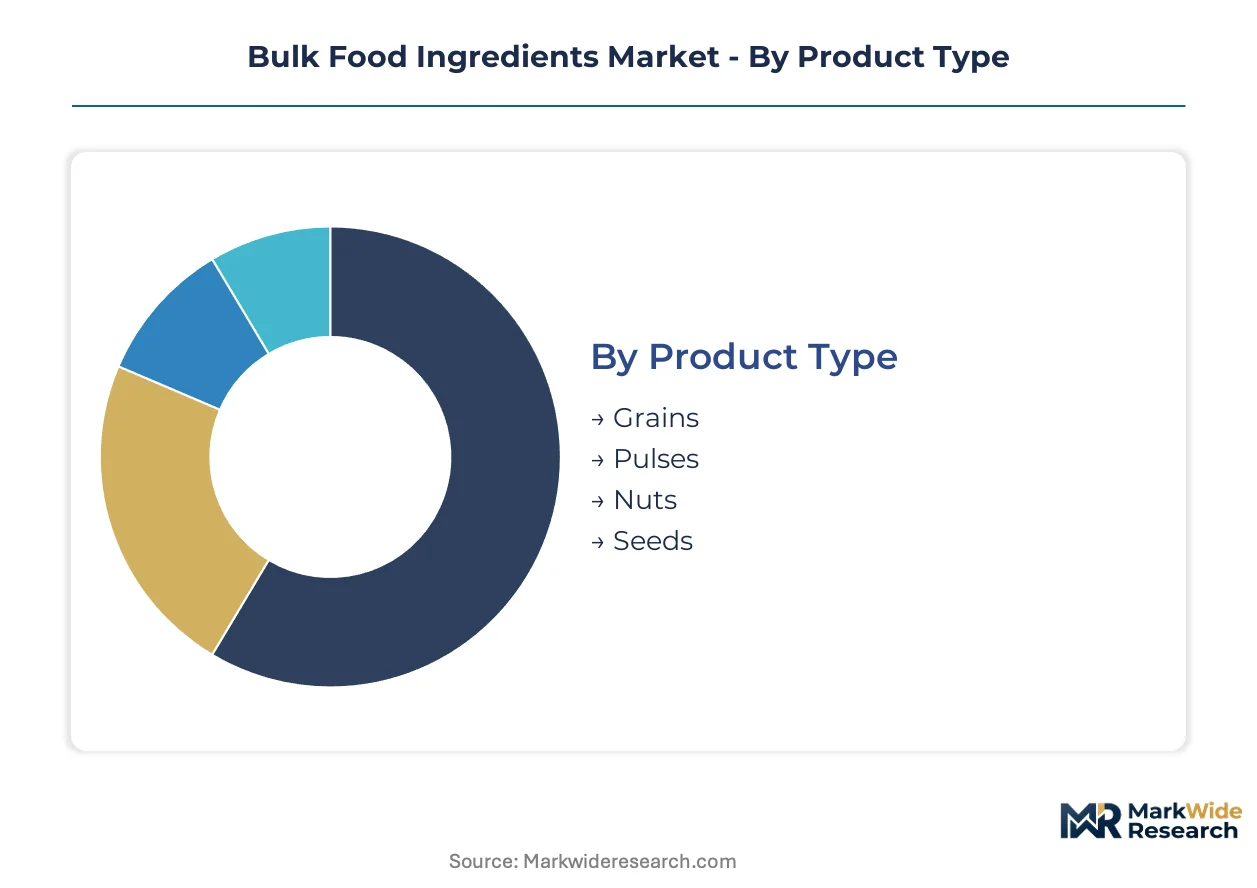
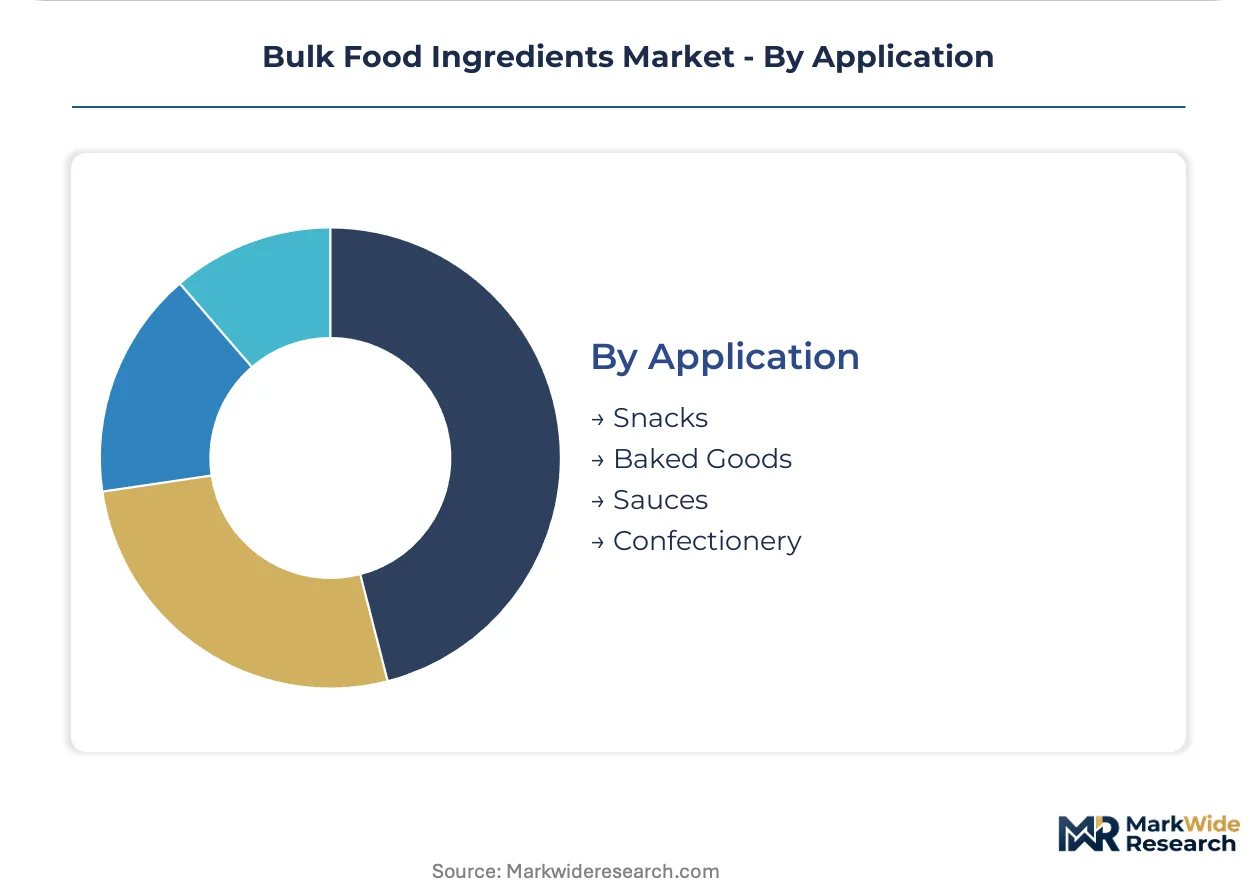
Bulk food ingredient procurement varies sharply by buyer sophistication, volume scale, and specification tolerance. Manufacturers segment their supplier portfolios across product type, processing form, and end-use application to balance cost efficiency against batch consistency requirements.
Product Type:
Grain handlers differentiate buyers by moisture specification stringency and defect tolerance thresholds.
- Grains:Wheat, corn, rice, and barley constitute the procurement backbone for industrial milling operations. Snack and cereal manufacturers in the United States contract hard red winter wheat through cooperative elevators to secure protein content above 12% for tortilla flour production.
- Pulses:Lentils, chickpeas, and dried peas deliver protein concentrates for plant-based formulation. Fractionation investments in Saskatchewan and North Dakota are expanding dehulled split capacity to serve European clean-label meat alternatives.
- Nuts:Almonds, walnuts, and cashews trade on grade standards for kernel size and aflatoxin limits. California handlers dominate almond flows, while Vietnam and India compete on cashew processing labor costs.
- Seeds:Sunflower, sesame, and chia seeds supply oil crushing and health-oriented bakery inclusion markets. Black Sea corridor disruptions have rerouted sunflower oilseed demand toward Argentine and Romanian origination.
Volume sits with grains; growth tilts toward pulses.
End User:
Customer scale determines contract structure, with multinational manufacturers demanding multi-year supply agreements and traceability documentation.
- Food Manufacturers:Processed food conglomerates purchase wheat flour, modified starches, and oilseed meals in railcar quantities. FSSAI fortification mandates in India are forcing these buyers to requalify suppliers against micronutrient premix integration capabilities.
- Catering Services:Institutional foodservice operators procure parboiled rice and dehydrated legumes in foodservice packs. Contract duration rarely exceeds one season given menu volatility and storage space constraints.
- Retailers:Private-label grocery chains source bulk grains for in-house milling and packaging. EU Green Deal traceability requirements are pushing these buyers toward certified sustainable origination programs with blockchain documentation.
- Bakeries:Artisan and industrial bakeries specify flour by protein content and ash levels. Hard wheat premiums for high-gluten bread flour have widened against soft wheat pastry grades in North American spot markets.
Procurement scale concentrates among food manufacturers; sustainability certification premiums are climbing fastest among retailers.
Form:
Processing intensity correlates with handling efficiency and hydration speed in manufacturing environments.
- Whole:Unprocessed kernels and seeds retain longest shelf life but require extended soaking or cooking cycles. Traditional dal mills in India and Ethiopia continue processing whole lentils and chickpeas for regional consumption.
- Powder:Milled flours and protein isolates dissolve rapidly and reduce batch mixing times. Bakery and confectionery segments are shifting toward pre-hydrated powder systems to cut production line changeover intervals.
- Flakes:Rolled oats and extruded cereal bases offer intermediate reconstitution speed. Breakfast cereal manufacturers specify flake thickness to control bowl saturation rates and texture retention in milk.
- Granules:Agglomerated starches and textured vegetable proteins balance dispersibility with flow characteristics. Sauce manufacturers favor granule forms to prevent lumping during high-shear mixing operations.
Whole formats dominate procurement tonnage; powder and flake forms are expanding share in hydration-sensitive applications.
Application:
End-use specifications diverge on particle size distribution, moisture absorption curves, and thermal stability under processing stress.
- Snacks:Extruded and puffed products demand specific starch gelatinization temperatures for texture control. Corn and rice grit specifications for tortilla chip production include tight tolerances on pericarp removal to prevent browning during frying.
- Baked Goods:Bread, pastry, and cracker formulations require flour with predictable gluten development and enzyme activity. European clean-label reformulation is pushing bakers toward single-source heritage wheat varieties with documented provenance chains.
- Sauces:Viscosity builders and emulsion stabilizers specify modified starches and hydrocolloids. Tomato paste and soy sauce manufacturers source bulk sugar and salt for fermentation substrate consistency.
- Confectionery:Chocolate and sugar confectionery applications prioritize fat bloom resistance and crystallization control. Cocoa butter alternatives from shea and palm fractions trade on melting point profiles and tempering behavior.
Snack and baked goods absorb the largest grain flows; confectionery commands the highest specification premiums per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's Cerrado soybean belt and India's Indo-Gangetic wheat belt anchor the geography of bulk food ingredient flows, with processing clusters concentrating near origination points to minimize freight drag on margin.
United States
Hard red winter wheat contracts from Kansas and Oklahoma elevators supply tortilla flour manufacturers with protein specifications above 12%. FDA Food Safety Modernization Act rules govern preventive controls at grain handling facilities across the Midwest. Omaha and Minneapolis anchor North American grain trading with integrated elevator networks feeding rail export corridors.
Brazil
Soybean crushing demand concentrates in Mato Grosso and Goiás states to serve domestic food oil manufacturers and export channels. ANVISA enforces contaminant thresholds on agricultural commodity shipments entering processing facilities. Santos port terminals handle the majority of soybean meal and oil exports to European and Asian destinations.
India
FSSAI fortification mandates for wheat flour and edible oils are expanding procurement volumes from certified bulk grain handlers in Punjab and Haryana. The FSSAI micronutrient standards apply to commodities distributed through public nutrition programs. Mumbai and Ahmedabad house major milling operations reformulating to meet premix integration requirements.
Germany
Clean-label reformulation among snack and bakery manufacturers is reshaping ingredient specifications toward single-source heritage wheat varieties. REACH and EU Green Deal traceability requirements impose sustainability documentation burdens on imported grain shipments. Hamburg port facilities serve as the primary entry point for oilseeds and specialty grains from Black Sea and South American origins.
China
Soybean import demand from crushing facilities in Shandong and Jiangsu provinces remains concentrated despite domestic production expansion. SAMR and GB standards regulate maximum residue limits and quality specifications for bulk agricultural commodities. Dalian commodity exchange futures anchor regional price discovery for soybean and corn flows.
Bulk Food Ingredients Market Vendor Landscape
Global majors compete with regional champions across origination networks and processing infrastructure, creating a tiered structure where scale advantages in logistics meet local knowledge in procurement. The market consolidates around integrated traders with elevator assets, specialized processors with fractionation capabilities, and diversified ingredient suppliers with formulation expertise. Strategic moves center on backward integration into origination assets and geographic expansion of crushing capacity.
Within the integrated trading tier, Cargill, Incorporated and Bunge Limited exemplify global scale with network density across multiple origination regions. Archer Daniels Midland Company anchors North American flows through inland elevator systems. Among diversified ingredient specialists, Associated British Foods plc and Tate & Lyle PLC occupy positions bridging bulk commodity supply with downstream formulation capabilities.
| Leading Market Players |
|---|
| Olam Group |
| Bunge Limited |
| Cargill, Incorporated |
| International Flavors & Fragrances Inc. |
| Associated British Foods plc |
| Archer Daniels Midland Company |
| Ingredion Incorporated |
| DuPont de Nemours, Inc. |
| Tate & Lyle PLC |
| Others |
Supply Flow & Price Mechanics
Chicago Board of Trade wheat futures cascade through cooperative elevator networks into three-tier pricing structures across premium, standard, and economy levels, with protein premiums widening against base grades as FSSAI fortification mandates force micronutrient premix bundling into contract specifications.
Pricing Analysis
Service bundling separates certified sustainable origination programs with blockchain traceability from unbundled spot market transactions lacking carbon certification documentation. Price differentiation hinges on fortification compliance tier and volume scale, with FSSAI-mandated premix integration commanding premiums over standard grades. Cost compression in economy tiers is intensifying because fertilizer and energy price volatility transmits directly into grain production economics. Small-scale bakeries exhibit highest price sensitivity, while multinational snack manufacturers absorb premiums for specification consistency.
Supply Chain Analysis
Ocean freight rates from Santos to Hamburg and rail tariffs from Mato Grosso to Santos terminals dictate margin allocation between Brazilian crushers and European food manufacturers. Supply concentrates in Brazil, India, and the United States, with Black Sea corridor disruptions rerouting sunflower seed flows toward Argentina and Romania. Raw material sourcing draws from fertilizer inputs, energy for drying and conditioning, and specialized premix formulations for fortification compliance. Single-source vulnerability persists in protein testing equipment and grain conditioning specialist labor pools. Distribution runs through integrated trader elevator networks feeding rail export corridors and direct-to-manufacturer contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bulk food ingredients market functions as a cost-of-compliance arena where India's FSSAI fortification mandates and the EU Green Deal traceability requirements erect barrier-to-entry moats favoring incumbents with certification infrastructure and documented supply chain audit capabilities.
For Market Incumbents: Hedge origination exposure by diversifying procurement across Brazil's Cerrado soybean belt and India's Indo-Gangetic wheat corridor to mitigate Black Sea supply disruption risk. Deepen backward integration into cooperative elevator assets in North American hard red winter wheat territories to secure protein specification consistency for tortilla flour contracts. Prioritize carbon certification investment to capture EU Green Deal border adjustment premiums before compliance deadlines tighten. For New Entrants and Emerging Players: Enter via direct-to-manufacturer contracting channels bypassing traditional merchant aggregators, targeting mid-scale regional bakeries in Germany and artisan millers in India's secondary cities seeking heritage wheat varieties with documented provenance. Pulse protein fractionation for plant-based meat alternatives represents the most penetrable white-space segment, with Saskatchewan and North Dakota processing capacity expansion creating supplier entry points. For Investors and Strategic Acquirers: The window for entry favors diversified ingredient specialists with formulation expertise bridging bulk commodity supply and downstream application development. Long-term viability rests on acquiring platforms with integrated traceability infrastructure capable of servicing both FDA Food Safety Modernization Act compliance and EU sustainability documentation requirements. Watch for inflection signals in carbon border adjustment mechanism implementation timelines affecting grain import economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Origination Assets | Cargill and Bunge leverage elevator networks to secure volume commitments across volatile harvest cycles in Brazil and North America. |
| Carbon Certification Program Deployment | EU Green Deal border adjustments create price premiums for verifiably low-carbon grain shipments entering Hamburg port facilities. |
| Pulse Protein Fractionation Capacity Expansion | Saskatchewan and North Dakota investments serve European clean-label meat alternative manufacturers demanding lentil and chickpea concentrates. |
| Direct-to-Manufacturer Channel Development | Food processors bypass merchant aggregators to contract with cooperative elevators for hard red winter wheat protein specifications. |
| Fortification Premix Integration Infrastructure | FSSAI-mandated micronutrient standards force milling operations in Mumbai and Ahmedabad to reformulate for public nutrition program compliance. |
Methodological Framework
Independent corroboration across grain elevator operators, procurement directors at multinational snack manufacturers, FSSAI compliance officers, and EU sustainability auditors underwrites the qualitative findings in this analysis. Primary interviews with plant managers at Brazilian crushing facilities, technical R&D directors at European bakery ingredient suppliers, and distribution channel partners in North American wheat territories combined with secondary validation from customs and trade data, SEC filings of integrated traders, and FSSAI regulatory notifications. Bottom-up volume modeling across product type, processing form, and end-use application segments triangulates against top-down macroeconomic indicators.
Comparable historical reference periods anchored the forecast window to pre-pandemic baseline volumes and post-disruption recovery trajectories across the analysis window. The analytical framework models segmentation dimensions including grain versus pulse versus nut product categories, whole versus powder versus flake processing forms, and snack versus baked goods versus confectionery applications. CAGRs were derived from trend extrapolation adjusted for regulatory mandate implementation schedules and sustainability certification adoption curves. Forecast inputs incorporated fertilizer price index movements and energy cost volatility transmission effects into grain production economics.
Revisions become necessary when Black Sea corridor stability shifts, FSSAI fortification mandate enforcement intensity changes, or EU carbon border adjustment mechanism timelines accelerate. Forecasts reflect assumptions about cooperative elevator network capacity expansion and precision agriculture data platform adoption rates among farm-level suppliers. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Cacao Extracts Market
Ingredients
Plant Sterols and Esters Market
Ingredients
Asia-Pacific Yeast Market
Ingredients
RTD/High Strength Premixes Market
Ingredients
Blackcurrant Concentrate Market
Ingredients
Vitamin B Complex Ingredients Market
Ingredients
North America Feed Yeast Market
Ingredients
Cocoa Market
Ingredients
Europe Vegetable Oil Market
Ingredients
Food Colors Market
Ingredients
Asia-Pacific Prebiotic Ingredients Market
Ingredients
North America Soybean Oil Market
Ingredients
Food Grade Hydrolyzed Casein Market
Ingredients
Protein Trends and Technologies Market
Ingredients
Glucuronolactone Market
Ingredients
Milk Ingredients Market