
 Dairy Concentrates Market | 2026-2036
Dairy Concentrates Market Size, Share, and Industry Trends Forecast 2026-2036
Dairy Concentrates Market Analytics
REACH compliance is consolidating the cost-of-entry calculus for European dairy concentrate suppliers, forcing smaller processors to invest in contaminant testing and supply chain traceability systems. Lactalis Ingredients leverages backward integration into milk collection networks across France to sustain margin control. Fonterra Co-operative Group anchors Oceania supply through its farmer-owned cooperative structure, while Arla Foods differentiates via farm-level sustainability certification programs that command premium positioning in retail channels.
Dairy concentrates denote protein-rich or fat-standardized fractions derived from milk or whey through ultrafiltration, evaporation, or spray-drying processes, typically achieving protein contents between 34% and 85% depending on intended application. These ingredients function primarily as functional binders, emulsifiers, and nutritional fortifiers in formulated foods and clinical nutrition products. Whey protein concentrates occupy the fastest-expanding margin pool as sports nutrition and senior nutrition formulations drive volume. Milk protein concentrates retain structural dominance in cheese analog and yogurt applications where water-binding capacity determines finished product texture. Cream concentrates command specialized positions in premium bakery and confectionery segments where fat standardization replaces fresh dairy logistics.
FDA nutrition labeling requirements and USDA organic certification standards shape product formulation decisions and channel access for North American suppliers, while EFSA health claim authorizations determine which protein concentration levels qualify for functional food positioning in Europe. China's NMPA and GB standards govern import thresholds for dairy-derived ingredients, creating compliance bottlenecks that favor established exporters with in-country testing partnerships. Stakeholders must monitor evolving protein content thresholds in infant formula regulations and carbon intensity disclosure mandates, as these dual pressures will determine which processing configurations remain viable across major procurement regions.
Market Dynamics
EU Green Deal sustainability mandates are compressing margin structures across European dairy concentrate supply chains, forcing processors to reconfigure sourcing protocols and carbon accounting systems to maintain market access.
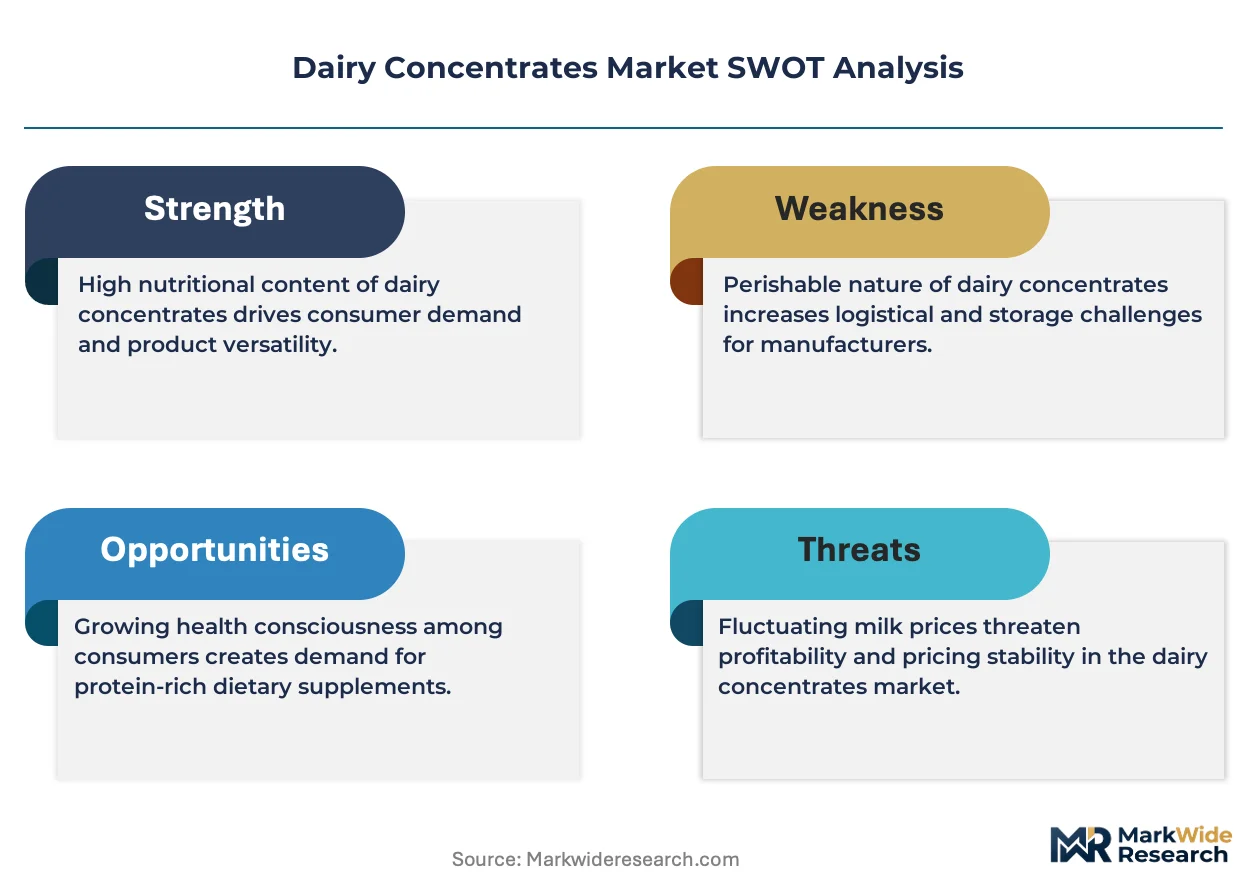
Growth Catalysts
- Protein-enriched diet prioritization:Consumer preference for sports nutrition and clinical nutrition formulations is pulling whey protein concentrates into expanded food manufacturing applications.
- REACH compliance consolidation:Stricter contaminant testing requirements in Europe are advantaging scaled suppliers with in-house traceability infrastructure over fragmented competitors.
- Ultrafiltration technology maturation:Advanced membrane separation processes are enabling higher protein concentration yields from whey streams, improving unit economics for processors.
Market Restraints
- Milk powder price volatility:Input cost swings in skim milk powder and whole milk powder squeeze margin predictability for concentrate blenders.
- Supply concentration in Oceania:Fonterra's cooperative dominance over New Zealand milk collection creates single-source risk for international buyers.
- Plant protein substitution:Pea and fava bean protein isolates are capturing share in sports nutrition formulations where sensory performance gaps have narrowed.
Strategic Opportunities
- Senior nutrition underpenetration:Clinical nutrition formulations for aging populations in Japan represent white space where whey protein concentrates can displace casein-dominant solutions.
- Farm-level sustainability certification:Arla Foods' carbon-reduction programs demonstrate premium positioning potential through verified environmental claims.
- Direct-to-manufacturer channel expansion:Food manufacturers are consolidating procurement relationships, bypassing traditional ingredient distributors for volume commitments.
Industry Challenges
- Membrane filtration engineering talent scarcity:Specialized process engineers for ultrafiltration and nanofiltration systems command premium compensation, constraining capacity expansion timelines.
- EFSA health claim substantiation delays:Protein concentration thresholds for functional food positioning require extensive clinical dossiers, extending time-to-market for new formulations.
- Legacy ERP integration with traceability platforms:Smaller processors face system architecture conflicts when layering blockchain or cloud-based supply chain tracking onto existing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dairy Concentrates Market |
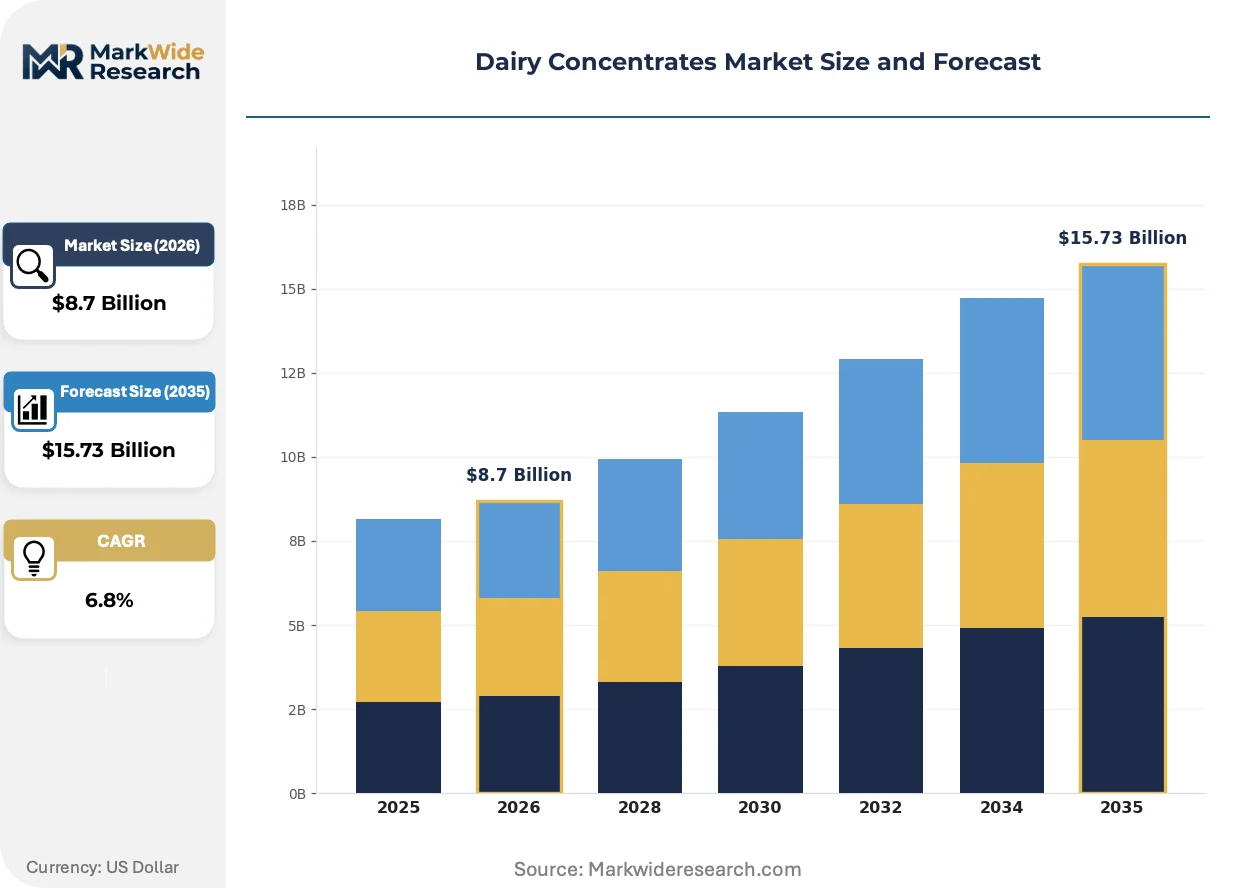
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk Protein Concentrates, Whey Protein Concentrates, Cream Concentrates, Lactose Concentrates Application: Dairy Products, Bakery Items, Snacks, Nutritional Supplements End User: Food Manufacturers, Beverage Producers, Retailers, Health Care Providers Distribution Channel: Direct Sales, Distributors, Online Retail, Wholesalers |
| Companies Covered | Lactalis Ingredients, FrieslandCampina Professional, Fonterra Co-operative Group, Arla Foods, Glanbia, Dairy Farmers of America, Grassland Dairy Products, California Dairies, Agropur Cooperative, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dairy Concentrates Market Evolving Landscape
Membrane filtration advances and sustainability verification protocols are restructuring competitive differentiation in dairy concentrates, shifting value capture toward processors with integrated carbon accounting and specialized protein fractionation capabilities.
Precision fermentation-derived dairy proteins are expanding into high-value concentrate applications, enabling manufacturers to produce whey protein isolates without cow agriculture. Sports nutrition brands in North America are piloting these ingredients for vegan-positioned product lines. This technology is expanding into premium segments where conventional supply constraints and methane emissions concerns create pricing headroom for bio-identical alternatives.
EFSA health claim authorization requirements are tightening substantiation standards for protein-based functional food positioning. Manufacturers must now demonstrate bioavailability equivalence through clinical trials to retain marketing claims. Senior nutrition and clinical nutrition segments face the steepest compliance burdens, with several pending dossiers stalled over peptide absorption methodology disputes.
Buyer consolidation among food manufacturers is compressing ingredient supplier margins through volume-based tender structures. Mid-sized dairy processors in Germany and France are responding by forming cooperative procurement alliances to defend pricing power. This pattern concentrates most visibly in cheese analog and yogurt applications where milk protein concentrate specifications have standardized across retail private label programs.
Dairy Concentrates Market Segmentation
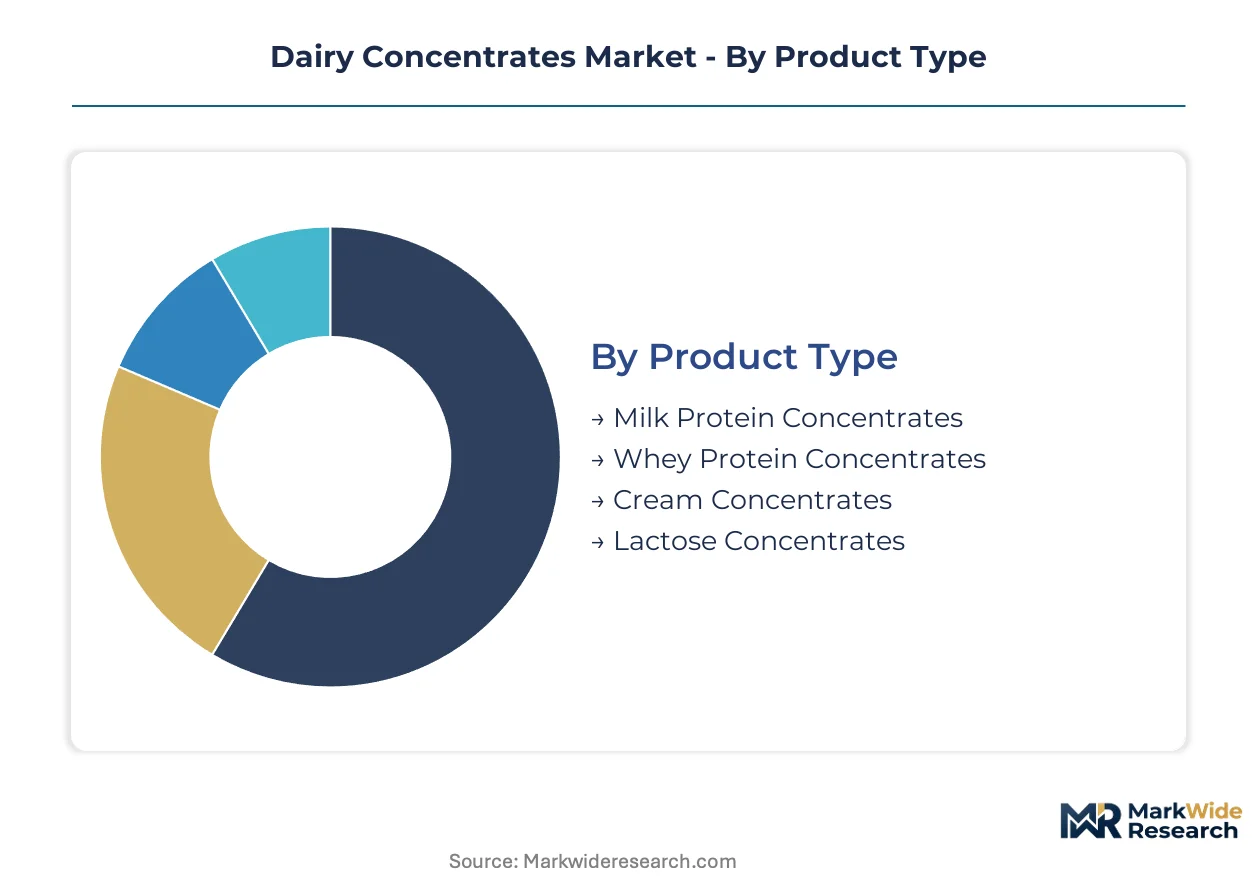
Dairy concentrate procurement decisions hinge on protein functionality requirements, processing compatibility, and supply chain reliability rather than commodity pricing alone. Manufacturers evaluate concentrate specifications against finished product performance targets, creating segment-specific sourcing patterns that reshape competitive dynamics.
Product Type:
Buyers prioritize protein concentration ratios and emulsification properties when selecting concentrate categories for specific formulation needs.
- Whey Protein Concentrates:These fractions achieve protein contents between 34% and 80% through ultrafiltration and diafiltration of cheese whey. Demand concentrates in Germany for sports nutrition powders and clinical nutrition beverages where rapid amino acid absorption drives formulation choices. Ultrafiltration technology maturation is improving yield economics for processors serving these high-value segments.
- Milk Protein Concentrates:Casein and whey protein combinations in ratios mirroring native milk structure deliver superior water-binding capacity in processed cheese and yogurt applications. Food manufacturers in France and the Netherlands scale procurement for cheese analog production where texture standardization replaces fresh dairy logistics.
- Cream Concentrates:Fat-standardized dairy fractions serve premium bakery and confectionery segments requiring consistent fat content without cold chain dependency.
- Lactose Concentrates:Purified milk sugar fractions function as crystallization controllers in confectionery and fermentation feedstocks for pharmaceutical applications.
Volume sits with milk protein concentrates for their structural dominance in cheese manufacturing; growth tilts toward whey protein concentrates.
Application:
End-use specifications determine protein concentration thresholds and functional property requirements across concentrate procurement.
- Nutritional Supplements:Protein-enriched diet prioritization is pulling whey concentrates into expanded applications. Sports nutrition formulations in North America and clinical nutrition products in Japan specify higher protein concentrations (70-80%) with enhanced bioavailability claims requiring EFSA substantiation.
- Dairy Products:Standardized milk protein concentrates enable consistent yogurt texture and processed cheese melt characteristics across private label retail programs.
- Bakery Items:Cream concentrates and milk proteins provide emulsification and browning control in premium pastry applications.
- Snacks:Savory extruded products incorporate whey concentrates for protein fortification and flavor enhancement in better-for-you positioning.
Revenue concentrates in nutritional supplements; formulation complexity peaks in dairy products where water-binding precision determines manufacturing yields.
End User:
Procurement scale and technical sophistication vary sharply across buyer categories, reshaping supplier relationship structures.
- Food Manufacturers:Direct-to-manufacturer channel expansion is consolidating procurement relationships around volume commitments. Large European bakery and confectionery groups bypass traditional distributors for whey and cream concentrate supply agreements.
- Beverage Producers:Ready-to-drink protein beverage specialists require instantized whey concentrates with specific dispersibility profiles for high-speed filling lines.
- Retailers:Private label program managers specify standardized milk protein concentrate grades across multiple supplier sources for cost control.
- Health Care Providers:Clinical nutrition procurement in hospital and long-term care settings demands batch-level traceability and contaminant testing documentation exceeding standard food-grade requirements.
Contract value peaks with food manufacturers; specification intensity defines health care provider relationships.
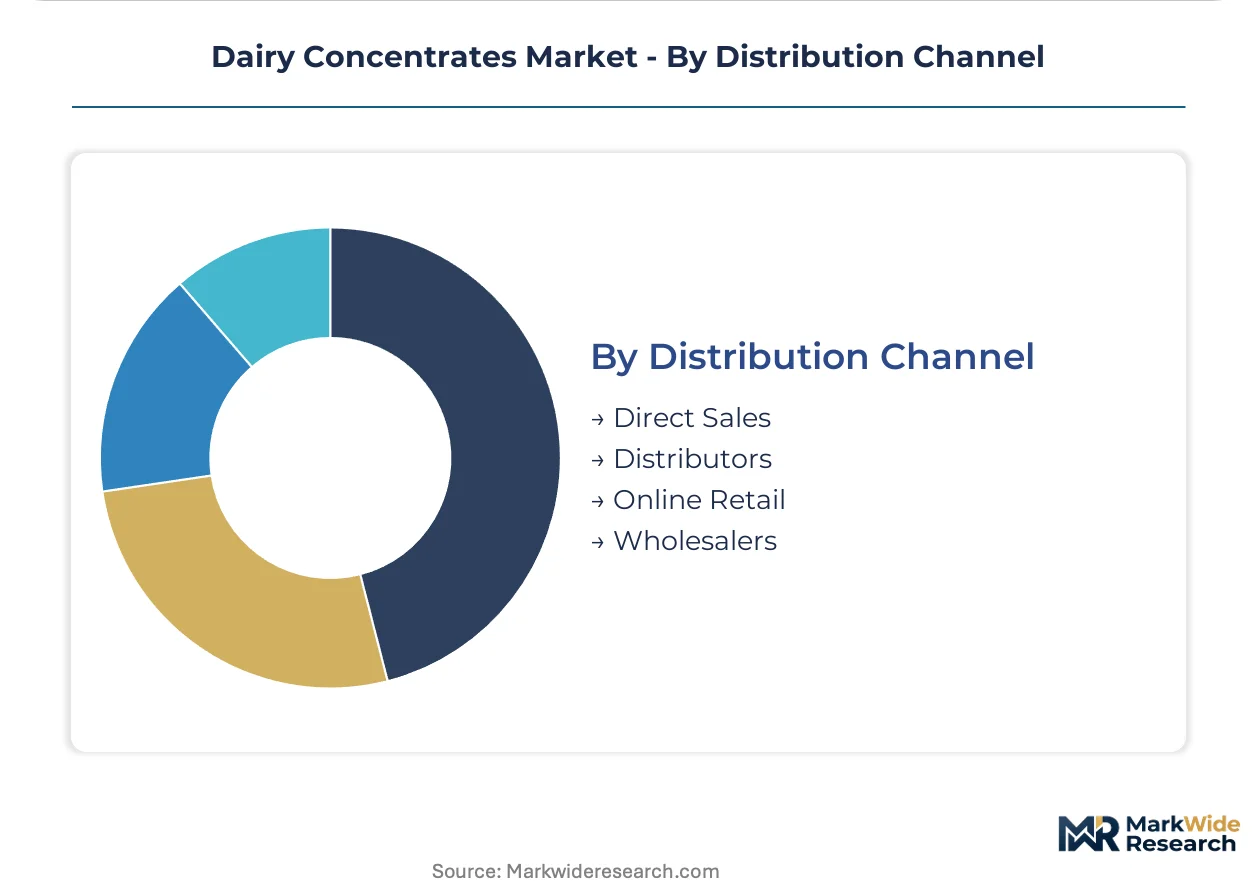
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic coverage needs across buyer segments.
- Direct Sales:Large food manufacturers negotiate direct supply agreements with Arla Foods and Lactalis Ingredients for milk protein concentrates, securing volume pricing and technical formulation support.
- Distributors:Regional ingredient distributors serve mid-sized bakery and snack manufacturers requiring smaller lot sizes and blended product portfolios.
- Online Retail:Specialty whey protein concentrates reach small sports nutrition startups and research institutions through B2B e-commerce platforms.
- Wholesalers:Traditional dairy ingredient wholesalers retain position in cream concentrate segments serving fragmented bakery and foodservice accounts.
Transaction volume flows through direct sales; channel diversification protects against buyer consolidation risk.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates and special economic corridors in Vietnam are accelerating dairy concentrate processing investments through tariff exemptions and streamlined customs protocols. These zones concentrate spray-drying and membrane filtration capacity serving re-export markets across the Middle East and Southeast Asia.
Germany
Sports nutrition manufacturers in Bavaria and North Rhine-Westphalia scale whey protein concentrate procurement for protein powder and ready-to-drink formulations. EU Green Deal sustainability mandates force processors to reconfigure carbon accounting systems and sourcing protocols. The Cologne-Düsseldorf industrial corridor hosts ultrafiltration facilities supplying clinical nutrition producers with high-concentration whey fractions.
United States
FDA nutrition labeling requirements and USDA organic certification standards shape formulation decisions for whey and milk protein concentrates across California and Wisconsin dairy processing clusters. The Wisconsin Cheese Belt generates substantial whey streams feeding concentrate production for sports nutrition brands. Chicago-area food manufacturers consolidate direct procurement relationships bypassing traditional distributors.
China
NMPA and GB standards govern import thresholds for dairy-derived ingredients, creating compliance bottlenecks that favor established exporters with in-country testing partnerships. Yangtze River Delta food manufacturers expand whey concentrate usage in infant formula and senior nutrition products. Shanghai's free trade zone facilitates bonded warehousing for imported milk protein concentrates serving domestic dairy processors.
Netherlands
EFSA health claim authorizations determine protein concentration levels qualifying for functional food positioning across European markets. Rotterdam's port infrastructure anchors dairy ingredient re-export operations serving German and French food manufacturers. FrieslandCampina's farmer-owned cooperative structure sustains margin control through backward integration into milk collection networks.
New Zealand
Fonterra's cooperative dominance over national milk collection creates single-source supply risk for international buyers seeking whey protein concentrates. Canterbury Plains dairy farming supports spray-drying capacity serving Asian sports nutrition markets. Auckland-based technical service teams manage formulation support for Chinese and Japanese food manufacturers.
Dairy Concentrates Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Cooperative structures anchor Oceania and European supply through farmer-owned governance models. Three archetypes dominate: multinational dairy processors with backward integration into milk collection, regional specialists with membrane filtration expertise, and farmer-owned cooperatives leveraging collective bargaining power. Competitive moves concentrate on sustainability certification programs and direct-to-manufacturer channel expansion bypassing distributors.
Among farmer-owned cooperatives, Fonterra Co-operative Group and Arla Foods exemplify governance structures that sustain margin control through captive milk supply. Lactalis Ingredients occupies a position within the diversified processor tier, leveraging French milk collection networks. These three anchors demonstrate how ownership structure shapes competitive positioning across procurement reliability and sustainability verification capabilities.
| Leading Market Players |
|---|
| Lactalis Ingredients |
| FrieslandCampina Professional |
| Fonterra Co-operative Group |
| Arla Foods |
| Glanbia |
| Dairy Farmers of America |
| Grassland Dairy Products |
| California Dairies |
| Agropur Cooperative |
| Others |
Value Network & Pricing Analysis
Membrane filtration engineering talent scarcity in Germany and the Netherlands widens spreads between premium-certified whey protein concentrates and standard-grade alternatives, as specialized process engineers command compensation premiums that processors pass through to buyers seeking rapid lead times for clinical nutrition formulations.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with food manufacturers paying markups for expedited whey protein concentrate delivery to sports nutrition bottling lines while spot inventory of milk protein concentrates trades at discounts due to standardized specifications across private label programs. Three-tier pricing structure across premium, standard, and economy levels reflects EFSA health claim substantiation status and farm-level sustainability certification tiers. Pricing pressure stems from buyer consolidation among European bakery and confectionery groups negotiating volume-based tenders. Mid-sized processors exhibit highest price sensitivity, while clinical nutrition formulators prioritize bioavailability documentation over unit cost.
Supply Chain Analysis
Workforce availability constraints in Bavaria and North Rhine-Westphalia limit ultrafiltration capacity expansion timelines, forcing processors to source engineering talent from Rotterdam's technical universities at elevated compensation packages. Supply concentrates in New Zealand, Germany, and the Netherlands, with Fonterra's cooperative dominance creating single-source vulnerability for international whey concentrate buyers. Raw material dependencies include fresh milk streams from farmer-owned cooperatives, specialized membrane filtration equipment from Dutch and German suppliers, and energy inputs for spray-drying operations. Tariff exposure runs through China's NMPA import thresholds for dairy-derived ingredients. Distribution runs through direct sales agreements with large food manufacturers bypassing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration capacity bottlenecks prop pricing power for processors with installed ultrafiltration infrastructure, as engineering talent scarcity constrains competitor expansion timelines across the analysis window.
For Market Incumbents: Cement supply security through backward integration into milk collection networks in France and Germany, mirroring Lactalis Ingredients' captive sourcing model. Invest in farm-level carbon accounting systems to meet EU Green Deal sustainability mandates before compliance deadlines harden. Plant protein substitution in sports nutrition formulations represents the core threat requiring differentiated bioavailability claims.
For New Entrants and Emerging Players: Launch via direct-to-manufacturer channel partnerships targeting mid-sized German sports nutrition brands bypassing established distributor relationships. Senior nutrition underpenetration in Japan offers the most penetrable white space, where whey protein concentrates can displace casein-dominant clinical solutions. Precision fermentation-derived dairy proteins provide a go-to-market angle for vegan-positioned premium segments.
For Investors and Strategic Acquirers: Re-rating potential sits with regional membrane filtration specialists given ultrafiltration technology maturation and sustainability verification capability premiums. Five-to-ten-year viability favors processors with integrated carbon accounting and traceability infrastructure over commodity blenders. Watch EFSA health claim authorization timelines as the signal for functional food positioning inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Milk Collection | Fonterra and Arla demonstrate margin control through farmer-owned cooperative structures. |
| Membrane Filtration Capacity Expansion | German ultrafiltration facilities in Cologne-Düsseldorf corridor serve clinical nutrition producers. |
| Farm-Level Sustainability Certification | Arla Foods' carbon-reduction programs command premium positioning in retail channels. |
| Direct-to-Manufacturer Channel Development | Chicago-area food manufacturers consolidate procurement relationships bypassing distributors. |
| Precision Fermentation Technology Adoption | Sports nutrition brands in North America pilot bio-identical whey proteins for vegan lines. |
Research Methodology
Independent corroboration across membrane filtration equipment suppliers, dairy processor procurement leads, and sports nutrition formulation directors underwrites the qualitative findings. Primary interviews with ultrafiltration process engineers, clinical nutrition product managers, and retail private label buyers combined with secondary validation from EFSA health claim dossiers, EU Green Deal implementation reports, and customs trade data. Bottom-up capacity assessments triangulate against top-down demand modeling from food manufacturer procurement disclosures.
Rate-of-change decomposition separates volume growth from protein concentration yield improvements across the projection horizon. Segmentation dimensions modeled include product type, application, end user, and distribution channel, with regional regulatory clusters and sustainability certification tiers as cross-cutting variables. CAGRs derive from processor capacity expansion timelines and buyer consolidation patterns. Forecast inputs incorporate membrane filtration technology maturation curves and EFSA substantiation pipeline status.
EFSA health claim authorization delays, plant protein substitution acceleration, and EU Green Deal compliance cost escalation are the dominant revision risks. Forecasts reflect assumptions regarding ultrafiltration yield improvements and cooperative procurement alliance formation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Global Goat Cheese Market
Dairy Products
Saudi Arabia Dairy Products Market
Dairy Products
India Milk Protein Market
Dairy Products
Cream Powder Market
Dairy Products
Low-Lactose Dairy Foods Market
Dairy Products
Global Reduced Fat Butter Market
Dairy Products
Germany Dairy Market
Dairy Products
Lactose Free Butter Market
Dairy Products
Probiotic Dairy Products Market
Dairy Products
Global Fortified Dairy Products Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
UHT Milk Market
Dairy Products
Evaporated Filled Milk Market
Dairy Products
Asia-Pacific Dairy Market
Dairy Products
US Yogurt and Probiotic Drink Market