
 Europe Dairy Market | 2026-2036
Europe Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Dairy Market Insights
Value-added processing revenue is reshaping margin distribution across the Europe dairy value chain, pulling returns away from raw milk collection toward branded cheese and functional yogurt production. Groupe Lactalis leverages its vertically integrated cheese operations across France and Italy to control regional supply. Danone S.A. specializes in probiotic and plant-dairy hybrid R&D, sustaining innovation pipelines in fermented categories. FrieslandCampina N.V. dominates ingredient supply to food manufacturers, extending its reach into specialized dairy proteins for bakery and nutrition applications.
Europe dairy encompasses milk-derived products processed through pasteurization, fermentation, churning, or enzymatic coagulation, with composition parameters such as minimum fat content and protein standards governed by EU marketing standards for milk and milk products. Cheese commands the largest product-type value pool due to aging premiums and protected-origin designations, while yogurt segments attract fastest growth through functional positioning and single-serve convenience formats. Supermarkets anchor volume throughput, though online retail channels are gaining share in recurring household purchases of fresh milk and chilled desserts.
EFSA governs health claim substantiation for dairy products, while EU Farm to Fork targets pesticide reduction and sustainable packaging mandates that reshape farm-level practices and processor compliance costs. CE marking requirements for dairy processing equipment and REACH chemical standards for cleaning agents add layered regulatory obligations across production facilities. Stakeholders must monitor evolving EU Green Deal carbon accounting rules and EUDR deforestation due diligence requirements that will soon extend to cattle feed sourcing transparency.
Market Dynamics
EFSA nutritional labeling mandates and the EU Farm to Fork Strategy are compressing reformulation timelines across European dairy processors, forcing simultaneous investment in reduced-fat lines and sustainable packaging transitions while raw milk costs fluctuate.
Growth Catalysts
- Protected Designation of Origin certification:France's Normandy and Brittany clusters command sustained buyer premiums through AOP status, concentrating high-margin cheese production in these heritage zones.
- Foodservice channel expansion:German, French, and Italian operators are scaling dairy procurement for prepared meals and artisan bakery applications, pulling volume through specialized distribution.
- Clean-label reformulation:EU marketing standards for milk products are accelerating ingredient simplification investments, with processors removing artificial stabilizers to meet retailer shelf requirements.
Market Restraints
- Feed cost volatility:Cattle feed input prices swing with grain and soy markets, compressing farmgate margins and forcing processors to absorb or pass through cost spikes.
- Supply concentration in Normandy:Premium cheese production clusters heavily in northern France, creating geographic vulnerability to climate disruption and logistics bottlenecks.
- Plant-based substitution:Oat and almond milk alternatives are capturing shelf space in German and Dutch supermarkets, eroding fluid milk volume in key markets.
Strategic Opportunities
- Eastern European underpenetration:Poland and Romania show low per-capita functional yogurt consumption, offering white space for probiotic product launches.
- Specialized dairy proteins:Bakery and sports nutrition manufacturers are demanding isolate and concentrate ingredients, opening ingredient supply contracts beyond commodity powders.
- EUDR deforestation due diligence:Upcoming cattle feed sourcing transparency rules will reward early compliance investments with preferred supplier status to major retailers.
Industry Challenges
- Fermentation science talent scarcity:Cultured product lines require microbiologists and process engineers that dairy regions struggle to retain against pharma and biotech competitors.
- Legacy equipment retrofit costs:CE-marked processing machinery from prior decades lacks data connectivity for carbon accounting compliance, forcing capital-intensive upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Dairy Market |
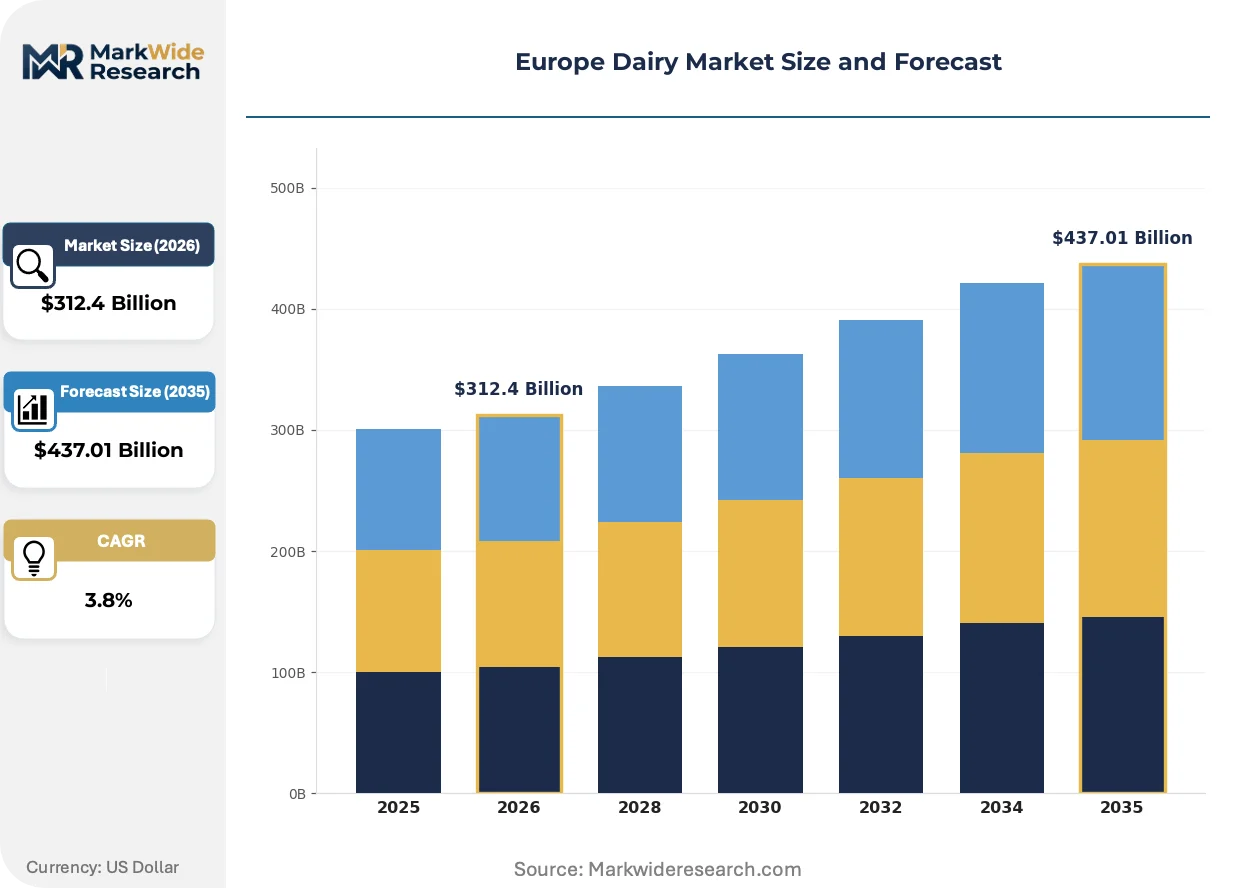
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $437.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cheese, Milk, Yogurt, Butter Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Specialty Stores End User: Households, Foodservice, Food Manufacturers, Bakeries Packaging Type: Cartons, Bottles, Sachets, Tetra Paks |
| Companies Covered | Groupe Lactalis, Arla Foods amba, Danone S.A., FrieslandCampina N.V., Nestlé S.A., Müller Group, DMK Deutsches Milchkontor GmbH, Sodiaal International SA, Zott SE & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Dairy Market Trends and Innovations
Precision fermentation and enzymatic processing are disrupting traditional coagulation methods, while regulatory pressure on health claims and carbon transparency rewrites product development priorities across the value chain.
Precision fermentation for dairy proteins is rendering obsolete conventional whey and casein extraction from raw milk. Specialized ingredient manufacturers in the Netherlands and Denmark are scaling recombinant protein production for bakery and nutrition applications. This biotechnology is compressing the farm-to-ingredient supply chain into single-site bioreactor operations.
EFSA health claim substantiation requirements are tightening evidentiary standards for probiotic and functional positioning. Dairy marketers must now fund clinical trials to retain immunity and digestive wellness messaging on yogurt packaging. German and French brands are diverting R&D budgets toward EFSA-compliant study designs.
Single-serve convenience formats are displacing bulk fresh milk purchases in urban households. French and Italian consumers are gravitating toward portion-controlled drinking yogurts and chilled desserts through convenience store channels. This behavioral shift is fragmenting volume across smaller pack sizes with higher per-liter price realization.
Europe Dairy Market Segmentation
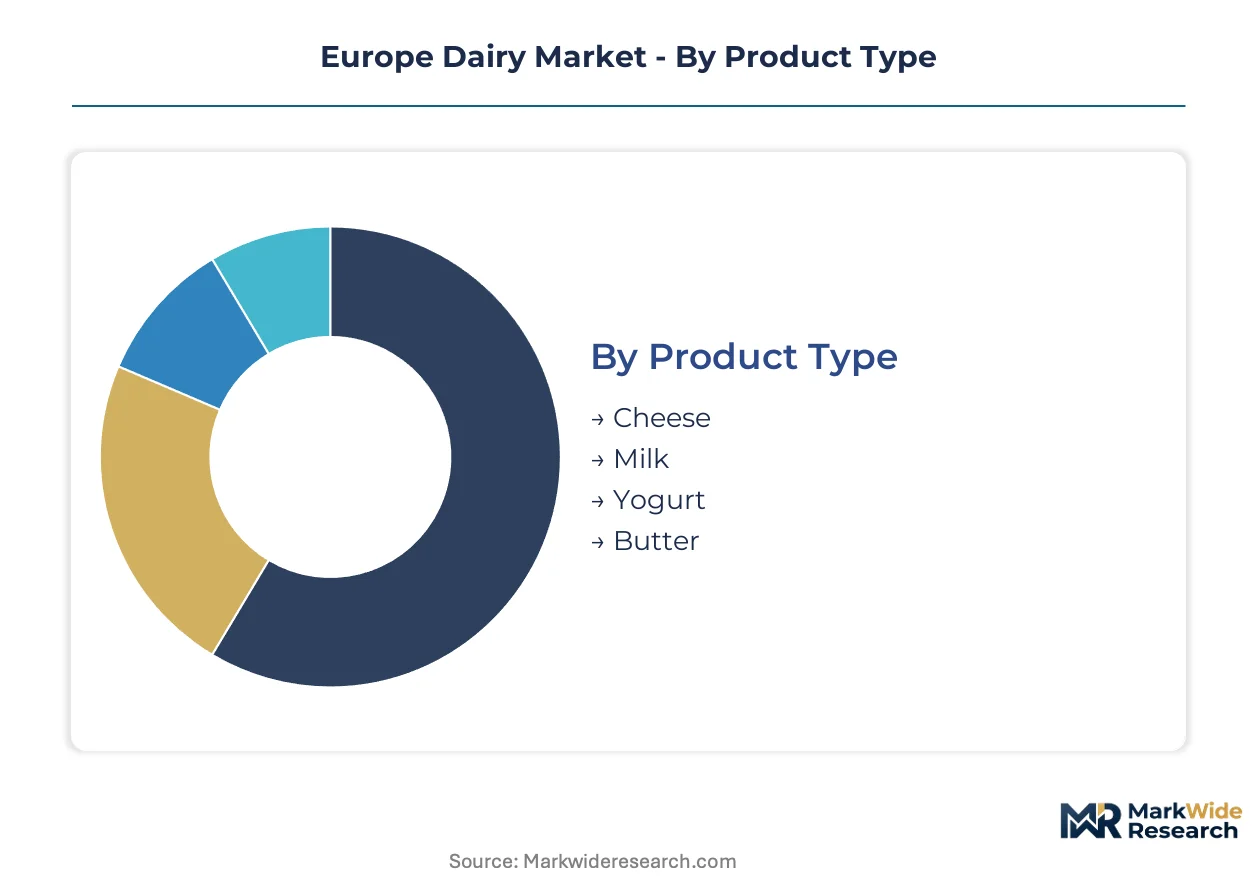
Segmentation in Europe dairy reveals how distinct buyer requirements reshape production priorities. EFSA labeling mandates and Farm to Fork compliance costs fragment processor strategies across product formats and channel specifications.
Product Type:
After-sales intensity varies sharply across dairy categories, with aged cheese requiring inventory aging management and functional yogurt demanding cold-chain service support.
- Cheese:AOP-certified wheels from Normandy and Brittany command sustained premiums through controlled aging protocols. German and Italian foodservice operators drive bulk procurement for prepared meal applications, though climate disruption risks concentrate supply vulnerability in northern France.
- Milk:Fluid milk faces eroding volume in German and Dutch retail as plant-based alternatives capture shelf space. Processors are diverting raw milk toward ingredient production to escape commodity margin compression.
- Yogurt:Probiotic lines attract R&D investment for EFSA-compliant health claims, with single-serve formats gaining urban convenience channel traction.
- Butter:Artisan bakery demand in France and Italy sustains cultured butter premiums.
By volume, milk leads. By expansion trajectory, yogurt is climbing fastest.
Distribution Channel:
Channel economics stratify around cold-chain investment requirements and buyer concentration patterns.
- Supermarkets:Anchor throughput for fresh milk and chilled desserts across French and German retail networks. Volume concentration forces processors to absorb listing fees and promotional funding.
- Online Retail:Recurring household subscriptions for fresh milk are gaining share in urban French markets, though last-mile cold-chain costs erode margin.
- Convenience Stores:Single-serve yogurt and drinking formats target Italian urban commuters.
- Specialty Stores:AOP cheese and artisan butter command direct-to-consumer premiums.
Supermarkets dominate current volume. Online retail is expanding most quickly.
End User:
End-user specifications fragment production runs between bulk commodity and precision-formulated ingredient grades.
- Households:Urban French and Italian consumers are shifting toward portion-controlled formats through convenience channels.
- Foodservice:German, French, and Italian operators scale dairy procurement for prepared meals and artisan bakery applications.
- Food Manufacturers:Specialized dairy proteins for sports nutrition and bakery applications attract ingredient supply contracts.
- Bakeries:Cultured butter and high-fat creams sustain regional processor relationships.
Foodservice leads by value concentration. Food manufacturers are gaining share fastest.
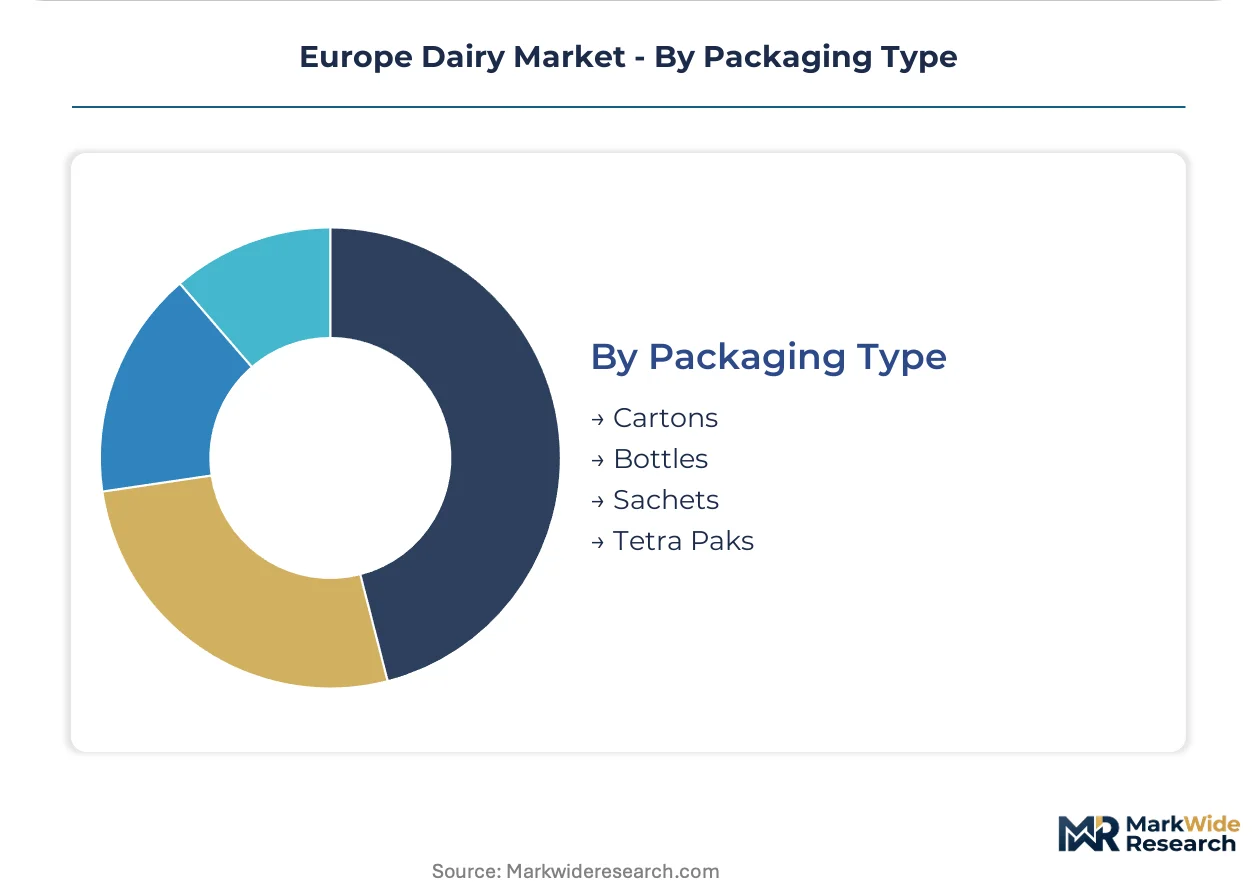
Packaging Type:
Packaging selection balances shelf-life extension against EU Green Deal sustainable packaging mandates.
- Cartons:Recyclable paperboard dominates fresh milk in German and French retail, though plastic laminate layers complicate circularity claims.
- Bottles:PET and HDPE formats serve drinking yogurt and flavored milk convenience segments.
- Sachets:Powdered dairy ingredients for food manufacturing use multi-layer barrier films.
- Tetra Paks:Aseptic cartons extend ambient yogurt shelf life for Eastern European distribution.
Cartons lead by environmental positioning compliance. Bottles are climbing fastest in convenience channel penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
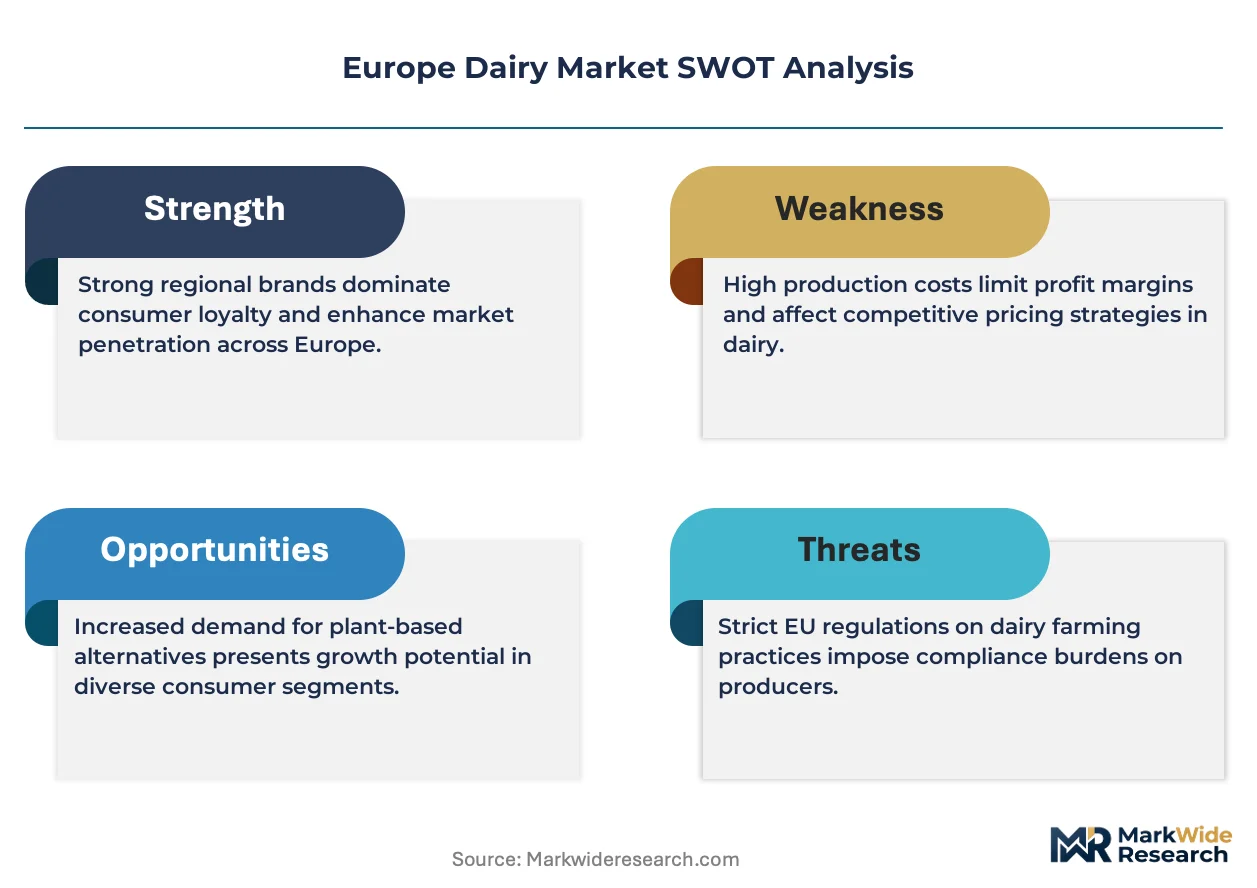
French households concentrate dairy expenditure on AOP-certified cheese and artisan butter, while German consumers divert fluid milk budgets toward oat and almond alternatives, and Italian foodservice channels pull bulk volumes for prepared meal production.
Germany
Plant-based substitution erodes fluid milk volumes in Berlin and Hamburg retail networks, though DMK Deutsches Milchkontor GmbH maintains processing scale in Lower Saxony. The country's national food regulator enforces strict labeling for dairy alternatives, preserving shelf space distinctions. Bavarian dairy cooperatives redirect raw milk toward specialized protein ingredients for bakery applications.
France
Normandy and Brittany clusters command sustained buyer premiums through AOP certification, concentrating high-margin cheese production in heritage zones. EFSA nutritional labeling requirements accelerate reformulation investments in reduced-fat lines. Parisian convenience channels drive single-serve yogurt penetration among urban commuters seeking portion-controlled formats.
Italy
Artisan bakery demand in Milan and Rome sustains cultured butter premiums, while foodservice operators scale procurement for prepared meal applications. The country's national agricultural ministry enforces protected designation protocols for regional cheese varieties. Emilia-Romagna processors leverage aging infrastructure to supply German and French wholesale channels.
Netherlands
FrieslandCampina N.V. anchors specialized dairy protein supply to food manufacturers across Rotterdam and Utrecht industrial corridors. REACH chemical standards for cleaning agents reshape processor compliance costs at production facilities. Dutch precision fermentation startups in the Amsterdam cluster pioneer recombinant protein production for bakery and nutrition applications.
Poland
Low per-capita functional yogurt consumption creates white space for probiotic product launches in Warsaw and Kraków retail networks. The country's national food safety authority aligns with EU Farm to Fork pesticide reduction targets for farm-level practices. Masovian dairy processors expand cold-chain distribution capacity to capture Eastern European demand growth.
Europe Dairy Market Competitive Landscape
Capability concentration sits with heritage AOP-certified producers; scale advantage sits with pan-European cooperatives and multinational processors. The market structures around three tiers: vertically integrated cheese specialists controlling regional supply, probiotic and functional yogurt innovators sustaining R&D pipelines, and ingredient-scale operators dominating specialized protein supply to food manufacturers. Dominant competitive moves include backward integration into captive milk supply and portfolio diversification across plant-dairy hybrid lines.
Within the heritage-producer tier, Groupe Lactalis and Sodiaal International SA exemplify vertically integrated operations anchored in French dairy clusters. Among cooperative-scale processors, Arla Foods amba occupies a position representing pan-Nordic supply consolidation. Danone S.A. sits within the innovation-driven tier, exemplifying investment in fermented category development. These three names anchor the competitive structure without exhausting the field.
| Leading Market Players |
|---|
| Groupe Lactalis |
| Arla Foods amba |
| Danone S.A. |
| FrieslandCampina N.V. |
| Nestlé S.A. |
| Müller Group |
| DMK Deutsches Milchkontor GmbH |
| Sodiaal International SA |
| Zott SE & Co. KG |
| Others |
Pricing and Supply Chain Analysis
Normandy and Brittany dairy clusters anchor European cheese pricing power through AOP-certified aging protocols that command sustained buyer premiums across German and Italian wholesale channels. Raw milk cost volatility in these heritage zones compresses processor margins while reinforcing geographic concentration in premium production.
Pricing Analysis
Long-term offtake contracts dominate bulk cheese procurement between French AOP producers and German foodservice distributors, while spot markets govern fluid milk trading in Dutch retail networks. Three-tier pricing structure across AOP-certified, standard industrial, and private-label economy levels reflects certification grade and aging duration differentiation. Pricing pressure stems from plant-based milk alternatives eroding volume in Berlin and Hamburg supermarkets. Private-label retailers exhibit highest price sensitivity; artisan bakery channels show lowest.
Supply Chain Analysis
EU Green Deal carbon accounting rules and REACH chemical standards for cleaning agents restrict equipment and input flows into European dairy processing facilities. Geographic supply concentrates in France, Netherlands, and Germany for aged cheese, specialized proteins, and fluid milk respectively. Raw material dependencies center on Normandy pasture land, Danish starter cultures, and Ukrainian feed grains. Single-source vulnerability runs through concentrated AOP production in northern France. Distribution feeds through cooperative-owned cold-chain networks into supermarket and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe dairy operates as a regulatory-moat market where EFSA health claim substantiation and AOP certification protocols create entrenched switching costs for established processors. Network effects in cooperative supply structures reinforce incumbent positioning.
For Market Incumbents: Insulate AOP-certified production through captive pasture land acquisition in Normandy and Brittany, blocking emerging entrants from heritage zone access. Accelerate probiotic clinical trial investment ahead of tightening EFSA evidentiary standards. Prioritize backward integration into cattle feed sourcing to preempt EUDR deforestation compliance disruption. For New Entrants and Emerging Players: Poland and Romania functional yogurt markets offer white-space penetration opportunity through probiotic product launches targeting low per-capita consumption gaps. Emilia-Romagna aging infrastructure partnerships provide Italian market entry without capital-heavy facility construction. Lead with convenience channel single-serve formats to bypass supermarket listing fee barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision fermentation specialists with recombinant protein platforms over conventional whey extraction operations. Five-to-ten year viability hinges on bioreactor scale-up execution and bakery ingredient contract capture. Watch for EUDR feed sourcing transparency compliance deadlines as inflection indicator for preferred supplier status allocation.| Strategic Initiative | Industry Significance |
|---|---|
| AOP Certification Investment | Secures protected-origin status for Normandy cheese aging operations against industrial competitors. |
| Precision Fermentation Scale-Up | Enables Dutch bioreactor facilities to supply recombinant dairy proteins for bakery applications. |
| EUDR Compliance Integration | Positions processors for preferred supplier status under upcoming cattle feed transparency mandates. |
| Probiotic Clinical Trial Funding | Preserves EFSA-compliant immunity messaging on German and French yogurt packaging. |
| Convenience Channel Expansion | Captures Parisian urban commuter demand through portion-controlled drinking yogurt formats. |
Research Methodology
The analysis maps cheese aging protocols, probiotic fermentation science, and specialized protein ingredient streams, each validated through cooperative supply managers, foodservice procurement directors, and retail category buyers. Primary interviews with AOP-certified producers, Dutch precision fermentation engineers, and German supermarket buyers combined with secondary validation through EFSA health claim registers, EU Farm to Fork policy documents, and customs trade data. Bottom-up volume modeling and top-down value triangulation anchored projections.
Assumptions held EFSA labeling mandates and EU Green Deal carbon accounting rules fixed across the modeling period, while feed cost volatility and plant-based substitution rates varied. Segmentation dimensions included product type, distribution channel, end-user specification, and packaging format. CAGRs derived from historical volume trajectories and elasticity-adjusted demand curves. Industry-specific inputs incorporated AOP aging duration premiums and cold-chain logistics cost structures.
Practitioners should monitor EUDR deforestation due diligence implementation timelines and precision fermentation scale-up announcements for early signals of supply chain restructuring. Forecasts reflect these documented assumptions. Material shifts in EFSA health claim substantiation requirements or EU Farm to Fork pesticide reduction enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
India Dairy Market
Dairy Products
Lactose Free Probiotic Yogurt Market
Dairy Products
Natural Cheese Market
Dairy Products
Global Butter Market
Dairy Products
United Kingdom Whey Protein Market
Dairy Products
Cheese Shreds Market
Dairy Products
GCC UHT Milk Market
Dairy Products
A2 Fresh Milk Market
Dairy Products
GCC Fresh Milk Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Cheese Crumbles Market
Dairy Products
Low Temperature Yogurt Market
Dairy Products
Argentina Whey Protein Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Concentrated Milk Fat Market