
 Italy Soy Protein Market | 2026-2036
Italy Soy Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Soy Protein Market Foresight
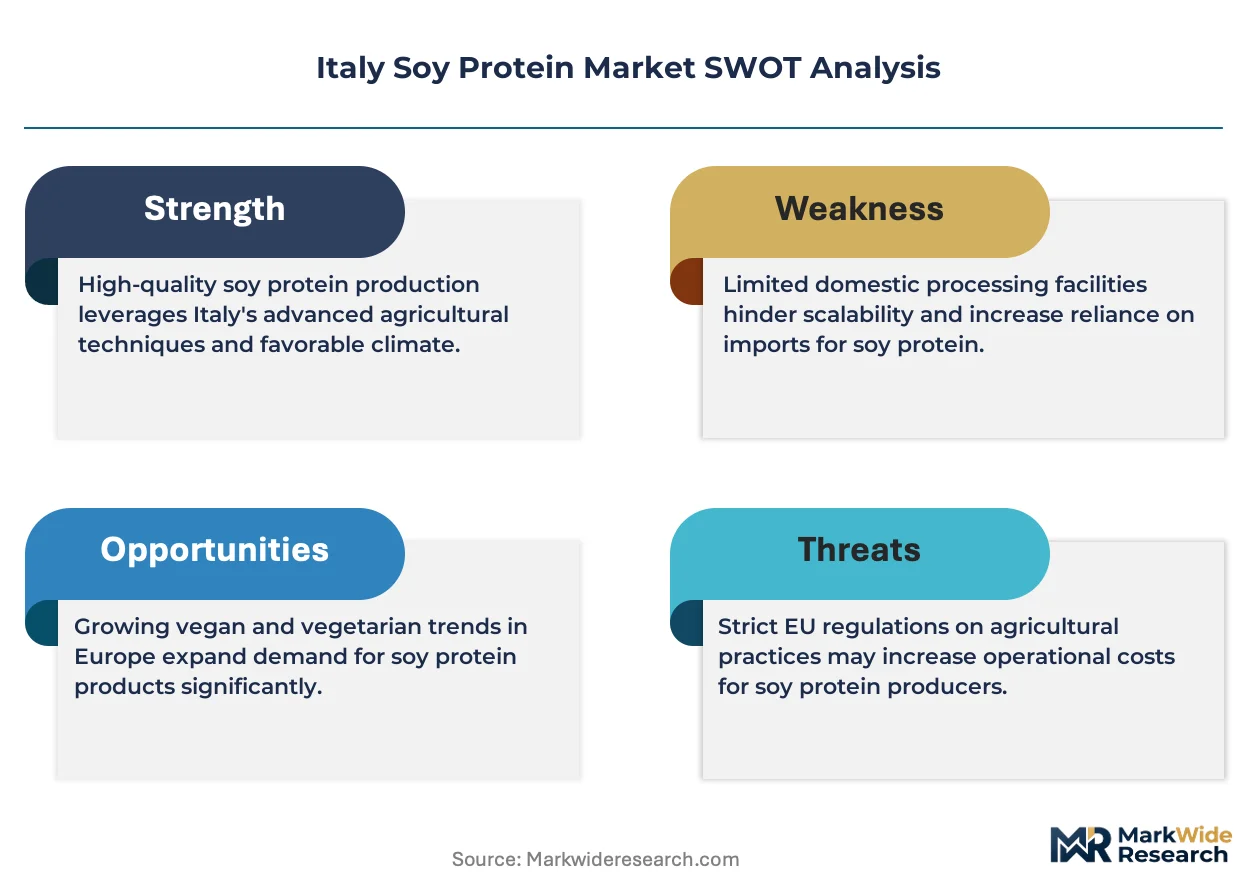
Food-grade isolate specifications are rotating toward higher protein purity thresholds as Italian buyers enforce stricter contract terms. Archer Daniels Midland Company leverages its European crushing network to secure non-GMO bean flows into northern Italy. Kerry Group differentiates through flavor-masked isolate systems tailored to Mediterranean taste profiles. A. Costantino & C. spa. anchors domestic production with its Emilia-Romana processing facility serving regional pasta and bakery accounts.
Soy protein denotes defatted soybean meal further processed into functional ingredients with protein contents spanning fifty to ninety percent on a dry-weight basis, serving primarily as a structural and nutritional substitute for animal-derived proteins in formulated foods. Isolate commands premium positioning due to its neutral flavor and minimum ninety percent protein content, while textured variants gain traction among Italian meat-analog producers seeking fibrous bite replication. Dairy Alternatives applications absorb the largest volume share as oat-soy blend milks and fermented yogurts expand shelf space across Italian retail banners.
EFSA novel food assessments and EU GMO labeling requirements shape ingredient sourcing protocols for Italian formulators, with the national pharmaceutical regulator AIFA monitoring health claim substantiation on fortified products. BIS-equivalent Italian standards for organic certification create parallel procurement tracks for premium-positioned brands. Stakeholders must track evolving EU protein strategy funding allocations and monitor regional Italian co-manufacturer consolidation to secure capacity in the expanding plant-protein value chain.
Market Dynamics
Italian soy protein demand is restructuring around the Farm to Fork Strategy's protein diversification mandates, forcing northern food processors to requalify suppliers against tightened sustainability audit protocols.
Growth Catalysts
- EU Protein Strategy funding:Dedicated allocations for domestic processing capacity are accelerating Emilia-Romana facility upgrades and reducing import dependency on North American isolates.
- Meat-analog formulation advances:Textured soy protein adoption by Milan-based ready-meal manufacturers is expanding addressable volume in refrigerated and frozen retail channels.
- Organic certification pipelines:BIS-equivalent Italian standards for organic soy are opening premium procurement tracks for pasta and bakery accounts seeking clean-label positioning.
Market Restraints
- Non-GMO bean supply concentration:Crushing capacity for identity-preserved soybeans clusters in specific EU port corridors, exposing Italian processors to freight volatility and origin-sourcing bottlenecks.
- EFSA novel food assessment timelines:Extended safety evaluation protocols for new soy protein variants delay product launches by 18-36 months, compressing innovation returns.
- Pulse protein substitution:Fava and pea protein isolates from French and Dutch suppliers are capturing formulation trials in dairy alternatives, threatening soy's volume dominance in plant-based beverages.
Strategic Opportunities
- Southern Italy underpenetration:Campania and Sicily retail banners carry minimal soy-fortified SKUs, creating whitespace for regional co-manufacturers to establish distribution partnerships.
- Fermented yogurt application expansion:Live culture soy bases are displacing coconut and almond in refrigerated sets, with Bologna-based producers piloting Mediterranean-flavor prototypes.
- CSRD-aligned supplier reporting:The EU Corporate Sustainability Reporting Directive is mandating Scope 3 disclosure, rewarding Italian processors with verified deforestation-free supply chains.
Industry Challenges
- Flavor chemist talent scarcity:Masking soy's beany off-notes for Mediterranean palates requires specialized formulation expertise that Italian technical institutes currently undersupply.
- AIFA health claim substantiation costs:Clinical trial investments required for protein-content marketing on fortified products strain mid-tier brand marketing budgets.
- Legacy dairy equipment retrofitting:Conventional milk processing lines require substantial capital modification to handle soy protein's distinct hydration and shear properties.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Soy Protein Market |
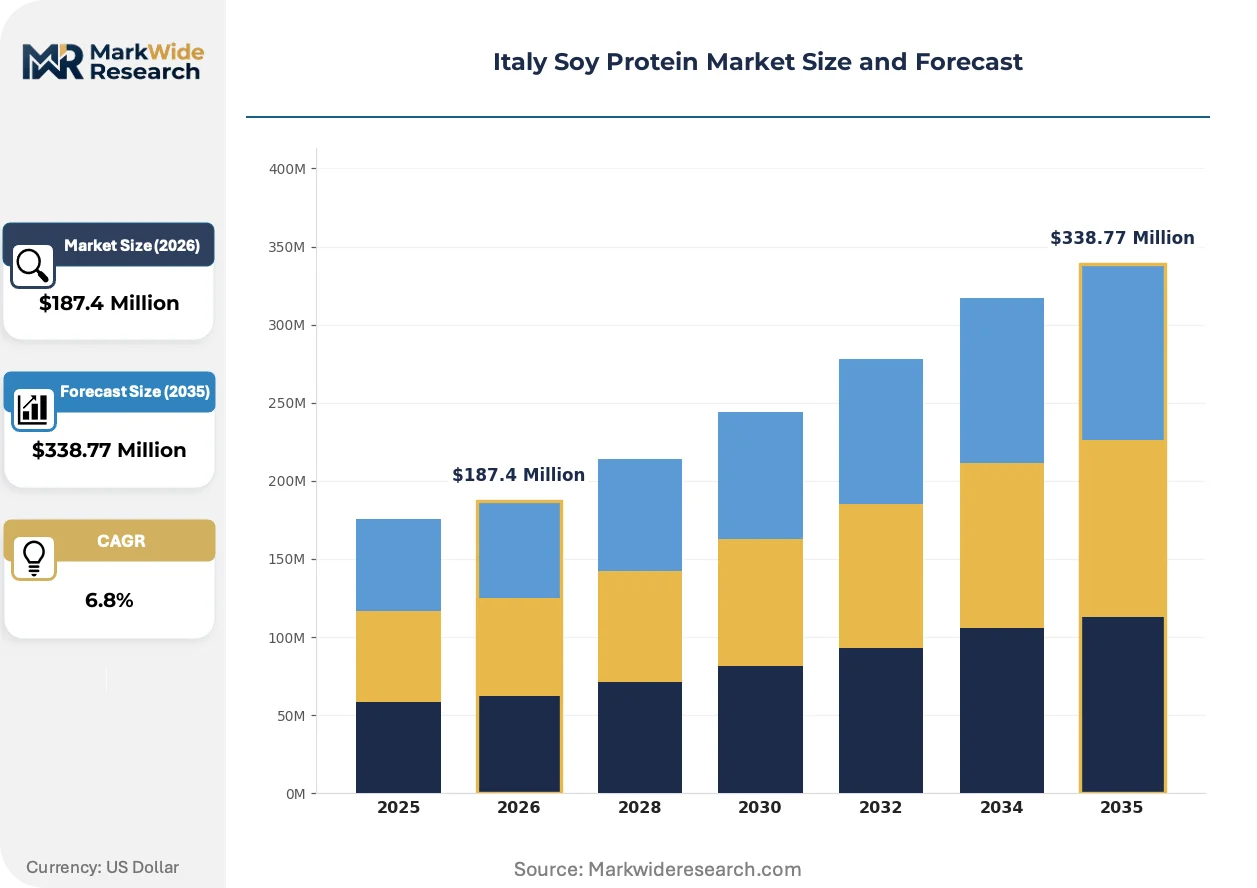
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isolate, Concentrate, Textured, Flour Application: Dairy Alternatives, Meat Substitutes, Snacks, Dietary Supplements End User: Food Manufacturers, Health Food Stores, Supermarkets, Restaurants Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesale |
| Companies Covered | Archer Daniels Midland Company, Cargill, Incorporated, DuPont de Nemours, Inc., Kerry Group, CJ Group, Bunge Limited, A. Costantino & C. spa., Wilmar International Limited, International Flavours and Fragrance Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Soy Protein Market Shifts & Advancements
Processing technology and regulatory disclosure requirements are simultaneously elevating product specifications and supplier qualification barriers across Italian soy protein value chains.
Enzymatic hydrolysis is bifurcating the isolate segment into standard and ultra-pure grades. Premium pasta and bakery accounts in Lombardy are adopting 95%+ protein variants for neutral flavor integration. This technological split is compressing margins on legacy 90% isolates while rewarding processors with enzymatic capability.
REACH-aligned contaminant thresholds for pesticide residues are tightening raw material acceptance criteria. Italian importers now require third-party testing for glyphosate and dioxin levels prior to customs release. Dairy alternative formulators in the Milan corridor are absorbing these compliance costs through dedicated supplier qualification teams.
Direct-procurement contracts between retail banners and crushing facilities are displacing traditional ingredient distributor intermediaries. Conad and Coop central buying offices are negotiating volume commitments with northern Italian processors for private-label plant-based ranges. This channel restructuring concentrates volume with vertically integrated suppliers and marginalizes smaller trading houses.
Italy Soy Protein Market Segmentation
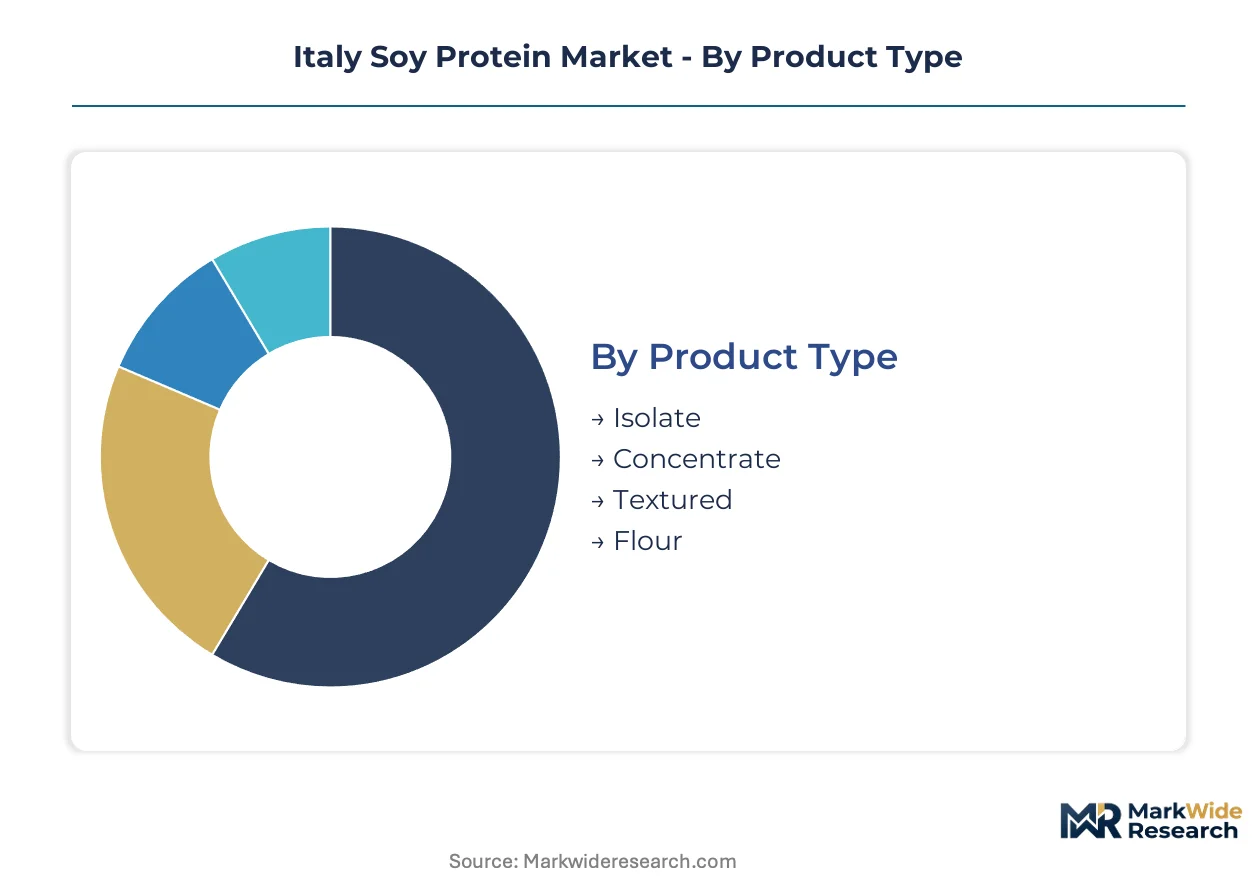
Italian soy protein procurement splits across four structural dimensions, each commanding distinct margin profiles and supplier qualification requirements. Product type and application layers determine pricing power, while end-user concentration in northern processing corridors shapes distribution economics.
Product Type:
Margin pools concentrate in enzymatically processed isolates where 95%+ protein purity commands contract premiums from Lombardy pasta and bakery accounts.
- Isolate:Enzymatic hydrolysis produces 90-95%+ protein fractions with neutral flavor profiles. Milan-based dairy alternative formulators enforce strict glyphosate residue thresholds, absorbing third-party testing costs into procurement budgets.
- Textured:Extruded fibrous structures replicate meat bite characteristics through controlled hydration and shear. Bologna ready-meal manufacturers are expanding refrigerated channel SKUs, driving volume commitments from Emilia-Romana processors.
- Concentrate:65-70% protein defatted flakes serve cost-sensitive bakery applications across northern Italy.
- Flour:Full-fat and defatted base grades supply traditional pasta fortification in Campania and Sicily regional mills.
The dominant share belongs to Isolate, while Textured is closing the gap fastest.
Application:
Volume concentration tracks retail banner expansion in plant-based beverage sets, with refrigerated yogurt and oat-soy blend milks absorbing the largest tonnage flows.
- Dairy Alternatives:Fermented soy bases displace coconut and almond in Bologna-piloted Mediterranean flavor prototypes. Live culture processing requires specialized hydration equipment, limiting co-manufacturer qualification to upgraded facilities.
- Meat Substitutes:Milan-based analog producers demand textured variants with calibrated fibrous structures for frozen and refrigerated retail channels. EFSA novel food timelines compress innovation returns by 18-36 months for new texture formats.
- Snacks:Extruded puffs and protein bars target health-conscious consumers through Conad and Coop private-label ranges.
- Dietary Supplements:AIFA health claim substantiation costs strain mid-tier brand marketing budgets for protein-fortified positioning.
Dairy Alternatives anchors volume leadership, though Meat Substitutes shows the steepest expansion trajectory as retail analog sets widen.
End User:
Procurement authority concentrates in food manufacturing procurement offices, where direct crushing contracts displace traditional ingredient distributors.
- Food Manufacturers:Northern Italy's processing corridor around Milan and Bologna drives consolidated volume through CSRD-aligned supplier reporting mandates. Scope 3 disclosure requirements reward verified deforestation-free supply chains.
- Supermarkets:Conad and Coop central buying offices negotiate private-label plant-based ranges with vertically integrated processors.
- Health Food Stores:Organic certification pipelines under BIS-equivalent Italian standards support premium positioning for clean-label accounts.
- Restaurants:Foodservice adoption lags retail, with southern Italy underpenetration creating whitespace for regional distribution partnerships.
Food Manufacturers command the dominant procurement volume, while Supermarkets are gaining share fastest through banner consolidation.
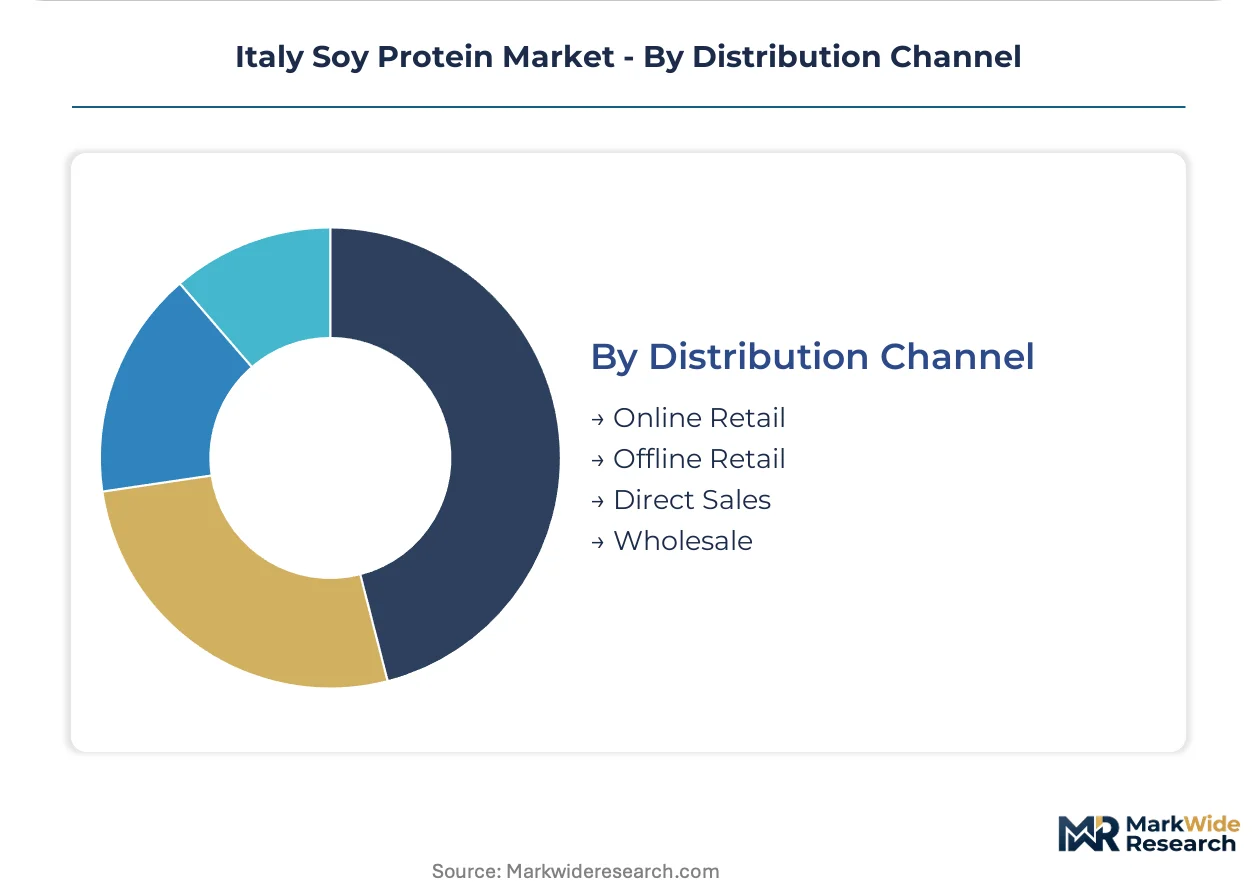
Distribution Channel:
Channel restructuring favors direct volume commitments, compressing margins for traditional trading intermediaries unable to offer integrated processing capabilities.
- Direct Sales:Crushing facilities negotiate multi-year contracts with retail central buying offices, bypassing distributor markups. REACH-aligned contaminant testing is embedded in supplier qualification protocols.
- Wholesale:Regional distributors serve mid-tier pasta and bakery accounts in Campania and Sicily with smaller minimum order quantities.
- Offline Retail:Traditional cash-and-carry networks supply independent health food stores and restaurants.
- Online Retail:E-commerce penetration remains limited for bulk ingredient procurement, concentrated in finished consumer packaged goods.
Direct Sales holds the dominant channel position, while Wholesale maintains relevance in southern underpenetrated zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy runs a structural deficit in soy protein isolates, importing the majority of high-purity grades from North American crushing facilities while exporting textured variants to Mediterranean neighbors. The trade imbalance concentrates procurement risk in northern port corridors and shapes domestic processing investments.
Lombardy
Milan anchors Italy's dairy alternative formulation cluster, with plant-based beverage manufacturers absorbing enzymatically processed isolates for neutral-flavor oat-soy blends. EFSA novel food assessments govern ingredient approvals for fermented yogurt prototypes. The Milan corridor drives CSRD-aligned supplier reporting mandates, rewarding processors with verified deforestation-free supply chains.
Emilia-Romagna
Bologna-based ready-meal manufacturers are expanding textured soy protein adoption for refrigerated meat-analog SKUs. EU Protein Strategy funding accelerates facility upgrades at regional crushing plants, reducing import dependency on North American isolates. The Emilia-Romagna processing corridor serves pasta and bakery accounts with domestically produced concentrates.
Piedmont
Turin food manufacturers source identity-preserved non-GMO beans through EU port corridors, exposing operations to freight volatility from origin-sourcing bottlenecks. REACH-aligned contaminant thresholds for pesticide residues tighten raw material acceptance criteria. Northern Piedmont mills supply defatted flakes to cost-sensitive regional bakery applications.
Veneto
Verona health food distributors channel organic-certified isolates through BIS-equivalent Italian standards pipelines, supporting premium positioning for clean-label accounts. AIFA health claim substantiation requirements strain mid-tier brand marketing budgets for protein-fortified positioning. The Veneto organic certification track opens parallel procurement channels for Campania and Sicily retail expansion.
Lazio
Rome central buying offices for national retail banners negotiate direct-procurement contracts with crushing facilities, displacing traditional ingredient distributor intermediaries. Farm to Fork Strategy protein diversification mandates force requalification of suppliers against tightened sustainability audit protocols. The Lazio distribution node concentrates volume with vertically integrated suppliers serving Conad and Coop private-label ranges.
Italy Soy Protein Market Competitive Landscape
Concentration sits with multinational agribusiness conglomerates controlling upstream crushing networks and downstream formulation capabilities. Three distinct archetypes populate the competitive terrain: North American traders with identity-preserved bean sourcing infrastructure, European ingredient specialists with flavor-system integration expertise, and domestic Italian processors with regional co-manufacturer relationships. Competitive moves center on backward integration into non-GMO supply chains and strategic partnerships with retail central buying offices for private-label volume commitments.
Among North American agribusiness operators, Archer Daniels Midland Company and Cargill, Incorporated exemplify the trader-processor archetype with European crushing network leverage. Kerry Group occupies a position within the European ingredient specialist tier, while A. Costantino & C. spa. anchors the domestic Italian processor category with Emilia-Romagna facility presence. These three represent the strategic positioning vectors shaping supplier qualification dynamics in northern Italy's food processing corridor.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Incorporated |
| DuPont de Nemours, Inc. |
| Kerry Group |
| CJ Group |
| Bunge Limited |
| A. Costantino & C. spa. |
| Wilmar International Limited |
| International Flavours and Fragrance Inc. |
| Others |
Supply & Pricing Matrix
Ninety-day inventory cycles at Milan-based dairy alternative formulators concentrate procurement power among crushing facilities with verified deforestation-free supply chains, compressing margins for distributors unable to offer CSRD-aligned transparency documentation. This lead-time discipline rewards processors with backward integration into identity-preserved non-GMO bean flows while penalizing trading intermediaries exposed to freight volatility from North American origin bottlenecks.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across northern Italy's food processing corridor. Three-tier pricing structure across premium, standard, and economy levels separates enzymatically hydrolyzed 95%+ isolates from legacy 90% grades and cost-sensitive concentrates. Cost compression in standard isolates is intensifying because REACH-aligned contaminant testing costs are being absorbed into procurement budgets rather than passed downstream. Mid-tier pasta and bakery accounts in Campania and Sicily exhibit highest price sensitivity, while Milan-based dairy alternative formulators prioritize purity thresholds over unit economics.
Supply Chain Analysis
Container availability constraints at Rotterdam and Hamburg port corridors expose Italian processors to freight volatility from North American and Argentine crushing origins. Supply draws from identity-preserved non-GMO bean flows through Archer Daniels Midland's European network, Kerry Group's flavor-system integration facilities, and A. Costantino & C. spa.'s Emilia-Romagna processing plant. Single-source vulnerability concentrates in glyphosate-residue testing capacity, where third-party verification bottlenecks delay customs release. Distribution runs through direct-procurement contracts between retail central buying offices and crushing facilities, displacing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Italy soy protein market sits at an inflection point where enzymatic hydrolysis capabilities and Farm to Fork Strategy protein diversification mandates are simultaneously elevating product specifications and supplier qualification barriers. EFSA novel food assessment timelines compress innovation returns, rewarding processors with established regulatory navigation expertise.
For Market Incumbents: Fortify backward integration into identity-preserved non-GMO supply chains through EU port corridor crushing partnerships. Expand enzymatic processing capacity at Emilia-Romagna facilities to capture premium 95%+ isolate demand from Lombardy pasta accounts. Pulse protein substitution from French and Dutch suppliers threatens soy's volume dominance in dairy alternatives, necessitating flavor-masked formulation investments to defend positioning. For New Entrants and Emerging Players: Fermented yogurt application expansion represents a service-layer gap where incumbents under-serve Mediterranean flavor prototype development. Target Campania and Sicily retail banners carrying minimal soy-fortified SKUs through regional co-manufacturer distribution partnerships. Live culture processing equipment requirements limit qualified competitors, creating whitespace for specialized hydration capability investments. For Investors and Strategic Acquirers: Long-term, this sits as a sustainability-premium play because CSRD-aligned Scope 3 disclosure mandates reward verified deforestation-free supply chains with retail banner volume concentration. Acquisition target archetype: domestic Italian processors with regional co-manufacturer relationships and BIS-equivalent organic certification pipelines. Monitor EU Protein Strategy funding allocation announcements as inflection indicator for domestic processing capacity expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Non-GMO Supply Chains | CSRD-aligned Scope 3 disclosure mandates reward verified deforestation-free bean flows with retail banner contracts. |
| Enzymatic Hydrolysis Capacity Expansion | Emilia-Romagna facility upgrades capture premium 95%+ isolate demand from Lombardy pasta and bakery accounts. |
| Flavor-Masked Formulation R&D Investment | Kerry Group's Mediterranean taste profile systems demonstrate differentiation potential against pulse protein substitutes. |
| Southern Italy Distribution Partnership | Campania and Sicily retail banner whitespace creates regional co-manufacturer acquisition targets for volume expansion. |
| Organic Certification Pipeline Development | BIS-equivalent Italian standards support premium positioning for clean-label accounts in Veneto health food channels. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with food manufacturing procurement directors, crushing facility operations managers, retail category buyers at Conad and Coop, regulatory affairs specialists navigating EFSA novel food pathways, and flavor chemists at technical institutes. Secondary validation drew from EU Protein Strategy funding documentation, EFSA safety assessment databases, REACH contaminant threshold registers, and Italian customs trade flow records. Bottom-up volume triangulation from application-level consumption estimates converged with top-down value reconstruction from crushing capacity and pricing band analysis.
Across the analysis window, the forecasting framework modeled product type segmentation by purity grade and processing technology, application segmentation by formulation complexity and channel placement, and end-user segmentation by procurement authority concentration and sustainability reporting maturity. CAGRs were derived from elasticity-adjusted demand projections incorporating protein diversification policy implementation timelines and retail banner private-label expansion commitments. Industry-specific inputs included enzymatic hydrolysis adoption curves and AIFA health claim substantiation investment patterns.
Forecasts assume regulatory continuity in EFSA novel food assessment protocols and Farm to Fork Strategy protein diversification mandates; material policy shifts would require re-modeling demand elasticity assumptions. Commodity price volatility in identity-preserved non-GMO bean markets and freight cost fluctuations through EU port corridors represent specific revision triggers. Practitioners should keep alternative scenarios live as pulse protein substitution rates and southern Italy retail penetration trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Egg Albumin Protein Market
Ingredients
Waxy Maize Starch Market
Ingredients
North America Plant Protein Ingredients Market
Ingredients
Dry Brewing Ingredients Market
Ingredients
Gum Arabic Market
Ingredients
Beef Concentrate Market
Ingredients
North America Algae Omega-3 Ingredients Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Global Apricot Oil Market
Ingredients
North America Feed Yeast Market
Ingredients
Meat Starter Culture Market
Ingredients
Chlorella Ingredients Market
Ingredients
Revivable Yeast Market
Ingredients
Salt Market
Ingredients
Fruit Powder Market
Ingredients
Cold Pressed Oil Market