
 Middle East and Africa Dairy Market | 2026-2036
Middle East and Africa Dairy Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Dairy Market Foresight
Plant-based fat blends is broadening formulation options for traditional ghee and processed cheese in price-sensitive segments. Almarai Company leverages its integrated feed-to-retail model across Saudi Arabia and Egypt to sustain cost discipline in fluid milk. Danone SA anchors its regional position through specialized pediatric and digestive health yogurt lines. Arla Foods amba competes via its cooperative structure, which controls farmer-gate milk quality across multiple African sourcing zones.
Middle East and Africa dairy encompasses bovine, caprine, and camelid milk and its derivatives, processed through heat treatment, fermentation, or mechanical separation to achieve specified fat content, protein stability, and shelf-life parameters; the category serves nutritional, culinary, and industrial ingredient functions across consumer and commercial channels. Milk remains the volume foundation, though margin pools concentrate in cheese and yogurt where processing complexity creates pricing power. The food service end user segment exhibits the fastest structural expansion, driven by quick-service restaurant chains and institutional catering across the Gulf. Distribution through supermarkets still dominates value capture, yet online retail is accelerating in South Africa and Nigeria's metropolitan corridors.
Saudi Arabia's SFDA governs dairy fortification standards and safety protocols, while Egypt's EOS administers local quality certifications that shape import competitiveness and domestic plant investment. The EU Green Deal's extraterritorial carbon border adjustments will progressively condition market access for European exporters serving Maghreb buyers. Stakeholders must monitor how climate-water stress across the Sahel and Horn of Africa redirects sourcing geography and herd management practices.
Market Dynamics
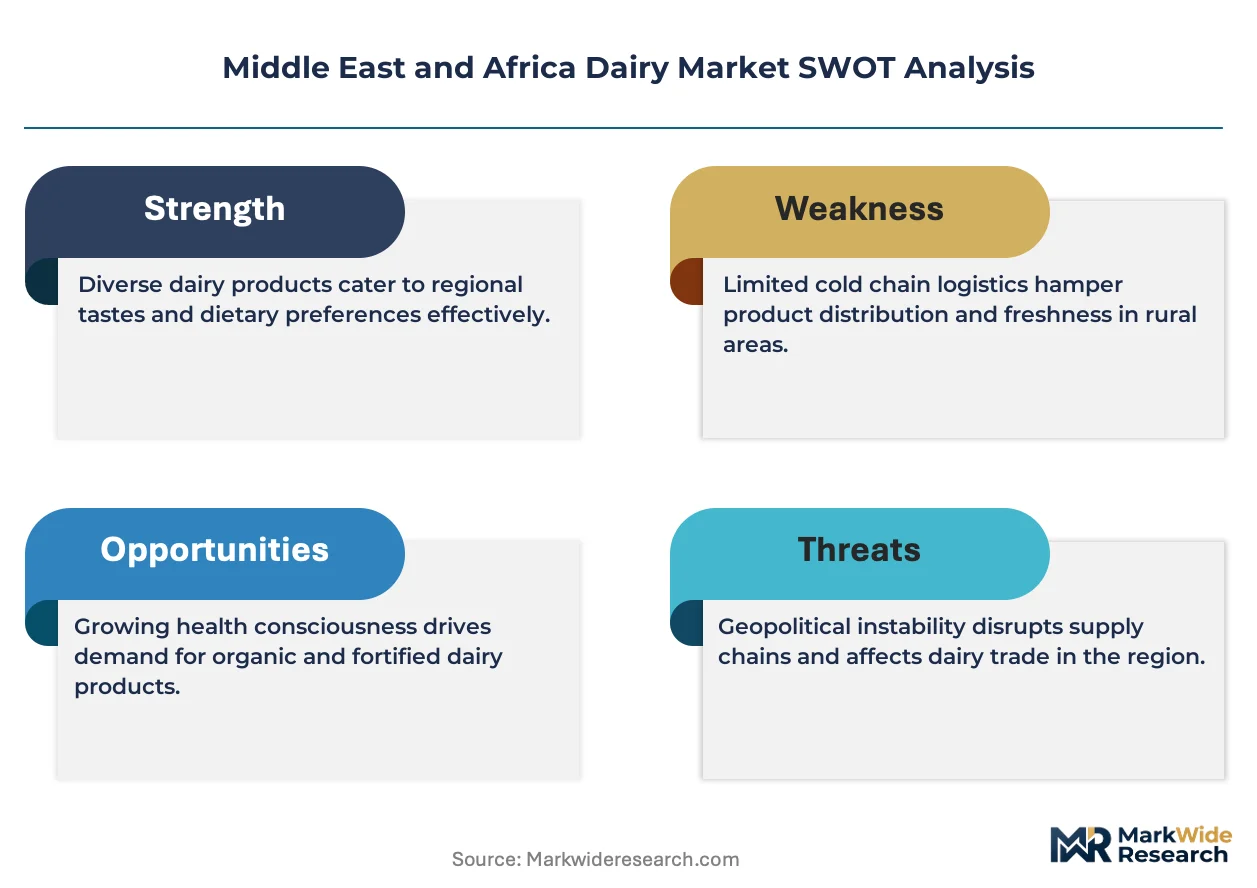
Saudi Arabia's SFDA fortification mandates and Egypt's import substitution policies are compressing formulation cycles and redirecting capital toward domestic processing capacity across the Middle East and Africa dairy landscape.
Growth Catalysts
- Hotel and restaurant procurement expansion:Gulf Cooperation Council food service chains are broadening dairy SKUs on menus, pulling fluid milk and processed cheese volumes into institutional channels.
- SFDA labeling compliance:Saudi Arabia's tightened fortification disclosure rules are forcing product reformulation that differentiates domestic processors from non-compliant imports.
- Urban pasteurization scaling:Egypt's Nile Delta processors are expanding heat-treatment capacity to serve Cairo and Alexandria population density.
Market Restraints
- Feed cost volatility:Alfalfa and soybean meal price swings compress margins for bovine and camelid operations across North African grazing zones.
- Water stress concentration:Sahel and Horn of Africa climate pressures are restricting herd mobility and forcing geographic consolidation of milk sourcing.
- EU carbon border friction:The EU Green Deal's extraterritorial adjustments are conditioning Maghreb market access terms for European dairy exporters.
Strategic Opportunities
- Nigeria metropolitan e-commerce:Online retail acceleration in Lagos and Abuja corridors creates direct-to-consumer pathways bypassing traditional cold-chain intermediaries.
- Pediatric nutrition specialization:Digestive health and early childhood yogurt formulations align with Gulf consumer willingness to pay for functional positioning.
- Plant-based fat blend convergence:Alternative lipid technologies are opening formulation space for price-sensitive processed cheese and traditional ghee segments.
Industry Challenges
- Veterinary pharmaceutical compliance timelines:Residue testing protocols for export-grade milk are extending certification cycles for Sahel cooperatives seeking Gulf market entry.
- Cold-chain capex intensity:Refrigerated transport and storage infrastructure requirements strain working capital for East African processors scaling beyond local catchment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Dairy Market |
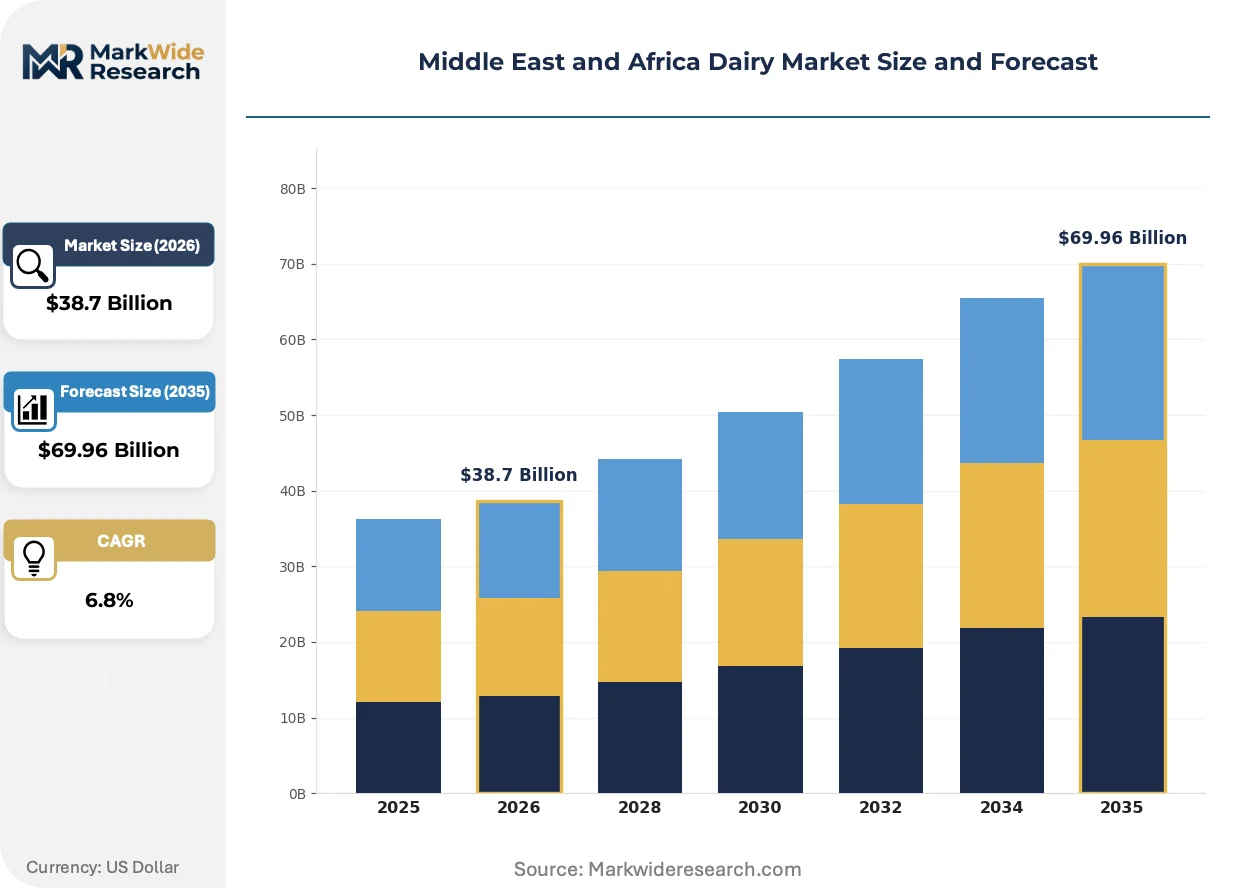
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Butter End User: Households, Food Service, Retailers, Manufacturers Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesalers Application: Beverages, Cooking Ingredients, Snacks, Nutritional Supplements |
| Companies Covered | Saudia Dairy and Foodstuff Company, Arla Foods amba, Almarai Company, Fonterra Co-operative Group, Groupe Lactalis, Nestlé SA, National Agricultural Development Company, AlRawabi Dairy Company, Danone SA, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Dairy Market Shifts & Advancements
Heat treatment automation and fermentation control systems are compressing quality variance in Middle East and Africa dairy processing, while regulatory fortification mandates and channel digitization reshape competitive positioning.
Extended shelf-life (ESL) processing technology is electrifying fluid milk distribution economics in the Gulf. Urban Saudi retailers are adopting membrane filtration and advanced pasteurization to reduce refrigeration dependency. This electrifying shift is compressing traditional cold-chain infrastructure requirements and enabling longer-radius sourcing from Egyptian and Sudanese supply zones.
Saudi Arabia's SFDA has issued tightened disclosure protocols for vitamin D and calcium fortification claims in dairy labeling. Domestic processors are reformulating recipes and redesigning packaging to meet the new documentation thresholds. Pediatric and functional yogurt lines face the steepest compliance recalibration, with several Gulf manufacturers accelerating in-house analytical laboratory investments.
Quick-service restaurant chains across the Gulf Cooperation Council are consolidating dairy procurement through centralized category management, displacing fragmented spot purchasing. This concentration is compressing supplier margins while favoring processors with integrated feed-to-retail traceability systems. The procurement pivot is most visible in Dubai and Riyadh, where hotel and institutional catering groups are awarding multi-year fluid milk and cheese contracts.
Middle East and Africa Dairy Market Segmentation
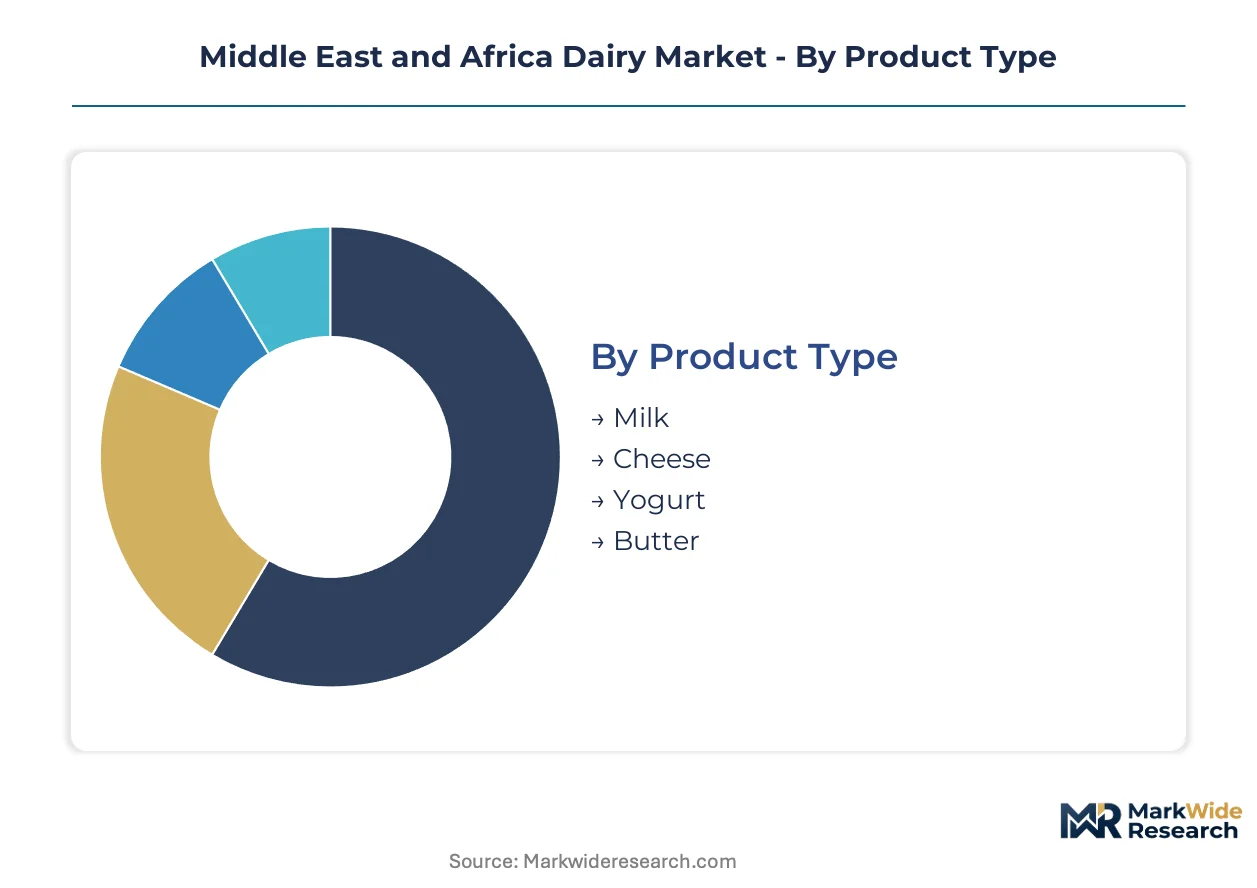
Segmentation in Middle East and Africa dairy reveals how distinct product forms, channel economics, and end-use requirements fragment procurement priorities across the region's heterogeneous markets. Understanding these splits clarifies where processors must configure separate production lines, cold-chain investments, and regulatory compliance pathways.
Product Type:
Standalone commodity formats dominate volume placements, while value-added derivatives increasingly embed functional fortification systems that command formulation premiums.
- Milk:Fluid milk serves as the foundational volume driver, with pasteurized and UHT variants anchoring household consumption across Egypt's Nile Delta and Saudi Arabia's urban corridors. Demand concentrates in Cairo and Riyadh metropolitan procurement, where SFDA fortification mandates and Egyptian EOS quality certifications reshape competitive positioning between domestic processors and import suppliers.
- Cheese:Processed cheese variants integrate into quick-service restaurant supply chains and institutional catering across Gulf Cooperation Council hotel networks, while traditional white cheeses retain household penetration in Levantine and North African markets. Margin pools favor processors with integrated feed-to-retail traceability systems that satisfy centralized category management requirements.
- Yogurt:Pediatric and digestive health formulations align with Gulf consumer willingness to pay for functional positioning.
- Butter:Traditional ghee and spreadable formats serve culinary applications across Maghreb and Horn of Africa markets.
Volume placements concentrate in Milk; the faster expansion belongs to Cheese.
End User:
Procurement concentration varies sharply between fragmented household purchasing and consolidated institutional contracting that reshapes supplier economics.
- Households:Retail-packaged fluid milk and yogurt drive repeat purchase frequency across urban Egyptian and South African supermarkets, with brand loyalty forming around fortification claims and shelf-stable convenience.
- Food Service:Hotel and restaurant chains across Dubai and Riyadh corridors are consolidating dairy procurement through multi-year fluid milk and cheese contracts, displacing fragmented spot purchasing and compressing margins for processors lacking integrated traceability.
- Retailers:Supermarket private-label programs in Lagos and Abuja are expanding pasteurized milk sourcing from domestic Nile Delta processors.
- Manufacturers:Industrial ingredient buyers procuring milk powders and whey derivatives for confectionery and bakery applications.
Procurement volume clusters in Households; Food Service exhibits the steepest expansion trajectory as Gulf institutional catering scales.
Distribution Channel:
Channel infrastructure maturity determines cold-chain investment requirements and margin capture potential across metropolitan versus peri-urban catchments.
- Supermarkets:Modern retail chains in Saudi Arabia, UAE, and South Africa dominate value capture through controlled-temperature display infrastructure and centralized distribution centers that reduce spoilage variance.
- Online Retail:Lagos and Abuja metropolitan corridors are accelerating direct-to-consumer pathways that bypass traditional cold-chain intermediaries, though last-mile refrigeration constraints limit SKU expansion beyond UHT and powdered formats.
- Convenience Stores:Small-format urban outlets in Cairo and Alexandria serve immediate-consumption demand for single-serve yogurt and flavored milk.
- Wholesalers:Traditional trade aggregators in Sudan and Ethiopia's informal supply zones.
Value capture concentrates in Supermarkets; Online Retail is gaining share fastest among channel investments.
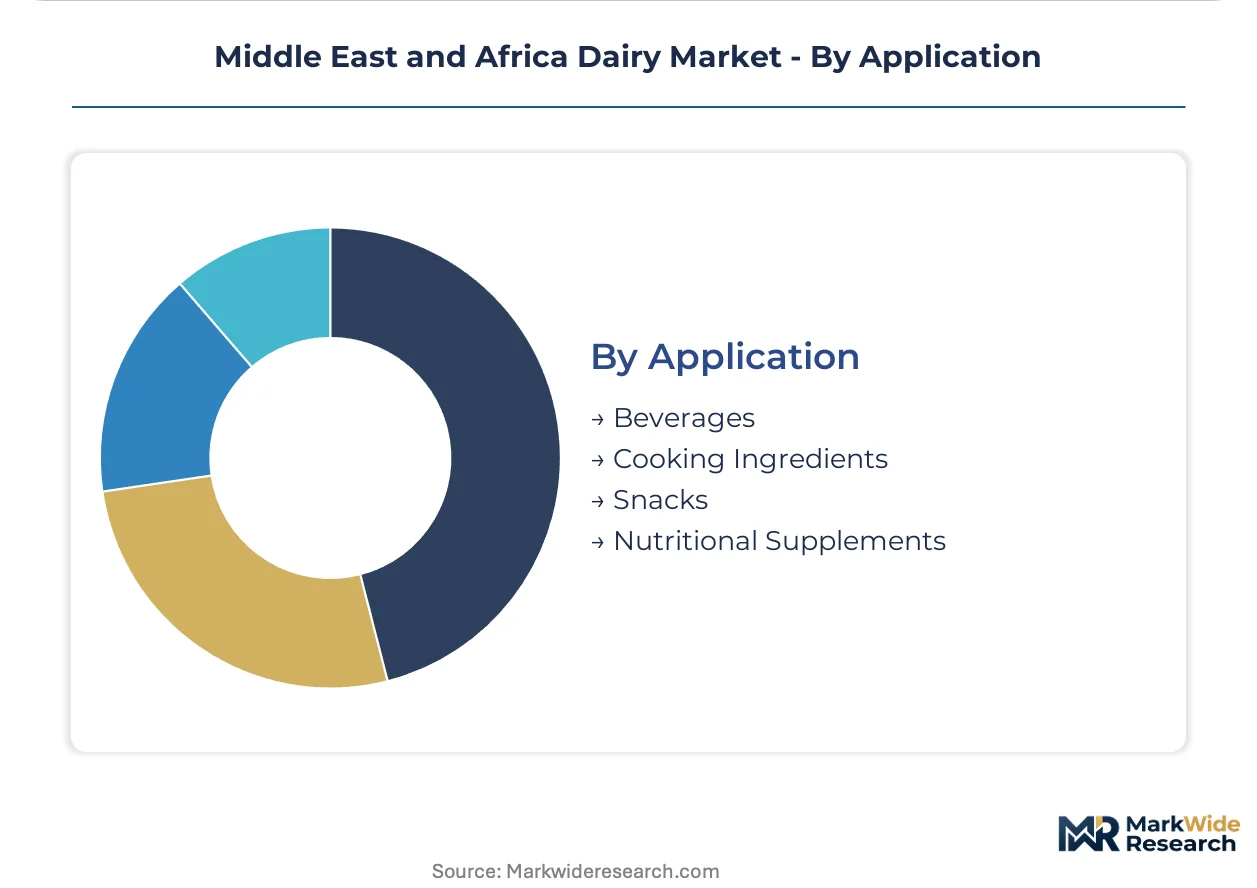
Application:
Functional positioning and culinary tradition split demand between nutritional supplementation markets and ingredient-input channels with divergent specification requirements.
- Beverages:Fortified flavored milks and drinkable yogurts target pediatric nutrition and adult digestive health positioning in Gulf markets, with vitamin D and calcium disclosure protocols compelling reformulation investments under tightened SFDA labeling rules.
- Cooking Ingredients:Traditional ghee, butter, and processed cheese integrate into institutional catering and household culinary applications across Maghreb and Levantine markets, where plant-based fat blend technologies are opening formulation space for price-sensitive segments.
- Snacks:Cheese portions and yogurt-based desserts serve convenience-oriented consumption occasions.
- Nutritional Supplements:Medical and sports nutrition applications for whey isolates and protein concentrates.
Volume demand anchors in Beverages; Cooking Ingredients are expanding most quickly as food service procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fortified dairy concentrates in Egypt's Nile Delta and Saudi Arabia's urban corridors, where population density and institutional procurement expansion reshape sourcing geography across the Middle East and Africa dairy landscape.
Saudi Arabia
Hotel and restaurant chains in Riyadh and Jeddah are consolidating fluid milk and cheese procurement through multi-year contracts. The Saudi Food and Drug Authority has tightened vitamin D and calcium fortification disclosure protocols, compelling domestic processors to redesign packaging and accelerate in-house laboratory investments. The Eastern Province dairy cluster is scaling pasteurization capacity to serve Gulf Cooperation Council export channels.
Egypt
Domestic processors in the Nile Delta are expanding heat-treatment output to supply Cairo and Alexandria metropolitan demand. The Egyptian Organization for Standardization administers quality certifications that shape import competitiveness and direct capital toward domestic plant investment. Alexandria's port logistics infrastructure is capturing re-export flows to Maghreb and Horn of Africa markets.
United Arab Emirates
Dubai's food service sector is broadening dairy SKUs across hotel and quick-service restaurant menus, pulling processed cheese and UHT milk into institutional channels. The Ministry of Health and Prevention governs safety protocols for fortified products entering retail distribution. Jebel Ali's free zone logistics hub is consolidating regional cold-chain aggregation for re-export to Saudi and Qatar markets.
South Africa
Supermarket private-label programs in Johannesburg and Cape Town are expanding pasteurized milk sourcing from domestic processors. The country's national food safety regulator enforces residue testing protocols that extend certification cycles for export-grade production. The Western Cape dairy belt is investing in membrane filtration technology to reduce refrigeration dependency in distribution.
Nigeria
Online retail acceleration in Lagos and Abuja corridors is creating direct-to-consumer pathways for UHT and powdered dairy formats. The central bank's foreign exchange policies condition import competitiveness for European milk powder suppliers. Kano's northern processing zone is scaling local yogurt production to bypass cold-chain constraints in last-mile distribution.
Middle East and Africa Dairy Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated feed-to-retail operators commanding procurement concentration in fluid milk while formulation houses capture margin in pediatric and functional yogurt lines. The vendor base organizes around three archetypes: Gulf-based integrated processors with captive herd supply, European cooperative exporters leveraging quality certifications, and regional private-label converters serving price-sensitive Maghreb markets. Dominant competitive moves include backward integration into alfalfa and feed grain sourcing to compress input volatility, and strategic partnerships with quick-service restaurant chains to secure multi-year volume commitments.
Within the integrated processor tier, Almarai Company and National Agricultural Development Company represent Gulf-based operators with feed-to-retail control across Saudi and Egyptian supply zones. Arla Foods amba exemplifies the European cooperative model, anchoring quality-positioned exports through farmer-gate milk standardization. Danone SA occupies a position in specialized pediatric and digestive health formulations aligned with Gulf consumer willingness to pay for functional positioning.
| Leading Market Players |
|---|
| Saudia Dairy and Foodstuff Company |
| Arla Foods amba |
| Almarai Company |
| Fonterra Co-operative Group |
| Groupe Lactalis |
| Nestlé SA |
| National Agricultural Development Company |
| AlRawabi Dairy Company |
| Danone SA |
| Others |
Supply & Pricing Matrix
Alfalfa and soybean meal price indices cascade through Middle East and Africa dairy supply chains, compressing margins for bovine and camelid operations while forcing tiered pricing stratification across Gulf institutional buyers, Egyptian retail channels, and Maghreb price-sensitive segments.
Pricing Analysis
Volume concentrates in fluid milk while margin pools shift toward cheese and yogurt where fortification complexity commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates SFDA-compliant fortified variants from Egyptian EOS-certified domestic output and unbranded traditional trade. Pricing pressure stems from feed cost volatility in North African grazing zones, with Gulf food service buyers least sensitive and Maghreb household segments most responsive to price fluctuations.
Supply Chain Analysis
Dual-sourcing requirements from Gulf quick-service restaurant chains mandate multi-supplier qualification across Saudi, Egyptian, and Sudanese milk zones. Raw material flows draw from alfalfa cultivation in the Nile Delta, soybean meal imports through Alexandria and Jebel Ali ports, and veterinary pharmaceutical inputs for export-grade certification. Single-source vulnerability concentrates in heat-treatment equipment and membrane filtration technology. Distribution runs through supermarket-controlled cold chains in Saudi Arabia and UAE, with online retail bypassing traditional intermediaries in Lagos and Abuja.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended shelf-life processing technology is displacing conventional pasteurization infrastructure across Gulf dairy operations, creating asymmetric returns for processors that electrify distribution economics ahead of regulatory fortification mandates.
For Market Incumbents: Anticipate margin compression from centralized food service procurement by securing multi-year contracts through integrated feed-to-retail traceability systems. Accelerate in-house analytical laboratory investments to meet SFDA vitamin D and calcium disclosure protocols before compliance deadlines tighten. Prioritize backward integration into alfalfa and feed grain sourcing to buffer input volatility across Saudi and Egyptian supply zones.
For New Entrants and Emerging Players: Capture white-space opportunity in Nigeria's metropolitan e-commerce corridors where direct-to-consumer pathways bypass fragmented cold-chain intermediaries. Target pediatric and digestive health yogurt formulations aligned with Gulf consumer willingness to pay for functional positioning. Deploy UHT and powdered format specialization to circumvent last-mile refrigeration constraints in Lagos and Abuja.
For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Egyptian processors with Nile Delta heat-treatment capacity and re-export logistics access to Maghreb markets. Long-term viability hinges on water stress adaptation capabilities across the Sahel and Horn of Africa sourcing geography. Monitor EU carbon border adjustment implementation as inflection indicator for European cooperative exporter competitiveness in Maghreb procurement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Supply | Captive alfalfa and grain sourcing buffers margin volatility from commodity price swings. |
| ESL Technology Deployment | Membrane filtration reduces refrigeration dependency and extends sourcing radius from Sudanese zones. |
| SFDA Compliance Certification | In-house analytical laboratories meet tightened fortification disclosure protocols for Gulf market access. |
| Food Service Contract Consolidation | Multi-year agreements with Dubai and Riyadh hotel chains displace fragmented spot purchasing. |
| Nigeria E-Commerce Channel Entry | Direct-to-consumer platforms in Lagos bypass traditional cold-chain infrastructure constraints. |
Research Methodology
Trade publications, veterinary pharmaceutical regulatory filings, and Gulf food service procurement databases formed the secondary backbone for this analysis. Primary interviews with dairy processing plant managers, SFDA regulatory affairs leads, Nile Delta agricultural cooperative representatives, and UAE supermarket category buyers validated input cost assumptions and channel flow estimates. Bottom-up volume triangulation across pasteurization capacity installations and top-down value validation through import-export customs records anchored the forecasting framework.
Bottom-up modeling segmented volume across product type, end user, distribution channel, and application dimensions throughout the forecast period. Top-down cross-checks incorporated population density projections for Cairo and Riyadh corridors, food service outlet expansion rates across Gulf Cooperation Council states, and climate-water stress indices for Sahel sourcing zones. CAGRs were derived from regression analysis against historical alfalfa price volatility and urban pasteurization capacity scaling trends.
The model holds under stable feed commodity price regimes and sustained SFDA enforcement timelines; deviation in EU carbon border adjustment implementation or acute drought cycles across the Horn of Africa would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Lactose Free Butter Market
Dairy Products
Enzyme Modified Cheese Market
Dairy Products
Lactose Free Dairy Products Market
Dairy Products
UHT Milk Market
Dairy Products
South America Dairy Protein Market
Dairy Products
Smoked Cheese Market
Dairy Products
Mexico Whey Protein Market
Dairy Products
Reduced Fat Dairy Market
Dairy Products
White Cheese Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Halloumi Cheese Market
Dairy Products
Europe Dairy Market
Dairy Products
Dairy Dessert and Yogurt Market
Dairy Products
Qatar Dairy Products Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
Recombined Milk Products Market