
 Global Cream Cheese Market | 2026-2036
Global Cream Cheese Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cream Cheese Market Analysis
Multi-source milk procurement is hardening as a competitive necessity across the industry. Saputo Inc. anchors its North American position through direct dairy farm partnerships in Wisconsin and Quebec. FrieslandCampina N.V. leverages its Dutch cooperative structure to secure consistent raw milk volumes for European production. The Kraft Heinz Company sustains brand dominance in U.S. retail through controlled distribution networks and private-label manufacturing scale.
Cream cheese is a fresh, unripened soft cheese produced from standardized milk and cream mixtures, typically containing at least 33% milk fat and stabilized with gums or carrageenan for spreadable texture; it functions primarily as a bakery filling, dessert base, and savory spread in commercial and home kitchens. Regular cream cheese occupies the mature volume core, while flavored variants capture expanding margin pools through premium positioning in North American and European retail. Food service distribution channels are accelerating fastest, driven by bakery chain expansion and QSR breakfast menu development across multiple geographies.
FDA standards of identity in the United States enforce minimum milk fat thresholds and restrict filler content, shaping product formulation decisions for export-bound manufacturers. EFSA and national EU dairy regulators enforce strict pathogen controls and labeling requirements under the General Food Law, while Codex Alimentarius guidelines influence trade specifications for cross-border cream cheese shipments. Stakeholders must monitor evolving front-of-pack labeling mandates and alternative protein competition in key dairy-consuming markets.
Market Dynamics
Clean-label reformulations and stricter dairy fat standards are forcing manufacturers to rebuild formulation pipelines while maintaining spreadable texture profiles.
Growth Catalysts
- Bakery chain expansion:QSR breakfast menu development across the United States and Canada is pulling cream cheese into standardized food service formats.
- FDA standards of identity:Minimum milk fat thresholds in the United States create formulation clarity that simplifies export-bound production decisions.
- Bagel culture concentration:Per-capita consumption leadership in the United States sustains volume anchors for flavored and premium variants.
Market Restraints
- Raw milk procurement volatility:Multi-source milk procurement requirements expose margins to feed cost fluctuations and seasonal supply gaps.
- European Union dairy fat standards:Stricter thresholds in EU member states redirect R&D spending away from volume markets toward compliance documentation.
- Plant-based cream cheese substitution:Alternative protein competition in North American retail is compressing shelf space allocation for conventional formats.
Strategic Opportunities
- Underpenetrated dessert bases:European bakery applications remain fragmented relative to United States penetration, offering white space for flavored variant introduction.
- EFSA pathogen control alignment:Harmonized EU safety documentation enables cross-border shipment scale-up for compliant manufacturers.
- Direct dairy farm partnerships:Backward integration into Wisconsin and Quebec milk supply is reducing procurement cost volatility for North American producers.
Industry Challenges
- Clean-label gum replacement:Carrageenan and stabilizer reformulation requires texture scientists capable of replicating spreadability without standard hydrocolloids.
- Front-of-pack labeling compliance:Evolving EU and United States disclosure mandates are forcing packaging redesign cycles that compress marketing calendars.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cream Cheese Market |
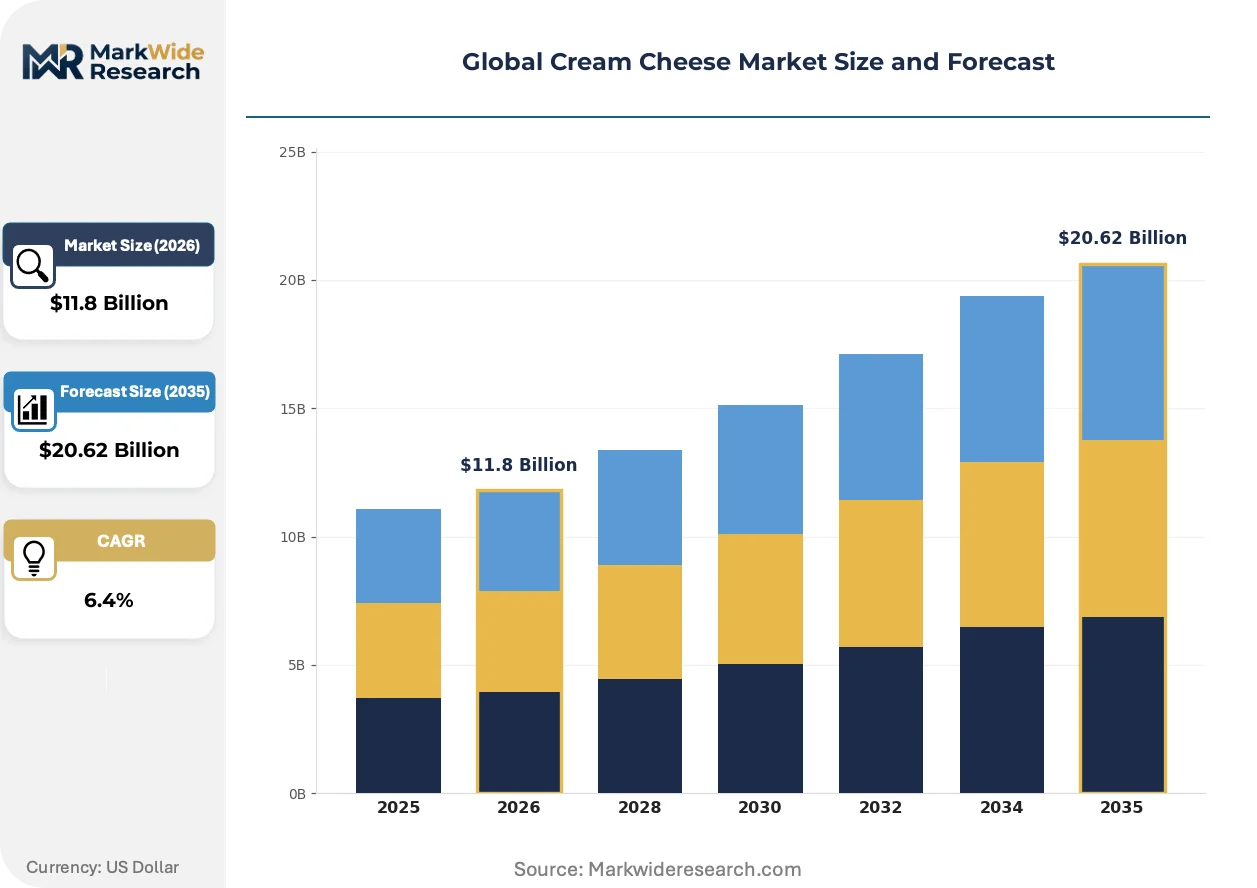
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Regular, Neufchâtel, Whipped, Flavored Packaging Type: Cup, Tub, Pouch, Single Serve Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Food Service End User: Households, Restaurants, Bakeries, Food Manufacturers |
| Companies Covered | Danone S.A., Saputo Inc., The Kraft Heinz Company, FrieslandCampina N.V., Savencia Fromage & Dairy, Lactalis Group, Fonterra Co-operative Group, Schreiber Foods, Arla Foods Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cream Cheese Market Emerging Trajectories
Formulation science and procurement control are rewriting how cream cheese manufacturers defend margin position against input cost pressure and clean-label mandates.
High-pressure processing is rewriting pathogen control economics for fresh unripened soft cheese. Mid-size United States dairies are adopting HPP lines at twice the historical rate to bypass thermal degradation of flavor compounds. The technology is rewriting the tradeoff between shelf-life extension and sensory quality that has constrained refrigerated distribution radius.
EU Green Deal farm-to-fork targets are tightening methane intensity benchmarks for dairy cooperatives supplying cream cheese production. FrieslandCampina's Dutch members face 2030 reduction mandates that require feed additive investments and manure management capex. German and French dairy regulators are aligning national enforcement with Brussels timelines, compressing compliance windows for cross-border suppliers.
Food service buyers are consolidating procurement around controlled distribution networks that demand private-label manufacturing scale. Bakery chains in the United States are displacing fragmented distributor relationships with direct contracts to single-source cream cheese producers capable of national refrigerated logistics. This concentration is most visible in the Northeast corridor, where bagel shop franchising has standardized spread specifications across hundreds of locations.
Global Cream Cheese Market Segmentation
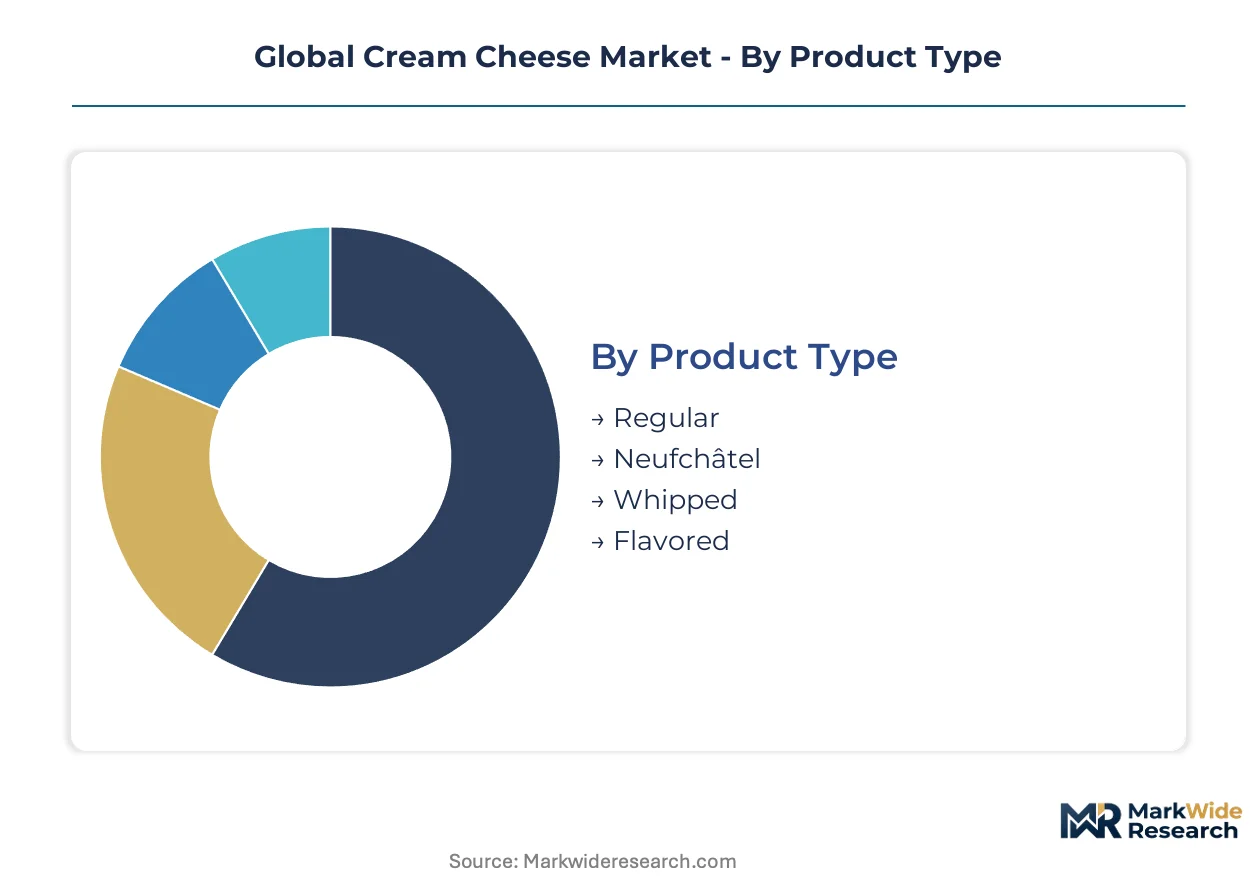
Cream cheese segmentation reflects divergent regulatory burdens across product formats and distribution pathways. FDA standards of identity govern fat content thresholds differently for regular versus Neufchâtel varieties, while EFSA pathogen controls intensify for food service volumes crossing EU borders.
Product Type:
FDA standards of identity impose distinct milk fat minimums across formats, with regular cream cheese requiring 33% fat versus Neufchâtel's 20-33% range. EFSA labeling requirements for fresh unripened soft cheese apply uniformly, though flavored variants face additional additive disclosure thresholds.
- Regular:Standardized at minimum 33% milk fat with stabilizers for spreadable texture. Demand concentrates in United States bagel shops and home kitchens, constrained by FDA enforcement of filler restrictions that limit cost-reduction formulations.
- Flavored:Fruit, herb, and savory inclusions expand margin pools through premium positioning. Growth concentrates in North American retail as bakery chains standardize flavored spread specifications across franchise networks.
- Neufchâtel:Lower fat content (20-33%) appeals to health-positioned segments. French AOC regulations protect traditional production methods for authentic variants.
- Whipped:Aerated texture achieved through nitrogen injection reduces density and extends yield. Popular in United States tub formats for home spreading applications.
Leading the category by volume: Regular. Growing fastest: Flavored.
Packaging Type:
Packaging selection tracks distribution radius and shelf-life requirements. Refrigerated supply chain economics favor formats that minimize headspace and optimize cube utilization for long-haul logistics.
- Tub:Dominant retail format in North America with resealable lids supporting multi-use consumption. United States supermarkets allocate prime dairy case positioning to 8-ounce and 12-ounce tubs.
- Single Serve:Portion-controlled 1-ounce cups and foil packs accelerate through QSR breakfast programs and airline catering contracts. United States bakery chains standardize on single-serve portions for grab-and-go bagel programs.
- Cup:Glass or plastic cups serve European retail preferences with premium positioning. German and French supermarkets favor cup formats for organic and artisanal cream cheese variants.
- Pouch:Flexible packaging reduces transport cost for food service volumes. Growing adoption in United States institutional feeding programs.
Tub formats command the volume base. Single serve climbs fastest as food service automates portion control.
Distribution Channel:
Channel selection determines regulatory exposure and margin structure. Food service volumes bypass retail labeling mandates but face stricter HACCP documentation for food safety audits.
- Food Service:Direct procurement by bakery chains and QSR operators concentrates volume in controlled distribution networks. United States bagel franchise systems now require single-source cream cheese suppliers capable of national refrigerated logistics.
- Supermarkets:Traditional retail anchors volume in North America and Europe. Shelf space allocation faces compression from plant-based alternatives in United States and German markets.
- Online Retail:E-commerce penetration accelerates in urban United States corridors with cold-chain delivery infrastructure. Subscription models for specialty flavored variants gain traction.
- Convenience Stores:Limited assortment focuses on single-serve and extended-shelf-life formats. United States c-store chains expand breakfast sandwich programs pulling cream cheese volumes.
Supermarkets retain volume leadership. Food service posts the steepest expansion trajectory as bakery chains consolidate procurement.
End User:
End-use segmentation reveals divergent specification requirements. Industrial buyers demand lot traceability and customized fat profiles, while household consumers prioritize price stability and format convenience.
- Bakeries:Commercial operators specify cream cheese for fillings, frostings, and layered desserts. United States bakery chains standardize formulations across hundreds of locations, creating volume anchors for compliant suppliers.
- Food Manufacturers:Industrial buyers incorporate cream cheese into processed desserts, dips, and sauce bases. FDA standards of identity compliance enables export-bound production for multinational CPG brands.
- Households:Retail purchasers drive flavored variant adoption and premium positioning. United States per-capita consumption sustains volume leadership for home spreading and baking applications.
- Restaurants:Full-service operators use cream cheese in appetizer and dessert preparations. Menu innovation in United States independent restaurants tests savory applications beyond traditional breakfast positioning.
Bakeries lead by volume. Food manufacturers gain share fastest as dessert base applications industrialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wisconsin and Quebec dairy belts anchor North American milk solids supply for cream cheese production, while Dutch cooperative structures and French AOC-protected traditions shape European competitive positioning.
United States
Bagel shop franchising and QSR breakfast menu standardization pull cream cheese volumes into controlled distribution networks. FDA standards of identity enforce minimum 33% milk fat thresholds that limit formulation flexibility. New York and Philadelphia metropolitan clusters concentrate food service procurement for bakery chain expansion.
Germany
Industrial bakery demand and retail premium positioning sustain flavored variant growth in German supermarkets. EFSA pathogen controls under EU General Food Law intensify documentation requirements for fresh unripened soft cheese. Bavarian dairy cooperatives invest in feed additive programs to meet EU Green Deal methane reduction mandates.
France
Traditional Neufchâtel production under AOC regulations protects authentic methods while limiting industrial scale-up. ANSM labeling enforcement and front-of-pack disclosure mandates compress packaging redesign cycles. Normandy and Brittany dairy basins concentrate artisanal cream cheese manufacturing for domestic and export markets.
Canada
Quebec dairy supply management stabilizes raw milk procurement costs for cream cheese manufacturers. Health Canada dairy fat standards align with FDA thresholds, simplifying cross-border production decisions. Ontario food service distributors consolidate procurement around single-source suppliers for national bakery chain contracts.
Netherlands
FrieslandCampina's cooperative structure secures consistent milk volumes for European cream cheese production. EU farm-to-fork targets drive 2030 methane reduction investments across Dutch member farms. Rotterdam logistics hubs enable refrigerated distribution radius extension into German and Belgian retail markets.
Global Cream Cheese Market Vendor Landscape
Global majors compete with regional champions across procurement control and distribution reach. The vendor base stratifies between multinational CPG conglomerates with private-label scale and cooperative-structured dairy groups with captive milk supply. Three archetypes dominate: vertically integrated dairy cooperatives, brand-centric consumer goods conglomerates, and food service-focused specialists. Capacity expansion in high-pressure processing lines and backward integration into direct farm partnerships represent the dominant competitive moves.
Within the cooperative archetype, FrieslandCampina N.V. and Fonterra Co-operative Group exemplify member-owned structures that anchor raw material security. Among brand-centric conglomerates, The Kraft Heinz Company occupies a position defined by retail shelf presence and controlled distribution network scale. These three entities represent contrasting strategic foundations—cooperative milk supply security, brand equity monetization, and food service logistics capability—that collectively shape competitive dynamics.
| Leading Market Players |
|---|
| Danone S.A. |
| Saputo Inc. |
| The Kraft Heinz Company |
| FrieslandCampina N.V. |
| Savencia Fromage & Dairy |
| Lactalis Group |
| Fonterra Co-operative Group |
| Schreiber Foods |
| Arla Foods Group |
| Others |
Supply Flow & Price Mechanics
Food service procurement consolidation around bakery chain networks in the United States and Canada anchors a contract-based pricing model where long-term offtake agreements lock in volume commitments against raw milk futures volatility. This buyer concentration compresses spot market liquidity and shifts pricing power toward suppliers with captive dairy farm partnerships.
Pricing Analysis
Warranty and service bundling remains unbundled in cream cheese procurement, with buyers absorbing refrigerated logistics risk separately from product cost. Three-tier pricing structure across premium flavored variants, standard regular formats, and economy private-label tiers dominates retail, while differentiation hinges on FDA standards of identity compliance certification and volume scale commitments. Pricing pressure stems from plant-based substitution squeezing shelf space allocation in North American supermarkets. Private-label buyers exhibit highest price sensitivity; artisanal bakery chains show lowest sensitivity due to specification rigidity.
Supply Chain Analysis
Dual-sourcing requirements from United States bakery chains mandate multi-supplier qualification across at least two of Wisconsin, Quebec, and California dairy belts. Raw material dependencies center on fluid milk, cream, and stabilizer hydrocolloids. Single-source vulnerability concentrates in carrageenan supply from Southeast Asian seaweed processors. Distribution runs through temperature-controlled third-party logistics networks with national refrigerated radius coverage.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Cream Cheese Market functions as a cost-of-compliance story where FDA standards of identity and EFSA pathogen controls erect regulatory moats that favor incumbent producers with documentation infrastructure and certified production lines.
For Market Incumbents: Anticipate clean-label reformulation mandates by investing in texture science capabilities for gum replacement without carrageenan, while consolidating backward integration into direct dairy farm partnerships in Wisconsin and Quebec to neutralize raw milk procurement volatility from feed cost fluctuations. For New Entrants and Emerging Players: Begin with European dessert base applications where bakery penetration remains fragmented relative to United States saturation, targeting German and French industrial bakers with flavored variant introductions through co-manufacturing partnerships that bypass capital-intensive production infrastructure. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size United States dairies with installed high-pressure processing lines in the Upper Midwest, where methane reduction capex burdens under EU Green Deal timelines may force cooperative member exits; watch for inflection when feed additive program subsidies accelerate consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Line Installation | HPP technology bypasses thermal degradation while extending refrigerated distribution radius for fresh unripened soft cheese. |
| Direct Dairy Farm Partnership | Backward integration into Wisconsin and Quebec supply stabilizes raw milk procurement costs against seasonal volatility. |
| Clean-Label Stabilizer Reformulation | Gum replacement R&D addresses EFSA and FDA disclosure mandates while maintaining spreadable texture profiles. |
| Food Service Distribution Network Expansion | National refrigerated logistics capability captures bakery chain consolidation toward single-source procurement contracts. |
| Flavored Variant Premium Positioning | Fruit and savory inclusions expand margin pools in North American retail and European dessert base applications. |
Methodological Framework
Independent corroboration across dairy cooperative procurement officers, food service distribution executives, and bakery chain purchasing managers underwrites the qualitative findings, validated against FDA standards of identity filings, EFSA safety documentation, USDA dairy production statistics, and customs trade records for cream cheese shipments. Bottom-up volume modeling triangulates with top-down category spending analysis.
Rate-of-change decomposition separates volume growth from price/mix effects across the projection horizon, modeling regular, flavored, Neufchâtel, and whipped product types against food service, supermarket, online retail, and convenience store channels. CAGRs derive from segmented trend extrapolation with milk fat standard compliance and clean-label adoption curves as primary forecast inputs.
Underlying measurement precision varies by segment; food service volumes with direct contract disclosure carry tighter precision than fragmented household retail estimates. Forecasts reflect documented assumptions about bakery chain expansion velocity and alternative protein substitution rates. Deviation in EU Green Deal enforcement timelines or FDA standards of identity revision would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Sour Milk Drinks Market
Dairy Products
Global Specialty Cheese Market
Dairy Products
Global Dairy Market
Dairy Products
Mexico Lactose-Free Dairy Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Fermented Dairy Ingredients Market
Dairy Products
Gruyere Market
Dairy Products
Cheddar Cheese Market
Dairy Products
North America Fluid Milk Market
Dairy Products
Donkey Milk Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Cholesterol Reduced Butter Market
Dairy Products
Qatar Dairy Products Market