
 Low-Lactose Dairy Foods Market | 2026-2036
Low-Lactose Dairy Foods Market Size, Share, and Industry Trends Forecast 2026-2036
Low-Lactose Dairy Foods Market Foresight
Plant-based protein formulations are pivoting toward hybrid dairy alternatives that blend low-lactose milk solids with oat or pea isolates, reducing reliance on pure dairy inputs while preserving nutritional density. Arla Foods leverages its Scandinavian farmgate network to secure raw milk with naturally lower lactose content for premium line production. Danone anchors its competitive position through dedicated R&D facilities in France focused on lactase treatment optimization. Valio specializes in patented ultra-filtration methods that remove lactose without compromising protein structure.
Low-lactose dairy foods comprise milk-derived products treated with lactase enzyme or processed through membrane filtration to reduce lactose content below 0.5 grams per 100 milliliters, serving consumers with primary or secondary lactase deficiency. The enzymatic hydrolysis process cleaves lactose into glucose and galactose, yielding sweeter taste profiles without added sugars while maintaining calcium and vitamin bioavailability. Yogurt and milk categories dominate current revenue pools due to established consumption habits and broad retail distribution, though ice cream represents the fastest-growing product type as manufacturers resolve texture challenges in frozen lactose-free formulations. Sports nutrition channels command premium pricing for powdered low-lactose protein isolates targeting athletic recovery segments.
FDA labeling requirements for lactose content declarations shape product positioning and shelf placement in United States retail environments, while EFSA health claim protocols govern how European manufacturers communicate digestive benefits to consumers. The EU F-Gas Regulation indirectly affects processing costs by restricting refrigerants used in cold-chain distribution of temperature-sensitive low-lactose products. Stakeholders must monitor evolving enzyme supplier consolidation and patent expirations that could democratize production technology across mid-tier dairy processors.
Market Dynamics
Lactase immobilization systems are compressing enzymatic treatment costs while simultaneously improving hydrolysis efficiency, fundamentally altering the cost structure for mid-tier dairy processors entering the low-lactose segment.
Growth Catalysts
- FDA Labeling Requirements:Mandatory lactose content declarations in United States retail environments create shelf placement incentives that favor clearly labeled low-lactose products over conventional alternatives.
- Sports Nutrition Channels:Athletic recovery segments command premium pricing for powdered low-lactose protein isolates, expanding the addressable market beyond traditional digestive sensitivity consumers.
- Enzymatic Hydrolysis:Advances in lactase treatment technology yield sweeter taste profiles without added sugars, removing a historical barrier to consumer acceptance in flavored milk categories.
Market Restraints
- Cold-Chain Infrastructure:Temperature-sensitive low-lactose products require specialized refrigerated distribution, with EU F-Gas Regulation restrictions on refrigerants elevating logistics costs for European processors.
- Membrane Filtration Equipment:Ultra-filtration systems for lactose removal without protein denaturation demand substantial capital investment, concentrating production capability among well-capitalized facilities.
- Plant-Based Substitution:Oat and pea protein isolates compete directly for lactose-intolerant consumers, particularly in younger demographics with weaker dairy consumption habits.
Strategic Opportunities
- Ice Cream Texture Innovation:Frozen lactose-free formulations historically suffered from crystallization defects; resolved texture challenges unlock premium positioning in dessert categories.
- Hybrid Protein Blends:Convergence of low-lactose milk solids with oat or pea isolates creates nutritional density advantages that pure plant alternatives cannot match.
- Clean-Label Positioning:United States consumer preferences for minimal ingredient lists favor enzymatically treated products over chemically modified alternatives in mainstream retail.
Industry Challenges
- Patent Expiration Monitoring:Stakeholders must track evolving enzyme supplier consolidation and intellectual property timelines that could democratize production technology across smaller processors.
- EFSA Health Claim Navigation:European manufacturers face complex protocols governing how digestive benefits are communicated to consumers, requiring specialized regulatory affairs capabilities.
- Enzyme Supplier Concentration:Limited sources of industrial-grade lactase create vulnerability to supply disruptions and pricing volatility for hydrolysis-dependent production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low-Lactose Dairy Foods Market |
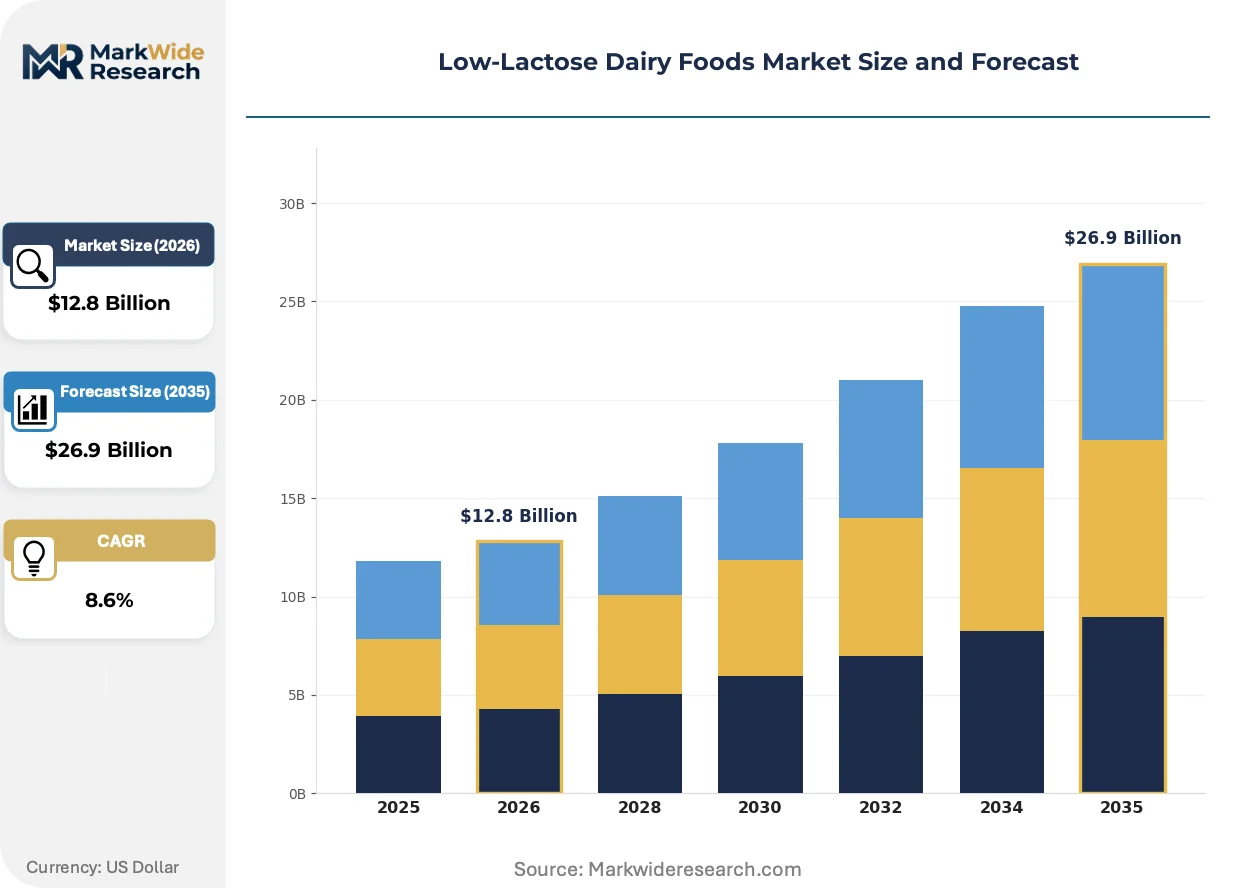
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milk, Cheese, Yogurt, Ice Cream End User: Retail Consumers, Food Service, Health Institutions, Sports Nutrition Distribution Channel: Supermarkets, Online Retail, Specialty Stores, Direct Sales Form: Liquid, Powder, Solid, Freeze-Dried |
| Companies Covered | Arla Foods, Nestlé, Danone, Valio, Lactalis, Fonterra Co-operative Group, General Mills, Organic Valley, Chobani, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low-Lactose Dairy Foods Market Shifts & Advancements
Clean-label preferences and enzymatic efficiency gains are restructuring how low-lactose products are formulated, positioned, and distributed across retail and foodservice channels.
Immobilized lactase reactor technology is converging with continuous-flow processing systems to enable real-time hydrolysis monitoring. Mid-sized United States dairy cooperatives are adopting these systems at accelerating rates to reduce batch variability. This convergence is compressing quality control timelines while expanding the technical feasibility of in-house enzymatic treatment versus outsourced processing.
EU F-Gas Regulation phase-down schedules are forcing cold-chain operators to retrofit refrigeration infrastructure for lower-global-warming-potential alternatives. European low-lactose yogurt and fresh cheese distributors face elevated capital requirements for compliant cold storage. German and French retail chains are responding by consolidating distribution networks to maximize load efficiency on retrofitted vehicles.
Athletic nutrition buyers are consolidating procurement around certified low-lactose protein isolates with third-party digestive tolerance verification. Sports nutrition e-commerce platforms and specialty retailers are displacing conventional brick-and-muscle supplement stores as primary channels. This channel rotation is most pronounced in United States metropolitan markets where direct-to-consumer subscription models capture recurring volume commitments.
Low-Lactose Dairy Foods Market Segmentation
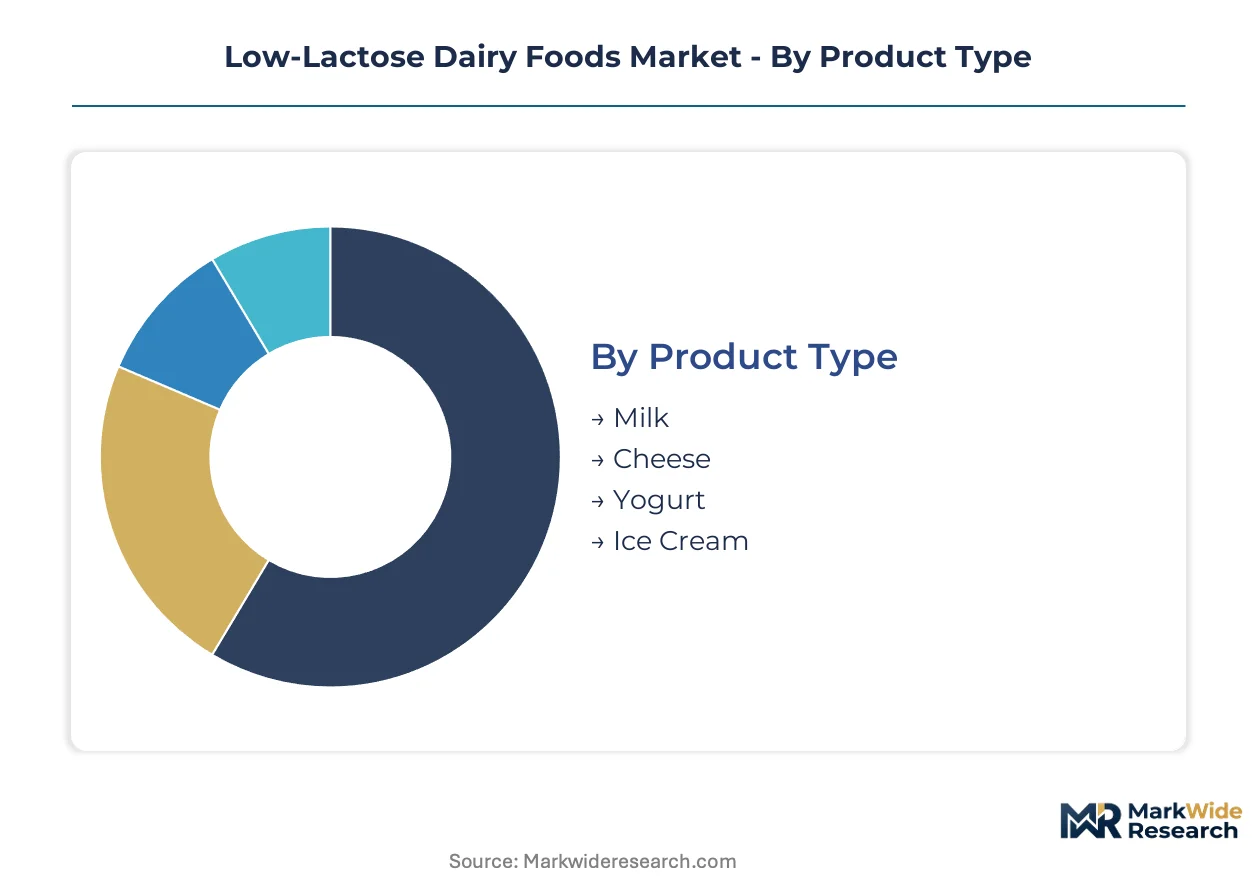
Low-lactose dairy foods segment across four dimensions that determine pricing power, shelf placement, and production technology selection. Each category reveals distinct margin structures and customer acquisition costs that shape processor investment priorities.
Product Type:
Volume concentration sits in everyday consumption formats, while premium positioning clusters in indulgence and functional categories.
- Milk:Enzymatically hydrolyzed fluid milk dominates household penetration due to direct substitution for conventional dairy. United States retail chains allocate expanded shelf space following FDA labeling mandates that favor clear lactose content declarations.
- Yogurt:Fermented low-lactose formulations leverage existing probiotic positioning to justify price premiums over standard yogurt. European demand concentrates in Germany and France where EFSA health claim protocols enable digestive benefit communication.
- Cheese:Aged varieties naturally deplete lactose through bacterial action, reducing enzymatic treatment requirements.
- Ice Cream:Texture innovation has resolved crystallization defects in frozen lactose-free formulations.
Mature deployment sits with Milk. Newer deployment is concentrated in Ice Cream.
End User:
Customer type determines formulation sophistication and channel strategy, with institutional buyers prioritizing cost efficiency over sensory attributes.
- Retail Consumers:Household purchasers with primary or secondary lactase deficiency drive baseline volume through supermarkets and online channels. Clean-label preferences favor enzymatically treated products over chemically modified alternatives in United States mainstream retail.
- Sports Nutrition:Athletic recovery segments command premium pricing for powdered low-lactose protein isolates with third-party digestive tolerance verification. E-commerce platforms and specialty retailers displace conventional supplement stores as primary channels in metropolitan markets.
- Food Service:Restaurant and hospitality procurement emphasizes batch consistency and extended shelf stability for menu integration.
- Health Institutions:Hospital and clinical nutrition programs specify low-lactose formulations for patient dietary management.
Volume leadership belongs to Retail Consumers. Margin expansion concentrates in Sports Nutrition.
Distribution Channel:
Channel selection shapes cold-chain requirements and working capital intensity, with temperature-sensitive products favoring controlled retail environments.
- Supermarkets:Dominant channel for fluid milk and yogurt categories requiring refrigerated display cases. United States chains leverage dedicated low-lactose sections to capture lactose-intolerant shoppers.
- Online Retail:Powdered protein isolates and shelf-stable formats achieve highest penetration through direct-to-consumer subscription models.
- Specialty Stores:Health food and organic retailers stock premium-priced artisanal low-lactose cheese and ice cream varieties.
- Direct Sales:Food service distributors and institutional procurement teams source bulk formats through negotiated supply agreements.
Established infrastructure dominates Supermarkets. Fastest channel expansion occurs in Online Retail.
Form:
Physical state determines enzymatic treatment timing, packaging technology, and reconstitution requirements for end-use flexibility.
- Liquid:Ready-to-drink formats require immediate post-hydrolysis stabilization and refrigerated distribution throughout shelf life.
- Powder:Dehydrated low-lactose milk solids and protein isolates enable ambient storage and extended supply chain reach. Sports nutrition applications favor this form for portion control and transport convenience.
- Solid:Cheese and cultured butter formats achieve lactose reduction through fermentation or membrane filtration rather than enzymatic hydrolysis.
- Freeze-Dried:Emergency preparedness and military ration applications value extended stability without refrigeration dependency.
Production maturity centers on Liquid. Emerging capacity investment targets Powder.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Denmark and the Netherlands concentrate enzymatic processing infrastructure for low-lactose dairy exports. These zones offer accelerated depreciation allowances for cold-chain equipment and reduced corporate tax rates on innovation-derived income.
United States
FDA labeling mandates for lactose content declarations drive supermarket shelf reallocation toward clearly marked low-lactose sections. The 2022 Inflation Reduction Act provisions for domestic food processing modernization support enzymatic hydrolysis equipment upgrades in Wisconsin and California dairy corridors. Chicago and Minneapolis metropolitan areas host the densest retail distribution networks for fluid low-lactose milk.
Germany
Consumer willingness to pay premiums for digestive wellness products sustains yogurt category expansion. EU F-Gas Regulation phase-down schedules force cold-chain retrofits, elevating logistics costs for Bavarian and North Rhine-Westphalia processors. Munich anchors R&D concentration for lactase immobilization reactor systems.
France
EFSA health claim protocols enable precise digestive benefit communication in marketing materials. ANSM oversight of novel food enzymes shapes approval timelines for next-generation hydrolysis treatments. The Brittany dairy basin concentrates artisanal low-lactose cheese production for export markets.
China
Rising diagnosed lactose intolerance rates expand addressable household penetration in tier-one cities. SAMR dairy labeling standards mandate lactose content disclosure on imported and domestic products alike. Yangtze River Delta metropolitan clusters drive e-commerce volume for powdered low-lactose protein formats.
Australia
Sports nutrition channel expansion creates premium pricing opportunities for hydrolyzed whey isolates. TGA therapeutic goods frameworks govern health claim substantiation for digestive tolerance positioning. Victorian dairy processing corridors integrate lactase treatment capacity for Asian export markets.
Low-Lactose Dairy Foods Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with proprietary enzymatic technology holders commanding premium positions in retail and direct-to-consumer channels. The market structure exhibits moderate consolidation at the top tier, where integrated dairy cooperatives leverage captive milk supply and in-house R&D facilities. Three strategic archetypes dominate: Scandinavian farmgate-integrated cooperatives, French nutrition science specialists, and North American organic dairy marketers. Competitive moves concentrate on enzymatic patent licensing arrangements and cold-chain distribution partnerships for temperature-sensitive fresh formats.
Within the cooperative archetype, Arla Foods and Fonterra Co-operative Group represent farmgate-integrated structures with direct raw milk sourcing advantages. Danone occupies a position exemplifying the nutrition science specialist tier, with European R&D facility concentration. Among North American organic marketers, Organic Valley and Chobani sit within the clean-label positioning segment, leveraging consumer preference for minimal ingredient declarations. Valio anchors the filtration technology specialist category through patented ultra-filtration methods. These named entities illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Arla Foods |
| Nestlé |
| Danone |
| Valio |
| Lactalis |
| Fonterra Co-operative Group |
| General Mills |
| Organic Valley |
| Chobani |
| Others |
Supply & Pricing Matrix
Scandinavian farmgate-integrated cooperatives anchor supply-side ownership patterns, compressing procurement timelines for enzymatic inputs while enforcing pricing discipline through captive milk sourcing and in-house lactase treatment capacity.
Pricing Analysis
Premium positioning commands short-lead-time fulfillment for fresh yogurt and fluid milk formats, while spot inventory of powdered protein isolates trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates certified organic enzymatically treated products from conventional hydrolyzed lines and private-label alternatives. Price differentiation hinges on lactose content certification thresholds and cold-chain integrity guarantees. Pricing pressure stems from plant-based oat and pea protein substitution in younger demographics. Food service procurement teams exhibit highest price sensitivity; sports nutrition channels show least.
Supply Chain Analysis
Domestic-content mandates in China's SAMR labeling standards and United States FDA facility registration requirements are reshaping sourcing toward regional enzyme production and local dairy processing infrastructure. Supply concentrates in Denmark, the Netherlands, and Wisconsin for lactase immobilization reactor systems and hydrolysis capacity. Raw material dependencies center on industrial-grade lactase enzymes, specialized membrane filtration membranes, and refrigerated transport refrigerants compliant with EU F-Gas Regulation phase-downs. Single-source vulnerability runs through concentrated enzyme supplier networks. Distribution runs through supermarket refrigerated display networks for liquid formats; ambient e-commerce channels dominate powdered isolates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic hydrolysis technology is displacing legacy membrane filtration methods as the dominant lactose reduction pathway, compressing capital requirements and democratizing production access for mid-tier processors.
For Market Incumbents: Hedge against plant-based substitution by deepening backward integration into lactase enzyme supply through exclusive supplier partnerships or in-house bioreactor capacity. Anchor premium positioning through third-party digestive tolerance certification investment. Defend shelf space allocation by accelerating clean-label product line extensions before patent expirations democratize hydrolysis technology. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription models targeting metropolitan sports nutrition buyers with certified low-lactose protein isolates. White-space concentration sits in ice cream texture innovation and hybrid oat-dairy protein blends where pure plant alternatives fail on nutritional density. The most penetrable segment is frozen dessert categories where crystallization defects historically blocked lactose-free formulation. For Investors and Strategic Acquirers: Distressed-cycle entries favor filtration technology specialists with patented ultra-filtration IP in European dairy basins facing elevated cold-chain retrofit costs from EU F-Gas Regulation compliance. Long-term viability across the projection horizon rests on enzymatic patent licensing revenue streams and captive raw milk sourcing. The signal to watch is lactase supplier consolidation announcements indicating pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Lactase Immobilization Reactor Deployment | Danish and Dutch special economic zones offer accelerated depreciation for enzymatic processing equipment upgrades. |
| Hybrid Protein Blend Formulation | Convergence of low-lactose milk solids with oat isolates creates nutritional density advantages pure plant alternatives cannot match. |
| Cold-Chain Refrigeration Retrofit | German and French retail chains consolidate distribution networks to maximize load efficiency on EU F-Gas compliant vehicles. |
| Third-Party Digestive Tolerance Certification | Sports nutrition e-commerce platforms demand verified low-lactose positioning for athletic recovery segment premium pricing. |
| Direct-to-Consumer Subscription Launch | United States metropolitan markets capture recurring volume commitments for powdered protein isolate formats. |
Research Methodology
Trade databases, regulatory filings, and dairy industry association reports formed the secondary backbone, supplemented by primary interviews with enzymatic processing plant managers, dairy cooperative procurement leads, supermarket category buyers, cold-chain logistics operators, and sports nutrition brand formulation directors. Bottom-up volume modeling triangulated against top-down value estimates derived from production capacity disclosures and retail audit data.
Historical trendline analysis established baseline consumption patterns across product type, end user, distribution channel, and form dimensions. Segmentation modeling incorporated enzymatic treatment technology tier, cold-chain dependency level, and regional regulatory framework clusters. CAGRs were derived from fitted growth curves applied to normalized baseline volumes, with cross-validation against input cost trajectories for lactase enzymes and membrane filtration equipment.
The model assumes a particular technology adoption path; alternative pathways for immobilized lactase reactor diffusion would alter the outlook. Forecasts reflect assumptions around patent expiration timelines, enzyme supplier consolidation patterns, and plant-based protein substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Solidified Yogurt Market
Dairy Products
Fat-Filled Milk Powder Market
Dairy Products
Middle East and Africa Dairy Market
Dairy Products
Asia-Pacific Flavored Milk Market
Dairy Products
Europe Yogurt Market
Dairy Products
Europe Cheese Market
Dairy Products
Low-Calorie Butter Market
Dairy Products
Latin America Cheese Market
Dairy Products
Lactic Butter Market
Dairy Products
Goat Milk Market
Dairy Products
Europe Chocolate Milk Market
Dairy Products
Camel Dairy Market
Dairy Products
Cream and Soft Cheese Market
Dairy Products
Dairy Blends Market
Dairy Products
Milk Fat Fractions Market
Dairy Products
North America Condensed Milk Market