
 Fractionated Fatty Acid Market | 2026-2036
Fractionated Fatty Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Fractionated Fatty Acid Market Foresight
Personal care formulators is unwinding legacy reliance on commodity surfactants toward performance-grade fractionated cuts. KLK OLEO leverages integrated Malaysian palm kernel supply chains to dominate caprylic and capric acid output. Emery Oleochemicals anchors North American demand through backward integration into fatty alcohol and ester derivatives. Wilmar International competes across Southeast Asian bulk supply channels with captive crushing and fractionation assets.
Fractionated fatty acids are distilled or crystallographically separated cuts from hydrolyzed natural oils, typically yielding carbon chain lengths from C8 to C18 with purity grades exceeding 90 percent for pharmaceutical and cosmetic applications. Caprylic and capric acid fractions serve as precursors for medium-chain triglycerides and antimicrobial esters in food and nutraceutical matrices. Lauric acid leads volume throughput due to its dominance in soap and detergent surfactant chains, while capric acid claims the fastest expansion trajectory through pharmaceutical-grade excipient demand. Personal care applications command the deepest margin pools as brand owners certify sulfate-free and naturally derived ingredient lineups.
EMA guidelines on excipient quality and REACH substance registration constrain market access for non-compliant Asian exporters into European pharmaceutical and cosmetic channels. FDA food additive regulations and FSSAI packaging material standards in India shape product specifications for edible-grade fractionated acids across diverging jurisdictional requirements. Stakeholders must monitor feedstock certification fragmentation as mass-balance and segregated supply chain claims become decisive in contract negotiations with multinational personal care and food brands.
Market Dynamics
Personal care brands are forcing feedstock certification upstream through contract terms that reject uncertified palm kernel and coconut supply chains, concentrating bargaining power among integrated Southeast Asian processors.
Growth Catalysts
- EU Green Deal procurement mandates:European cosmetic formulators now require segregated-chain documentation for lauric acid derivatives, pulling volume toward RSPO-certified Malaysian suppliers.
- Sulfate-free surfactant chemistry:Caprylic and capric acid esters are displacing sodium lauryl sulfate in premium shampoo and body wash formulations across North American and European personal care channels.
- Pharmaceutical excipient grade expansion:EMA quality guidelines for parenteral drug delivery systems are expanding demand for capric acid fractions above 99% purity in European sterile manufacturing.
Market Restraints
- Feedstock price volatility:Crude palm kernel oil fluctuates with Malaysian ringgit exchange rates and Indonesian export levy adjustments, compressing fractionation margins unpredictably.
- Geographic supply concentration:Over 70% of global C8-C14 fractionation capacity sits within 500 kilometers of Port Klang and Surabaya, exposing buyers to port congestion and regional climate disruption.
- Regulatory fragmentation:Diverging FDA food additive classifications versus EFSA novel food opinions create formulation lock-in, preventing standardized global product launches.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's accelerating drug master file approvals for imported excipients opens a 1.4 billion-population market for caprylic acid-based drug delivery systems.
- Mass-balance certification arbitrage:Book-and-claim systems allow European brands to meet CSRD disclosure requirements while sourcing from mixed-certified Asian supply pools at lower premiums than fully segregated chains.
- Biotechnology convergence:Microbial fermentation of C8-C12 fatty acids from sugar feedstocks is creating synthetic alternatives that bypass agricultural commodity cycles entirely.
Industry Challenges
- Specialized process engineering talent:Crystallographic fractionation and molecular distillation operations require technicians trained in thermal separation physics, a skillset concentrated among retiring European and Japanese specialists.
- Multi-jurisdiction certification timelines:REACH substance registration for new fractionated acid derivatives demands 18-24 month dossier preparation, delaying product commercialization against faster-moving competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fractionated Fatty Acid Market |
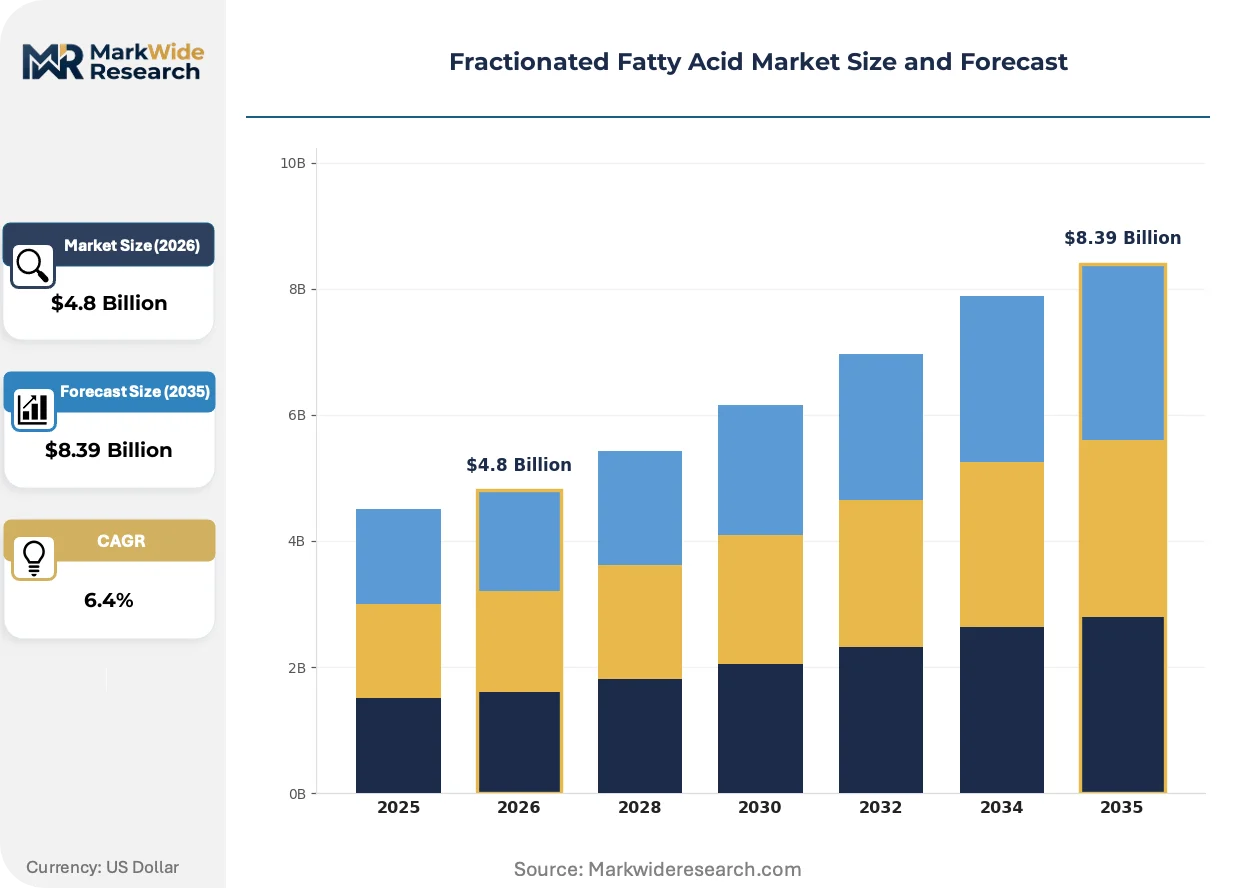
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caprylic Acid, Capric Acid, Lauric Acid, Myristic Acid, Palmitic Acid Application: Food & Beverage, Personal Care, Animal Nutrition, Pharmaceuticals, Industrial Lubricants End Use Industry: Cosmetics Manufacturing, Veterinary Nutrition, Nutraceuticals, Polymer Production, Candle Fabrication Packaging Type: Drums, Bulk Bags, Intermediate Bulk Containers, Totes, Cartridge Containers |
| Companies Covered | Twin Rivers Technologies, KLK OLEO, Emery Oleochemicals, Vantage Specialty Chemicals, Oleon NV, BASF SE, AAK, PMC Biogenix, Wilmar International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fractionated Fatty Acid Market Shifts & Advancements
Fractionation technology and certification systems are diverging along performance-grade versus commodity-grade lines, with capital allocation following divergent customer willingness to pay for chain-of-custody documentation.
Supercritical CO2 extraction is bifurcating the caprylic and capric acid purification market. European pharmaceutical manufacturers are adopting this solvent-free technology for excipient-grade output above 99.5% purity. The process is compressing demand for traditional high-vacuum distillation equipment in premium segments while leaving commodity surfactant grades to legacy crystallization methods.
REACH substance registration deadlines are compressing market access for Asian exporters without European legal entity representation. ECHA's 2023 update to guidance on substance identity for UVCB substances created additional testing burdens for palm-derived complex mixtures. Small and mid-sized Indonesian processors are responding by partnering with Rotterdam-based regulatory consultancies to maintain European cosmetic and pharmaceutical channel presence.
Brand-led supply chain auditing is replacing third-party certification as the primary trust mechanism. Unilever and L'Oréal procurement teams now conduct direct mill and refinery inspections in Malaysia and Indonesia, bypassing RSPO mass-balance claims they view as insufficiently granular. This behavioral shift is most visible in personal care, where ingredient storytelling requirements demand photographic and GPS-tagged provenance documentation that certification bodies cannot provide.
Fractionated Fatty Acid Market Segmentation
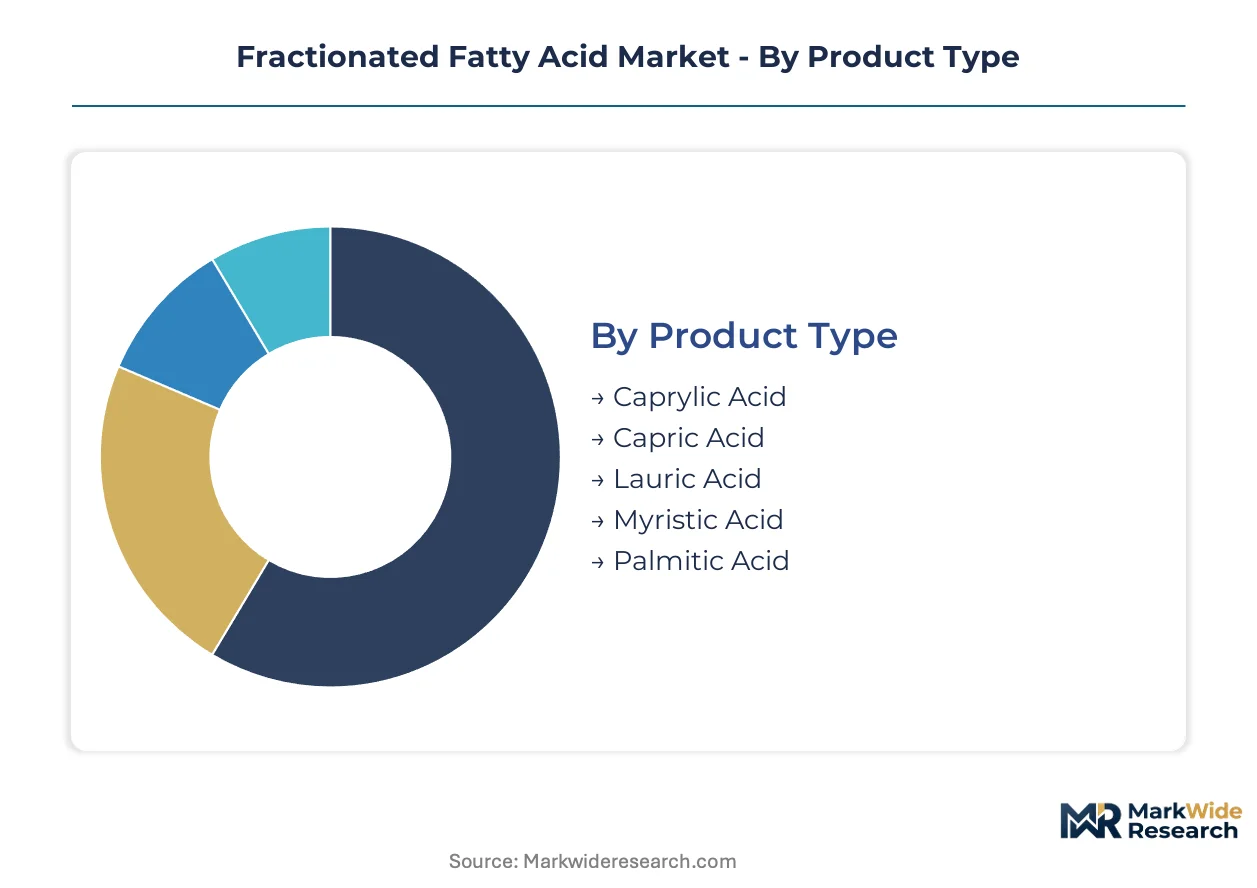
Fractionated fatty acid procurement patterns diverge sharply across product cuts and end-use channels. Certification requirements and purity specifications fragment the addressable market into distinct commercial tiers with divergent margin structures.
Product Type:
Export-led demand concentrates in C8-C12 fractions for pharmaceutical and nutraceutical channels, while domestic consumption across Southeast Asia absorbs lauric acid for soap and detergent manufacturing.
- Caprylic Acid:An eight-carbon saturated fatty acid refined to 99%+ purity grades for parenteral drug delivery systems. European pharmaceutical manufacturers in Germany and Switzerland are expanding offtake for medium-chain triglyceride formulations, constrained by EMA excipient quality dossier requirements.
- Capric Acid:A ten-carbon fraction commanding premium pricing in antimicrobial ester applications. North American personal care brands in California and New Jersey are substituting capric acid esters for sulfate surfactants, pulling Malaysian export volumes toward RSPO-segregated certification tiers.
- Lauric Acid:Twelve-carbon workhorse for surfactant chains across Indian and Indonesian domestic soap markets.
- Myristic Acid:Fourteen-carbon cut serving cosmetic emollient formulations in Japanese and South Korean skincare manufacturing.
- Palmitic Acid:Sixteen-carbon fraction supplying candle fabrication and polymer plasticizer channels across Brazilian and Mexican industrial buyers.
Lauric acid commands the established base. The steepest expansion runs through capric acid.
Application:
Cost-tier stratification separates pharmaceutical-grade specifications from commodity surfactant volumes, with certification premiums widening the price spread between tiers.
- Food & Beverage:Medium-chain triglyceride production for infant nutrition and sports supplements. FDA food additive classifications and FSSAI packaging standards in India create divergent formulation lock-in for edible-grade fractionated acids.
- Personal Care:Sulfate-free surfactant systems and naturally derived emulsifiers. L'Oréal and Unilever procurement teams are forcing direct mill audits in Malaysia, bypassing traditional certification bodies for GPS-tagged provenance documentation.
- Animal Nutrition:Energy-dense feed additives for poultry and swine operations across Vietnam and Thailand.
- Pharmaceuticals:Excipient-grade fractions for sterile drug delivery, constrained by REACH substance registration timelines.
- Industrial Lubricants:Ester-base stocks for biodegradable metalworking fluids in German automotive supply chains.
Personal care applications generate the deepest margin pools. Food and beverage channels are climbing fastest on nutraceutical demand.
End Use Industry:
Customer-type concentration drives packaging and logistics specifications, with multinational cosmetics manufacturers demanding lot-level traceability unavailable to polymer and candle producers.
- Cosmetics Manufacturing:Premium emollients and surfactants for skincare and haircare formulations. CDSCO's accelerating drug master file approvals in India are opening excipient channels previously blocked by import documentation barriers.
- Veterinary Nutrition:Medium-chain fatty acid supplementation for livestock gut health optimization.
- Nutraceuticals:Dietary supplement-grade MCT oils and encapsulated fatty acid delivery systems.
- Polymer Production:Plasticizer and lubricant additives for PVC processing across Chinese manufacturing clusters.
- Candle Fabrication:Stearic acid blends for hardness and burn characteristics in North American retail channels.
Cosmetics manufacturing anchors volume throughput. Nutraceutical end-use is expanding most quickly on functional food convergence.
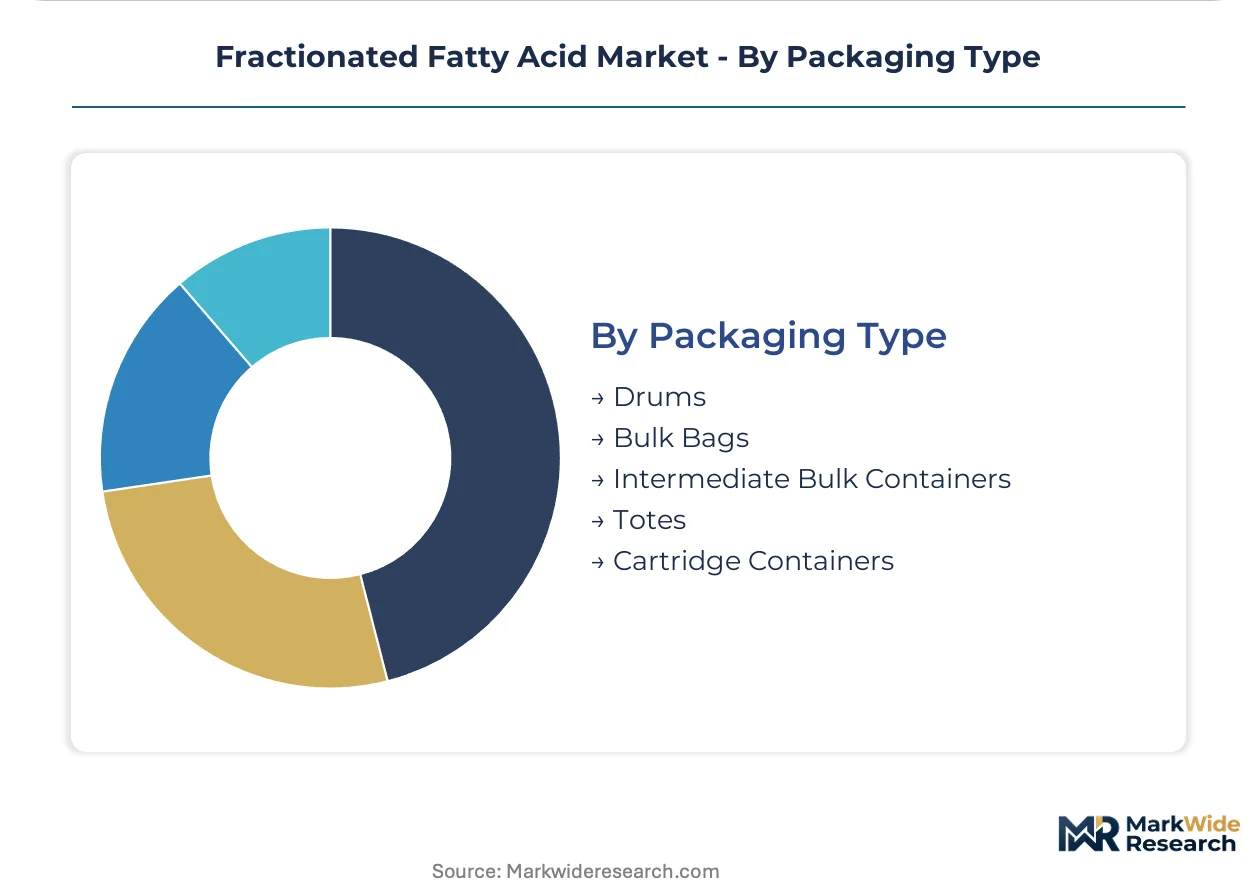
Packaging Type:
Supply concentration around Port Klang and Surabaya dictates bulk logistics economics, with drum and tote formats dominating pharmaceutical and personal care shipments requiring contamination control.
- Drums:Stainless steel and epoxy-lined containers for pharmaceutical and cosmetic-grade fractions. European importers through Rotterdam are specifying UN-certified drum fleets with tamper-evident sealing for excipient-grade caprylic acid.
- Bulk Bags:Flexible intermediate bulk containers for lauric acid shipments to Indian soap manufacturers.
- Intermediate Bulk Containers:Reusable totes for integrated oleochemical processors with captive filling operations.
- Totes:Polyethylene containers for personal care compounders in New Jersey and California.
- Cartridge Containers:Specialized formats for pharmaceutical sampling and clinical trial material distribution.
Drum formats command the established base. IBC configurations are gaining share fastest on sustainability and handling efficiency priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian exporters ship lauric and caprylic acid fractions to Rotterdam and Hamburg for European pharmaceutical and personal care compounders. Indonesian processors serve Indian soap manufacturers through Port of Chennai bulk terminals. This trade architecture concentrates procurement leverage among Southeast Asian integrated oleochemical houses.
Malaysia
Caprylic acid exports to German pharmaceutical manufacturers climb on EMA excipient quality requirements. The Malaysian Palm Oil Board enforces MSPO certification standards for domestic processors. Port Klang clusters host integrated fractionation plants supplying RSPO-segregated lauric acid to Unilever and L'Oréal procurement teams.
Indonesia
Surabaya-based processors export capric acid fractions to California personal care formulators seeking sulfate-free surfactant alternatives. The Indonesian Sustainable Palm Oil certification program tightens export documentation for EU-bound shipments. Oleochemical capacity expansion continues in East Java to serve Indian and Chinese detergent manufacturers.
Germany
Specialty chemical distributors in Hamburg and Frankfurt import pharmaceutical-grade caprylic acid for parenteral drug delivery formulations. REACH substance registration requirements filter Asian suppliers without European legal entity representation. The Rhine-Ruhr industrial corridor hosts formulation facilities for medium-chain triglyceride nutraceutical production.
India
CDSCO's accelerating drug master file approvals open excipient channels for Malaysian caprylic acid imports into Mumbai and Ahmedabad pharmaceutical clusters. FSSAI packaging material standards shape edible-grade fractionated acid specifications for domestic food manufacturers. Tamil Nadu and Gujarat soap producers absorb lauric acid volumes from Indonesian bulk shipments.
United States
California and New Jersey personal care brands substitute capric acid esters for sodium lauryl sulfate in premium shampoo formulations. FDA food additive classifications constrain MCT oil labeling claims for sports supplement manufacturers. Gulf Coast oleochemical processors blend imported Southeast Asian fractions with domestic fatty alcohol production.
Fractionated Fatty Acid Market Competitive Landscape
Listed leaders compete with private specialists across certification tier and geographic coverage dimensions. The vendor base stratifies into three tiers: integrated Southeast Asian processors with captive palm kernel supply, European specialty distributors with REACH compliance infrastructure, and North American compounders with backward integration into fatty alcohol derivatives. Two dominant competitive moves define current positioning: direct mill auditing partnerships with multinational personal care brands and mass-balance certification arbitrage to meet CSRD disclosure requirements at lower premium costs than fully segregated chains.
Within the integrated processor tier, KLK OLEO and Wilmar International exemplify Southeast Asian supply chain control, while Emery Oleochemicals anchors North American demand through captive production assets. These three names represent divergent geographic anchoring strategies—Malaysian palm kernel integration versus Indonesian bulk supply channels versus North American downstream formulation proximity—each commanding distinct certification premium capture in personal care and pharmaceutical channels.
| Leading Market Players |
|---|
| Twin Rivers Technologies |
| KLK OLEO |
| Emery Oleochemicals |
| Vantage Specialty Chemicals |
| Oleon NV |
| BASF SE |
| AAK |
| PMC Biogenix |
| Wilmar International |
| Others |
Supply & Pricing Matrix
Integrated fractionation capacity above 200,000 tonnes annually at Port Klang and Surabaya compresses unit costs by 15-20 percent against smaller European or North American facilities, anchoring price floors for C8-C14 cuts while concentrating bargaining power among Malaysian and Indonesian processors serving RSPO-segregated contract demand.
Pricing Analysis
High-vacuum distillation equipment pricing diverges from supercritical CO2 extraction premiums by 40-60 percent at equivalent purity thresholds. Three-tier pricing structure across pharmaceutical-grade excipient, personal care-certified, and commodity surfactant levels separates buyers by documentation burden and purity specification. Pricing pressure stems from Malaysian ringgit volatility and Indonesian export levy adjustments compressing fractionation margins unpredictably. Indian soap manufacturers exhibit highest price sensitivity on lauric acid bulk shipments, while German pharmaceutical compounders absorb premiums for EMA-compliant caprylic acid dossiers.
Supply Chain Analysis
Port congestion at Port Klang and container availability constraints on the Asia-Europe trade lane inflate inbound logistics costs by 8-12 percent during monsoon quarters. Geographic supply concentrates in Malaysia, Indonesia, and the Philippines, with over 70 percent of global C8-C14 fractionation capacity clustered within 500 kilometers of Surabaya. Raw material dependencies center on crude palm kernel oil, coconut oil, and hydrolyzed fatty acid feedstocks. Single-source vulnerability from Indonesian export policy shifts creates supply chain risk. Distribution runs through Rotterdam bulk terminals for European pharmaceutical channels and Chennai for Indian domestic soap absorption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology convergence on microbial fermentation of C8-C12 fatty acids from sugar feedstocks represents a technological inflection threatening agricultural commodity cycles, while EU Green Deal procurement mandates accelerate certification tier fragmentation.
For Market Incumbents: Compound backward integration into certified-sustainable palm kernel estates to defend RSPO-segregated contract share against emerging fermentation alternatives. Expand molecular distillation capacity in East Java to capture Indian pharmaceutical excipient demand as CDSCO accelerates drug master file approvals. Certification investment in mass-balance book-and-claim systems preserves margin capture against fully segregated chain premiums.
For New Entrants and Emerging Players: CDSCO fast-track excipient registration opens white-space penetration into Mumbai and Ahmedabad pharmaceutical clusters previously blocked by import documentation barriers. Target Indian domestic MCT oil nutraceutical formulation as the most penetrable segment given FSSAI packaging standard convergence. Pursue toll manufacturing partnerships with Surabaya-based fractionators to bypass capital-intensive distillation asset requirements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated Southeast Asian processors with captive palm kernel supply and long-term offtake contracts to Unilever and L'Oréal procurement teams. Five-to-ten year viability favors processors with REACH-compliant European legal entity infrastructure. Acquisition target archetype: mid-cap Indonesian fractionators with Surabaya port access and incomplete certification coverage. Signal to watch: ECHA substance identity guidance updates for UVCB substances compressing market access timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Feedstock Estates | Secures RSPO-segregated supply chains for L'Oréal and Unilever procurement compliance. |
| Supercritical CO2 Capacity Addition | Captures German pharmaceutical excipient premiums above 99.5% purity thresholds. |
| CDSCO Regulatory Fast-Track Investment | Unlocks Mumbai pharmaceutical cluster demand for caprylic acid drug delivery systems. |
| Mass-Balance Certification Arbitrage | Enables European brand CSRD disclosure compliance at lower premium than segregated chains. |
| Fermentation Technology Partnership | Diversifies beyond agricultural commodity cycles through microbial C8-C12 production. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with oleochemical plant managers, procurement leads at personal care OEMs, European regulatory affairs directors, and Indian pharmaceutical formulation scientists; and secondary validation through customs trade data, Malaysian Palm Oil Board production statistics, ECHA REACH registration databases, and SEC filings from listed processors. Bottom-up capacity modeling triangulated against top-down demand segmentation across pharmaceutical, personal care, and food channels.
Across the analysis window, forecasts applied a segmented growth framework by product cut, certification tier, and regional regulatory cluster. CAGRs derived from historical volume trajectories adjusted for EMA excipient quality guideline implementation and EU Green Deal procurement mandate phase-ins. Industry-specific inputs included Malaysian ringgit exchange rate sensitivity models and Indonesian export levy policy scenario testing.
Underlying assumptions cover sustained RSPO certification adoption rates and REACH substance registration timeline stability, with deviation risk concentrated in biotechnology fermentation cost curves and palm kernel oil price volatility. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Components and Additives
Flavonoids Market
Food Components and Additives
Inulin and Fructooligosaccharide Market
Food Components and Additives
Europe Food Anti Caking Agents Market
Food Components and Additives
Canada Food Hydrocolloids Market
Food Components and Additives
Russia Food Hydrocolloids Market
Food Components and Additives
North America Food Hydrocolloids Market
Food Components and Additives
Bergamot Polyphenol Ingredient Systems Market
Food Components and Additives
Global Food Carbohydrase Market
Food Components and Additives
Europe Omega-3 for Food Application Market
Food Components and Additives
Food Premix Market
Food Components and Additives
Spain Food Hydrocolloids Market
Food Components and Additives
Europe Food Stabilizers Market
Food Components and Additives
Europe Food Preservatives Market
Food Components and Additives
Food Grade Calcium Carbonate Market
Food Components and Additives
Europe Food Premix Market
Food Components and Additives
Food Hydrocolloids Market