
 Non-Fat Milk Market | 2026-2036
Non-Fat Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Fat Milk Market Analytics
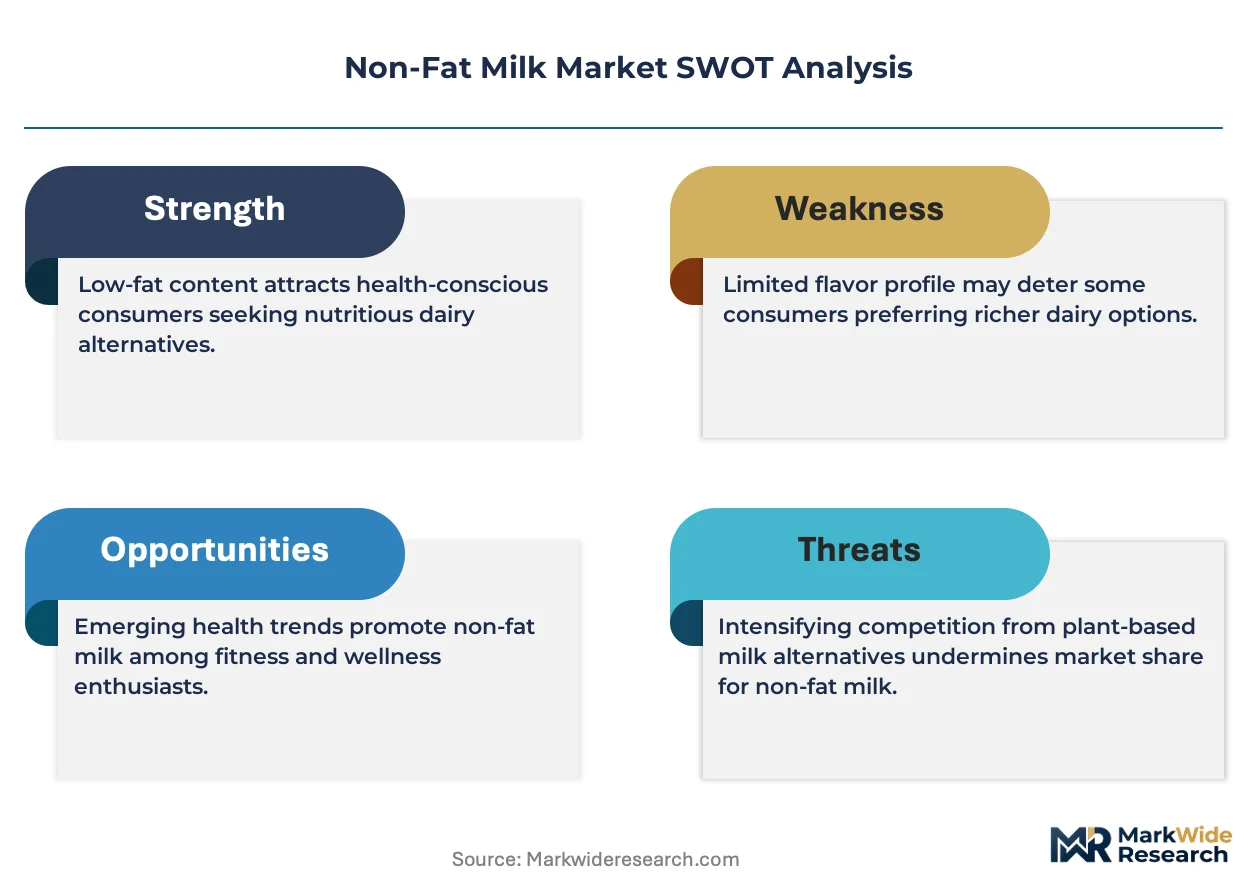
Plant-based creamers are hardening competition for traditional fluid non-fat milk in cafe channels. Fonterra Co-operative Group leverages its New Zealand sourcing base to sustain bulk ingredient supply for industrial bakeries. Nestlé SA anchors retail shelf presence through UHT portfolio breadth across European markets. Danone SA differentiates via probiotic-enhanced non-fat formulations targeting health-conscious households.
Non-fat milk denotes fluid or dried dairy product containing less than 0.5% milkfat by weight, produced through centrifugal separation followed by standardization to 8.25% non-fat solids. The ingredient serves as a protein-fortified base for recombined dairy products, nutritional beverages, and baked goods requiring moisture without added fat. Powdered non-fat milk commands the largest volume share due to extended shelf stability and lower logistics costs in cross-border trade. Liquid non-fat milk retains margin concentration in premium private-label contracts with supermarket chains. UHT non-fat milk is gaining fastest in tropical markets where cold-chain infrastructure remains fragmented.
The FDA enforces Grade A Pasteurized Milk Ordinance standards that govern pathogen limits and sanitary processing for interstate non-fat milk commerce. The USDA administers federal milk marketing orders that set minimum prices for non-fat solids, directly influencing processor margins and farmgate returns. The EU Green Deal's Farm to Fork strategy tightens methane emission benchmarks for dairy cooperatives supplying defatted milk ingredients. Stakeholders must monitor how carbon border adjustment mechanisms reshape competitive access for New Zealand and Australian exporters into European food manufacturing supply chains.
Market Dynamics
Centrifugal separation efficiency gains are compressing processor margins while expanding supply availability, forcing cooperatives to differentiate through fortification and shelf-stable formats rather than commodity volume.
Growth Catalysts
- India's PLI scheme for food processing:The Production Linked Incentive scheme subsidizes cold-chain infrastructure buildout, enabling AMUL and regional dairy federations to extend defatted milk distribution into rural hinterlands previously unreachable.
- Bakery sector reformulation:Industrial bakeries are substituting fresh fluid milk with powdered non-fat equivalents to eliminate spoilage risk and lock input costs across multi-month production cycles.
- UHT technology diffusion:Tetra Pak aseptic filling systems are penetrating tropical markets where refrigeration gaps previously limited liquid dairy penetration, unlocking new consumption occasions.
Market Restraints
- Skim milk powder price volatility:Global dairy auction clearing prices at Fonterra's GDT platform swing 15-40% within quarters, destabilizing bakery and confectionery procurement budgets.
- EU methane benchmarks:The Farm to Fork strategy's emission ceilings are raising compliance costs for defatted milk powder exports into European food manufacturing supply chains.
- Oat and almond protein concentrates:Barista-grade plant creamers achieving foam stability parity are displacing fluid non-fat milk in specialty coffee channels across urban centers.
Strategic Opportunities
- Sub-Saharan Africa cold-chain gaps:Powdered non-fat milk bypasses refrigeration requirements entirely, positioning suppliers to capture institutional demand from humanitarian feeding programs and school nutrition initiatives.
- Probiotic strain integration:Lactobacillus and Bifidobacterium fortification creates premium positioning in functional dairy segments where consumers pay for digestive health claims.
- Direct-to-bakery bulk dispensing:Tanker-delivered liquid concentrate systems eliminate bagged powder handling labor for industrial-scale bread and pastry manufacturers.
Industry Challenges
- Aseptic technician scarcity:UHT line operators require HACCP certification and thermal processing expertise that dairy cooperatives struggle to recruit outside established production clusters.
- FDA Grade A compliance timelines:Interstate fluid milk licensing demands 90-180 day facility inspection queues that delay new plant commissioning and capacity expansion.
- Legacy ERP integration:Dairy processors running 1990s-era manufacturing execution systems face data architecture gaps when connecting to modern traceability platforms demanded by retail buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Fat Milk Market |
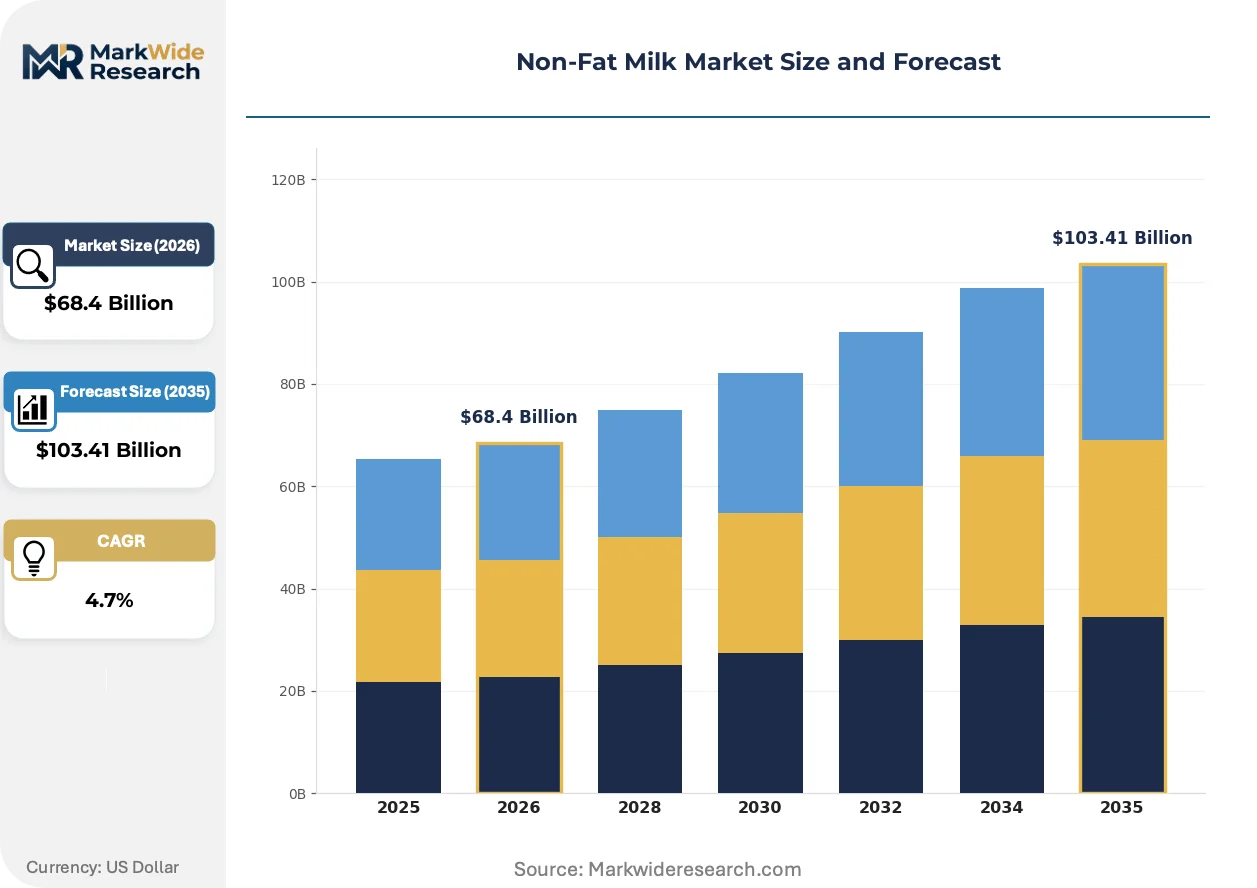
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Non-Fat Milk, Powdered Non-Fat Milk, UHT Non-Fat Milk, Flavored Non-Fat Milk Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Specialty Dairy Shops End User: Households, Cafes, Restaurants, Bakeries Packaging Type: Bottles, Tetra Pak, Cartons, Sachets |
| Companies Covered | Dairy Farmers of America, Nestlé SA, Arla Foods amba, Danone SA, Fonterra Co-operative Group, Glanbia plc, All American Foods Inc, AMUL, Hilmar Cheese Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Fat Milk Market Evolving Landscape
Membrane filtration advances and enzymatic processing are unlocking protein fractionation capabilities that transform non-fat milk from a commodity input into a precision ingredient platform for nutrition and functional food formulators.
Microfiltration and ultrafiltration cascades are rewriting protein recovery economics in whey and milk protein concentrate production. Ingredient suppliers are deploying ceramic membrane systems to harvest native micellar casein for sports nutrition applications. This technology is compressing the premium gap between commodity skim milk powder and specialized protein isolates.
The EU Green Deal's carbon border adjustment mechanism is tightening emission disclosure requirements for dairy ingredients entering European food manufacturing. Processors must now document farm-level methane and energy inputs across their supply bases. New Zealand exporters are investing in on-farm anaerobic digesters to preserve quota access into EU recombined dairy product channels.
Contract structures are shortening from annual to quarterly price resets as bakery and beverage manufacturers seek flexibility amid powder price volatility. Procurement teams are blending spot auction purchases with forward cover to manage margin exposure. This pattern is most pronounced in Southeast Asian markets where currency fluctuations compound commodity risk.
Non-Fat Milk Market Segmentation
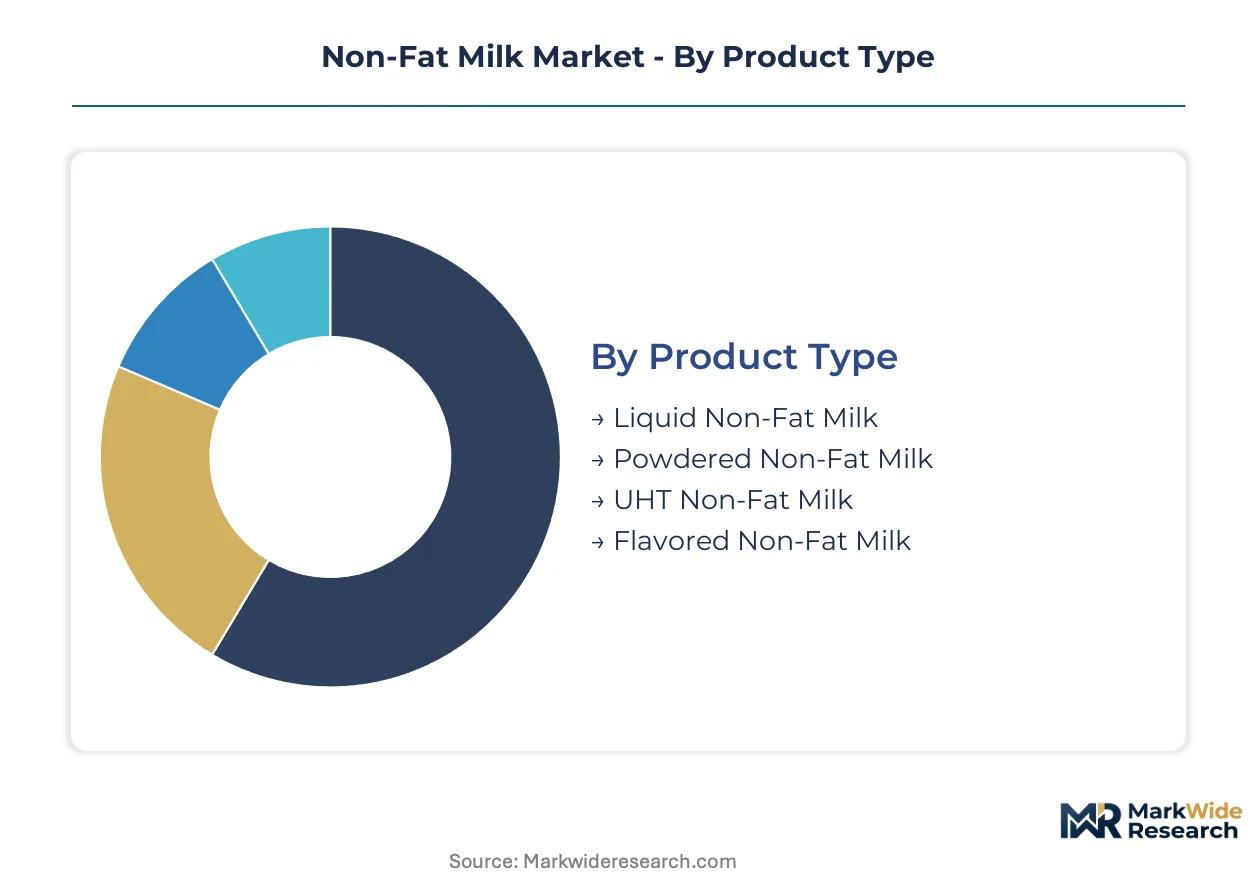
Non-fat milk processors must navigate divergent certification pathways across product formats, with fluid variants requiring Grade A Pasteurized Milk Ordinance compliance while dried products face international sanitary standards. Segmentation reveals how regulatory burden, shelf stability, and channel economics allocate margin across distinct supply chains serving household, foodservice, and industrial demand.
Product Type:
FDA Grade A certification governs interstate fluid commerce, while Codex Alimentarius standards apply to powdered exports; UHT formats require additional thermal processing validation.
- Liquid Non-Fat Milk:Fluid dairy containing less than 0.5% milkfat by weight, standardized to 8.25% non-fat solids. Cold-chain dependency limits distribution radius to 300-400 miles from processing plants, concentrating demand in premium private-label contracts with supermarket chains seeking regional freshness claims.
- Powdered Non-Fat Milk:Spray-dried or roller-dried concentrate with moisture content below 5%, enabling 12-24 month shelf stability. Institutional procurement from humanitarian feeding programs and school nutrition initiatives in Sub-Saharan Africa drives volume, bypassing refrigeration infrastructure gaps entirely.
- UHT Non-Fat Milk:Aseptically processed at 135-150°C for 2-8 seconds, packaged in sterile barrier materials. Tetra Pak filling systems penetrate tropical markets where fragmented cold chains previously excluded liquid dairy.
- Flavored Non-Fat Milk:Fortified with vanilla, chocolate, or strawberry formulations targeting pediatric nutrition. Added sugars and stabilizers trigger separate FDA labeling requirements under the updated nutritional disclosure standards.
Leading the category by volume: Powdered Non-Fat Milk. Growing fastest: UHT Non-Fat Milk.
Distribution Channel:
Channel economics stratify sharply between high-volume supermarket contracts with 90-day payment terms and cash-positive convenience store networks with rapid inventory turns.
- Supermarkets:Dominant volume channel commanding 30-45 day shelf space negotiations and exclusive private-label manufacturing agreements. Retail buyers demand full traceability platform integration, excluding processors running legacy ERP systems.
- Online Retailers:Direct-to-consumer fulfillment requiring temperature-controlled last-mile logistics for fluid variants. Powdered formats thrive here due to shipping weight efficiency and damage resistance.
- Convenience Stores:Impulse-driven single-serve purchases with premium pricing tolerance. UHT shelf-stable formats dominate this channel.
- Specialty Dairy Shops:Curated local and organic positioning with direct farm relationships. Limited scale but highest per-unit margins.
Supermarkets capture the largest revenue pool. Online Retailers expand most quickly.
End User:
Procurement sophistication varies dramatically: bakeries negotiate quarterly price resets while households accept retail markups.
- Households:Retail consumers prioritizing convenience and health claims. Probiotic-enhanced formulations command premium positioning.
- Cafes:Specialty coffee channels where oat and almond protein concentrates now achieve foam stability parity, displacing fluid non-fat milk in urban centers.
- Restaurants:Foodservice operators balancing portion control with labor efficiency. UHT portion packs reduce spoilage waste.
- Bakeries:Industrial-scale manufacturers substituting fresh fluid milk with powdered equivalents to eliminate spoilage risk and lock input costs across multi-month production cycles.
Bakeries dominate institutional procurement. Cafes face the steepest displacement pressure from plant-based alternatives.
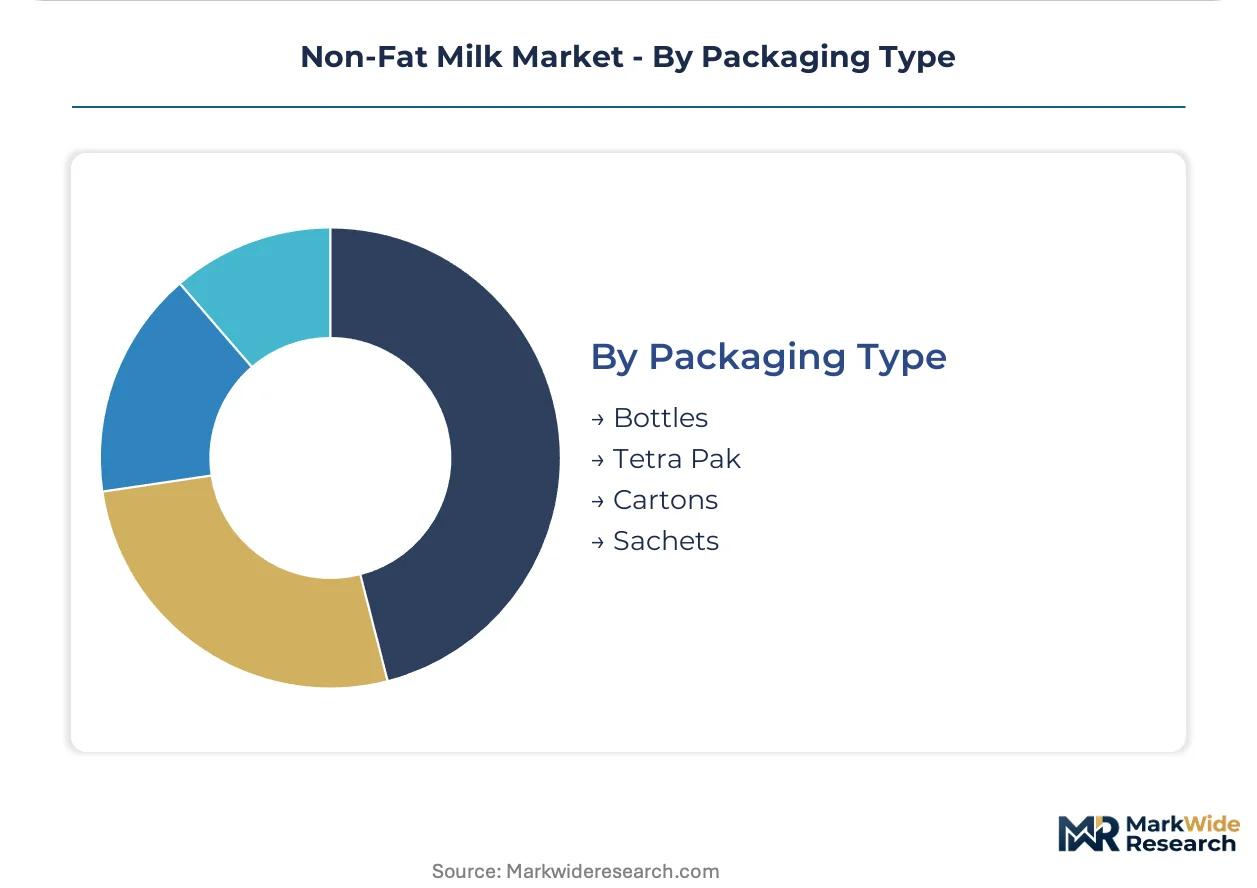
Packaging Type:
Material selection hinges on shelf-life extension requirements versus recycling infrastructure availability in target markets.
- Bottles:HDPE or PET containers for fluid non-fat milk with 7-14 day refrigerated shelf life. Widely recyclable but cold-chain dependent.
- Tetra Pak:Aseptic carton systems enabling 6-9 month ambient stability. Complex multi-layer materials challenge recycling streams in developing markets.
- Cartons:Gable-top paperboard for short-life chilled distribution. Lower cost than aseptic alternatives.
- Sachets:Flexible film pouches for powdered non-fat milk in price-sensitive markets. Minimal material cost but limited resealability.
Tetra Pak leads value retention. Sachets dominate unit volume in emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates demand through AMUL's cooperative network, while New Zealand and European suppliers anchor export supply. Regulatory divergence across FDA, EU Green Deal, and India's PLI scheme reshapes competitive access.
United States
Bakery sector reformulation and institutional procurement drive volume. The FDA enforces Grade A Pasteurized Milk Ordinance standards governing pathogen limits and sanitary processing. Wisconsin and California dairy clusters supply defatted milk powder to industrial bakeries seeking cost-stable inputs.
India
Rural distribution expansion and school nutrition programs concentrate consumption. The PLI scheme for food processing subsidizes cold-chain infrastructure buildout. Gujarat-based AMUL extends defatted milk reach into previously unreachable hinterlands through cooperative federation networks.
New Zealand
Bulk ingredient supply for industrial bakeries and recombined dairy products anchors export revenue. Fonterra's Global Dairy Trade platform sets international price benchmarks. Canterbury region processors invest in on-farm anaerobic digesters to preserve EU quota access under carbon border adjustment mechanisms.
Germany
Supermarket private-label contracts and UHT portfolio breadth sustain retail presence. The EU Green Deal's Farm to Fork strategy tightens methane emission benchmarks for dairy cooperatives. Bavarian processing clusters face rising compliance costs for defatted milk powder exports.
Brazil
Tropical market penetration and fragmented cold-chain infrastructure favor UHT formats. ANVISA regulates dairy product standards alongside MERCOSUR sanitary protocols. São Paulo state processors deploy Tetra Pak aseptic filling systems to unlock consumption occasions previously excluded by refrigeration gaps.
Non-Fat Milk Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with cooperatives dominating bulk supply and multinationals anchoring retail shelf presence. Market structure tilts toward consolidated supply at the farmgate and fragmented downstream formulation. Three archetypes prevail: dairy cooperatives with captive milk supply, diversified nutrition conglomerates with UHT expertise, and ingredient specialists with protein fractionation capabilities. Dominant competitive moves include backward integration into farm-level supply control and geographic expansion through aseptic processing technology licensing.
Among cooperative-structured suppliers, Fonterra Co-operative Group and Dairy Farmers of America exemplify farmgate-integrated models that secure raw milk access. Nestlé SA and Danone SA occupy positions within the diversified nutrition tier, leveraging UHT portfolio breadth and probiotic-enhanced formulations respectively. Glanbia plc represents the ingredient specialist archetype, sitting within the protein fractionation and sports nutrition supply chain. These anchors illustrate how scale, cooperative ownership structure, and functional positioning stratify competitive capability across fluid, dried, and specialized non-fat milk segments.
| Leading Market Players |
|---|
| Dairy Farmers of America |
| Nestlé SA |
| Arla Foods amba |
| Danone SA |
| Fonterra Co-operative Group |
| Glanbia plc |
| All American Foods Inc |
| AMUL |
| Hilmar Cheese Company |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's Farm to Fork strategy gates qualified supply and premium-tier pricing access by mandating farm-level methane disclosure and carbon border compliance for defatted milk ingredients entering European food manufacturing channels. Processors lacking documented emission reductions face exclusion from high-margin contracts while certified suppliers command price premiums.
Pricing Analysis
Volume concentrates in commodity powdered non-fat milk while margins pool in UHT and probiotic-enhanced fluid formats. Three-tier pricing structure across premium, standard, and economy levels separates Fonterra's bulk auction supply from Danone's functional positioning and private-label economy tiers. Price differentiation hinges on certification grade and geographic delivery cost. Pricing pressure stems from skim milk powder volatility at Global Dairy Trade auctions. Bakeries exhibit highest price sensitivity due to quarterly procurement resets, while specialty dairy shops tolerate premium markups.
Supply Chain Analysis
Dual-sourcing requirements from industrial bakeries and multinational food manufacturers mandate multi-supplier qualification across New Zealand, India, and Germany to mitigate Fonterra GDT price swings. Raw material flows draw from Canterbury dairy herds, Gujarat cooperative networks, and Bavarian processing clusters. Supply chain risk centers on single-source vulnerability to EU methane benchmarks disrupting export access. Distribution runs through dairy cooperative federations for bulk powder, direct tanker delivery for liquid concentrate, and Tetra Pak aseptic systems for tropical UHT penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration technology is displacing legacy centrifugal separation, compressing protein recovery economics and forcing processors to choose between commodity volume and precision ingredient specialization.
For Market Incumbents: Lock in farmgate supply control through cooperative federation expansion in India and on-farm anaerobic digester investment in New Zealand to preserve EU quota access. Deepen backward integration into captive milk supply while accelerating ceramic membrane deployment for micellar casein fractionation. The oat and almond protein concentrate threat in cafe channels demands fortified fluid innovation. For New Entrants and Emerging Players: India's PLI scheme for food processing opens a window for cold-chain infrastructure plays targeting AMUL's unreached rural hinterlands. Sub-Saharan Africa's institutional procurement from humanitarian feeding programs offers white-space entry with powdered non-fat milk bypassing refrigeration gaps. Direct-to-bakery bulk dispensing systems eliminate bagged powder handling labor for industrial-scale manufacturers. For Investors and Strategic Acquirers: Fonterra's GDT auction price volatility exceeding 15-40% quarterly swings is the leading indicator that commodity exposure requires hedging through integrated processing assets. Long-term viability favors ingredient specialists with protein fractionation capabilities over pure-play commodity powder suppliers. Watch for contract structure shortening from annual to quarterly resets as the inflection signal for procurement flexibility premium.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Farmgate Supply | Cooperative federation networks in India and New Zealand secure raw milk access against auction volatility. |
| Ceramic Membrane System Deployment | Protein fractionation capabilities transform commodity skim milk powder into sports nutrition isolate inputs. |
| UHT Technology Licensing Expansion | Tetra Pak aseptic systems unlock tropical markets where fragmented cold chains previously excluded liquid dairy. |
| Probiotic Strain Integration | Lactobacillus fortification commands premium positioning in functional dairy segments targeting digestive health claims. |
| Carbon Border Compliance Investment | On-farm anaerobic digesters preserve EU quota access under Farm to Fork methane benchmarks. |
Research Methodology
Independent corroboration across dairy cooperative procurement directors, industrial bakery supply chain managers, and Tetra Pak technical specialists underwrites the qualitative findings. Primary interviews with Fonterra trading desk operators, AMUL federation leaders, and Danone R&D directors combined with secondary validation from USDA federal milk marketing order filings, FDA Grade A Pasteurized Milk Ordinance standards, and EU Green Deal Farm to Fork strategy documents. Bottom-up volume modeling and top-down value triangulation anchored the analysis.
Comparable-period anchoring to historical skim milk powder auction clearing prices and UHT penetration rates in tropical markets established the forecast baseline. Segmentation dimensions modeled include product format, distribution channel, end-user procurement sophistication, and packaging shelf-life requirements across the projection horizon. CAGRs derived from trend extrapolation of membrane filtration adoption curves and PLI scheme infrastructure buildout timelines. Forecast inputs incorporated bakery sector reformulation patterns and plant-based creamer displacement rates in specialty coffee channels.
The model assumes a particular technology adoption path; alternative pathways for enzymatic protein processing would alter the outlook if fractionation economics shift faster than membrane system deployment. Deviation in EU carbon border adjustment mechanism enforcement timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
Europe Dairy Based Beverages Market
Dairy Products
Filled Cheese Market
Dairy Products
US and Europe Nuts and Seeds Cheese Market
Dairy Products
Global Goat Cheese Market
Dairy Products
Butter Fat Fraction Market
Dairy Products
North America Fluid Milk Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Flavored Yogurt Market
Dairy Products
Ricotta Market
Dairy Products
Europe Cow Milk Minerals Market
Dairy Products
Low Fat Yogurt Market
Dairy Products
Dry Whole Milk Powder Market
Dairy Products
Cream Powder Market
Dairy Products
Gruyere Market
Dairy Products
Processed Cheese Market