
 South America Food Emulsifiers Market | 2026-2036
South America Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Emulsifiers Market Analytics
Direct supply agreements between multinational ingredient houses and Brazilian dairy cooperatives is reconfiguring how emulsifiers reach food manufacturers across the continent. Cargill, Incorporated leverages its oilseed processing footprint to secure captive lecithin supplies for regional bakery customers. BASF SE anchors its position through specialized synthetic emulsifier portfolios tailored to high-performance sauce applications. Palsgaard competes by extending technical service capabilities directly into Argentine and Chilean production facilities.
Food emulsifiers are surface-active agents that reduce interfacial tension between immiscible phases such as oil and water, typically functioning at concentrations between 0.1% and 2.0% by weight to stabilize texture, extend shelf life, and control fat crystallization in processed foods. Lecithin dominates volume flows due to its clean-label positioning and cost efficiency in standard bakery and chocolate applications, though synthetic variants sustain margin pools where thermal stability and precise HLB values prove critical. Dairy applications are registering the most rapid formulation shift, as UHT milk and recombined cream processors adopt semi-synthetic blends to replace costlier natural alternatives without sacrificing emulsion integrity.
ANVISA governs food additive approvals and maximum usage limits across Brazil, while Mercosur's harmonized technical regulations shape cross-border trade standards for emulsifier imports among member states. Argentina's national food code and Chile's Ministry of Health impose additional labeling and purity requirements that filter which suppliers gain shelf access. Stakeholders must monitor pending updates to Mercosur's unified food additive positive list, as these revisions will determine whether regional formulators consolidate supplier relationships or diversify sourcing to meet divergent national implementations.
Market Dynamics
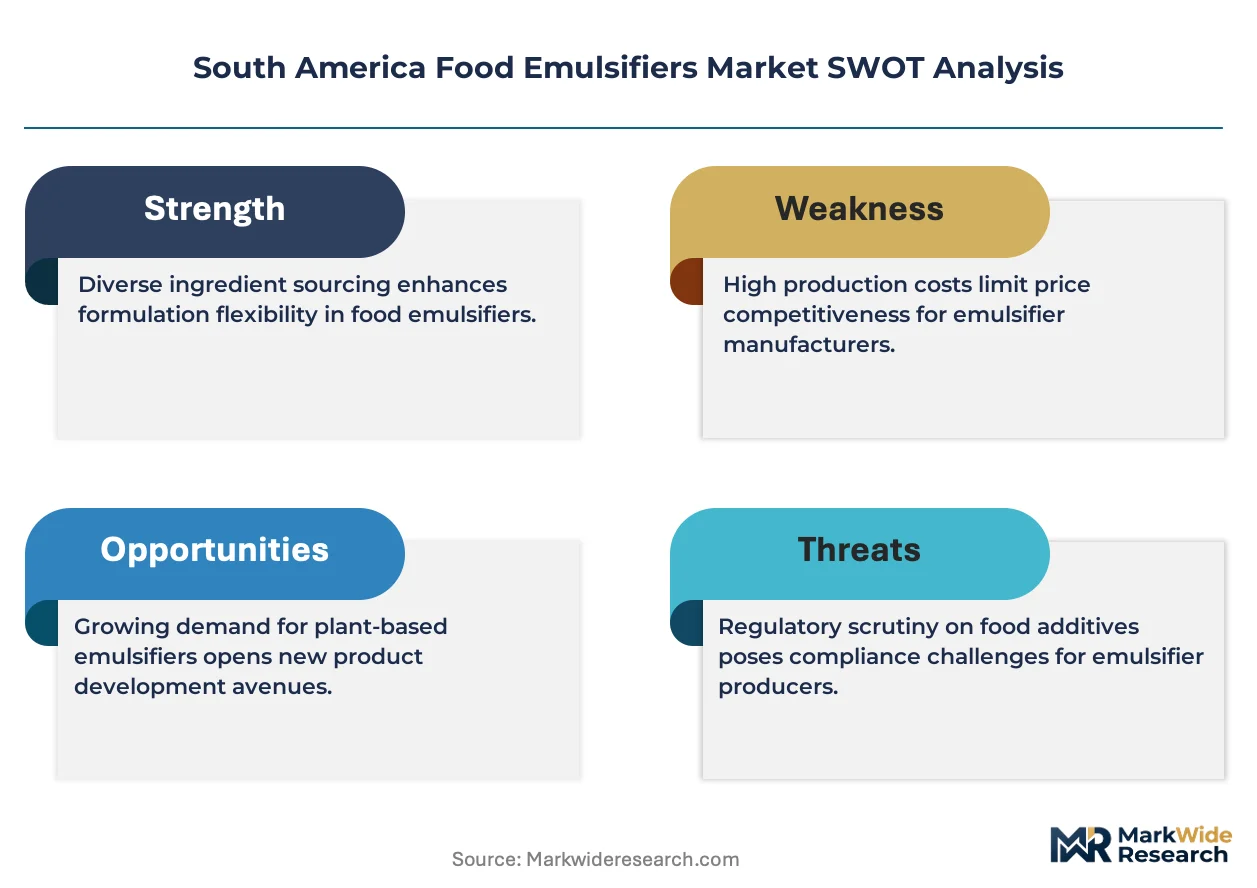
ANVISA's tightening additive approval pathways are forcing regional formulators to revalidate entire emulsifier portfolios, compressing supplier qualification timelines and consolidating procurement toward pre-certified multinational houses with established Brazilian regulatory dossiers.
Growth Catalysts
- Clean-label bakery reformulation:Argentine and Brazilian consumers reject E-number ingredients, pulling natural lecithin and plant-derived mono-diglycerides into mainstream bread and pastry applications.
- Mercosur harmonization momentum:Pending unified food additive positive list revisions promise streamlined cross-border trade, reducing duplicate testing costs for emulsifier blends moving between São Paulo and Buenos Aires processing corridors.
- UHT dairy capacity expansion:Southeast Brazilian recombined cream processors require semi-synthetic emulsifier systems to stabilize extended shelf-life products for export-grade quality consistency.
Market Restraints
- Soybean input cost volatility:Brazilian lecithin production depends on domestic oilseed crush margins, exposing formulators to commodity price swings that synthetic alternatives partially hedge.
- Import dependency for specialty synthetics:High-HLB polyglycerol esters and propylene glycol esters concentrate in European and Asian manufacturing bases, creating currency and logistics exposure for Argentine sauce manufacturers.
- ANVISA approval lag:Novel emulsifier chemistries face 18-24 month evaluation windows versus 6-8 months in comparable jurisdictions, delaying innovation pipelines for regional R&D centers.
Strategic Opportunities
- Chilean confectionery export corridor:Santiago-based chocolate processors serving Pacific Rim markets seek emulsifier suppliers with dual organic-conventional certification to access premium retail channels.
- Enzymatic interesterification convergence:Lipase-catalyzed fat modification technologies pair with emulsifier systems to reduce saturated fat content in Brazilian margarine formulations without texture degradation.
- Direct technical service embedding:Suppliers placing formulation chemists inside Argentine dairy cooperative R&D labs capture specification lock-in before procurement committees finalize approved vendor lists.
Industry Challenges
- Regulatory dossier compilation expertise:Few Brazilian food technology programs train specialists in ANVISA additive petition preparation, creating talent scarcity as approval requirements tighten.
- Legacy equipment compatibility:Older spray-drying and extrusion lines in regional bakeries cannot process next-generation cold-water-dispersible emulsifier granules without capital retrofit investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Emulsifiers Market |
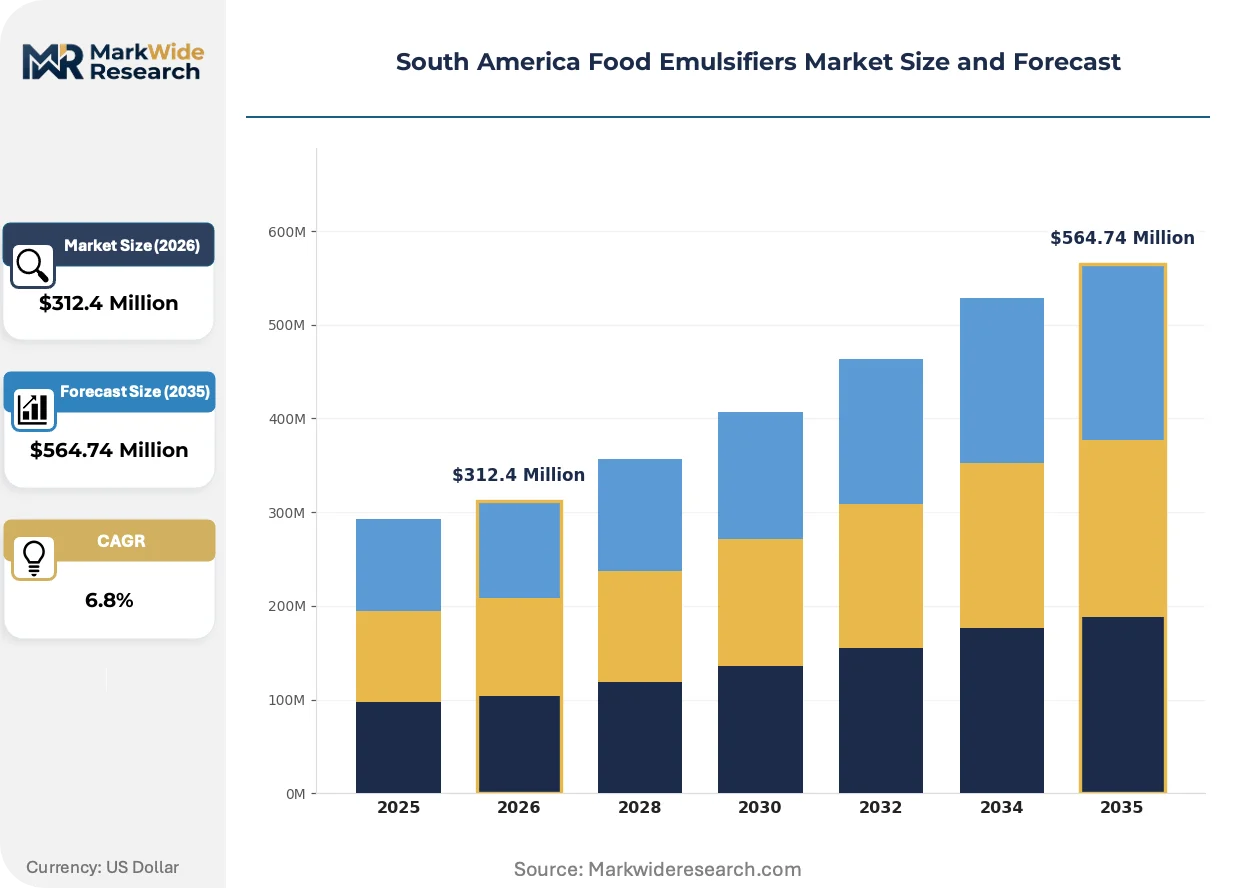
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Natural, Synthetic, Semi-synthetic, Lecithin Application: Beverages, Sauces, Bakery, Dairy Form: Liquid, Powder, Granular, Gel End User: Food Manufacturers, Retailers, Restaurants, Catering Services |
| Companies Covered | Cargill, Incorporated, Archer Daniels Midland, BASF SE, Kerry Group plc, Ingredion Incorporated, DuPont de Nemours Inc., The Dow Chemical Company, Palsgaard, Fourchem, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Emulsifiers Market Evolving Landscape
Enzymatically modified lecithin and precision-fermented phospholipids are disrupting traditional extraction-based supply models, while regulatory data-sharing initiatives between Mercosur members promise to compress multi-market approval cycles for innovative emulsifier architectures.
Enzymatic degumming and fractionation technologies now yield lecithin fractions with tailored phosphatidylcholine concentrations for specific emulsion stability requirements. Brazilian chocolate manufacturers adopt these refined grades to replace synthetic alternatives in clean-label premium lines. Conventional solvent-extracted lecithin with standard phospholipid profiles is rendering obsolete for applications above mid-tier price positioning.
ANVISA's alignment with Codex Alimentarius standards for food additive maximum levels is tightening purity specifications for imported emulsifier shipments. Regional distributors must now submit batch-specific contaminant testing documentation that previously applied only to pharmaceutical-grade materials. Argentine import agents serving confectionery processors face the steepest compliance cost escalation as they rebuild documentation workflows.
Direct procurement contracts between large Brazilian dairy cooperatives and emulsifier manufacturers are displacing traditional ingredient distributor intermediaries. These bilateral arrangements embed volume commitments and technical service obligations that distributors cannot match. São Paulo state's industrial dairy corridor exhibits the most advanced channel consolidation, with cooperative procurement committees negotiating three-year supply frameworks.
South America Food Emulsifiers Market Segmentation
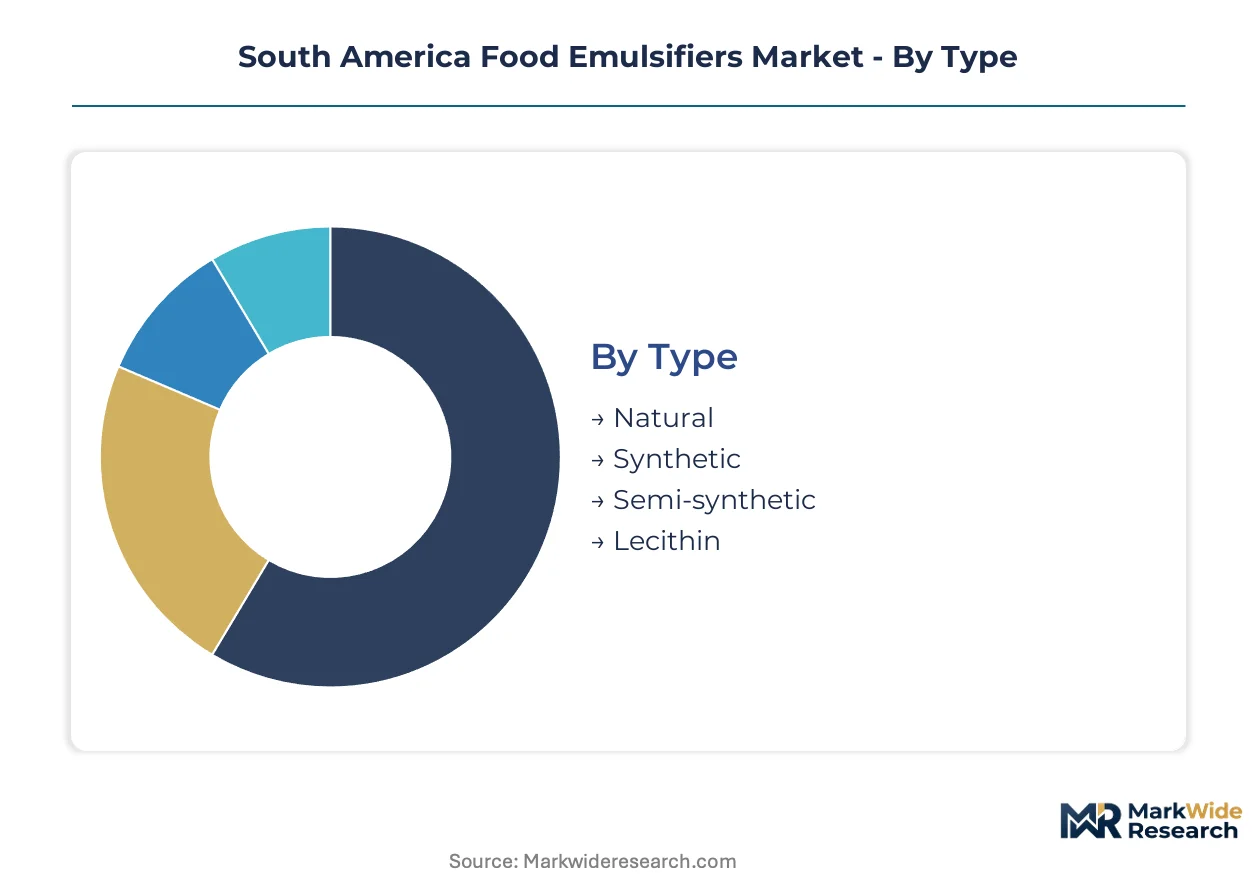
Segmentation in the South America Food Emulsifiers Market reveals how formulation requirements diverge across regulatory environments and processing technologies. Each dimension—type, application, form, and end user—carries distinct procurement patterns and technical service expectations that suppliers must address separately.
Type:
Use cases span clean-label bakery reformulation in Argentina to thermal-stable sauce systems in Brazil's industrial corridor.
- Lecithin:Phospholipid mixtures extracted from soybean oil processing deliver cost-efficient emulsification at 0.3-1.5% dosage rates. Argentine chocolate manufacturers specify high-phosphatidylcholine grades for premium clean-label positioning.
- Natural:Plant-derived mono-diglycerides and sorbitan esters satisfy ANVISA-compliant additive petitions without E-number labeling. Brazilian southeast dairy cooperatives source these for recombined cream export lines.
- Synthetic:Polyglycerol polyricinoleate and propylene glycol esters provide precise HLB control for high-temperature processing.
- Semi-synthetic:Chemically modified natural base stocks balance cost and performance in UHT milk stabilization.
Established volume favors lecithin; emerging adoption favors natural.
Application:
Cost tiers separate commodity bakery applications from premium dairy formulations requiring extended technical support.
- Bakery:Bread and pastry processing consumes emulsifiers primarily for dough conditioning and crumb softening, with Brazilian industrial bakeries driving volume through automated continuous mixing lines.
- Dairy:UHT milk, recombined cream, and processed cheese demand semi-synthetic blends for emulsion stability across 6-12 month shelf lives. Southeast Brazilian processors specify these for export-grade consistency.
- Sauces:Mayonnaise and dressing manufacturers require high-HLB systems for cold-process emulsification.
- Beverages:Clouding agents and flavor emulsions in soft drinks and dairy alternatives use low-dosage lecithin dispersions.
Volume concentrates in bakery; margin expansion concentrates in dairy.
Form:
Supply concentration in liquid processing equipment shapes regional availability, with powder investments lagging in older Argentine facilities.
- Liquid:Fluid lecithin and emulsifier concentrates ship in bulk tankers to large Brazilian dairy cooperatives, minimizing handling costs and enabling automated dosing.
- Powder:Spray-dried emulsifier blends serve remote bakery operations lacking liquid storage infrastructure, particularly in Chilean provincial markets.
- Granular:Free-flowing agglomerates address dust-control requirements in high-volume bread plants.
- Gel:Thickened emulsifier preparations target small-batch artisan producers.
Logistics efficiency favors liquid; formulation flexibility favors powder.
End User:
Customer type determines specification authority, with food manufacturers controlling ingredient selection while retailers and restaurants inherit finished-product choices.
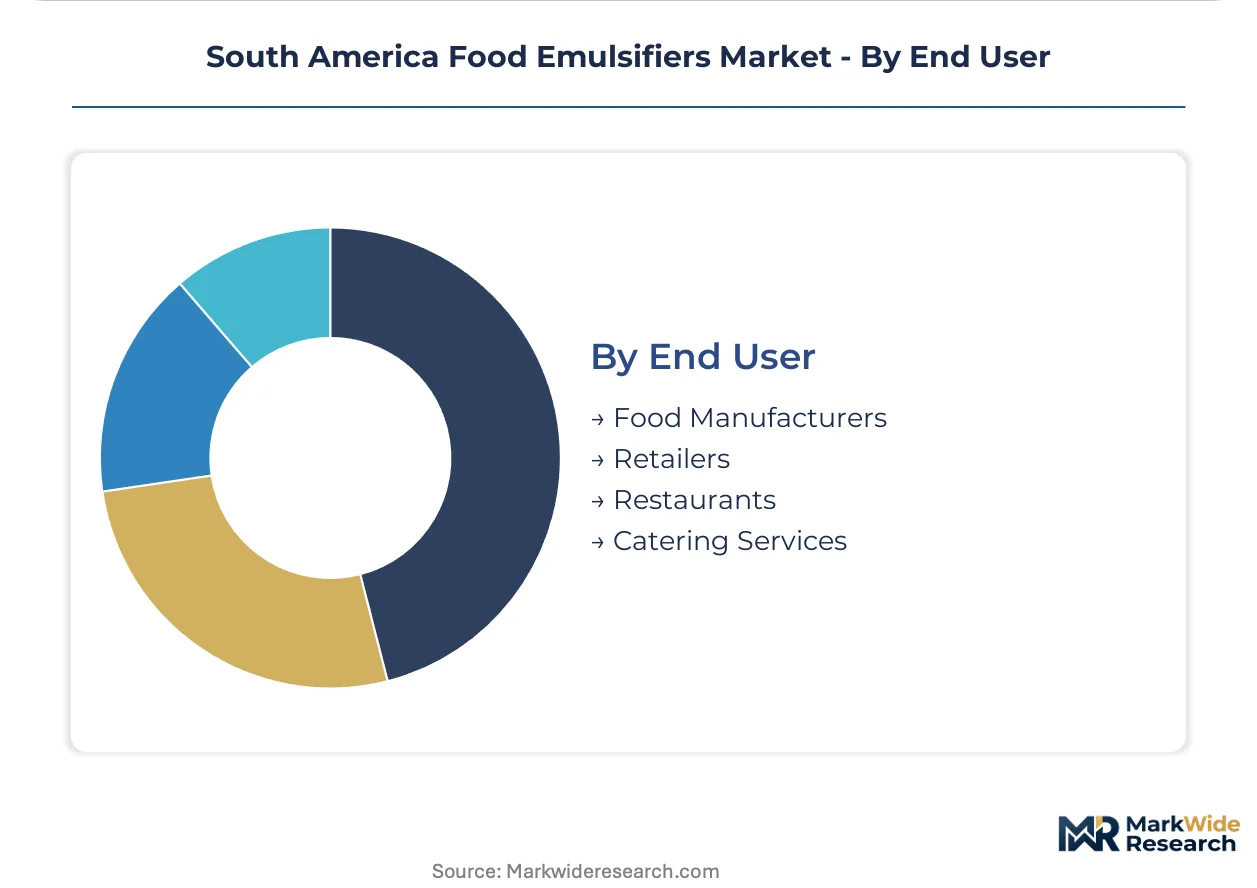
- Food Manufacturers:Industrial processors across Brazil's southeast corridor negotiate direct supply agreements with emulsifier houses, embedding three-year volume commitments and technical service obligations.
- Restaurants:Chain kitchens and central commissaries specify emulsifier-stabilized bases for sauce and dressing consistency across multiple locations.
- Retailers:Private-label programs in Argentine supermarket chains drive demand for clean-label emulsifier systems in store-brand bakery and dairy lines.
- Catering Services:Institutional foodservice operators prioritize cost-stable emulsifier supplies for high-volume sauce production.
Procurement consolidation favors food manufacturers; specification influence favors retailers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's evolving additive standards are reshaping procurement patterns across South America, with Mercosur harmonization efforts creating both compliance pressure and cross-border trade facilitation for emulsifier suppliers.
Brazil
Southeast industrial dairy corridors in São Paulo and Minas Gerais drive concentrated demand for semi-synthetic emulsifier systems. ANVISA's batch-specific contaminant documentation requirements filter import eligibility toward pre-certified multinational houses. São Paulo state's cooperative procurement committees negotiate three-year direct supply frameworks that displace traditional distributor channels.
Argentina
Chocolate manufacturers in Buenos Aires specify high-phosphatidylcholine lecithin grades for clean-label premium positioning. The national food code imposes additional labeling purity requirements that complicate sourcing from non-regional suppliers. Argentine import agents serving confectionery processors face steep compliance cost escalation as they rebuild documentation workflows.
Chile
Santiago-based chocolate processors serving Pacific Rim export markets seek dual organic-conventional certification for premium retail channel access. The Ministry of Health maintains stringent additive approval pathways that align with Codex Alimentarius standards. Provincial bakery operations in remote markets rely on spray-dried powder emulsifiers lacking liquid storage infrastructure.
Colombia
Andean dairy cooperatives are adopting UHT processing technologies that require stabilized emulsion systems for extended shelf-life products. National food safety regulators implement additive positive lists derived from Mercosur technical regulations. Bogotá's industrial food processing corridor exhibits emerging demand for technical service-embedded supplier relationships.
South America Food Emulsifiers Market Competitive Landscape
On the supply side, the industry is consolidating around multinational ingredient houses with established Brazilian regulatory dossiers and captive raw material positions. Three strategic archetypes dominate: oilseed processors leveraging backward integration into lecithin production, specialized emulsifier houses competing through technical service embedding, and diversified chemical conglomerates offering synthetic portfolio breadth. Capacity expansion in southeast Brazilian dairy corridors and direct procurement contract negotiation represent the dominant competitive moves reshaping channel structure.
Within the integrated processor tier, Cargill, Incorporated anchors regional supply through its oilseed processing footprint and captive lecithin availability. BASF SE exemplifies the specialized synthetic portfolio approach, while Palsgaard represents the technical service-embedded competitive model extending formulation support directly into Argentine and Chilean production facilities.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Archer Daniels Midland |
| BASF SE |
| Kerry Group plc |
| Ingredion Incorporated |
| DuPont de Nemours Inc. |
| The Dow Chemical Company |
| Palsgaard |
| Fourchem |
| Others |
Value Network & Pricing Analysis
Brazilian soybean crush capacity concentration in the southeast industrial corridor anchors lecithin supply costs and positions captive processors to capture margin pools downstream. Pricing power accrues to integrated houses with in-house phospholipid extraction, while independent formulators absorb commodity volatility through contract structures.
Pricing Analysis
Volume-discount tiering structures separate large dairy cooperatives negotiating three-year direct supply frameworks from smaller bakeries purchasing through distributor channels. Three-tier pricing stratifies across enzymatically modified lecithin premiums, standard solvent-extracted grades, and economy unbleached variants. Cost compression in synthetic emulsifier tiers intensifies as Argentine sauce manufacturers face currency exposure on European and Asian imports. Food manufacturers with automated dosing infrastructure exhibit lowest price sensitivity; provincial Chilean bakeries relying on spray-dried powders face highest cost pressure.
Supply Chain Analysis
Upstream feedstock availability centers on Brazilian soybean oil processing, Argentine sunflower seed crush, and imported palm-derived fractions from Southeast Asia. Raw material flows draw from domestic oilseed crush margins, international phospholipid concentrate shipments, and specialty polyglycerol ester imports. Single-source vulnerability concentrates in high-HLB synthetic emulsifiers where European and Asian manufacturing bases dominate. Distribution runs through direct procurement contracts displacing traditional ingredient distributors in São Paulo state's industrial dairy corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in ANVISA additive petition preparation represents the critical capability gap constraining regional innovation pipelines. Suppliers with established regulatory dossiers and embedded technical service teams command disproportionate specification authority.
For Market Incumbents: Pre-empt emerging competition from precision-fermented phospholipid suppliers by deepening captive lecithin positions and accelerating enzymatic modification capacity in Brazilian oilseed processing hubs. Lock in three-year direct supply frameworks with southeast dairy cooperatives before procurement committees finalize approved vendor lists. Certification investment in dual organic-conventional standards for Chilean confectionery export corridors defends margin position against clean-label entrants. For New Entrants and Emerging Players: Establish a beachhead in Colombian Andean dairy cooperatives adopting UHT processing technologies where technical service-embedded relationships remain underdeveloped. Target Argentine chocolate manufacturers seeking high-phosphatidylcholine lecithin grades for premium clean-label positioning, a segment where established suppliers underinvest in formulation support. Lead with enzymatic interesterification convergence offerings that pair with emulsifier systems for Brazilian margarine fat reduction formulations. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap regional distributors losing share to direct procurement contracts in Brazil's southeast corridor. Five-to-ten year viability hinges on regulatory dossier depth and technical service embedding capabilities rather than commodity trading relationships. Watch for ANVISA's pending alignment with Codex Alimentarius standards as the inflection signal determining which suppliers consolidate procurement relationships versus face specification displacement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Captive lecithin supply secures cost position against Brazilian soybean margin volatility. |
| ANVISA Regulatory Dossier Expansion | Pre-certified additive petitions compress supplier qualification timelines for regional formulators. |
| Technical Service Embedding in Dairy R&D Labs | Formulation chemist placement captures specification lock-in before vendor list finalization. |
| Enzymatic Lecithin Modification Capacity Buildout | Refined phosphatidylcholine grades displace synthetic alternatives in Argentine premium chocolate. |
| Dual Organic-Conventional Certification | Chilean Pacific Rim confectionery exports demand certified emulsifier access to premium retail channels. |
Research Methodology
Operator-level perspectives from ANVISA regulatory affairs specialists, Brazilian dairy cooperative procurement committees, Argentine chocolate manufacturer R&D directors, and Chilean confectionery export quality managers anchored the qualitative base. Primary interview findings combined with secondary validation from ANVISA additive registry filings, Mercosur technical regulation harmonization documents, Brazilian customs trade data, and SEC filings from listed ingredient houses. Bottom-up segment sizing triangulated against top-down market reconstruction across type, application, form, and end-user dimensions.
Scenario-bracketing framed demand projections across the analysis window through sensitivity testing of regulatory approval timelines, soybean crush margin trajectories, and UHT dairy capacity expansion rates. Segmentation modeling captured lecithin versus synthetic versus natural versus semi-synthetic type splits; bakery, dairy, sauces, and beverage application tiers; liquid, powder, granular, and gel form factors; and food manufacturer, restaurant, retailer, and catering end-user channels. CAGRs derived from fitted growth curves applied to base-year sizing with cross-validation against historical volume flows and capacity utilization patterns in southeast Brazilian processing corridors.
Sensitivities concentrate around ANVISA approval lag extensions, Mercosur harmonization implementation divergence, and enzymatic modification technology adoption curves. Forecasts reflect documented assumptions on regulatory timeline stability and commodity input cost trajectories. Cross-checking against Brazilian oilseed crush margin indices and regional dairy cooperative capital expenditure disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Microencapsulated Phytosterols Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Meat Tenderizing Agents Market
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Monk Fruit Ingredient Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Food Grade Release Agent Market