
 Greek Yogurt Market | 2026-2036
Greek Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Greek Yogurt Market Intelligence
The European Union's Farm to Fork strategy, emphasizing sustainable food systems and reduced packaging waste, is restructuring supply chain priorities. Danone S.A. leverages its vast scale to roll out products with lower environmental footprints across Europe and North America. Chobani LLC differentiates its brand through a focus on natural ingredients and strict non-GMO sourcing policies. FAGE International S.A. sustains its premium market position with its signature thick texture achieved via proprietary straining techniques.
Greek yogurt is a strained dairy product, technically defined by the removal of whey and other liquids to achieve a much thicker consistency and higher protein content than unstrained yogurt. It primarily serves as a nutrient-dense food for direct consumption or as a versatile culinary ingredient in both sweet and savory dishes. Flavored products lead retail volume, but the plain segment is critical for foodservice applications and as a base for home cooking. Single-serve cups distributed through supermarkets represent the largest and most profitable channel-format combination.
In the United States, the FDA's standards of identity regulate labeling terms like 'strained', while the European Food Safety Authority (EFSA) governs health and nutrition claims on packaging. International food safety standards, including ISO 22000, dictate manufacturing practices to ensure product quality and prevent microbiological contamination. Producers must continually navigate evolving consumer preferences for plant-based alternatives alongside persistent demands for more sustainable packaging solutions.
Market Dynamics
The central force shaping the Greek yogurt market is the intersection of consumer demand for high-protein, nutrient-dense foods and mounting regulatory pressure for sustainable packaging, forcing producers to innovate on both product formulation and container materials.
Growth Catalysts
- High-Protein Demand:The sustained focus on fitness and wellness drives consumption among health-conscious demographics seeking nutrient-dense, high-protein food options for post-workout recovery and meal replacement.
- Sustainable Packaging Innovation:The EU Green Deal's circular economy action plan incentivizes the development of fully recyclable and compostable packaging, creating a value-add for brands targeting environmentally-aware consumers.
- Culinary Versatility:Increased adoption in the foodservice sector and by home cooks as a versatile ingredient in savory sauces, dips, and baked goods expands consumption beyond the traditional breakfast-snack occasion.
Market Restraints
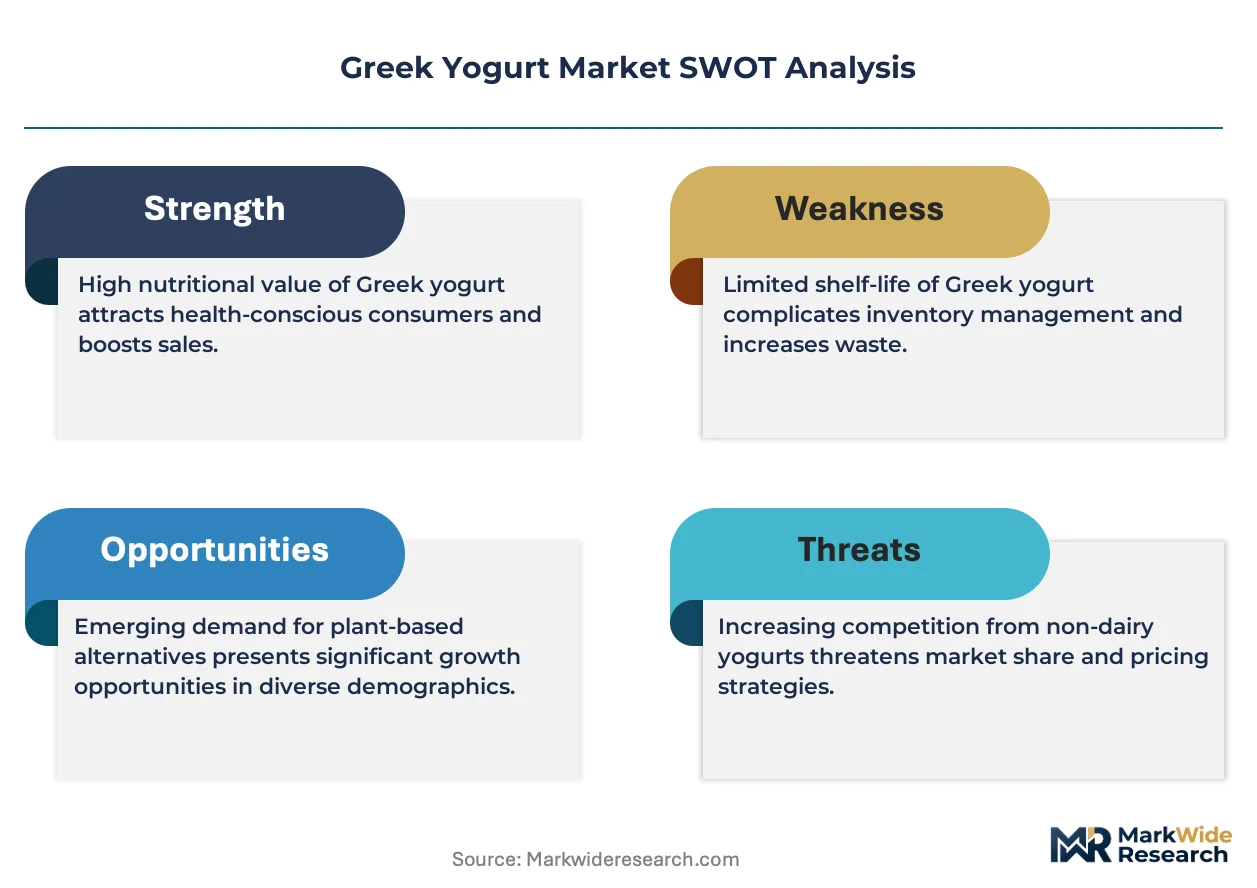
- Raw Material Price Volatility:The market is exposed to fluctuations in the price of raw milk, a primary input, which can compress manufacturer margins and lead to price instability for consumers.
- Plant-Based Substitution:The proliferation of plant-based yogurt alternatives, made from soy, almond, coconut, or oats, directly competes for shelf space and the same health-conscious consumer segment.
- Regulatory Labeling Standards:The FDA's standard of identity for "strained" yogurt creates a compliance barrier for new entrants and can limit formulation flexibility for manufacturers in the United States.
Strategic Opportunities
- Geographic Expansion:There is significant potential in Latin American and Southeast Asian markets, where a growing middle class and rising health awareness create new consumer bases for premium dairy products.
- Functional Food Development:Fortifying Greek yogurt with probiotics, prebiotics, vitamins, and botanicals can create new product lines targeting specific health outcomes, such as gut health or immune support.
- Ingredient Transparency Platforms:Leveraging blockchain or QR code technology on packaging allows brands to provide verifiable information on non-GMO sourcing and animal welfare, appealing to discerning consumers.
Industry Challenges
- Packaging Reconfiguration:Shifting to recyclable or compostable materials requires significant capital investment in new machinery and supply chain adjustments to ensure material availability and quality.
- International Compliance Complexity:Producers must navigate complex food safety and labeling laws, including ISO 22000 and differing health claim regulations from bodies like the EFSA and FDA.
- Acid Whey Disposal:The straining process produces large volumes of acid whey, a byproduct requiring costly treatment or repurposing to avoid environmental and regulatory issues.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greek Yogurt Market |
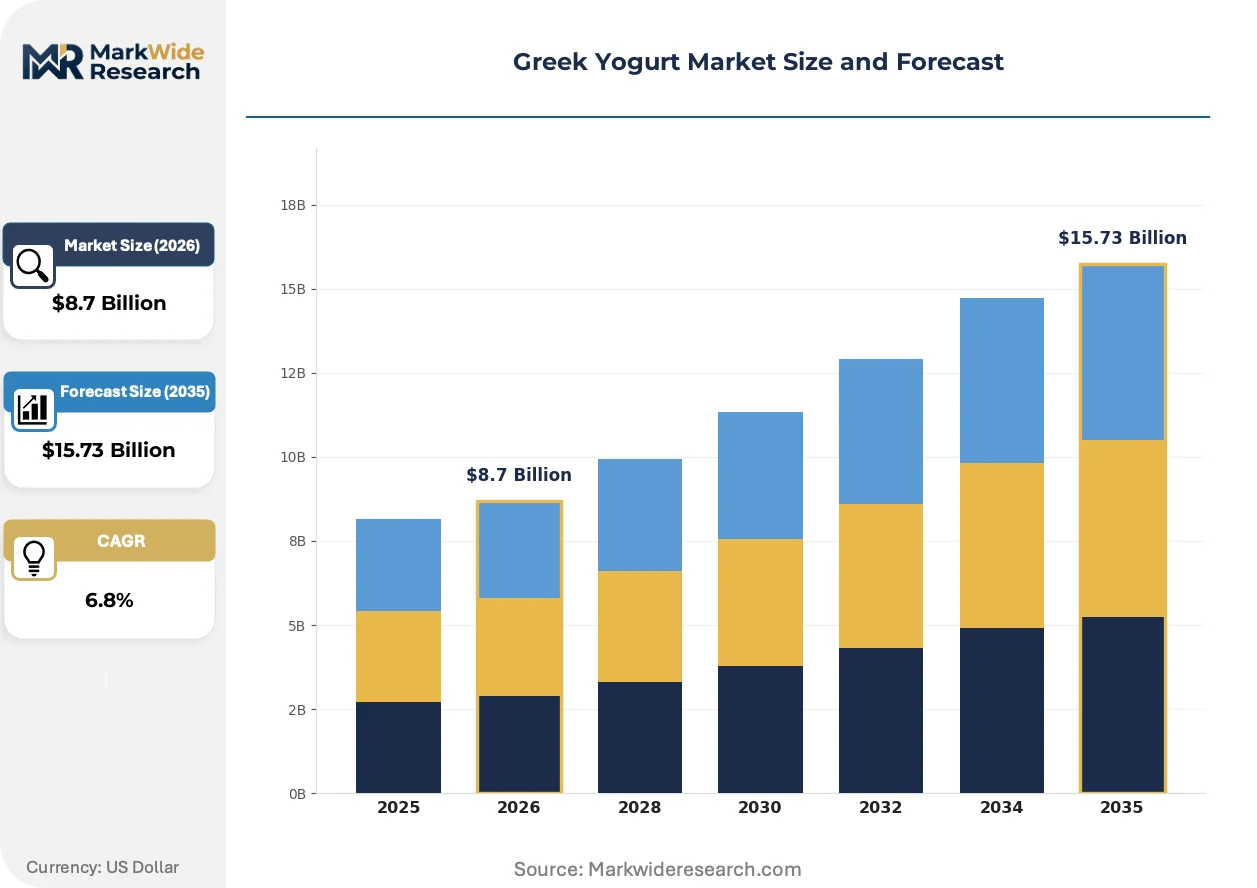
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain, Flavored, Organic, Low-Fat Consumer Type: Health-Conscious, Families, Fitness Enthusiasts, Millennials Packaging Type: Tubs, Single-Serve Cups, Squeeze Pouches, Bulk Containers Distribution Channel: Supermarkets, Online Retailers, Health Food Stores, Foodservice |
| Companies Covered | Lactalis Groupe, Nestlé S.A., FAGE International S.A., Unilever Plc, FrieslandCampina, Chobani LLC, Arla Foods amba, General Mills Inc., Danone S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greek Yogurt Market Strategic Shifts & Innovations
Product development is increasingly defined by a dual focus on clean-label formulations and sustainable packaging. This evolution reflects a direct response to consumer demand for natural ingredients and regulatory mandates aimed at reducing the food industry's environmental footprint.
Proprietary straining and ultrafiltration systems are key for achieving the high protein content and thick texture of authentic Greek yogurt. Premium brands and private-label manufacturers adopt these advanced methods to ensure product consistency and differentiate from regular yogurt. The focus on these techniques is consolidating the market around producers with advanced technical capabilities.
The European Union's Farm to Fork strategy sets stringent targets for sustainable food production and packaging waste reduction. This policy impacts manufacturing by pushing for circular economy materials. The single-serve cup segment is most affected, compelling producers in or exporting to Europe to redesign containers for full recyclability or compostability.
A notable consumer shift is occurring from flavored, single-serve products toward plain, unflavored Greek yogurt as a culinary base. This behavior disrupts the retail dominance of small cups, elevating the importance of larger tubs for home cooking. This trend is visible in the United States and Germany, where consumers use it in savory dishes and baking.
Greek Yogurt Market Segmentation
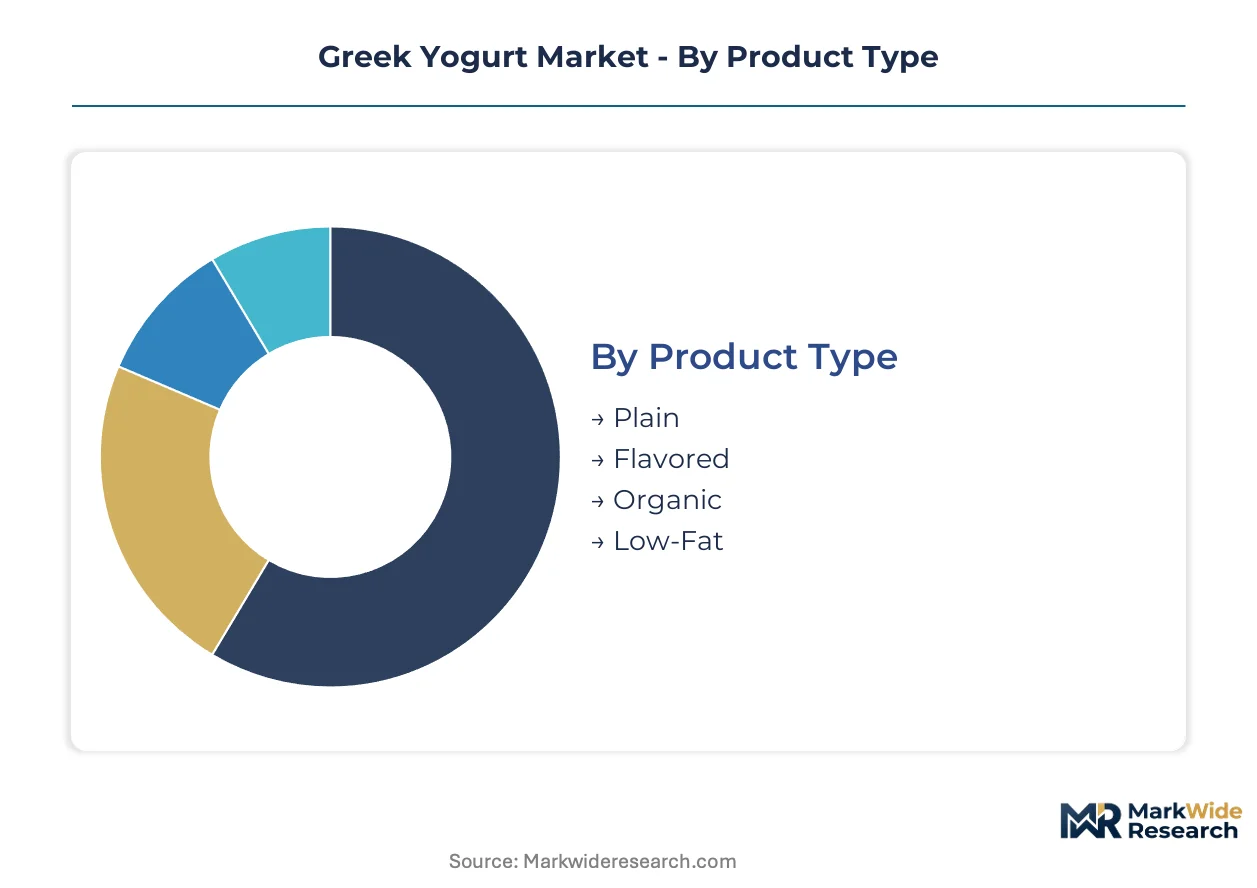
Understanding the Greek yogurt market's structure requires a detailed breakdown of its diverse segments. This segmentation analysis identifies key product variations, consumer profiles, packaging formats, and distribution channels that collectively define market dynamics. Each segment responds to distinct consumer needs and operational efficiencies.
Product Type:
The Greek yogurt market’s evolution often involves consumers upgrading from conventional yogurts or replacing less nutritious snack options with higher-protein alternatives.
- Flavored:These products incorporate fruit purees, sweeteners, and other additives to enhance palatability for direct consumption. Retail volume for Greek yogurt is substantially driven by flavored varieties across supermarkets in the United States and Germany.
- Plain:This segment comprises unsweetened, unflavored Greek yogurt, valued for its natural tang and high protein content. Plain Greek yogurt is critical for foodservice applications and as a versatile culinary ingredient in home cooking.
- Organic:Products in this category adhere to organic farming standards, appealing to consumers prioritizing natural and sustainably sourced ingredients.
- Low-Fat:This segment caters to calorie-conscious consumers, offering reduced fat content while retaining the characteristic thick texture and high protein.
Volume placements concentrate in Flavored products; the faster expansion belongs to Plain varieties due to culinary versatility.
Consumer Type:
Different consumer groups exhibit distinct purchasing behaviors and preferences within the Greek yogurt category.
- Fitness Enthusiasts:This demographic actively seeks high-protein foods for muscle recovery and satiety, often consuming Greek yogurt post-workout or as a meal replacement. Their demand drives product innovation in protein concentration and functional additives.
- Health-Conscious:These consumers prioritize overall well-being, opting for Greek yogurt due to its nutrient density, probiotic benefits, and clean label potential. This segment influences the market towards natural ingredients and reduced sugar options.
- Families:This segment often seeks convenient, nutritious snack and breakfast options for children and adults, influencing demand for multi-packs and kid-friendly flavors.
- Millennials:This generation values transparency, sustainability, and plant-based options, pushing brands towards ethical sourcing and innovative product lines.
Demand from Fitness Enthusiasts exerts significant influence; the market is also adapting to the evolving preferences of Millennials.
Packaging Type:
Packaging choices directly influence product shelf-life, convenience, and environmental footprint, impacting overall market volume.
- Single-Serve Cups:These individual portions dominate retail sales due to their convenience for on-the-go consumption and portion control. The EU Green Deal significantly impacts the material choices for these containers, pushing for recyclability.
- Tubs:Larger multi-serving containers cater to home usage, serving as a culinary ingredient or for family consumption. The shift towards plain Greek yogurt for cooking elevates the importance of this format in the United States and Germany.
- Squeeze Pouches:This format targets children and active consumers, offering mess-free consumption and portability, often with fruit-blended varieties.
- Bulk Containers:Primarily used in foodservice and industrial applications, these larger formats cater to restaurants, bakeries, and institutional settings for ingredient supply.
The Single-Serve Cups segment holds the largest market share; however, Tubs are experiencing a notable expansion in household consumption.
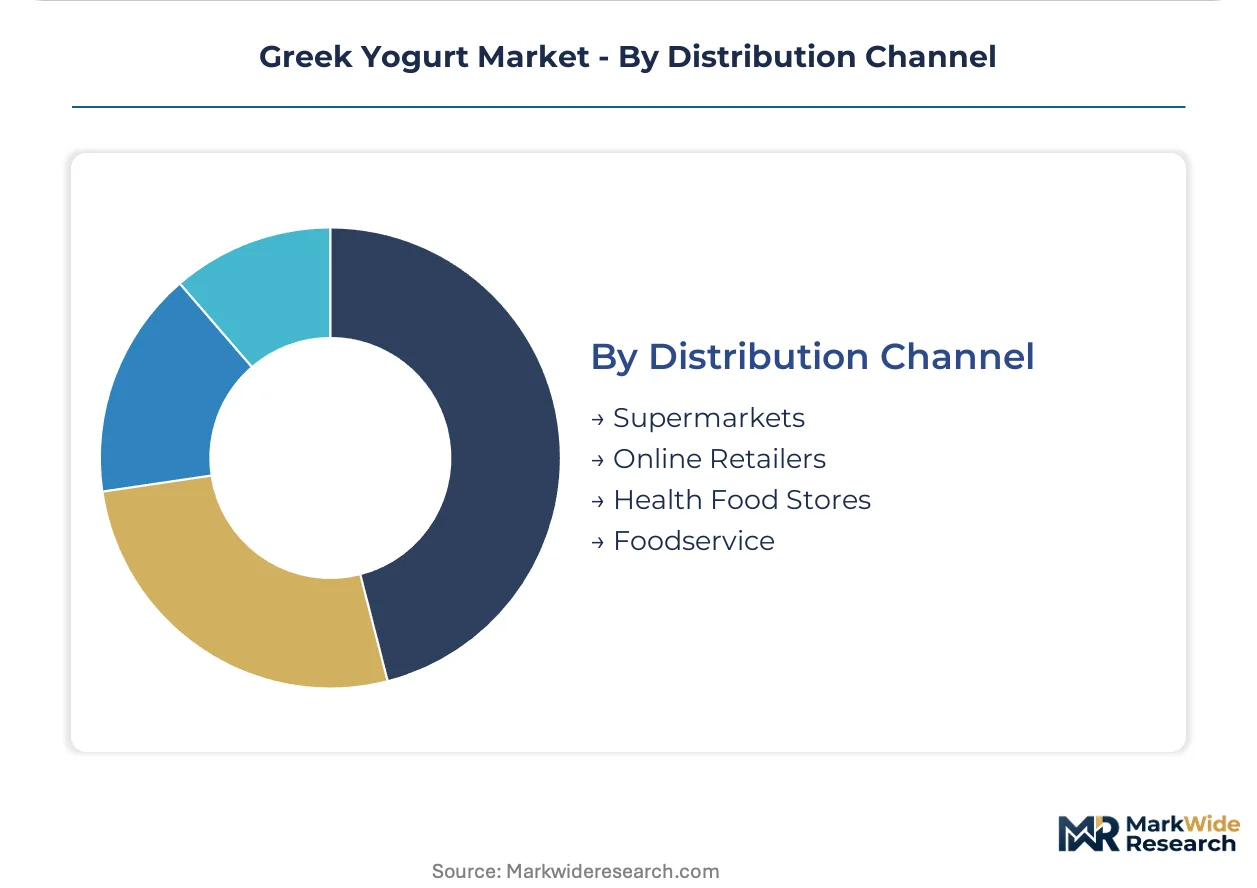
Distribution Channel:
The distribution channels define how Greek yogurt reaches consumers, each serving distinct purchasing occasions and customer bases.
- Supermarkets:These large-format retail stores represent the primary channel for Greek yogurt sales, benefiting from extensive reach and established cold chain logistics. They offer a wide array of brands and product types to a broad consumer base.
- Foodservice:This channel includes restaurants, cafes, hotels, and institutional caterers, utilizing Greek yogurt as an ingredient in various dishes or as a healthy menu option. Its culinary versatility drives adoption in this segment.
- Online Retailers:E-commerce platforms provide convenience and direct-to-consumer options, particularly for specialty or bulk Greek yogurt products, supporting niche brands.
- Health Food Stores:These specialized retailers cater to consumers seeking organic, non-GMO, and natural ingredient options, often featuring premium or niche Greek yogurt brands.
Supermarkets remain the dominant distribution point; Online Retailers are steadily gaining traction with convenience-seeking consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City's vibrant food scene and health-conscious consumer base drive significant demand for Greek yogurt, influencing product innovation and market trends across the United States. This metropolitan hub, alongside other major urban centers, demonstrates a strong preference for high-protein, versatile food options. Regional consumption patterns reflect broader national trends in wellness and sustainable food choices.
United States
Demand for high-protein, nutrient-dense foods propels Greek yogurt consumption among fitness enthusiasts and health-conscious individuals. The FDA's standards of identity for "strained" yogurt regulate labeling terms, ensuring product authenticity for consumers. California's extensive dairy industry and food processing clusters innovate new formulations and sustainable packaging solutions.
Germany
Health-conscious consumer preferences and established retail infrastructure fuel consistent demand for Greek yogurt across Germany. The European Food Safety Authority (EFSA) governs health and nutrition claims on packaging, ensuring transparent product information. Bavaria, a prominent dairy region, hosts numerous processing facilities that supply both national and European markets.
France
Culinary versatility and a strong traditional dairy culture contribute to the growing adoption of Greek yogurt in France. The EU Green Deal's circular economy action plan influences packaging material choices, pushing for fully recyclable containers. Brittany, a significant agricultural and food production area, sees increased investment in dairy processing technologies.
Canada
Fitness enthusiasts and consumers seeking natural ingredients drive the Canadian Greek yogurt market. Health Canada's food labeling regulations ensure accurate nutritional information, supporting informed consumer choices. Ontario's food manufacturing cluster, particularly around Toronto, acts as a hub for product development and distribution.
Greek Yogurt Market Key Industry Players
The competitive structure tilts toward established food conglomerates and specialized dairy producers, creating a dynamic market environment. This landscape features a mix of global dairy giants, dedicated Greek yogurt brands, and agile private-label manufacturers. Dominant competitive moves include portfolio diversification into plant-based alternatives and continuous geographic expansion.
Global dairy giants like Danone S.A. exemplify scale-driven market penetration, leveraging extensive distribution networks across continents. Chobani LLC represents a specialized brand focusing on natural ingredients and non-GMO sourcing, appealing to discerning consumer segments. FAGE International S.A. maintains its premium market position through proprietary straining techniques, ensuring a signature thick texture and high protein content.
| Leading Market Players |
|---|
| Lactalis Groupe |
| Nestlé S.A. |
| FAGE International S.A. |
| Unilever Plc |
| FrieslandCampina |
| Chobani LLC |
| Arla Foods amba |
| General Mills Inc. |
| Danone S.A. |
| Others |
Cost & Logistics Intelligence
The EU Green Deal's circular economy action plan gates qualified supply and premium-tier pricing access in the Greek yogurt market. This mandate drives investment in sustainable packaging, influencing material costs and consumer price points.
Pricing Analysis
Value-based pricing anchors the Greek yogurt market, reflecting its perceived health benefits and high protein content. Price differentiation stems from proprietary straining techniques, organic certifications, and established brand premiums. Raw material price volatility, particularly for milk, creates upward pricing pressure for manufacturers. Health-conscious consumers and fitness enthusiasts exhibit lower price sensitivity, while families often seek more economical options for household consumption.
Supply Chain Analysis
Reverse logistics for acid whey disposal presents a significant environmental and cost challenge in the Greek yogurt supply chain. Production concentrates in dairy-rich regions like California, Bavaria, and Brittany, drawing from raw milk, fruit purees, and sustainable packaging materials. Commodity price volatility for milk and the complexity of acid whey treatment introduce structural risks. Distribution runs predominantly through established supermarket networks, with growing online retail penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Greek yogurt market is a consolidation play, driven by mounting regulatory pressure for sustainable packaging that strains smaller producers. This environment favors large players capable of significant capital investment in material science and processing.
For Market Incumbents: Deploy vertical integration into sustainable packaging materials to mitigate supply chain risks and meet regulatory mandates. Incumbents must also diversify product portfolios with plant-based alternatives to counter substitution threats. Investing in advanced straining technologies can further differentiate premium offerings against private-label competition. Protecting market share requires continuous innovation in both product formulation and eco-friendly container solutions.
For New Entrants and Emerging Players: The EU Green Deal in Europe opens a window for new entrants specializing in compostable or fully recyclable packaging. Target the functional food segment by fortifying Greek yogurt with probiotics or botanicals for specific health outcomes. A go-to-market angle leveraging blockchain for ingredient transparency can attract discerning health-conscious consumers. Focus on underpenetrated geographic markets in Latin America and Southeast Asia for initial expansion.
For Investors and Strategic Acquirers: Increased investment in acid whey repurposing technologies is the leading indicator that sustainability is driving long-term value creation. The market remains viable over a 5-10 year window, favoring companies with strong intellectual property in processing and sustainable materials. Target acquisition archetypes include niche brands with innovative functional food formulations or advanced packaging solutions. Monitor consumer preference shifts towards new protein sources for early signals of market disruption.
| Strategic Initiative | Industry Significance |
|---|---|
| Sustainable Packaging Transition | Reduces environmental footprint and ensures compliance with European regulations like the EU Green Deal. |
| Plant-Based Portfolio Diversification | Captures market share from consumers seeking dairy alternatives and expands product appeal. |
| Functional Ingredient Fortification | Creates new premium product lines targeting specific health benefits such as gut health. |
| Geographic Market Entry | Taps into growing middle-class demand and health awareness in Latin American regions. |
| Advanced Straining Technology Investment | Enhances product quality, consistency, and protein content, differentiating premium brands. |
Research Approach
Company annual reports, regulatory body publications from the FDA and EFSA, and industry association whitepapers formed the secondary backbone of this analysis. This was combined with primary interviews involving brand managers, R&D directors, sustainability officers, and procurement leads across the value chain. A rigorous bottom-up and top-down triangulation process validated all market data and insights.
Historical trendline analysis established foundational data points for market projections across the analysis window. The analytical framework segmented the market by product type, consumer type, packaging type, and distribution channel, alongside regional consumption. Compound annual growth rates were derived from a multi-factor model incorporating raw milk price fluctuations and consumer health spending trends.
The model assumes a particular technology adoption path; alternative pathways for plant-based protein fermentation would alter the outlook. Forecasts reflect assumptions regarding raw material stability and consistent regulatory enforcement. Practitioners should monitor shifts in consumer preferences and evolving packaging mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Grass Fed Dairy Product Market
Dairy Products
Africa Dairy Protein Market
Dairy Products
Dairy Products Market
Dairy Products
Buttermilk Powder Market
Dairy Products
Europe Dairy Market
Dairy Products
Canada Milk Protein Market
Dairy Products
Clotted Cream Market
Dairy Products
Whipping Cream Market
Dairy Products
Low-Fat Sour Cream Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Global Milk Powder Market
Dairy Products
India Milk Protein Market
Dairy Products
UHT Whipping Cream Market
Dairy Products
Skim Milk Powder Market
Dairy Products
Lactose-Free Cheese Market
Dairy Products
Flavoured Milk Market