
 Global Milk Protein Market | 2026-2036
Global Milk Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Global Milk Protein Market Foresight
ISO 22000 certification for food safety management systems is collapsing the supplier base as smaller processors fail audit cycles. Fonterra Co-operative Group Limited leverages its New Zealand dairy cooperative structure to control raw milk supply chains. Glanbia plc sustains competitive advantage through specialized whey protein fractionation technology. Lactalis Ingredients anchors European production capacity with multi-site manufacturing across France and Italy.
Milk protein encompasses casein and whey protein fractions extracted through membrane filtration, ion exchange, or enzymatic hydrolysis, yielding products with protein concentrations from 35% to 95% dry weight for nutritional fortification and functional food applications. Whey protein dominates sports nutrition formulations due to rapid amino acid bioavailability, while casein protein retains structural advantages in bakery and confectionery applications where gelation and water-binding properties command premium positioning. Infant formula applications concentrate demand for hydrolyzed milk protein variants with reduced allergenic potential.
FDA nutrition labeling requirements and EU REACH chemical safety standards shape ingredient disclosure protocols and processing aid restrictions across export markets. China's NMPA and SAMR enforce infant formula registration requirements that dictate protein source qualification and clinical substantiation for new entrants. Stakeholders must monitor evolving allergen threshold regulations and precision fermentation alternatives that threaten conventional dairy protein sourcing economics.
Market Dynamics
ISO 22000 certification requirements are collapsing the supplier base as smaller processors fail audit cycles, concentrating supply among vertically integrated cooperatives with captive laboratory infrastructure and traceability systems.
Growth Catalysts
- Sports nutrition formulation demand:Athlete-grade protein fortification drives whey protein fractionation capacity expansion across North American and European processing facilities.
- EU Green Deal sustainability mandates:Carbon footprint disclosure requirements favor pasture-based dairy sourcing from New Zealand and Ireland with verified lifecycle data.
- China NMPA infant formula registration:Clinical substantiation protocols for hydrolyzed milk proteins create qualified supplier premiums for export-certified manufacturers.
Market Restraints
- Raw milk input cost volatility:Feed grain price fluctuations and drought cycles in Oceania transmit directly to protein concentrate margins without pass-through mechanisms.
- Precision fermentation substitution:Microbial whey protein from Perfect Day and competitors threatens conventional dairy protein economics in sports nutrition applications.
- EU REACH processing aid restrictions:Enzyme and solvent disclosure protocols complicate ion exchange fractionation for export-bound ingredients.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Indonesia and Vietnam infant formula sectors lack domestic protein isolate production, creating import substitution openings for certified suppliers.
- Cellular agriculture hybrid formulations:Blended dairy-cultured protein products command premium positioning in European clean-label segments.
- SAMR functional food registration pathway:China's expanded health food catalog permits novel protein positioning for senior nutrition and metabolic health applications.
Industry Challenges
- Membrane filtration engineering talent scarcity:Specialized process engineers with ultrafiltration and diafiltration expertise command premium compensation and extended recruitment cycles.
- Allergen threshold harmonization delays:Discrepancies between FDA, EFSA, and Food Standards Australia New Zealand labeling thresholds complicate multi-market packaging and liability exposure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Milk Protein Market |
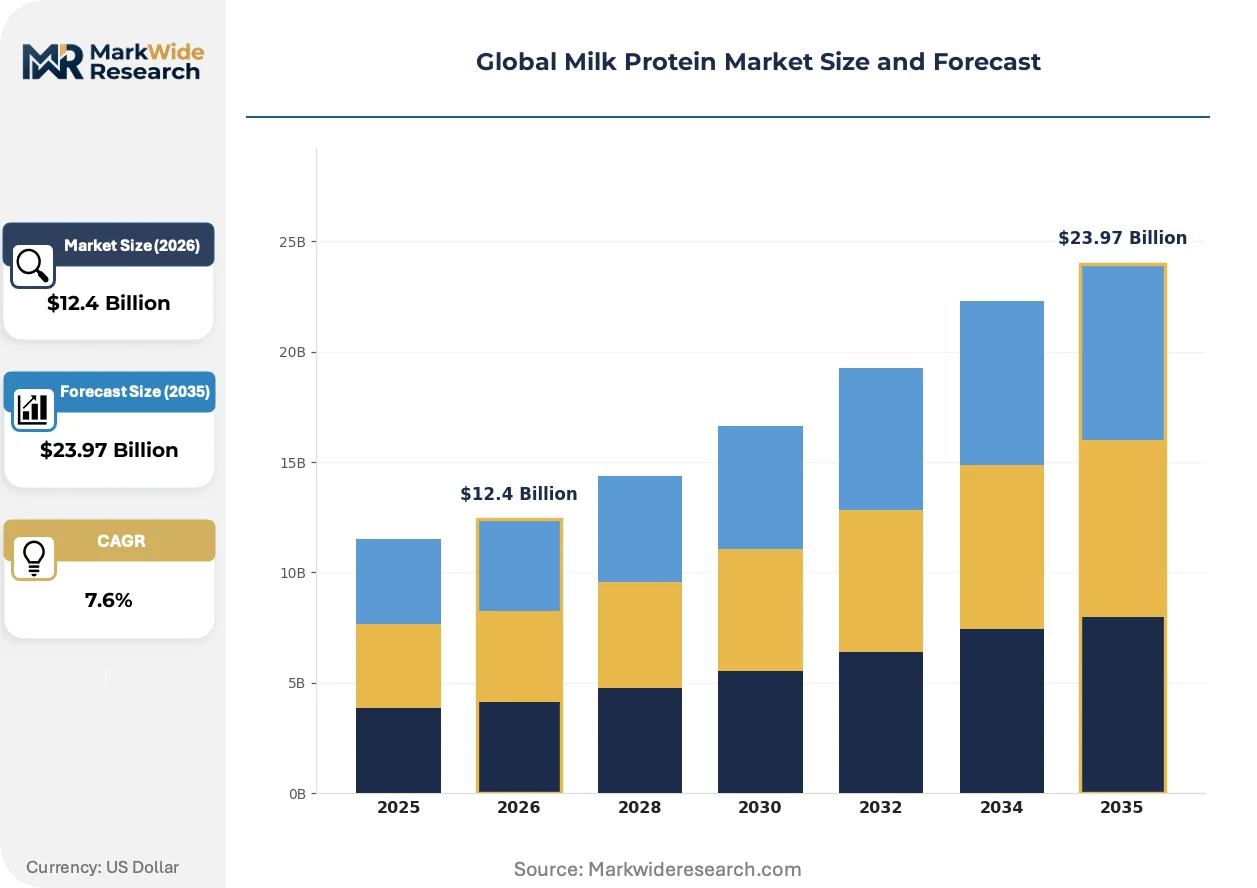
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $23.97 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein, Casein Protein, Milk Protein Concentrate, Milk Protein Isolate, Hydrolyzed Milk Protein Application: Sports Nutrition, Infant Formula, Bakery & Confectionery, Dairy Products, Dietary Supplements, Functional Foods End User: Food & Beverage Manufacturers, Nutraceutical Companies, Pharmaceuticals, Animal Nutrition Providers, Personal Care Producers Form: Powder, Liquid, Concentrate, Spray-Dried, Freeze-Dried |
| Companies Covered | Fonterra Co-operative Group Limited, Glanbia plc, Lactalis Ingredients, Kerry Group plc, Arla Foods Ingredients, Royal FrieslandCampina N.V., Saputo Inc., Nestlé S.A., Danone S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Milk Protein Market Shifts & Advancements
Membrane filtration advances and precision fermentation alternatives are fragmenting traditional dairy protein sourcing models while regulatory disclosure requirements reshape competitive qualification barriers.
Cross-flow microfiltration with ceramic membranes is decomposing conventional cheese whey dependency by enabling direct milk protein concentration without casein-whey separation. Infant formula manufacturers in the Netherlands and Germany adopt this technology to secure isolate supply independent of cheese production cycles. The process is decomposing geographic concentration risk by permitting protein extraction at smaller scale across distributed dairy regions.
EU CSRD sustainability reporting mandates now require Scope 3 dairy supply chain disclosure from protein ingredient purchasers. Large food manufacturers face audit liability for upstream methane and land-use data gaps. European sports nutrition brands accelerate supplier consolidation toward cooperatives with farm-level traceability infrastructure.
Direct-to-manufacturer ingredient sourcing is compressing traditional distributor margins in North American and Asian markets. Bulk buyers now contract directly with New Zealand and Irish processors for containerized isolate shipments, bypassing regional warehousing intermediaries. This pattern is most visible in Chinese infant formula manufacturers establishing captive procurement offices in Auckland and Dublin.
Global Milk Protein Market Segmentation
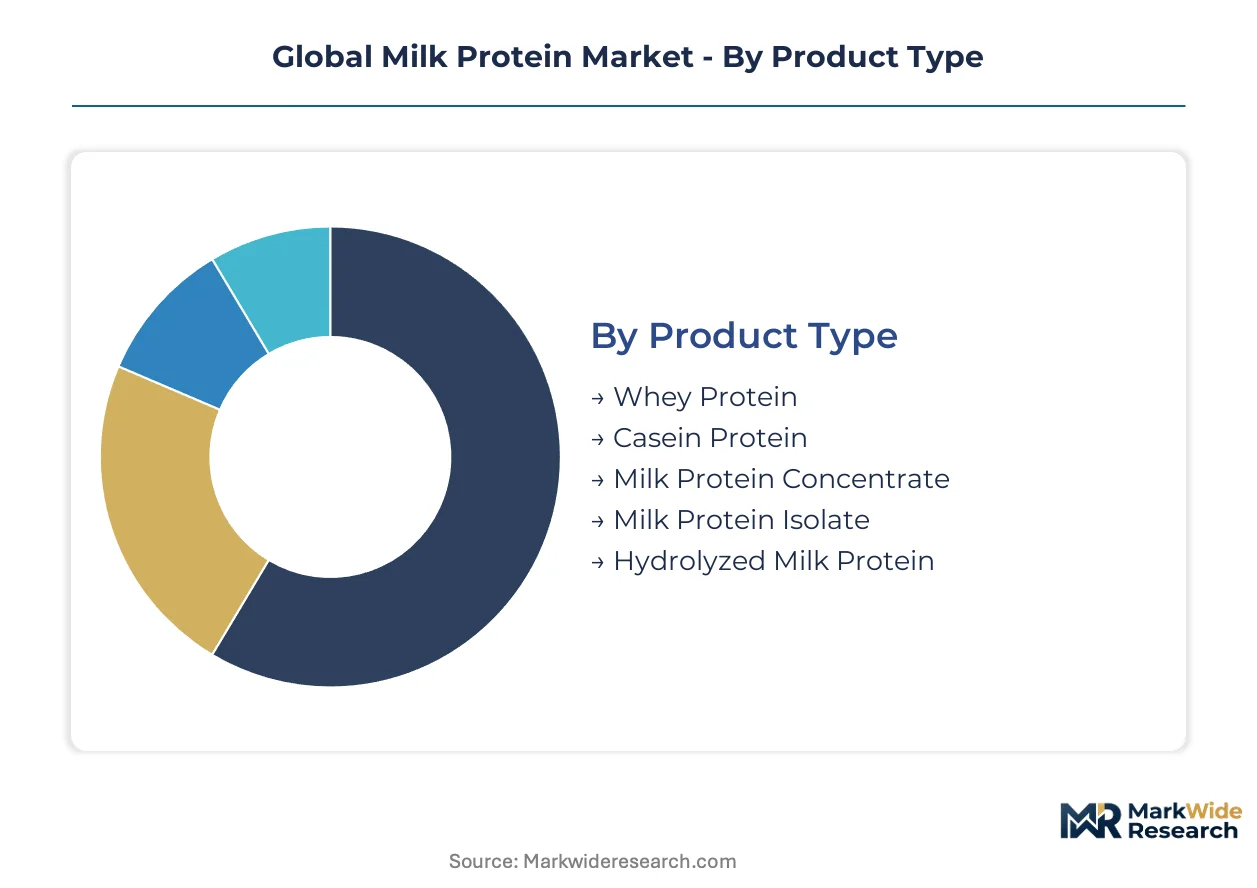
Milk protein segmentation reveals distinct channel economics where whey fractions command sports nutrition premiums while casein variants anchor bakery functional properties. Form and application categories dictate margin structures, with infant-grade isolates requiring clinical substantiation that filters supplier participation.
Product Type:
Whey protein flows predominantly through sports nutrition distributors and direct-to-manufacturer contracts, while casein variants route through bakery ingredient suppliers and confectionery formulators.
- Whey Protein:Rapidly absorbed amino acid profile with 80-90% protein concentration in isolate form. Sports nutrition brands in the United States and Germany concentrate procurement here, driven by athlete-grade fortification protocols that specify leucine content thresholds.
- Casein Protein:Slow-digesting micellar structure delivers sustained amino acid release over 6-8 hours. Bakery applications in France and Italy utilize gelation properties for texture modification, constrained by seasonal milk supply fluctuations that compress margin visibility.
- Milk Protein Concentrate:Intermediate 40-85% protein content serves cost-sensitive fortification. Processed cheese manufacturers represent anchor demand.
- Milk Protein Isolate:90%+ protein purity with minimal lactose residue. Infant formula registration requirements in China filter supplier qualification.
- Hydrolyzed Milk Protein:Enzymatically pre-digested fractions with reduced allergenic potential. Hypoallergenic formula segments specify clinical validation documentation.
Whey protein dominates installed base. Hydrolyzed variants are where expansion concentrates.
Application:
Cost tier stratification separates pharmaceutical-grade infant formula specifications from commodity bakery fortification, with sports nutrition occupying premium-mid positioning.
- Sports Nutrition:Protein powders, ready-to-drink beverages, and bar formulations requiring rapid amino acid bioavailability. North American contract manufacturers consolidate volume here, facing substitution pressure from precision fermentation alternatives.
- Infant Formula:Stringent protein ratio requirements and hydrolysate specifications for allergen management. Chinese NMPA registration creates qualified supplier premiums.
- Bakery & Confectionery:Water-binding and emulsification functional properties command technical specification adherence. European industrial bakeries specify foaming stability metrics.
- Dairy Products:Greek yogurt and processed cheese fortification utilizing MPC cost advantages.
- Dietary Supplements:Capsule and tablet excipient applications with moderate purity requirements.
- Functional Foods:Senior nutrition and metabolic health positioning under China's expanded SAMR health food catalog.
Infant formula commands highest purity premiums. Functional foods represent the steepest expansion trajectory.
End User:
Volume concentration varies sharply, with food and beverage manufacturers absorbing bulk commodity flows while pharmaceutical buyers specify small-batch clinical-grade isolates.
- Food & Beverage Manufacturers:Integrated dairy processors and branded food companies with captive formulation capabilities. New Zealand and Irish cooperatives secure long-term supply agreements here.
- Nutraceutical Companies:Sports nutrition and supplement brands with direct-to-consumer distribution. Direct sourcing from fractionation facilities is compressing traditional distributor margins.
- Pharmaceuticals:Clinical nutrition and specialized medical foods requiring GMP certification and batch documentation.
- Animal Nutrition Providers:Calf milk replacer and pet food applications with lower protein purity thresholds.
- Personal Care Producers:Cosmetic-grade hydrolysates for hair and skin conditioning formulations.
Food and beverage manufacturers dominate procurement volume. Nutraceutical companies are where channel disruption concentrates.
Form:
Supply concentration clusters on powder formats, with liquid and specialized dried forms serving niche specification requirements.
- Powder:Standardized bulk format with 12-24 month stability under controlled humidity. Containerized ocean freight from Auckland and Dublin anchors intercontinental supply.
- Liquid:Refrigerated concentrate requiring cold chain integrity, primarily serving regional dairy processors in proximity to fractionation facilities.
- Concentrate:Intermediate moisture content reducing transport economics for short-haul distribution.
- Spray-Dried:Rapid thermal processing preserving functional properties for instantized beverage applications.
- Freeze-Dried:Premium format retaining native protein structure for pharmaceutical and specialized clinical applications.
Powder commands installed base economics. Spray-dried formats are where functional innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Infant formula manufacturers in China absorb the highest-grade milk protein isolates, while sports nutrition brands in the United States and Germany drive whey protein fractionation capacity expansion.
China
NMPA infant formula registration requirements concentrate demand for hydrolyzed milk protein variants with clinical substantiation documentation. SAMR functional food catalog expansion permits novel protein positioning for senior nutrition applications. Shanghai-based procurement offices now coordinate direct containerized shipments from Auckland processors.
United States
FDA nutrition labeling requirements shape ingredient disclosure protocols for sports nutrition and dietary supplement channels. Athlete-grade protein fortification specifications drive leucine content thresholds in whey isolate procurement. California and Texas contract manufacturers consolidate volume through direct-to-processor contracting.
Germany
EFSA allergen threshold regulations interact with EU REACH processing aid restrictions to complicate ion exchange fractionation for export-bound ingredients. Industrial bakeries in Bavaria specify foaming stability metrics for casein protein gelation applications. The country's membrane filtration engineering talent scarcity extends recruitment cycles for ultrafiltration specialists.
New Zealand
Pasture-based dairy sourcing with verified lifecycle data satisfies EU Green Deal carbon footprint disclosure requirements. Fonterra's cooperative structure controls raw milk supply chains for fractionation facilities in Waikato and Canterbury. Auckland hosts captive procurement offices for Chinese infant formula manufacturers.
Netherlands
Cross-flow microfiltration with ceramic membranes enables direct milk protein concentration independent of cheese production cycles. Infant formula manufacturers in Friesland adopt this technology to secure isolate supply. The country's dairy cluster advances membrane filtration engineering for distributed protein extraction.
Global Milk Protein Market Competitive Landscape
Player mix skews toward dairy cooperatives with captive raw milk supply and specialized fractionation technology providers. Market structure concentrates among vertically integrated processors with ISO 22000 certification infrastructure and traceability systems. Two strategic archetypes dominate: pasture-based cooperatives leveraging sustainability credentials, and technology-specialized fractionators commanding premium positioning. Competitive moves center on direct-to-manufacturer sourcing compression and membrane filtration capacity expansion.
Among cooperative-structured processors, Fonterra Co-operative Group Limited and Royal FrieslandCampina N.V. occupy positions anchored in pasture-based supply chain control. Glanbia plc exemplifies the technology-specialized archetype through whey protein fractionation capabilities. Lactalis Ingredients represents European multi-site manufacturing scale. Kerry Group plc and Arla Foods Ingredients sit within the ingredient solutions tier serving branded food manufacturers.
| Leading Market Players |
|---|
| Fonterra Co-operative Group Limited |
| Glanbia plc |
| Lactalis Ingredients |
| Kerry Group plc |
| Arla Foods Ingredients |
| Royal FrieslandCampina N.V. |
| Saputo Inc. |
| Nestlé S.A. |
| Danone S.A. |
| Others |
Supply & Pricing Matrix
ISO 22000 certification gates both supplier qualification and price differentiation simultaneously, concentrating procurement among processors with captive laboratory infrastructure while collapsing margins for uncertified competitors unable to pass audit cycles.
Pricing Analysis
Cost-plus contracts with Global Dairy Trade indexation anchor intercontinental whey protein transactions, with Fonterra's fortnightly auction providing transparent price discovery for Oceania-origin isolates. Three-tier pricing structure across infant-grade, sports nutrition, and commodity bakery tiers reflects purity thresholds and clinical documentation requirements. Pricing pressure stems from precision fermentation alternatives threatening conventional dairy protein economics in North American sports nutrition channels. Bakery and confectionery manufacturers exhibit highest price sensitivity due to functional property substitutability, while infant formula buyers absorb premiums for NMPA-registered hydrolysate supply.
Supply Chain Analysis
Strategic stockpiling of spray-dried isolates dominates Chinese infant formula procurement, contrasting with just-in-time whey concentrate flows to North American contract manufacturers. Raw milk supply concentrates in New Zealand, Ireland, and the Netherlands, where pasture-based systems satisfy EU Green Deal carbon disclosure mandates. Feed grain price volatility and drought cycles in Oceania transmit directly to protein concentrate margins without contractual pass-through mechanisms. Distribution runs through direct-to-manufacturer containerized shipments from Auckland and Dublin, compressing traditional regional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery driven by post-drought Oceania milk supply normalization, though precision fermentation substitution threatens medium-term pricing power in sports nutrition segments.
For Market Incumbents: Fortify membrane filtration engineering capabilities through targeted recruitment in the Netherlands and Germany, where talent scarcity extends production ramp timelines. Deepen backward integration into farm-level traceability infrastructure to satisfy EU CSRD Scope 3 disclosure requirements and defend positioning against pasture-based cooperative competitors. Prioritize ISO 22000 certification maintenance as smaller processors fail audit cycles and collapse the supplier base.
For New Entrants and Emerging Players: Differentiate on precision fermentation-derived whey protein positioning for North American sports nutrition brands seeking clean-label alternatives to conventional dairy sourcing. Target underpenetrated Indonesian and Vietnamese infant formula markets where domestic isolate production remains absent and import substitution premiums persist. Pursue direct-to-manufacturer procurement relationships with Shanghai-based infant formula offices to bypass entrenched distributor networks.
For Investors and Strategic Acquirers: China's SAMR functional food catalog expansion reshapes the acquisition landscape, creating qualified supplier premiums for hydrolyzed protein manufacturers with clinical substantiation documentation. Long-term viability favors technology-specialized fractionators with ceramic membrane capabilities over commodity processors exposed to raw milk cost volatility. Monitor Perfect Day and competitor microbial protein scale-up as the signal indicating conventional dairy protein economics displacement thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Ceramic Membrane Capacity Expansion | Cross-flow microfiltration enables direct milk protein concentration independent of cheese production cycles. |
| Farm-Level Traceability Infrastructure Investment | EU CSRD mandates Scope 3 dairy supply chain disclosure from protein ingredient purchasers. |
| Precision Fermentation Partnership | Microbial whey protein from Perfect Day threatens conventional dairy protein sports nutrition positioning. |
| Direct-to-Manufacturer Procurement Office Establishment | Chinese infant formula manufacturers bypass regional warehousing intermediaries through Auckland and Dublin offices. |
| Clinical Substantiation Documentation Investment | NMPA infant formula registration requirements filter supplier participation for hydrolyzed protein variants. |
Research Methodology
Initial hypotheses were tested against primary input from membrane filtration process engineers, infant formula procurement directors, sports nutrition brand formulators, and dairy cooperative supply chain managers, and refined through secondary validation against Fonterra Global Dairy Trade auction records, EU EFSA allergen threshold documentation, China NMPA registration filings, and SEC 10-K disclosures from listed ingredient processors. Bottom-up volume modeling across fractionation facility capacities triangulated with top-down demand segmentation from end-use applications.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects, with segmentation modeling spanning product type purity tiers, application specification requirements, end-user procurement scale, and regional regulatory clusters. CAGRs derive from facility capacity expansion announcements, infant formula birth rate correlations, and sports nutrition brand formulation shift indicators. Forecast inputs incorporate EU Green Deal carbon disclosure implementation timelines and precision fermentation commercial scale-up milestones.
The analysis sits within stated boundaries; outcomes outside sustained Oceania pasture productivity or accelerated microbial protein cost parity would require recalibration. Forecasts reflect documented assumptions regarding NMPA registration pathway stability and membrane filtration engineering labor market conditions. Revision becomes warranted when precision fermentation production costs cross conventional dairy protein extraction economics thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Probiotic Yogurt Market
Dairy Products
Global Yogurt Powder Market
Dairy Products
Drinkable Yogurt Market
Dairy Products
Filled Cheese Market
Dairy Products
Fermented Dairy Products Market
Dairy Products
Milk Protein Concentrate Market
Dairy Products
Dairy Protein Market
Dairy Products
Lactose and Derivative Market
Dairy Products
Middle East and Africa Flavored Milk Market
Dairy Products
United States Milk Protein Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Global Specialty Cheese Market
Dairy Products
Fruit Yogurt Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
Low Fat Cream Cheese Nutrition Market
Dairy Products
Table Butter Market