
 United Kingdom Whey Protein Market | 2026-2036
United Kingdom Whey Protein Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Whey Protein Market Analytics
FSSA novel food classification is hardening the cost-of-entry calculus for whey protein importers seeking UK market access. Arla Foods amba leverages its cooperative dairy infrastructure to secure traceable whey streams from Danish and Swedish farms. Glanbia PLC sustains R&D intensity in fractionation technology that yields higher-purity isolates. Myprotein anchors its position through direct-to-consumer channel control and aggressive digital marketing spend.
United Kingdom whey protein comprises the soluble protein fraction isolated from cheese whey, typically containing beta-lactoglobulin, alpha-lactalbumin, and immunoglobulins with protein concentrations ranging from 35% to 90% depending on processing grade, serving primarily as a bioavailable amino acid source for muscle protein synthesis and nutritional fortification. Whey Protein Isolate commands premium positioning due to its lower lactose and fat profile, while Hydrolyzed Whey Protein captures the fastest-growing functional niche among consumers with digestive sensitivities. Sports Nutrition dominates application volumes, though Functional Foods represents an emerging margin pool as bakery and dairy processors incorporate whey for texture and protein enrichment.
The Food Standards Agency enforces novel food assessments for innovative whey derivatives, while Trading Standards monitors label claims under UK nutrition and health claims regulations. BSI technical standards for food-grade protein specifications further constrain product formulation and sourcing flexibility. Stakeholders must monitor divergence between retained EU food law and emerging Great Britain-specific regulatory frameworks to anticipate compliance cost trajectories.
Market Dynamics
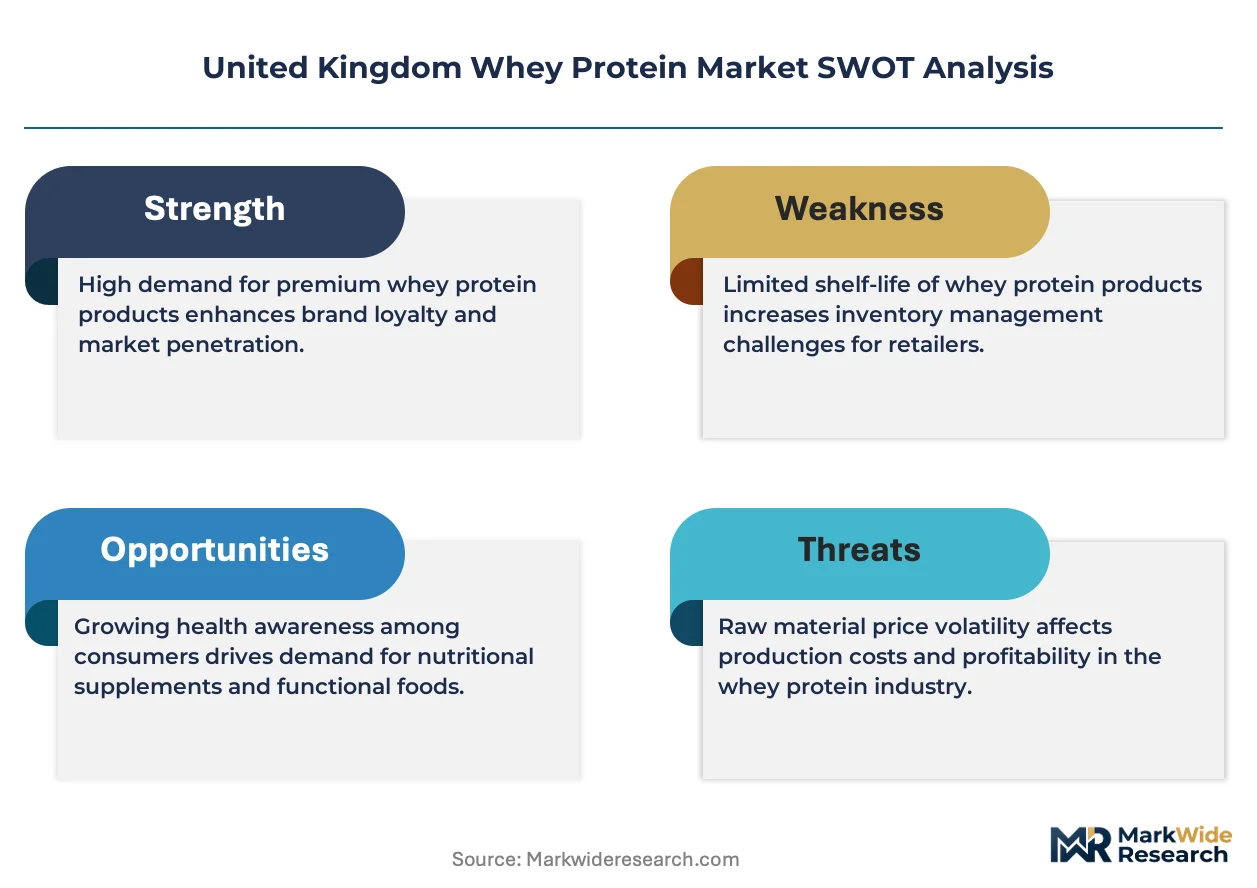
The Food Standards Agency's novel food classification regime is tightening compliance thresholds for whey protein importers, forcing supply chain reconfiguration toward traceable European dairy streams and raising capital requirements for market entry.
Growth Catalysts
- Sports nutrition application expansion:Amateur athletes and weekend warriors in Greater London and the South East are driving volume uptake as gym penetration deepens and protein fortification becomes routine in training regimens.
- Trading Standards label enforcement:Stricter monitoring of nutrition and health claims under UK regulations is professionalizing the competitive landscape and advantaging compliant domestic formulators.
- Hydrolyzed whey technology maturation:Advanced enzymatic fractionation is unlocking digestive-tolerance positioning for consumers with lactose sensitivities, expanding addressable demand beyond traditional bodybuilding segments.
Market Restraints
- Input cost volatility:Cheese whey supply fluctuations from Danish and Swedish cooperative dairies create margin pressure for concentrate processors dependent on spot purchasing.
- Regulatory friction:Divergence between retained EU food law and emerging Great Britain-specific frameworks generates compliance uncertainty for formulations crossing the Irish Sea.
- Substitution threat:Plant-based protein isolates from pea and fava bean sources are capturing shelf space in premium retail channels targeting sustainability-conscious consumers.
Strategic Opportunities
- Functional foods white space:Bakery and dairy processors in the Midlands are incorporating whey for texture and protein enrichment, opening margin pools beyond sports nutrition.
- BSI standards alignment:Early adoption of technical specifications for food-grade protein creates first-mover positioning for export-ready manufacturers targeting Commonwealth markets.
- Direct-to-consumer channel innovation:Subscription models and digital-native branding are bypassing traditional wholesale distribution in Greater Manchester and Birmingham urban clusters.
Industry Challenges
- Fractionation talent scarcity:Specialized protein chemists and process engineers with membrane filtration expertise command premium compensation, constraining R&D scaling for mid-tier processors.
- Certification timeline compression:Novel food assessments from the Food Standards Agency are extending product launch cycles, requiring working capital buffers for inventory holding during approval windows.
- Legacy system integration:ERP and traceability software from dairy cooperative origins requires costly adaptation to meet UK-specific digital reporting mandates for imported concentrates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Whey Protein Market |
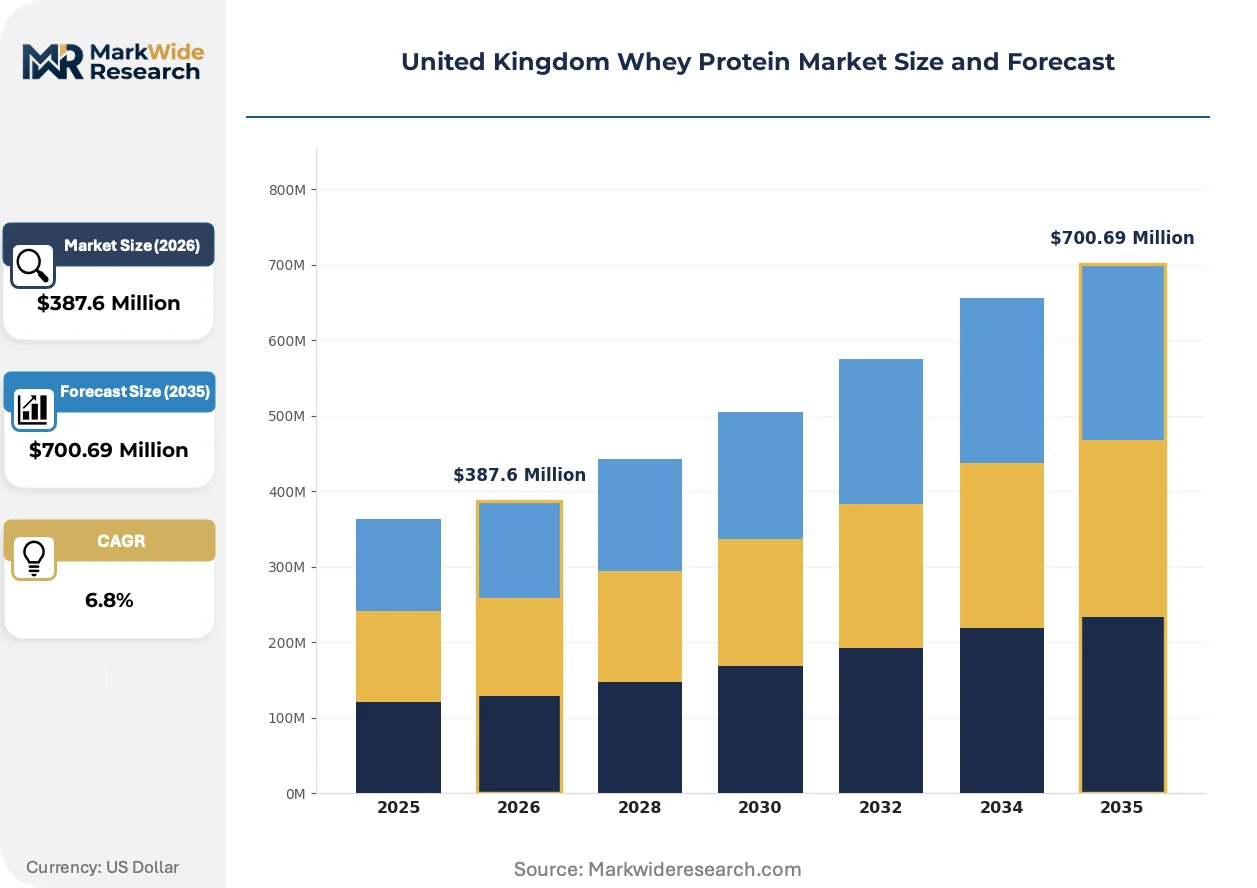
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whey Protein Concentrate, Whey Protein Isolate, Hydrolyzed Whey Protein, Native Whey Protein Application: Sports Nutrition, Dietary Supplements, Functional Foods, Infant Nutrition Form: Powder, Liquid, Bars, Ready-to-Drink End User: Athletes, Bodybuilders, Health Enthusiasts, Elderly |
| Companies Covered | Arla Foods amba, First Milk Limited, Glanbia PLC, Kerry Group plc, Royal FrieslandCampina N.V, Carbery Food Ingredients Limited, Volac International Limited, Myprotein, Optimum Nutrition, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Whey Protein Market Evolving Landscape
Membrane filtration advances and enzymatic processing are compressing purity thresholds while regulatory divergence between UK and EU frameworks is reshaping sourcing geography. Demand patterns are fragmenting across amateur athletic, clinical nutrition, and mainstream food fortification segments.
Cold-processed microfiltration is overtaking traditional heat-based whey isolation in premium isolate production. Sports nutrition brands serving the South East are adopting this technology to preserve bioactive peptide integrity. The shift is overtaking conventional ion-exchange methods in new facility investment decisions, compressing capital allocation timelines for older thermal processing assets.
Retained EU novel food assessments continue governing innovative whey derivatives while Great Britain-specific frameworks emerge through secondary legislation. Food Standards Agency enforcement is hardening documentation requirements for hydrolyzed and bioactive fractions. Hydrolyzed whey protein manufacturers are responding by front-loading regulatory submissions and building dedicated compliance teams in London.
Amateur athletes are consolidating purchase decisions around certification-driven preference hierarchies, prioritizing Informed Sport and Banned Substance Control Group accreditation over price positioning. Specialty retailers in Edinburgh and Glasgow are curating assortments around these third-party validations, displacing unverified bulk offerings. This pattern is most visible in Scottish urban markets where cycling and triathlon participation rates exceed national averages.
United Kingdom Whey Protein Market Segmentation
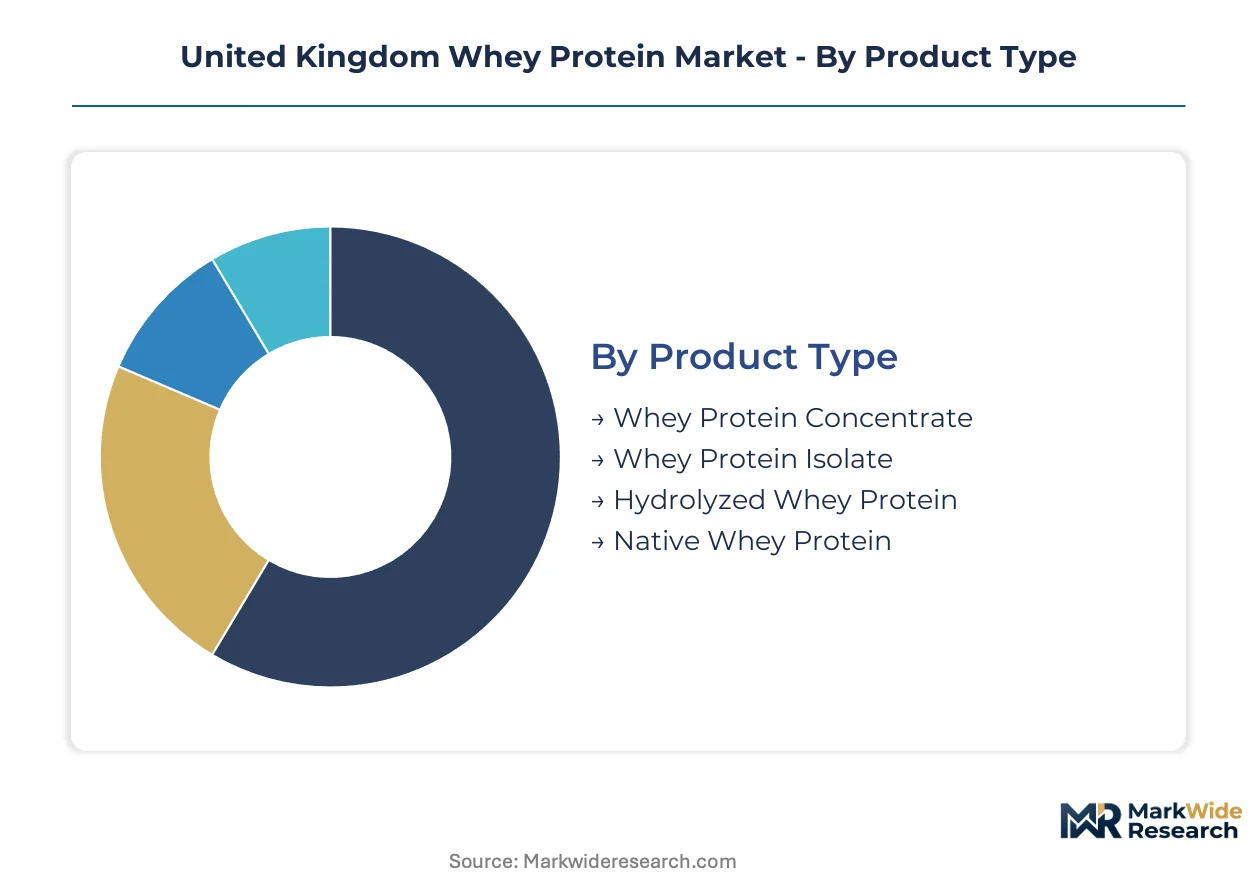
Whey protein segmentation in the United Kingdom reflects divergent processing economics and distinct channel access requirements. Each category maps to specific regulatory exposure and margin architecture that shapes supplier strategy.
Product Type:
Supply concentration among Danish and Swedish cooperative dairies funnels raw whey streams toward differentiated processing tiers based on capital intensity and technical capability.
- Whey Protein Concentrate:Contains 35-80% protein by weight with retained lactose and lipid fractions, making it the cost-accessible entry point for mass-market sports nutrition brands. Demand clusters in Greater Manchester and Birmingham urban clusters where price-sensitive amateur athletes drive volume through direct-to-consumer channels.
- Whey Protein Isolate:Achieves 90%+ protein purity through microfiltration or ion-exchange processing, commanding premium positioning in South East retail channels. Gym penetration in Greater London sustains uptake among serious recreational athletes prioritizing macronutrient efficiency.
- Hydrolyzed Whey Protein:Pre-digested enzymatic fractions reduce allergenic potential for lactose-sensitive consumers.
- Native Whey Protein:Cold-processed isolation preserves undenatured protein structures for bioactive peptide applications.
Whey Protein Concentrate absorbs the bulk of installed capacity; Hydrolyzed Whey Protein is expanding most quickly.
Application:
End-use fragmentation across athletic, clinical, and mainstream food sectors creates divergent certification requirements and formulation expertise demands.
- Sports Nutrition:Protein powders, pre-workout formulations, and recovery drinks dominate volume consumption. Trading Standards enforcement of nutrition claims in Greater London and the South East professionalizes competitive positioning for compliant domestic formulators.
- Functional Foods:Bakery and dairy processors incorporate whey for texture modification and protein fortification. Midlands food manufacturers are opening margin pools beyond traditional sports applications.
- Dietary Supplements:Capsule and tablet formats target convenience-oriented health enthusiasts.
- Infant Nutrition:Specialized fractionation meets stringent Food Standards Agency purity thresholds for pediatric applications.
Sports Nutrition commands dominant revenue share; Functional Foods demonstrates the steepest expansion trajectory.
Form:
Manufacturing asset allocation follows channel control logic, with powder production concentrating near dairy processing infrastructure and ready-to-drink capacity locating near urban demand clusters.
- Powder:Bulk dry blending dominates manufacturing economics and enables flavor customization at contract packaging facilities. Scottish urban markets show preference for unflavored bulk formats among cycling and triathlon participants.
- Ready-to-Drink:Aseptic filling requirements and cold-chain logistics create barrier to entry for new market entrants. Convenience positioning captures commuter demand in Edinburgh and Glasgow metropolitan areas.
- Liquid:Concentrated protein solutions serve industrial food manufacturing applications.
- Bars:Extrusion and coating technologies integrate whey with carbohydrate matrices for portable nutrition.
Powder maintains the largest production footprint; Ready-to-Drink is climbing the fastest.
End User:
Customer archetypes stratify by certification sensitivity, purchase frequency, and channel preference, driving distinct marketing investment patterns.
- Athletes:Amateur competitors in cycling, triathlon, and functional fitness prioritize Informed Sport and Banned Substance Control Group accreditation. Scottish retailers curate assortments around third-party validation.
- Health Enthusiasts:Mainstream consumers integrating protein into routine wellness regimens drive volume growth in suburban retail channels.
- Bodybuilders:Traditional strength sports participants sustain demand for high-dose protein delivery formats.
- Elderly:Sarcopenia prevention and clinical nutrition applications require specialized formulation and medical channel access.
Athletes generate the highest per-capita expenditure; Health Enthusiasts are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for whey protein concentrates heavily in Greater London and the South East, where gym penetration rates and premium retail distribution density create the UK's highest per-capita consumption clusters.
Greater London and the South East
Amateur athletes and weekend warriors sustain volume growth through specialized sports nutrition retailers and direct-to-consumer subscription models. Trading Standards enforcement of nutrition and health claims operates most intensively in this region, professionalizing competitive positioning for compliant domestic formulators. Central London and Brighton host the densest concentrations of Informed Sport-certified product assortments.
Midlands
Functional food manufacturers in Birmingham and Leicester incorporate whey protein for bakery texture modification and dairy fortification applications. The Food Standards Agency maintains regional inspection capacity for novel food assessments at its Birmingham office. Derbyshire and Nottinghamshire food processing corridors are expanding contract manufacturing capacity for whey-enriched consumer goods.
North England
Greater Manchester anchors direct-to-consumer channel innovation with digital-native brands bypassing traditional wholesale distribution. Price-sensitive amateur athletes in Liverpool and Leeds drive Whey Protein Concentrate volumes through bulk purchasing platforms. Yorkshire dairy cooperatives supply traceable whey streams to regional fractionation facilities.
Scotland
Cycling and triathlon participation rates in Edinburgh and Glasgow exceed national averages, creating certification-driven preference hierarchies around third-party validated products. Scottish retailers curate assortments emphasizing Banned Substance Control Group accreditation over price positioning. Aberdeen's clinical nutrition research cluster explores whey protein applications for sarcopenia prevention in elderly populations.
Wales
Dairy processing infrastructure in rural Welsh counties supplies raw whey streams to English fractionation facilities under cross-border supply arrangements. The Welsh Government's food and drink sector support programs incentivize traceability system investments for cooperative dairy suppliers. Cardiff metropolitan demand remains secondary to English urban clusters but shows accelerating health enthusiast segment growth.
United Kingdom Whey Protein Market Competitive Landscape
Scandinavian cooperative dairies anchor one tier; Irish and British specialists hold processing and formulation positions. The market structure reflects moderate consolidation among upstream whey suppliers alongside fragmentation in branded finished goods. Three archetypes dominate: cooperative-backed dairy processors with captive raw material access, specialized fractionation technology operators, and direct-to-consumer digital brands with channel control advantages. Competitive moves concentrate on backward integration into traceable dairy sourcing and regulatory compliance capacity building for Food Standards Agency novel food assessments.
Within the cooperative processor tier, Arla Foods amba and Royal FrieslandCampina N.V represent European dairy-backed supply security. Glanbia PLC occupies a position among specialized nutrition ingredient operators with advanced fractionation capabilities. Myprotein anchors the direct-to-consumer archetype through digital-native market presence and subscription model infrastructure.
| Leading Market Players |
|---|
| Arla Foods amba |
| First Milk Limited |
| Glanbia PLC |
| Kerry Group plc |
| Royal FrieslandCampina N.V |
| Carbery Food Ingredients Limited |
| Volac International Limited |
| Myprotein |
| Optimum Nutrition |
| Others |
Value Network & Pricing Analysis
Amateur athletes in Greater Manchester and Birmingham urban clusters anchor volume demand for economy-grade whey protein concentrates, forcing a three-tier pricing structure across premium, standard, and economy levels that rewards traceable sourcing and certification investment.
Pricing Analysis
Volume concentrates in Whey Protein Concentrate segments while margins pool in Whey Protein Isolate and Hydrolyzed tiers. Price differentiation hinges on Informed Sport certification status and microfiltration purity grades. Pricing pressure stems from plant-based protein substitution in premium retail channels. Health enthusiasts in suburban clusters show highest price sensitivity; amateur triathletes and cyclists in Scottish markets accept certification premiums.
Supply Chain Analysis
Direct-to-consumer channels handle digital-native brand demand in Greater Manchester and Birmingham while traditional wholesale distribution serves Midlands food processors. Raw whey streams concentrate in Denmark, Sweden, and Yorkshire cooperative dairies. Membrane filtration equipment and enzymatic processing inputs draw from German and Dutch specialty suppliers. Single-source vulnerability exists for cold-processed microfiltration capacity. Distribution runs through South East retail networks and Scottish specialty retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food Standards Agency novel food assessment timelines are compressing product launch cycles and forcing working capital buffers that weaker formulators cannot sustain, making this market a consolidation play for well-capitalized operators.
For Market Incumbents: Lock in traceable whey streams from Danish and Swedish cooperative dairies through long-term offtake agreements. Deepen backward integration into cold-processed microfiltration capacity to preserve bioactive peptide integrity against plant-based substitution threats. Prioritize dedicated compliance team investment in London to navigate Food Standards Agency documentation requirements. For New Entrants and Emerging Players: The gap between premium isolate pricing and economy concentrate positioning opens white space in mid-tier hydrolyzed formats for lactose-sensitive consumers. Target Midlands functional food processors seeking whey for bakery texture modification. Pursue direct-to-consumer subscription models in underserved Welsh urban clusters with digital-native branding. For Investors and Strategic Acquirers: The window for entry favors specialized fractionation technology operators with membrane filtration expertise. Long-term viability rests on regulatory compliance capacity and captive dairy sourcing. Watch Food Standards Agency enforcement intensity as inflection indicator for compliance cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Traceable Dairy Sourcing | Arla Foods amba leverages cooperative infrastructure to secure Danish and Swedish whey streams. |
| Regulatory Compliance Capacity Buildout | Dedicated London-based teams navigate Food Standards Agency novel food assessment timelines. |
| Cold-Processed Microfiltration Investment | Preserved bioactive peptides command premium positioning in South East retail channels. |
| Direct-to-Consumer Channel Expansion | Subscription models bypass wholesale distribution in Greater Manchester urban clusters. |
| Functional Foods Partnership Development | Midlands bakery and dairy processors incorporate whey for texture and protein enrichment. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with sports nutrition brand managers, dairy cooperative procurement leads, Food Standards Agency compliance officers, Midlands food processing R&D directors, and Scottish specialty retail buyers. Food Standards Agency novel food assessment databases, BSI technical standards documentation, Nielsen retail audit data, and cooperative dairy production records supplied validation layers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Granularity extended to product type, application, form, and end user dimensions with regional disaggregation across Greater London, South East, Midlands, North England, Scotland, and Wales. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Forecast inputs incorporated gym penetration rates, Informed Sport certification adoption curves, and enzymatic processing technology maturation timelines across the projection horizon.
Inputs from Food Standards Agency assessment databases and cooperative dairy production records were available through the study window; gaps in real-time spot pricing for cheese whey feedstocks introduce uncertainty bands around margin projections. Forecasts reflect assumptions regarding regulatory divergence stabilization and plant-based protein substitution elasticity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Products
Global Cultured Dairy Products Market
Dairy Products
Russia Whey Protein Market
Dairy Products
Skimmed Milk Market
Dairy Products
Sweetened Condensed Milk Market
Dairy Products
Asia-Pacific Yogurt Market
Dairy Products
Japan Casein Market
Dairy Products
Plain Yogurt Market
Dairy Products
Global Milk Protein Market
Dairy Products
Donkey Milk Market
Dairy Products
Cream Powder Market
Dairy Products
Organic Dairy Products Market
Dairy Products
Low Fat Yogurt Calories Market
Dairy Products
Halal Cheese Market
Dairy Products
Low Temperature Pasteurized Milk Market
Dairy Products
North America Condensed Milk Market
Dairy Products
Middle East and Africa UHT Milk Market