
 Emulsifier Enhancers Market | 2026-2036
Emulsifier Enhancers Market Size, Share, and Industry Trends Forecast 2026-2036
Emulsifier Enhancers Market Foresight
The EU Green Deal is realigning emulsifier enhancer procurement across European food manufacturing. Corbion N.V. leverages its biotechnology platform to develop fermentation-derived solutions that meet tightening sustainability criteria. BASF SE anchors its position through backward integration into bio-based feedstocks, reducing reliance on petrochemical precursors. Kerry Group plc differentiates via customized emulsifier systems for plant-based dairy alternatives, a segment where clean-label claims command premium positioning.
Emulsifier enhancers are functional additives that improve the stability, texture, and shelf life of heterogeneous mixtures by reducing interfacial tension between immiscible phases such as oil and water, typically comprising modified phospholipids, polysaccharide derivatives, or surfactant blends processed through enzymatic or chemical modification. Natural emulsifiers dominate value capture as food manufacturers reformulate away from synthetic variants to satisfy retailer clean-label mandates. The dairy products application segment leads volume consumption, though beverages represent the fastest-growing category where emulsion stability challenges intensify with rising oil-load functional drinks.
REACH registrations and EFSA safety assessments govern emulsifier enhancer compositions entering European food and cosmetic channels, while FDA food additive regulations and FSSAI standards in India shape permissible ingredient lists and labeling requirements in their respective jurisdictions. The EU AI Act and emerging digital product passport rules under CSRD will soon require traceability documentation across emulsifier supply chains. Stakeholders must monitor regulatory divergence between jurisdictions to avoid formulation lock-ins that restrict multi-market access.
Market Dynamics
Clean-label reformulation mandates from major retail chains are compressing formulation cycles for emulsifier enhancers, forcing ingredient suppliers to validate natural alternatives against synthetic baselines within shortened qualification windows.
Growth Catalysts
- EU Green Deal procurement alignment:European food manufacturers now embed sustainability criteria into emulsifier sourcing decisions, redirecting R&D budgets toward bio-based feedstock development.
- Plant-based dairy expansion:Oat, almond, and pea protein beverages require specialized emulsifier systems to stabilize oil-in-water emulsions at neutral pH, creating sustained formulation demand.
- Enzymatic modification advances:Lipase-catalyzed phospholipid restructuring delivers cleaner-label lecithin derivatives without solvent residues, satisfying retailer clean-label mandates.
Market Restraints
- Sunflower lecithin supply volatility:Ukraine and Russia supply over 60% of global sunflower seed oil, concentrating raw material risk in a geopolitically unstable corridor.
- REACH registration cost barriers:Novel emulsifier molecules require extensive toxicological dossiers, pricing out smaller ingredient developers from European market entry.
- Mono- and diglyceride substitution pressure:Clean-label formulators increasingly reject synthetic emulsifiers in favor of phospholipid or polysaccharide alternatives, eroding established product lines.
Strategic Opportunities
- India FSSAI alignment services:Western ingredient houses can capture share by pre-qualifying emulsifier systems for India's evolving food additive standards ahead of domestic competitors.
- Precision fermentation lipids:Microbially-derived phospholipids bypass agricultural commodity cycles entirely, offering supply security premiums to risk-averse manufacturers.
- Direct-to-bakery distribution:Bypassing traditional distributor networks, emulsifier suppliers now sell formulated systems directly to artisanal and industrial bakeries via technical service agreements.
Industry Challenges
- Food toxicologist recruitment gaps:EFSA-compliant safety dossier preparation requires specialized regulatory toxicology expertise that remains scarce across European ingredient sectors.
- Legacy equipment retrofit costs:Switching from synthetic to natural emulsifiers often requires pasteurization line recalibration and homogenizer pressure adjustments, complicating plant trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emulsifier Enhancers Market |
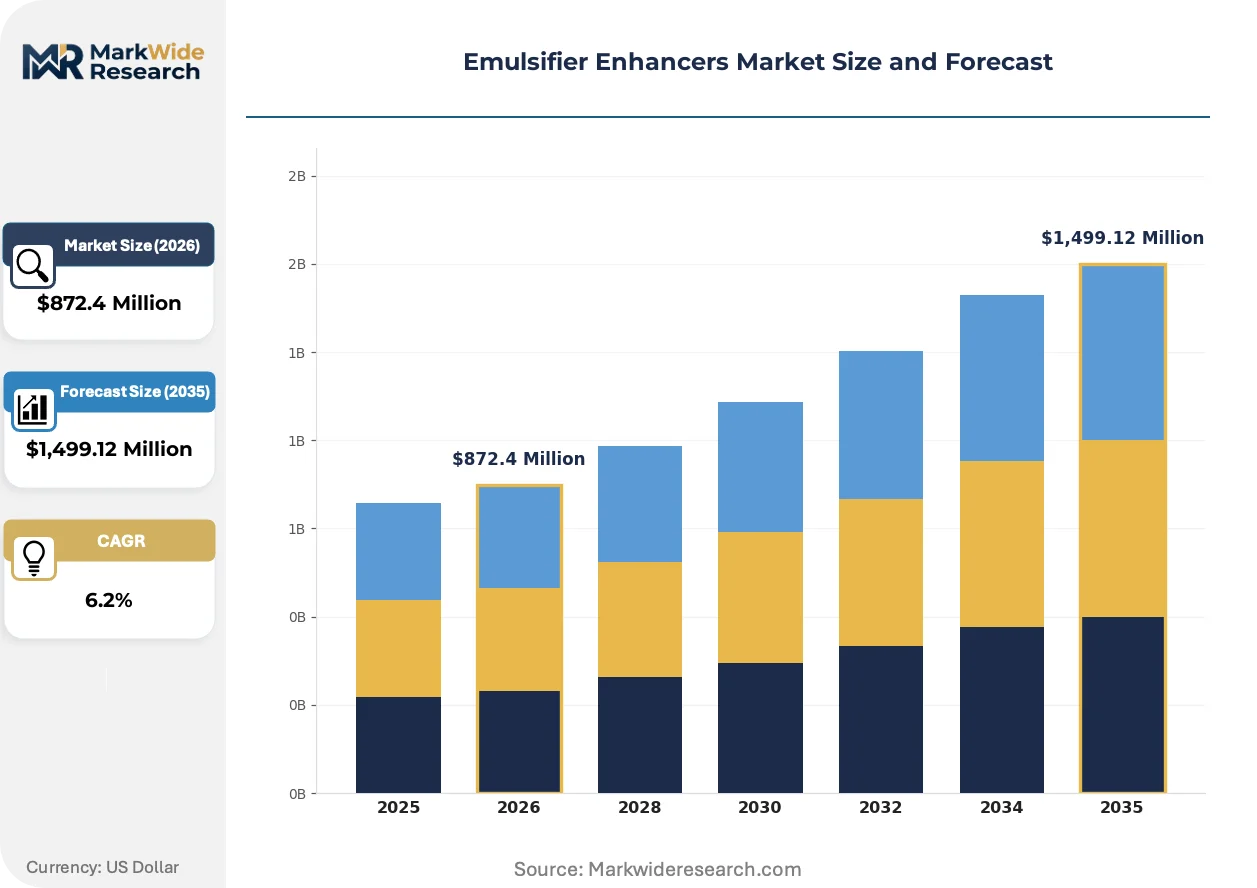
| Market Size in 2026 | $872.4 Million |
| Market Size in 2035 | $1,499.12 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Emulsifiers, Synthetic Emulsifiers, Modified Starches, Lecithin Application: Dairy Products, Sauces & Dressings, Bakery Products, Beverages End User: Food Industry, Cosmetics, Pharmaceuticals, Nutraceuticals Form: Powder, Liquid, Granules, Emulsions |
| Companies Covered | Kerry Group plc, Corbion N.V., BASF SE, Solvay S.A., International Flavors & Fragrances Inc., Archer Daniels Midland Company, Evonik Industries AG, Croda International Plc, Cargill, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emulsifier Enhancers Market Shifts & Advancements
Fermentation-derived emulsifiers are disrupting established extraction-based supply chains, while digital product passport requirements under CSRD force traceability investments that reshape procurement relationships.
Enzymatic interesterification of phospholipids is rewriting stability performance benchmarks for natural emulsifiers. Bakery and confectionery manufacturers in Germany and France are adopting these modified lecithins at accelerated qualification schedules. The technology is compressing price premiums between synthetic and natural emulsifier categories, forcing margin recalibration across supplier tiers.
REACH registrations now incorporate persistent, bioaccumulative, and toxic (PBT) screening criteria that disqualify certain ethoxylated surfactants from food-contact applications. Manufacturers serving European dairy processors must reformulate or face supply contract non-renewals. German ingredient houses are responding by accelerating bio-based polyglycerol ester development programs.
Clean-label certification requirements from retail chains are compressing supplier qualification timelines. North American bakery cooperatives now demand full supply chain documentation within 90-day windows, displacing traditional 12-month approval cycles. This pattern concentrates procurement among vertically integrated suppliers capable of rapid traceability disclosure, particularly visible in California and Pacific Northwest food manufacturing clusters.
Emulsifier Enhancers Market Segmentation
Emulsifier enhancer procurement patterns diverge sharply between commodity-scale food manufacturing and premium-positioned clean-label segments. Understanding these splits enables suppliers to calibrate R&D investment and distribution strategy against margin profiles rather than treating the market as uniform.
Product Type:
Volume concentrates in cost-optimized synthetic variants, while value capture tilts toward fermentation-derived natural systems commanding sustainability premiums.
- Natural Emulsifiers:Fermentation-derived phospholipids and plant-based lecithin derivatives processed through enzymatic modification. German dairy processors and French bakery cooperatives dominate demand as clean-label mandates from retail chains force reformulation away from petrochemical precursors.
- Synthetic Emulsifiers:Ethoxylated surfactants and mono-diglyceride formulations manufactured from petrochemical feedstocks. Established positions in emerging-market processed food sectors face erosion as REACH PBT screening disqualifies certain chemistries from European food-contact applications.
- Modified Starches:Hydroxypropylated and acetylated starch derivatives providing viscosity stabilization across neutral pH applications.
- Lecithin:Sunflower and rapeseed-sourced phospholipid concentrates, with supply security emerging as a procurement priority following Black Sea corridor disruptions.
Today's leader: Synthetic Emulsifiers. Tomorrow's challenger: Natural Emulsifiers.
Application:
End-use concentration patterns reveal where emulsion stability challenges command specialized formulation investment versus commodity substitution tolerance.
- Dairy Products:Yogurt, ice cream, and processed cheese applications requiring oil-in-water emulsion stability across variable shear and temperature conditions. Pan-European processors in the Netherlands and Ireland drive specification tightening as extended shelf-life claims become competitive necessities.
- Beverages:Functional drinks with elevated oil loads—omega-3 fortification, plant protein suspensions, and flavor emulsions—present the steepest expansion trajectory. Neutral pH stabilization requirements exceed conventional emulsifier performance envelopes, forcing qualification of modified lecithin and polyglycerol ester systems.
- Bakery Products:Clean-label bread and pastry applications where phospholipid derivatives replace synthetic dough conditioners.
- Sauces & Dressings:Mayonnaise and vinaigrette manufacturing where emulsion breakdown during freeze-thaw cycles drives specification requirements.
Dairy Products anchor current procurement volumes. Beverages are climbing the fastest as functional formulation complexity intensifies.
End User:
Regulatory pathway differentiation separates food-grade qualification requirements from cosmetic and pharmaceutical safety dossier standards.
- Food Industry:Dominant consumption segment spanning processed dairy, bakery, and beverage manufacturing. FDA food additive regulations and EFSA safety assessments govern permissible ingredient lists, with retailer clean-label mandates compressing supplier qualification timelines to 90-day windows in North American markets.
- Cosmetics:Skin care and personal care emulsions where REACH registration and persistent bioaccumulative toxic screening reshape permissible surfactant chemistries.
- Pharmaceuticals:Oral and topical drug delivery systems requiring excipient-grade emulsifier certification.
- Nutraceuticals:Dietary supplement softgels and lipid-based nutrient delivery formats.
Food Industry maintains procurement dominance. Cosmetics represents the regulatory-complexity frontier where ECHA guidance revisions force continuous reformulation.
Form:
Physical format selection tracks manufacturing equipment compatibility and supply chain handling economics across liquid-dominant beverage versus powder-preferred bakery segments.
- Liquid:Pumpable emulsifier concentrates preferred by high-volume dairy and beverage processors for direct-injection dosing. German ingredient houses supply formulated liquid systems to industrial bakeries via technical service agreements that bypass traditional distribution.
- Powder:Free-flowing granules with enhanced shelf stability for remote manufacturing locations and artisanal bakery segments. California and Pacific Northwest food manufacturing clusters concentrate procurement among vertically integrated suppliers capable of rapid traceability disclosure.
- Granules:Intermediate particle size formats bridging dissolution speed and handling convenience.
- Emulsions:Pre-dispersed systems reducing homogenization energy requirements in high-oil-load applications.
Liquid formats dominate industrial-scale procurement. Powder formats are gaining share fastest as direct-to-bakery distribution models expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial emulsifier production first scaled in European chemical corridors during the mid-twentieth century, establishing formulation expertise that now diffuses across diversified global manufacturing bases. Procurement patterns today track regulatory stringency and clean-label retail mandates more than historical production geography.
Germany
Pan-European dairy processors source reformulated emulsifier systems from ingredient houses concentrated in the Rhineland and Bavaria. REACH registrations and EFSA safety assessments govern permissible compositions entering food channels. The Hamburg-Bremen corridor anchors technical service agreements that bypass traditional distribution networks for direct bakery supply.
United States
California and Pacific Northwest food manufacturing clusters demand 90-day supplier qualification windows with full supply chain documentation. FDA food additive regulations shape permissible ingredient lists for clean-label bakery applications. Clean-label mandates from North American retail chains compress formulation cycles and concentrate procurement among vertically integrated suppliers.
France
Bakery and confectionery manufacturers accelerate adoption of enzymatically modified lecithins at compressed qualification schedules. EU Green Deal procurement alignment redirects R&D budgets toward bio-based feedstock development. The Paris Basin and Lyon corridor host fermentation-derived emulsifier development programs responding to REACH PBT screening criteria.
India
FSSAI standards on food-grade additives shape permissible ingredient lists and labeling requirements for domestic processed food sectors. Western ingredient houses capture share by pre-qualifying emulsifier systems ahead of domestic competitors. Maharashtra and Gujarat industrial corridors concentrate beverage manufacturing where oil-load functional drinks drive emulsion stability demand.
China
SAMR and GB standards govern food additive approvals for emulsifier enhancers entering domestic and export channels. Dual carbon goals accelerate biotechnology platform investments for fermentation-derived alternatives. Yangtze River Delta processors supply reformulated systems to pan-Asian dairy and beverage manufacturers.
Emulsifier Enhancers Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the emulsifier enhancer supply base. The market structure concentrates among diversified chemical conglomerates with backward integration into bio-based feedstocks and specialized ingredient houses with technical service capabilities. Three archetypes dominate: fermentation-platform biotechnology firms, petrochemical-anchored diversified suppliers, and application-focused formulation specialists. Competitive moves center on enzymatic modification technology licensing and direct-to-manufacturer distribution bypassing traditional wholesale channels.
Among European-anchored biotechnology platforms, Corbion N.V. exemplifies the fermentation-derived archetype, while BASF SE represents petrochemical-rooted diversification into bio-based feedstocks. Kerry Group plc occupies a position within the application-specialist tier, anchoring customized system development for plant-based dairy alternatives. These three patterns illustrate how regulatory pressure and clean-label retail mandates reshape competitive positioning without requiring identical strategic responses.
| Leading Market Players |
|---|
| Kerry Group plc |
| Corbion N.V. |
| BASF SE |
| Solvay S.A. |
| International Flavors & Fragrances Inc. |
| Archer Daniels Midland Company |
| Evonik Industries AG |
| Croda International Plc |
| Cargill, Incorporated |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between REACH-registered fermentation-derived systems and commodity synthetic alternatives drives parallel divergence in procurement economics and supplier qualification pathways. Food manufacturers in Germany and France pay sustainability premiums for bio-based phospholipids while processors in emerging markets optimize around sunflower lecithin spot positions, creating tiered supply relationships that reshape inventory strategies and contract structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates fermentation-derived natural emulsifiers from enzymatically modified lecithins and petrochemical-based synthetics. Price differentiation rests on REACH registration status and EFSA safety dossier completeness, with clean-label certification commanding substantial premiums. Cost compression in the synthetic tier is intensifying because REACH PBT screening disqualifies established ethoxylated surfactants from European food-contact applications. Artisanal bakeries in North America exhibit the highest price sensitivity, while pan-European dairy processors prioritize supply security over unit cost.
Supply Chain Analysis
REACH registration and FSSAI pre-qualification requirements gate supplier access to European and Indian food manufacturing channels respectively. Raw material sourcing concentrates in Ukraine and Russia for sunflower seed oil, Germany and France for rapeseed-derived phospholipids, and the Yangtze River Delta for fermentation-derived alternatives. Supply chain risk centers on Black Sea corridor disruptions that have destabilized sunflower lecithin availability. Distribution runs through technical service agreements that bypass traditional wholesale networks, with German ingredient houses supplying formulated liquid systems directly to industrial bakeries and dairy processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Emulsifier Enhancers Market has entered a late-cycle quality phase where specification premiums widen as clean-label mandates from North American and European retail chains displace commodity-grade alternatives. This shift rewards suppliers with fermentation-platform capabilities and REACH-compliant dossiers while eroding positions anchored in synthetic chemistries facing regulatory disqualification.
For Market Incumbents: Anticipate margin compression in mono- and diglyceride product lines as clean-label formulators accelerate substitution toward phospholipid and polysaccharide alternatives. Defensive repositioning requires backward integration into bio-based feedstock production and accelerated enzymatic modification technology licensing to capture premium-tier volume. Capacity expansion in fermentation-derived phospholipids within the Hamburg-Bremen corridor secures supply relationships with risk-averse pan-European dairy processors. For New Entrants and Emerging Players: FSSAI alignment services in India open a window for Western ingredient houses to capture share ahead of domestic competitors by pre-qualifying emulsifier systems for the country's evolving food additive standards. Precision fermentation lipids represent the most penetrable white-space opportunity, offering supply security premiums that bypass agricultural commodity cycles entirely. Direct-to-bakery distribution via technical service agreements provides the most viable go-to-market angle, displacing traditional distributor markups with formulation partnerships. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation-platform capabilities and REACH registration expertise concentrate among a limited pool of qualified European biotechnology firms. Long-term viability favors acquisition targets with enzymatic modification IP and established EFSA safety dossiers over commodity-scale synthetic producers facing regulatory headwinds. The signal to watch is ECHA guidance revisions on persistent bioaccumulative toxic screening criteria, which will trigger accelerated reformulation demand across European cosmetics and food-contact applications.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Microbially-derived phospholipids bypass Ukraine-Russia sunflower supply volatility for German dairy processors. |
| Enzymatic Modification Licensing | Lipase-catalyzed lecithin restructuring satisfies 90-day retailer qualification windows in California food clusters. |
| REACH Registration Acceleration | EFSA-compliant dossier completion secures contract renewals with pan-European dairy manufacturers facing PBT screening. |
| Direct-to-Bakery Distribution | Technical service agreements bypass traditional wholesale channels for Rhineland and Bavaria ingredient houses. |
| FSSAI Pre-Qualification Services | Western suppliers capture Maharashtra and Gujarat beverage manufacturing share ahead of domestic competitors. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with fermentation platform R&D directors, procurement leads at pan-European dairy processors, regulatory affairs specialists at ingredient houses, and bakery cooperative technical managers with secondary validation against EFSA safety assessments, REACH registration databases, FSSAI additive notifications, and customs trade data for sunflower and rapeseed oil flows. Bottom-up segment sizing and top-down market triangulation cross-verified volume and value estimates.
Comparable-period anchoring against historical consumption patterns in dairy, beverage, and bakery applications established the forecast baseline across the projection horizon. The analytical framework modeled segmentation dimensions including product type tier, end-use application, physical form factor, and regional regulatory cluster. CAGRs were derived from trend extrapolation adjusted for substitution elasticity between synthetic and natural emulsifier categories, with enzymatic modification adoption curves and plant-based dairy expansion rates serving as key forecast inputs.
Revisions become necessary when ECHA guidance revisions on persistent bioaccumulative toxic criteria materialize or when Black Sea corridor disruptions extend beyond current supply adjustment periods. Forecasts reflect assumptions about clean-label mandate diffusion rates and fermentation-platform cost reduction trajectories. A model refresh is warranted upon material change in EU Green Deal procurement alignment timelines or FSSAI standard implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Enhancers and Additives
Food Raising Agents Market
Food Enhancers and Additives
Brazzein Market
Food Enhancers and Additives
North America Food Flavor and Enhancer Market
Food Enhancers and Additives
Instant Whipping Agents Market
Food Enhancers and Additives
Canada Food Flavor and Enhancer Market
Food Enhancers and Additives
North America Feed Palatability Enhancers Market
Food Enhancers and Additives
Trans-Resveratrol Market
Food Enhancers and Additives
North America Water Enhancer Market
Food Enhancers and Additives
Japan Water Enhancer Market
Food Enhancers and Additives
Thaumatin Market
Food Enhancers and Additives
Feed Palatability Enhancers and Modifiers Market
Food Enhancers and Additives
Veratrole Market
Food Enhancers and Additives
Liquid Smoke Market
Food Enhancers and Additives
Resveratrol Market
Food Enhancers and Additives
Australia & New Zealand Food Flavors and Enhancers Market
Food Enhancers and Additives
Italy Anti-Caking Market