
 Microcontroller Socket Market | 2026-2036
Microcontroller Socket Market Size, Share, and Industry Trends Forecast 2026-2036
Microcontroller Socket Market Intelligence
Capital-intensity divergence between high-volume foundry-linked players and boutique test-socket specialists is bifurcating competitive dynamics. Texas Instruments leverages captive wafer capacity to anchor pricing power across industrial-grade sockets. Infineon Technologies sustains automotive qualification pipelines that competitors struggle to replicate. Cypress Semiconductor specializes in programmable socket configurations for rapid prototyping workflows.
A microcontroller socket is a mechanical interconnect device that provides removable electrical coupling between a microcontroller unit and a printed circuit board, typically specifying contact resistance below 30 milliohms and insertion force ratings per MIL-STD-883. It enables field replaceability, test access, and burn-in validation without soldering the chip directly. Surface-mount sockets command premium positioning in space-constrained consumer electronics, while burn-in sockets capture concentrated margins from automotive reliability testing. Through-hole variants retain cost advantages in industrial automation where vibration tolerance outweighs density requirements.
RoHS and REACH in Europe restrict cadmium and lead content in contact plating, compelling alloy reformulation across supply chains. EPA guidelines in the United States govern hazardous substance handling in semiconductor test facilities, elevating compliance costs for socket recyclability. FDA device-quality standards indirectly shape medical-grade socket specifications through downstream equipment requirements. Stakeholders must monitor how dual carbon goals in China and evolving automotive functional-safety mandates redistribute qualification priorities across manufacturing footprints.
Market Dynamics
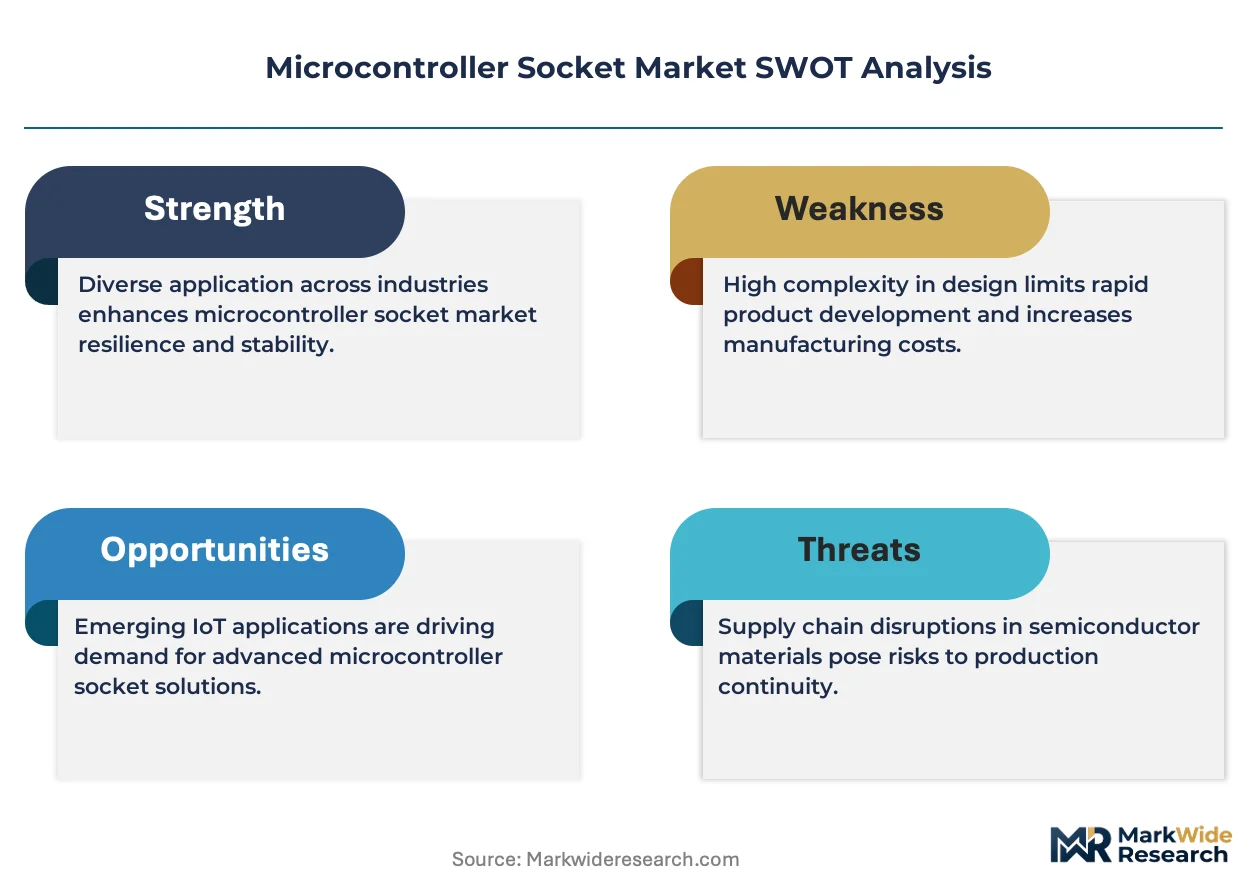
Automotive ECU complexity is forcing socket manufacturers to reconcile burn-in reliability requirements with miniaturization pressures from space-constrained vehicle architectures. This structural tension between thermal cycling durability and contact density is reshaping alloy selection and contact geometry across the supply base.
Growth Catalysts
- Automotive Functional Safety Mandates:ISO 26262 certification requirements for ECU validation are expanding demand for high-reliability burn-in sockets capable of extended temperature cycling. Tier-1 suppliers are qualifying socket vendors against these standards ahead of volume production ramps.
- China Domestic Semiconductor Production:MIIT localization targets for microcontroller manufacturing are concentrating socket procurement within domestic foundry ecosystems. Local packaging houses are scaling test capacity to serve this captive demand.
- REACH Material Restrictions:ECHA enforcement of cadmium and lead limits in electrical contacts is accelerating adoption of palladium-nickel and gold-flash plating chemistries. European automotive OEMs are requiring full material disclosure from socket suppliers.
Market Restraints
- Precious Metal Input Volatility:Palladium and gold price swings in commodity markets are compressing gross margins for contact-plating operations. Socket manufacturers lack pricing power to pass through these cost movements to automotive customers locked into annual contracts.
- High-Volume Foundry Concentration:Taiwan and South Korea dominate advanced microcontroller wafer supply, creating geographic risk concentration for socket demand tied to specific packaging flows. Disruptions to these foundry outputs cascade directly to socket order volatility.
- Direct Solder Attachment Substitution:Improvements in board-level reliability testing are reducing the need for socketed interfaces in cost-sensitive consumer applications. Surface-mount microcontroller placement is displacing removable interconnects below certain ASP thresholds.
Strategic Opportunities
- India Electronics Manufacturing:PLI scheme incentives for semiconductor packaging are attracting socket vendors to establish local test-socket production. Domestic EMS growth is creating pull for standard-grade surface-mount variants.
- Medical Device Integration:FDA device-quality standards are propagating through downstream equipment requirements, opening specifications for medical-grade sockets with traceable contact resistance. Diagnostic equipment OEMs represent an underpenetrated vertical.
- Edge AI Hardware Prototyping:Convergence of microcontroller-based inference engines with rapid iteration workflows is creating demand for programmable socket configurations. Development kit vendors are sourcing configurable contact arrays to accelerate customer evaluation cycles.
Industry Challenges
- Automotive Qualification Timelines:AEC-Q100 test socket validation cycles extend 18-24 months, locking working capital and engineering resources before revenue realization. Competitors struggle to replicate Infineon's sustained qualification pipeline depth.
- Contact Geometry IP Complexity:Patent thickets around high-density cantilever contact designs are forcing second-tier vendors into licensing arrangements or inferior mechanical alternatives. Freedom-to-operate analyses consume legal budgets disproportionate to product revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microcontroller Socket Market |
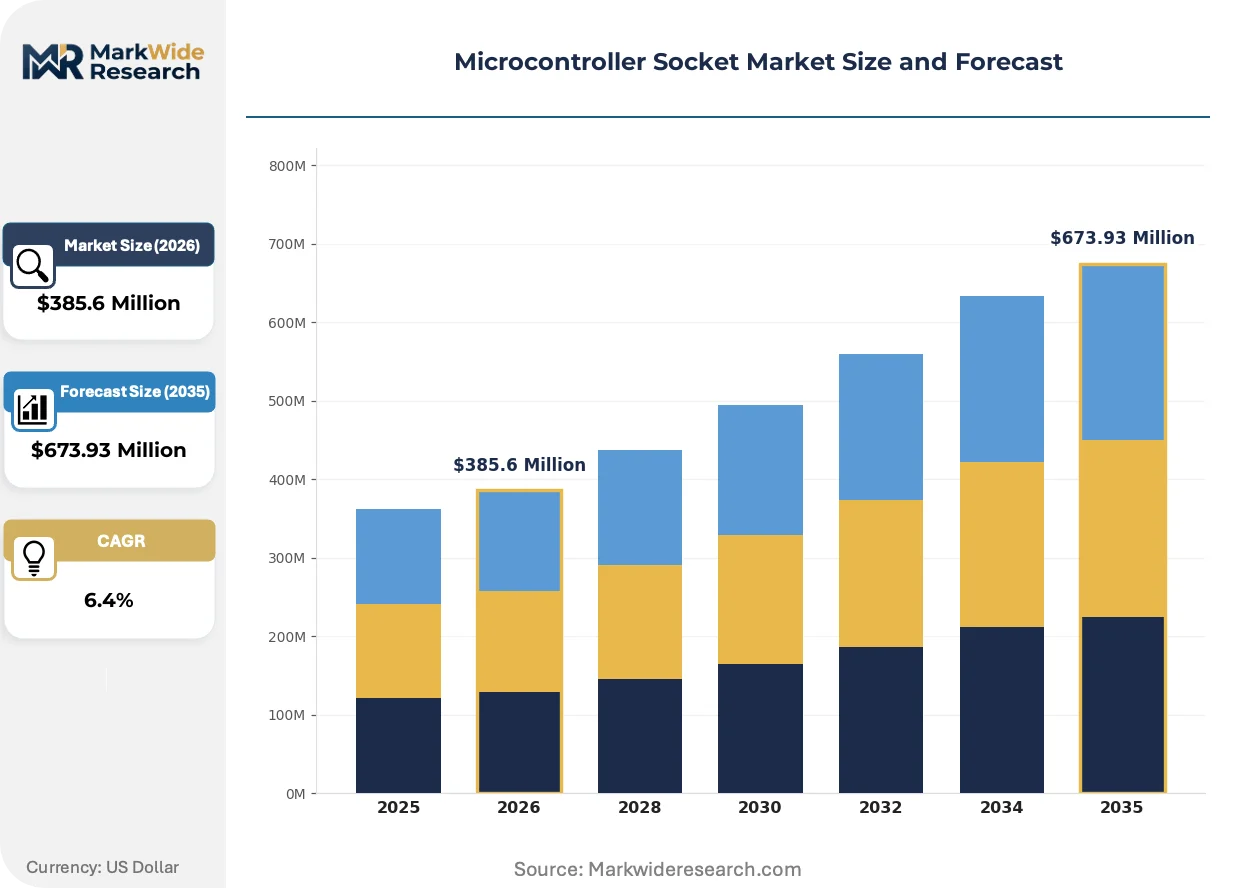
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Through-Hole, Surface-Mount, Test Sockets, Burn-In Sockets Application: Consumer Electronics, Automotive, Industrial Automation, Medical Devices Technology: Analog, Digital, Mixed-Signal, Embedded Systems End User: OEMs, Contract Manufacturers, Research Institutions, Engineering Firms |
| Companies Covered | STMicroelectronics, Analog Devices, Texas Instruments, ON Semiconductor, Renesas Electronics Corporation, Microchip Technology, Infineon Technologies, Cypress Semiconductor, NXP Semiconductors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microcontroller Socket Market Strategic Shifts & Innovations
Contact metallurgy and thermal management architectures are undergoing simultaneous transformation as automotive reliability requirements intensify and consumer density constraints tighten. These parallel pressures are compressing legacy socket form factors while elevating performance specifications.
Liquid metal thermal interface materials are supplanting traditional thermal grease in high-power burn-in sockets for automotive-grade microcontrollers. Tier-1 test houses in Germany and Japan are adopting these interfaces to achieve uniform junction temperature control during extended stress testing. This transition is enabling higher thermal dissipation density per contact, compressing socket footprint for multi-site parallel testing configurations.
EU F-Gas Regulation restrictions on fluorinated greenhouse gases are eliminating certain dielectric cooling fluids previously used in temperature-forcing systems for socket testing. European test equipment OEMs are retrofitting thermal management subsystems with alternative refrigerant chemistries or transitioning to conductive heating architectures. Automotive qualification labs in Stuttgart and Munich are absorbing these capital costs ahead of 2025 phase-down deadlines.
Consolidated procurement through foundry-linked packaging houses is displacing fragmented distributor purchasing for high-volume socket categories. IDM captive packaging operations in China and Taiwan are negotiating direct annual contracts with socket specialists, extracting volume discounts and technical customization commitments. This concentration is most visible in consumer electronics microcontroller flows where packaging scale dominates supplier selection criteria.
Microcontroller Socket Market Segmentation
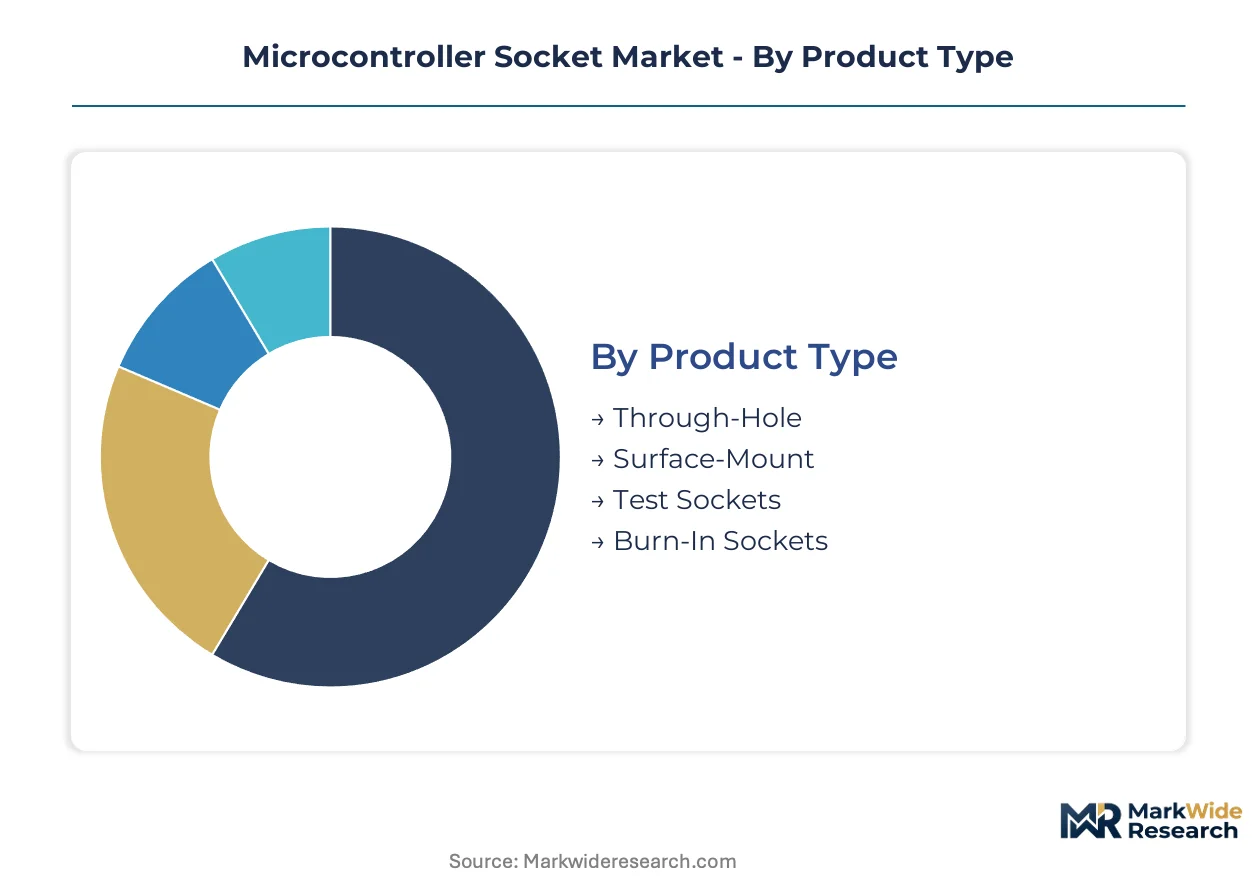
Segmentation in the microcontroller socket market reveals how technical specifications, end-use reliability requirements, and procurement patterns fragment demand across incompatible product categories. Each dimension carries distinct margin profiles and qualification barriers that reshape competitive positioning.
Product Type:
Through-hole variants dominate domestic industrial automation procurement in Germany and Japan, while surface-mount and test sockets flow through export-oriented packaging hubs in Taiwan and South Korea.
- Through-Hole:These sockets employ solder-tail leads penetrating PCB substrates, delivering mechanical stability under vibration stress. Industrial automation OEMs in Stuttgart and Nagoya specify these for factory-floor controllers where shock tolerance outweighs density constraints. Cost advantages sustain adoption in legacy equipment refurbishment.
- Surface-Mount:Compact gull-wing or J-lead configurations enable high-density placement on multilayer boards. Consumer electronics EMS providers in Shenzhen and Ho Chi Minh City drive procurement for smartphone and wearable microcontroller integration. Miniaturization pressures from space-constrained architectures accelerate contact pitch reduction.
- Test Sockets:Temporary interconnect systems for wafer-level and package-level validation, featuring zero-insertion-force mechanisms.
- Burn-In Sockets:High-temperature cycling interfaces for automotive reliability qualification, commanding concentrated margins from tier-1 test houses.
Through-hole holds the largest share; momentum sits with surface-mount variants as consumer density requirements intensify.
Application:
Cost tier differentiation separates premium automotive qualification sockets from economy-grade consumer electronics variants, with medical and industrial occupying mid-tier positioning.
- Consumer Electronics:High-volume, low-margin procurement from smartphone and wearable OEMs prioritizes cost-per-contact metrics over extended reliability. Surface-mount dominance reflects space constraints in handheld device architectures.
- Automotive:ISO 26262 functional safety mandates drive burn-in socket demand for ECU validation. Extended temperature cycling requirements from -40°C to 150°C elevate palladium-nickel plating specifications. Tier-1 suppliers in Germany and Japan lock vendors into 18-24 month qualification pipelines.
- Industrial Automation:Vibration-tolerant through-hole configurations retain preference for programmable logic controllers and motor drives.
- Medical Devices:FDA device-quality standards propagate through diagnostic equipment requirements, opening specifications for traceable contact resistance.
Automotive commands premium pricing; medical devices represent the steepest expansion trajectory as diagnostic equipment integration accelerates.
Technology:
Volume concentration favors digital microcontroller sockets serving high-unit consumer applications, while analog and mixed-signal variants serve specialized industrial and automotive signal conditioning.
- Analog:Precision signal conditioning sockets for sensor interface microcontrollers, requiring shielded contact geometries to minimize noise coupling.
- Digital:High-pin-count configurations for general-purpose microcontrollers dominate unit volume. Consumer electronics packaging houses in China and Taiwan drive procurement scale.
- Mixed-Signal:Integrated analog-digital peripherals demand specialized contact layouts balancing signal integrity with power delivery.
- Embedded Systems:Application-specific socket configurations for system-on-chip integration, gaining share fastest in edge AI prototyping workflows.
Digital sockets anchor volume; embedded systems variants are climbing the fastest as inference engine integration proliferates.
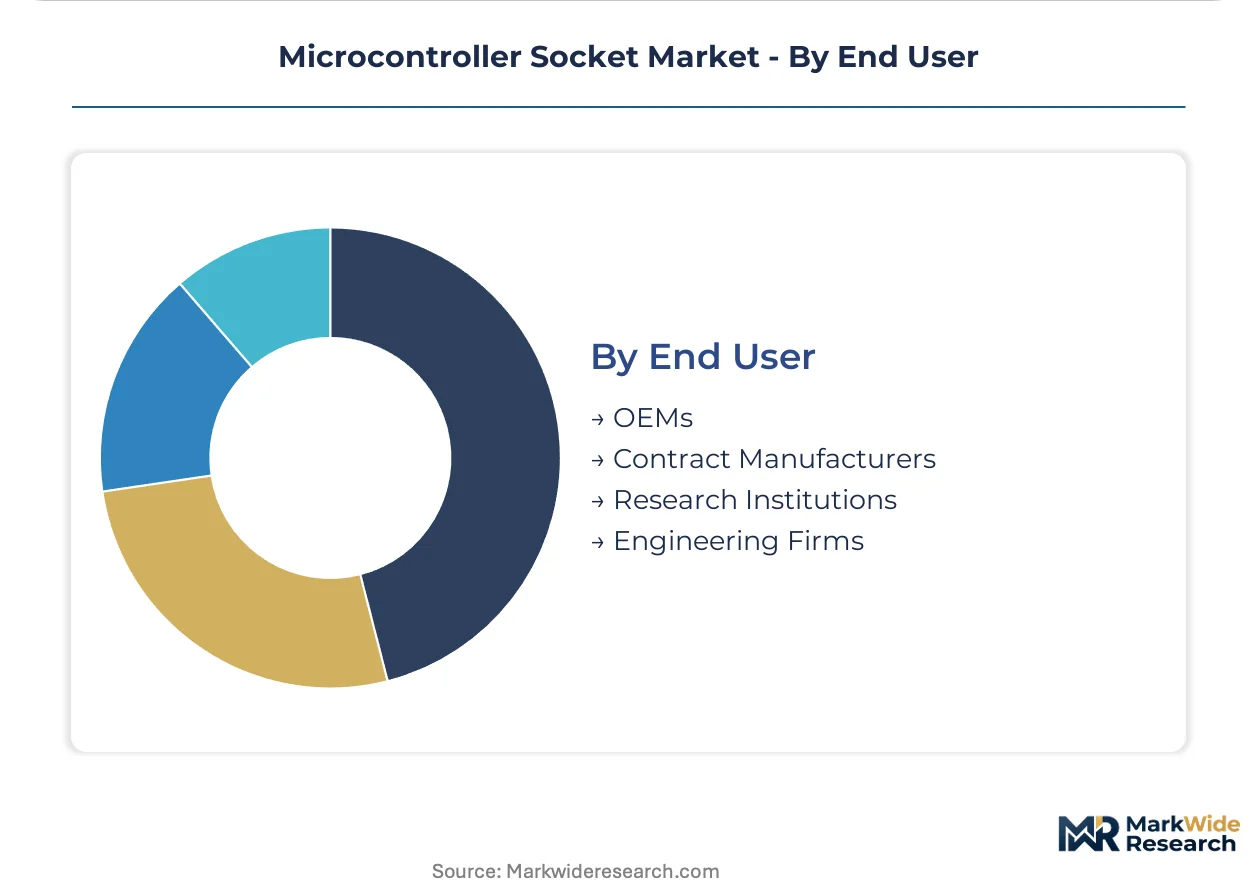
End User:
Customer type determines procurement modality: OEMs negotiate direct annual contracts, while contract manufacturers consolidate fragmented demand through distributor channels.
- OEMs:Original equipment manufacturers in automotive and medical verticals specify custom socket configurations with dedicated qualification cycles. Captive packaging operations at IDMs like Texas Instruments and Infineon Technologies bypass distributor markup.
- Contract Manufacturers:Foxconn, Jabil, and Flex consolidate high-volume consumer electronics socket procurement through foundry-linked packaging houses. Volume discounts extract margin compression from socket specialists.
- Research Institutions:Low-volume, high-mix procurement for academic and government labs prioritizes configurability over unit cost.
- Engineering Firms:Rapid prototyping demand drives programmable socket adoption for pre-production validation.
Contract manufacturers hold the largest share; engineering firms are gaining share fastest as edge AI hardware prototyping accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows concentrate socket procurement in manufacturing hubs with captive packaging capacity, while deficit regions absorb finished microcontroller modules. Trade balances reflect foundry-linked demand clustering versus end-market consumption dispersion.
China
Domestic microcontroller production scales under MIIT localization targets, concentrating socket demand in Yangtze River Delta packaging houses. Dual carbon goals from MEE redirect material sourcing toward lead-free alloy suppliers. Shenzhen and Suzhou clusters absorb volume procurement for consumer electronics EMS flows.
Germany
Automotive ECU validation drives burn-in socket procurement from tier-1 test houses in Stuttgart and Munich. ECHA REACH enforcement compels palladium-nickel plating transitions across supplier bases. Bavarian automotive qualification labs absorb capital costs for F-Gas Regulation thermal system retrofits ahead of 2025 deadlines.
United States
Industrial automation OEMs in Midwest manufacturing corridors sustain through-hole socket demand for programmable logic controllers. EPA hazardous substance guidelines elevate compliance costs for semiconductor test facility operations. Texas Instruments anchors captive packaging demand in Dallas-Fort Worth metroplex.
Japan
Precision industrial controllers in Nagoya and Tokyo manufacturing belts specify vibration-tolerant socket configurations. METI industrial standards propagate through domestic equipment supply chains. Automotive tier-1 suppliers in Toyota City lock vendors into extended qualification pipelines.
South Korea
Advanced microcontroller wafer output from Samsung and SK Hynix creates concentrated socket demand in Seoul Capital Area packaging operations. MFDS traceability standards shape medical-grade socket specifications for diagnostic equipment exports. Busan-Ulsan industrial corridor absorbs high-volume surface-mount procurement.
Microcontroller Socket Market Key Industry Players
Concentration sits with IDM captive packaging operations and specialized test-socket fabricators serving automotive qualification pipelines. Texas Instruments and Infineon Technologies anchor pricing power through backward integration into wafer capacity and sustained AEC-Q100 validation depth. Three archetypes dominate: vertically integrated semiconductor manufacturers, boutique high-reliability specialists, and configurable prototyping solution providers. Competitive moves center on qualification pipeline lock-in and geographic proximity to foundry packaging hubs.
Among IDM-based fabricators, Texas Instruments, Infineon Technologies, and Cypress Semiconductor occupy distinct positioning vectors. Texas Instruments exemplifies scale-driven captive supply integration. Infineon Technologies anchors automotive-tier qualification depth. Cypress Semiconductor represents the prototyping-specialist archetype with programmable configuration capabilities.
| Leading Market Players |
|---|
| STMicroelectronics |
| Analog Devices |
| Texas Instruments |
| ON Semiconductor |
| Renesas Electronics Corporation |
| Microchip Technology |
| Infineon Technologies |
| Cypress Semiconductor |
| NXP Semiconductors |
| Others |
Cost & Logistics Intelligence
Captive packaging capacity at IDM facilities in Dallas-Fort Worth and Toyota City compresses unit economics for automotive-grade burn-in sockets, establishing price floors that independent test-socket fabricators struggle to match without comparable qualification pipeline depth or backward integration into wafer supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across through-hole socket categories, while automotive tier-1 suppliers negotiate annual volume commitments with AEC-Q100 certification tiers embedded as price differentiation drivers. Palladium-nickel plating specifications from ECHA REACH enforcement are elevating input costs faster than contract pass-through mechanisms allow, compressing gross margins for contact-plating operations. Consumer electronics EMS providers exhibit highest price sensitivity, prioritizing cost-per-contact metrics over extended reliability warranties.
Supply Chain Analysis
Container availability constraints on transpacific trade lanes from Shanghai and Busan are elevating inbound logistics costs for precious metal feedstock sourced from South African refineries. Socket manufacturing draws from palladium and gold plating chemistries, high-performance copper alloys, and liquid metal thermal interface materials. Single-source vulnerability concentrates in Taiwan and South Korea foundry-linked packaging houses. Distribution runs through consolidated procurement channels at IDM captive operations and foundry-direct annual contracts, displacing fragmented distributor purchasing for high-volume categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Socket qualification as a service—encompassing AEC-Q100 validation cycles, material disclosure documentation, and thermal management subsystem integration—is expanding faster than hardware unit sales as automotive OEMs outsource compliance burden to specialized vendors.
For Market Incumbents: Fortify qualification pipeline lock-in by extending AEC-Q100 validation depth beyond competitors' replication timelines, while anchoring pricing power through captive wafer capacity or exclusive palladium-nickel plating alloy formulations. Direct solder attachment substitution in consumer electronics represents the primary substitution threat requiring defensive patent positioning around zero-insertion-force contact geometries. For New Entrants and Emerging Players: AEC-Q100 certification fast-track partnerships with Bavarian automotive qualification labs in Stuttgart and Munich offer the most penetrable entry vector, targeting burn-in socket demand from tier-1 test houses locked out of incumbent qualification queues. Medical device integration represents underpenetrated white space where FDA device-quality standards propagate through diagnostic equipment requirements with less entrenched supplier relationships. Engineering-led direct sales to rapid prototyping workflows bypasses consolidated procurement channels. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors boutique test-socket specialists with sustained automotive qualification pipelines and programmable configuration IP for edge AI hardware prototyping. Long-term viability rests on defensible contact geometry patents and geographic proximity to foundry packaging hubs rather than scale economies. Watch for inflection signals in MIIT localization target acceleration or ECHA REACH enforcement intensity shifts that would redistribute qualification priority across manufacturing footprints.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Qualification Pipeline Expansion | Locks tier-1 automotive test houses into 18-24 month validation cycles before revenue realization. |
| Palladium-Nickel Plating Alloy Proprietary Formulation | Defends margin position against ECHA REACH-driven material cost pass-through limitations. |
| Programmable Socket Configuration Platform Launch | Captures edge AI hardware prototyping demand from development kit vendors accelerating evaluation cycles. |
| India PLI Scheme Packaging Hub Establishment | Positions local test-socket production to serve domestic EMS growth for standard-grade surface-mount variants. |
| Liquid Metal Thermal Interface Material Integration | Enables higher thermal dissipation density for multi-site parallel testing configurations in automotive burn-in applications. |
Research Approach
Two parallel data streams informed the analysis: primary field engagement with socket procurement managers at tier-1 automotive test houses, packaging engineers at IDM captive operations, thermal management subsystem designers, and burn-in equipment OEMs; combined with secondary validation against SEC semiconductor filings, ECHA substance restriction databases, MIIT industrial policy circulars, and customs trade flow records. Bottom-up unit demand modeling triangulated against top-down foundry capacity forecasts established volume and value boundaries.
Across the projection horizon, the analytical framework segmented demand by product type, application reliability tier, microcontroller technology class, and end-user procurement modality. CAGRs derived from fitted growth curves incorporating automotive ECU complexity trajectories, China domestic production localization rates, and REACH material transition timelines. Forecast inputs included foundry packaging capacity expansion schedules and precious metal commodity price volatility assumptions.
Decision-makers should treat outputs as directional under sustained automotive functional safety mandate enforcement and China dual carbon goal implementation; material deviation in foundry output concentration or regulatory phase-down acceleration would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Automation Component Market
Electronic Components
PTC Resettable Device Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Flash Charger Adapter Market
Electronic Components
Low-Dropout (LDO) Regulator Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
Braking Resistors Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
Audio Power Amplifier Market
Electronic Components
Capacitor Aluminum Polymer Market
Electronic Components
Data Acquisition Hardware Market
Electronic Components
High-Voltage Capacitor Market
Electronic Components
5G Base Station BAW Filters Market
Electronic Components
North America MLCC Market
Electronic Components
Docking Station Market
Electronic Components
Data Bus Market