
 High-Voltage Capacitor Market | 2026-2036
High-Voltage Capacitor Market Size, Share, and Industry Trends Forecast 2026-2036
High-Voltage Capacitor Market Intelligence
Project finance and long-term equipment leasing for grid infrastructure is reshaping competitive dynamics in the high-voltage capacitor sector. ABB Ltd. leverages its integrated power-grid portfolio to anchor turnkey capacitor-bank installations across transmission networks. Siemens AG sustains R&D intensity in ceramic dielectric formulations for extreme-voltage environments. TDK Corporation specializes in film-capacitor architectures that serve industrial motor-drive applications with precision-tuned capacitance stability.
High-voltage capacitors store and release electrical energy at rated potentials typically exceeding 1 kV, employing dielectric media such as polypropylene film, ceramic formulations, or electrolytic oxide layers to withstand intense electric field stress without breakdown. Their primary industrial purpose centers on power-factor correction, harmonic filtering, and transient voltage suppression within transmission and distribution systems. Film capacitors occupy the dominant share in utility-scale deployments due to superior self-healing properties and extended operational lifecycles under continuous AC stress. Ceramic variants command premium positioning in compact, high-frequency power electronics modules where thermal cycling resistance determines reliability. Supercapacitor technology leads growth velocity within renewable energy buffering, where rapid charge-discharge cycles bridge intermittency gaps in wind and solar generation.
The U.S. Federal Energy Regulatory Commission and the EPA jointly influence capacitor procurement through efficiency standards and environmental restrictions on dielectric fluids containing polychlorinated biphenyls. Europe's ECHA enforces REACH compliance on insulating materials, while the EU Green Deal mandates carbon-accounting transparency across power-component supply chains. China's National Energy Administration and GB standards dictate local-content thresholds and testing protocols for grid-connected equipment. Stakeholders must monitor evolving material-compliance regimes and assess captive dielectric-film supply as regulatory stringency intensifies.
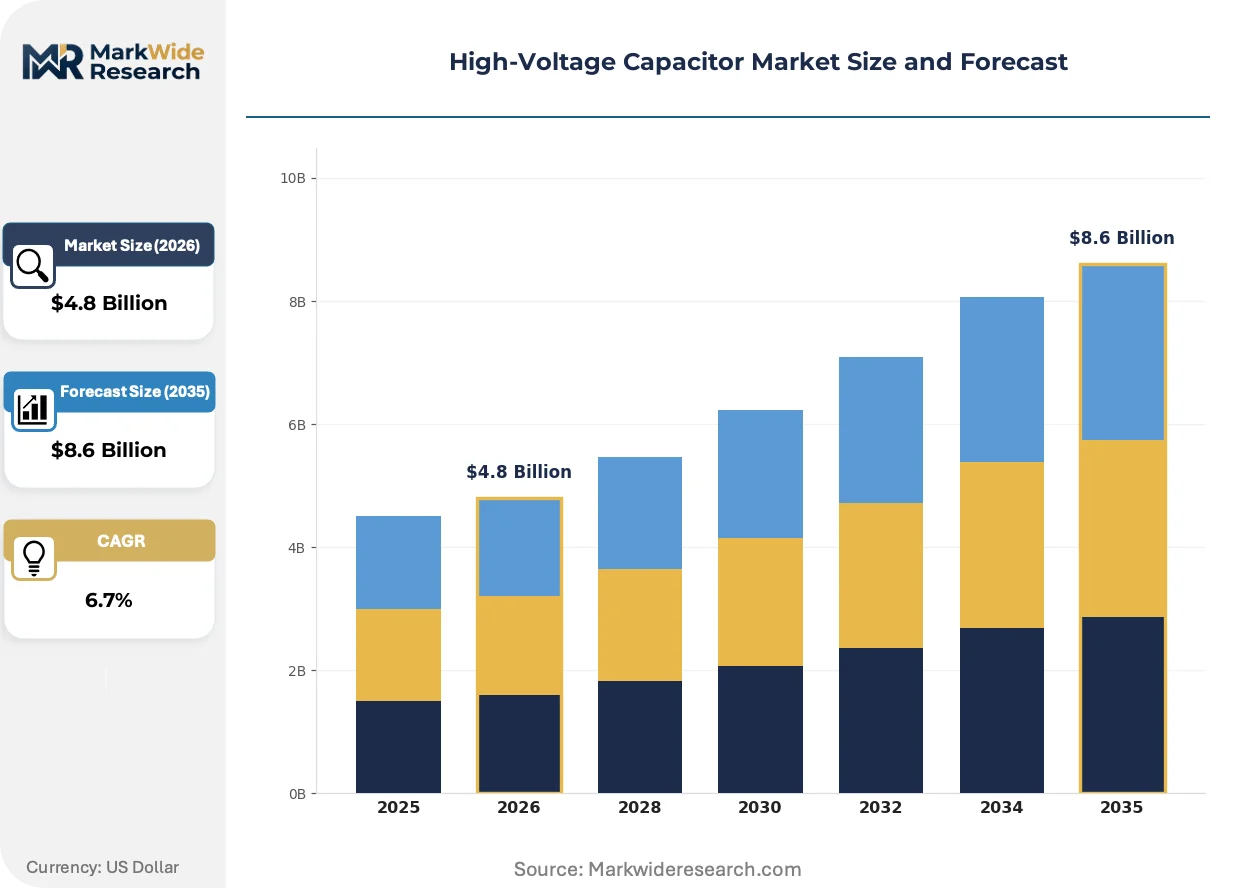
Market Dynamics
Dielectric material transitions under the EU F-Gas Regulation and China's dual carbon mandates are compressing incumbent supply chains while opening procurement windows for fluorine-free alternatives. This regulatory compression is forcing capacitor manufacturers to requalify insulation systems ahead of accelerated phase-out timelines.
Growth Catalysts
- EU F-Gas Regulation:Accelerated phase-down of hydrofluorocarbon-based dielectric fluids is redirecting utility procurement toward biodegradable ester and synthetic hydrocarbon formulations.
- Grid-scale battery integration:Utility-scale energy storage deployments in China and Germany require high-voltage capacitor banks for harmonic filtering and DC-link stabilization in converter stations.
- Offshore wind expansion:Subsea transmission corridors from North Sea wind clusters demand pressurized gas-insulated capacitor units rated for marine environments.
Market Restraints
- Polypropylene film concentration:Biaxially oriented polypropylene film supply concentrates among Japanese and German specialty chemical producers, creating input vulnerability for film capacitor manufacturers.
- REACH compliance costs:ECHA substance-of-very-high-concern listings for legacy epoxy resin hardeners are forcing reformulation of potting compounds used in ceramic capacitor assemblies.
- Supercapacitor energy density gap:Electrochemical double-layer capacitors remain limited to short-duration power buffering, constraining displacement of electrostatic capacitors in bulk energy storage roles.
Strategic Opportunities
- India transmission buildout:Central Electricity Authority mandates for 765 kV and 1200 kV corridors create demand for ultra-high-voltage capacitor banks with localized manufacturing incentives under PLI schemes.
- Solid-state transformer convergence:Integration of wide-bandgap silicon carbide power electronics with high-frequency capacitor modules enables compact substation designs for urban density constraints.
- Performance-based O&M contracts:Asset owners in Germany and California are unbundling capacitor bank maintenance from equipment purchase, creating recurring revenue streams for condition-monitoring service providers.
Industry Challenges
- High-voltage testing technician scarcity:Specialized skills for partial discharge analysis and impulse voltage testing are concentrated among aging workforces in Japan and Switzerland.
- Multi-standard certification burden:Simultaneous compliance with IEC 60871, IEEE 18, and GB/T 11024 requires redundant testing protocols that extend product qualification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Voltage Capacitor Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolytic, Ceramic, Film, Supercapacitor Technology: Power Electronics, Energy Storage, Smoothing, Filtering End User: Utility Providers, Industrial Equipment, Renewable Energy, Automotive Application: Power Generation, Power Distribution, Motor Drive, Power Factor Correction |
| Companies Covered | ABB Ltd., Vishay Intertechnology Inc., General Atomics, Eaton Corporation PLC, TDK Corporation, HVC Capacitor Manufacturing, Siemens AG, CalRamic Technologies LLC, Hitachi Energy Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Voltage Capacitor Market Strategic Shifts & Innovations
Capacitor architectures are fragmenting along voltage-frequency axes as end-use applications diverge between bulk power transmission and power electronics integration. This divergence is compressing the addressable market for general-purpose designs while rewarding specialized formulations.
Self-healing metallized polypropylene film is migrating from conventional oil-impregnated paper capacitors in utility power-factor correction banks. European transmission system operators in Germany and Italy are adopting all-film designs for reduced maintenance intervals. The technology is migrating from niche renewable applications into mainstream grid infrastructure, compressing demand for legacy paper-film hybrid constructions.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of dielectric fluids and capacitor impregnants across European supply chains. Industrial capacitor manufacturers must substitute fluorinated performance additives with bio-based alternatives or secure time-limited authorizations. Film capacitor producers serving German automotive and industrial motor-drive markets are accelerating qualification of ester-based impregnants ahead of 2025 substance restriction deadlines.
Utility procurement offices are consolidating capacitor bank specifications into framework agreements with integrated turnkey suppliers, displacing component-only purchasing. Engineering-procurement-construction contractors in China and the United States are bundling capacitor installation with switchgear and protection systems. This concentration is most visible in state grid tenders in Shandong and Jiangsu provinces, where single-source accountability for harmonic filter performance is becoming mandatory.
High-Voltage Capacitor Market Segmentation
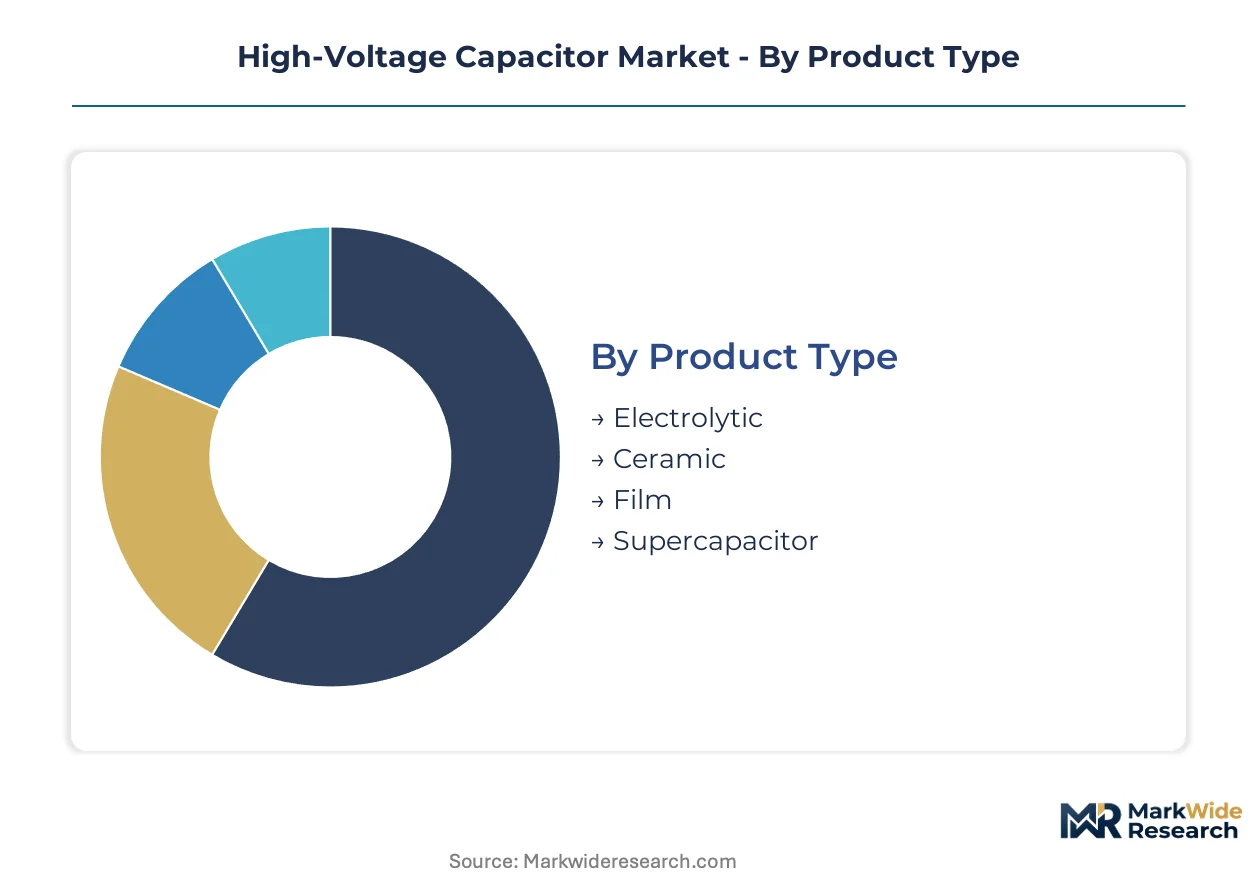
High-voltage capacitor procurement patterns diverge sharply across dielectric technologies and end-use applications. Segment boundaries reflect distinct performance requirements, lifecycle economics, and regulatory exposure profiles that reshape supplier positioning.
Product Type:
Mature film architectures dominate utility-scale installations while supercapacitor formats accelerate from emerging energy storage niches.
- Film:Metallized polypropylene dielectrics with self-healing properties withstand continuous AC stress in transmission-grade power-factor correction banks. German and Italian transmission system operators specify all-film designs for extended maintenance intervals in grid stabilization networks. REACH-driven reformulation of impregnants is compressing incumbent supply chains while opening procurement windows for ester-based alternatives.
- Supercapacitor:Electrochemical double-layer architectures deliver rapid charge-discharge cycles for renewable intermittency buffering in wind and solar converter stations. Chinese state-backed grid modernization programs sustain large-scale orders for DC-link stabilization modules. Energy density constraints limit displacement of electrostatic capacitors in bulk storage roles.
- Ceramic:Compact formulations serve high-frequency power electronics modules where thermal cycling resistance determines reliability in silicon carbide converter applications.
- Electrolytic:Aluminum oxide dielectric layers provide cost-effective capacitance for industrial motor drives with moderate voltage stress requirements.
Film retains volume leadership; supercapacitor holds the steepest expansion curve.
Technology:
Application-driven cost tiers separate commodity smoothing functions from precision-filtering premium segments.
- Filtering:Harmonic suppression networks in offshore wind transmission corridors demand pressurized gas-insulated units rated for marine environments. North Sea cluster developments in Germany and the United Kingdom specify these for subsea cable compensation.
- Power Electronics:Wide-bandgap silicon carbide integration enables compact high-frequency capacitor modules for urban substation density constraints. Solid-state transformer convergence is accelerating qualification timelines.
- Energy Storage:Grid-scale battery deployments require capacitor banks for DC-link stabilization in converter stations across Chinese and German utility networks.
- Smoothing:Bulk voltage ripple reduction in industrial motor drives represents the most price-sensitive technology tier with established supply competition.
Filtering commands premium pricing; power electronics is gaining share fastest.
End User:
Customer concentration patterns concentrate procurement leverage among integrated grid operators while fragmenting industrial demand.
- Utility Providers:State grid tenders in Shandong and Jiangsu provinces mandate single-source accountability for harmonic filter performance. Framework agreements with turnkey suppliers are displacing component-only purchasing across Chinese and US transmission buildouts.
- Renewable Energy:Offshore wind developers in the North Sea and onshore solar integrators in China drive specialized specifications for environmental resilience and rapid cycling durability.
- Industrial Equipment:Motor drive OEMs in Germany prioritize precision-tuned capacitance stability for automation systems with varying batch sizes.
- Automotive:Electric vehicle powertrain manufacturers specify compact ceramic variants for onboard charging and inverter modules.
Utility providers anchor procurement volume; renewable energy shows the steepest demand climb.
Application:
Geographic deployment patterns concentrate power generation and distribution investments in Asia-Pacific grid corridors while motor drive demand fragments globally.
- Power Factor Correction:Utility-scale banks compensate reactive power in 765 kV and 1200 kV transmission corridors mandated by India's Central Electricity Authority. PLI scheme localization incentives are reshaping supplier qualification requirements.
- Power Distribution:Urban density constraints in Chinese and German cities drive compact substation designs with integrated capacitor-switchgear bundles.
- Power Generation:Conventional plant retrofits and renewable integration programs sustain replacement cycles across European and North American markets.
- Motor Drive:Industrial automation upgrades in automotive and material processing sectors generate fragmented demand with specification diversity.
Power factor correction leads installed base; power distribution is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC efficiency standards and EPA restrictions on dielectric fluids are redirecting utility procurement in the United States toward compliant capacitor banks. China's dual carbon mandates and state-backed grid modernization sustain large-scale orders through provincial tenders. India's PLI localization incentives are reshaping supplier qualification requirements for ultra-high-voltage corridors.
United States
Utility-scale energy storage deployments require high-voltage capacitor banks for harmonic filtering in converter stations. FERC and EPA jointly influence procurement through efficiency standards and environmental restrictions on polychlorinated biphenyl-containing fluids. Engineering-procurement-construction contractors in Texas and California are bundling capacitor installation with switchgear systems.
Germany
Offshore wind transmission corridors from North Sea clusters demand pressurized gas-insulated capacitor units rated for marine environments. ECHA enforces REACH compliance on insulating materials under EU Green Deal carbon-accounting mandates. Transmission system operators in Bavaria and North Rhine-Westphalia specify all-film designs for extended maintenance intervals.
China
State grid tenders in Shandong and Jiangsu provinces mandate single-source accountability for harmonic filter performance. The National Energy Administration and GB standards dictate local-content thresholds and testing protocols for grid-connected equipment. State-backed renewable integration programs in the Yangtze River Delta sustain replacement cycles for power-factor correction banks.
India
Central Electricity Authority mandates for 765 kV and 1200 kV transmission corridors create demand for ultra-high-voltage capacitor banks. PLI scheme localization incentives require domestic manufacturing qualification for grid infrastructure procurement. Industrial automation upgrades in Maharashtra and Gujarat generate fragmented demand for motor-drive applications.
Japan
Specialized skills for partial discharge analysis and impulse voltage testing concentrate among aging workforces in industrial clusters. METI and JIS standards govern qualification protocols for high-voltage testing equipment. Ceramic dielectric formulation expertise in the Kanto region supports compact power electronics modules for silicon carbide converters.
High-Voltage Capacitor Market Key Industry Players
On the supply side, the industry is consolidating around integrated power-grid portfolios and specialized dielectric formulations. Tiered competitive positioning separates turnkey installation providers from component specialists and materials innovators. Strategic archetypes include integrated electrical equipment conglomerates, film dielectric specialists, and ceramic formulation experts. Dominant competitive moves encompass framework agreement consolidation with utility procurement offices and accelerated qualification of fluorine-free dielectric alternatives.
Among integrated electrical equipment providers, ABB Ltd., Siemens AG, and TDK Corporation exemplify distinct competitive positioning archetypes. ABB Ltd. represents the turnkey installation vector through its integrated power-grid portfolio. Siemens AG occupies a position within the ceramic dielectric specialization tier for extreme-voltage environments. TDK Corporation sits within the precision-tuned capacitance stability segment serving industrial motor-drive applications.
| Leading Market Players |
|---|
| ABB Ltd. |
| Vishay Intertechnology Inc. |
| General Atomics |
| Eaton Corporation PLC |
| TDK Corporation |
| HVC Capacitor Manufacturing |
| Siemens AG |
| CalRamic Technologies LLC |
| Hitachi Energy Ltd. |
| Others |
Cost & Logistics Intelligence
Shanghai-Rotterdam container freight corridors transmit cost volatility from biaxially oriented polypropylene film concentration in Japan and Germany directly into utility-scale capacitor bank quotations, compressing margins for component-only suppliers while amplifying pricing power for integrated turnkey providers with captive dielectric sourcing.
Pricing Analysis
Certification level under IEC 60871 and IEEE 18 standards creates the primary spread between premium and commodity tiers. Project-based long-term contracting dominates utility procurement, with volume scale and after-sales service bundling as secondary differentiation factors. Cost compression in standard-grade film capacitors is intensifying because REACH-driven reformulation of ester-based impregnants is extending qualification cycles. Industrial motor drive OEMs exhibit highest price sensitivity; offshore wind developers with marine-environment specifications show lowest.
Supply Chain Analysis
Export controls on semiconductor manufacturing equipment are constraining advanced ceramic dielectric production technology flows to Chinese capacitor manufacturers. Geographic supply concentrates in Japan, Germany, and China for polypropylene film, ceramic formulations, and aluminum foil electrodes respectively. Raw material dependencies center on biaxially oriented polypropylene resin, rare-earth oxide dopants, and high-purity etched aluminum foil. Single-source vulnerability in Japanese specialty chemical producers for film substrates presents structural risk. Distribution runs through engineering-procurement-construction contractors bundling capacitor banks with switchgear systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized skills for partial discharge analysis and impulse voltage testing are thinning across aging workforces in Japan and Switzerland, constraining quality assurance capacity and creating acquisition premiums for technical talent pools.
For Market Incumbents: Build regulatory compliance moats through accelerated qualification of fluorine-free dielectric alternatives ahead of EU F-Gas phase-down timelines. Secure backward integration into biaxially oriented polypropylene film supply through offtake agreements with Japanese specialty chemical producers. Expand captive testing laboratory capacity in Germany and Switzerland to offset technician scarcity. For New Entrants and Emerging Players: Build out localized manufacturing capabilities for ultra-high-voltage capacitor banks under India's PLI scheme incentives, targeting 765 kV and 1200 kV transmission corridor tenders. Focus initial penetration on ester-based impregnant formulations for European industrial motor-drive markets facing 2025 REACH deadlines. Pursue partnership routes with Chinese state grid EPC contractors rather than direct utility sales. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified electrical equipment conglomerates seeking to monetize non-core capacitor divisions amid portfolio rationalization. Five-to-ten-year viability hinges on dielectric material transition execution rather than legacy market share. Signal to monitor: acceleration of solid-state transformer deployments integrating silicon carbide power electronics with high-frequency capacitor modules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene Film Supply | Captive sourcing from Japanese specialty chemical producers insulates against input volatility. |
| Fluorine-Free Dielectric Qualification Acceleration | EU F-Gas Regulation phase-down timelines compress incumbent reformulation windows. |
| India PLI Localization Manufacturing | CEA-mandated ultra-high-voltage corridors require domestic qualification for grid tenders. |
| Solid-State Transformer Convergence Partnership | Silicon carbide integration with high-frequency modules enables compact urban substation designs. |
| Performance-Based O&M Contract Unbundling | German and California asset owners separate capacitor bank maintenance from equipment purchase. |
Research Approach
Two parallel data streams informed the analysis: primary interviews with utility procurement officers, EPC contractors, capacitor manufacturing plant managers, and high-voltage testing technicians; and secondary validation through IEC standards documentation, FERC efficiency filings, ECHA REACH substance listings, Chinese National Energy Administration tender records, and trade flow data for biaxially oriented polypropylene film. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Forecast inputs incorporated dielectric technology transition timelines, grid modernization investment patterns across Chinese provincial tenders, and offshore wind transmission corridor development in the North Sea. Segmentation modeled product type, application voltage class, end-user concentration, and regional regulatory framework clusters. CAGRs derived from installed base replacement cycles and emerging technology displacement curves.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-backed Chinese manufacturers or accelerated solid-state transformer adoption would shift outcomes. Material shifts in EU F-Gas phase-down schedules or REACH substance restriction timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Power Resistor Market
Electronic Components
High Temperature Capacitor Market
Electronic Components
Global Capacitor Market
Electronic Components
Ceramic Capacitors Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
China Data Converter Market
Electronic Components
Circuit Protection Kits Market
Electronic Components
GPIO Expanders Market
Electronic Components
Loudspeaker Market
Electronic Components
Gas Discharge Tube Market
Electronic Components
Buffered Encoders and Decoders Market
Electronic Components
Lead Zirconate Titanate (PZT) Market
Electronic Components
Flash Charger Adapter Market
Electronic Components
Structural Electronics Market
Electronic Components
Digital Electronic Detonator Market
Electronic Components
PTC Resettable Device Market